Gov Sovereigns/Treasurys
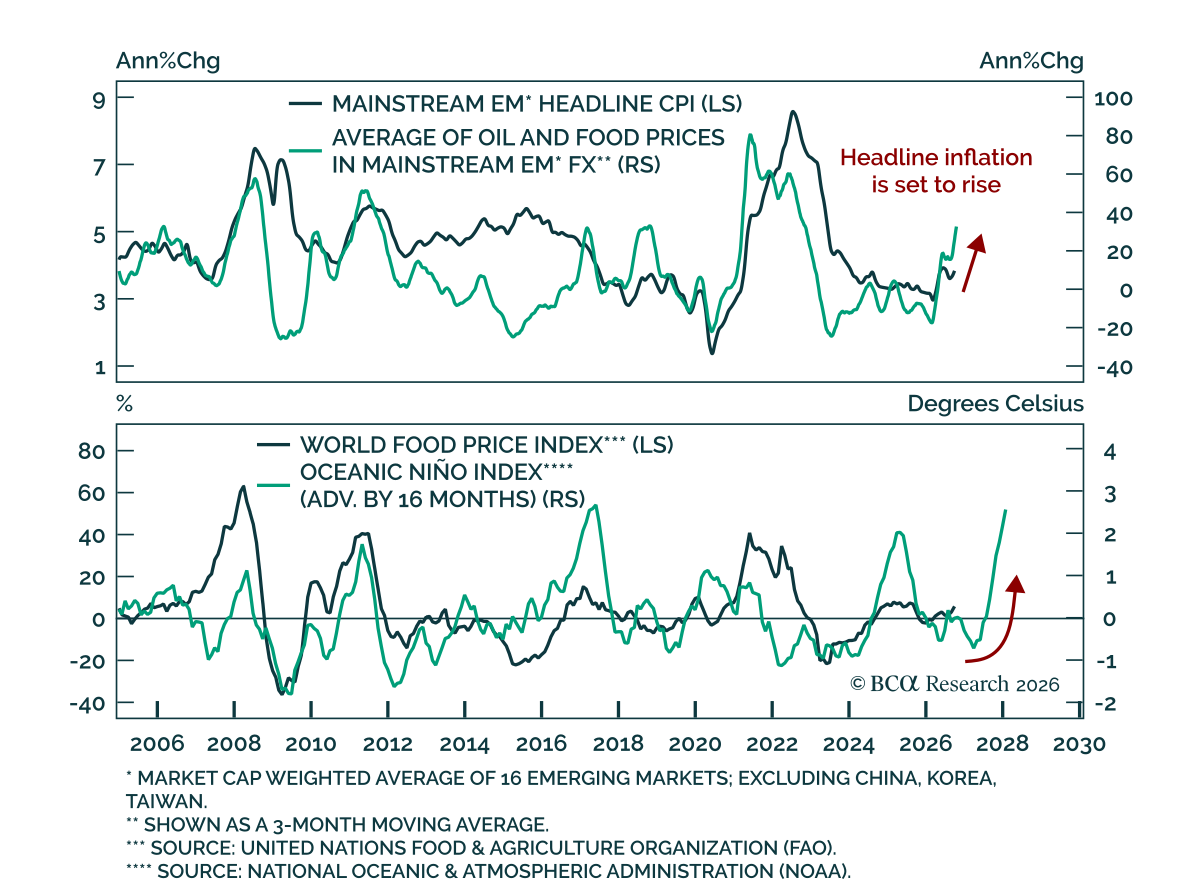
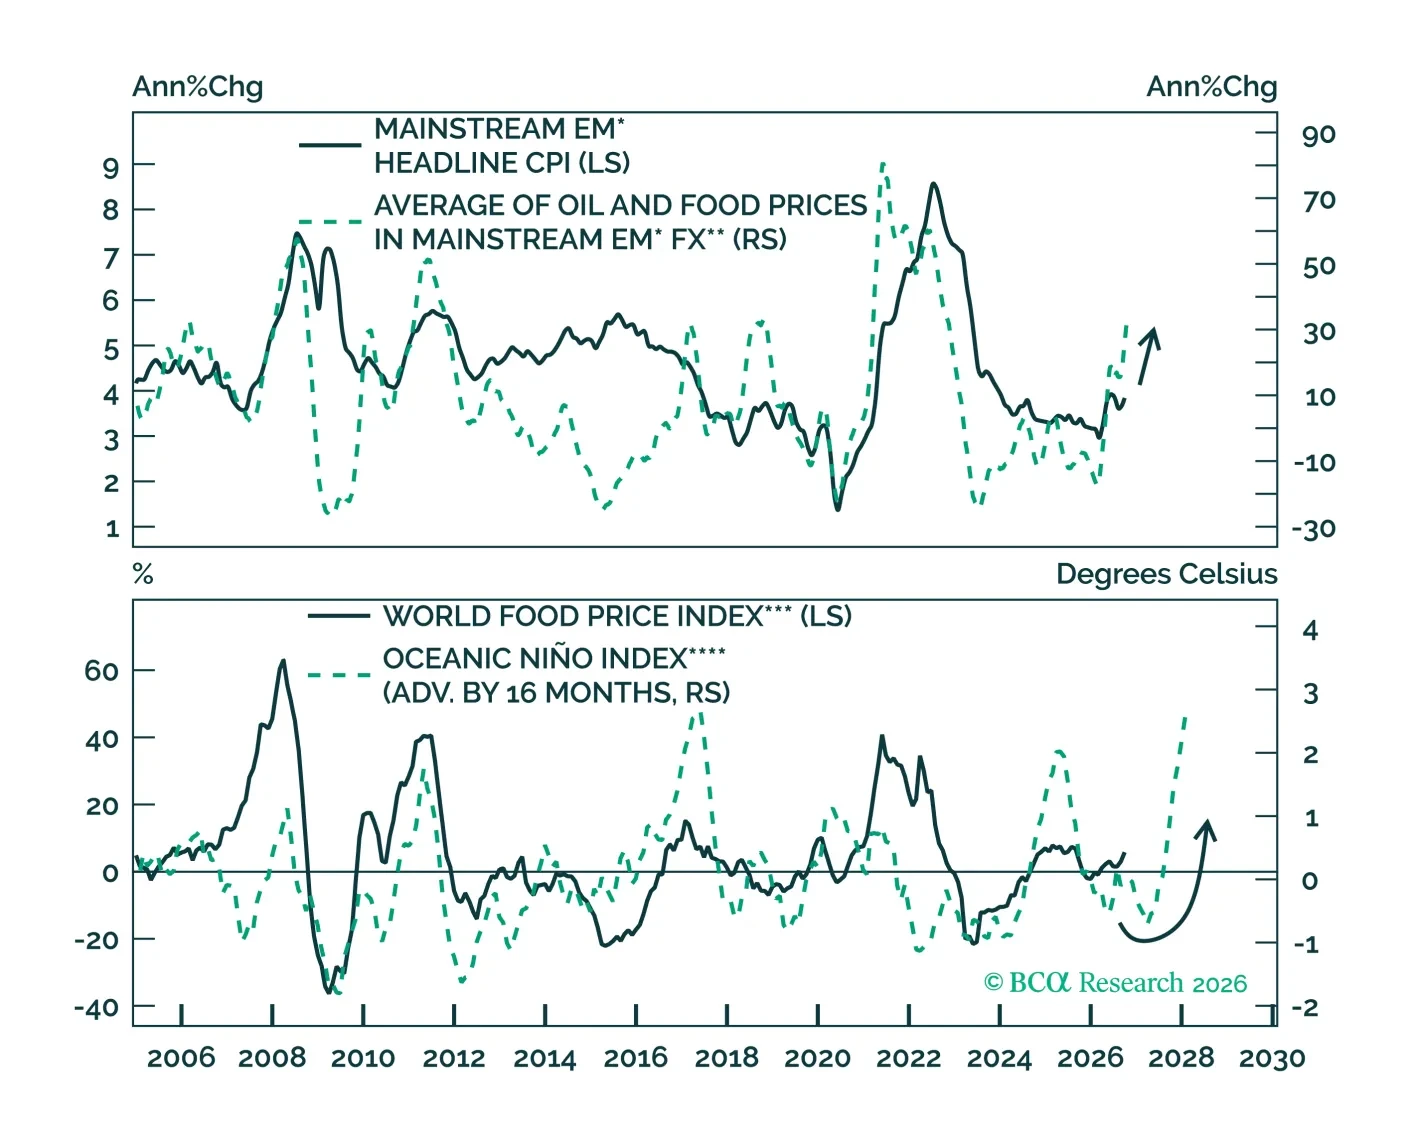
EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
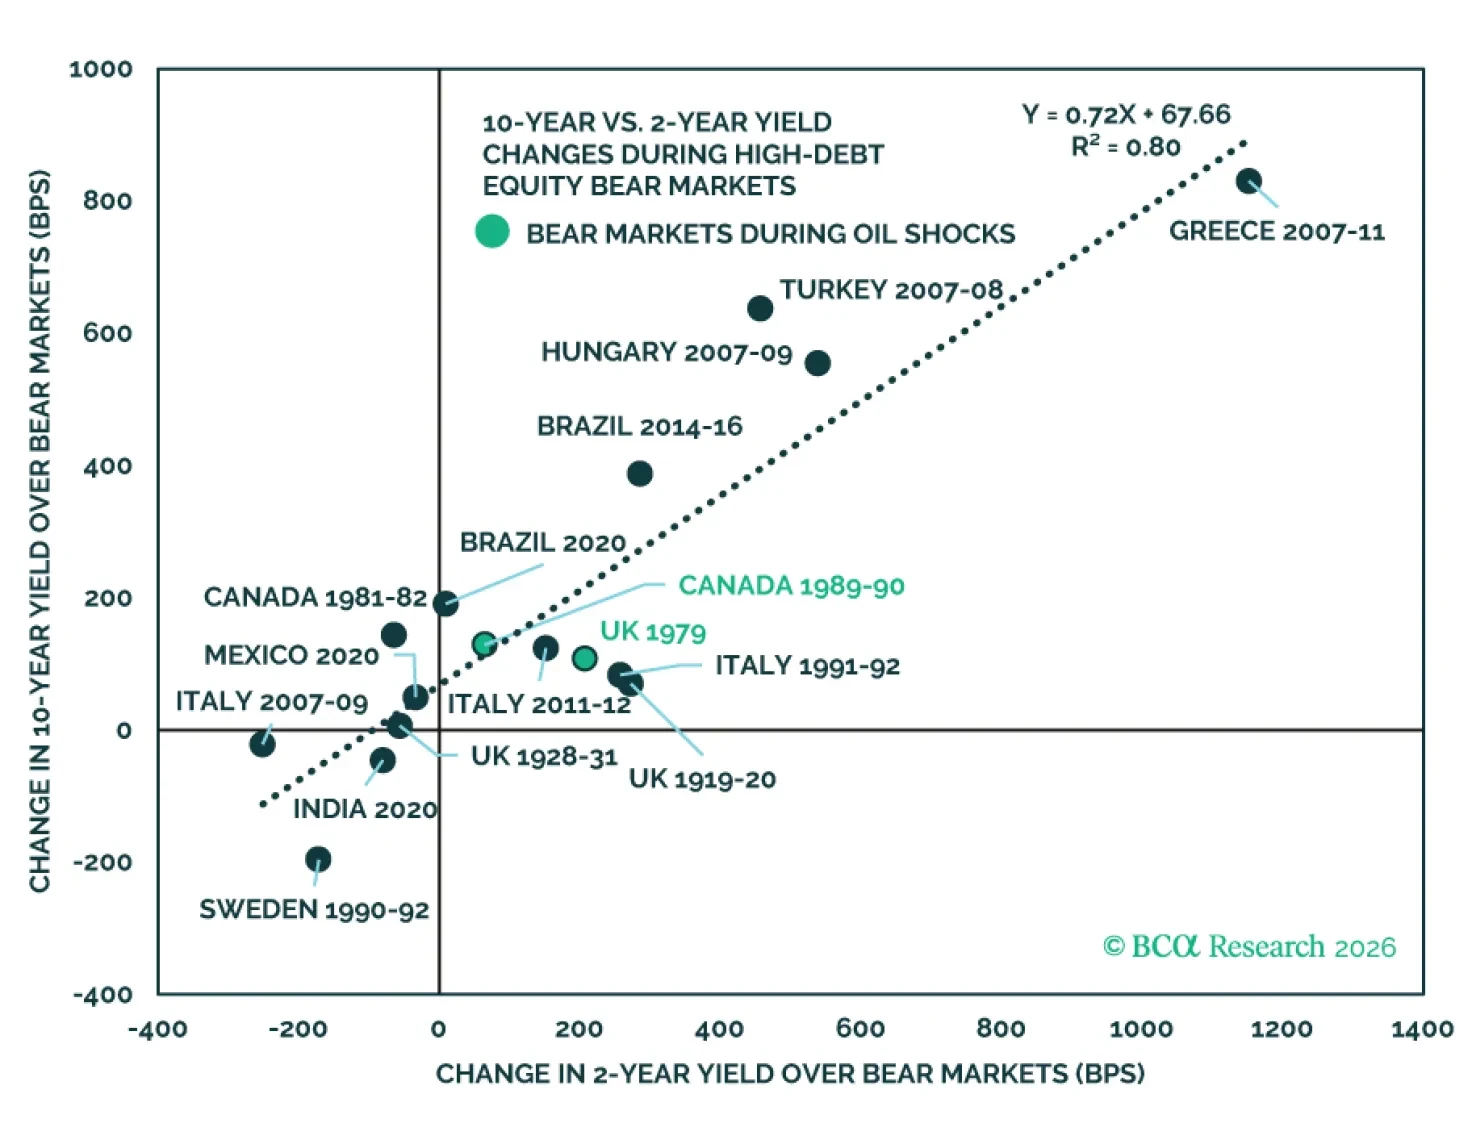
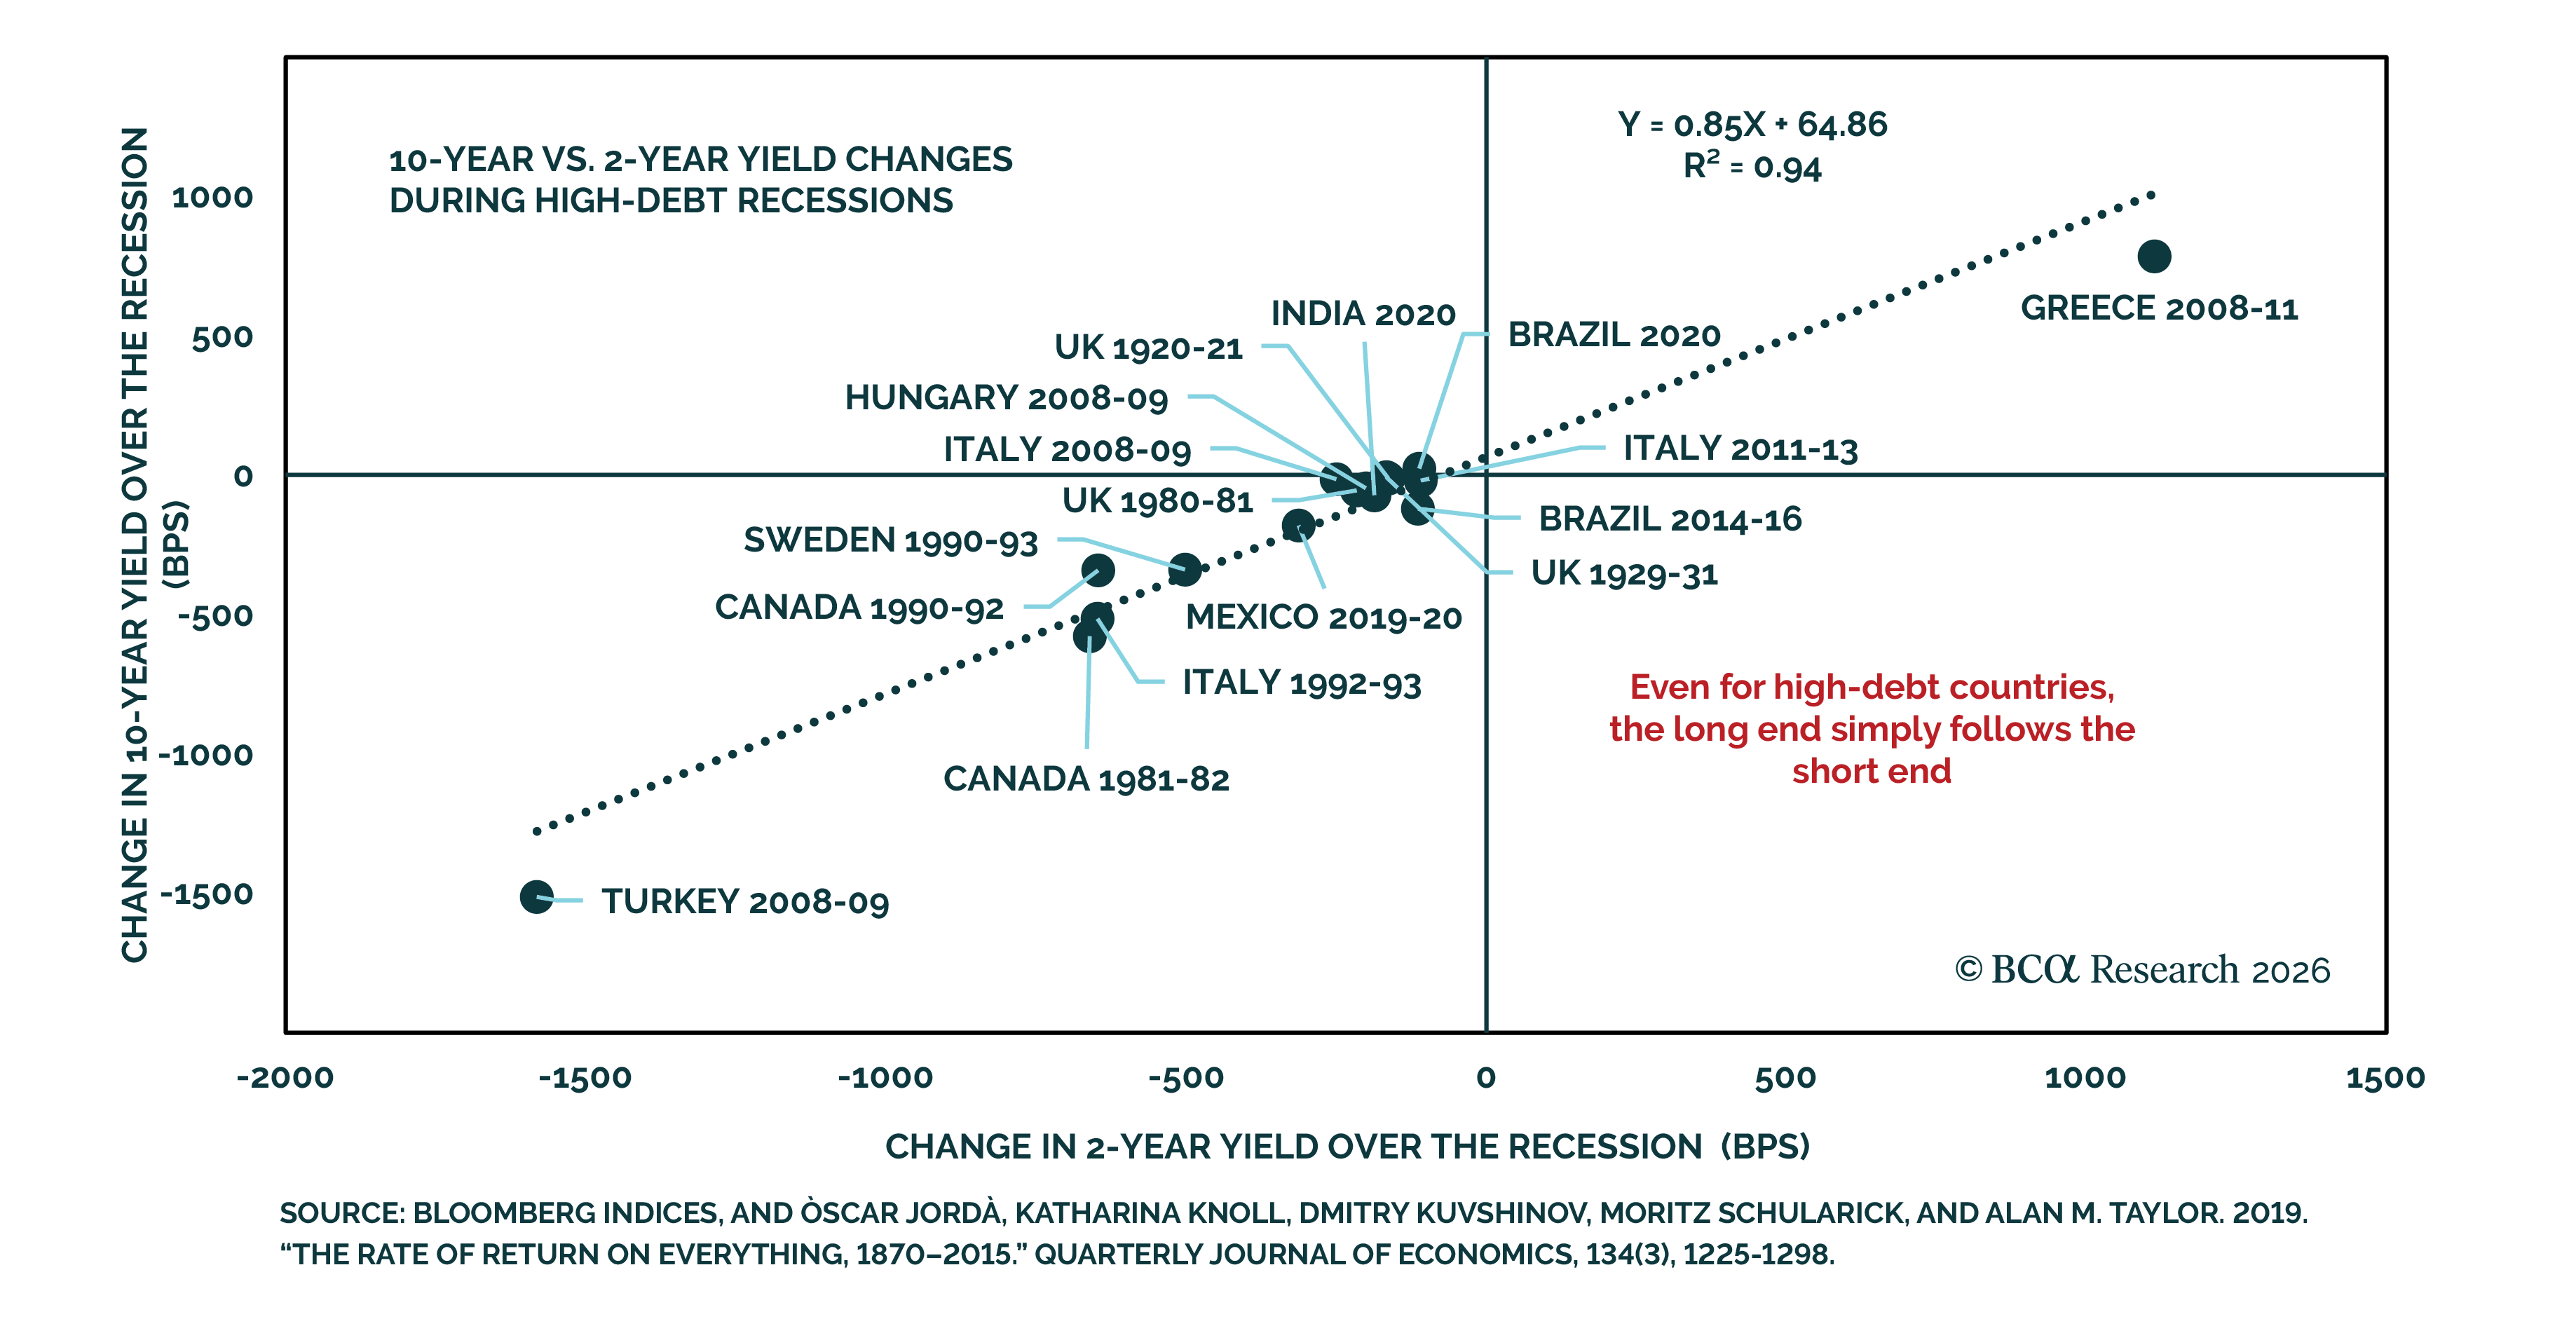
History suggests central bank policy determines how bonds behave in recessions, even for high-debt countries. The Fed should be able to cut into a slowdown, making Treasurys an effective equity hedge… for USD-based investors. Foreign investors will see currency depreciation erase their gains.
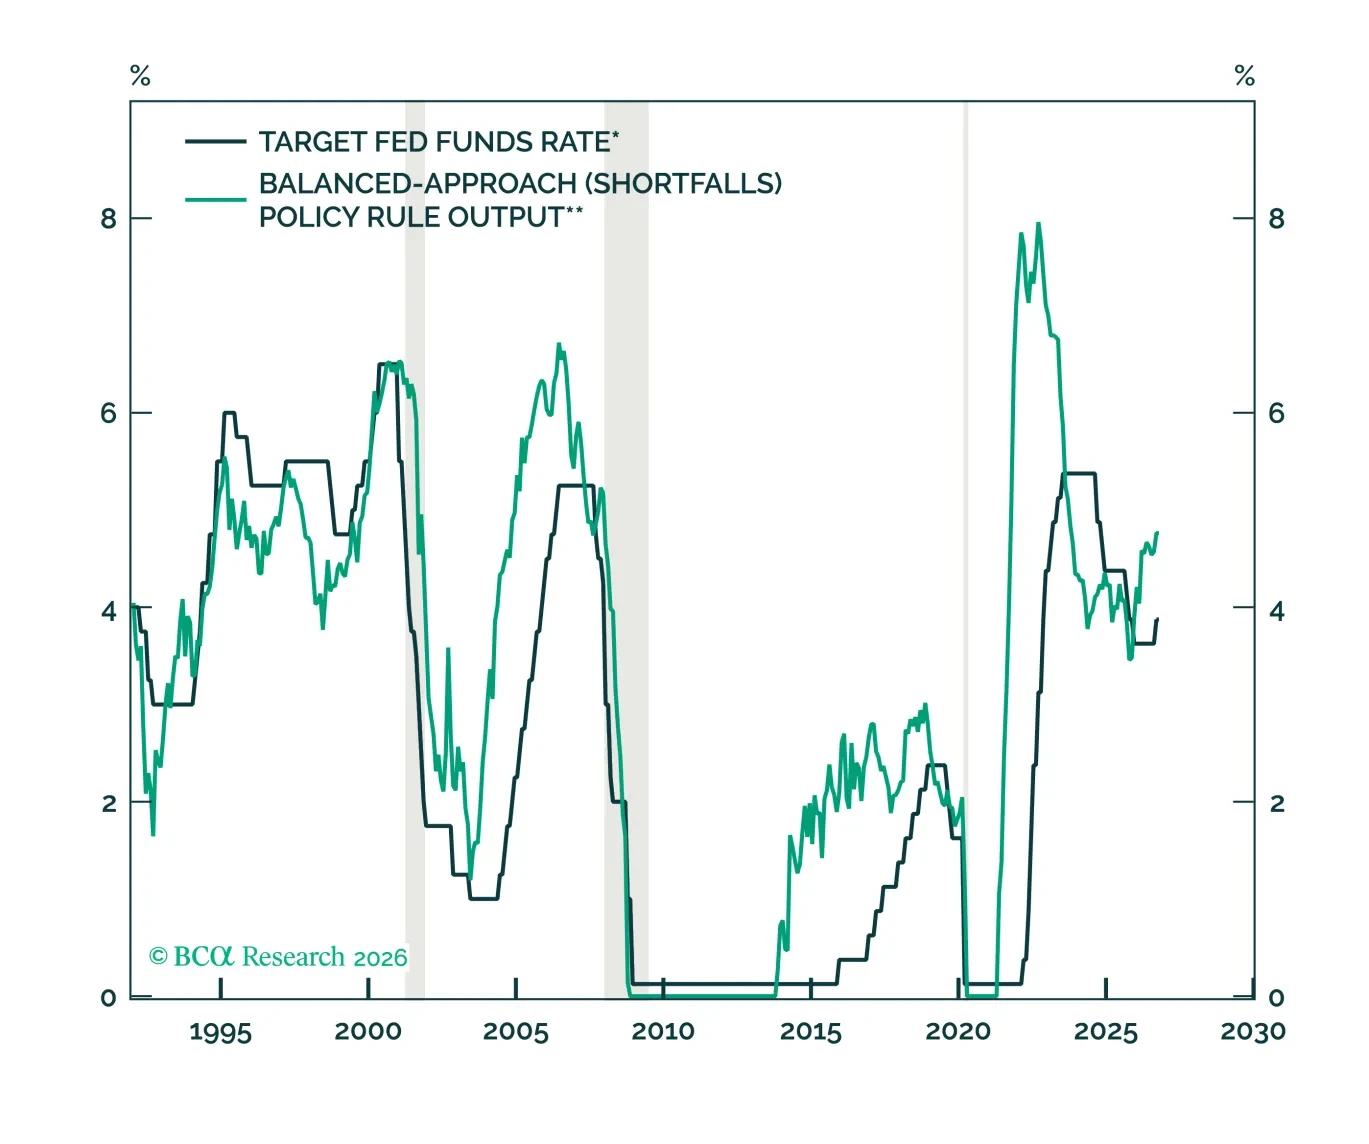
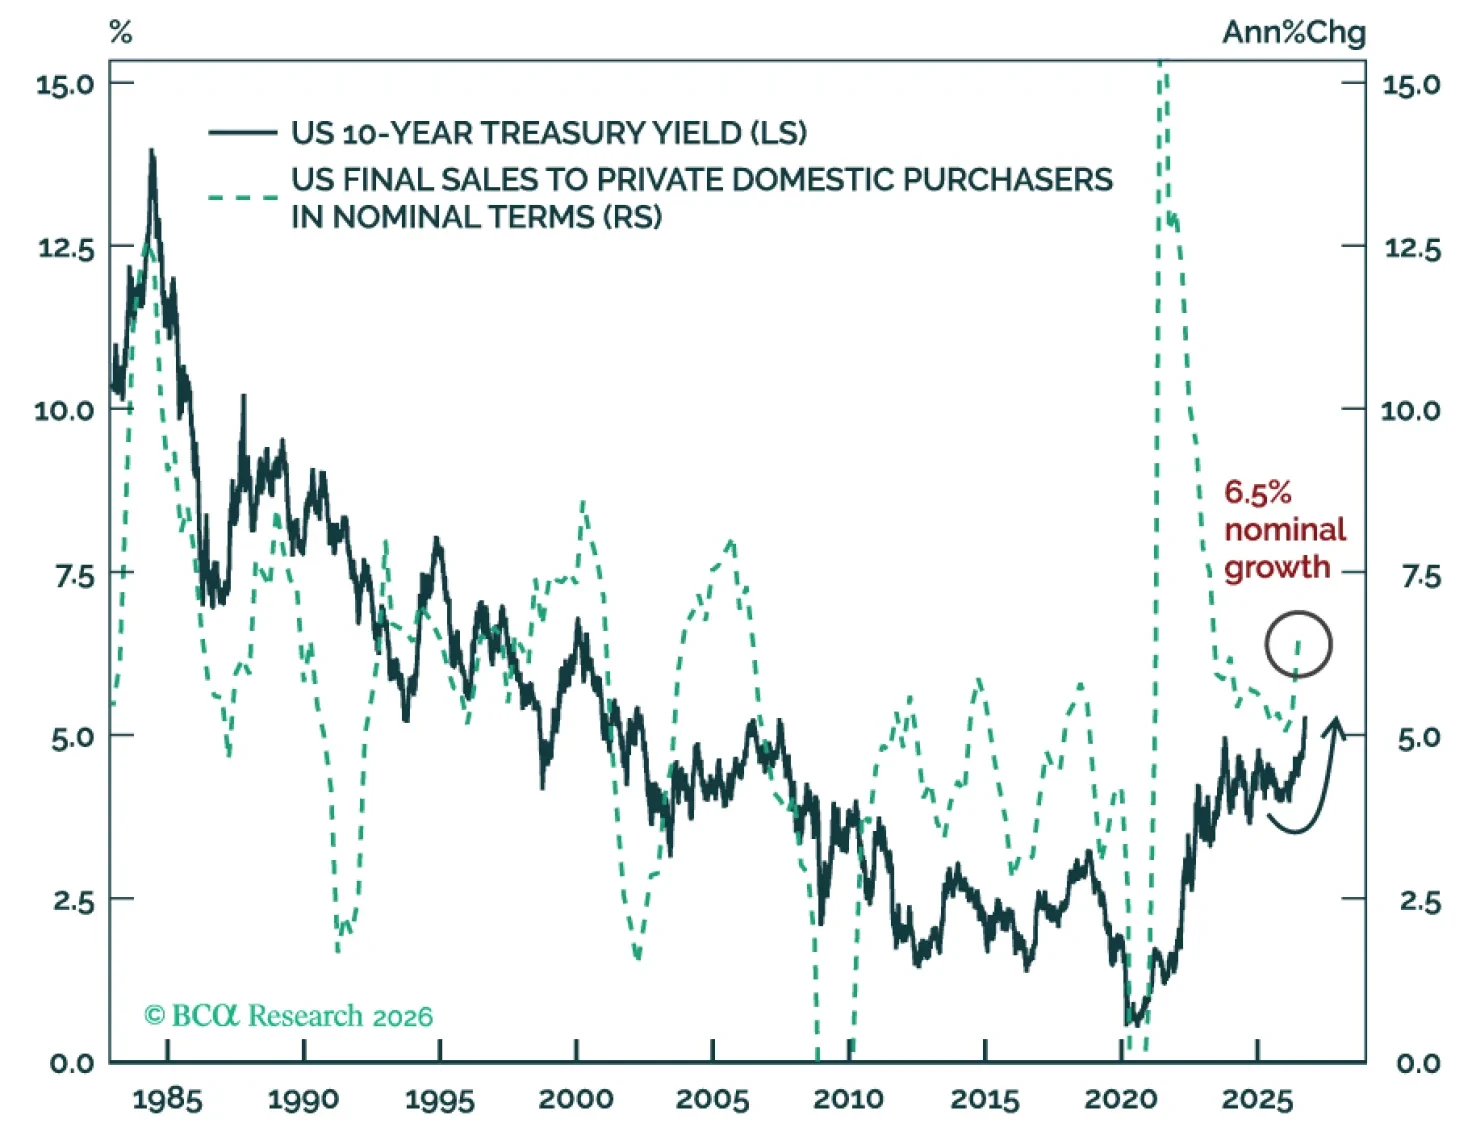
US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.
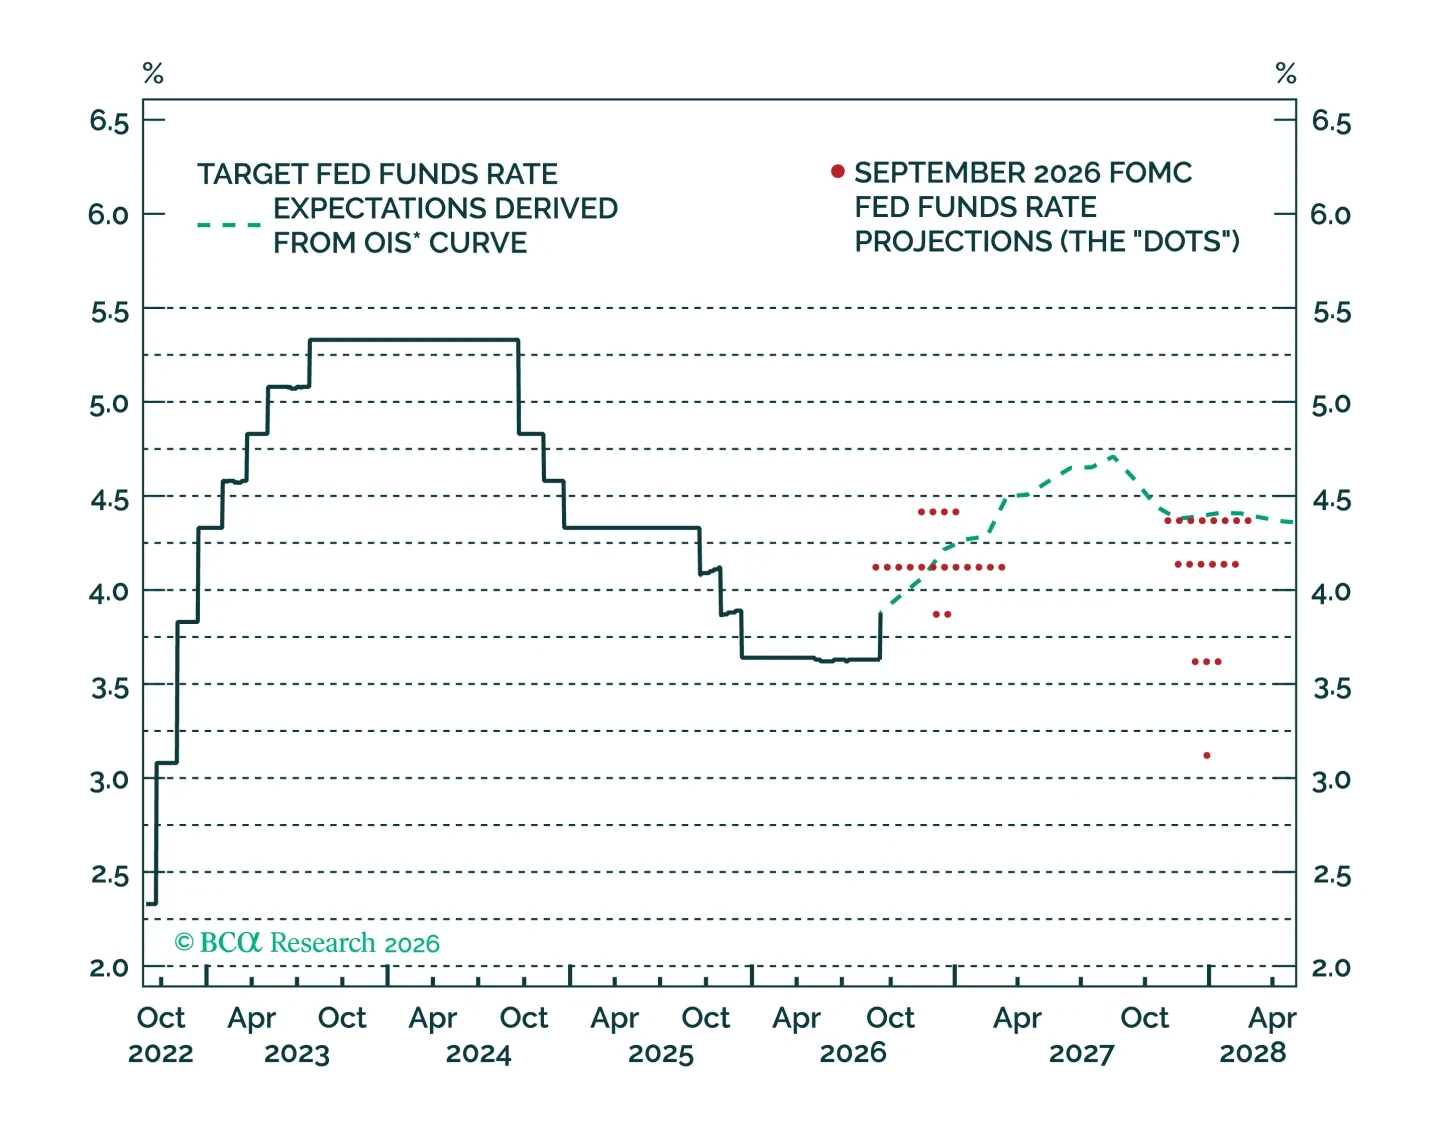
The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.
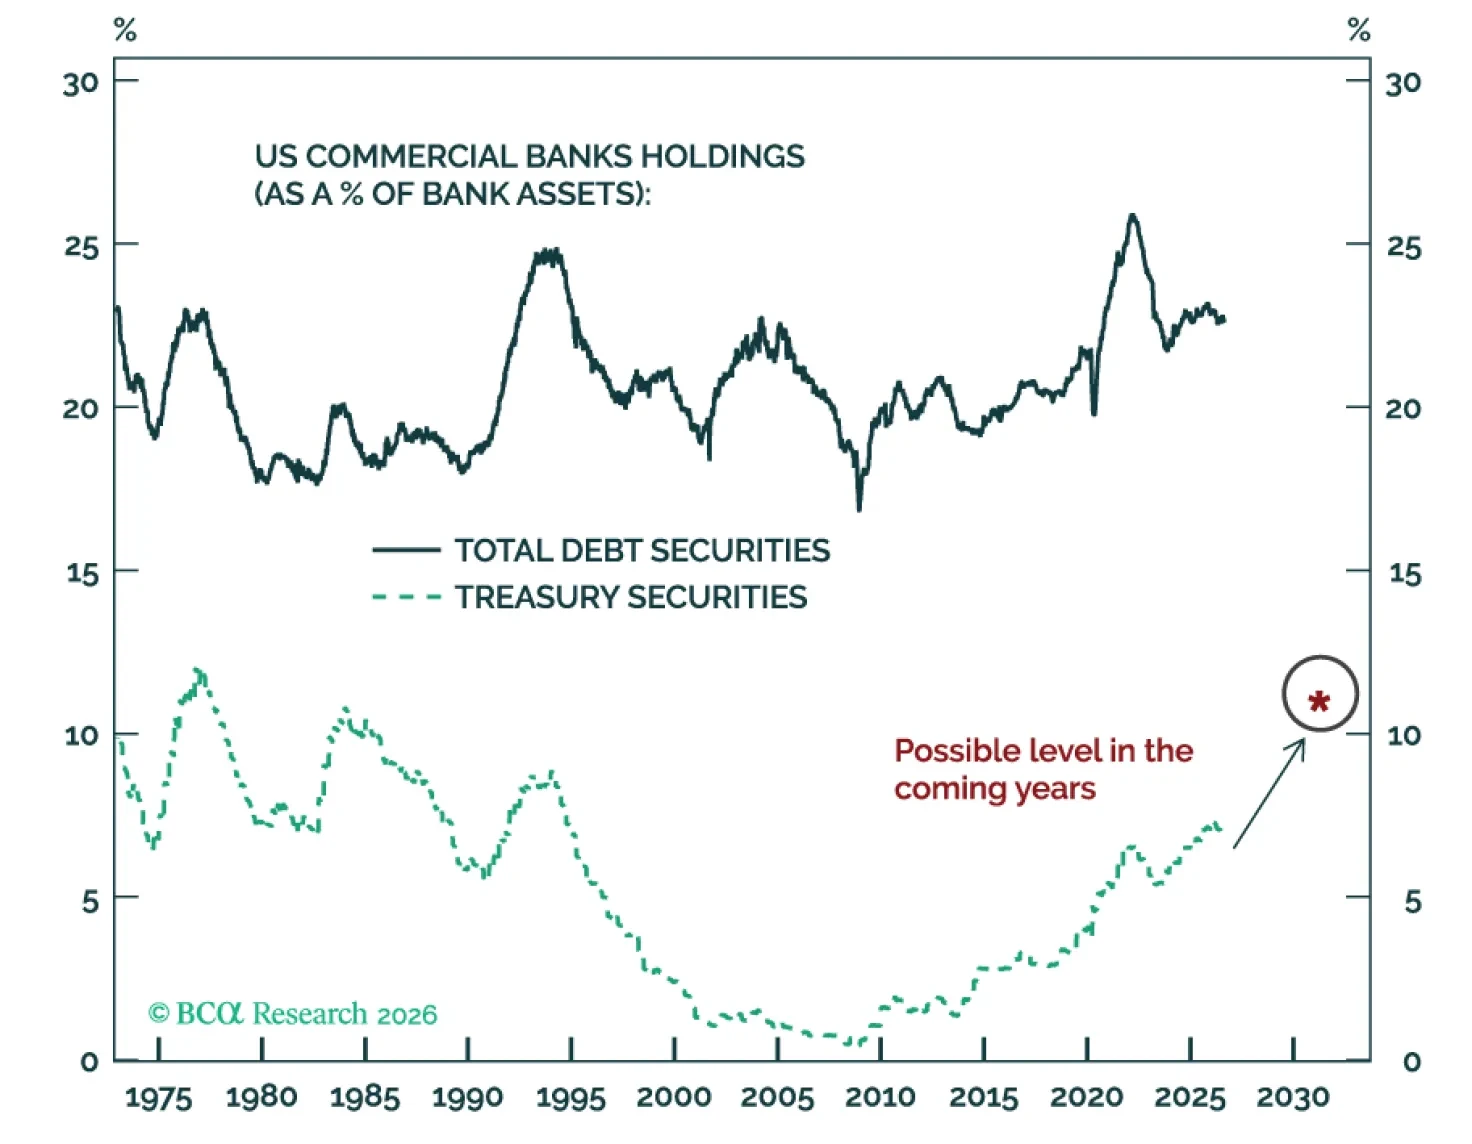
Scott Bessent’s attempts to suppress yields while financing large twin deficits risk crashing foreign inflows, the dollar, US bonds, and equities. Without a major equity selloff or large-scale commercial bank purchases of Treasurys, the bond selloff will persist – producing a major equity drawdown and a lower dollar.
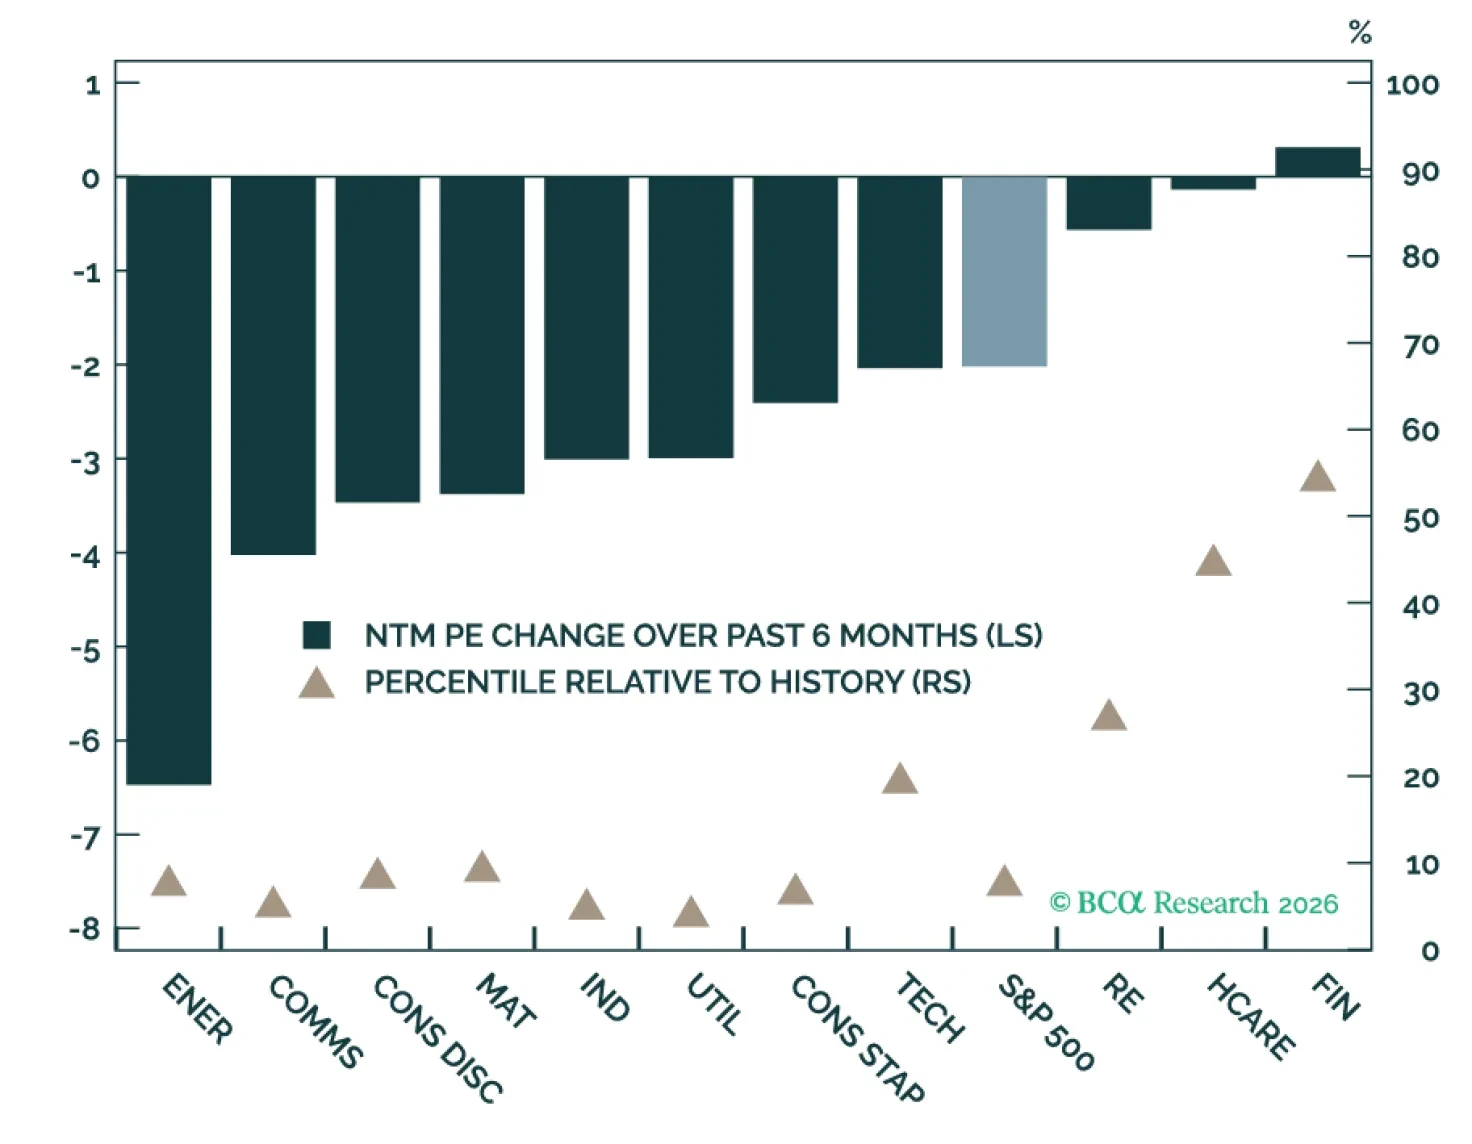
We remain constructive on US equities, but higher yields, slower EPS growth and heavy IPO issuance remain significant risks to valuations, leaving the path to our year-end target increasingly dependent on earnings. Tactically, there has already been a significant, but benign, compression in multiples, as earnings have outpaced prices. A well-communicated Fed hike could ease rather than intensify bond-market uncertainty.
