Fixed Income
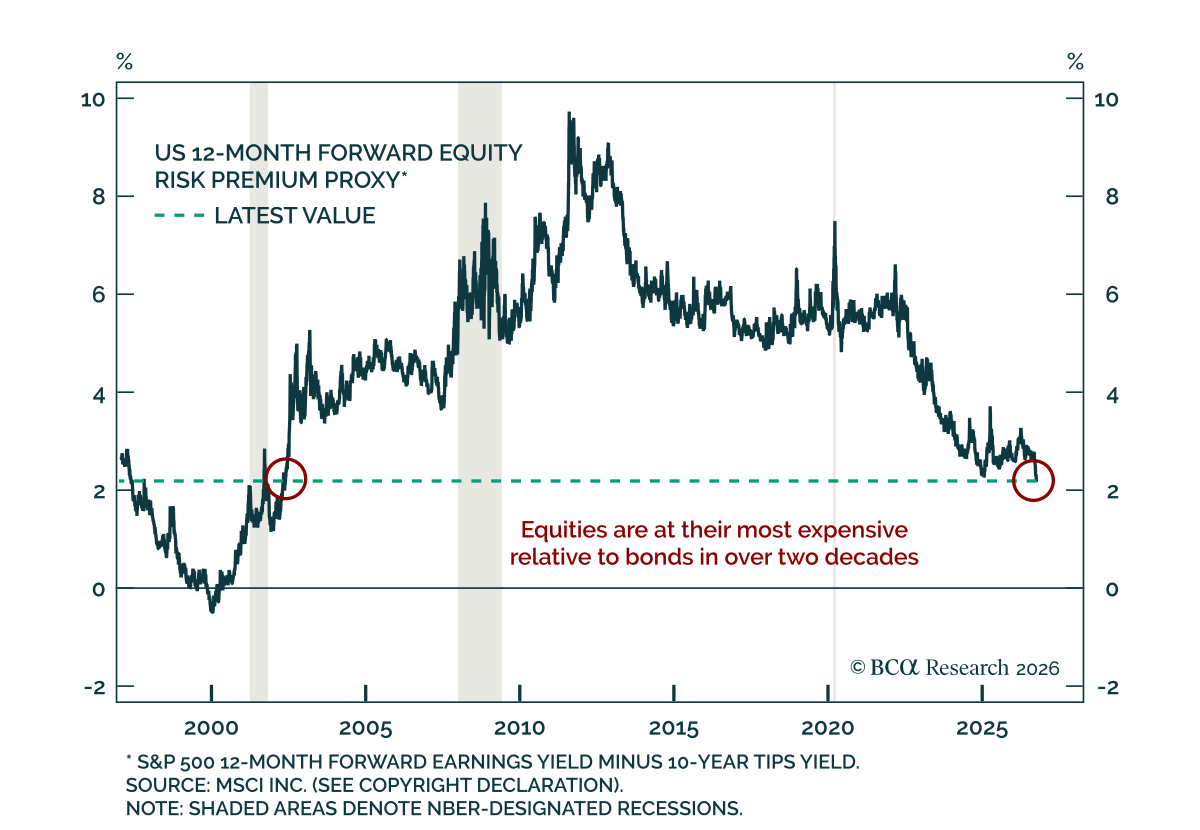
Relative to bonds, equities have become the most expensive in over two decades. Investors often examine P/E ratios in isolation, but equity valuations should take the prevailing level of bond yields into consideration. In a world with low risk-free rates of…
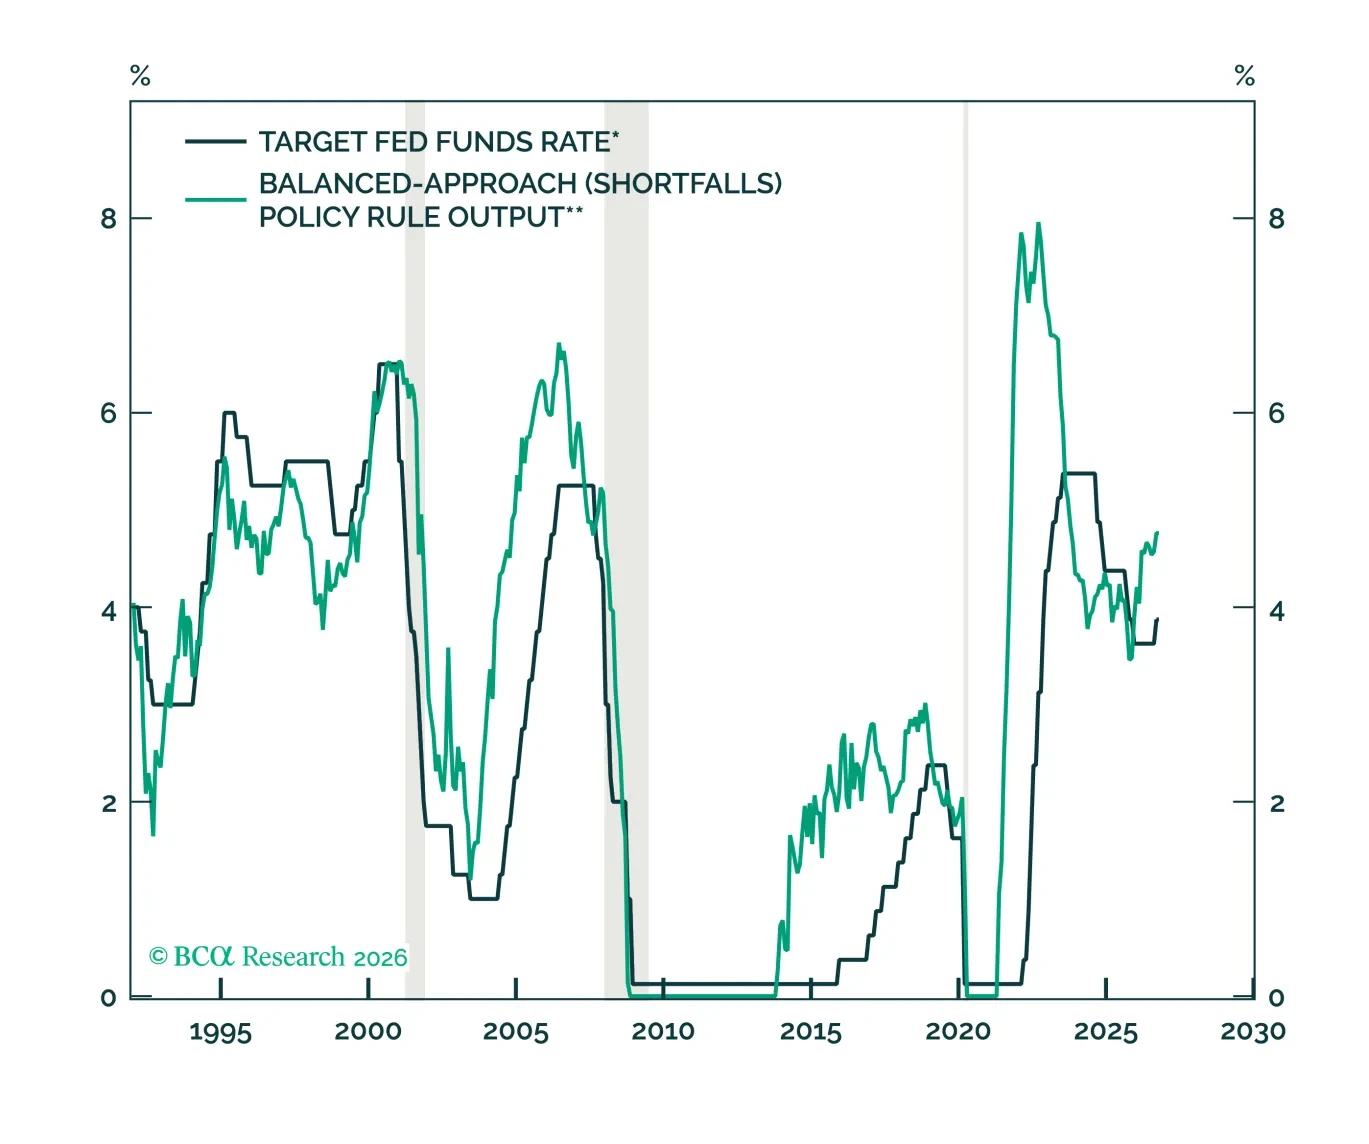
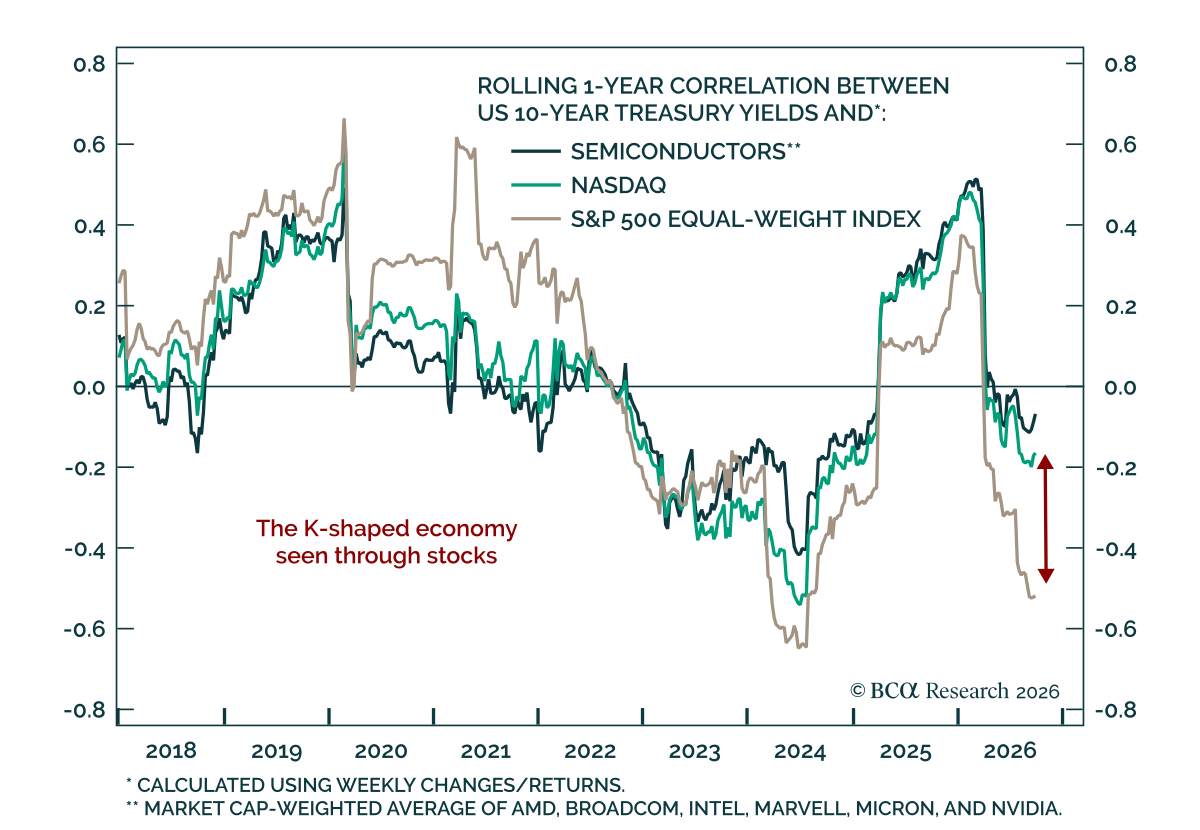
The relative resilience of tech-related stocks to higher rates, in the face of more sensitivity to yields felt by the average stock, reflects the K-shaped dynamics in the real economy. Many investors have noted that US equities have been surprisingly…
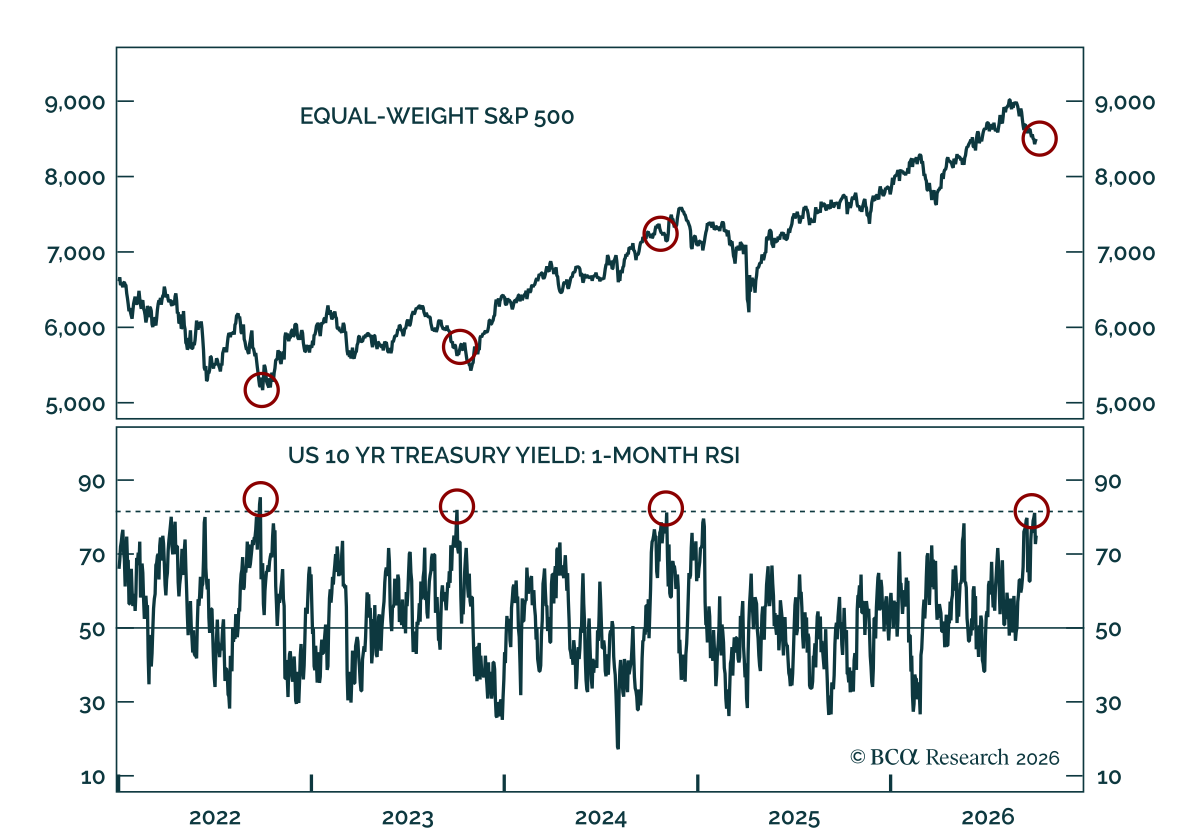
The ongoing bond selloff is becoming long in the tooth. Both stocks and bonds should experience a tactical rally into year’s end, but risks remain heading into next year. Treasury bonds are now deeply oversold, with the monthly relative strength index for the…
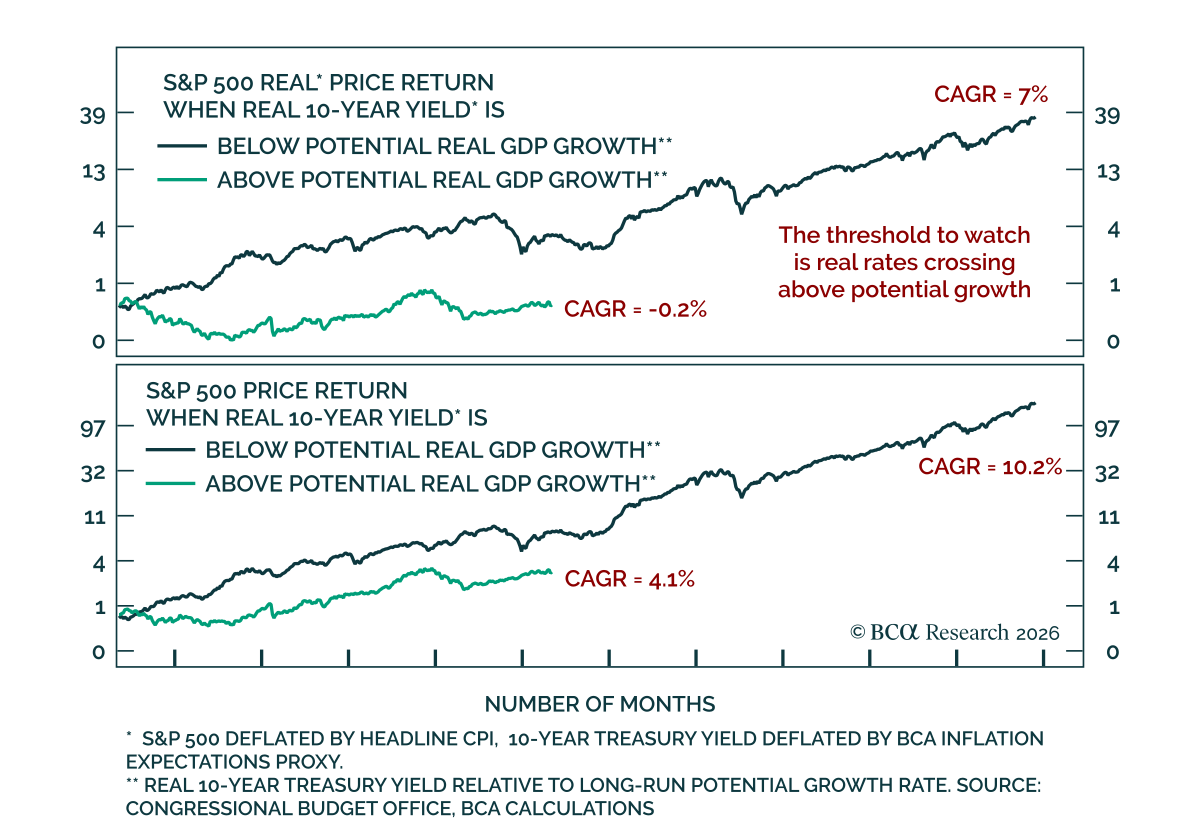
Our US investment strategists argue that the tipping point for equities lies not in the direction or absolute level of bond yields, but in real yields’ relation to the economy's underlying growth rate. Duration is a red herring for equities because the…
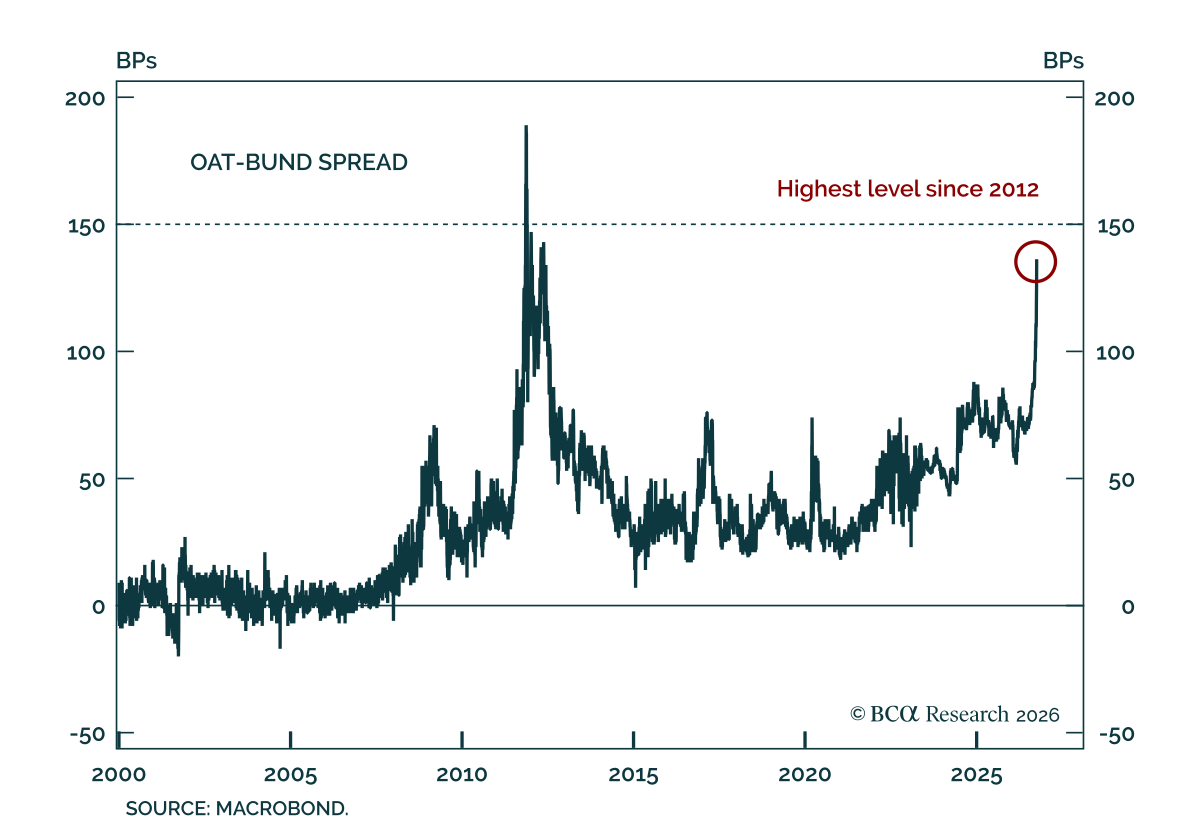
The OAT-Bund spread has widened sharply in recent weeks, reaching 150 bps last Friday, before falling back towards 140 bps. The drivers are homegrown: rising concerns about the fiscal outlook and the political uncertainty surrounding the upcoming presidential…
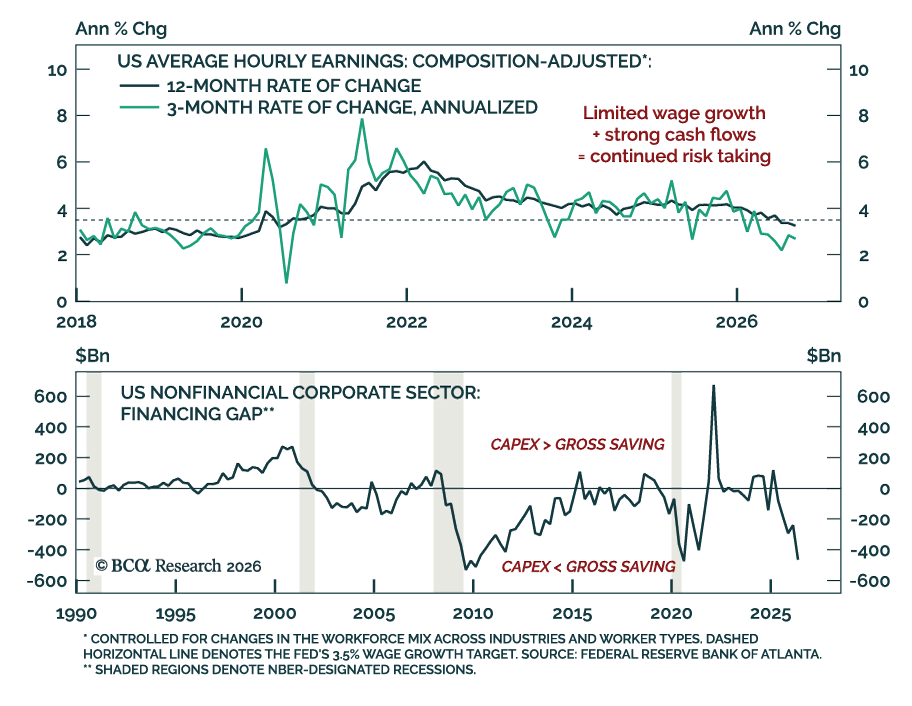
Our FICC strategists recommend staying long risk, holding neutral duration, and fading volatility spikes over the next six to nine months. While worries keep piling up, spanning politics, wars, higher yields, and doubts about AI, our colleagues argue the one…
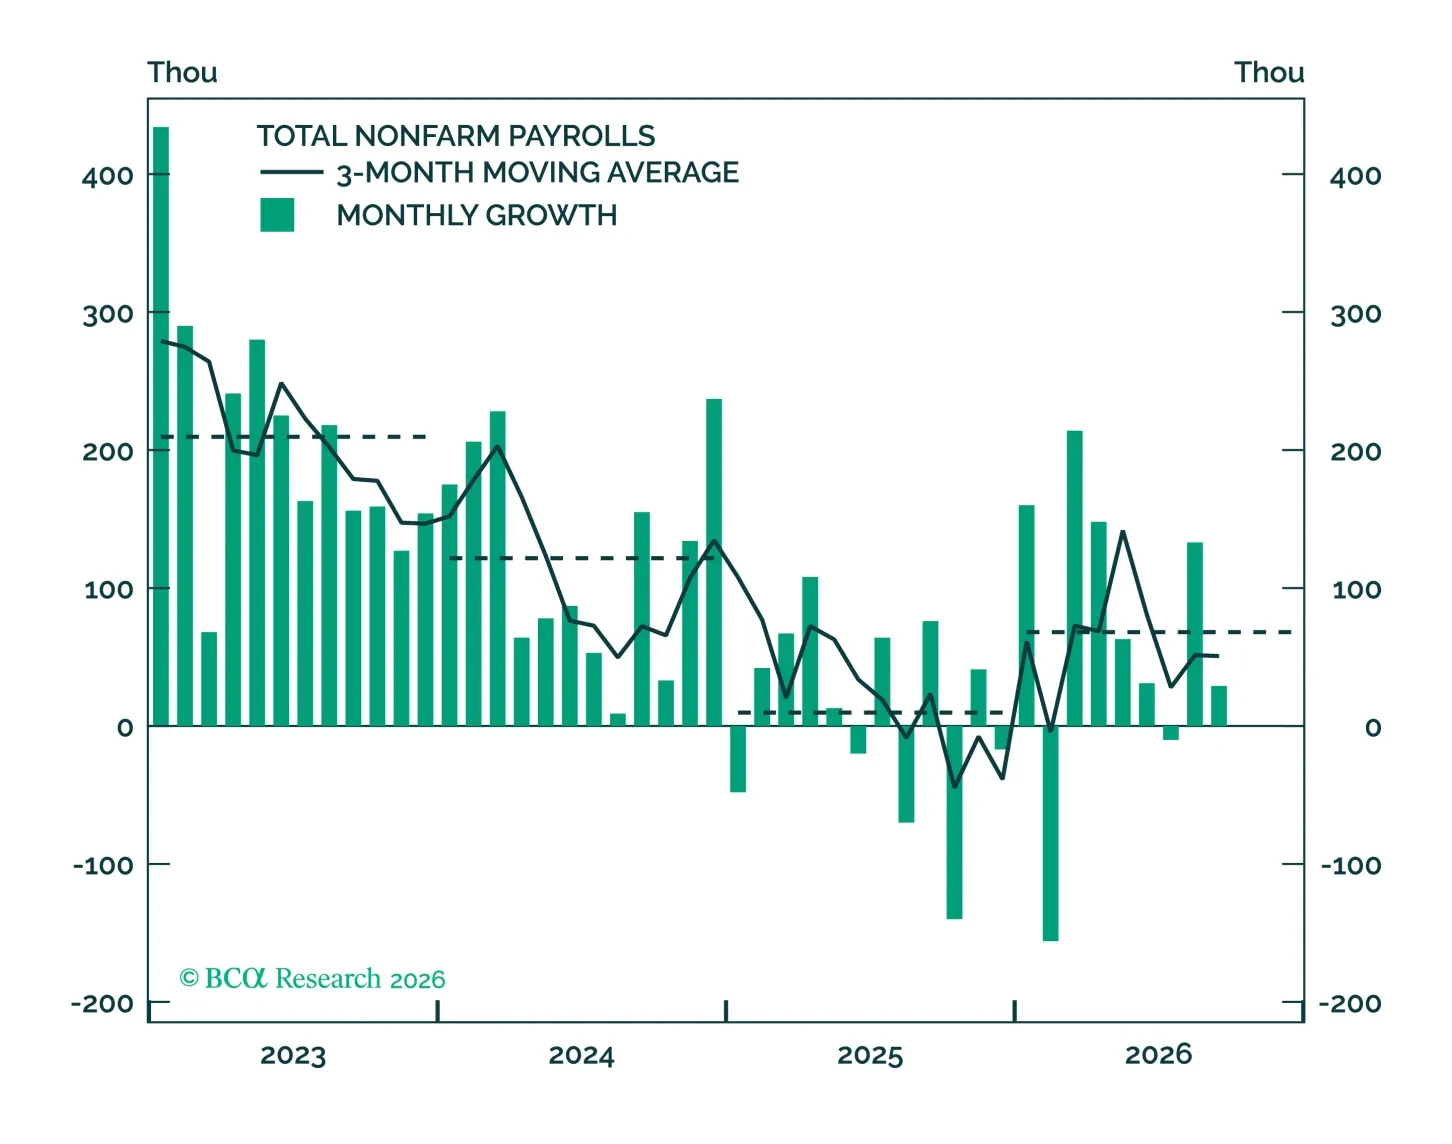
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
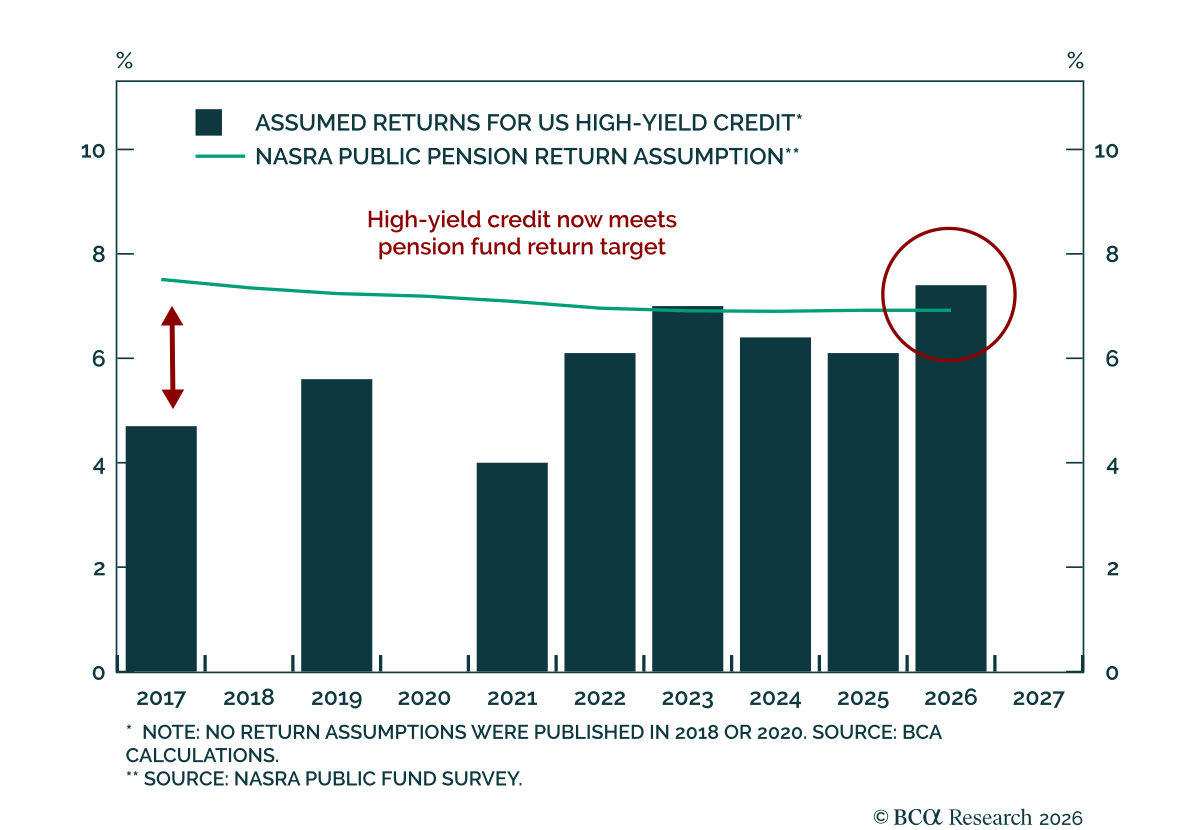
Our Portfolio Construction strategists maintain their overweight to high-yield credit, both within their public asset allocation and versus Private Credit. Higher government bond yields have reset the opportunity set. BCA's capital market assumptions project…
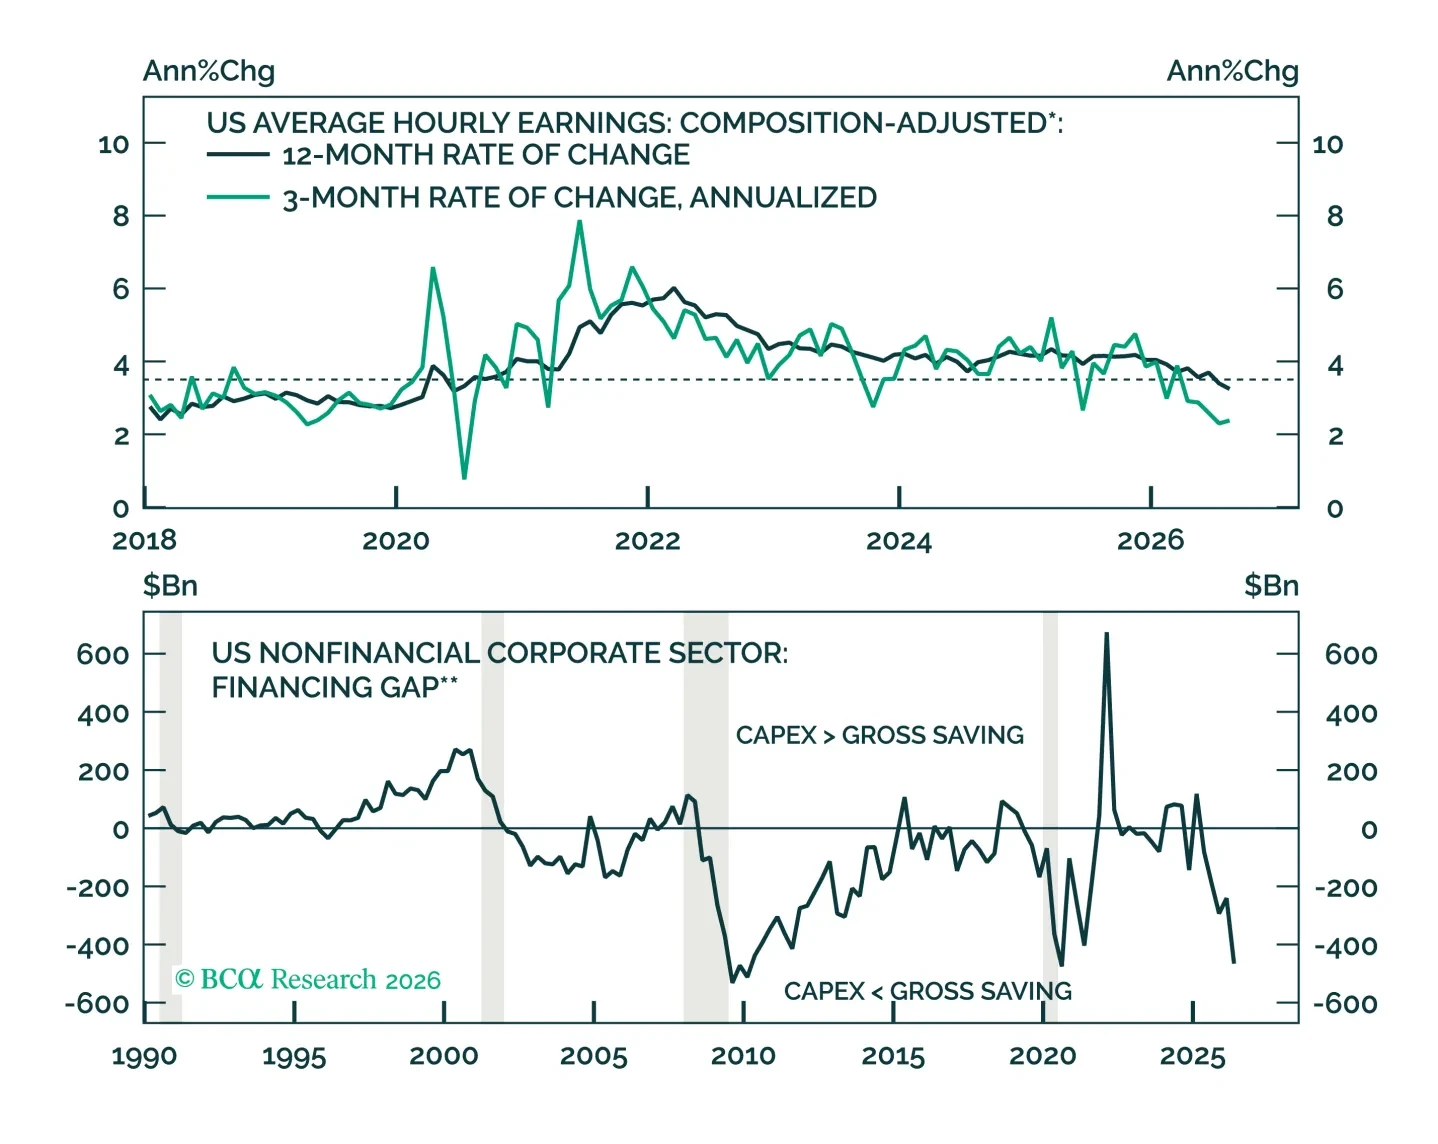
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.