Skip to main content

Equities

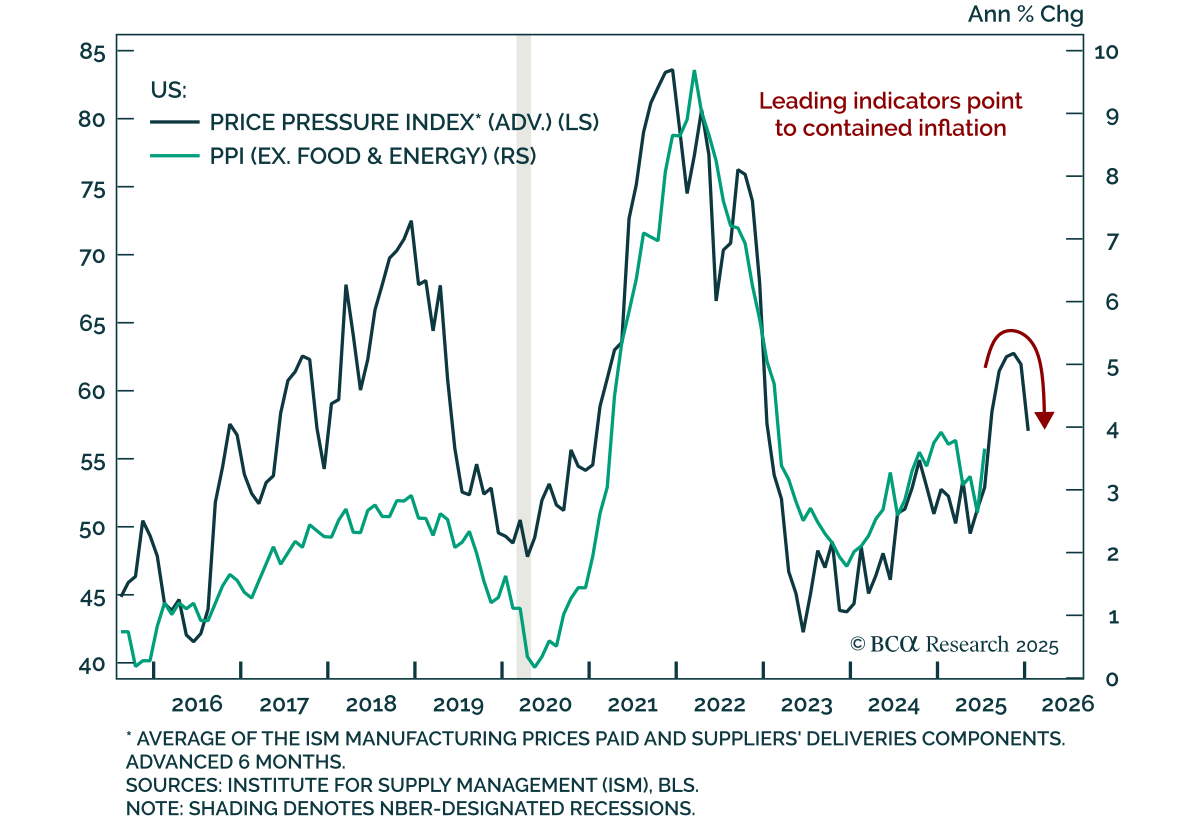
July PPI surprised sharply to the upside, but inflation pressures are likely to remain limited. Headline PPI rose 0.9% m/m (3.3% y/y) in July from 0.0% m/m (2.3% y/y) in June, while core PPI gained 0.6% m/m (2.8% y/y). PPI components feeding into PCE…
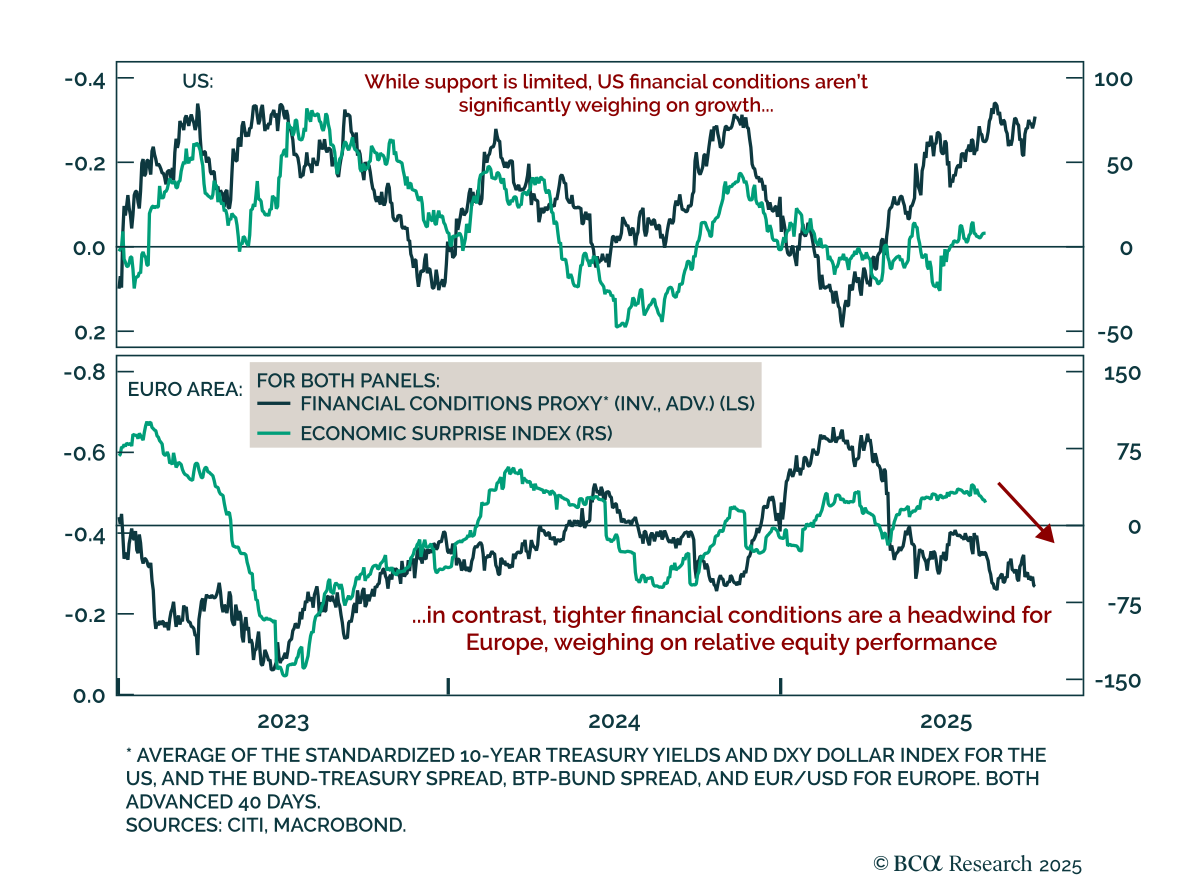
Dollar softness has had little growth impact, and European equities should keep lagging. A key 2025 trend has been USD depreciation, but the associated easing in financial conditions has offered minimal support to US growth, reflecting higher term premia…
Special Report

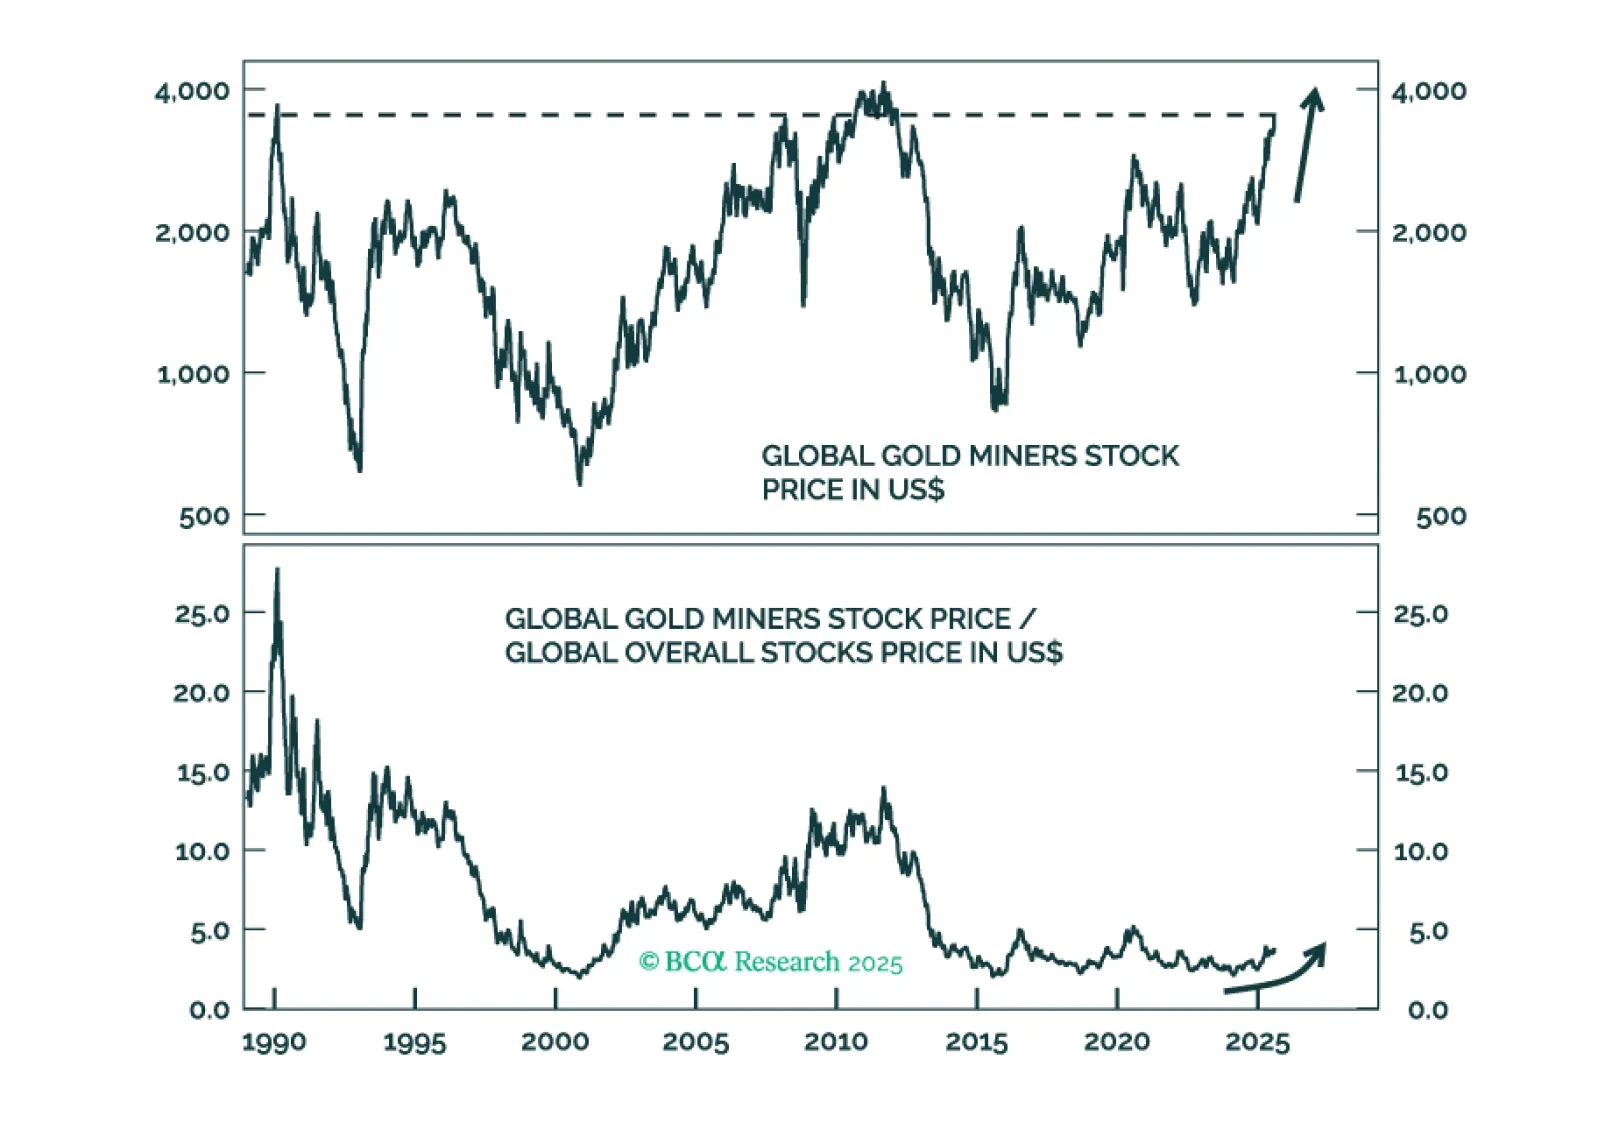
The fact that the yellow metal’s rally has defied headwinds from key cyclical drivers suggests that the bull market is structural, not cyclical. Buy gold and gold mining stocks in absolute and relative terms.
Special Report

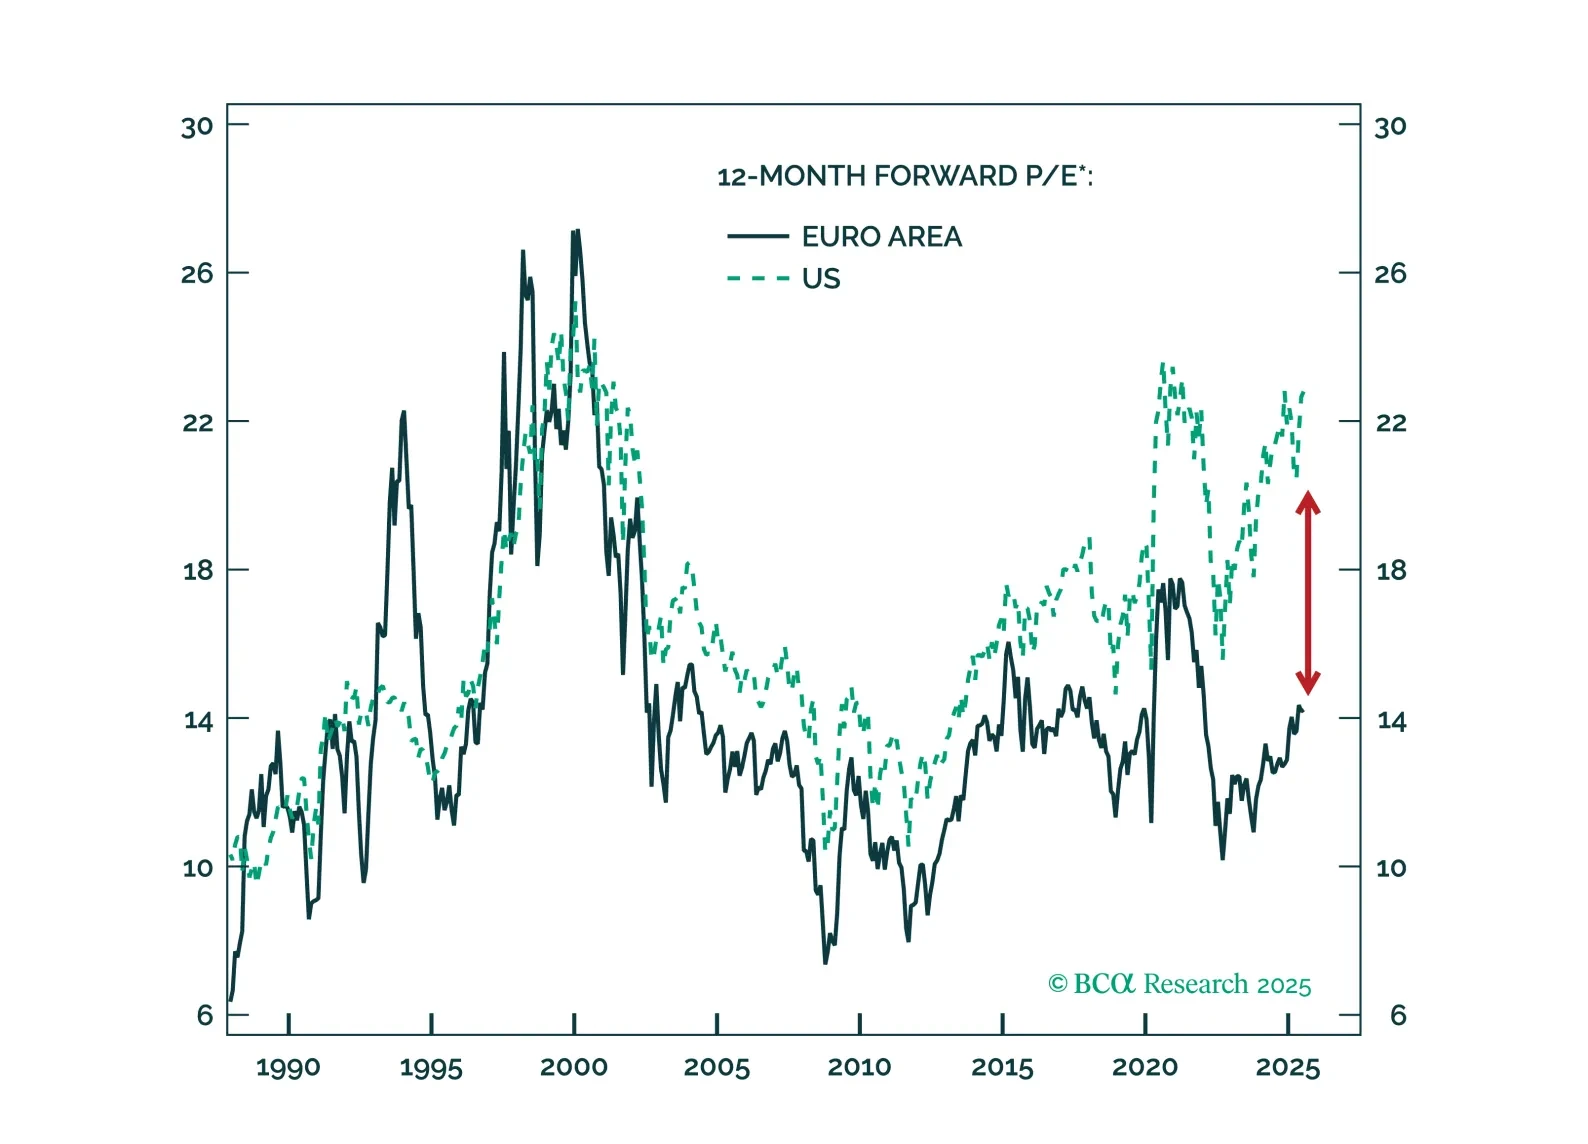
The outlook for European equities is becoming more appealing relative to US equities. Many structural headwinds are fading in Europe, and valuations remain historically cheap. Investors should position accordingly to benefit from the region’s cyclical rerating.
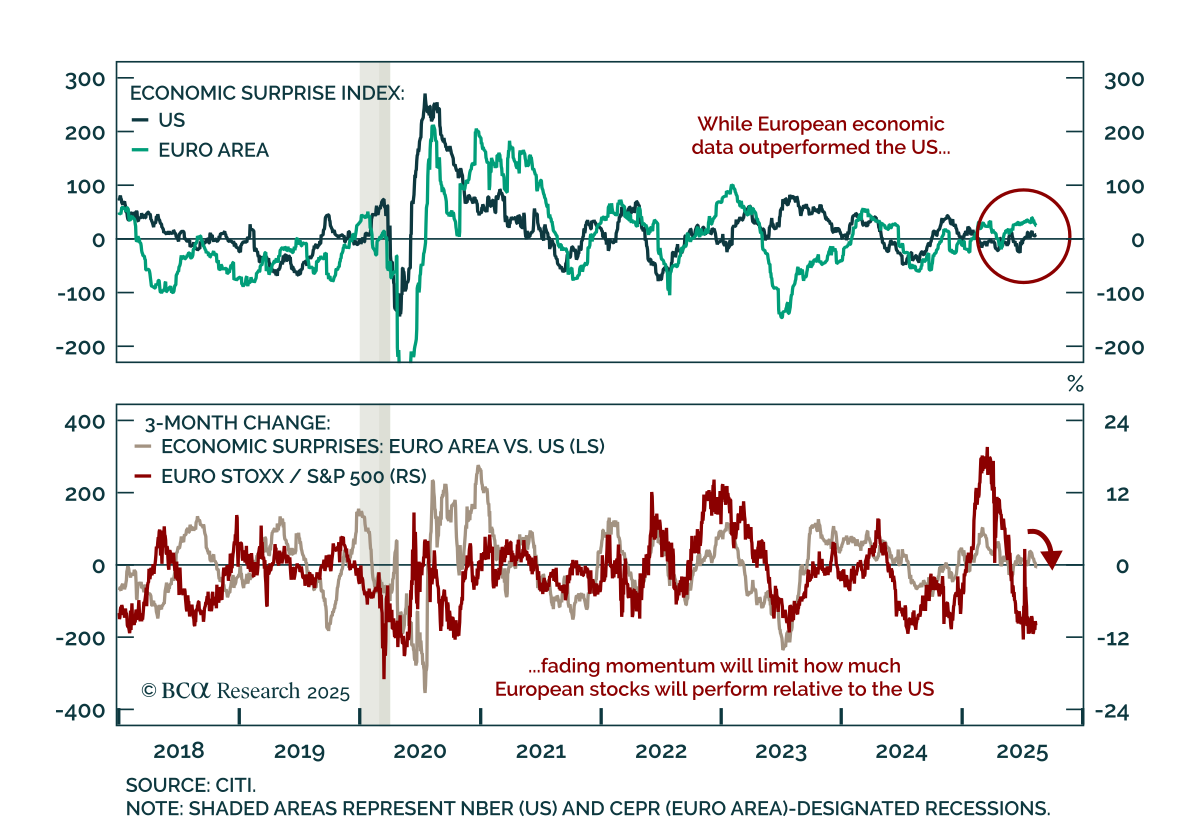
US equities are set for tactical outperformance versus Europe, but dips or underperformance in European assets remain entry points for long-term investors. European stocks have stalled below prior highs, while the S&P 500 has rebounded to record levels after…
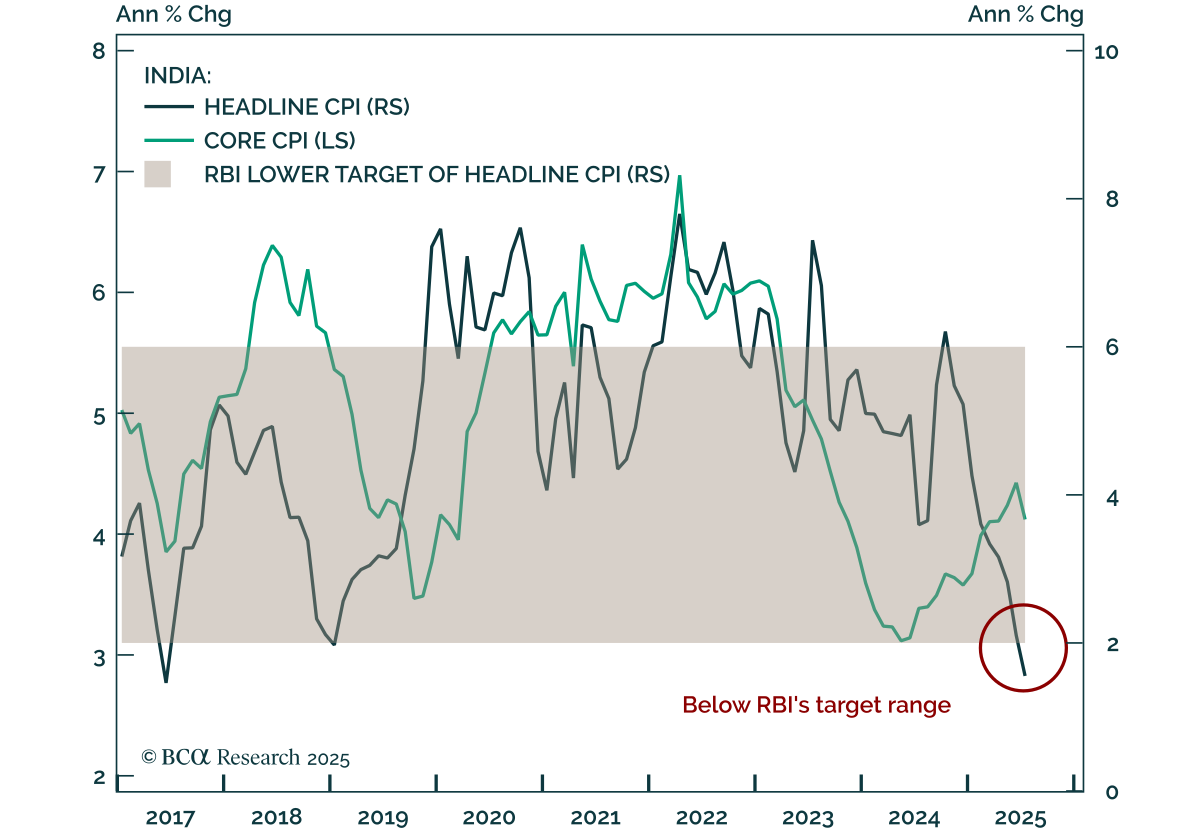
India’s sharp CPI undershoot will bring forward rate cuts, supporting a long on local bonds. Headline CPI fell to 1.55%, well below the RBI’s 2-6% target range, pointing to earlier and deeper easing than markets price. Our Emerging Markets strategists have…
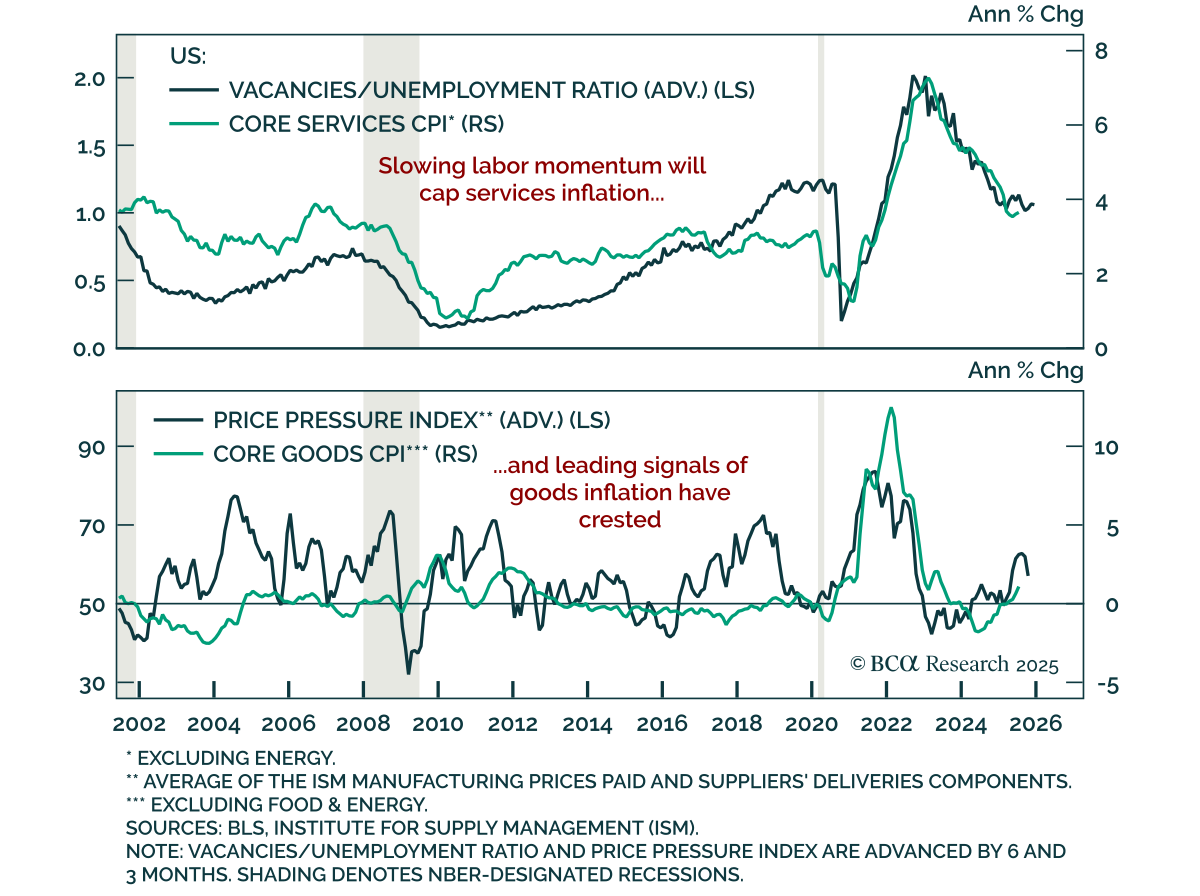
July US CPI met expectations as leading indicators point to disinflation, supporting our long duration stance and preference for 2s5s steepeners. Headline CPI rose 0.2% m/m (2.7% y/y), while core increased 0.3% m/m and accelerated to 3.1% y/y. Both goods and…
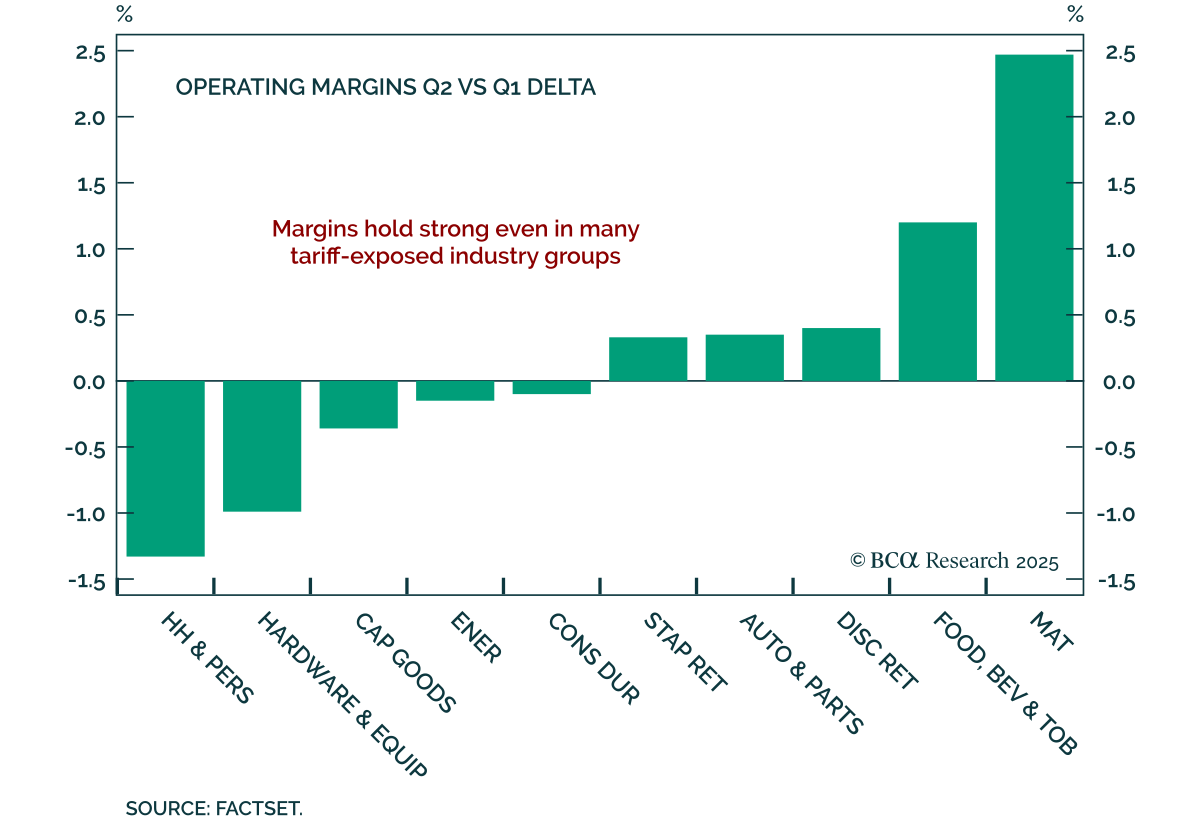
Our US Equity strategists view Q2 earnings as confirmation of corporate resilience, but caution that the full impact of tariffs is still ahead. Strong results show that companies have weathered tariff-related costs through effective mitigation strategies,…

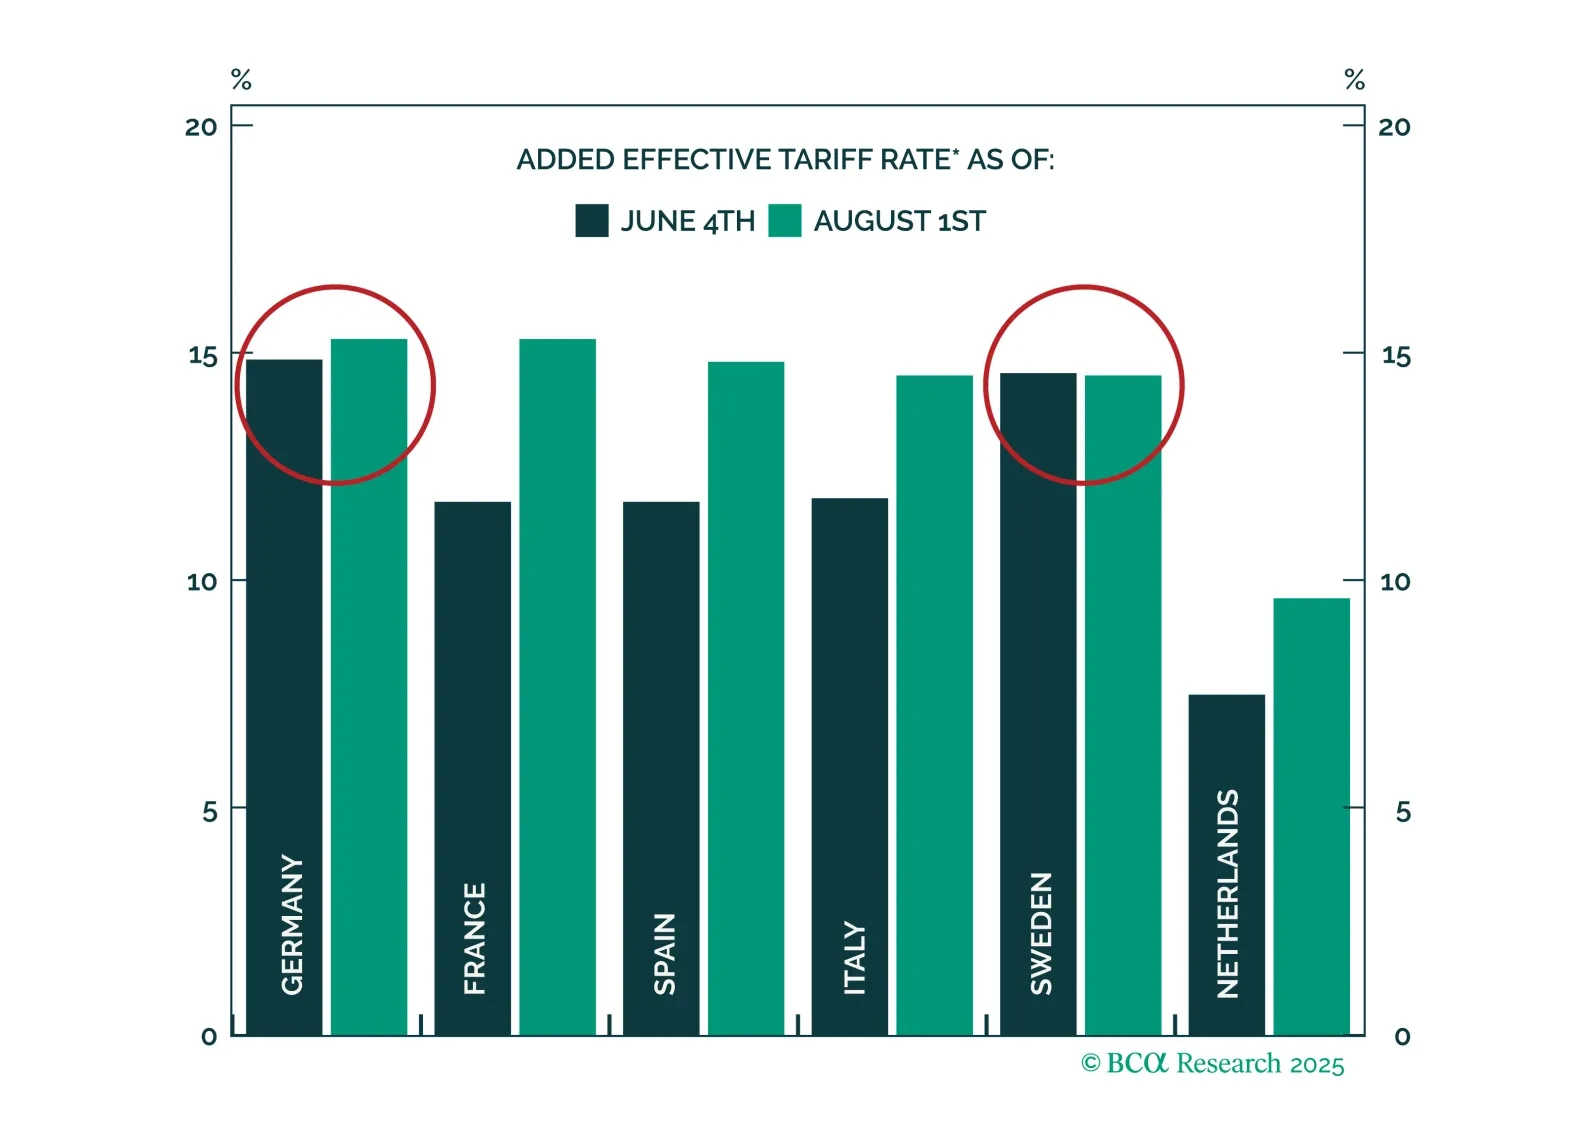
US tariffs will not derail the low-inflation economic recovery underway in the Euro Area. Investors should overweight European equities, focusing on parts of the market more insulated from tariffs.
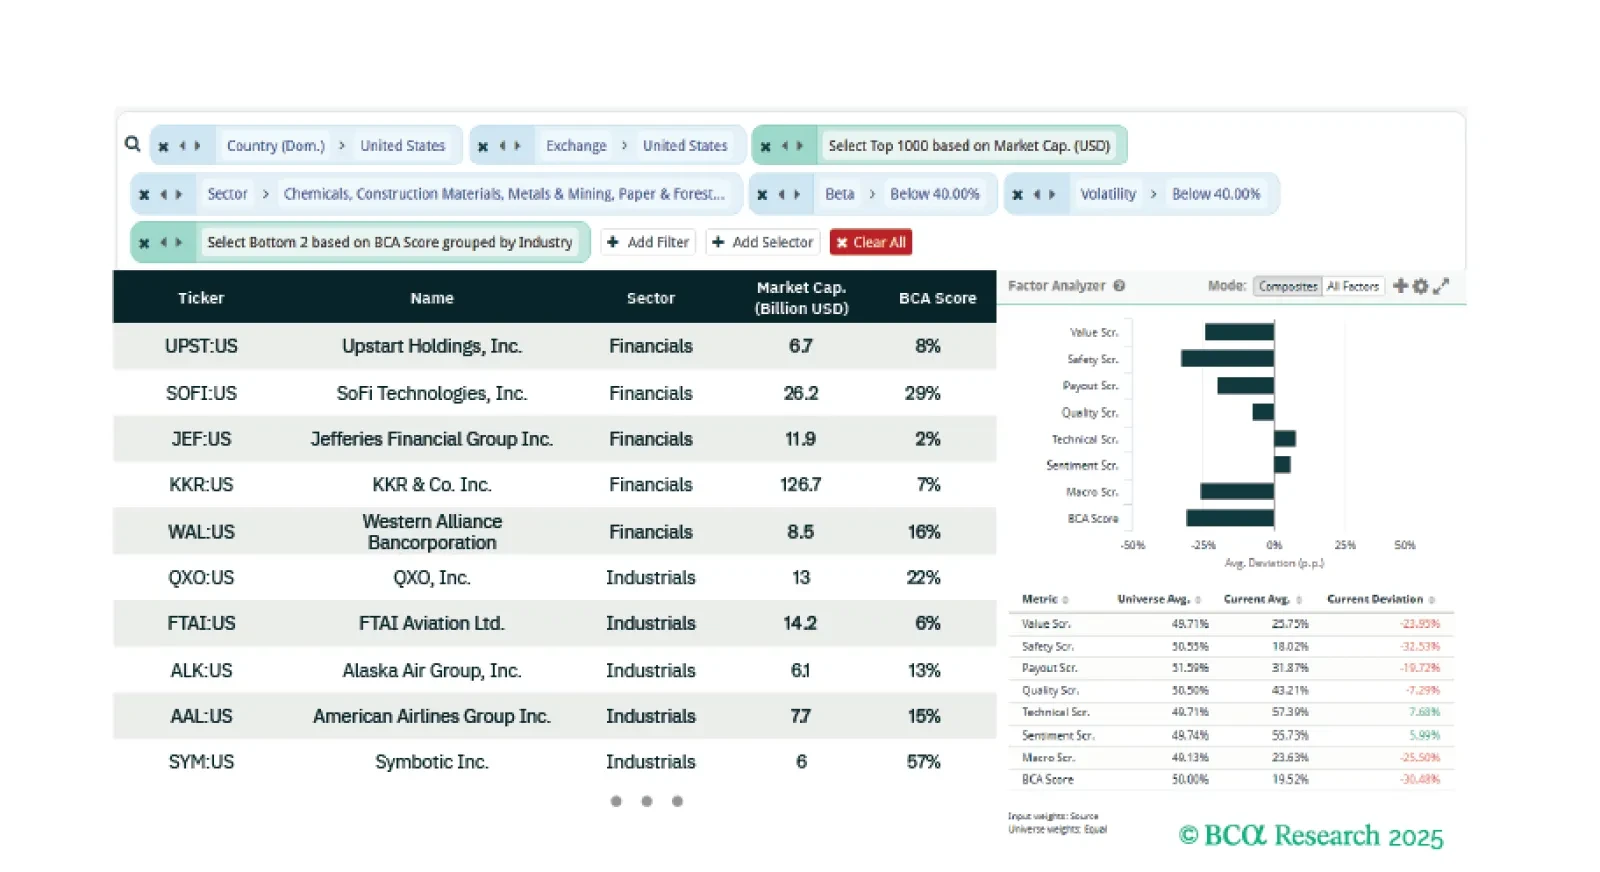
This week we develop two ideas with three screeners. The first identifies deep cyclical sectors that continue to outperform post Liberation Day in the US. We provide two screens to identify equity opportunities for this.  Our final screener identifies momentum stocks that are cheap and trending and will benefit from a soft landing.