Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Economy

Special Report

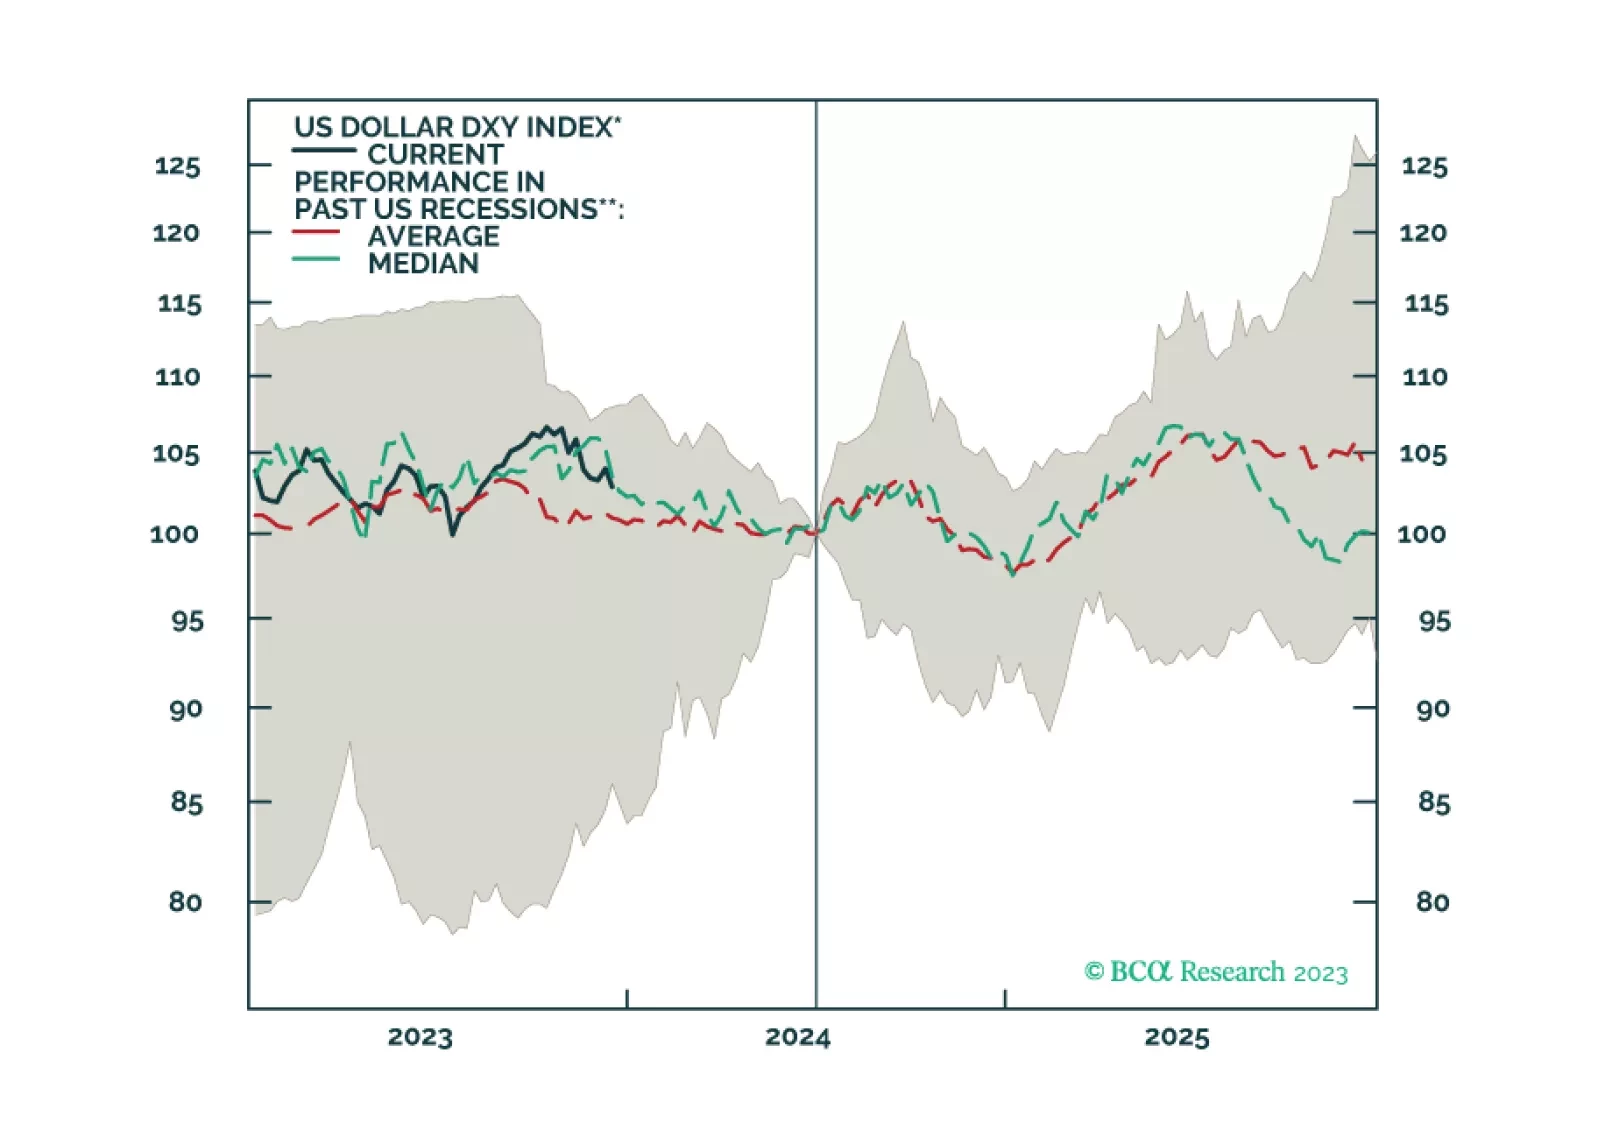
In this week’s report, we present our dollar view for 2024 and beyond, with a few trade ideas.

The November US retail sales release for November delivered a positive signal about consumer spending. Overall retail sales unexpectedly increased by 0.3% m/m, surprising expectations of a 0.1% m/m decline. The details of the report were also favorable. Eight…
As expected, the ECB kept its policy rate unchanged on Thursday. In the updated macroeconomic projections, the central bank revised down its inflation and growth forecasts for next year. It now expects inflation to ease to 2.7% in 2024 – 0.5 percentage…
The short answer, according to our colleagues at BCA’s Commodity & Energy Strategy (CES) is straightforward, but not simple: Political economy – i.e., how states organize and operate their economies to support policy and advance their interests. …
According to BCA Research’s Emerging Markets Strategy service, domestic demand and corporate profits will disappoint across mainstream Emerging Market economies (excluding China, India, Korea, and Taiwan) in H1 2024. Retail sales volume growth has been…
Special Report

The major question facing EM investors in 2024 is whether or not EM will cross the Rubicon. The path to a soft landing in the US remains elusive. The recent improvement in global manufacturing/trade will likely prove to be a mid-cycle bounce rather than the beginning of a cyclical recovery.
Special Report

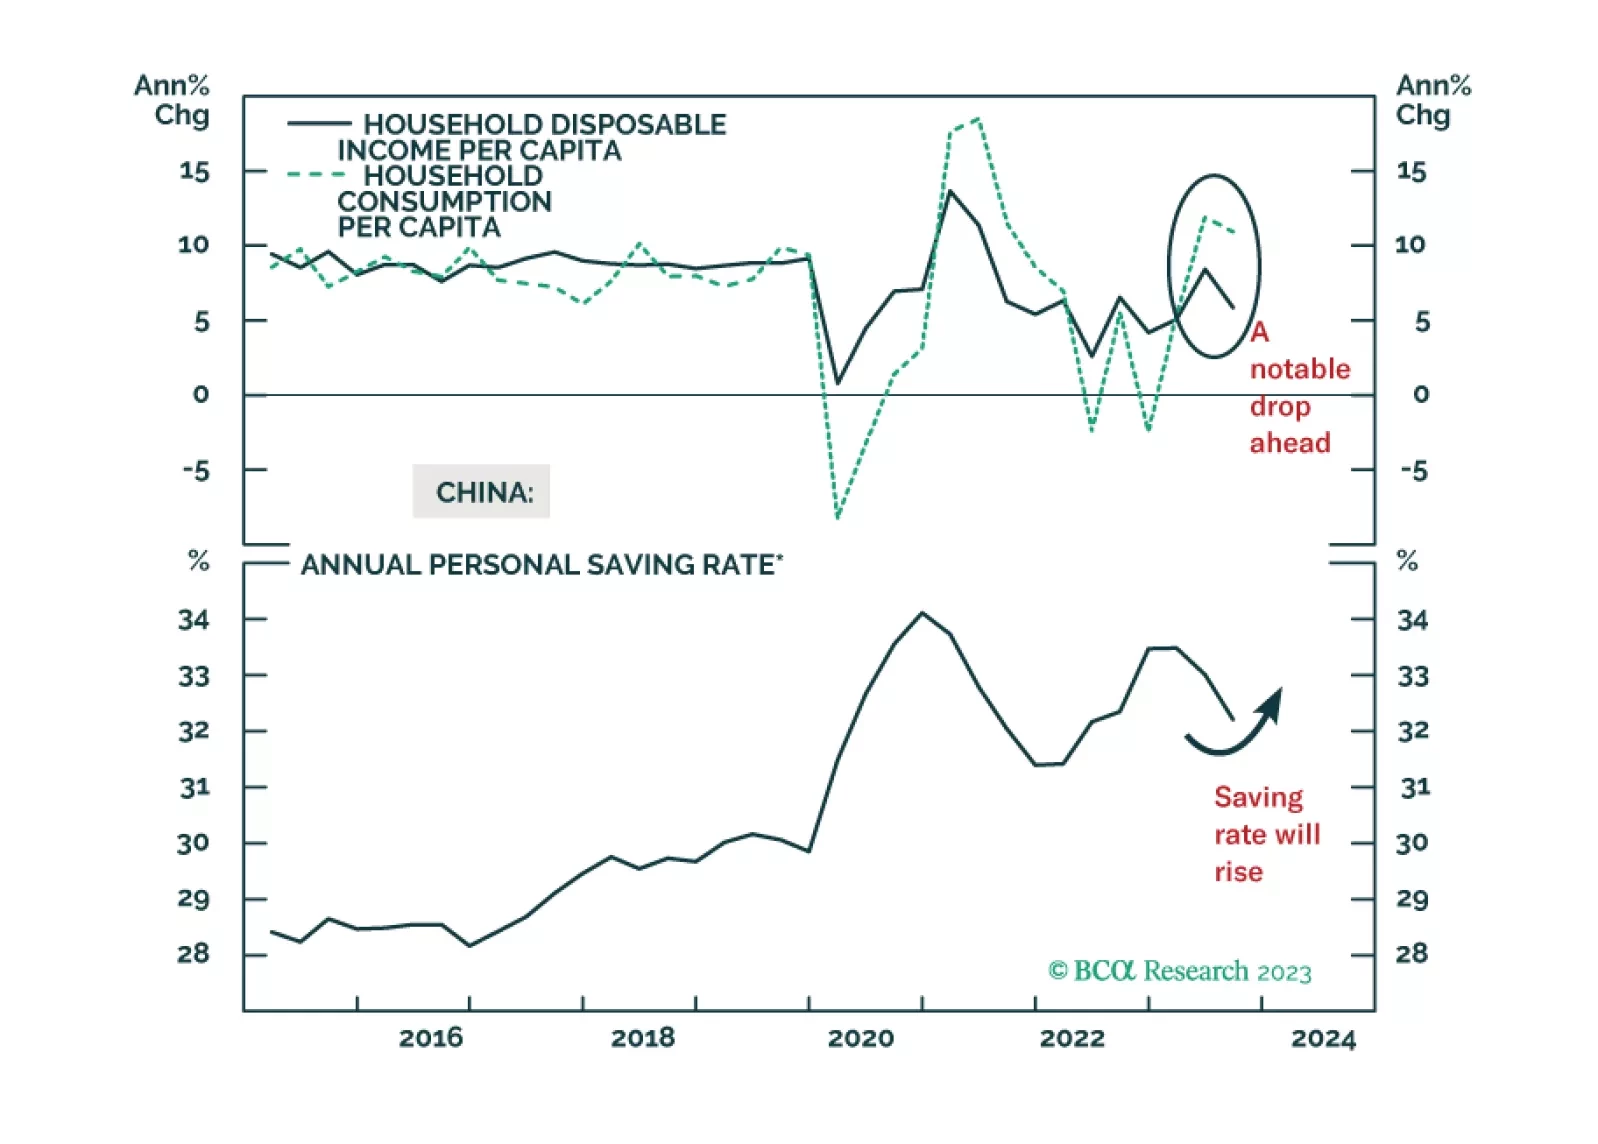
Nominal household spending growth in China will slow in 2024. Strong headwinds will arise from a slower household income expansion, falling house prices, a downbeat employment outlook, and shrinking exports. Spending on healthcare services will post solid gains but durable goods consumption will experience anemic growth in 2024. We favor consumer staples and healthcare stocks versus the domestic benchmark.

China’s credit expanded by less than expected in November. The CNY 2.45 trillion increase in aggregate financing fell short of anticipations of CNY 2.595 trillion following a CNY 1.845 trillion rise in October. Similarly, the CNY 1.09 trillion in new yuan…
Weaker-than-anticipated economic data caused a sharp decline in UK gilt yields over the past few days with the 10 year yield now at its lowest since May.   The weakness in economic data was broad-based across various sectors of the UK economy. In the…
As expected, the Fed kept the policy rate unchanged in the 5.25%-5.50% range on Friday. Although the statement continued to indicate that the Fed is prepared to tighten further, it also acknowledged that there has been a slowdown in economic growth and that…