China
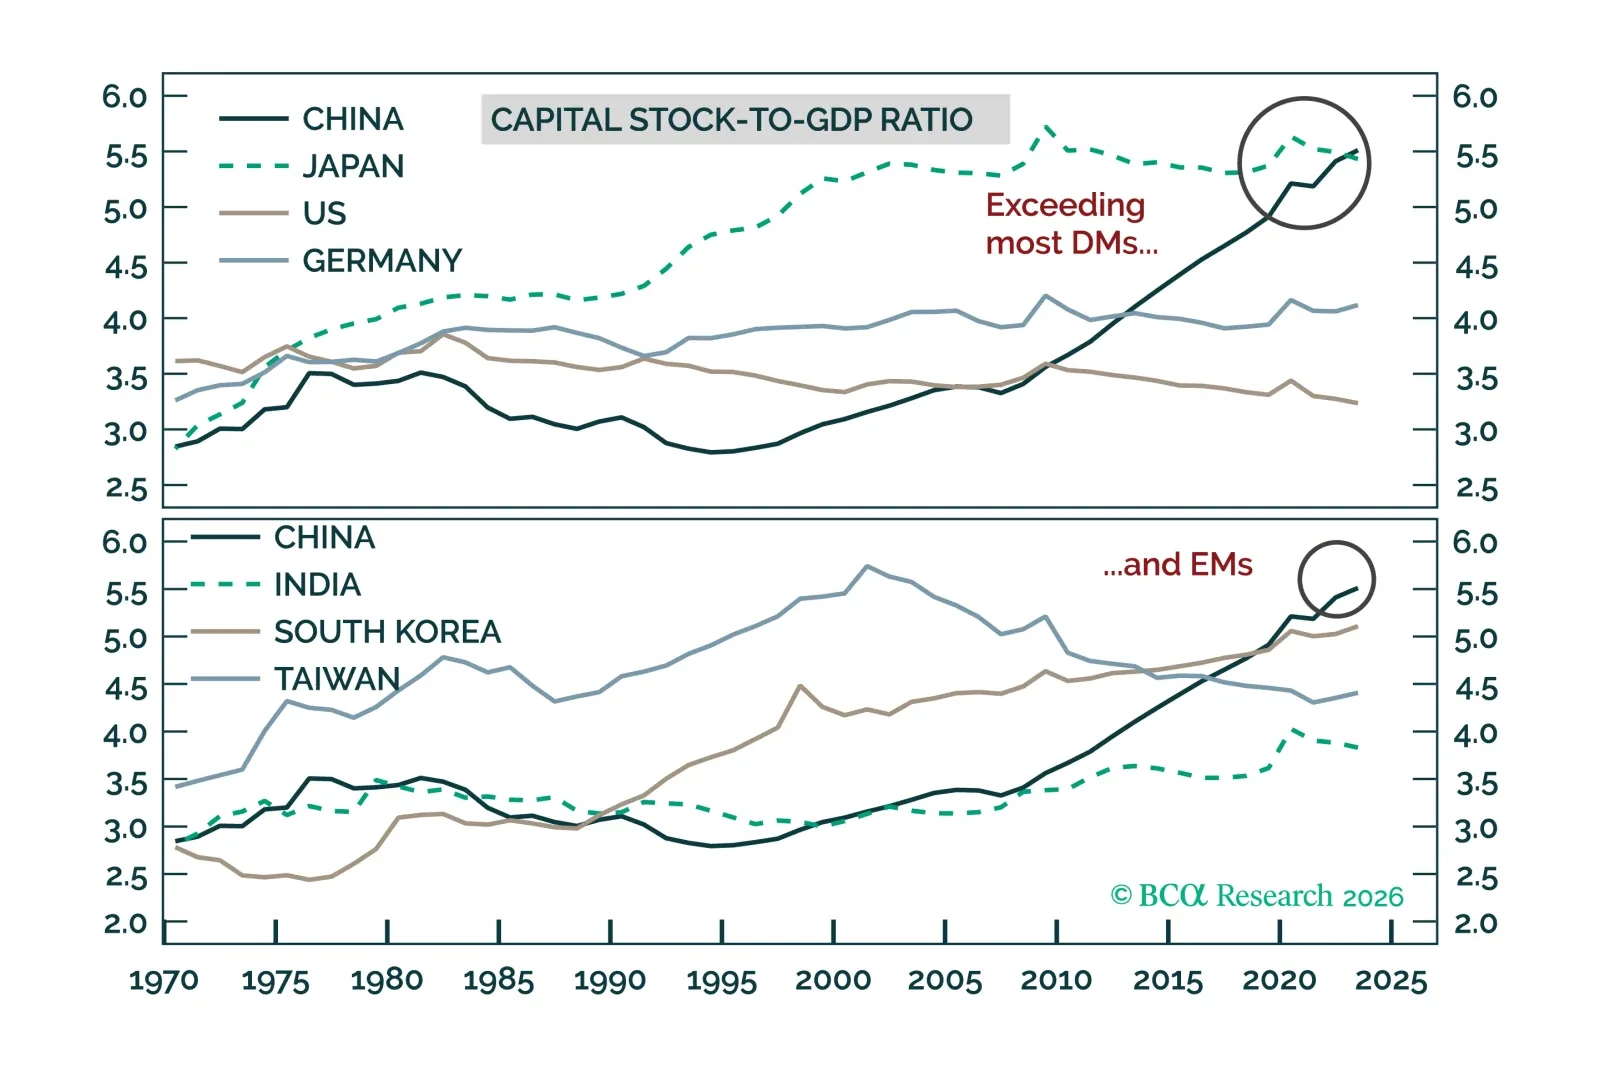
China’s investment has hit cyclical and structural limits. Mounting economic pressures will likely push Beijing toward a more aggressive, consumer-focused reflationary stance over the next one to two years.
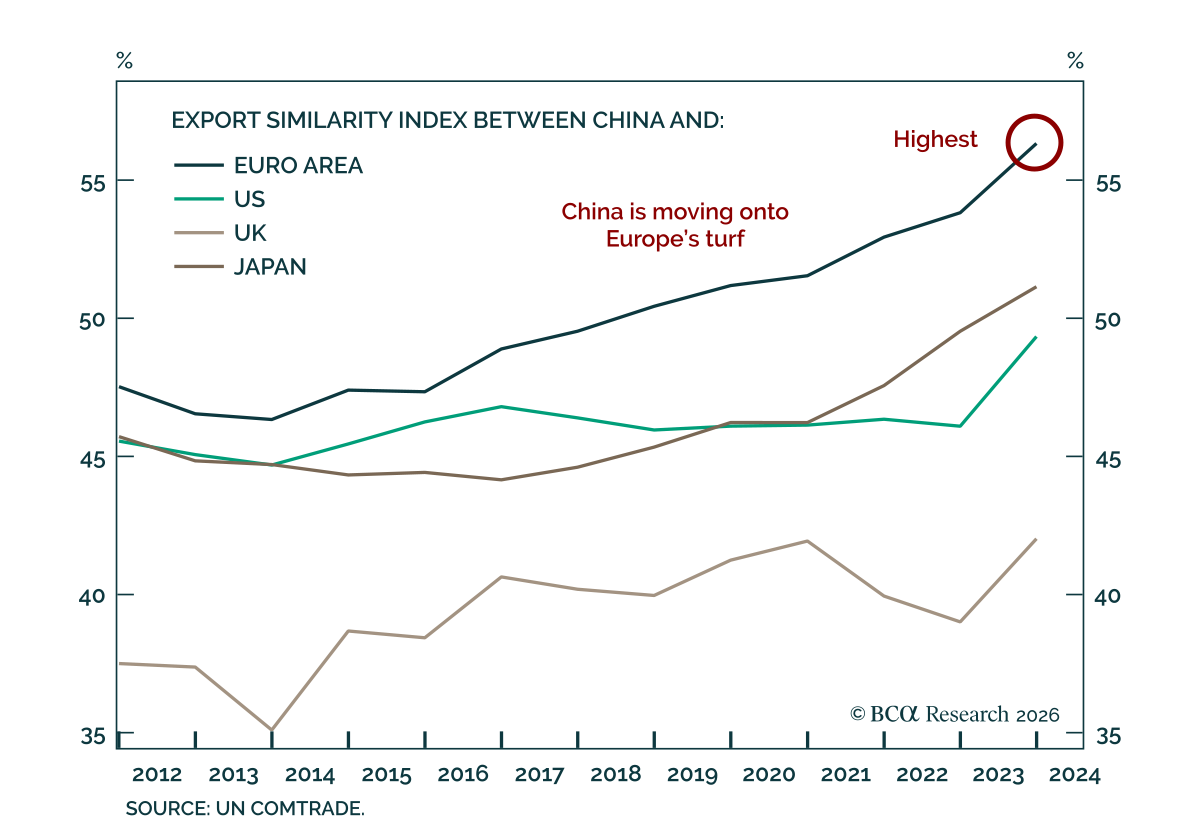
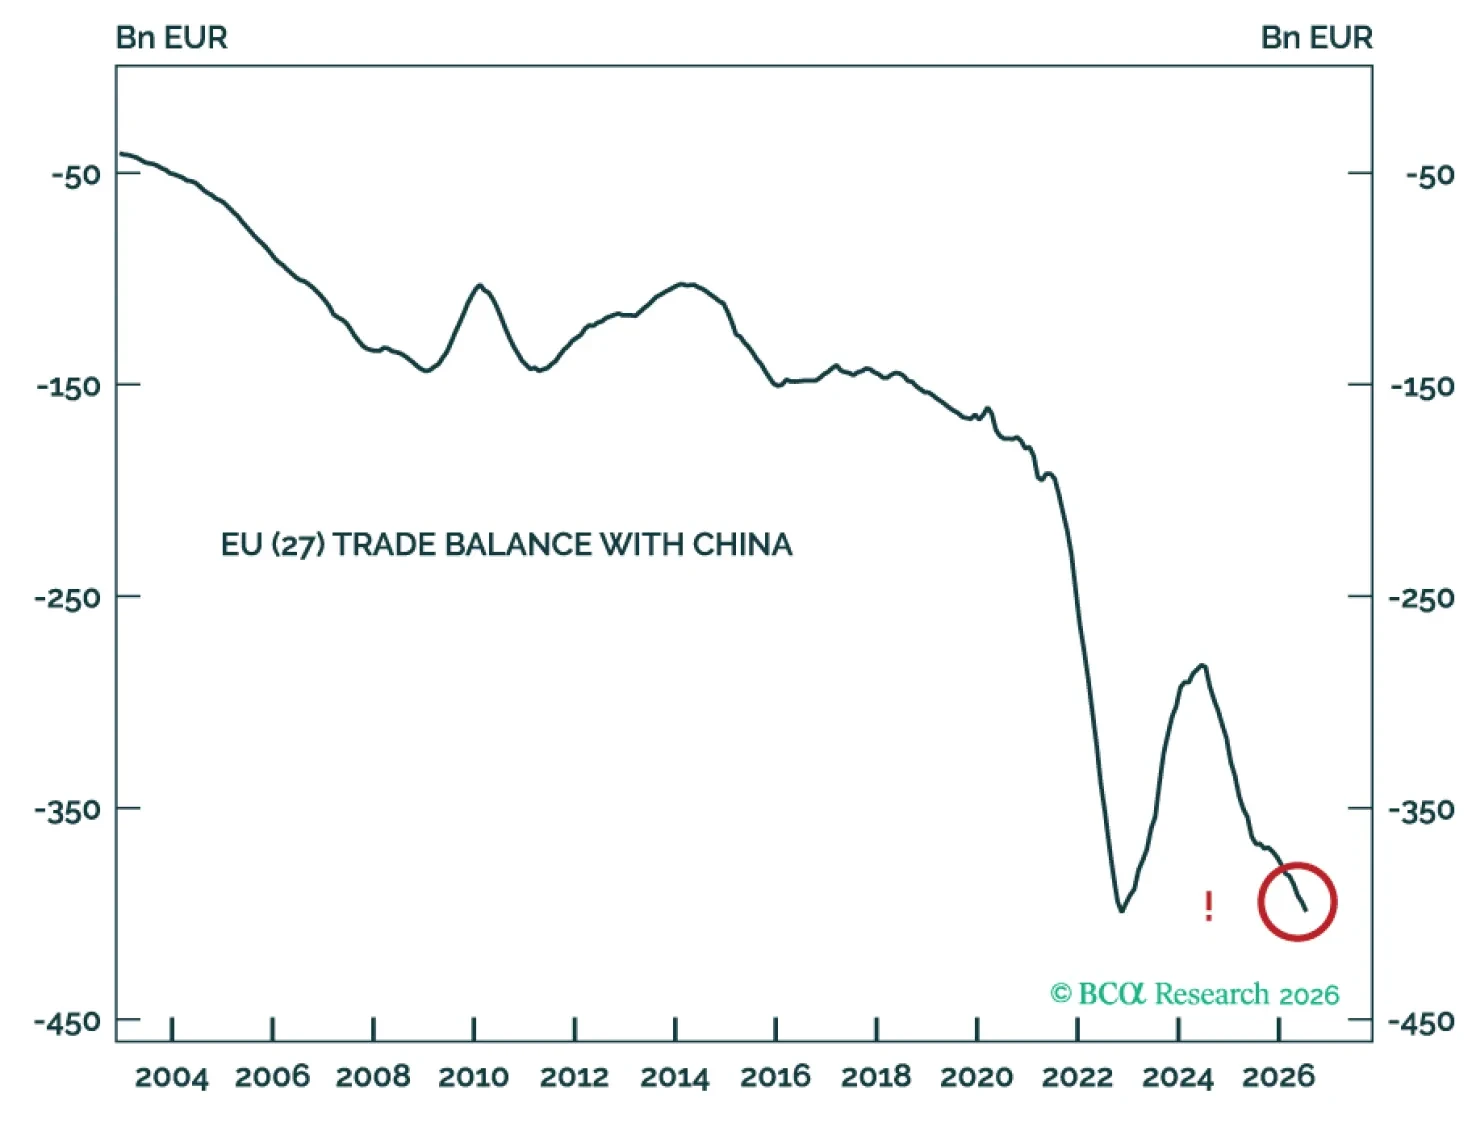
China shock 2.0 threatens Europe’s industrial core, but it is also forcing a long-overdue response. China stands to lose more than the EU from the coming confrontation. Beijing cannot afford to alienate Europe while its domestic demand remains weak. Europe, meanwhile, can turn protectionism into a stronger fiscal multiplier and an industrial revival.
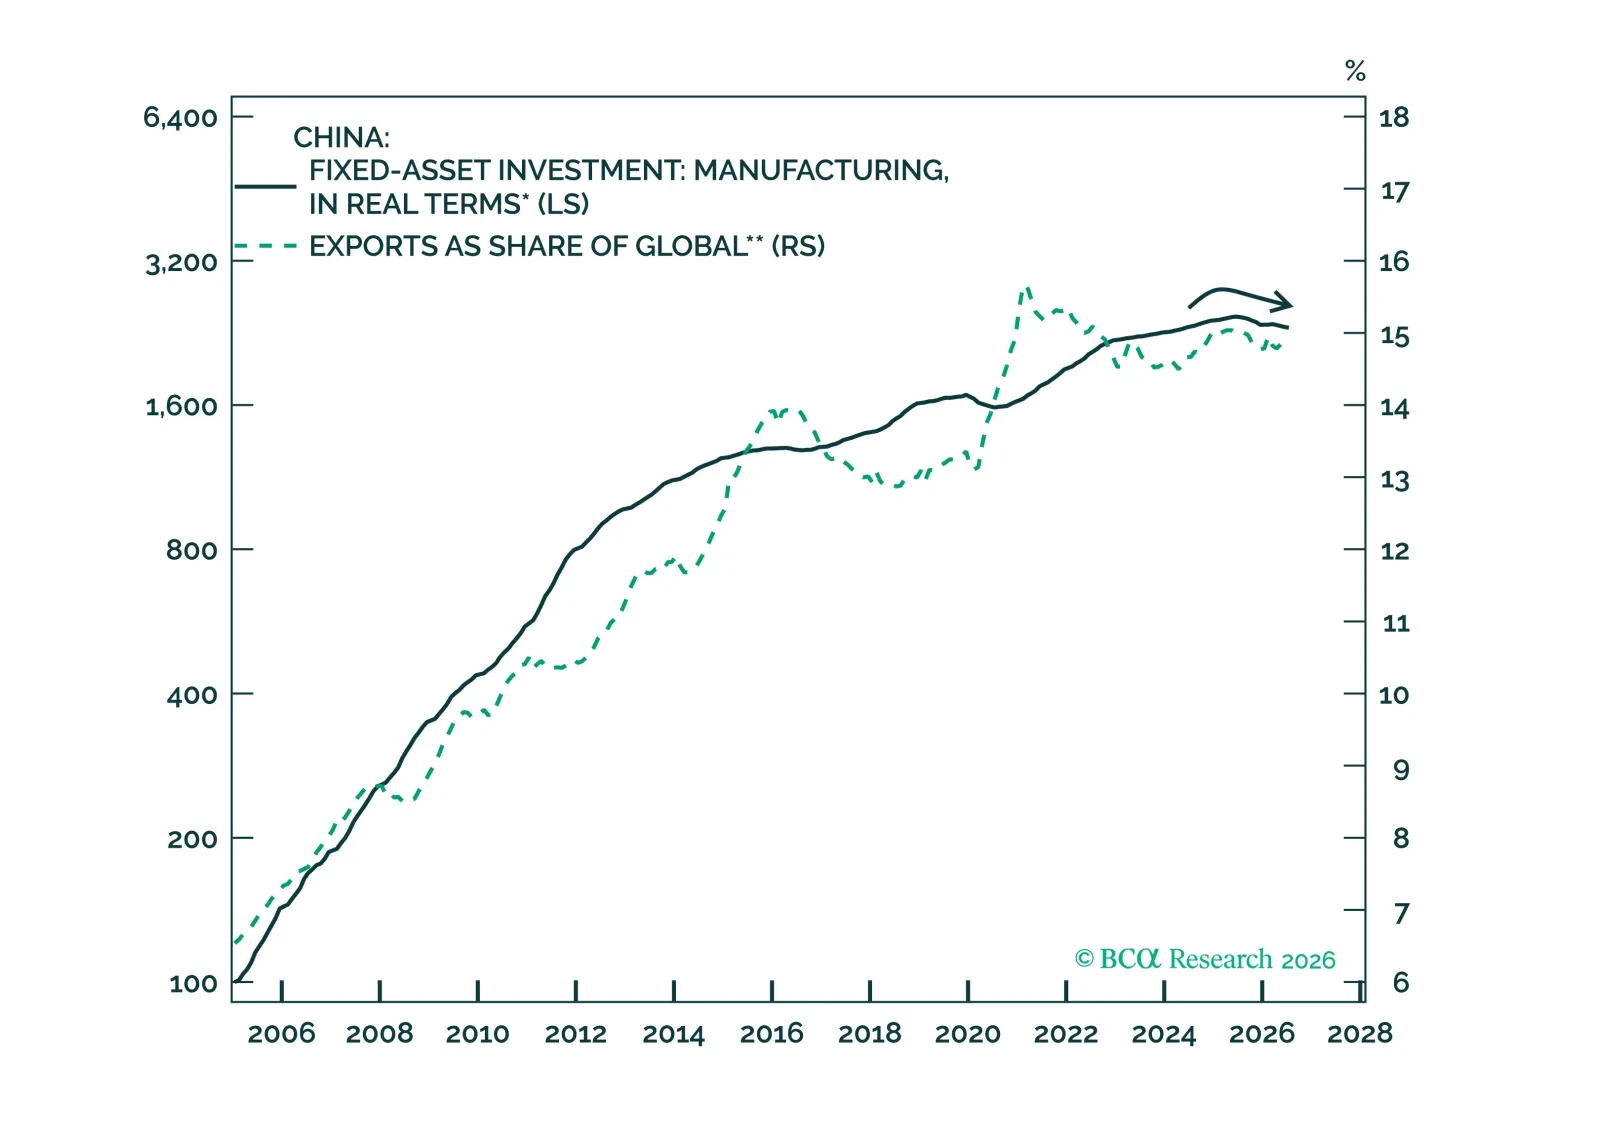
China’s manufacturing edge should endure in the next few years. AI will challenge the country’s advantage in some industries, but geopolitics and weakening productive investment pose greater threats to sustaining China’s industrial leadership.

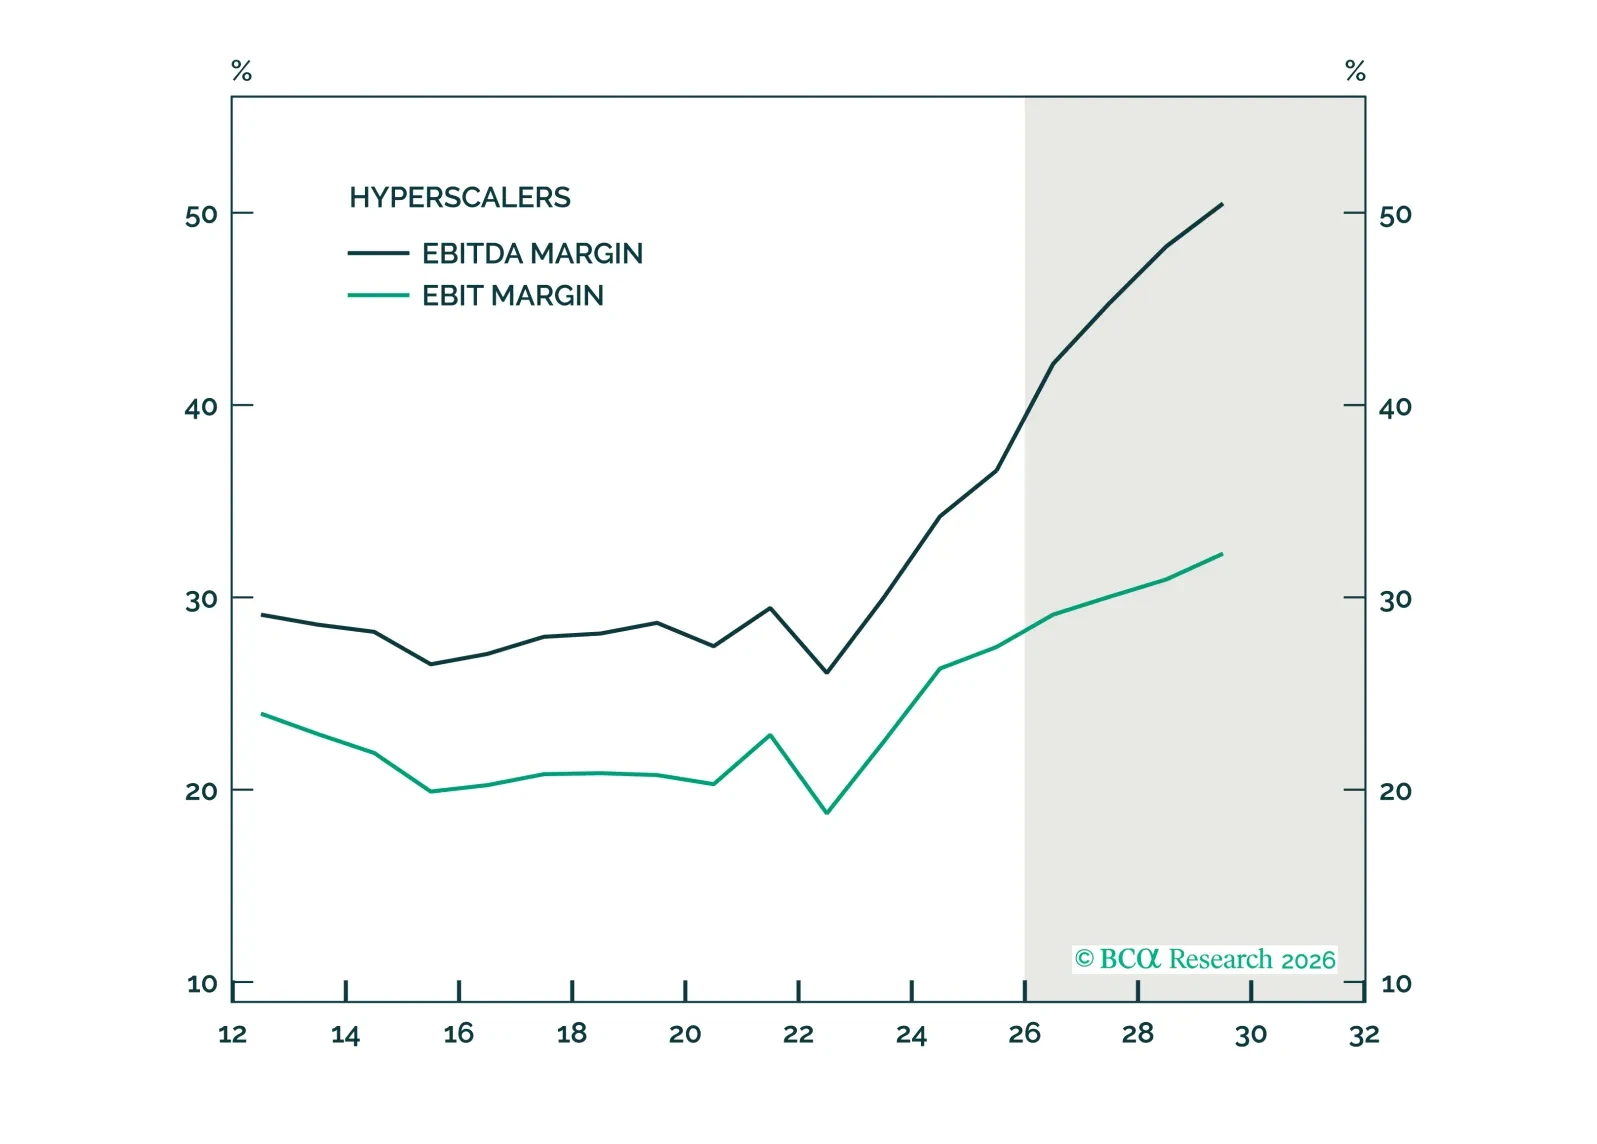
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
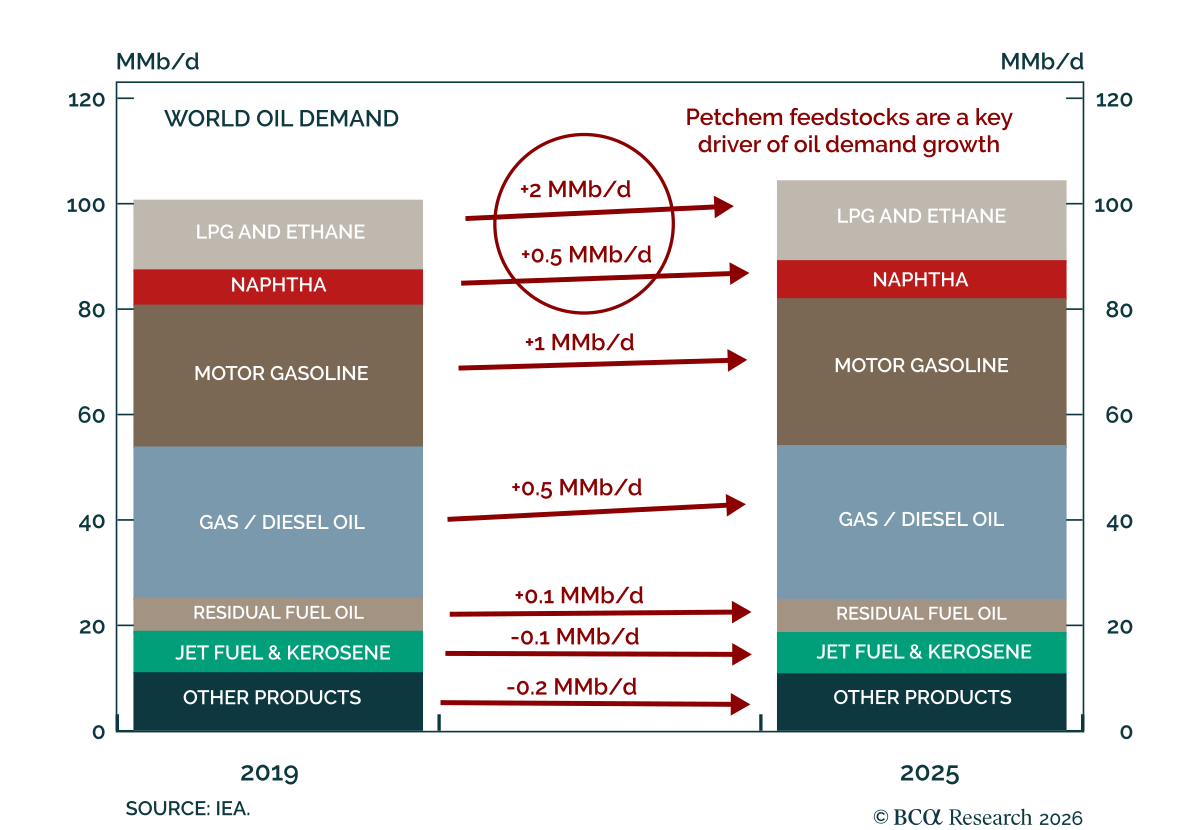
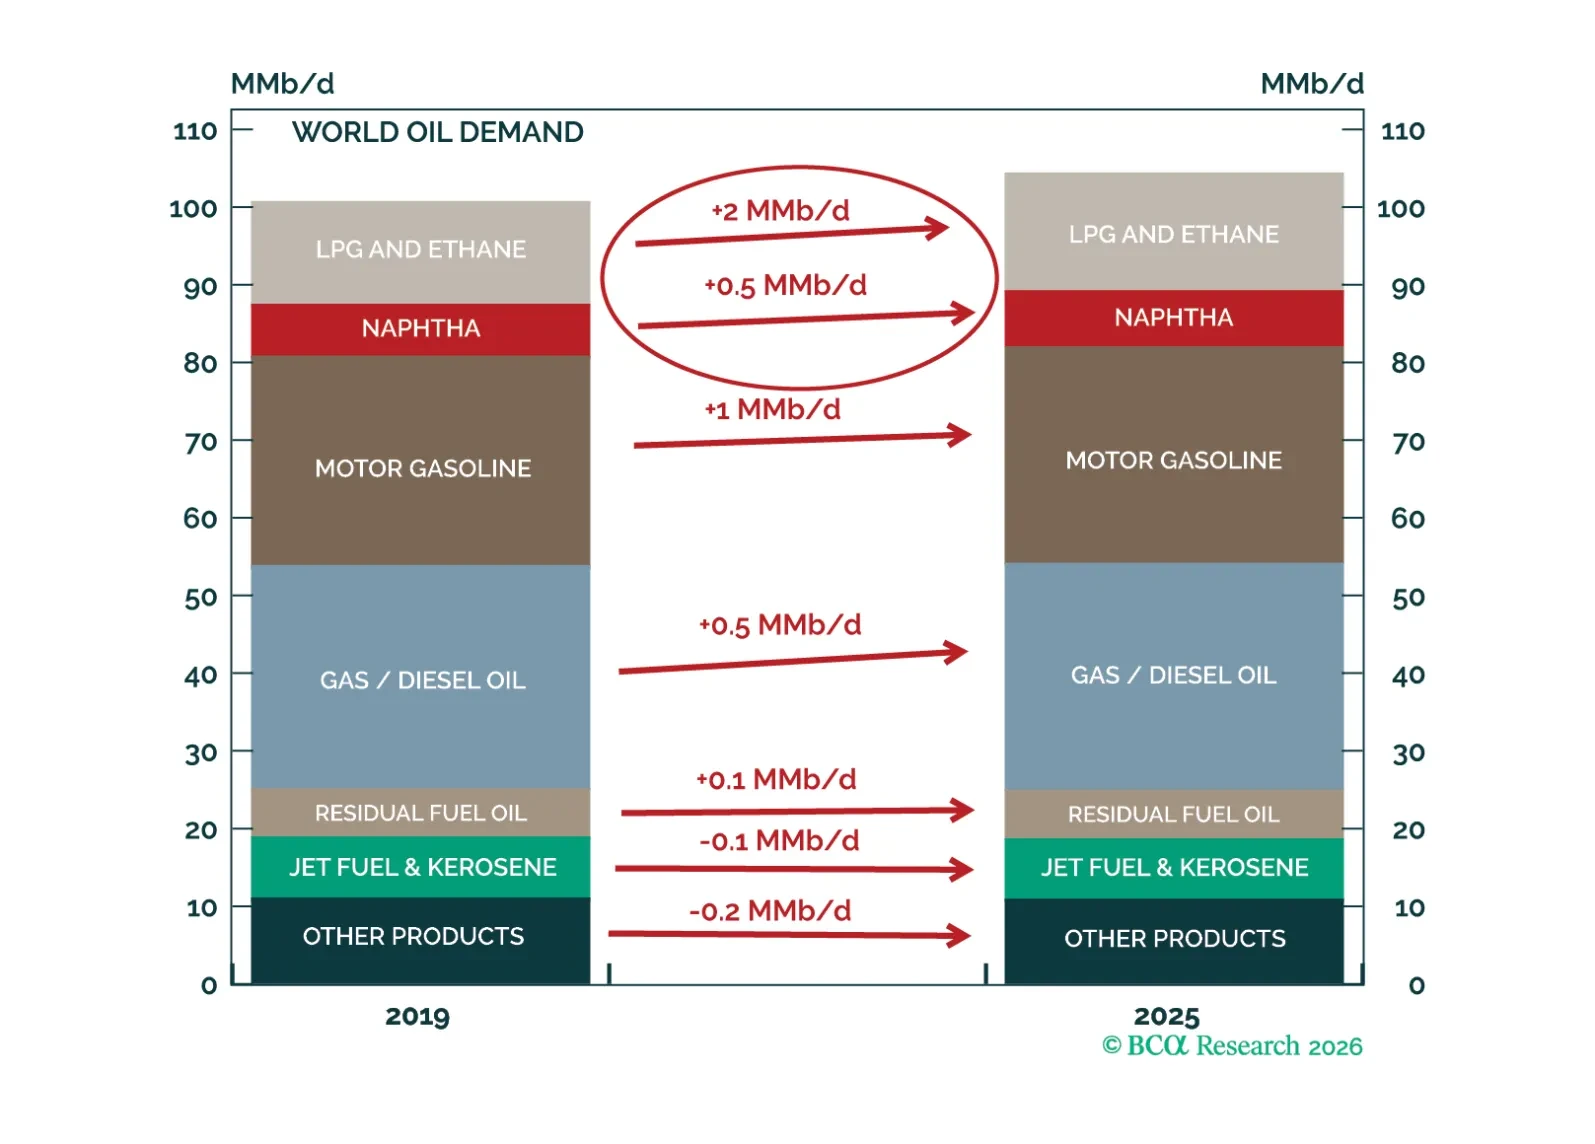
The Hormuz crisis has exposed a structural vulnerability in China's petrochemical value chain. Going forward, Beijing will look to build greater supply security by scaling up coal-to-olefins capacity — a shift that creates a structural tailwind for coal prices and a structural headwind for oil.
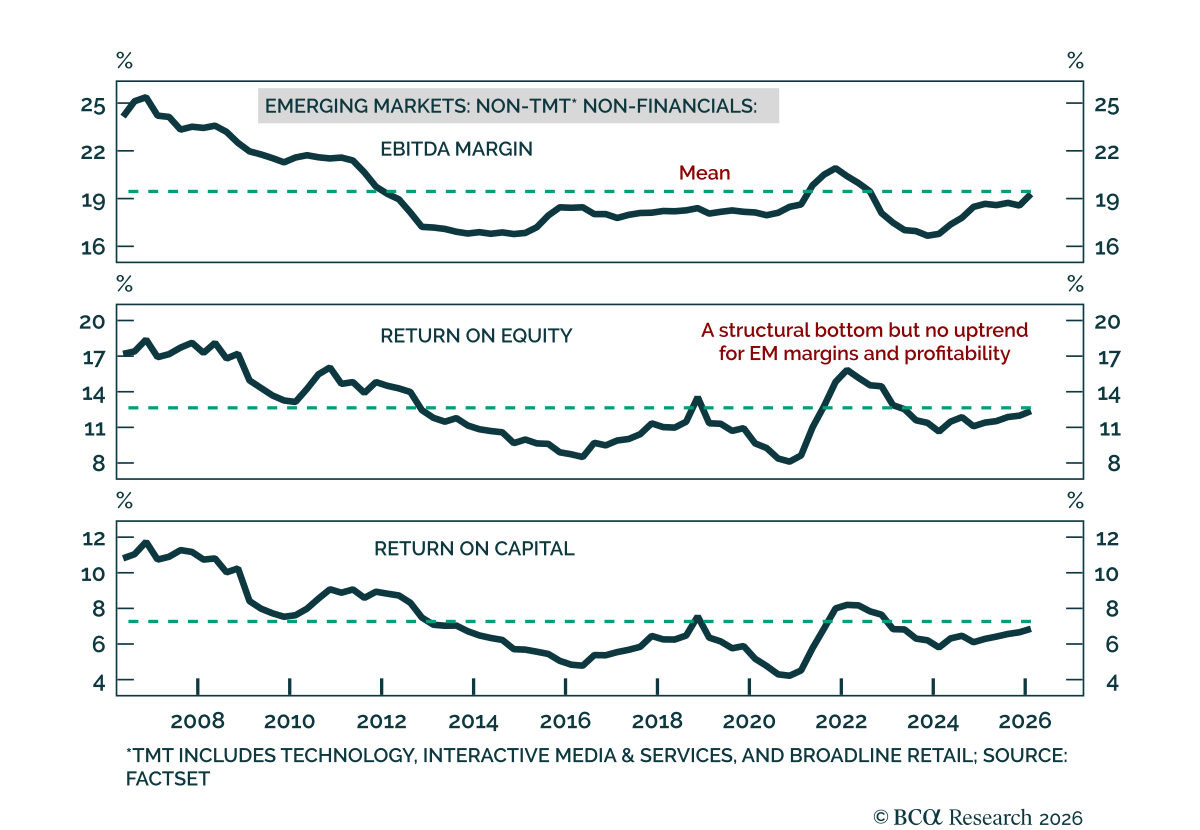
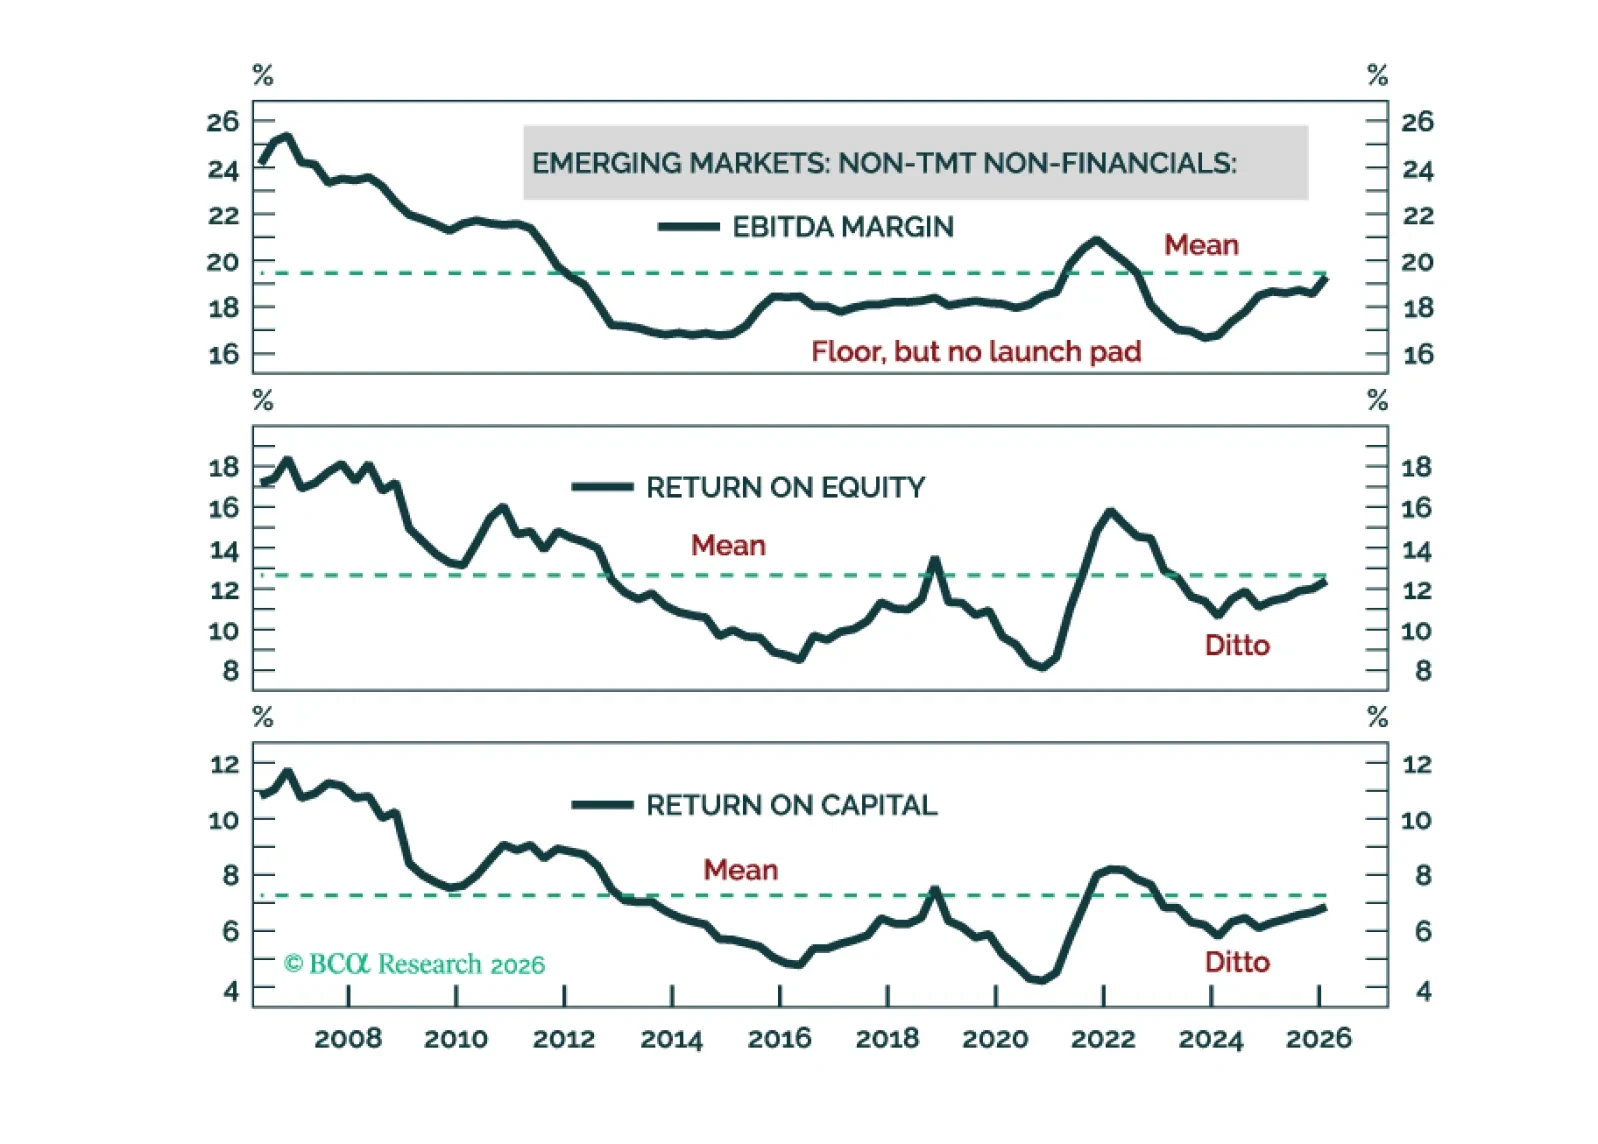
Outside semiconductor stocks, EM/China profitability has been well below both their US peers and the levels that prevailed during the EM structural bull market in the 2000s. Over a 3- to 5-year horizon, EM/China relative equity performance versus global will be range-bound.