Brazil
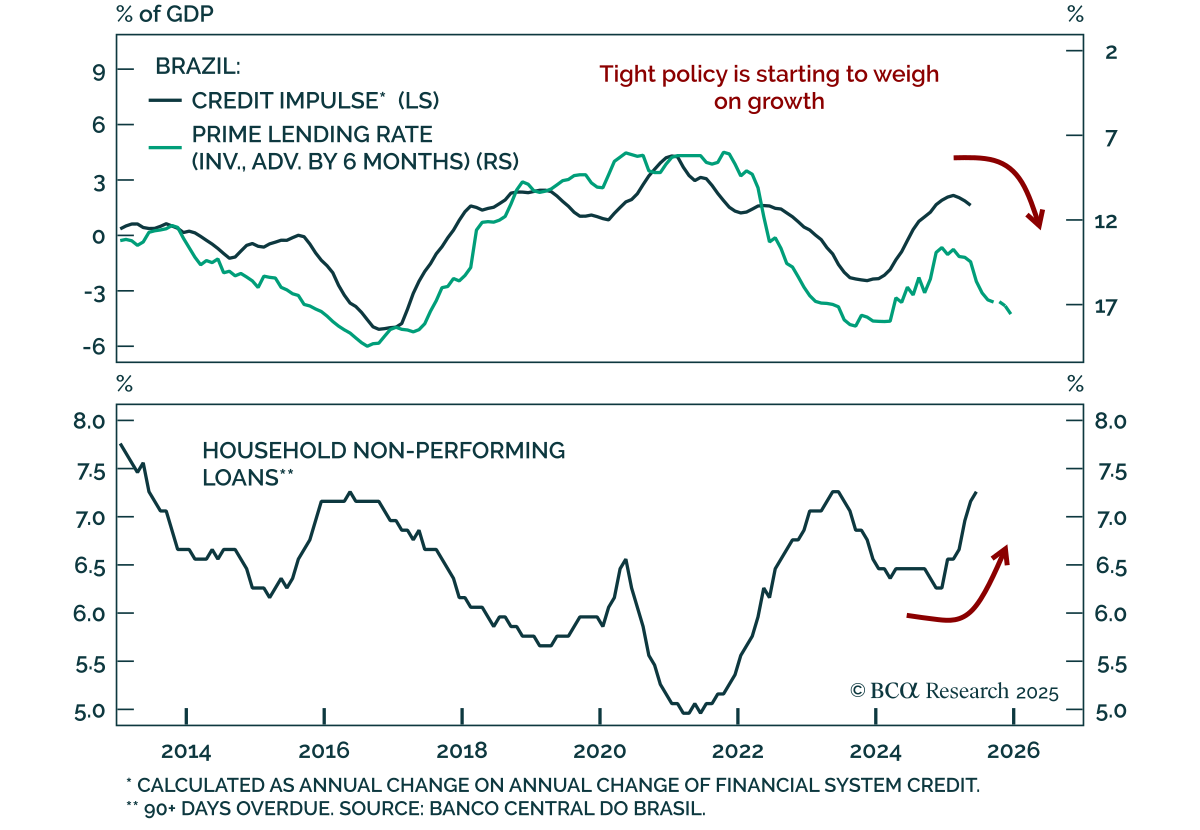
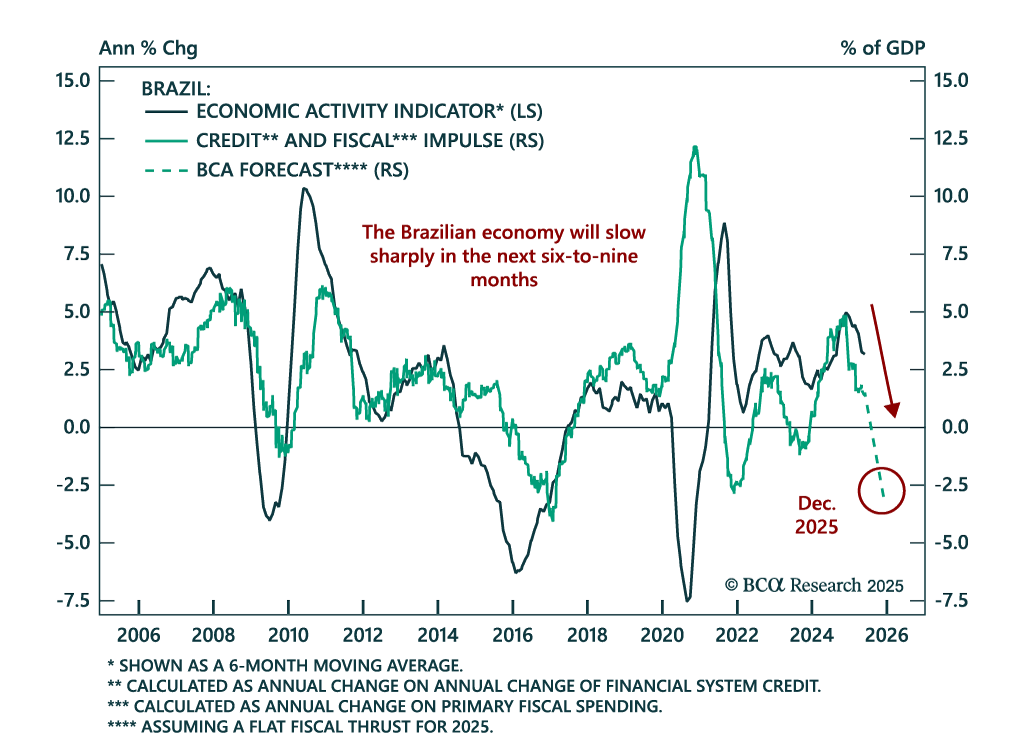
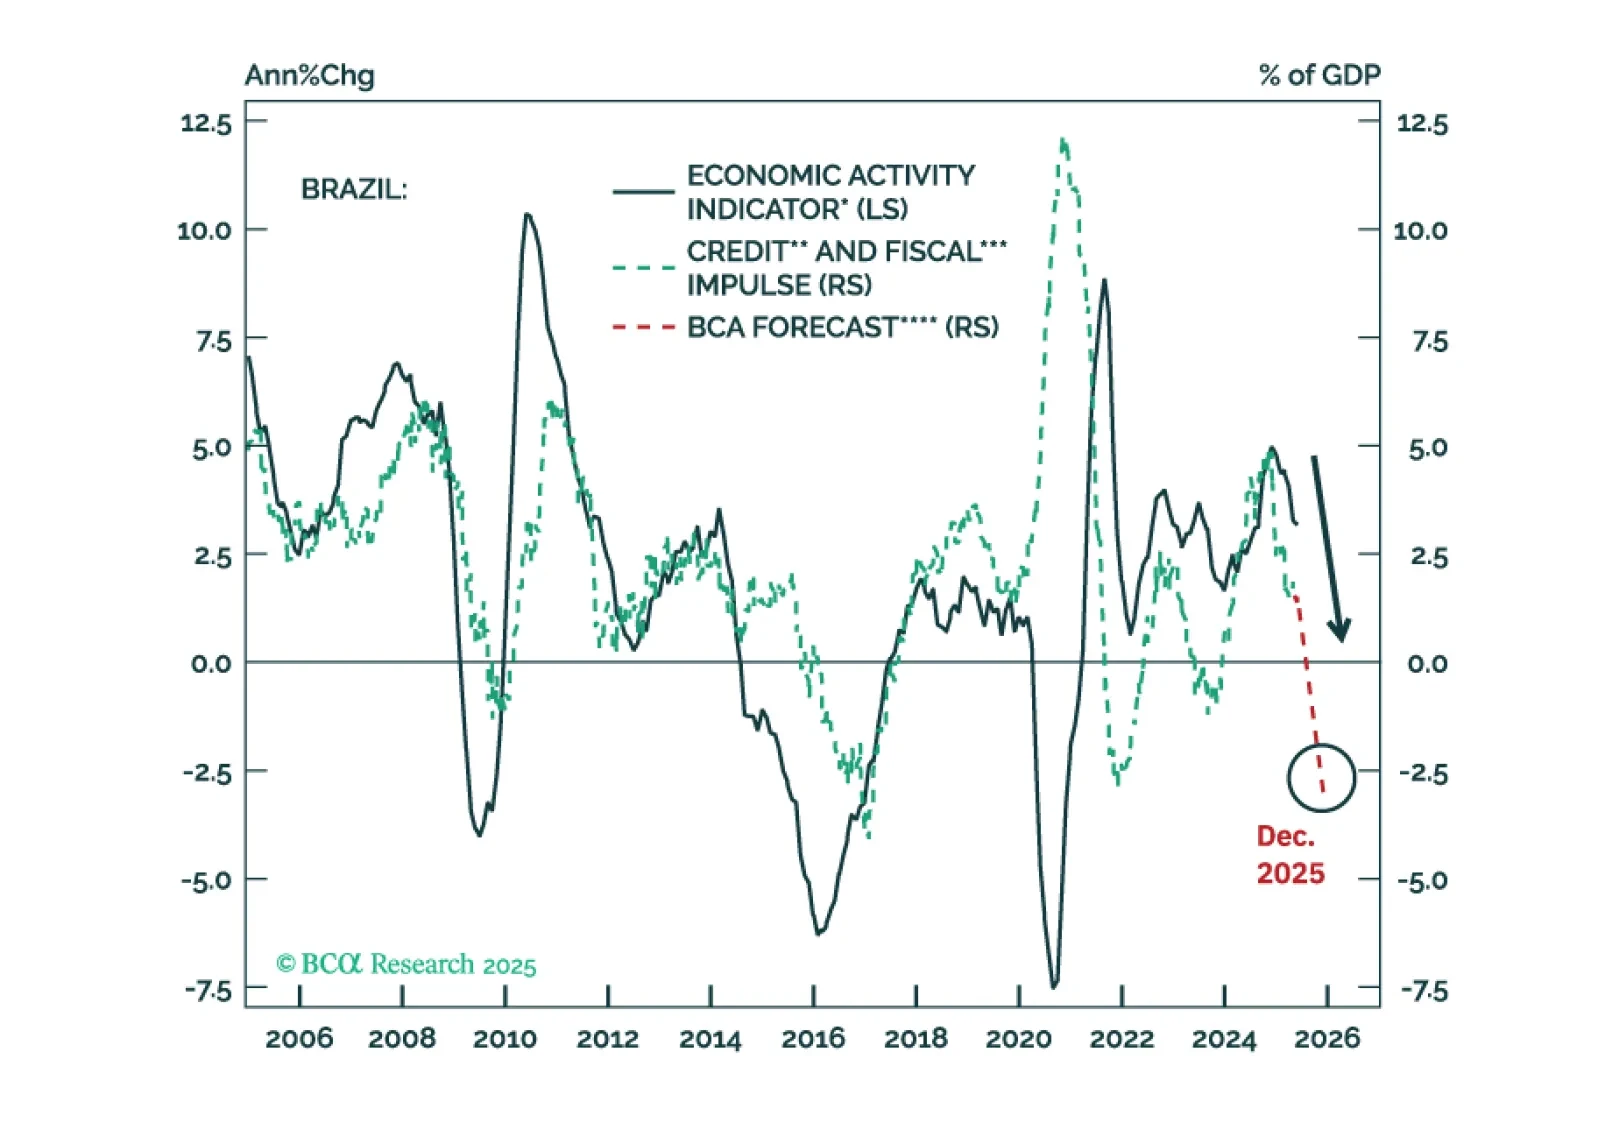
A potential right-wing government in 2027 will not stabilize the trajectory of the public debt-to-GDP ratio. Unsustainable public debt, a large current account deficit, and a sharp growth slowdown will lead Brazilian markets to underperform EM. Yet, to benefit from a quickly decelerating economy, we recommend receiving 2-year swap rates.
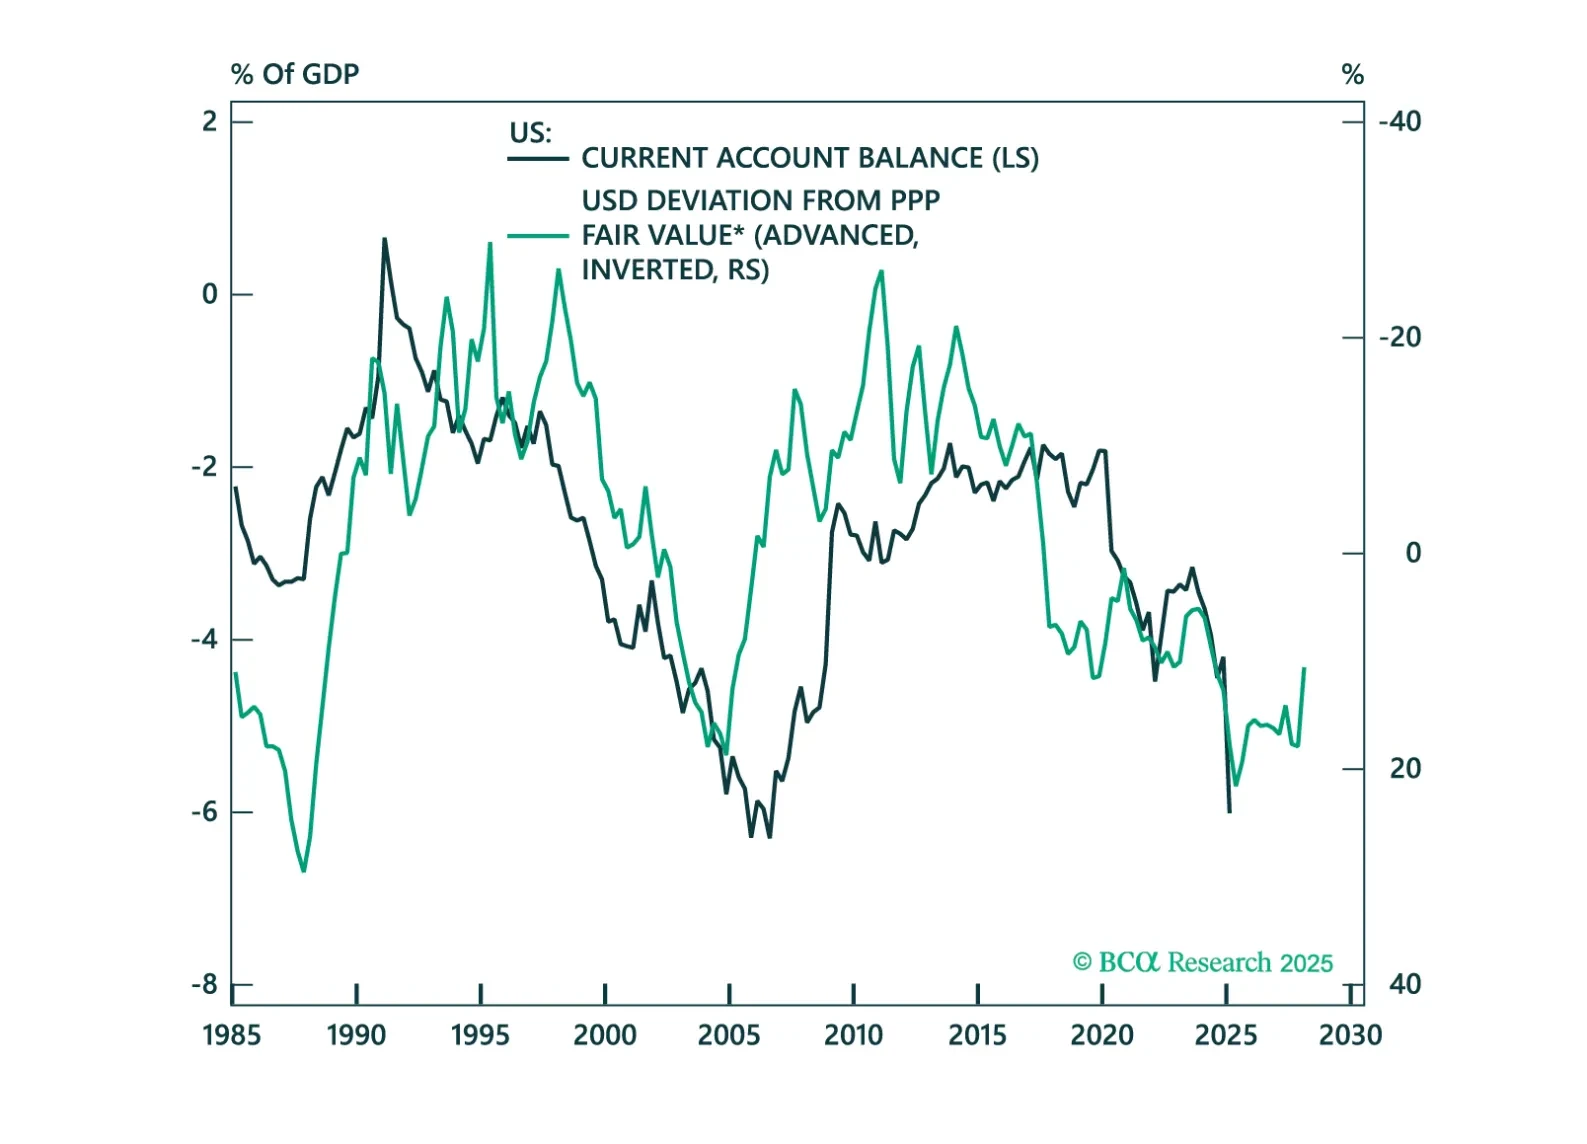
In this chartbook, we look at the balance of payments across DM and EM countries. The US does not fare well, but neither do a few other countries.
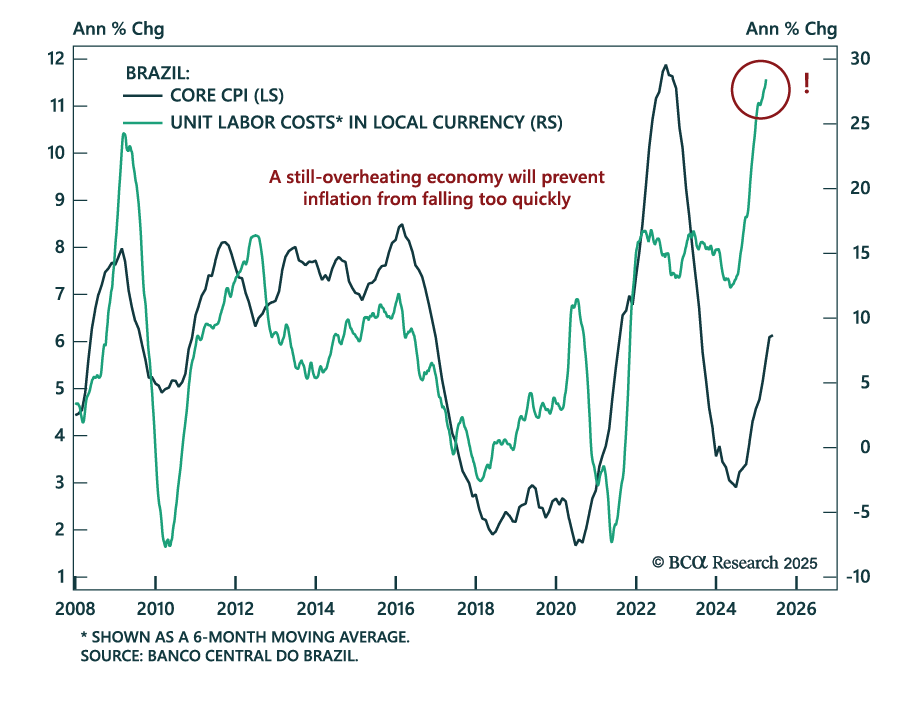
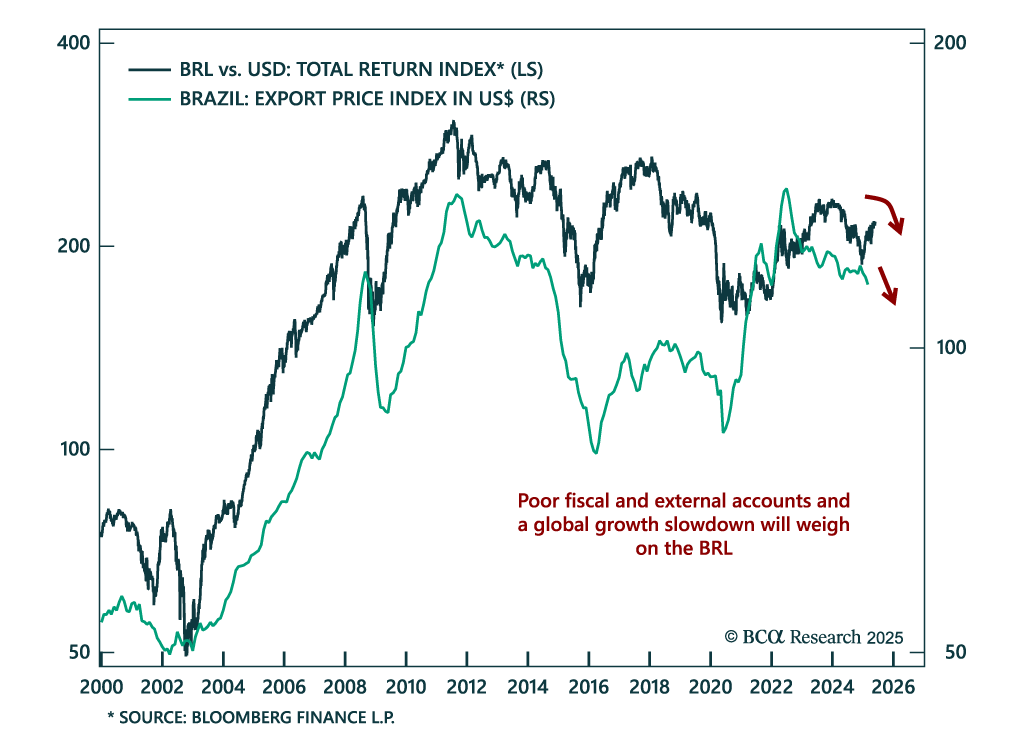
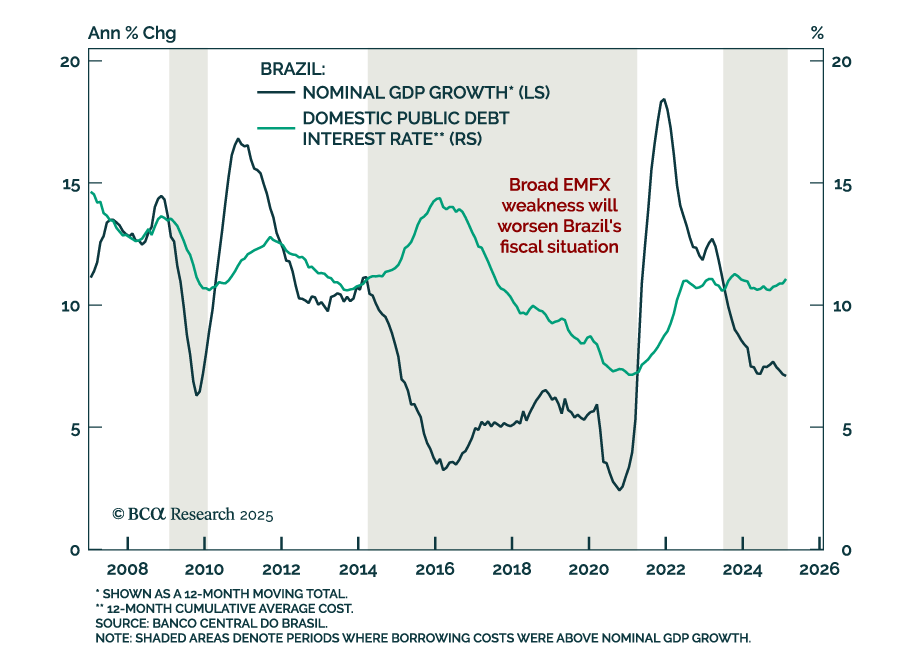
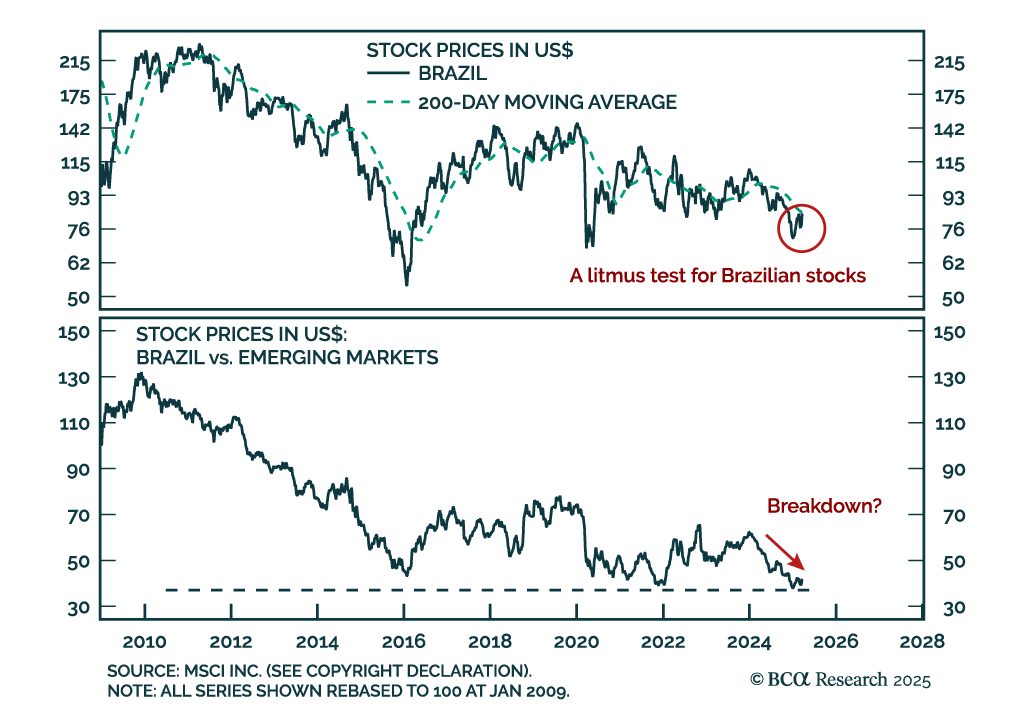

Brazilian policymakers are stuck between a rock and a hard place. There is no combination of fiscal and monetary policies that can assure decent growth, on-target inflation, a stable exchange rate, and public debt sustainability. We recommend investors maintain an underweight allocation to Brazilian fixed-income markets versus their EM peers and continue shorting BRL versus MXN. We have been bearish on the Bovespa in absolute terms and are now downgrading Brazilian stocks from neutral to underweight within an EM equity portfolio.
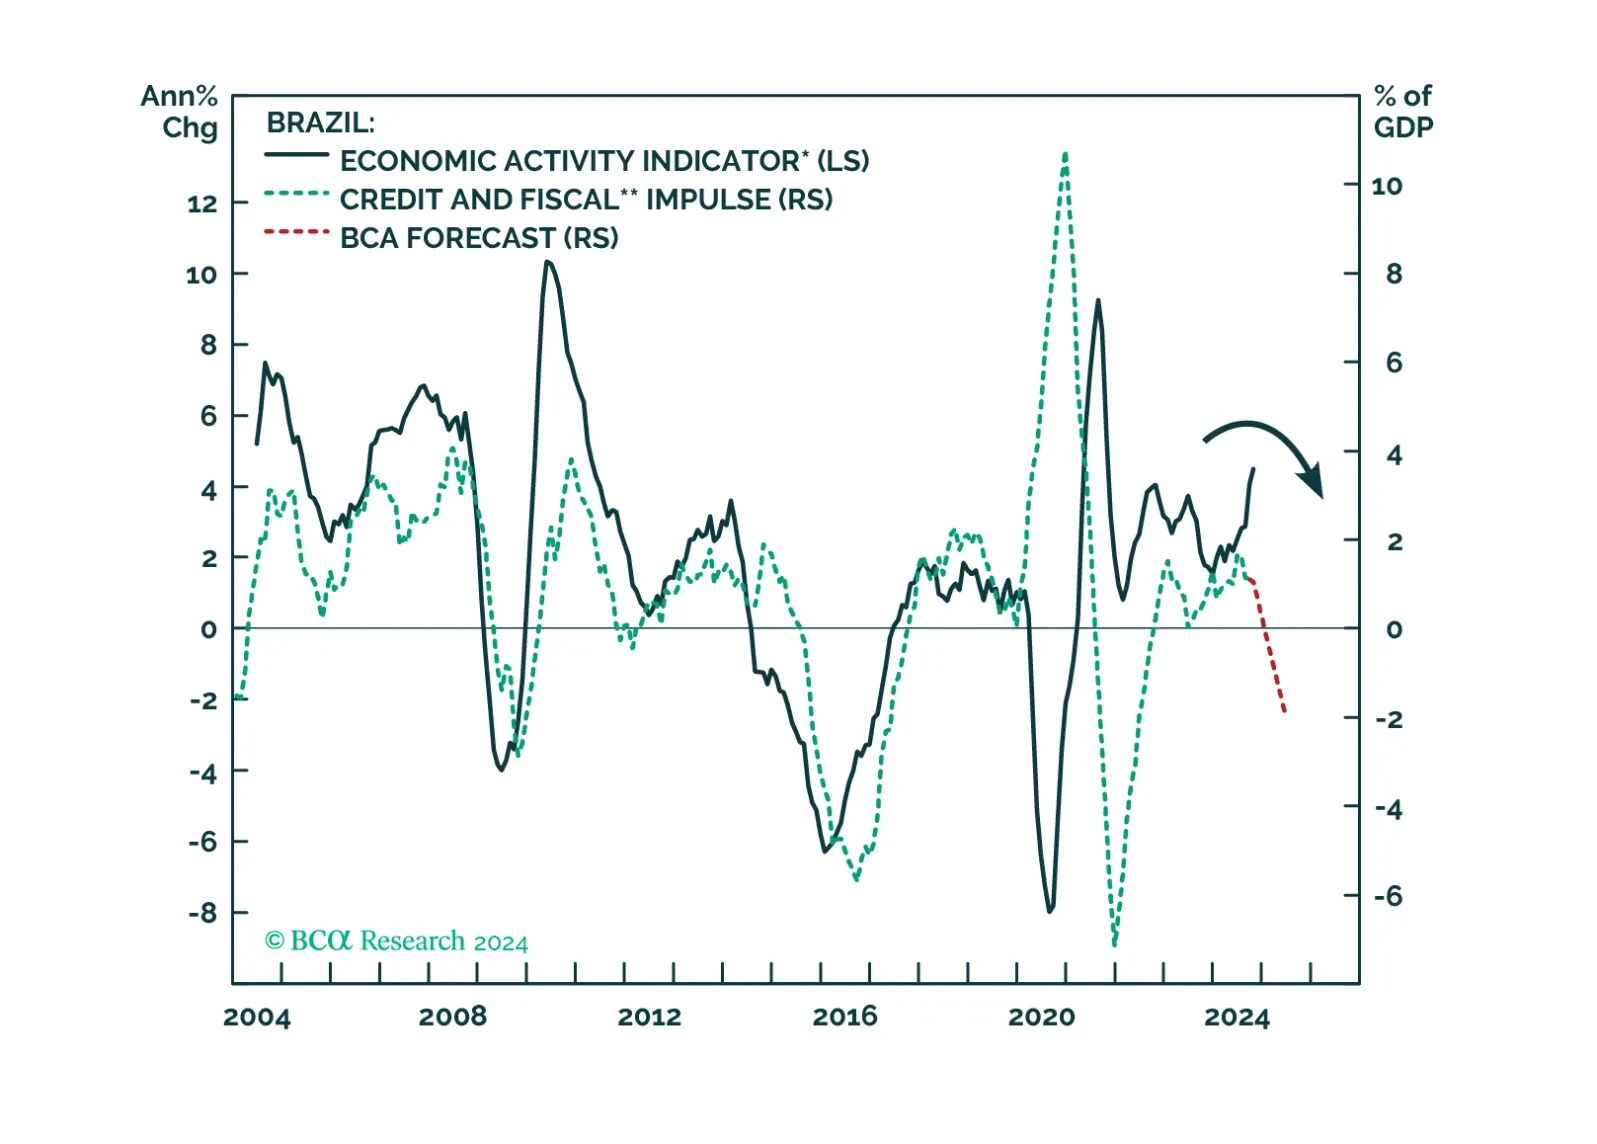
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.