Brazil
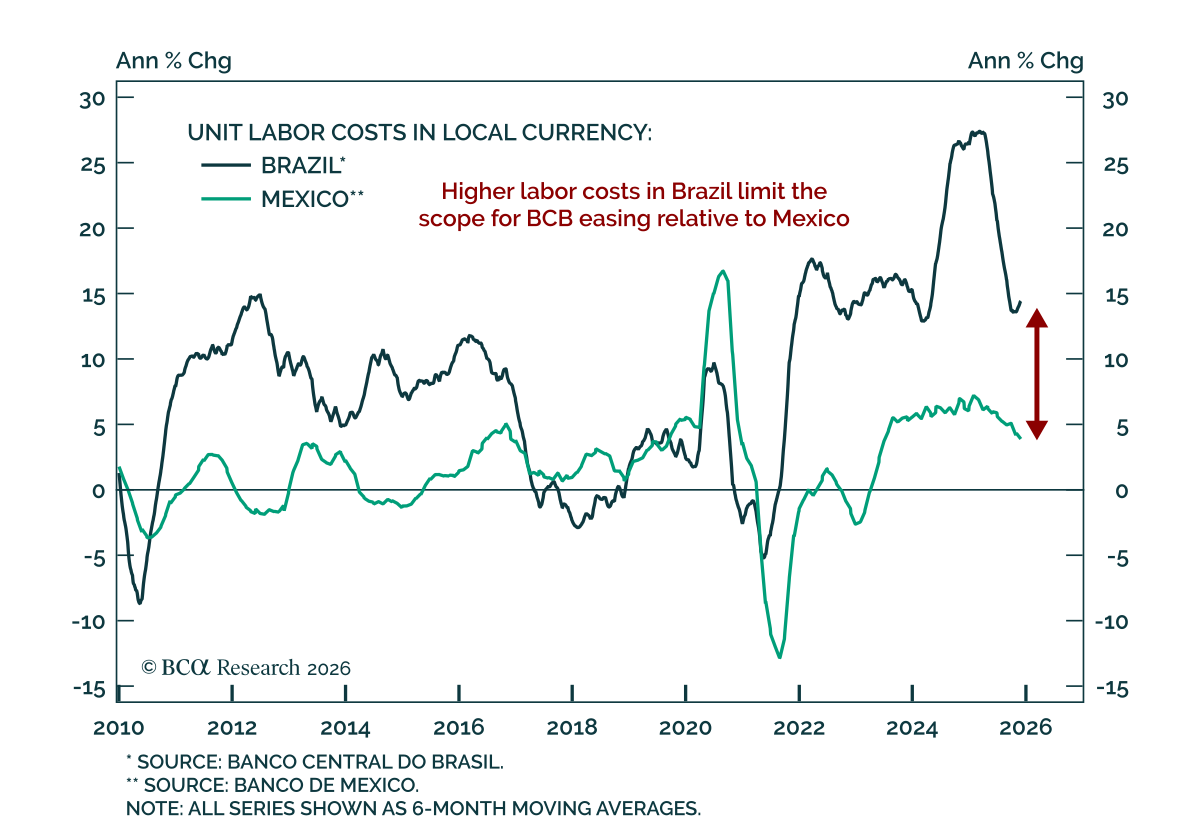
Despite similar headline inflation, underlying dynamics favor Mexico over Brazil across EM assets. Brazil’s latest CPI print was in line with consensus at 4.44%, near the upper end of the target range. In Mexico, inflation surprised modestly to the downside…
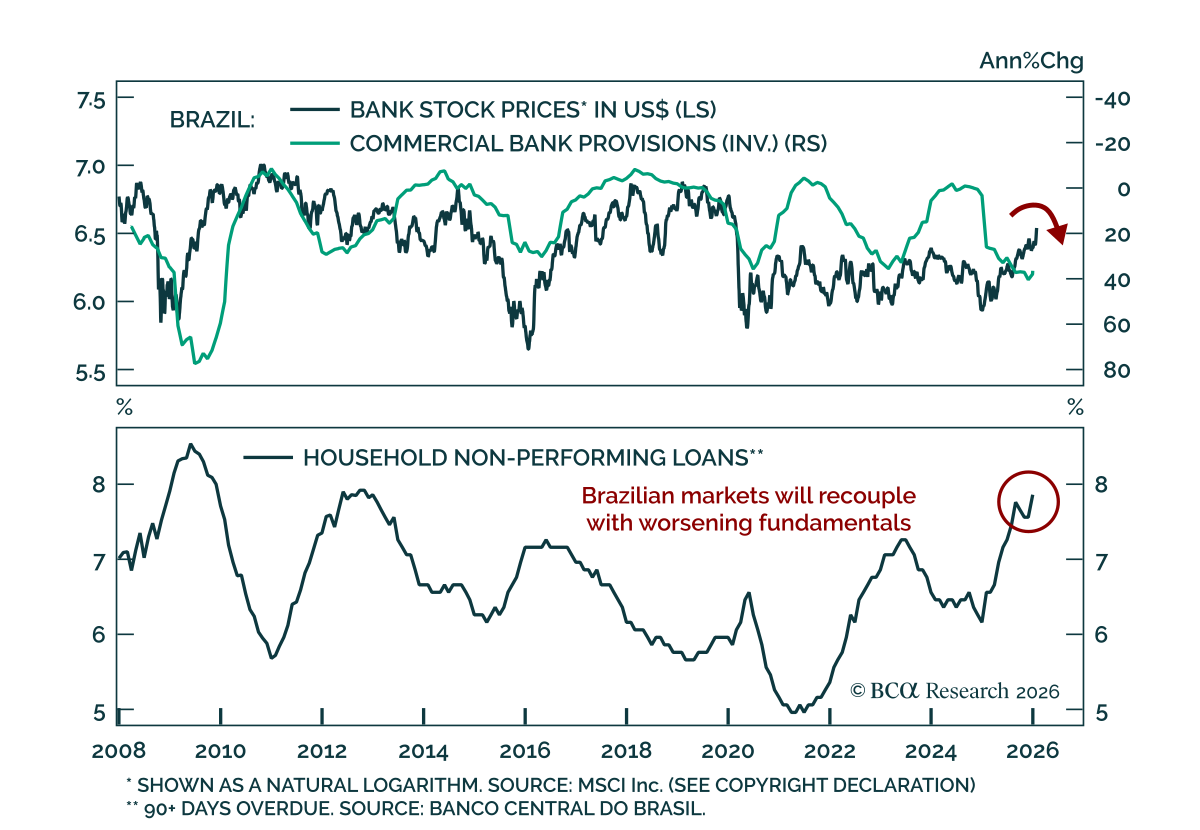
Brazilian risk assets will underperform global peers on the back of ultra hawkish monetary policy. The Brazilian Central Bank (BCB) opted to hold interest rates at 15% due to still elevated inflationary pressures. The decision will reinforce a continued…
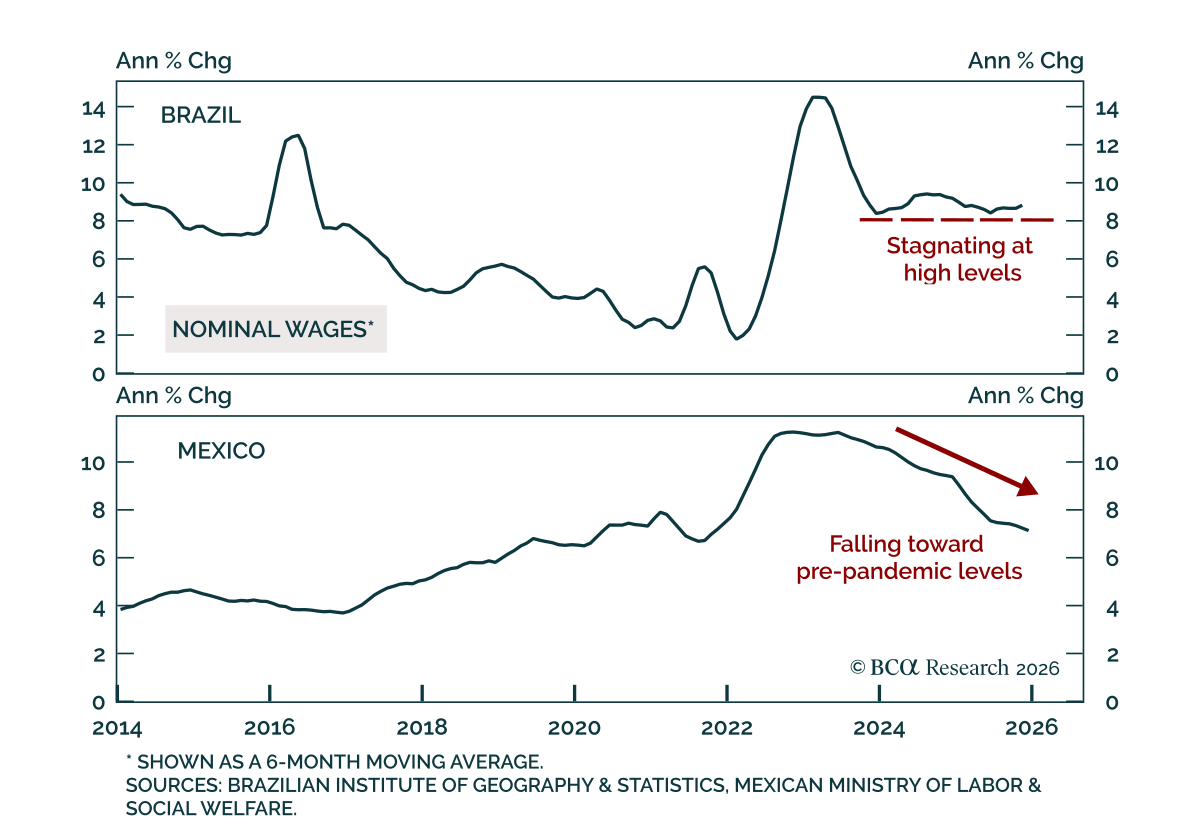
Although inflation has fallen within the upper end of the target range in both of LatAm’s largest economies, our EM strategists are more constructive on monetary easing and financial markets in Mexico than in Brazil. Mexico’s latest CPI prints surprised to…
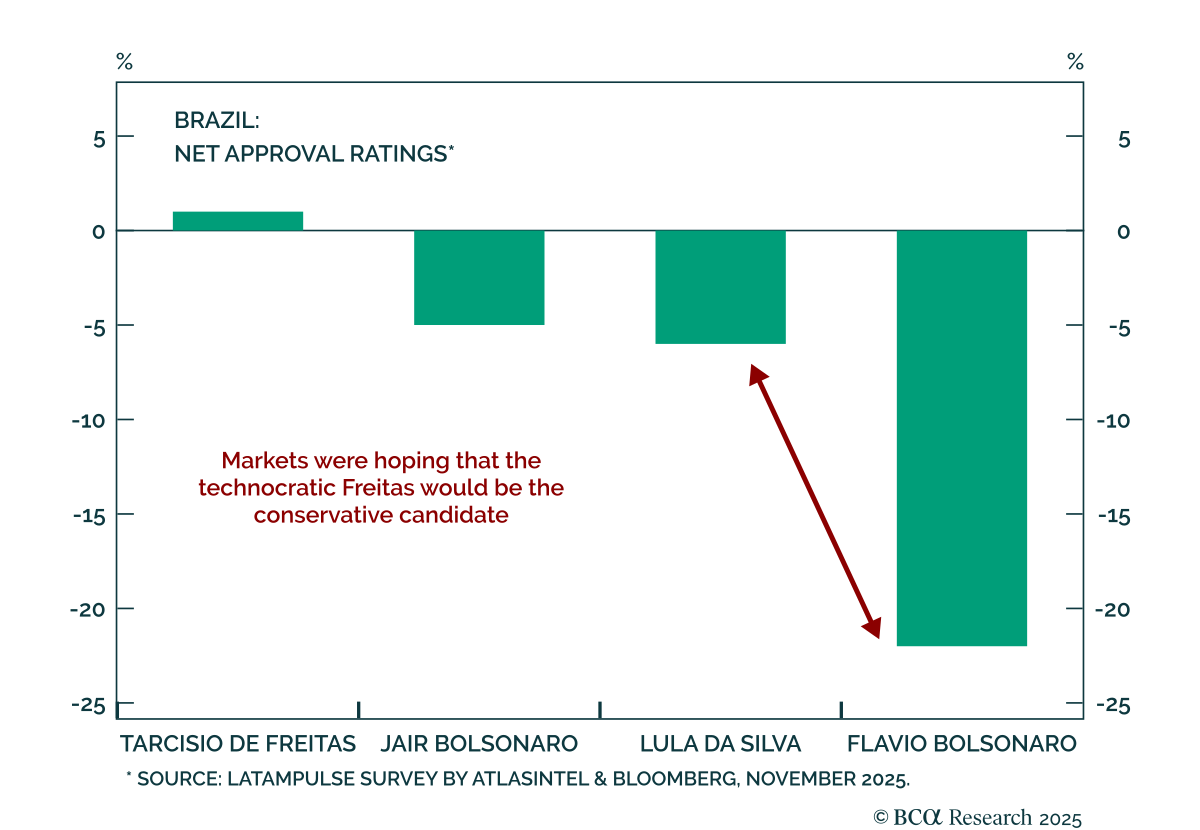
Brazil’s financial markets are on shaky ground following the central bank’s hawkish meeting and disappointing political developments, reinforcing our negative view on the country’s risk assets. The three pillars of this year’s rally in Brazilian risk assets…
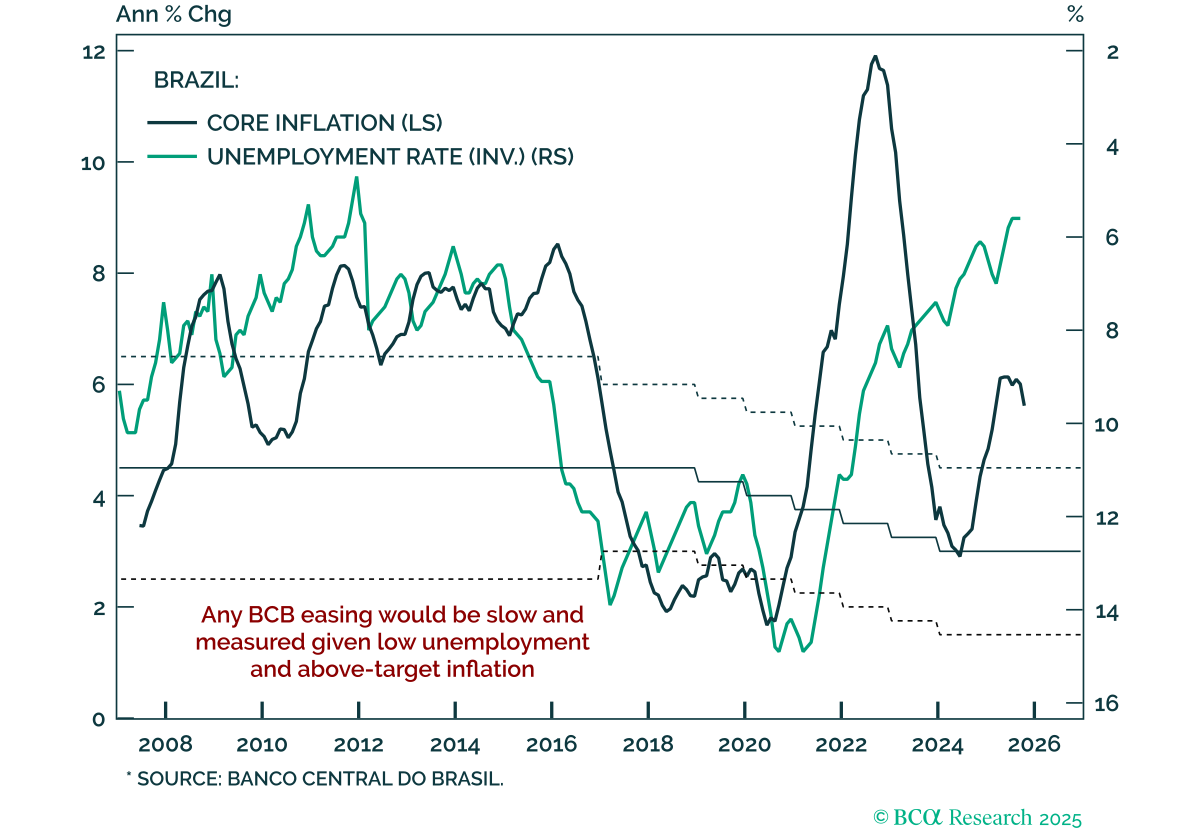
Despite a shift toward an easing bias, a December cut remains unlikely in Brazil. A BCB committee member stated the tightening cycle has ended and the next move could be a cut, shifting the bias from tightening to easing. But a single voice does not influence…
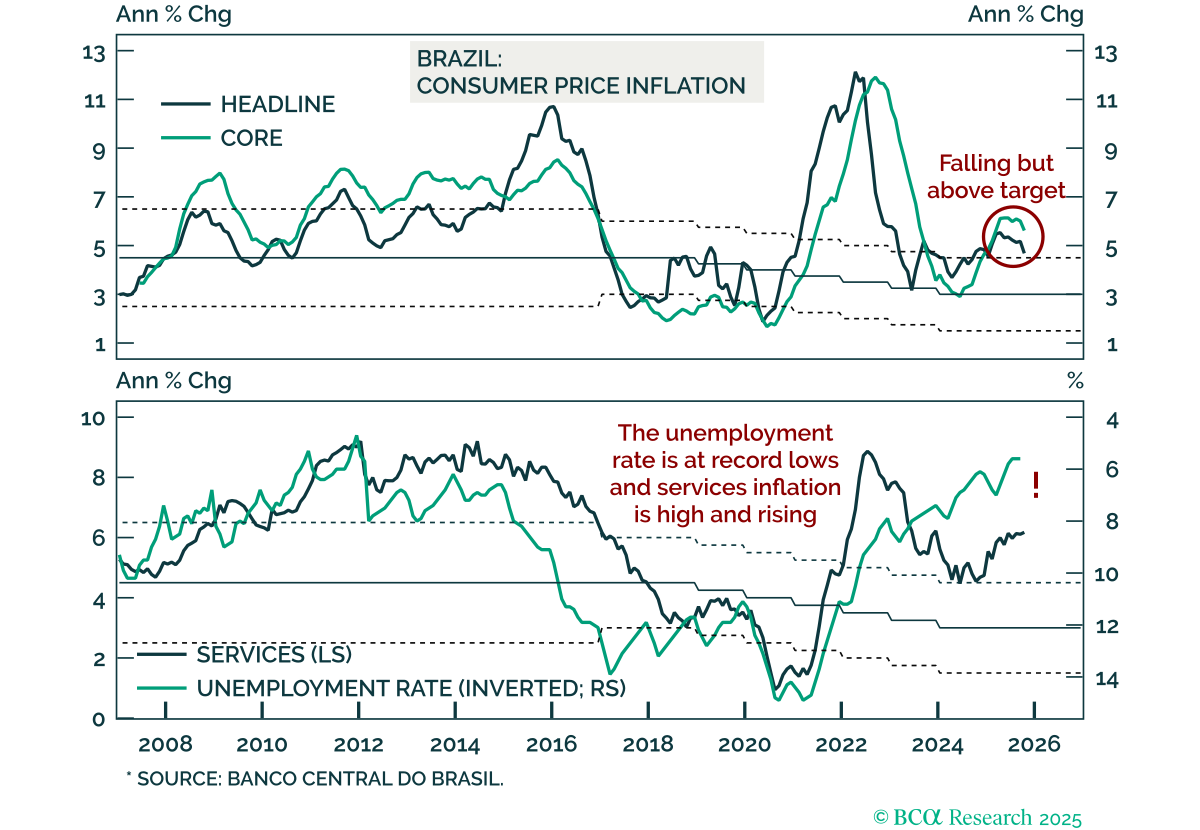
While Brazilian inflation has surprised to the downside, odds are the BCB will not ease anytime soon, creating a headwind for Brazilian markets. The October headline CPI print came in below expectations at 4.68%, lower than the 5.17% recorded in September.…
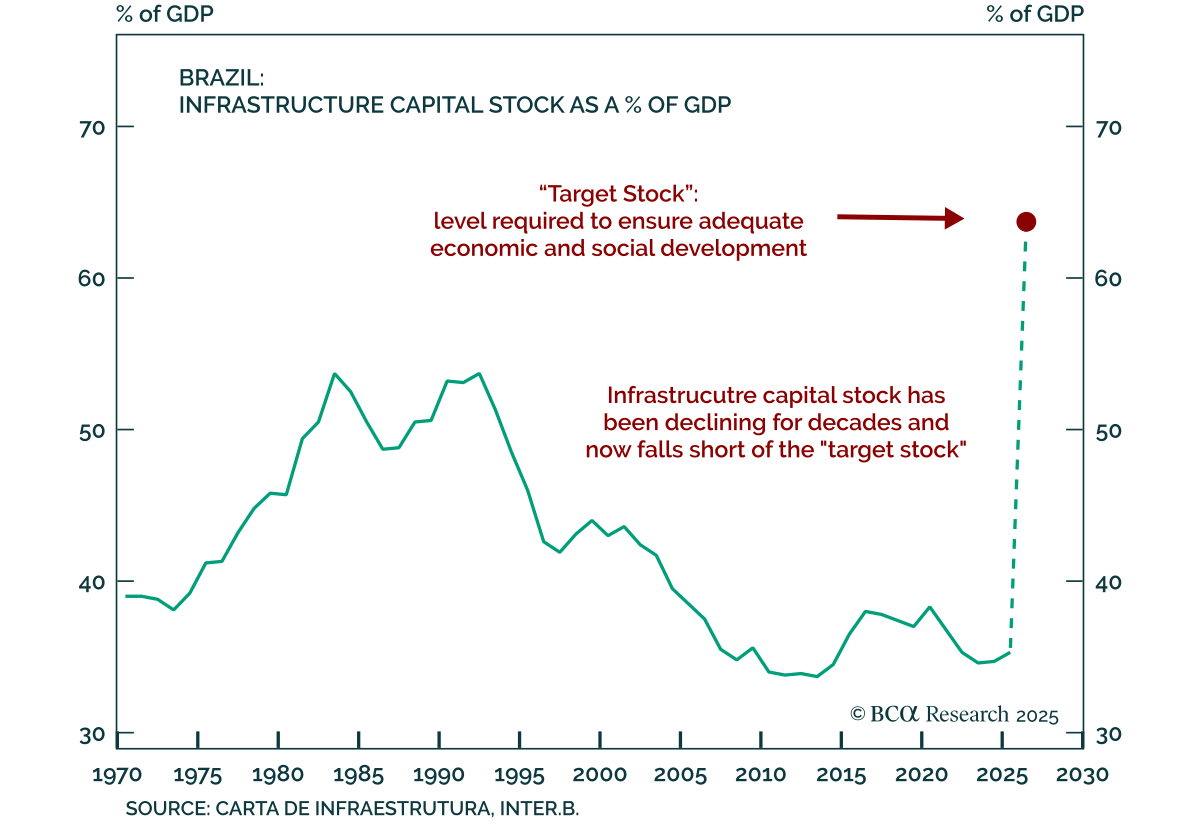
Our GeoMacro, Geopolitical, and EM strategists remain underweight Brazilian equities, local bonds, and sovereign credit over the next 6–12 months, as structural and macro constraints weigh on the outlook. Brazil has made some reform progress, but changes…
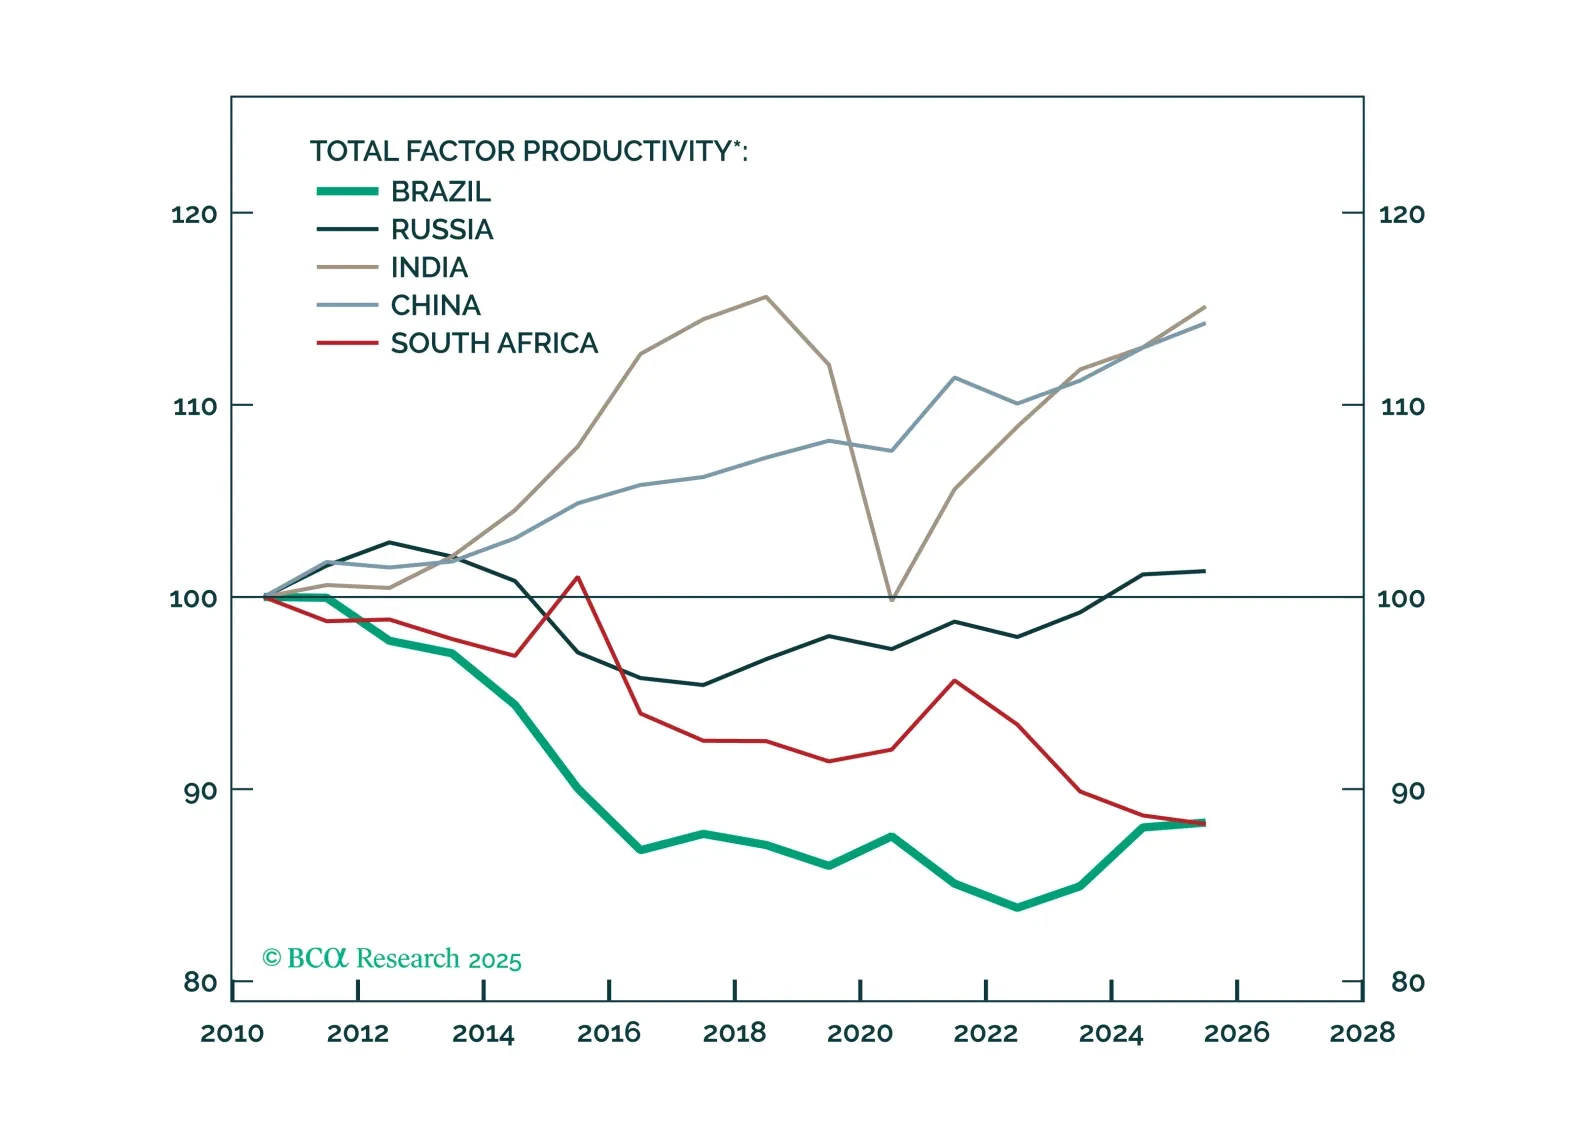
Brazil’s bleak macro outlook persists – rising debt, weak productivity, and political inertia. With 2026 elections looming, genuine reform seems unlikely, though Argentina’s bold turnaround could pressure Brasília to rethink its cycle of governability over growth.
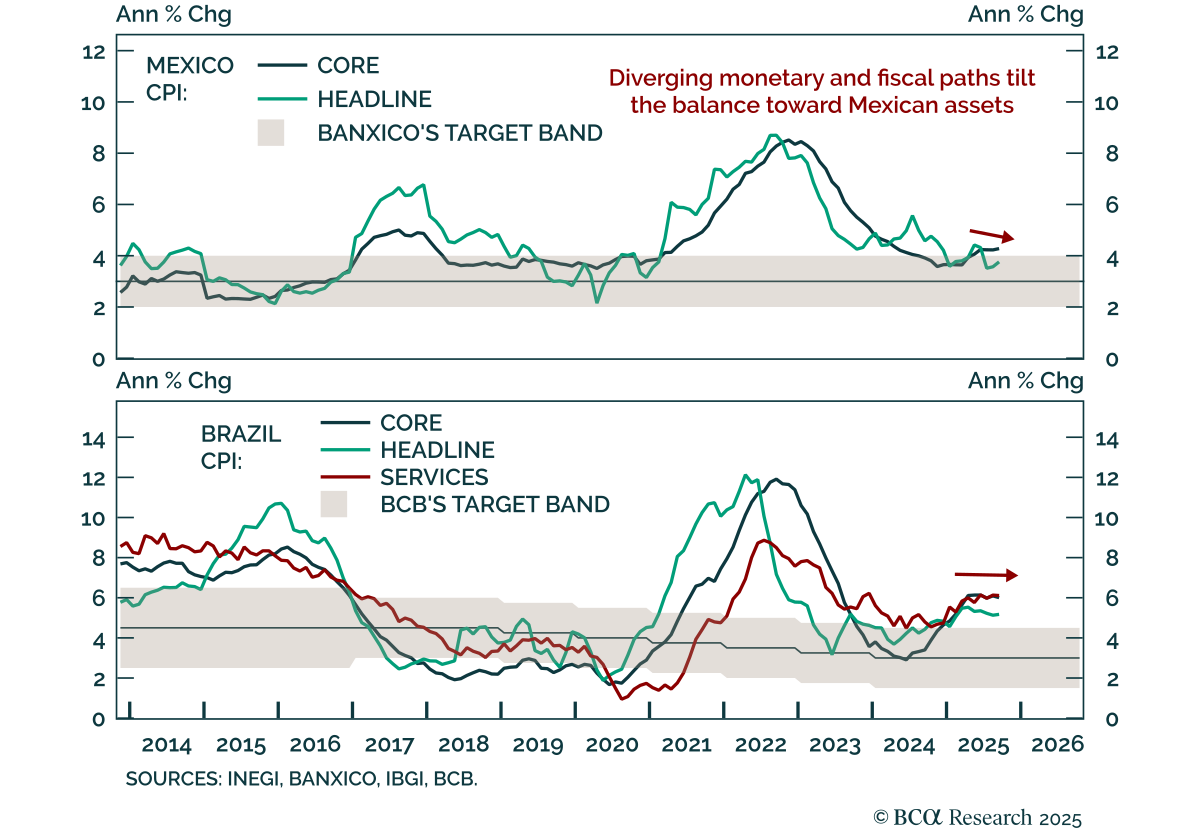
September CPI releases in Brazil and Mexico reinforce a divergent inflation and policy outlook that supports an overweight stance in Mexican local bonds and currency relative to Brazilian assets. Brazil’s headline CPI at 5.2% was slightly higher than in…
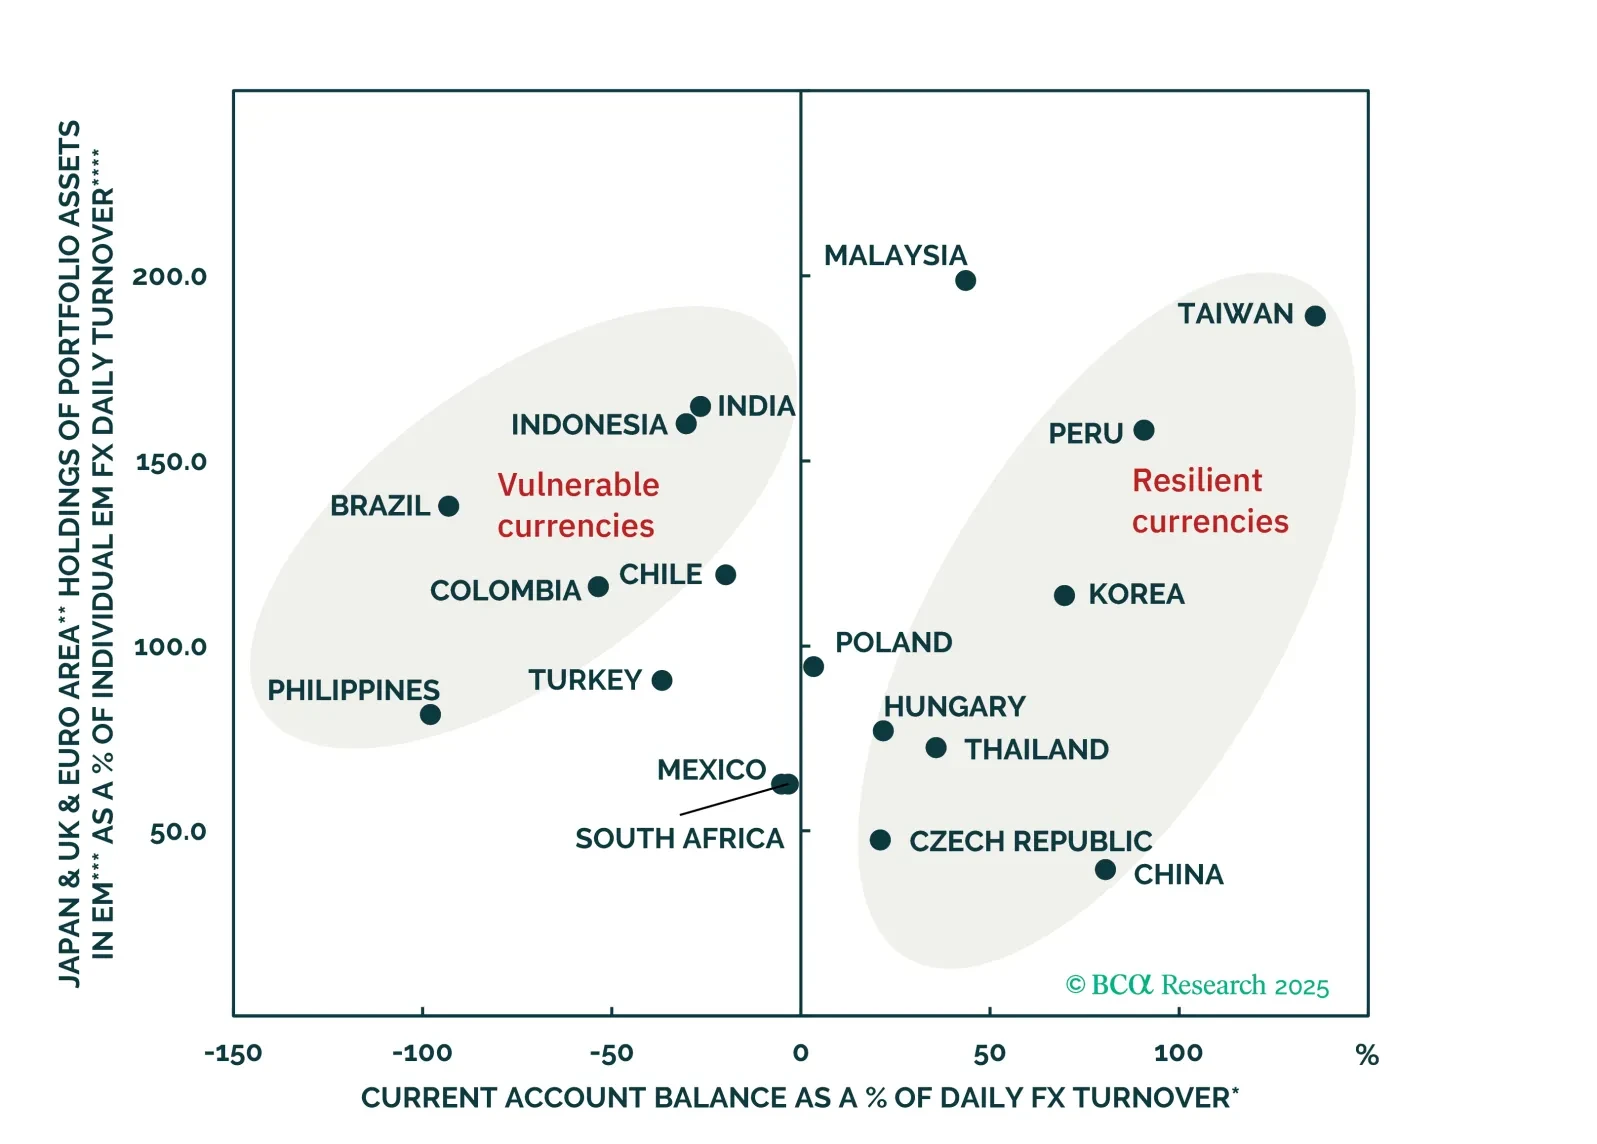
Despite widespread investor optimism Brazil’s currency outlook is challenged by a toxic mix of poor external, fiscal, and macro fundamentals. Expect BRL to underperform most EM peers.