財政政策
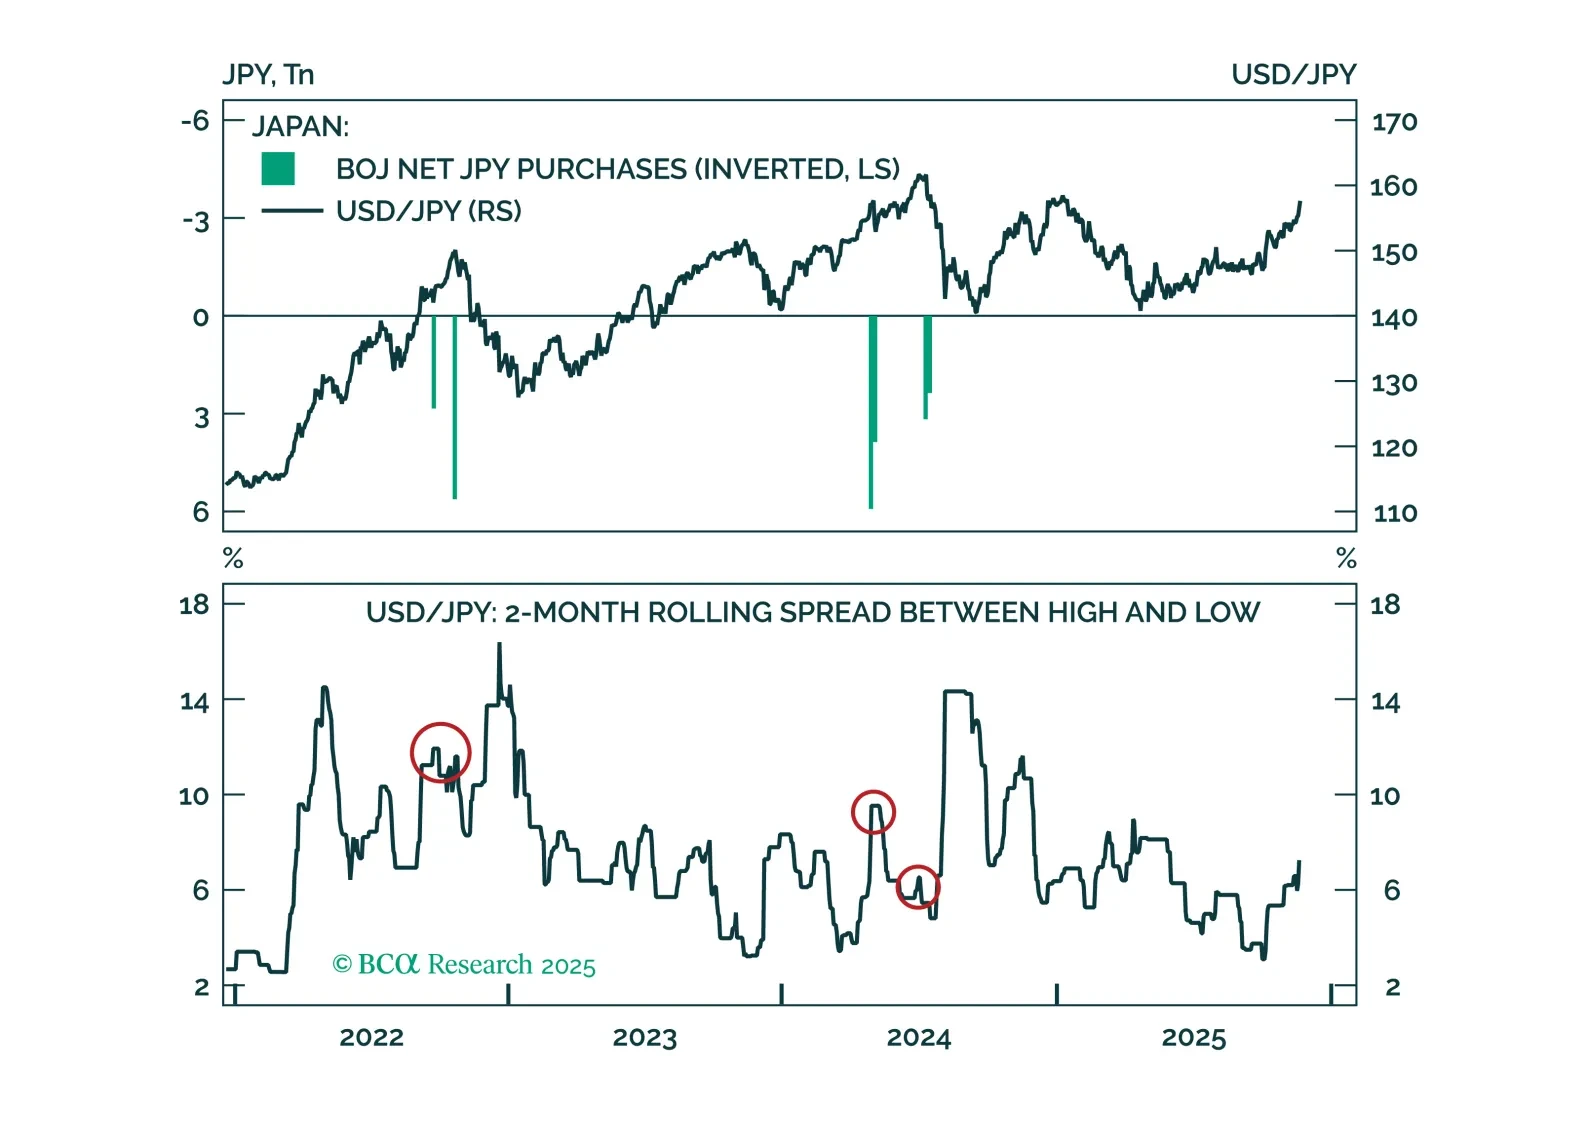
市場は日本の財政に関する見出しを誤解しています。最新のインサイトでは、次に日銀政策を左右する要因、介入の可能性、そして円反転のタイミングについて検討します。
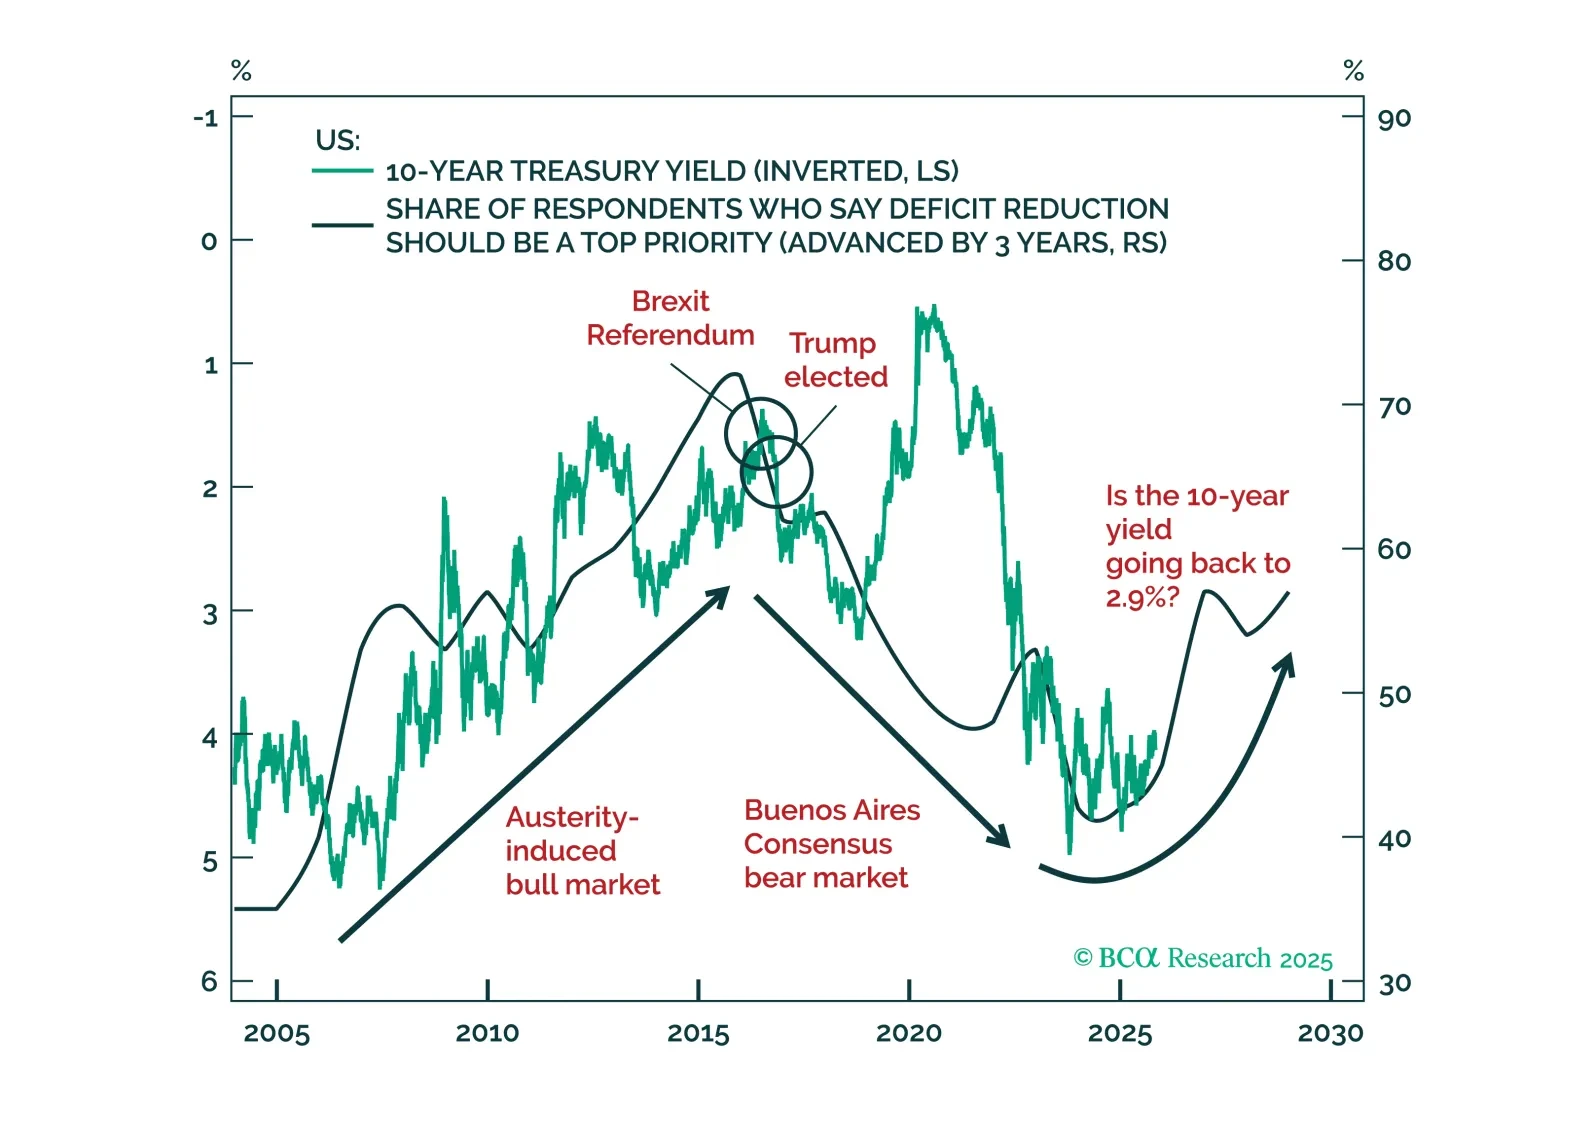
デタント(中国と米国の関係改善)は大きな出来事です。経済データは引き続きFRBに利下げの理由を提供しています。何を心配する必要があるでしょうか?ほとんどありません。ただし、2026年について考え始めるにあたり、いくつか弱気な考えを検討します。
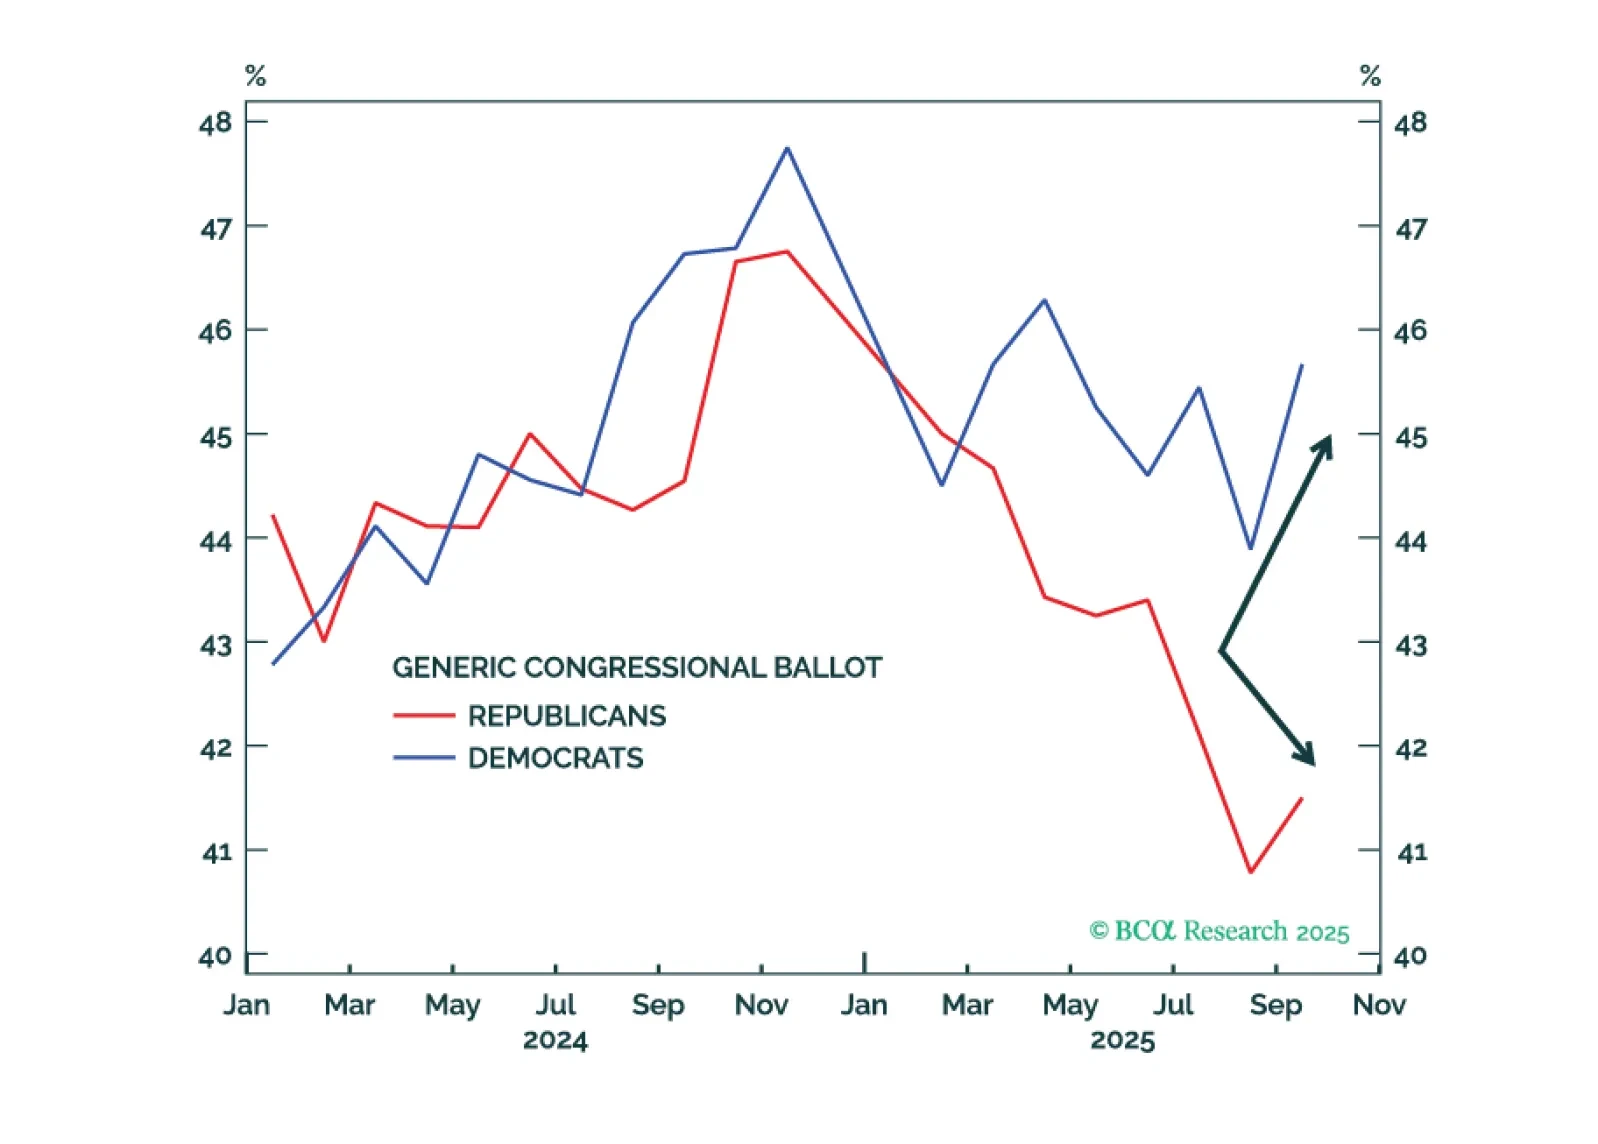
連邦政府閉鎖の可能性は3分の1と見ています。11月以前に発生する可能性は低いでしょう。最悪の場合、政府閉鎖は一時的な市場の変動を引き起こすだけです。
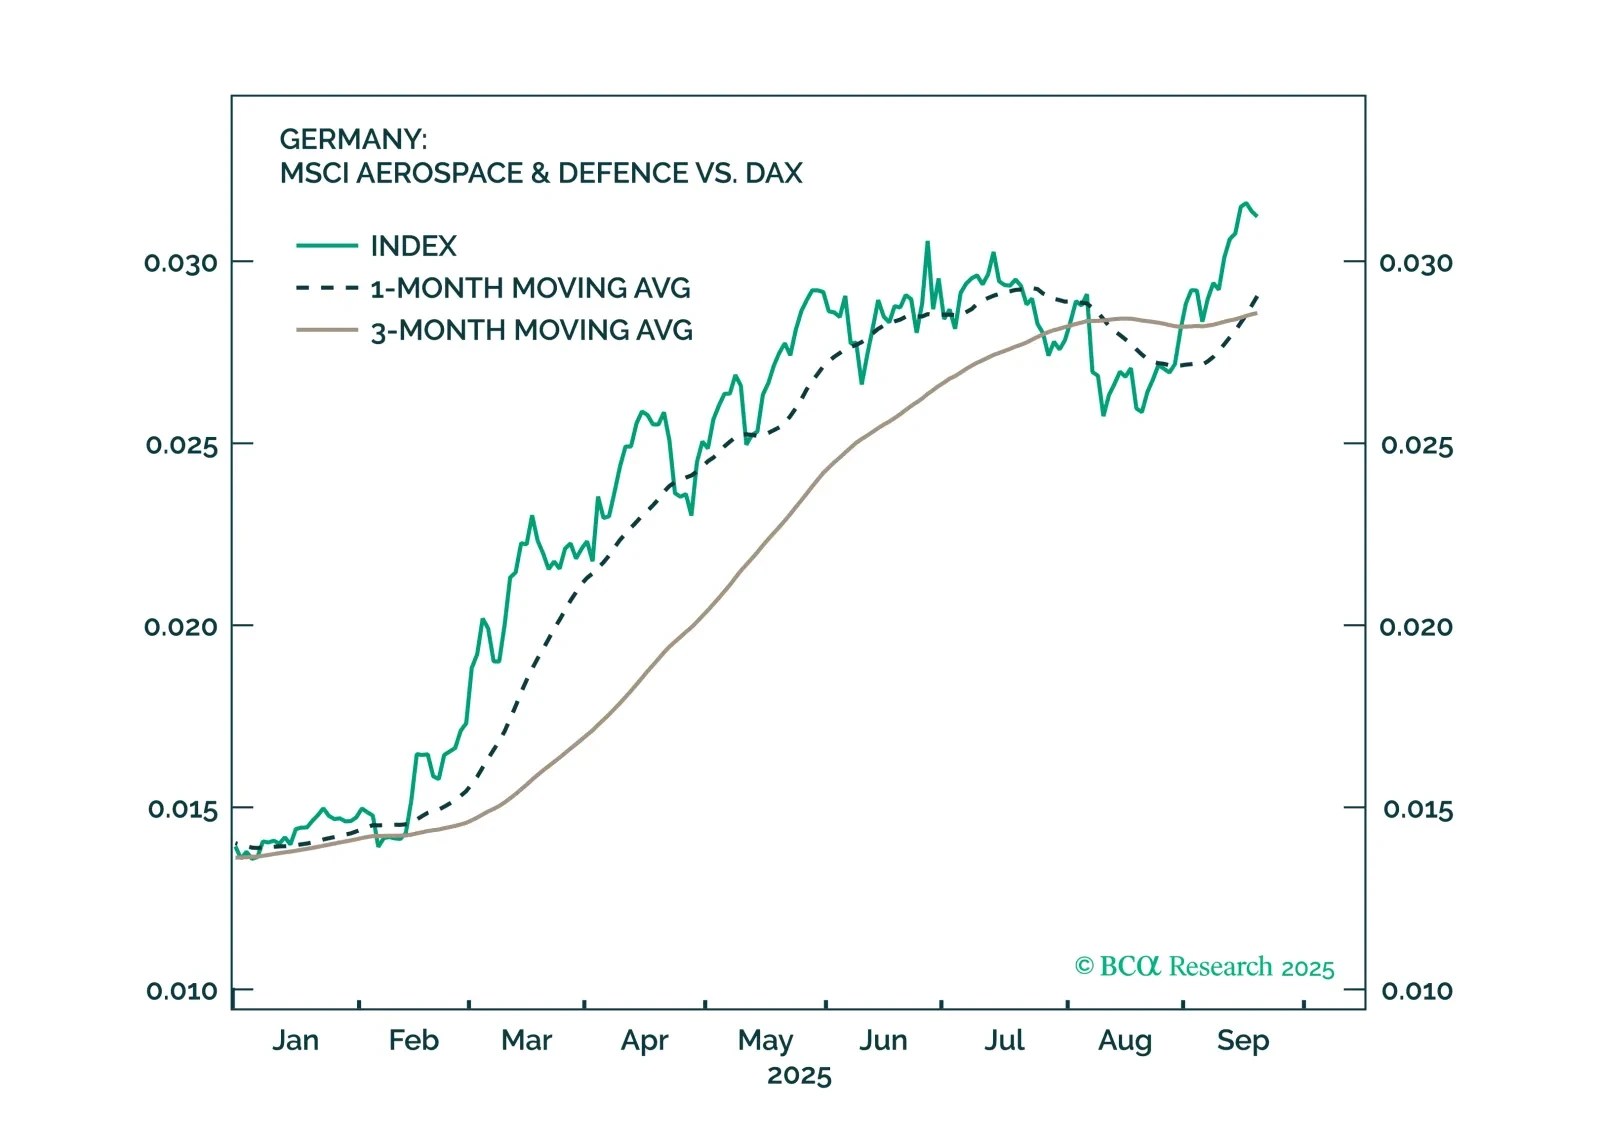

インドネシアの政策緩和は国内需要を押し上げるが、インフレを助長します。経常収支赤字は拡大し、ルピアは下落するでしょう。ルピアをショートで維持し、インドネシア株、国内債券、ソブリン信用をそれぞれの新興市場ポートフォリオでアンダーウェイトにしてください。
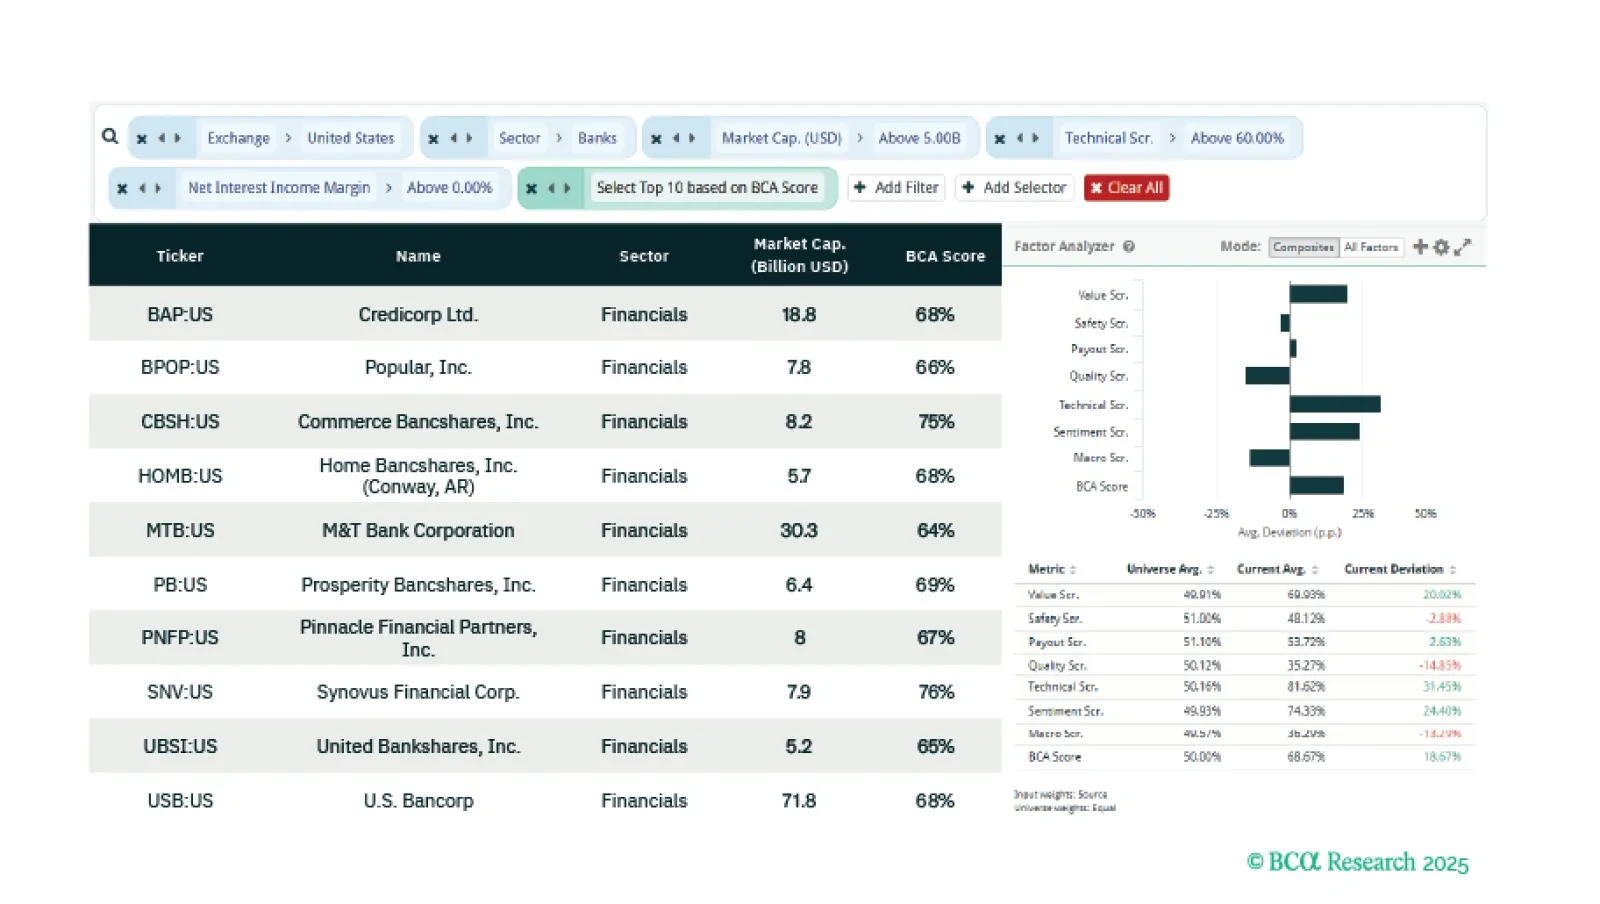
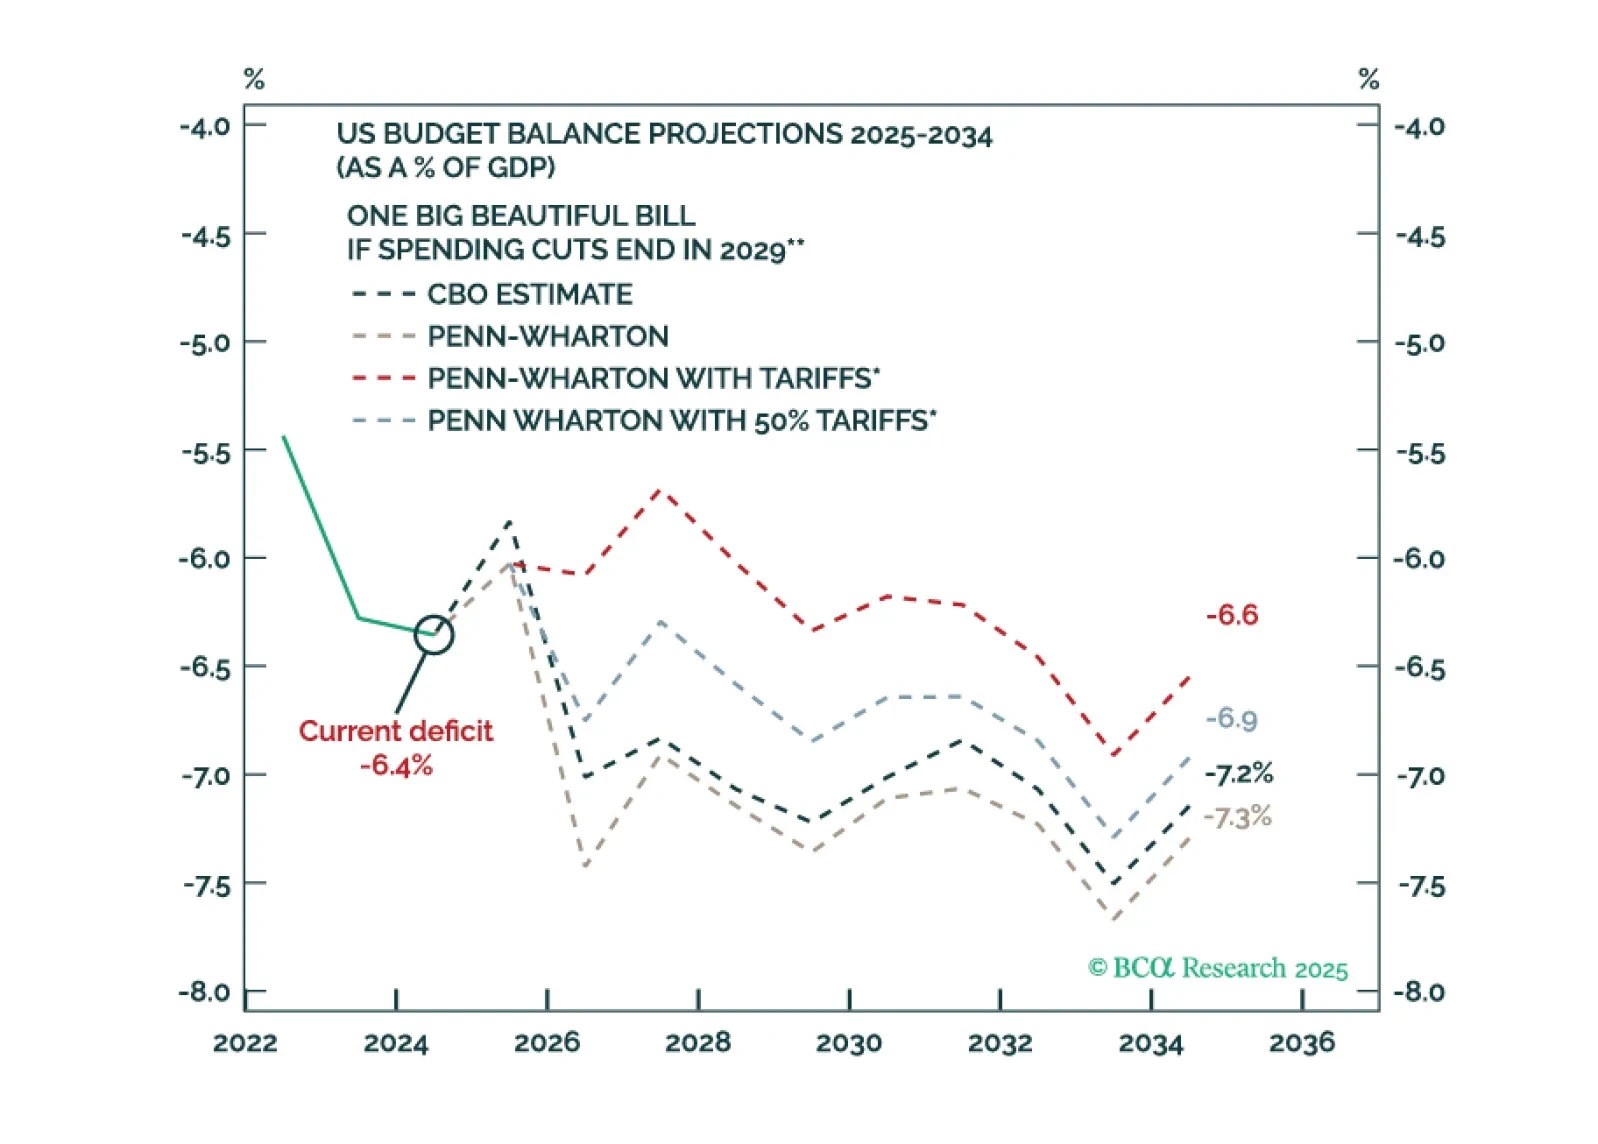
Bond market volatility will spike again in the near term. The Fed is committed to an easing cycle yet the Trump administration’s signature fiscal policy action will stimulate the economy. Tariffs are supposed to keep the budget deficit contained but they are inflationary.
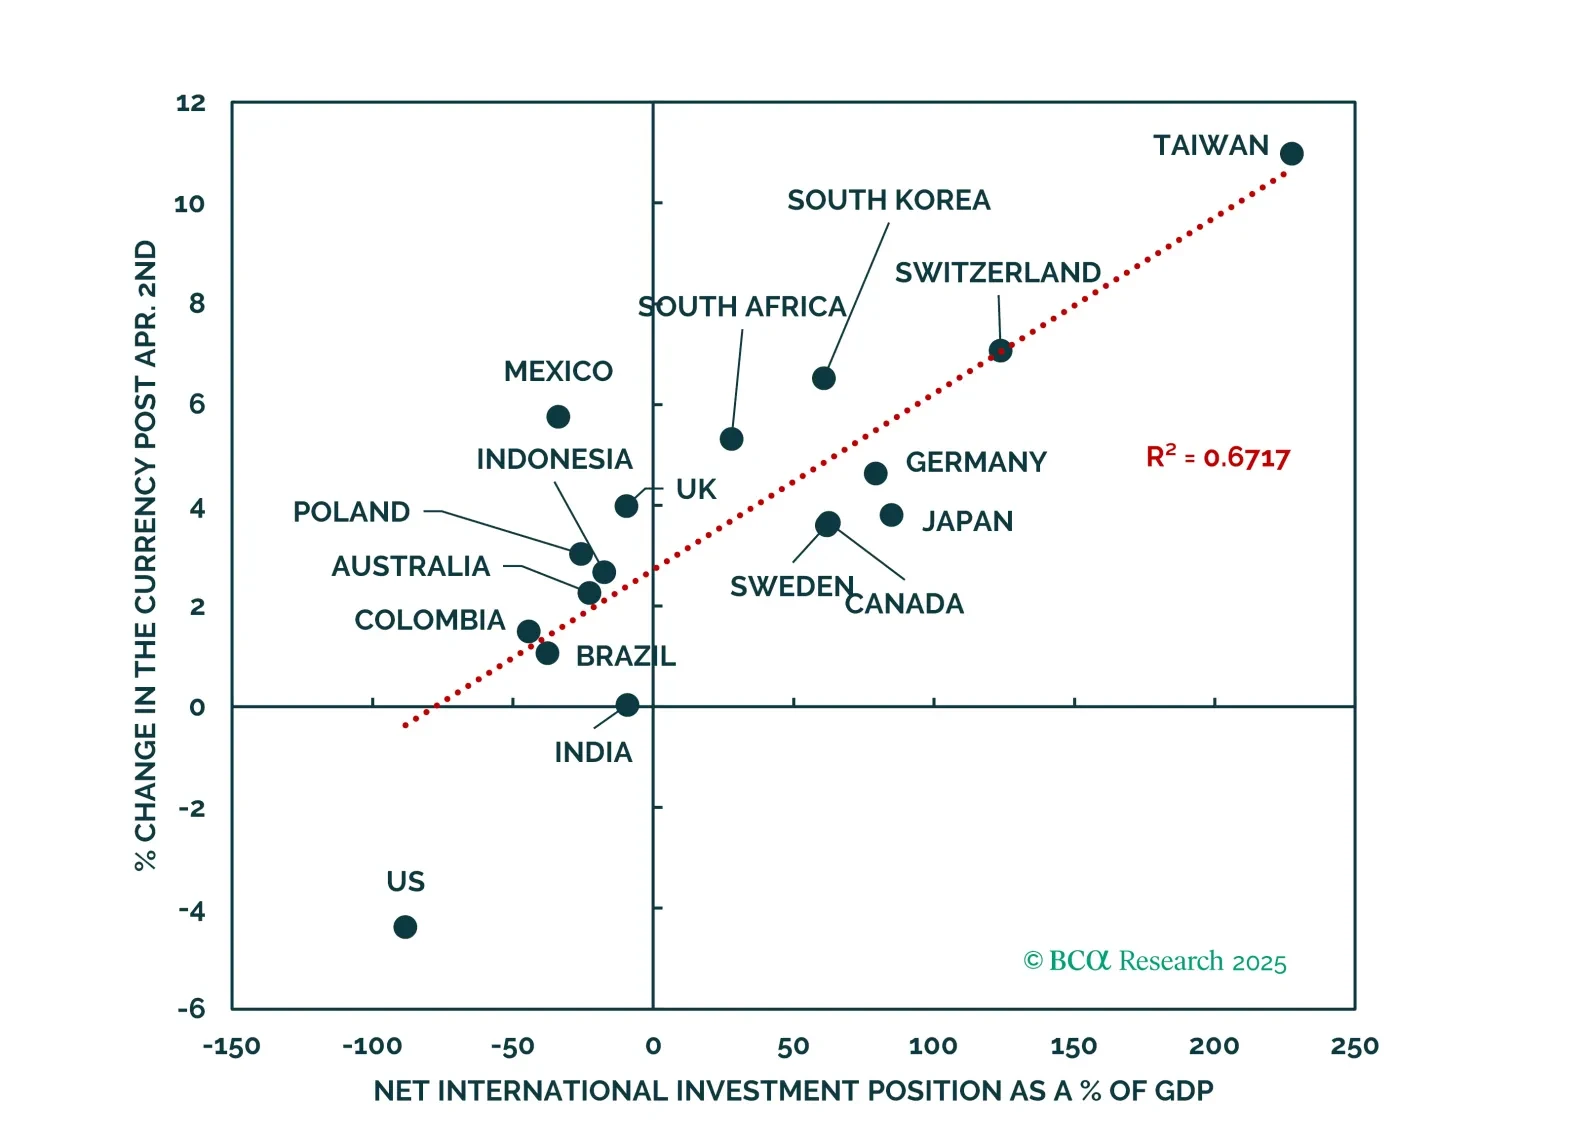
Fiscal policy, not tariffs, is now driving markets as Congress advances the One Big Beautiful Bill. The Senate cannot afford to remove the spending cuts in the bill, as they risk sparking a bond market riot. Even with this more modest bill, US interest rates are already pressuring housing and labor markets. US assets are also losing their defensive tilt. Better opportunities for both equity and fixed income investors are available internationally. We conserve our defensive stance but do not want to be dogmatic. Sentiment is more cautious than last year, and the US economy is not showing signs of imminent collapse. We remain underweight the US dollar and US equities. Upgrade Communication Services and downgrade Consumer Staples. Upgrade the CNY and EM currencies to neutral.
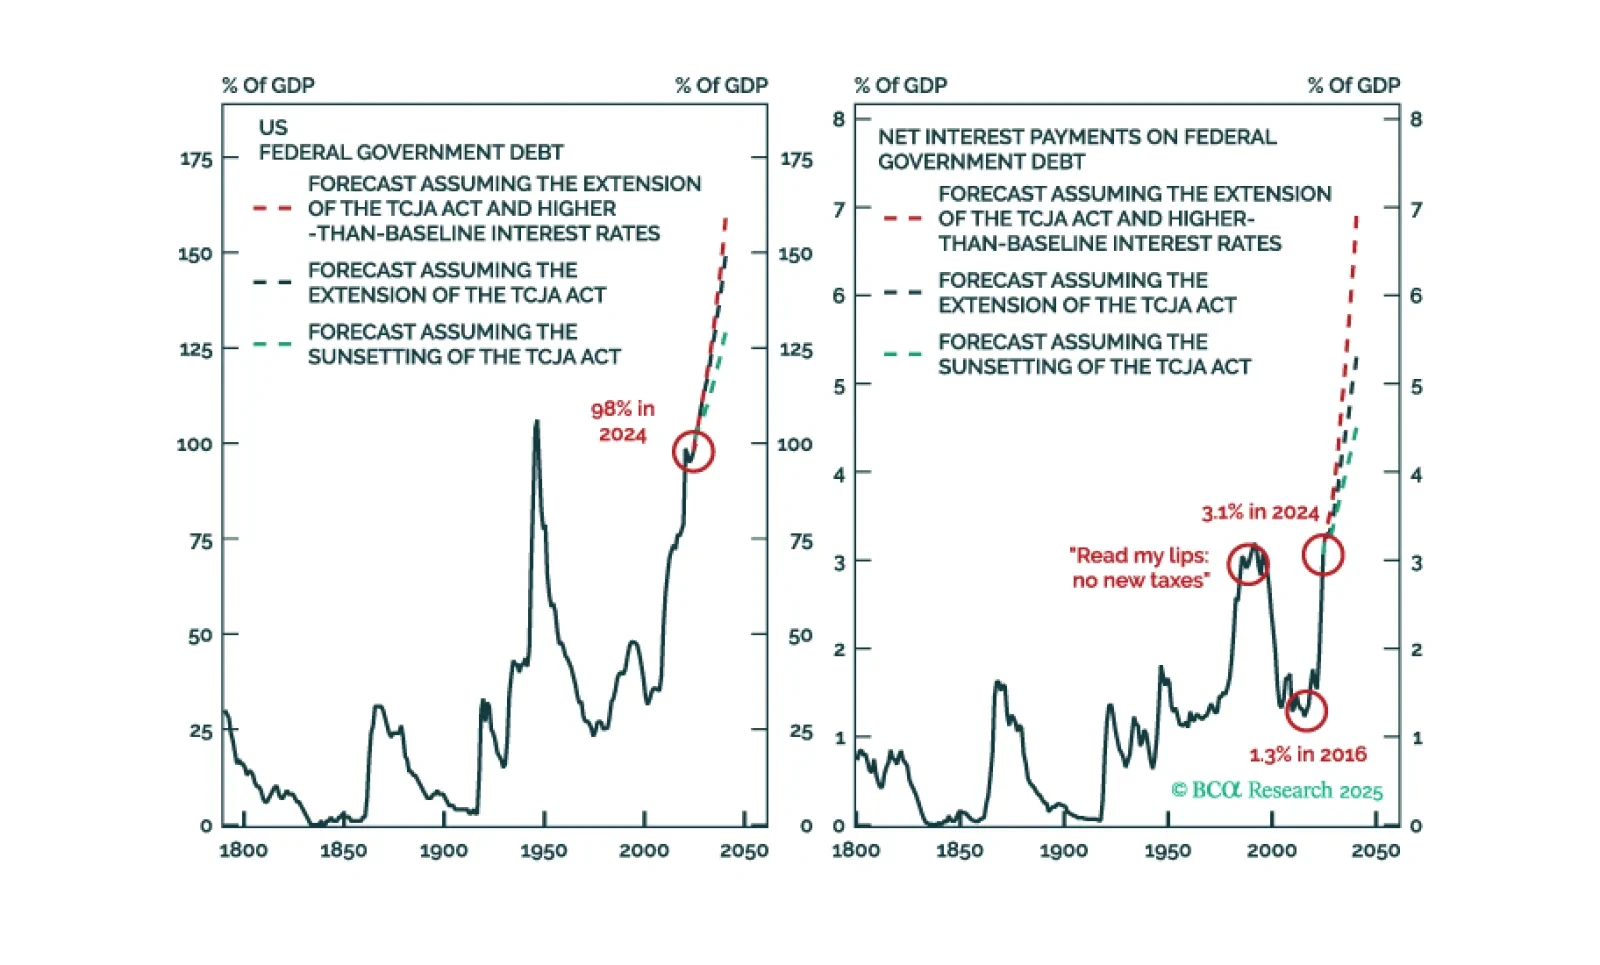
Rising bond yields may present an even greater danger to the global economy than the trade war. With equity valuations no longer discounting much economic risk, investors should position themselves defensively.
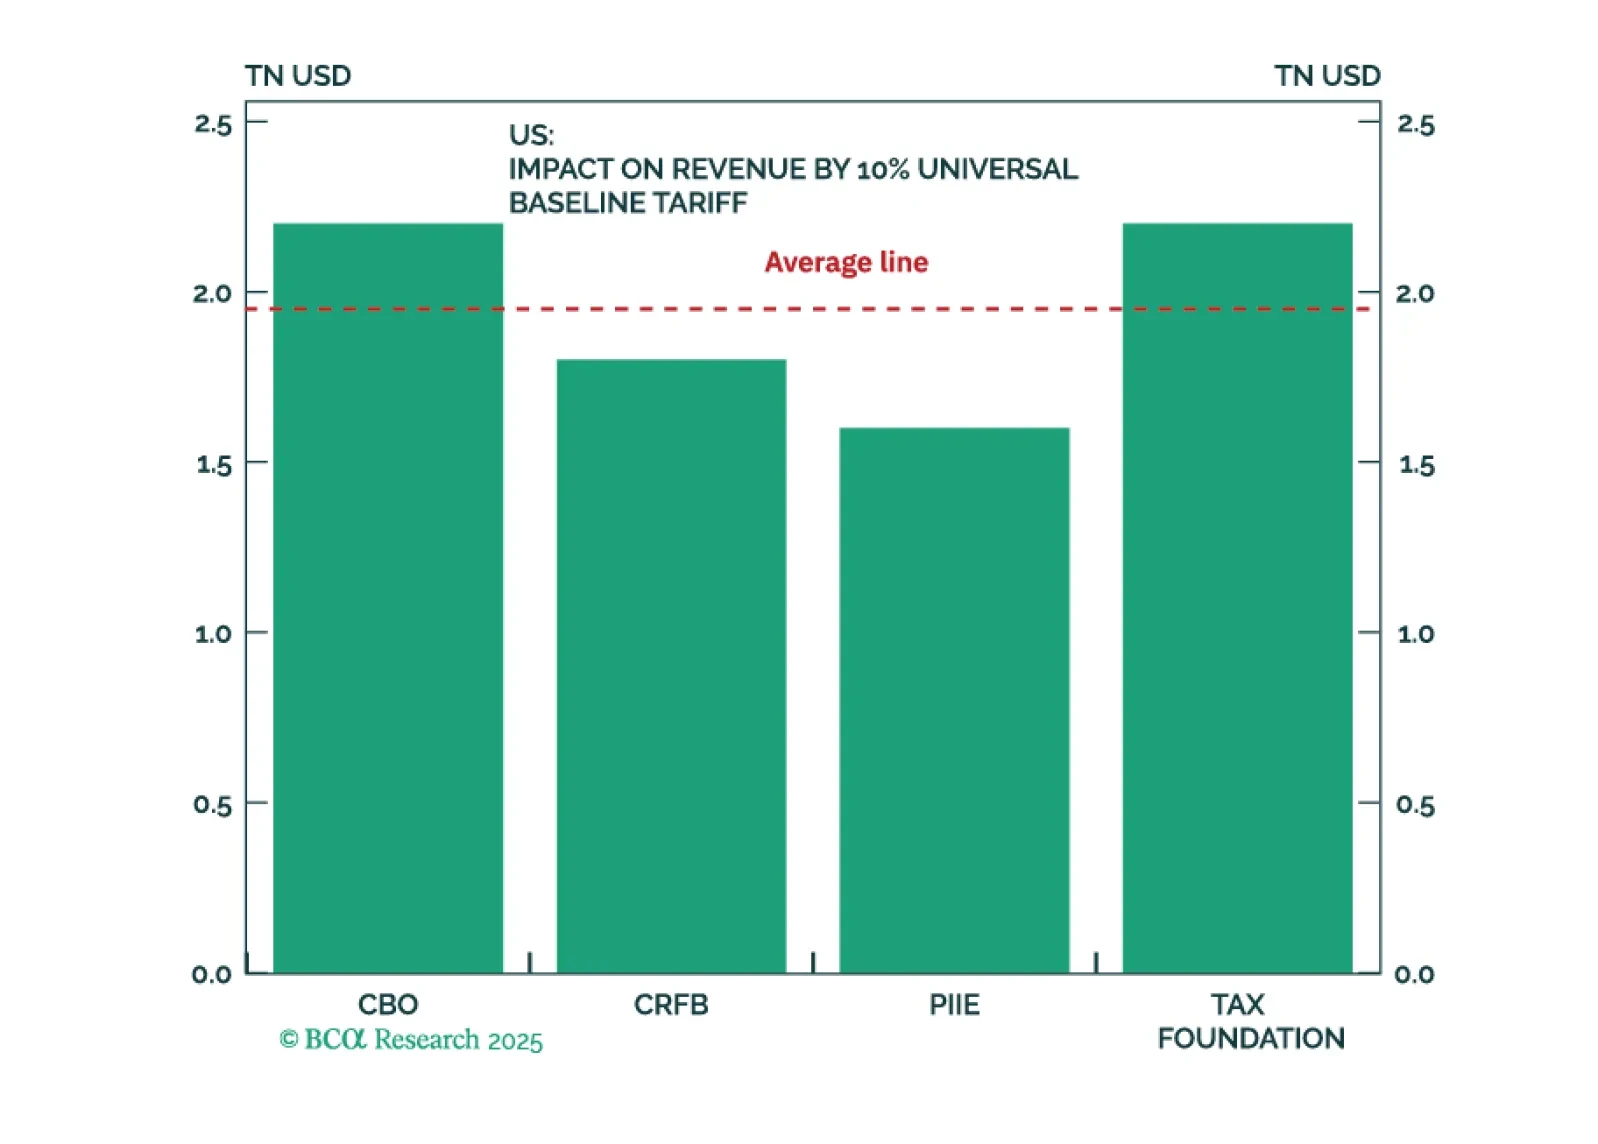
Trump’s signature bill is surprising to the upside with budget deficits, as predicted. Some version is guaranteed to pass – but higher bond yields and inflation will weigh on the economy and stock market.