Las políticas de Trump
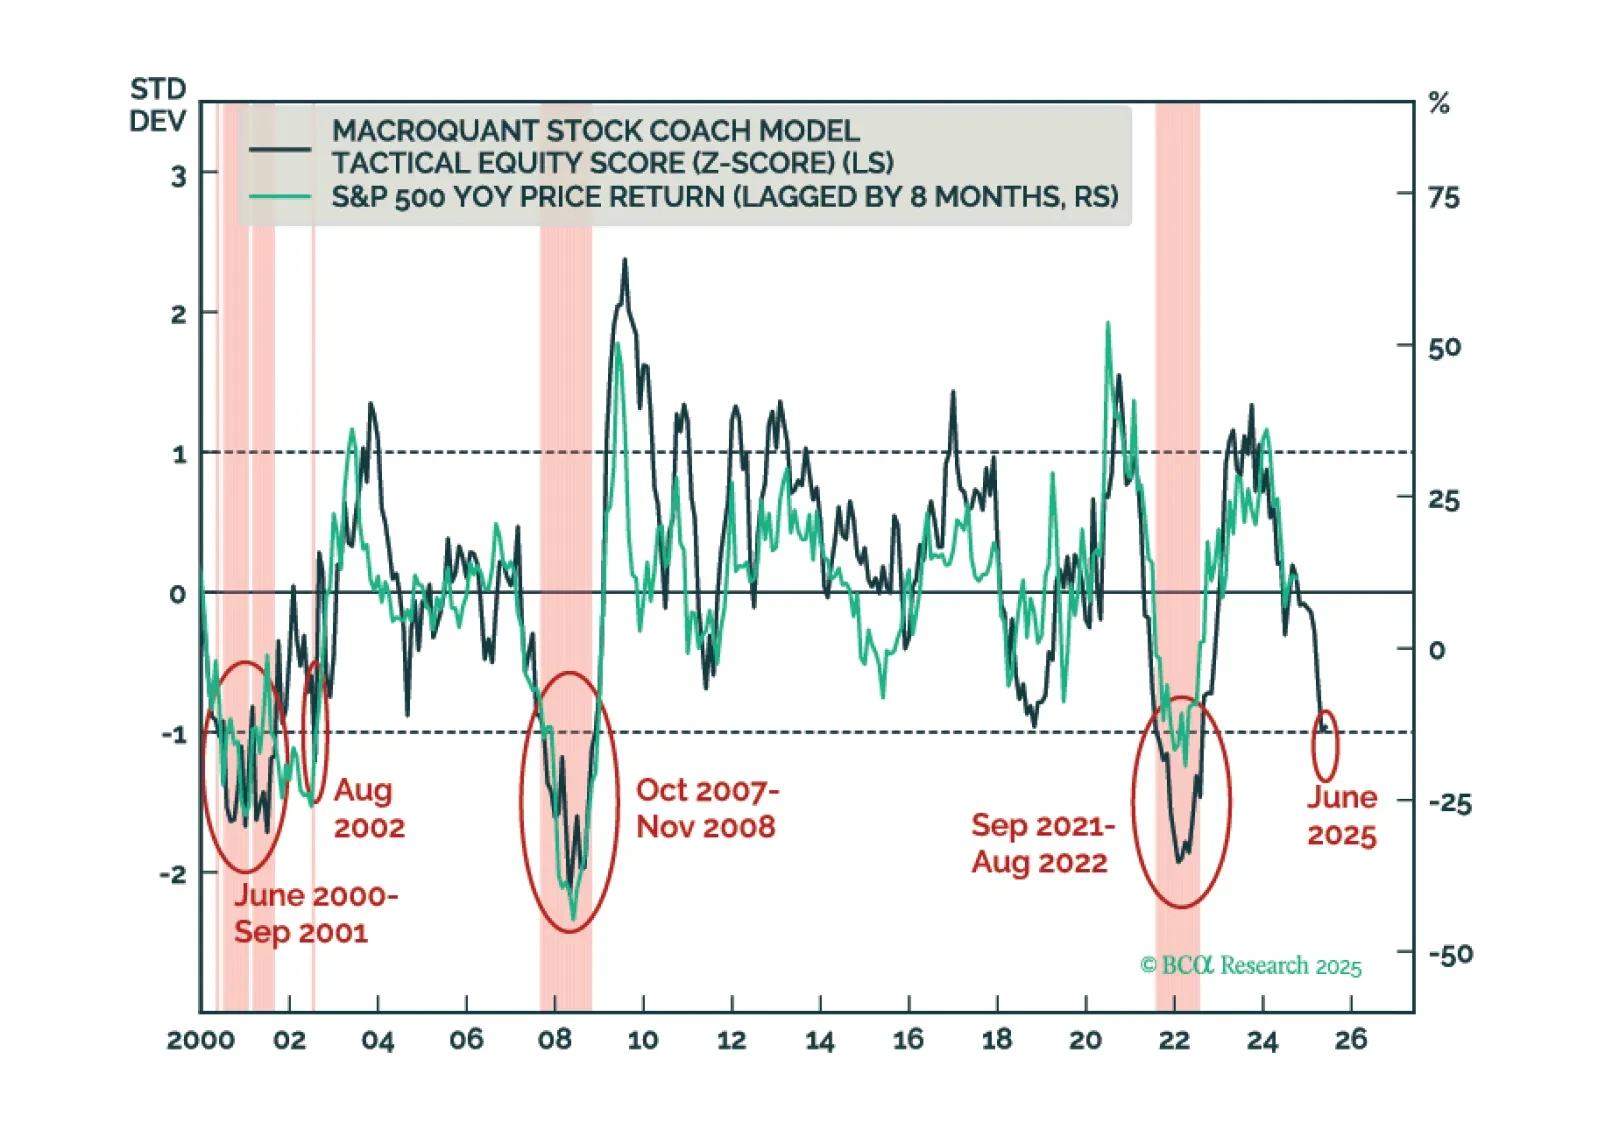
Los inversores deberían reducir modestamente la ponderación de las acciones en sus carteras y buscar adoptar una posición más agresivamente defensiva una vez que los signos claros de la recesión sean visibles. Creemos que eso sucederá en los próximos meses.
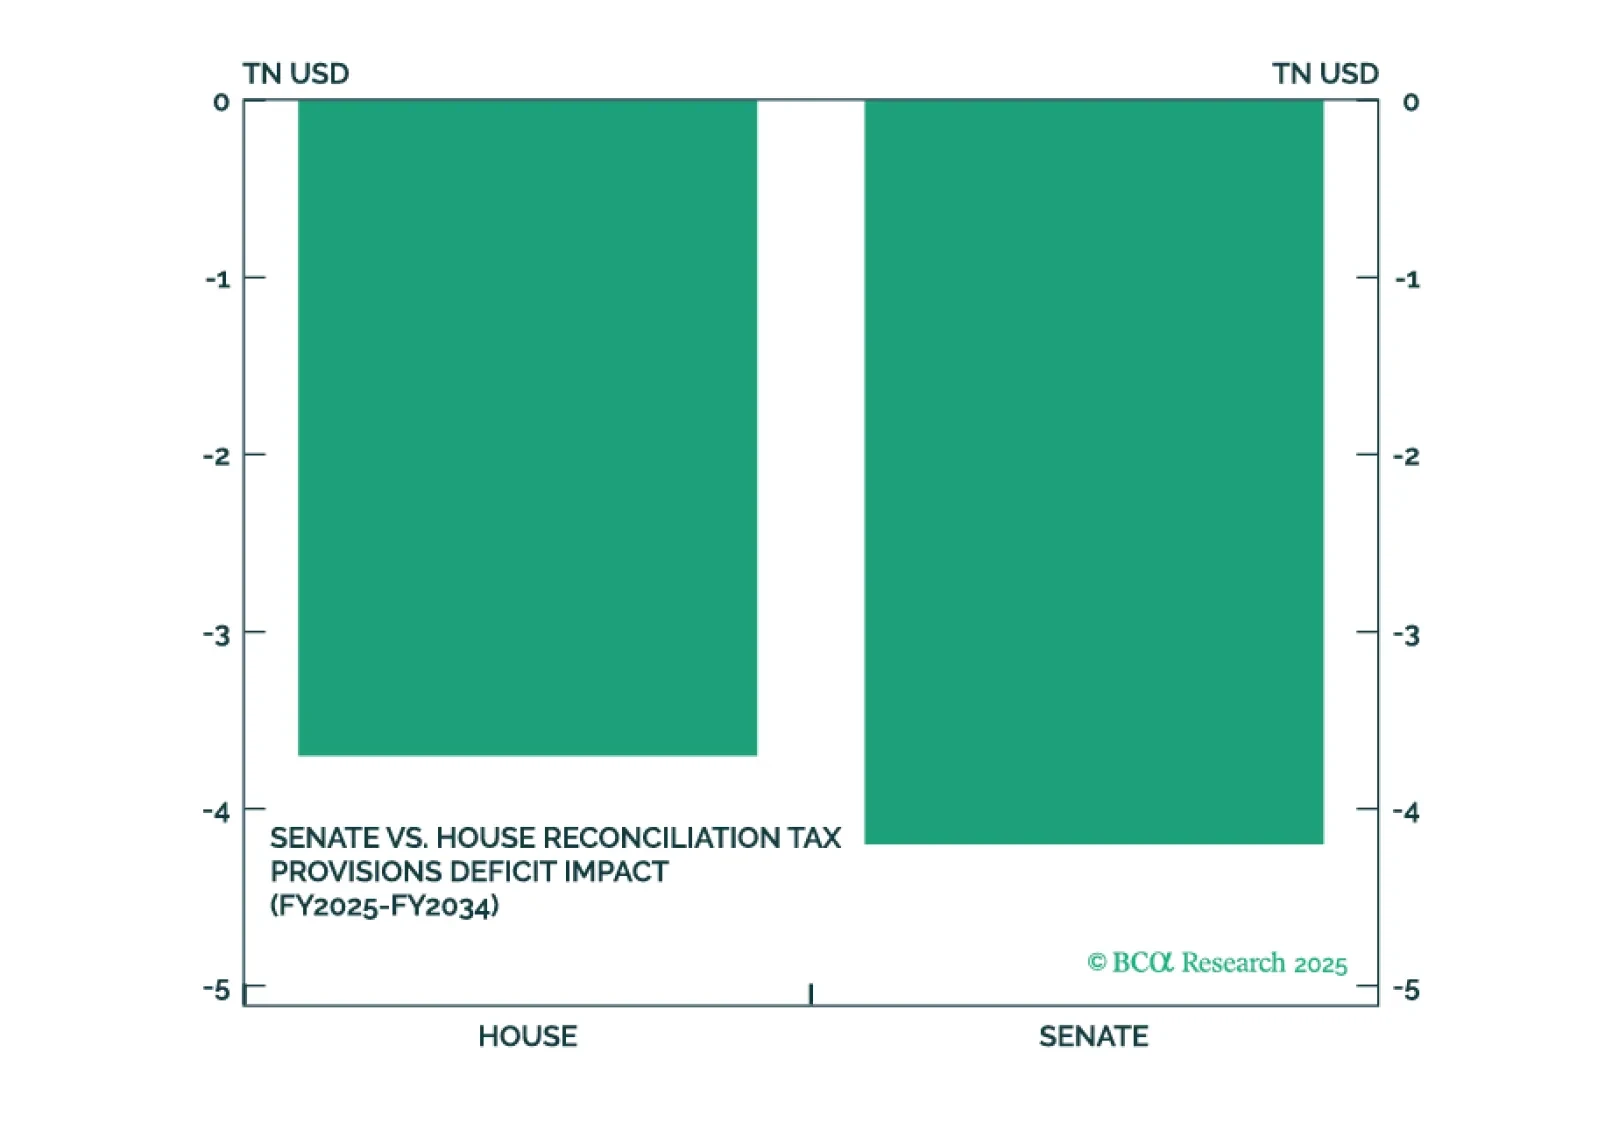
El gran y hermoso proyecto de ley del presidente Trump se aprobará pero enfrentará obstáculos a corto plazo y no ajustará el cinturón del gobierno. Se combinará con la implementación renovada de aranceles para generar un riesgo a corto plazo tanto para el mercado de bonos como para el mercado de valores. La crisis de Irán se desvaneció, salvando a Trump de un gran impacto petrolero que podría haber descarrilado su segundo mandato.
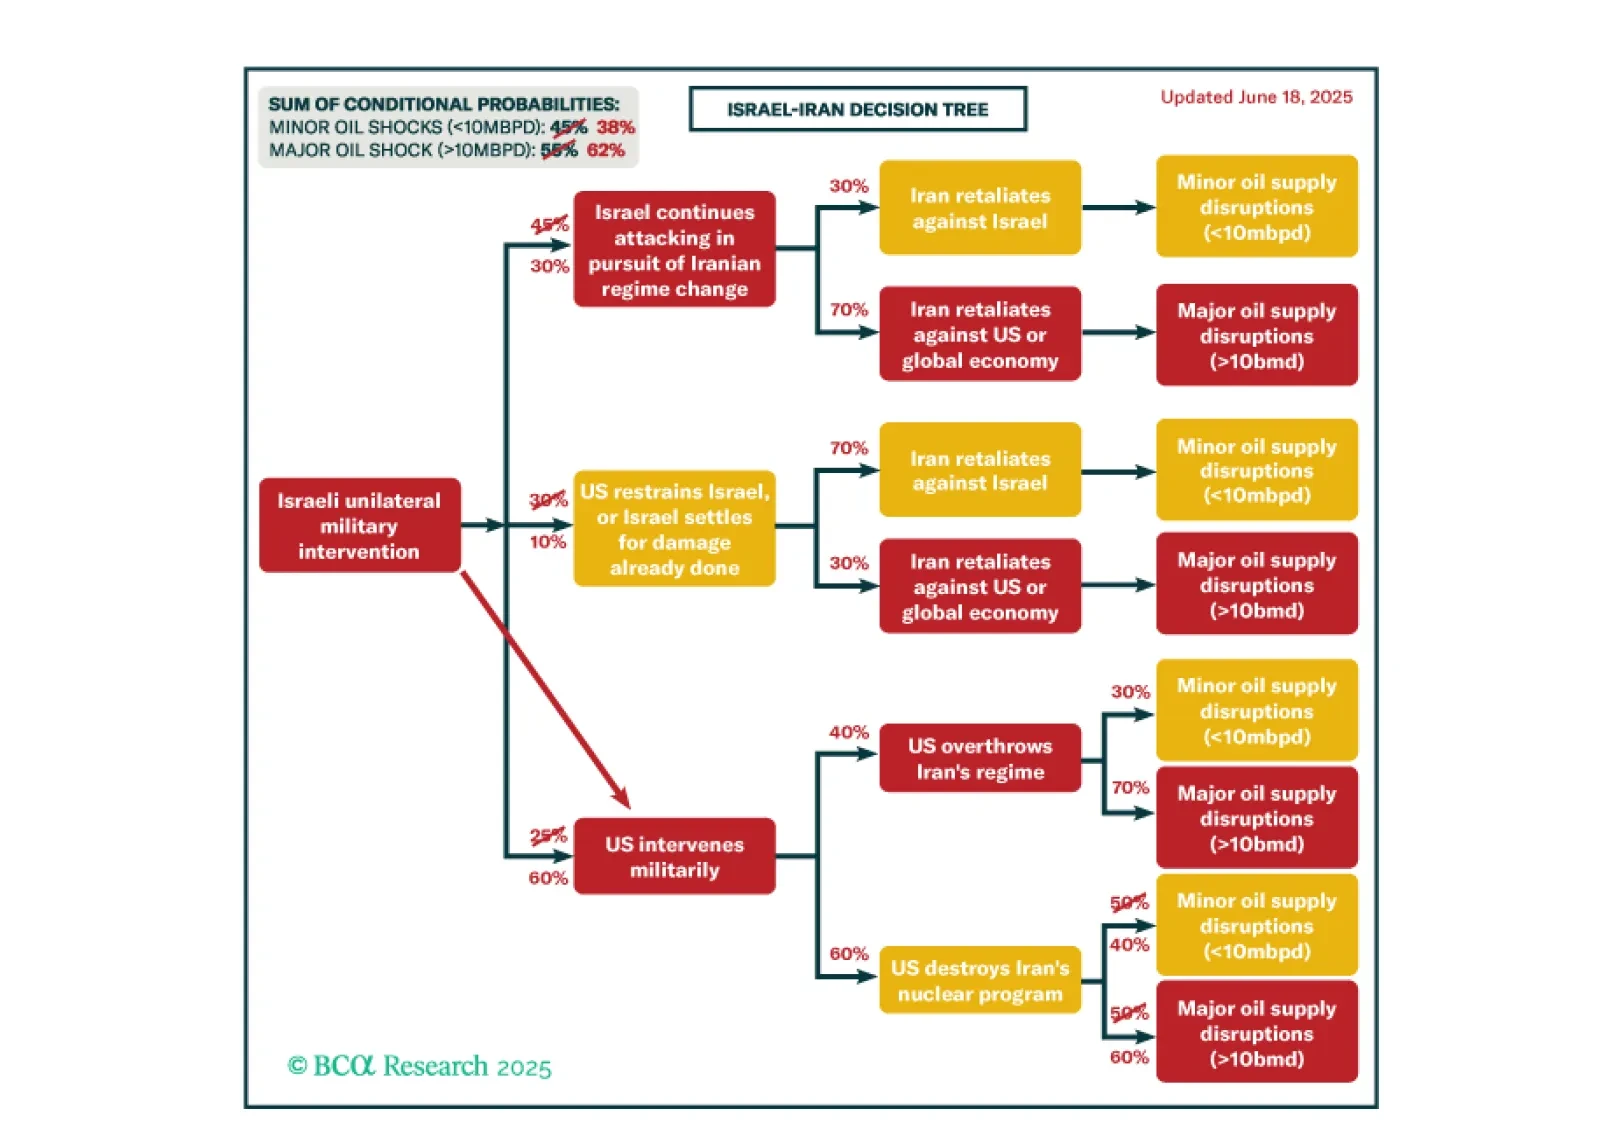
Incluso si Irán intenta revivir las conversaciones, Estados Unidos tiene una oportunidad irresistible para desmantelar su programa nuclear. Tácticamente, los inversionistas deberían favorecer los bonos del Tesoro sobre el S&P, los sectores defensivos sobre los cíclicos, las acciones de energía sobre los cíclicos y las acciones estadounidenses sobre las europeas a corto plazo.
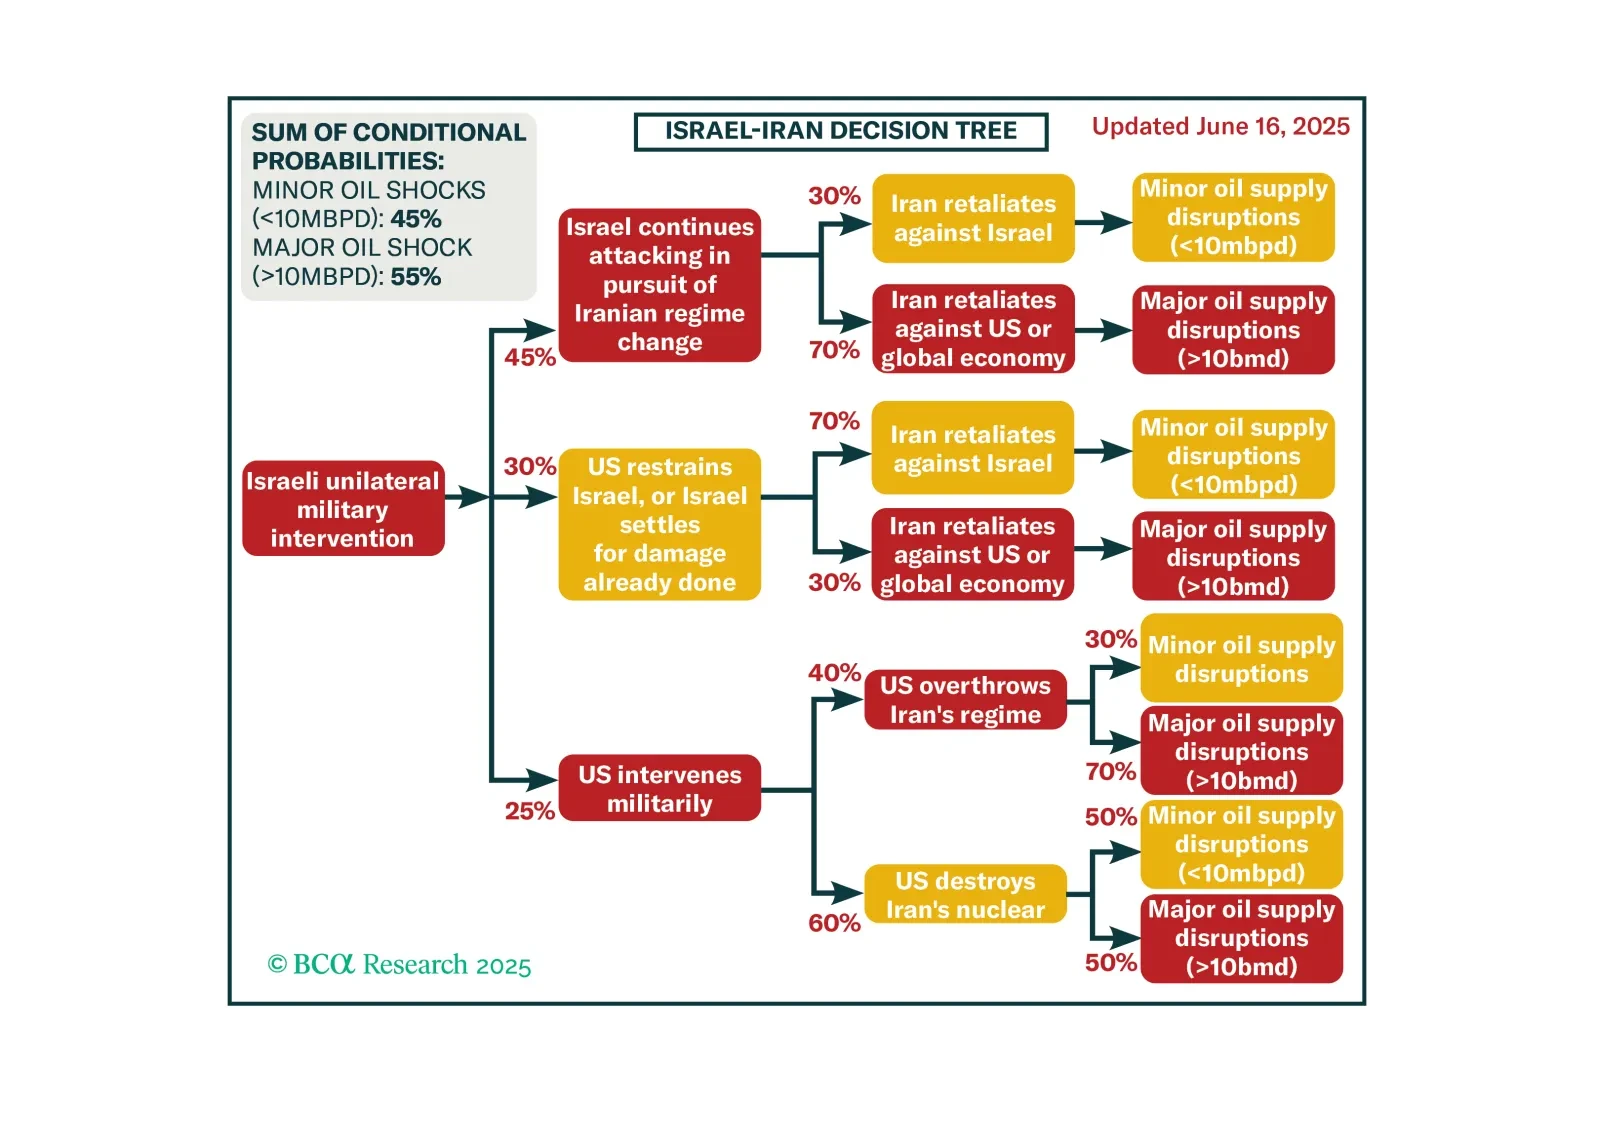
Los ataques de Israel a Irán continuarán hasta que Irán se vea obligado a atacar el suministro regional de petróleo para que Estados Unidos frene a Israel. Eso podría no funcionar. Los inversores deben prepararse para un impacto económico más amplio del conflicto.

The US economy has held up better so far this year than we had expected. For the time being, investors should remain modestly underweight equities. A more aggressive underweight would be justified only once the “whites of the recession’s eyes” are visible.
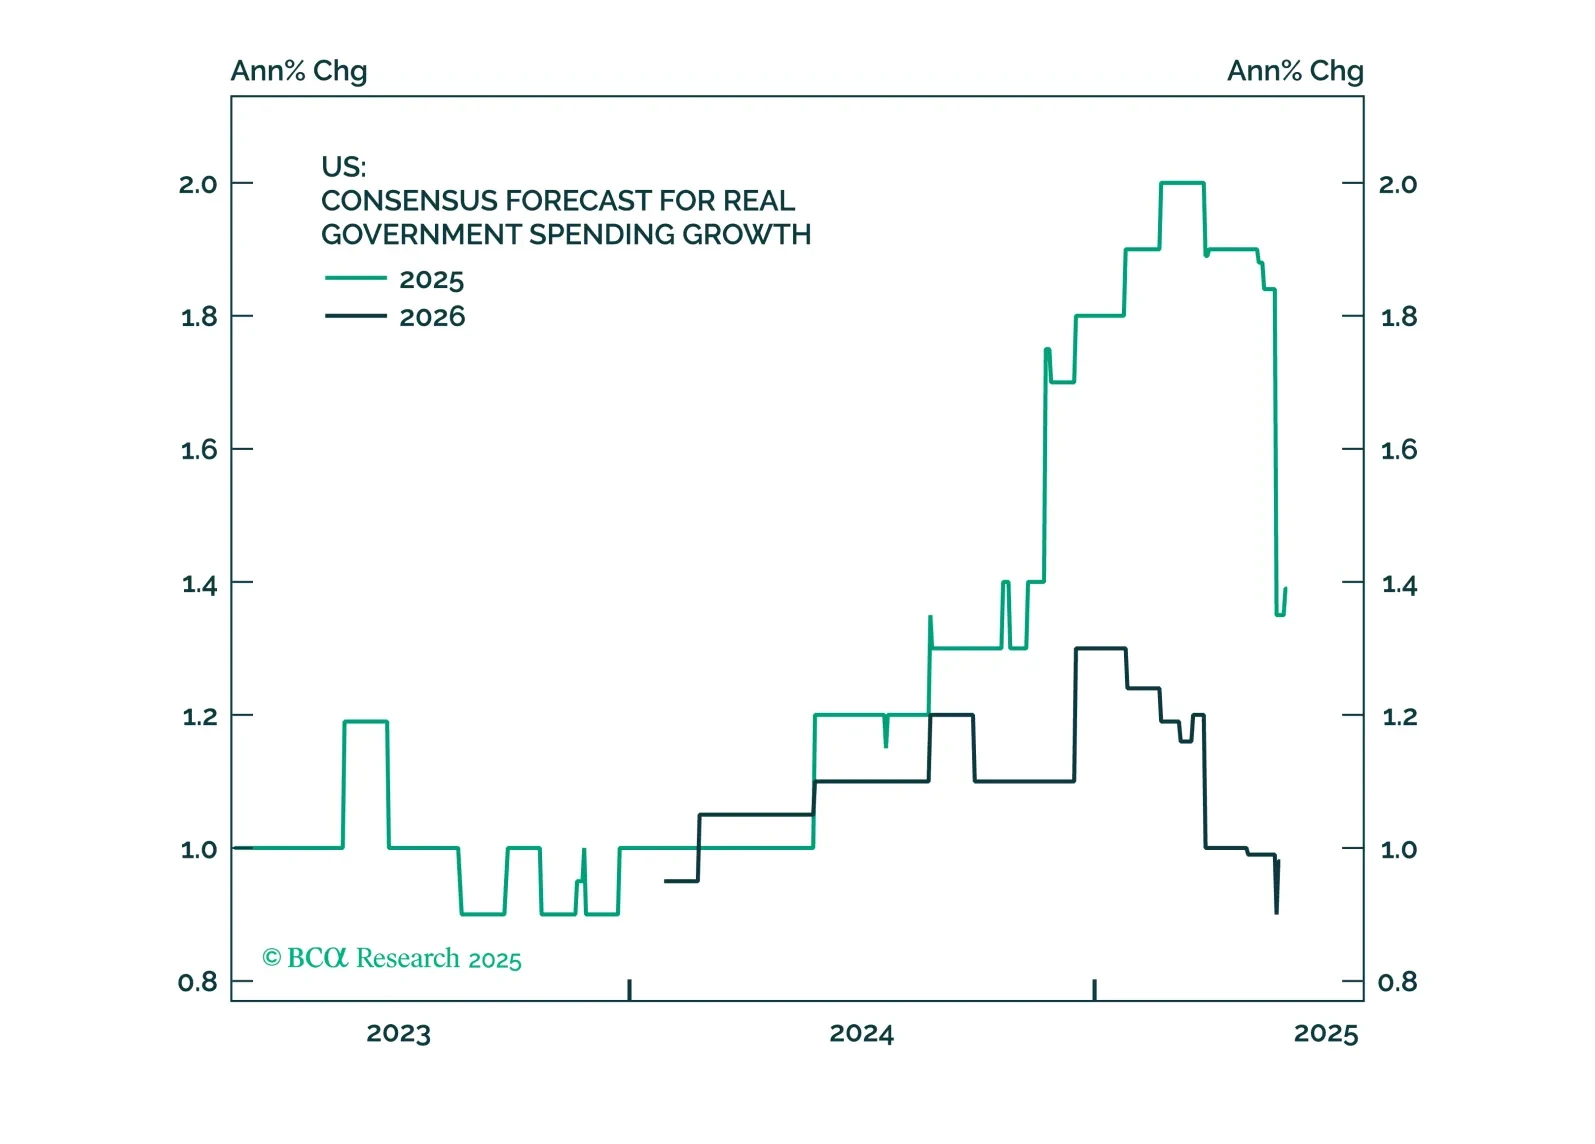
This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.

Después de considerar algunos de los argumentos alcistas más comunes, mantenemos nuestra visión de recesión y reiteramos nuestras recomendaciones de asignación defensiva de activos.
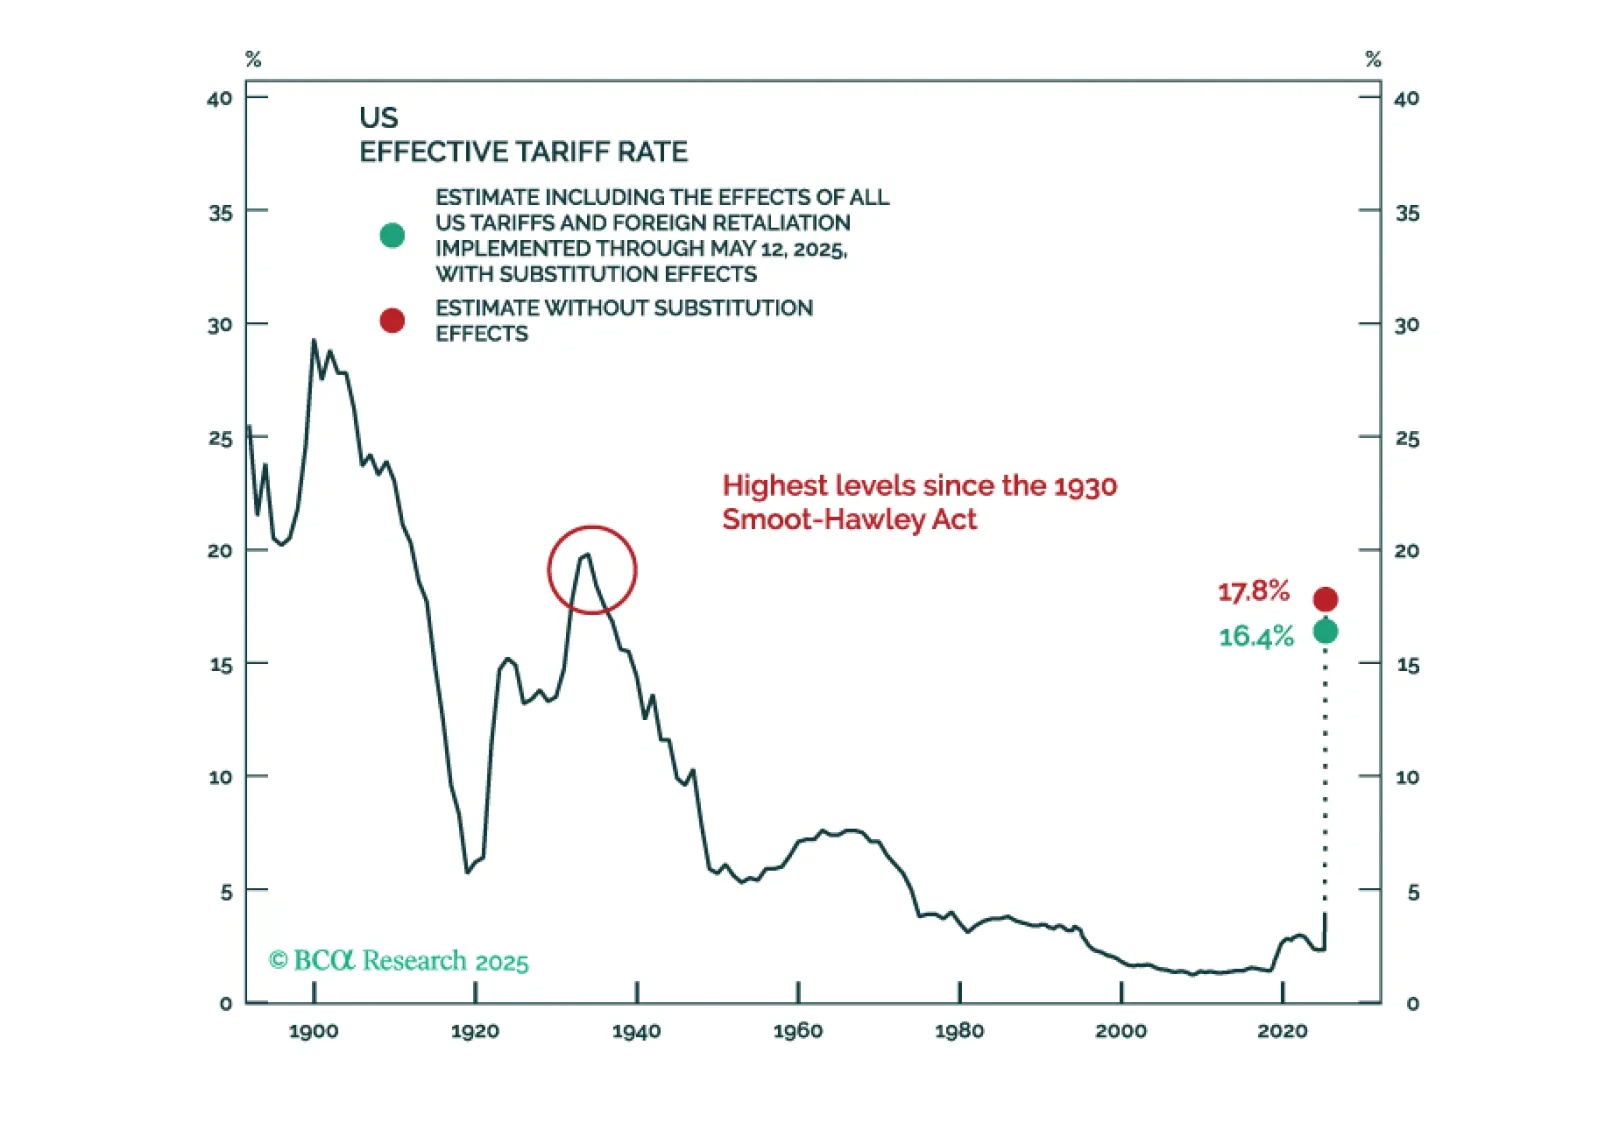
In Section I, Doug warns that US trade policy may produce a considerably worse outcome than investors currently expect. The administration’s apparent 10% tariff baseline is likely to be negative for the US economy and particularly the small business sector. Investors should remain defensively positioned for now, although judicial constraints on the administration’s ability to wage a trade war, if confirmed, would sharply reduce our estimated recession probability. In Section II, Jonathan discusses the arguments in favor and against the view that US inflation will be structurally elevated over the longer term. Our base case view remains that US inflation will not be significantly above 2%, but this view may change if US tariffs are put in place permanently and the US avoids a recession.
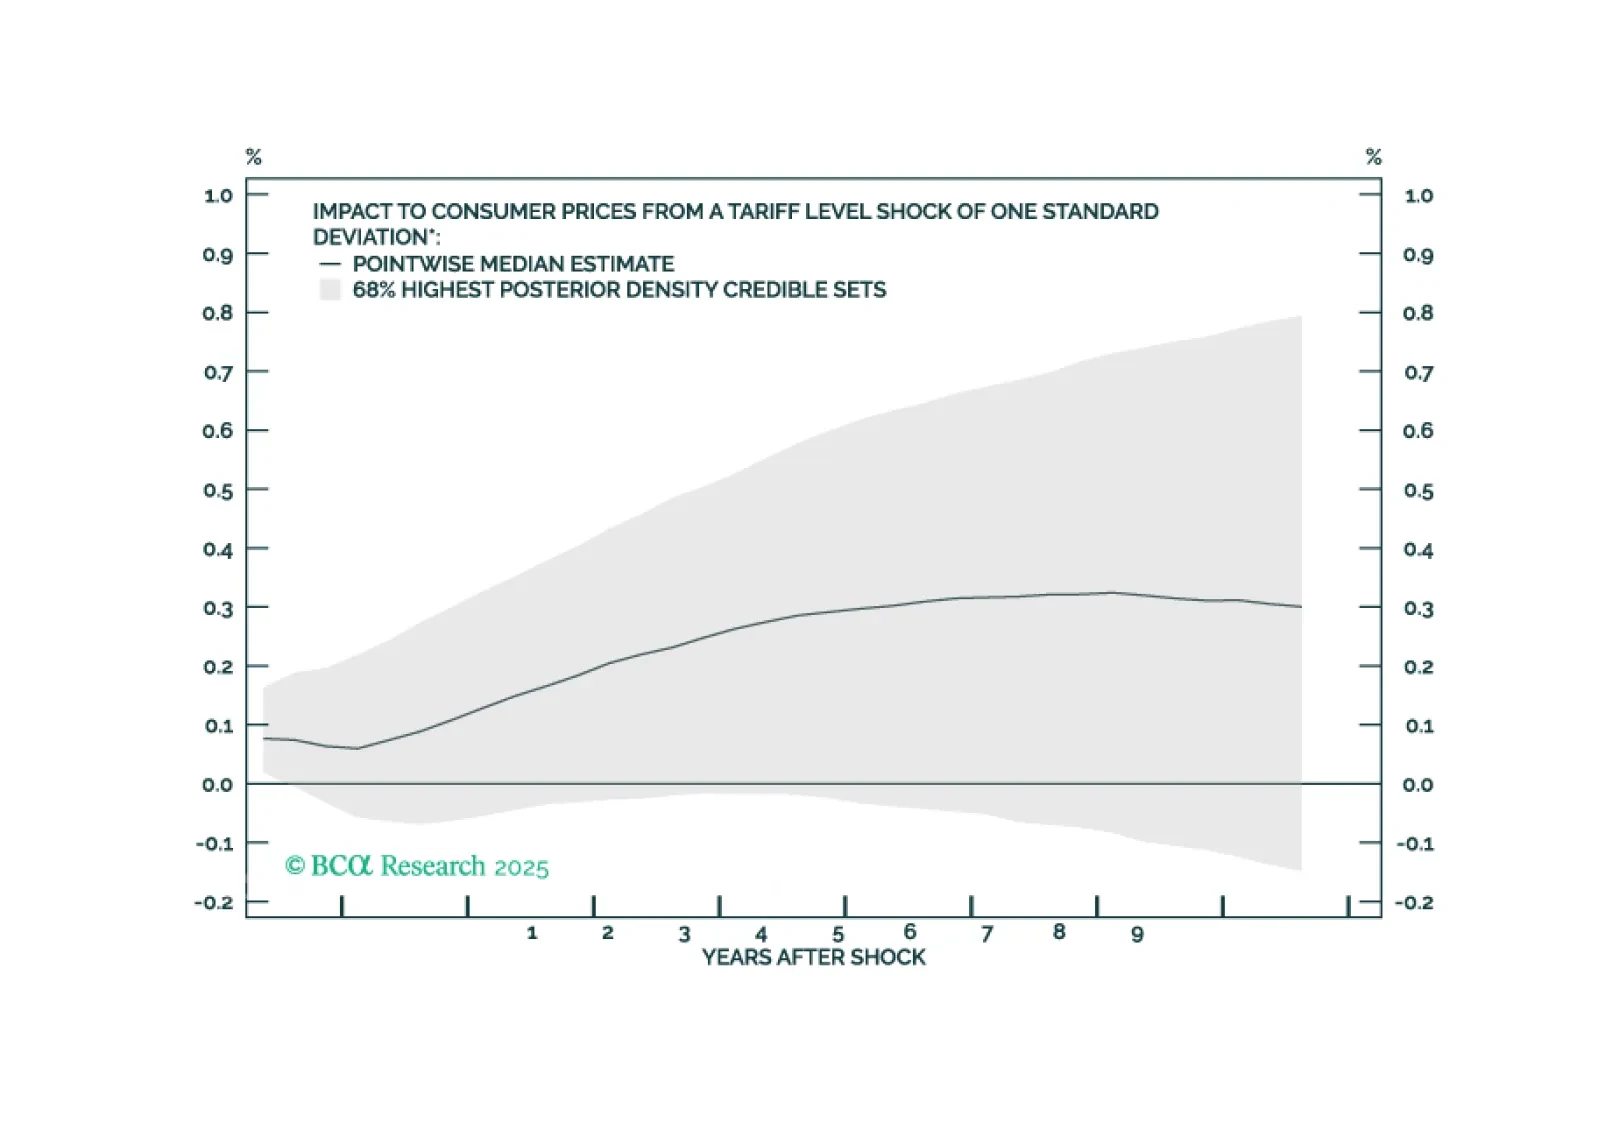
In Section II, Jonathan discusses the arguments in favor and against the view that US inflation will be structurally elevated over the longer term. Our base case view remains that US inflation will not be significantly above 2%, but this view may change if US tariffs are put in place permanently and the US avoids a recession.
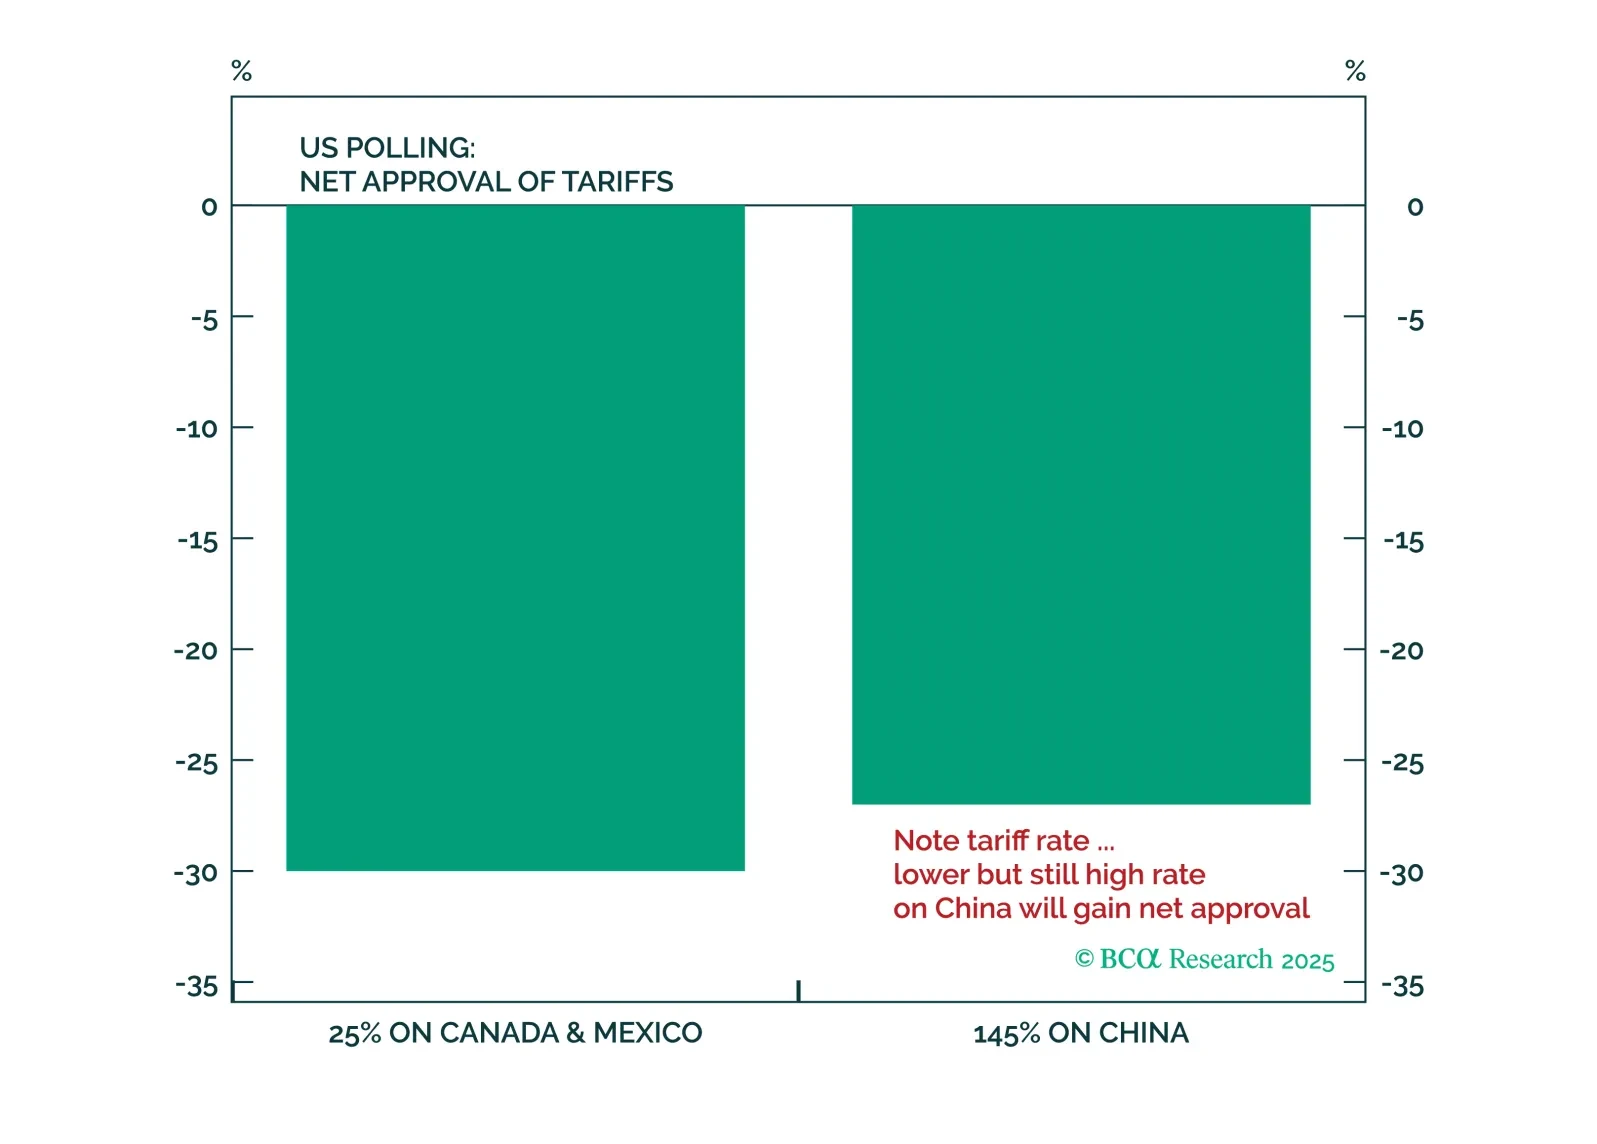
President Trump faces new restrictions on his trade powers coming from the US judicial branch, but they will not prevent him from continuing to restrict trade and investment with China. Rather, they will establish some curbs against entirely arbitrary executive tariffs, especially when wielded against US allies and partners.