Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Emerging Markets

Informe especial

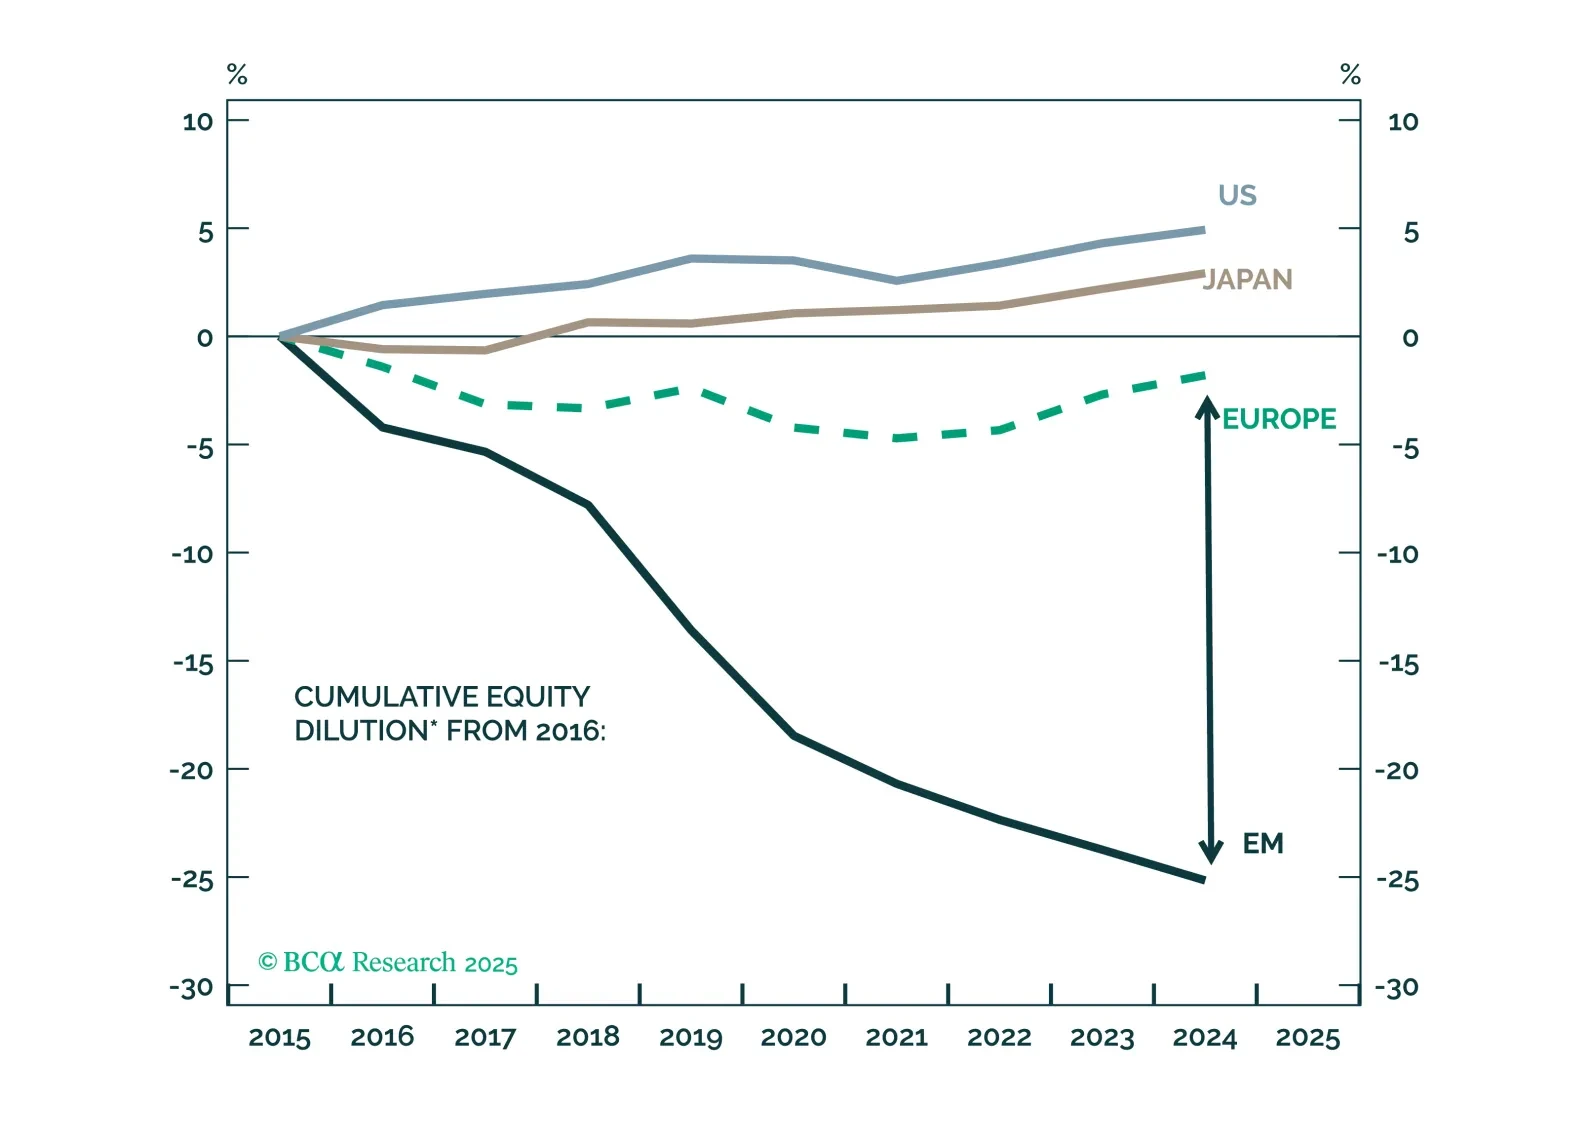
La dilución es una de las dos razones principales por las que el BPA de los mercados emergentes (EM EPS) ha sido mucho más débil que el PIB de los mercados emergentes (EM GDP) y las ganancias no diluidas de los mercados emergentes. Calculamos la dilución "pura", ajustada por la inclusión y exclusión de empresas en el índice bursátil, para varias bolsas alrededor del mundo. Según nuestro conocimiento, esta es la primera vez que se realiza este análisis.

Reevaluando las ganancias de EM Reevaluando las ganancias de EM Los estrategas de EM de BCA permanecen pesimistas sobre las acciones de EM a pesar de una visión bajista del dólar estadounidense, citando obstáculos en las ganancias y soporte de valoración…

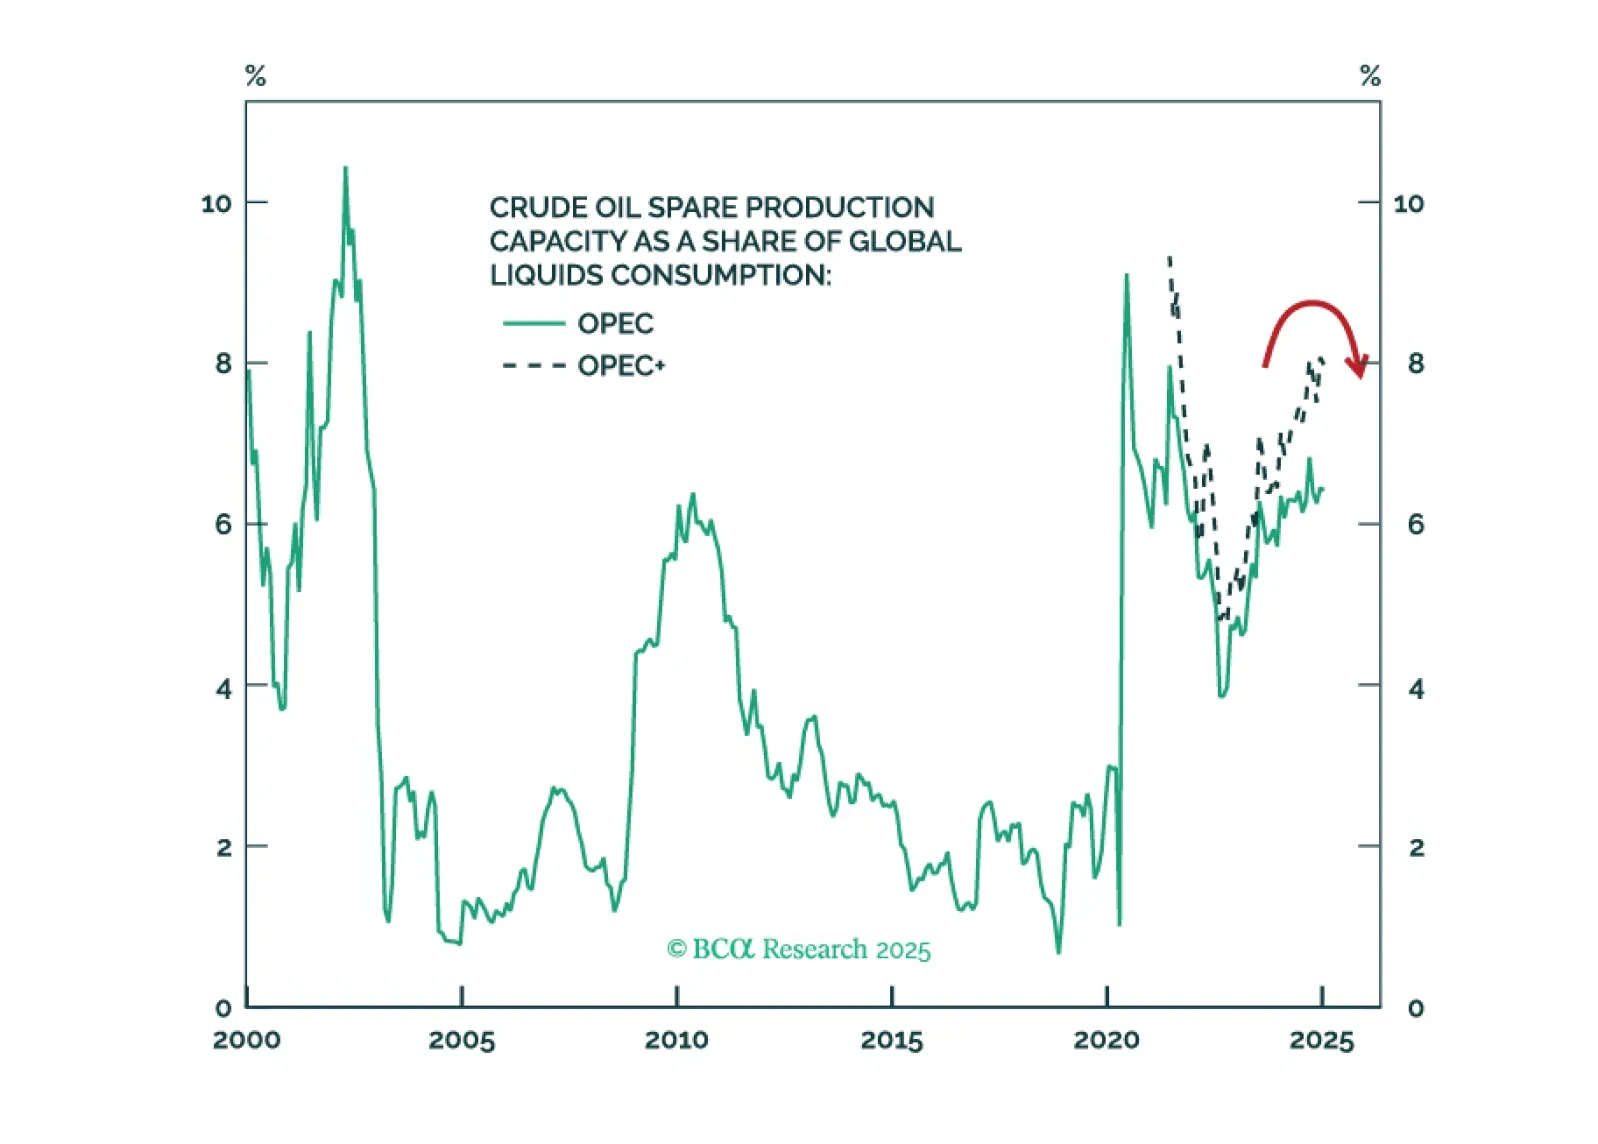
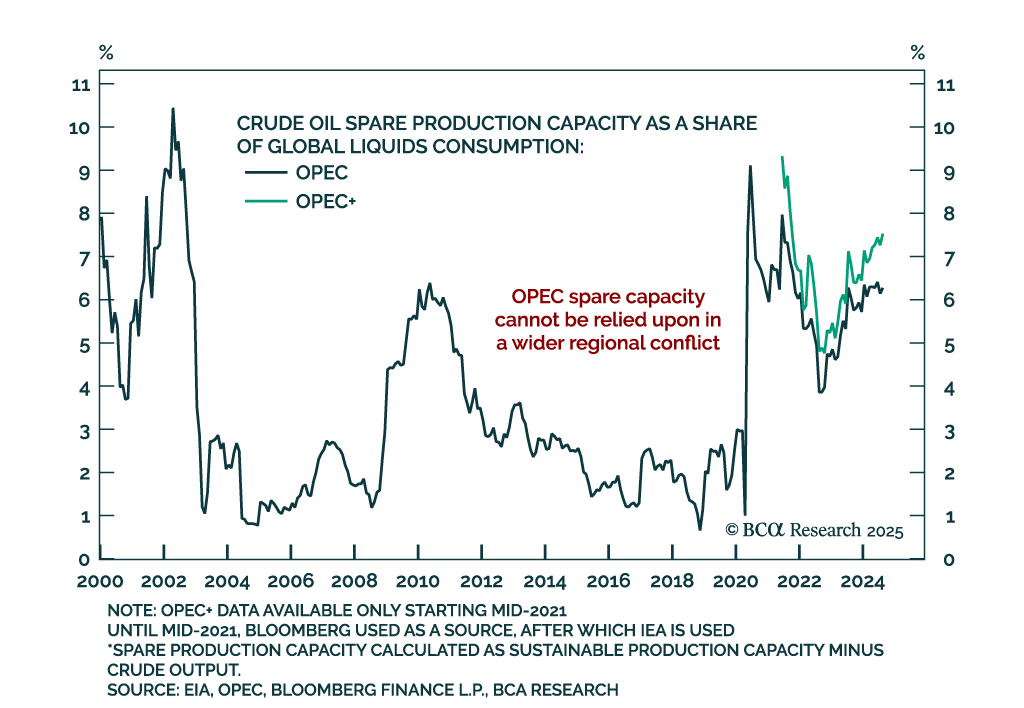
Investors should hold gold, build up some cash, tactically overweight US equities relative to global, and prepare for at least minor oil supply shocks – possibly major shocks – as the Israel-Iran war escalates.
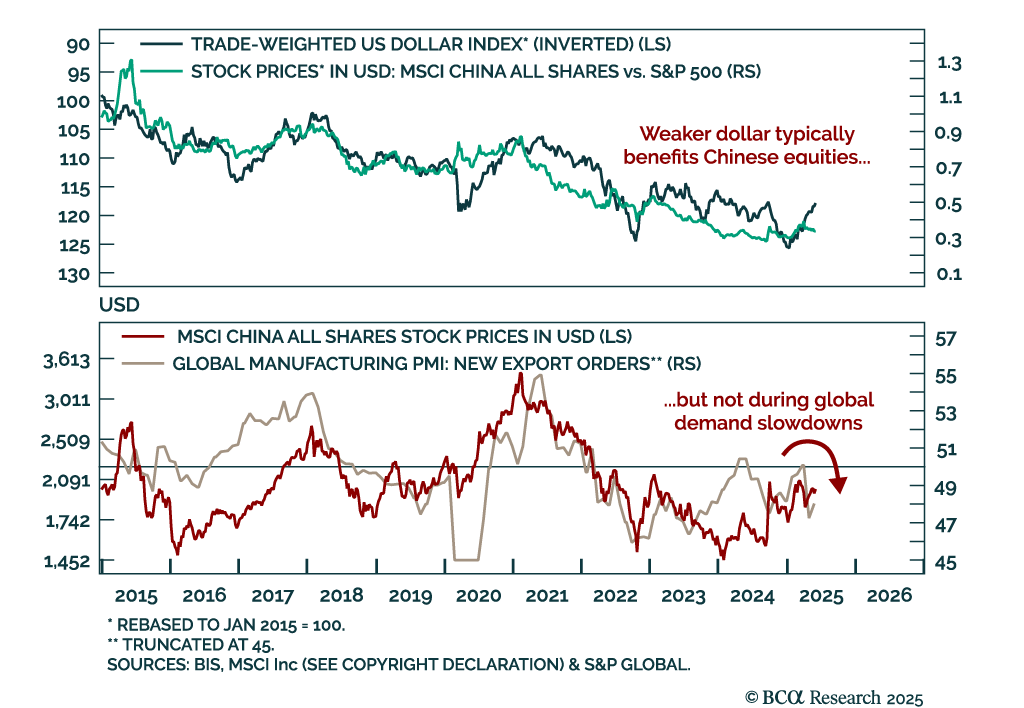
BCA’s China Investment strategists see limited upside for Chinese equities and favor bonds, as trade tensions ease but domestic headwinds persist. This week’s US-China trade talks in London lowered the risk of near-term escalation or new retaliatory tariffs,…
The Israel-Iran conflict is escalating, raising the odds of a major oil supply shock and reinforcing the case for cash, US equity overweight, and tactical energy exposure. Our Chart Of The Week comes from Matt Gertken, Chief Geopolitical and US Political…
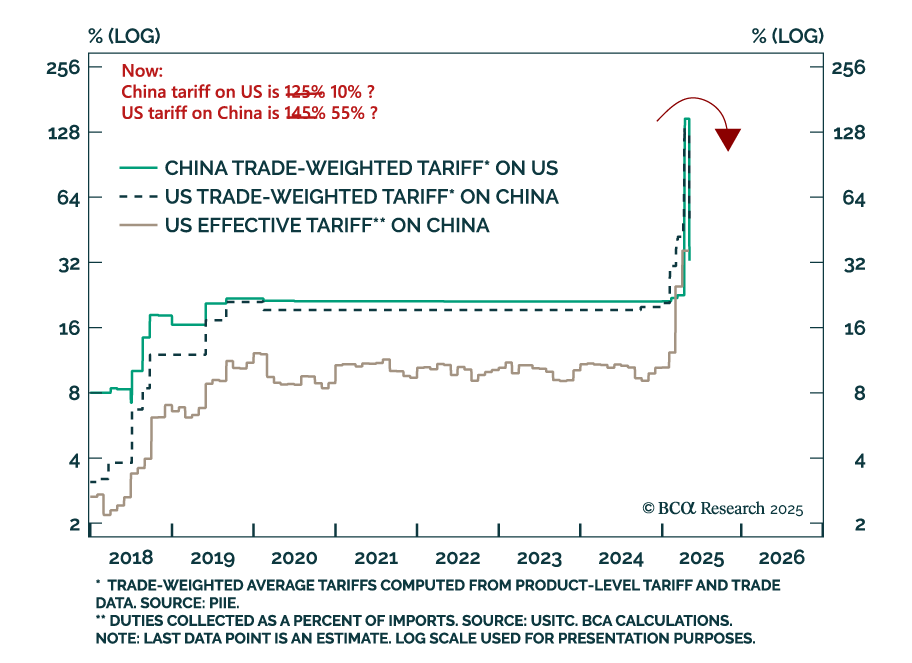
The US-China tariff deal confirms one thing: markets are still priced for perfection, with little upside even if a recession is dodged. The London negotiations yielded a partial agreement: The US will reduce tariffs, and China will remove export restrictions…
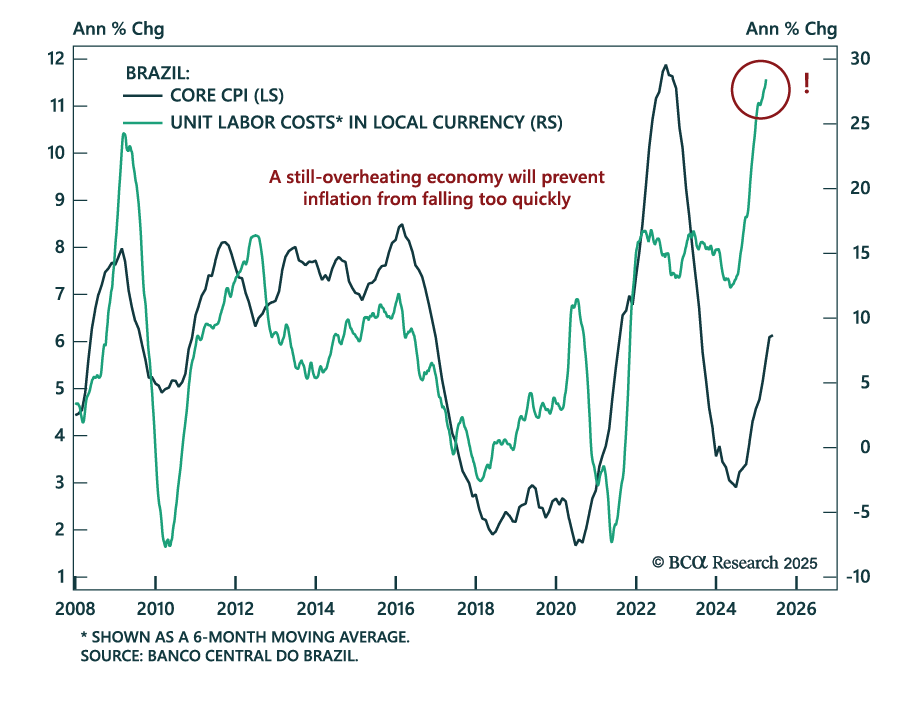
The May Brazilian CPI suggests that price pressures may have reached a peak, but do not expect immediate monetary easing to support fixed income markets. Headline CPI slowed to 5.3% y/y from 5.5% April, but core CPI remained flat at 6.1%. Despite peaking…
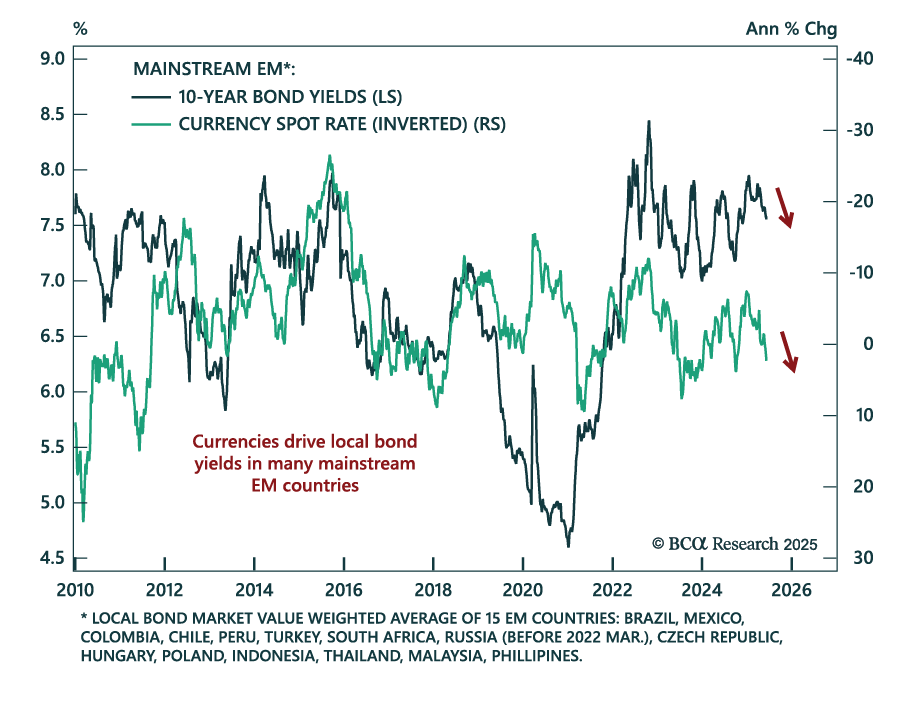
BCA’s EM strategists argue that a global macro shift is underway: A weaker US dollar will drive a retrenchment in US domestic demand and imports. Unlike previous cycles, dollar depreciation will be deflationary for the rest of the world rather than…
Informe especial

Unlike in past episodes, US dollar weakness will be deflationary, not reflationary, for the rest of the world. In this context, EM local currency bonds offer a superior risk-reward profile. Stay long domestic bonds in select EM countries.
Our Portfolio Allocation Summary for June 2025.