Elections
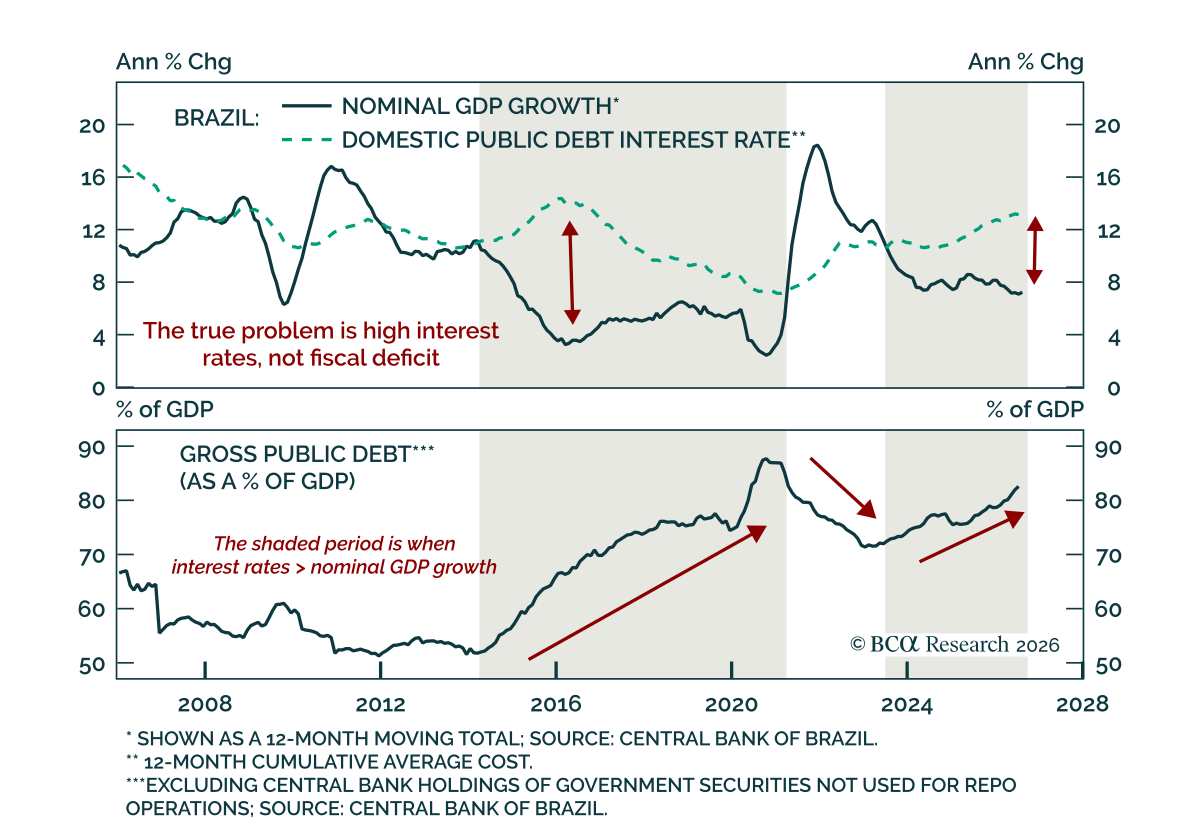
The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.
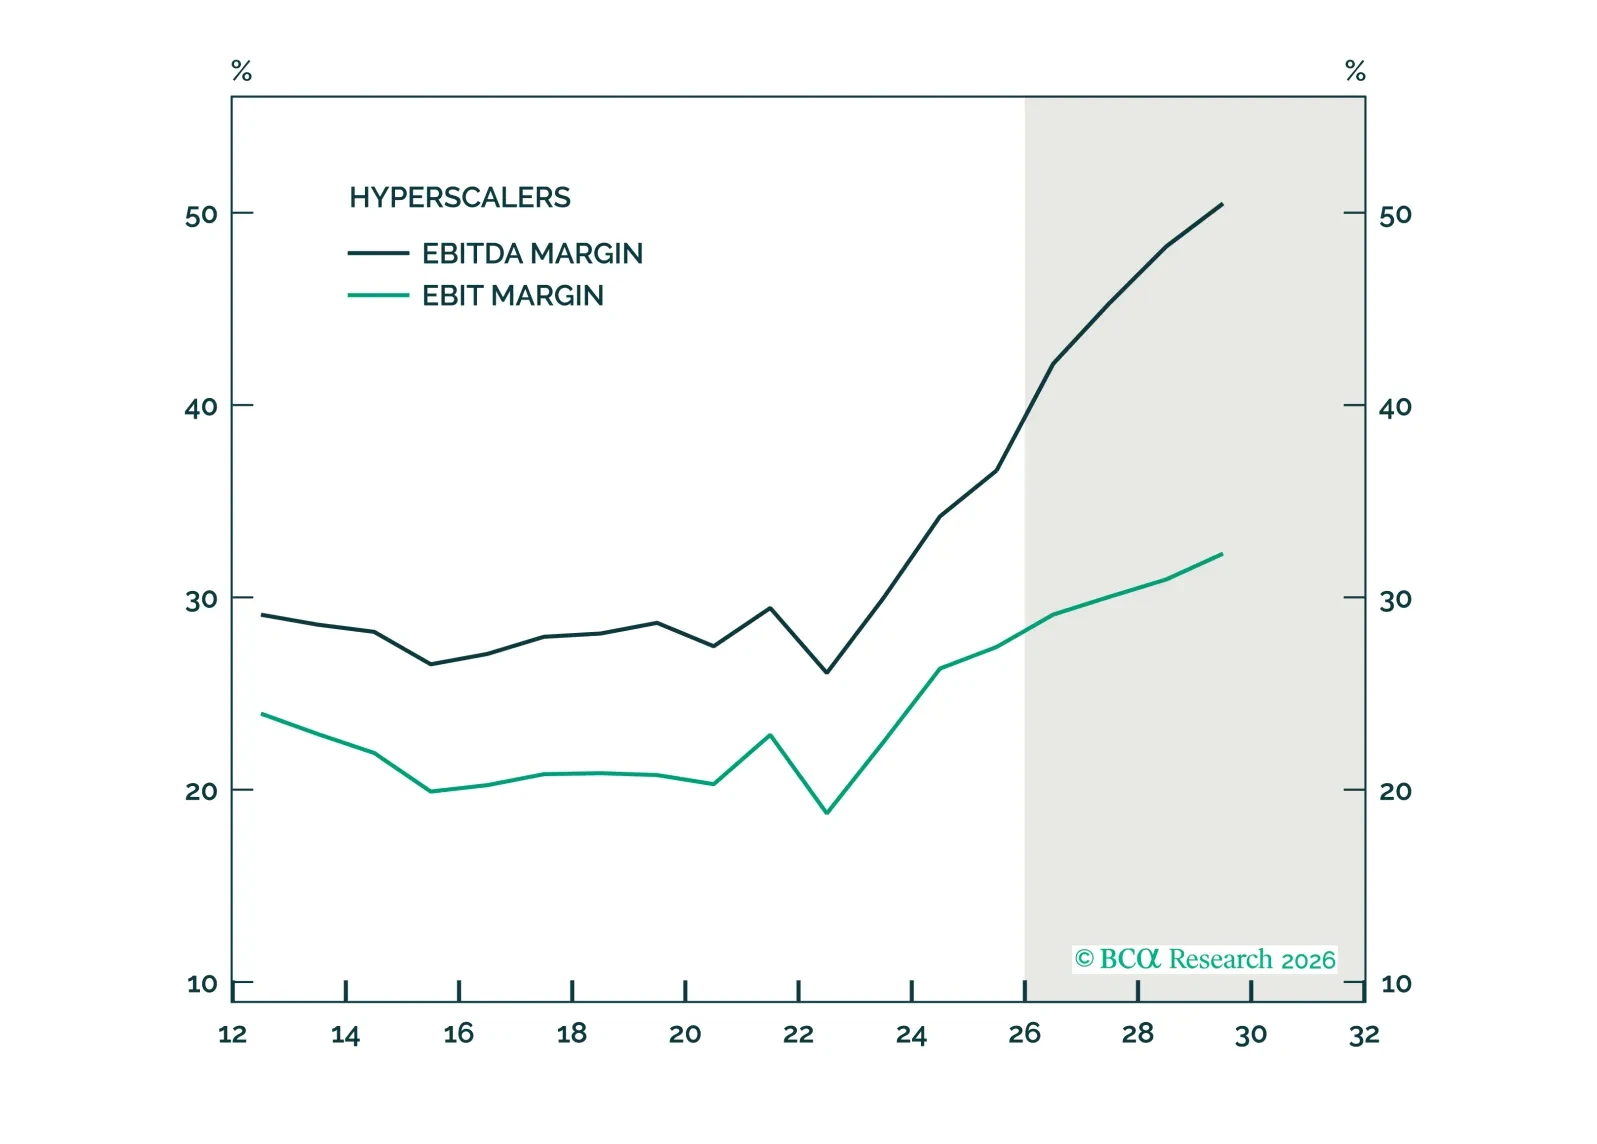
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
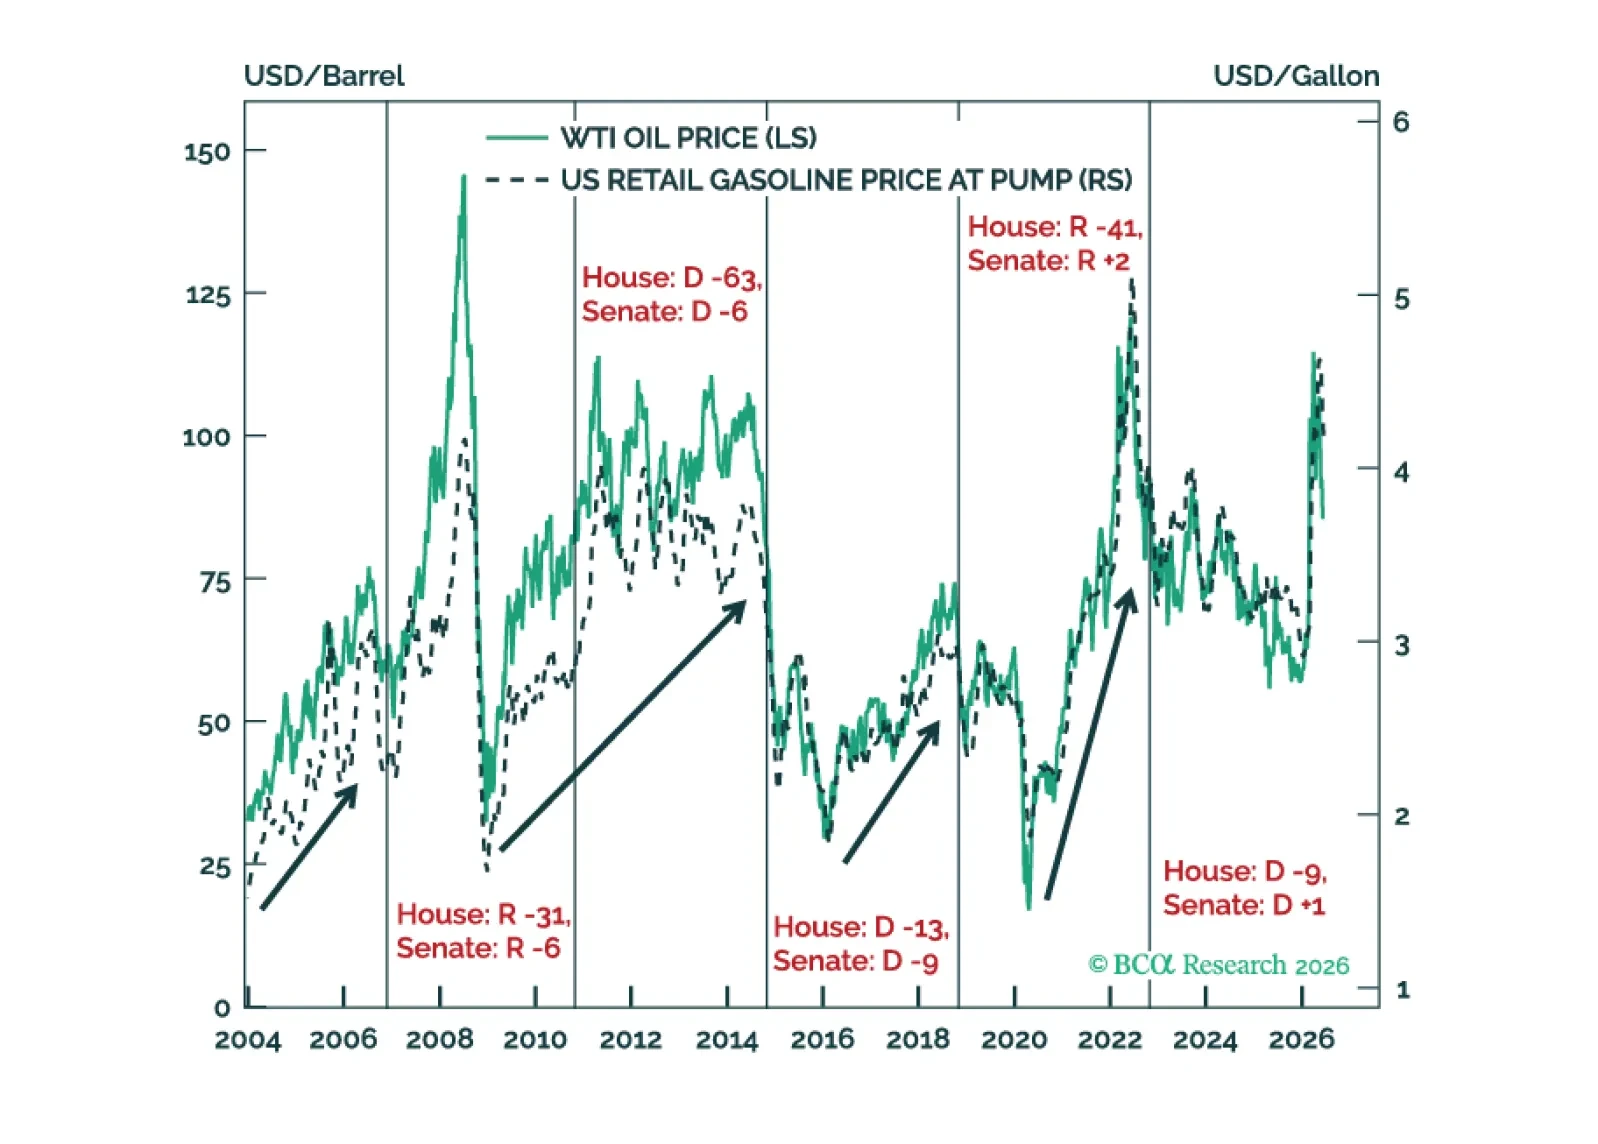
The US-Iran deal offers temporary relief from oil supply risk, but both Hormuz and trade tensions could revive in 2027.
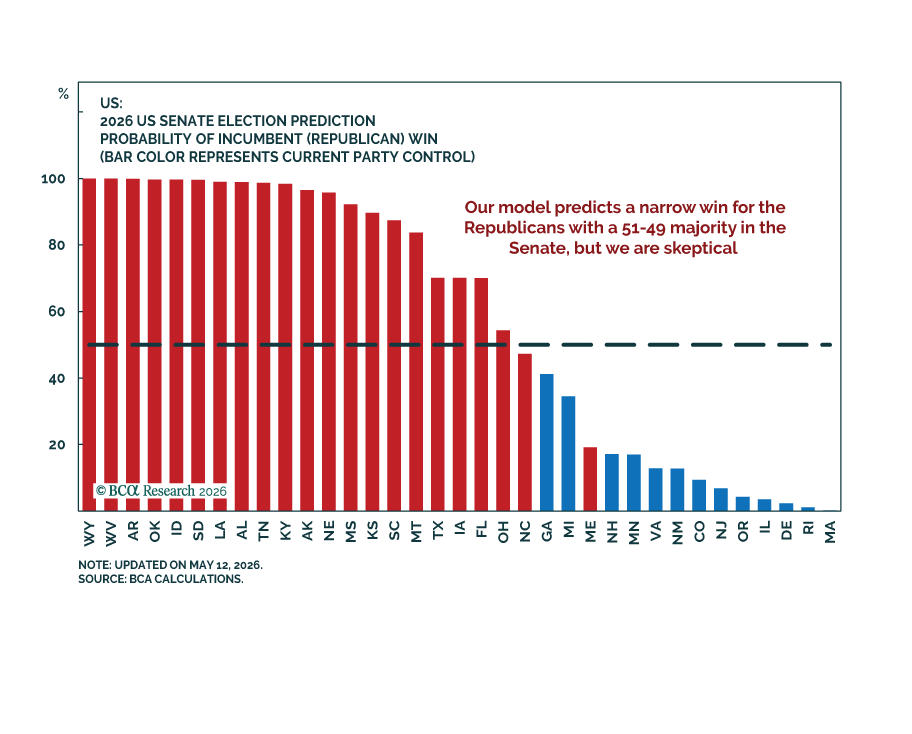
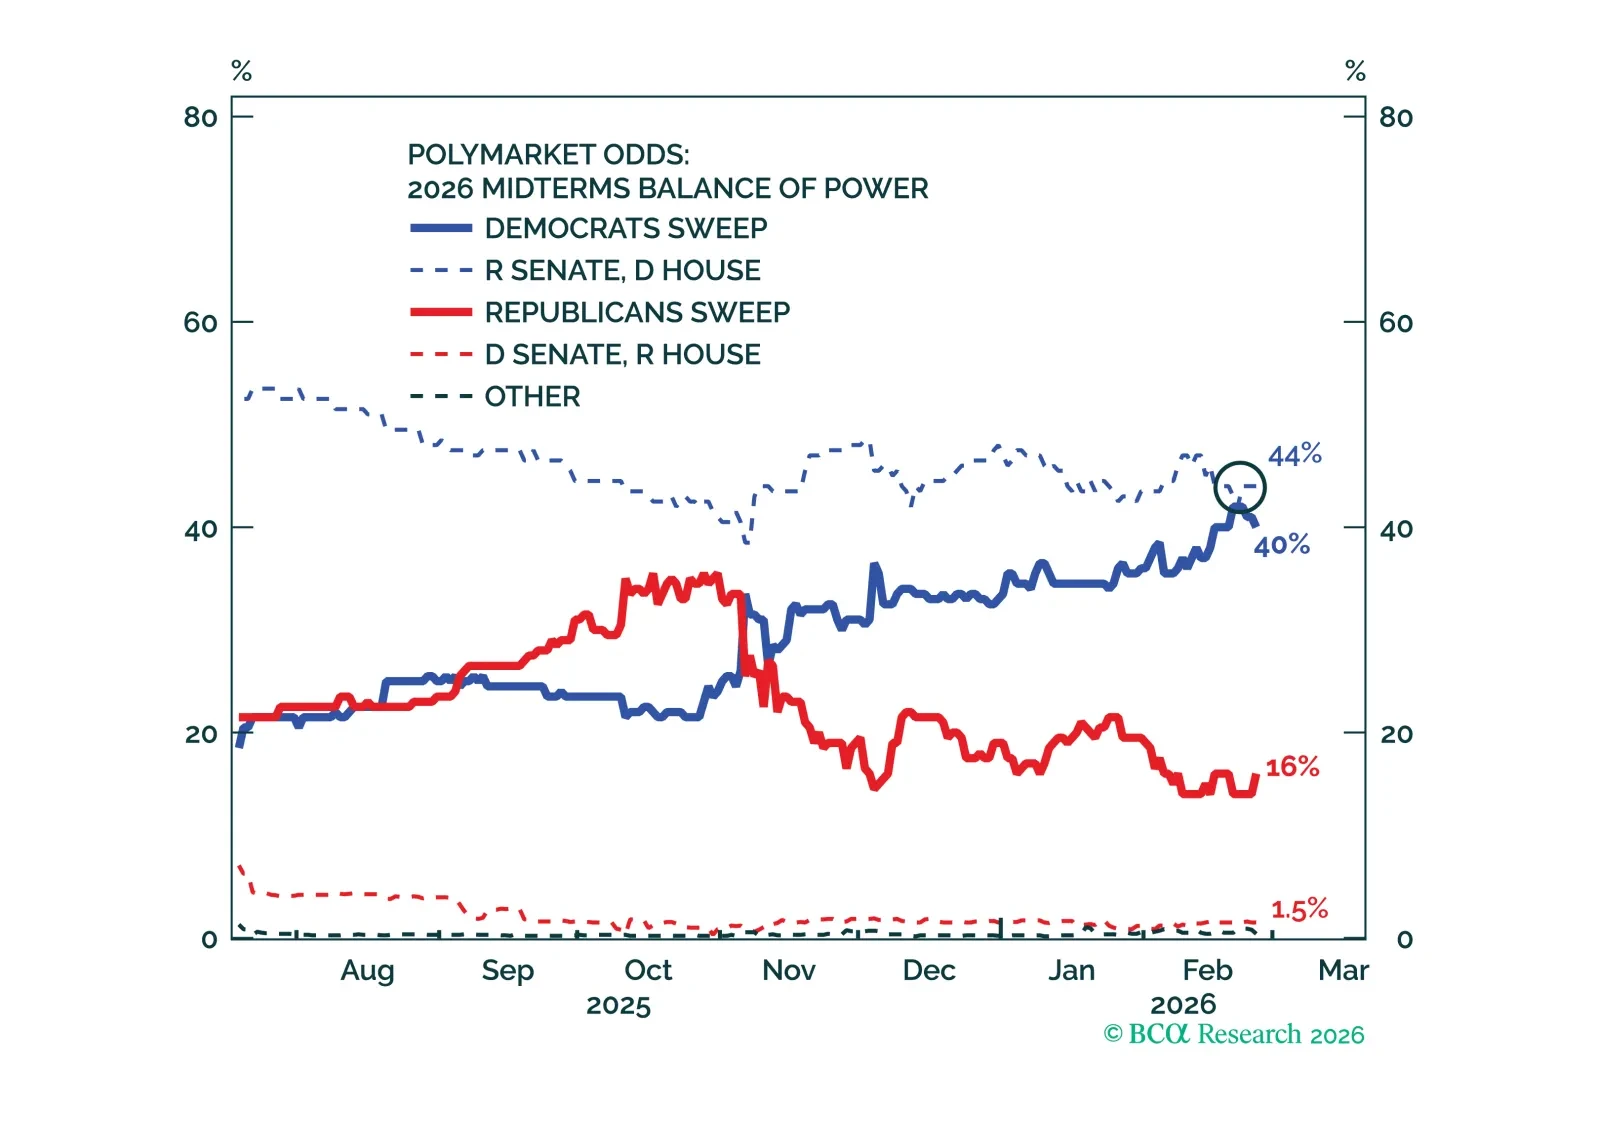
Democrats are likely to win big in this year's midterm elections. Our new quant model still slightly favors Republicans for the Senate, but we expect the oil shock to deliver surprise Democratic victories.
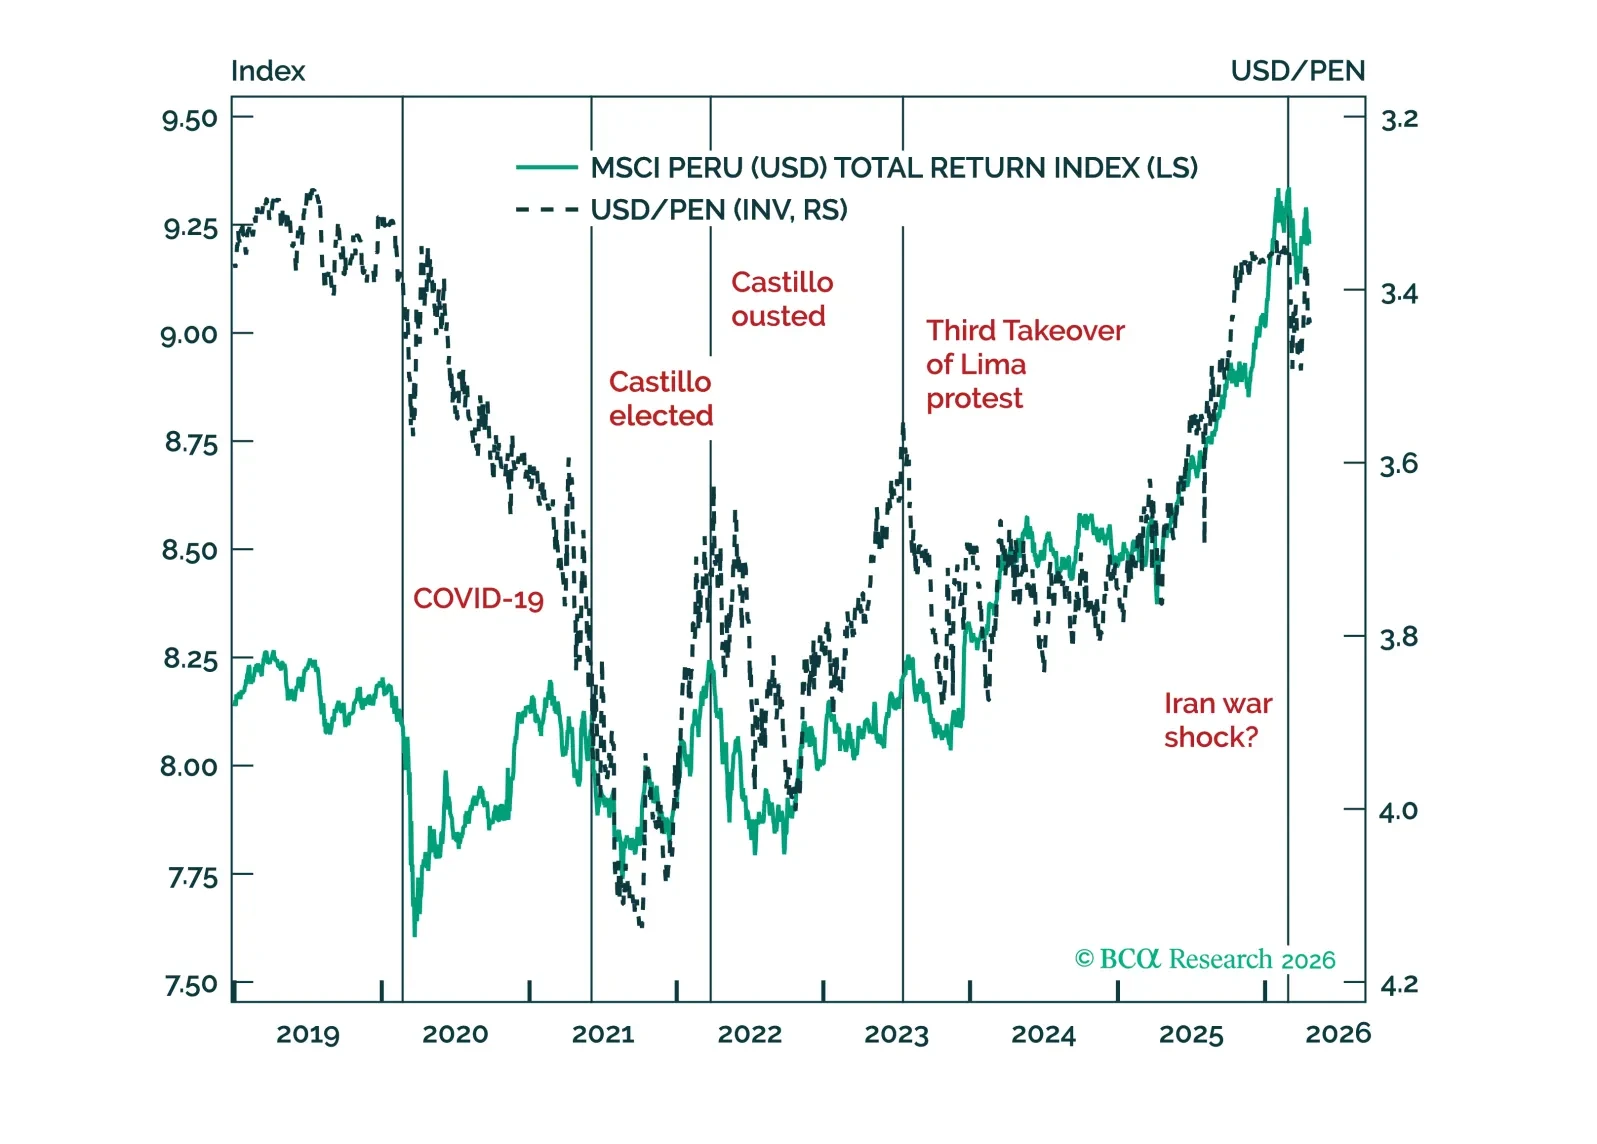
Peru is well established to elect a pro-market government in the June 7 run-off, with institutional constraints limiting left-tail policy risks. We will go long Peruvian assets when Hormuz volatility subsides.
The president did not announce significant new tax cuts or economic stimulus.
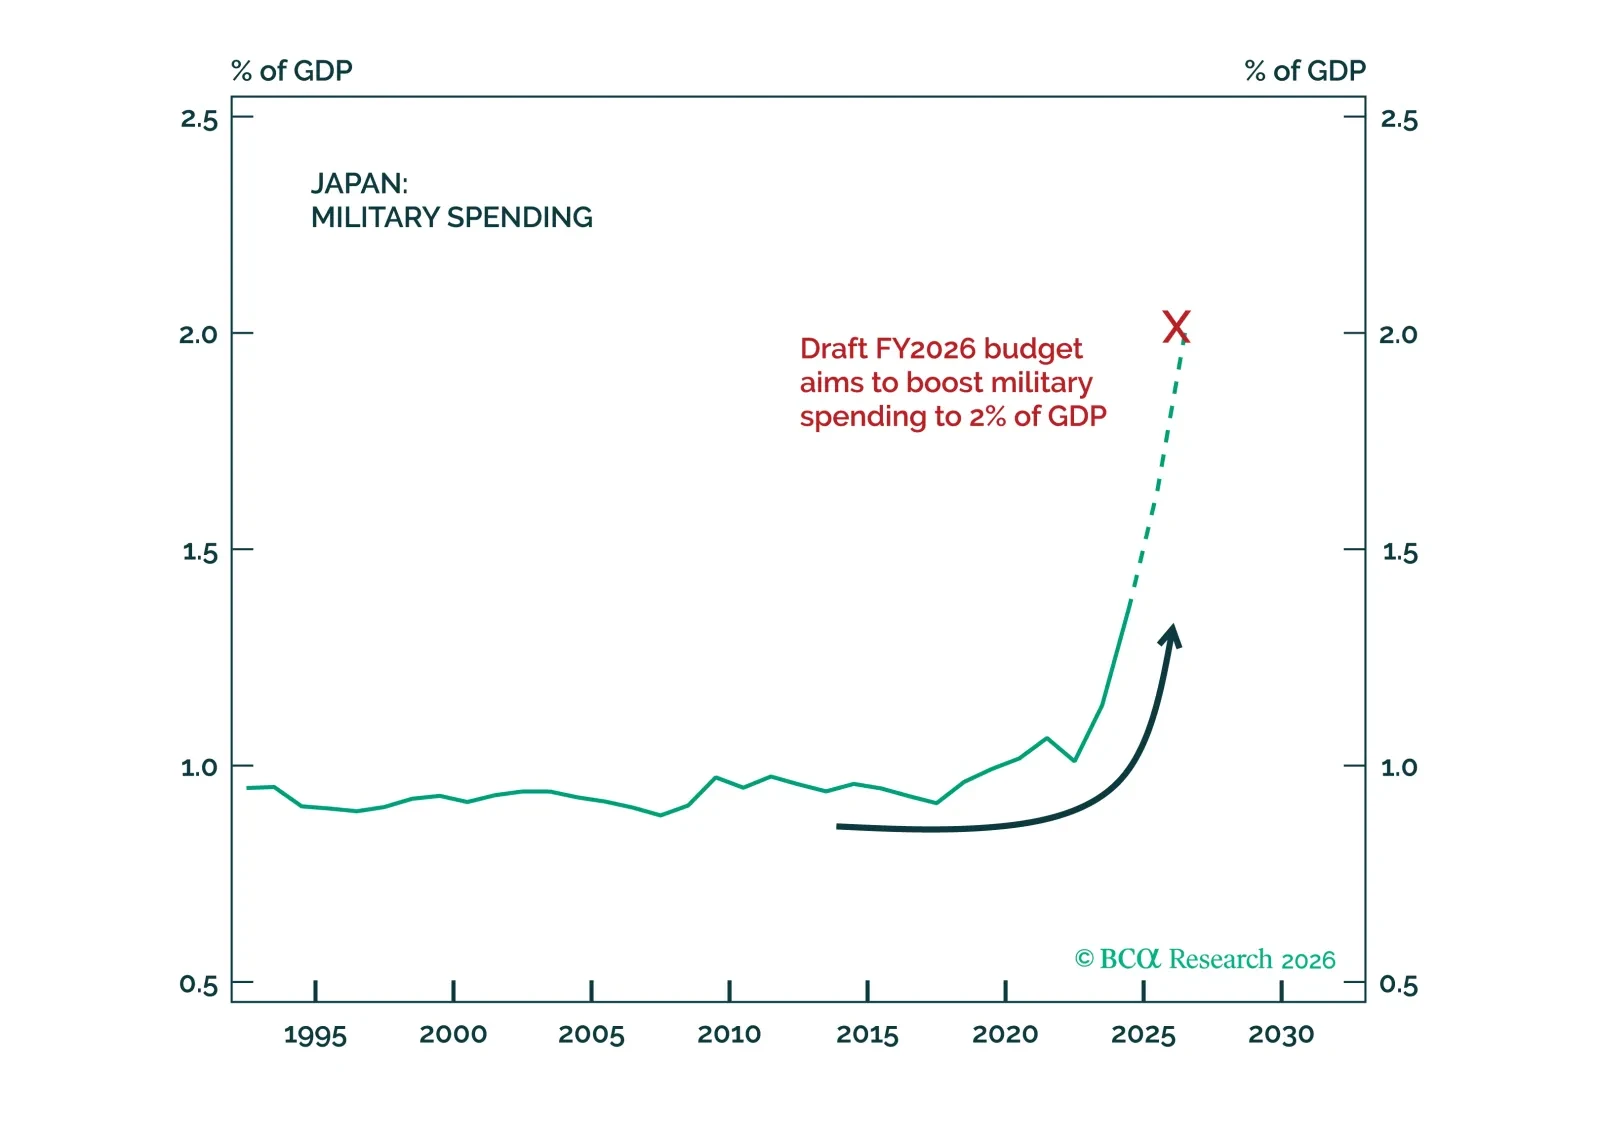
Ignore Japan's constitutional debate. Rearmament will accelerate anyway. Tech, defense stocks, and industrials will benefit. The threat to JGBs is real but will probably be contained.
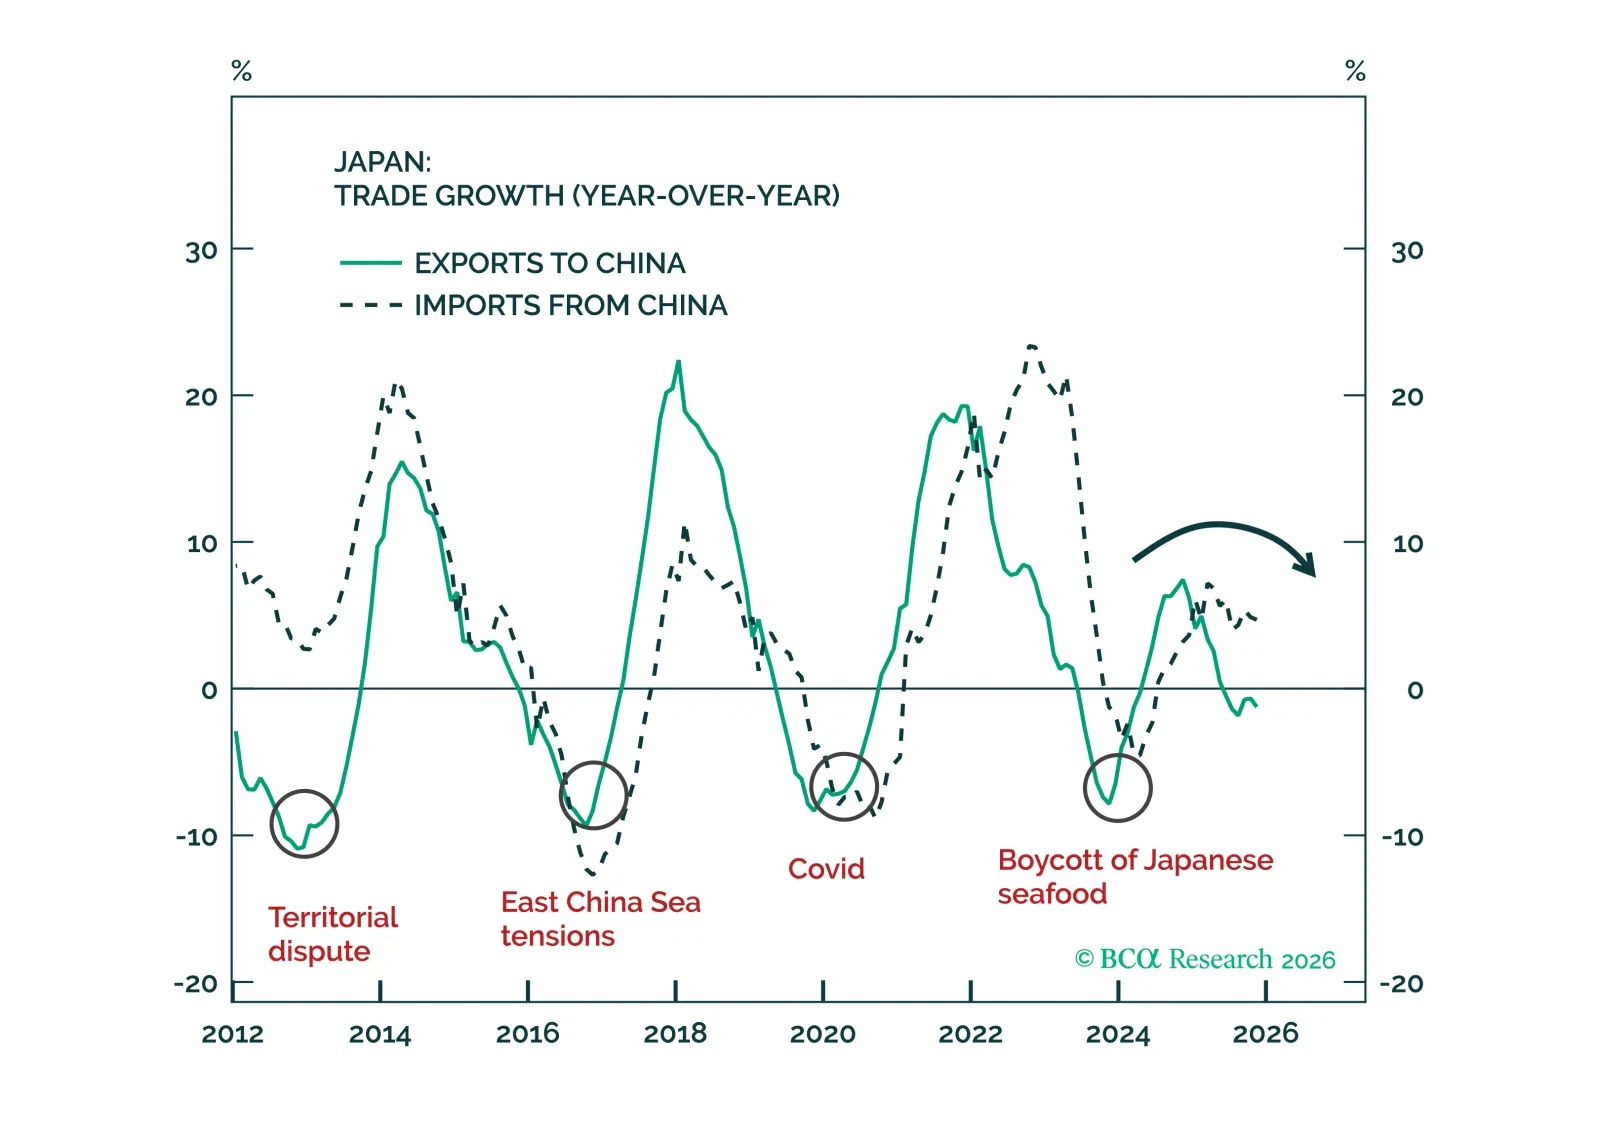
Japan's new government will continue, but politics and foreign policy have become more competitive.