 CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
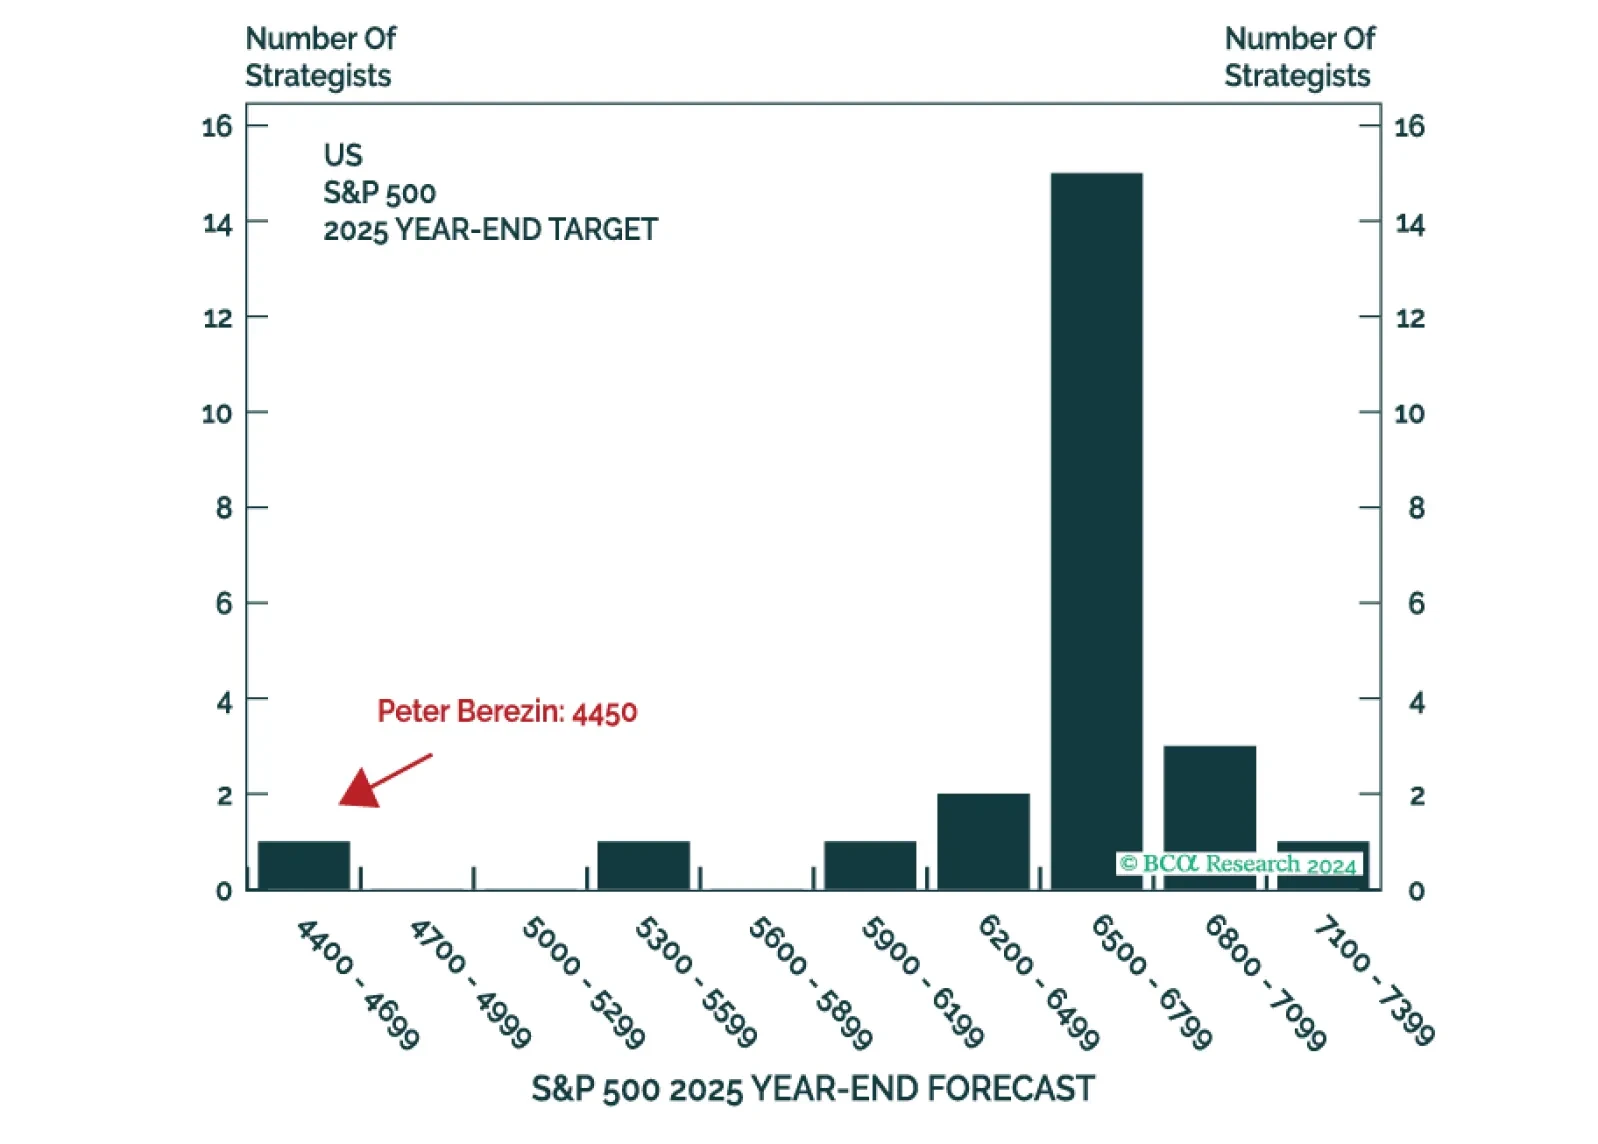
This is the time of the year when strategists are busy sending out their annual outlooks. Here on the Global Investment Strategy team, we decided to go one step further. Rather than pontificating about what could happen in 2025, we decided to harness the power of the multiverse to tell you what did happen (in at least one highly representative timeline). Next week, please join me for a Webcast on Tuesday, December 17 at 10:30 AM EST (3:30 PM GMT, 4:30 PM CET) to discuss the economy and financial markets. And with that, I will sign off for the year. I wish you and your loved ones a very happy and healthy 2025. We will be back in the first week of January with our MacroQuant Model Update.
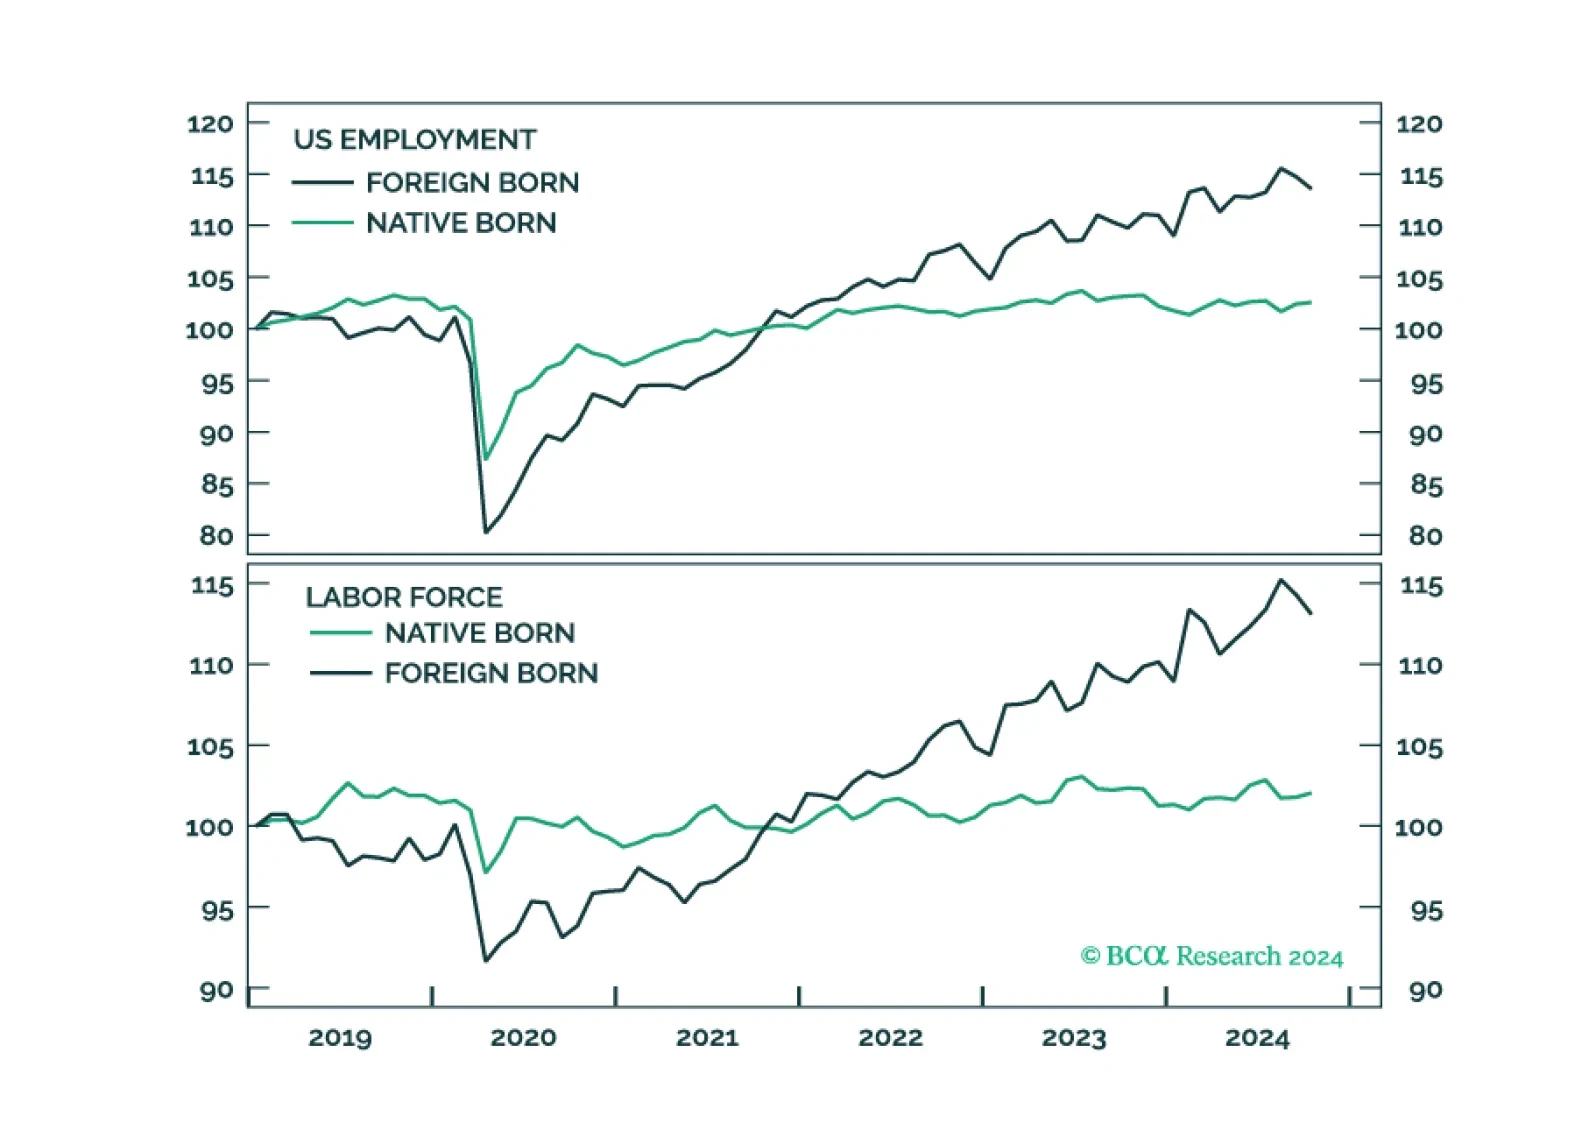
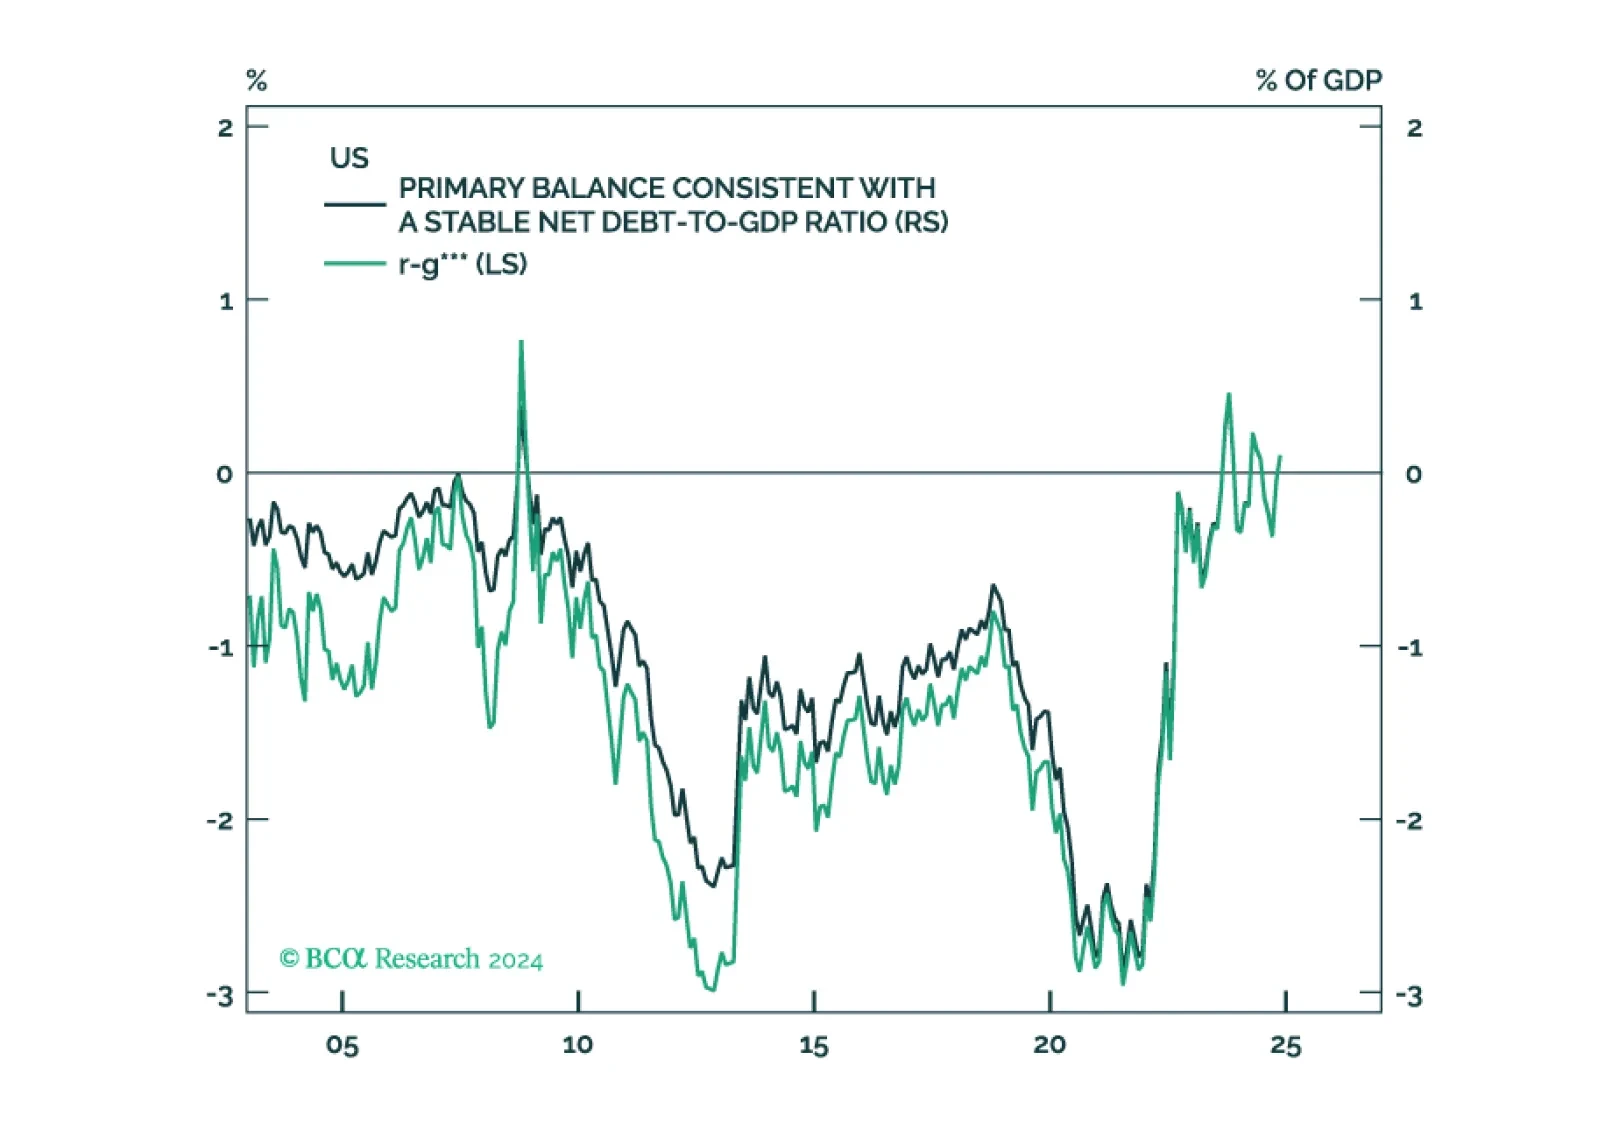
I have been generally sceptical of the reflationary aspects of the so-called Trump trade. If Trump's first term is any guide, lower tax rates will have little impact on business spending while higher tariffs are unlikely to trigger much reshoring of manufacturing activity. Meanwhile, rising debt-service costs could force the Trump administration to cut social spending under the guise of reducing government waste. One open question surrounds immigration. The market consensus seems to be that decreased immigration will lead to a tighter labour market, stoking inflationary pressures in the process.
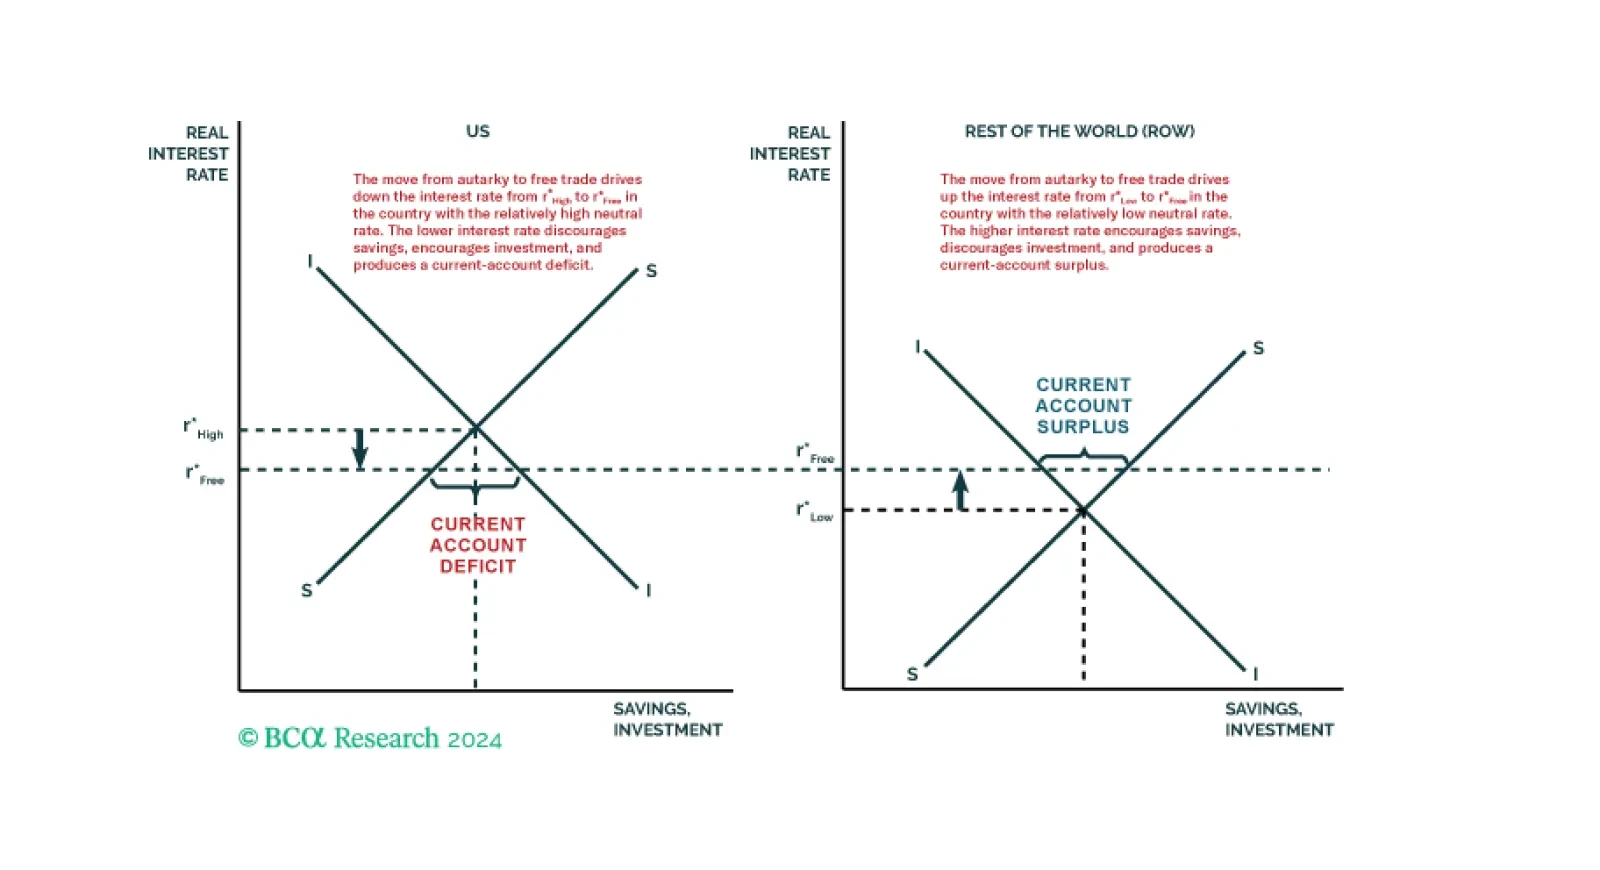
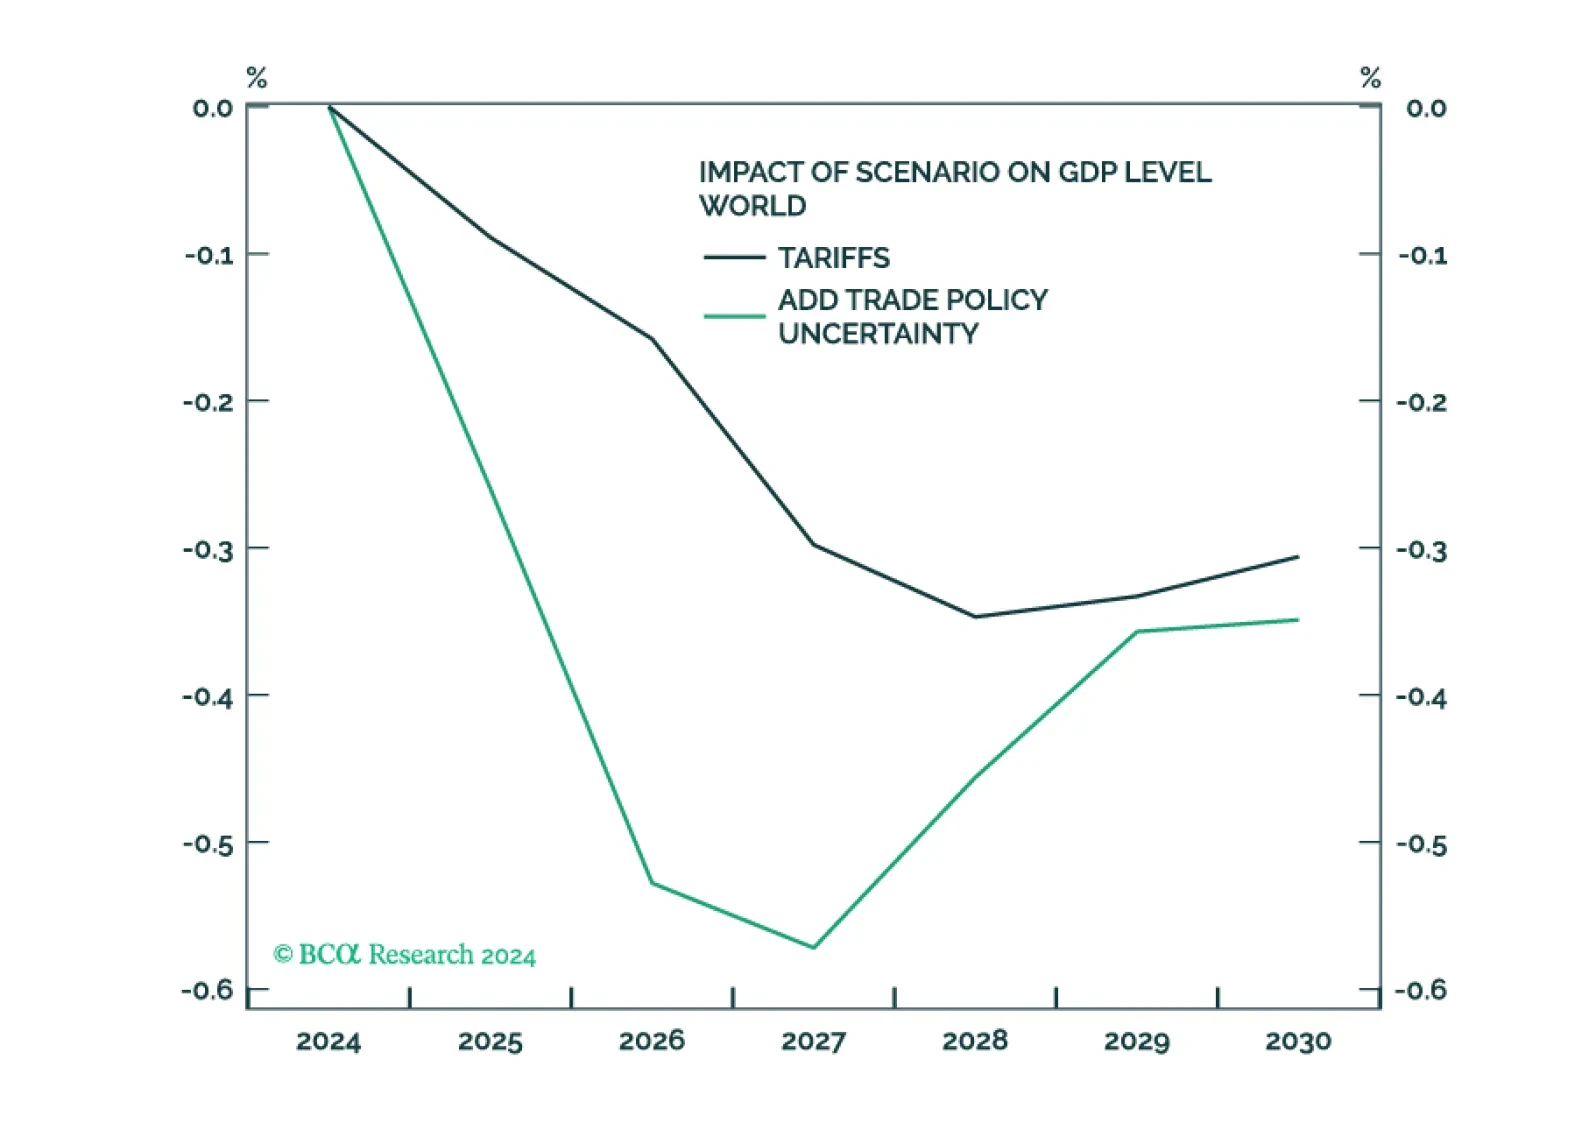
On October 15, speaking at the Economic Club of Chicago, Donald Trump called tariffs “the most beautiful word in the dictionary.” On Monday, he put those words into action by threatening to slap a 25% tariff on all imports from Canada and Mexico, and an additional 10% tariff on Chinese imports. Collectively, the three countries account for 45% of US imports.
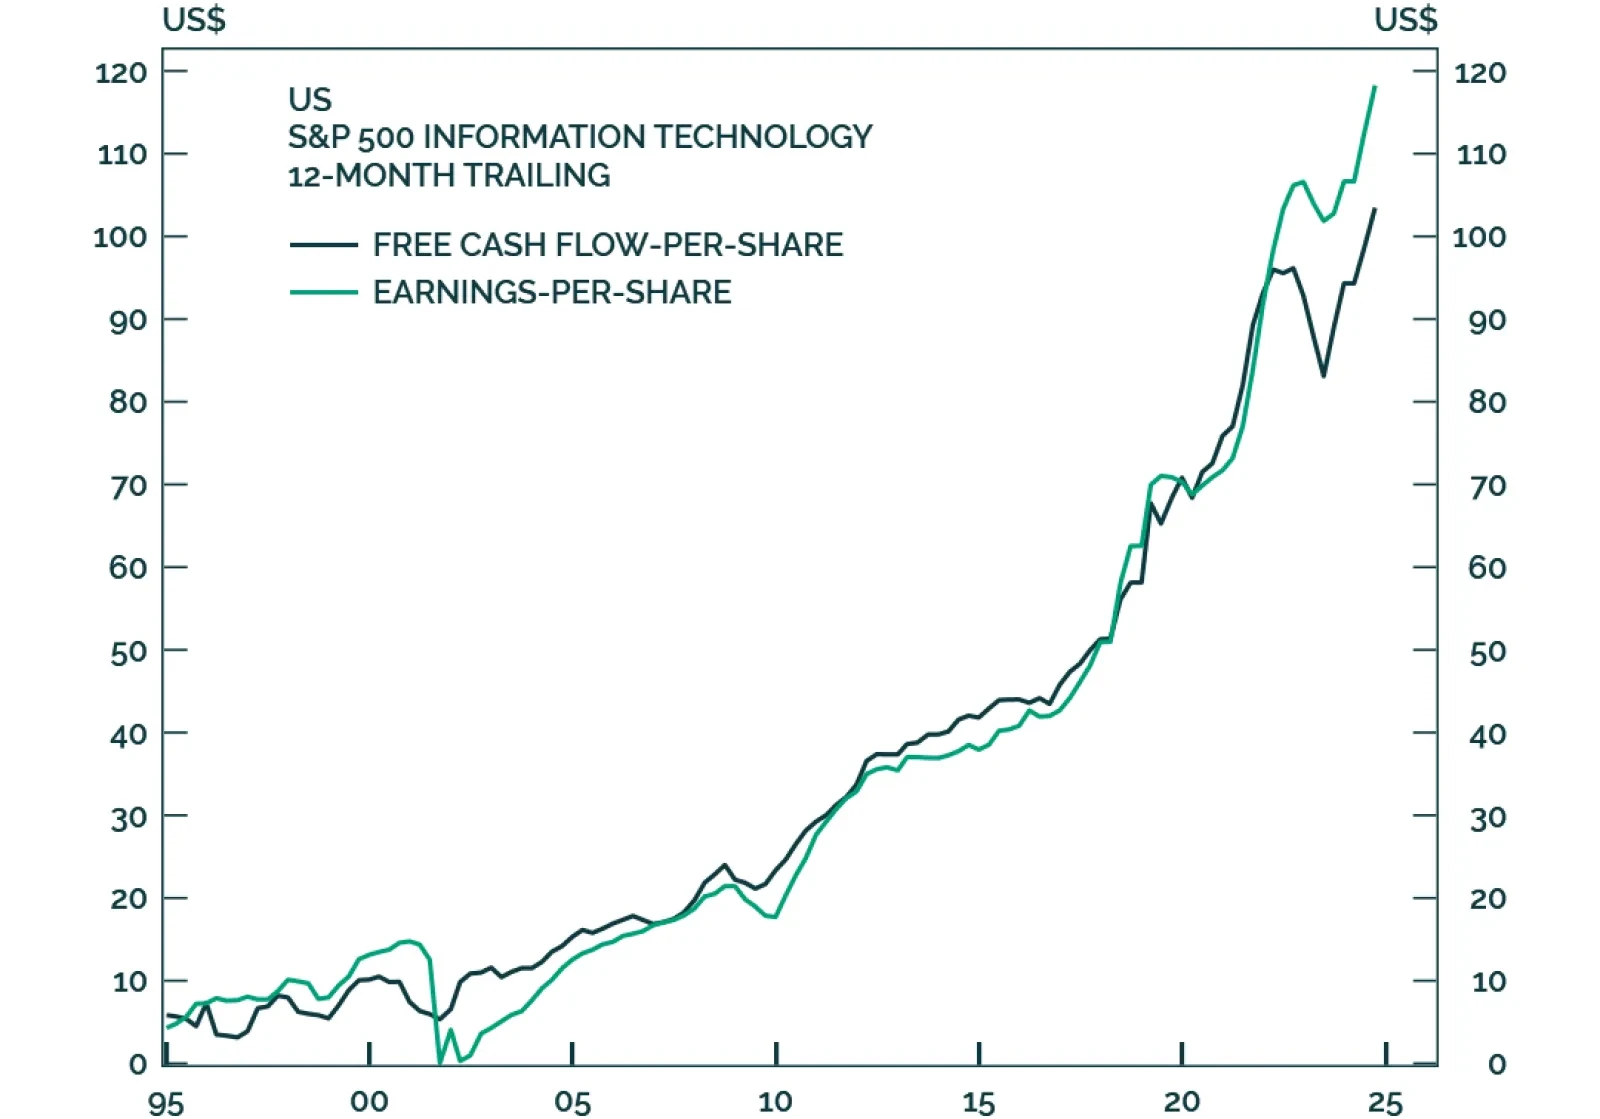
Since the end of 2021, EPS for the S&P 500 Information Technology sector has grown by 29%. In contrast, free cash flow-per-share has grown by only 11%.
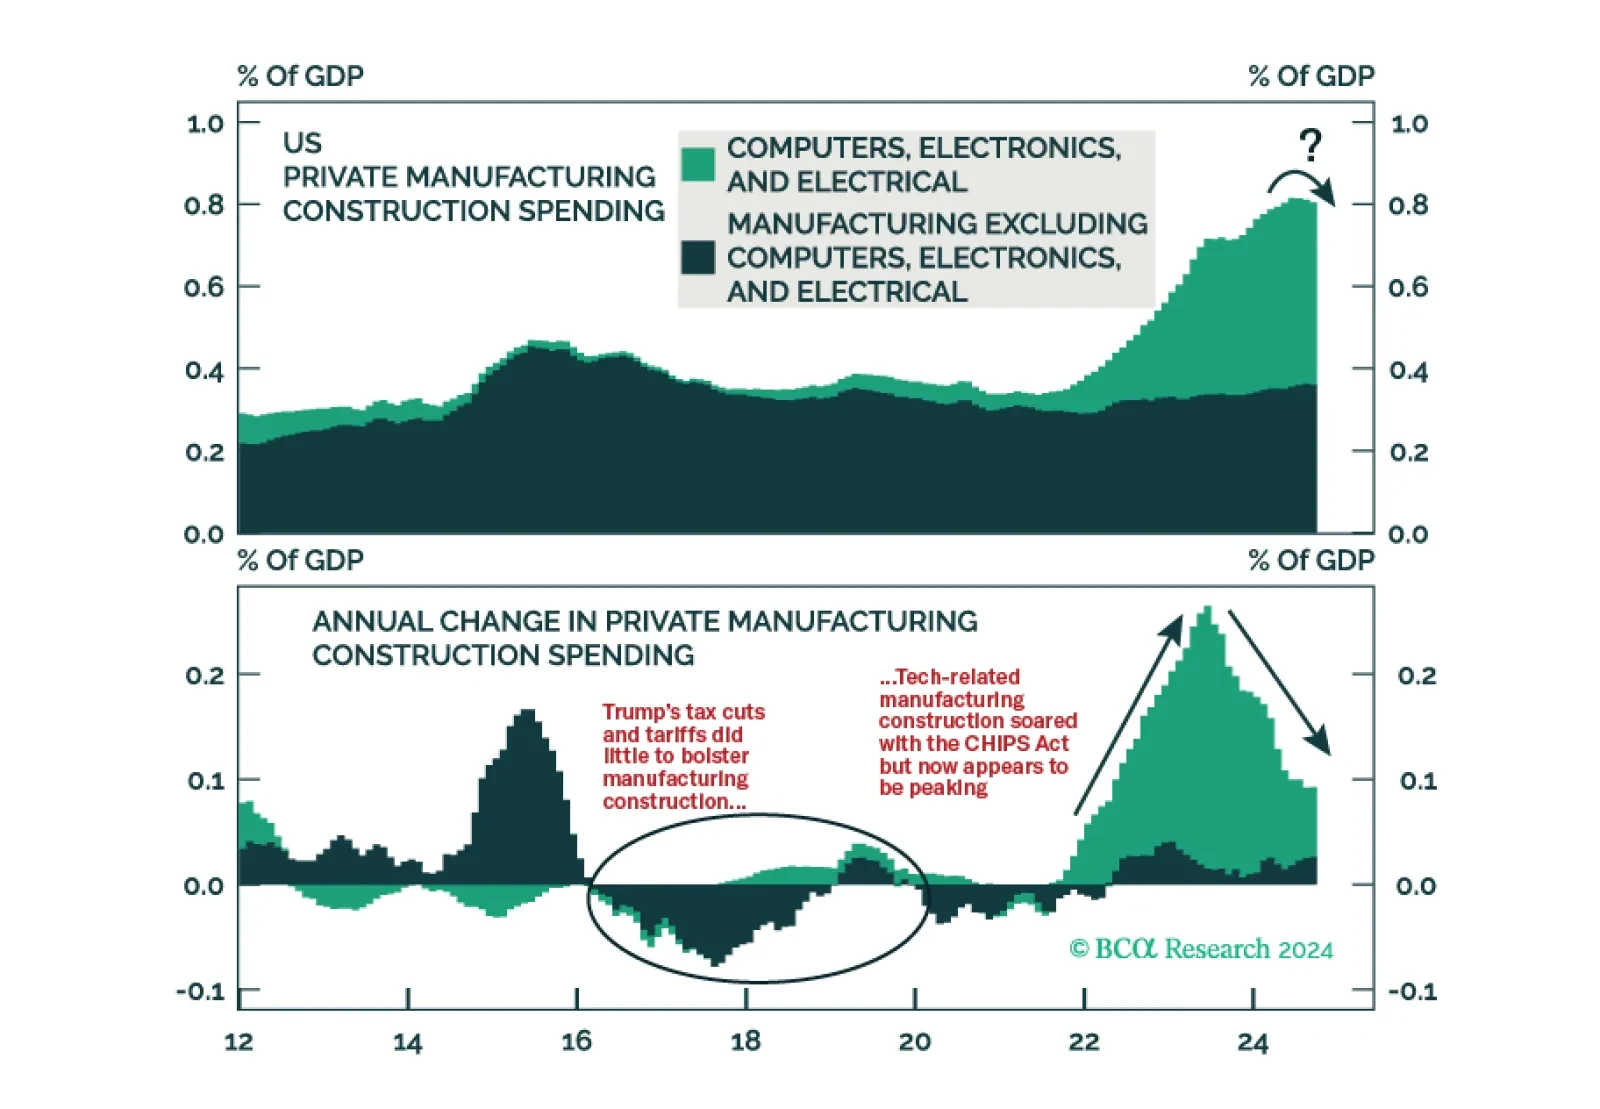
The prospect of a new trade war more than offsets the other pro-business parts of Trump’s agenda. With the labor market already weakening going into the election, we are raising our 12-month US recession probability from 65% to 75%.
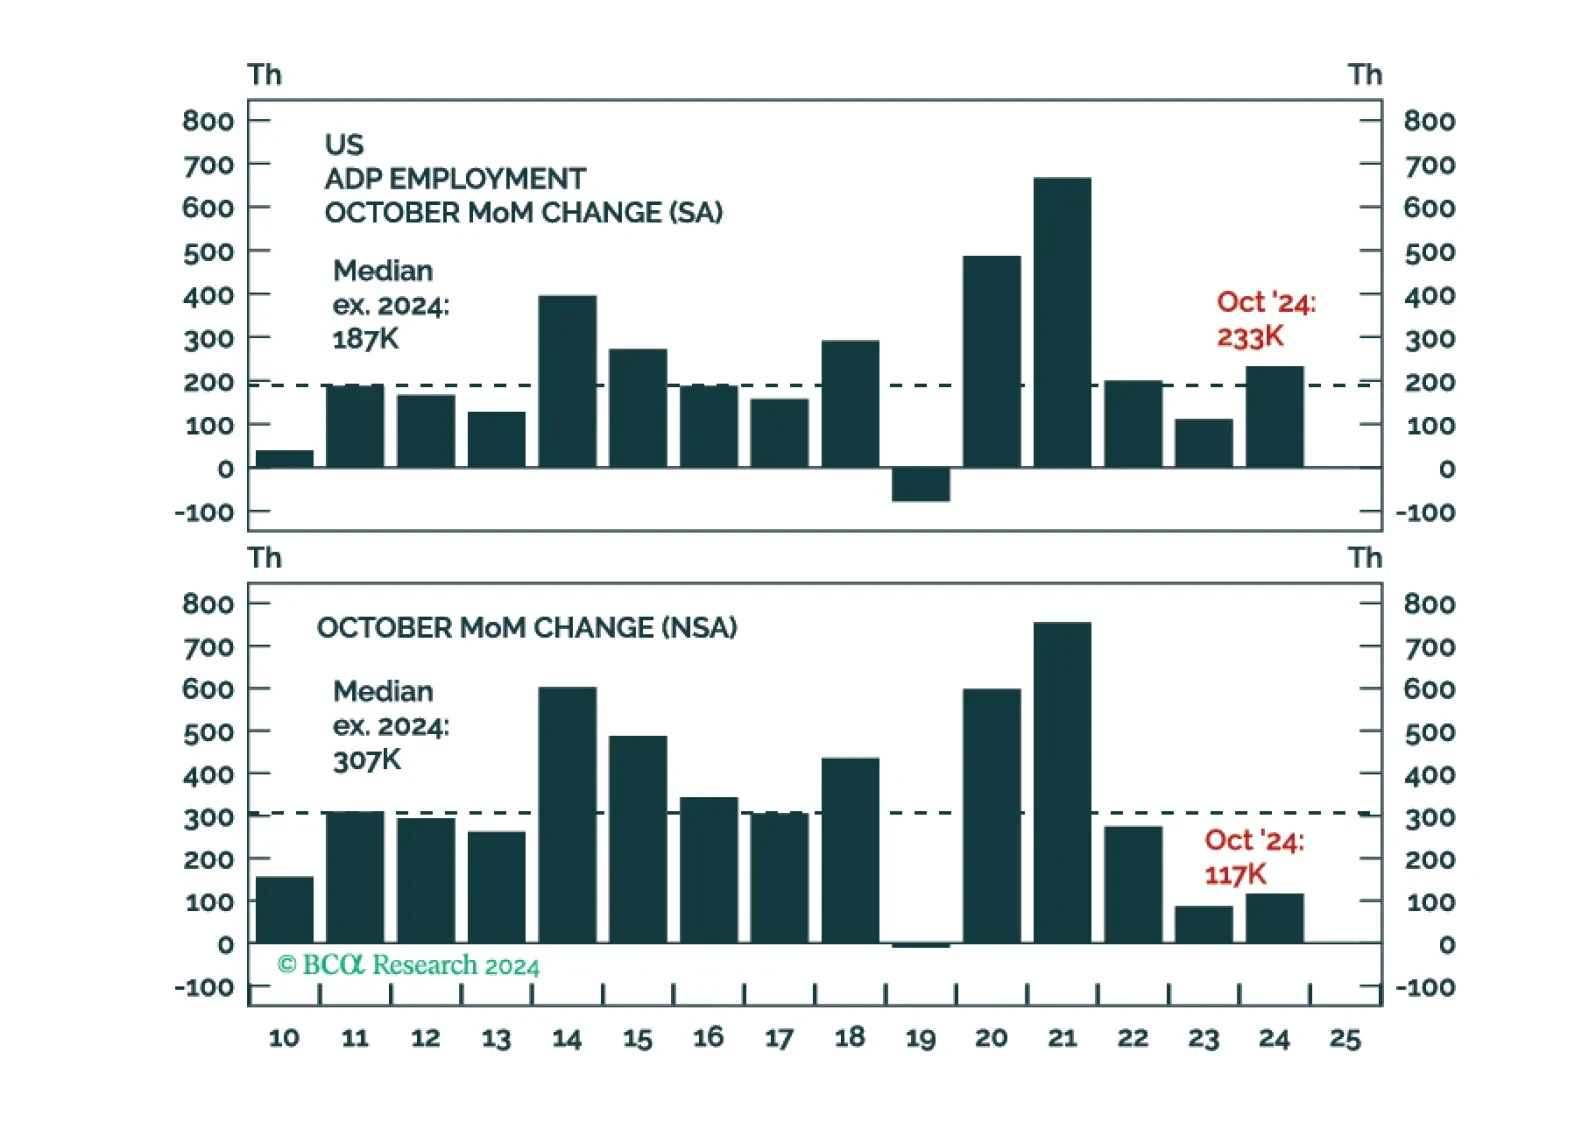
ADP's estimate of private payrolls rose by 233K on a seasonally adjusted basis in October, blowing away the consensus estimate of 111K.