Developed Countries
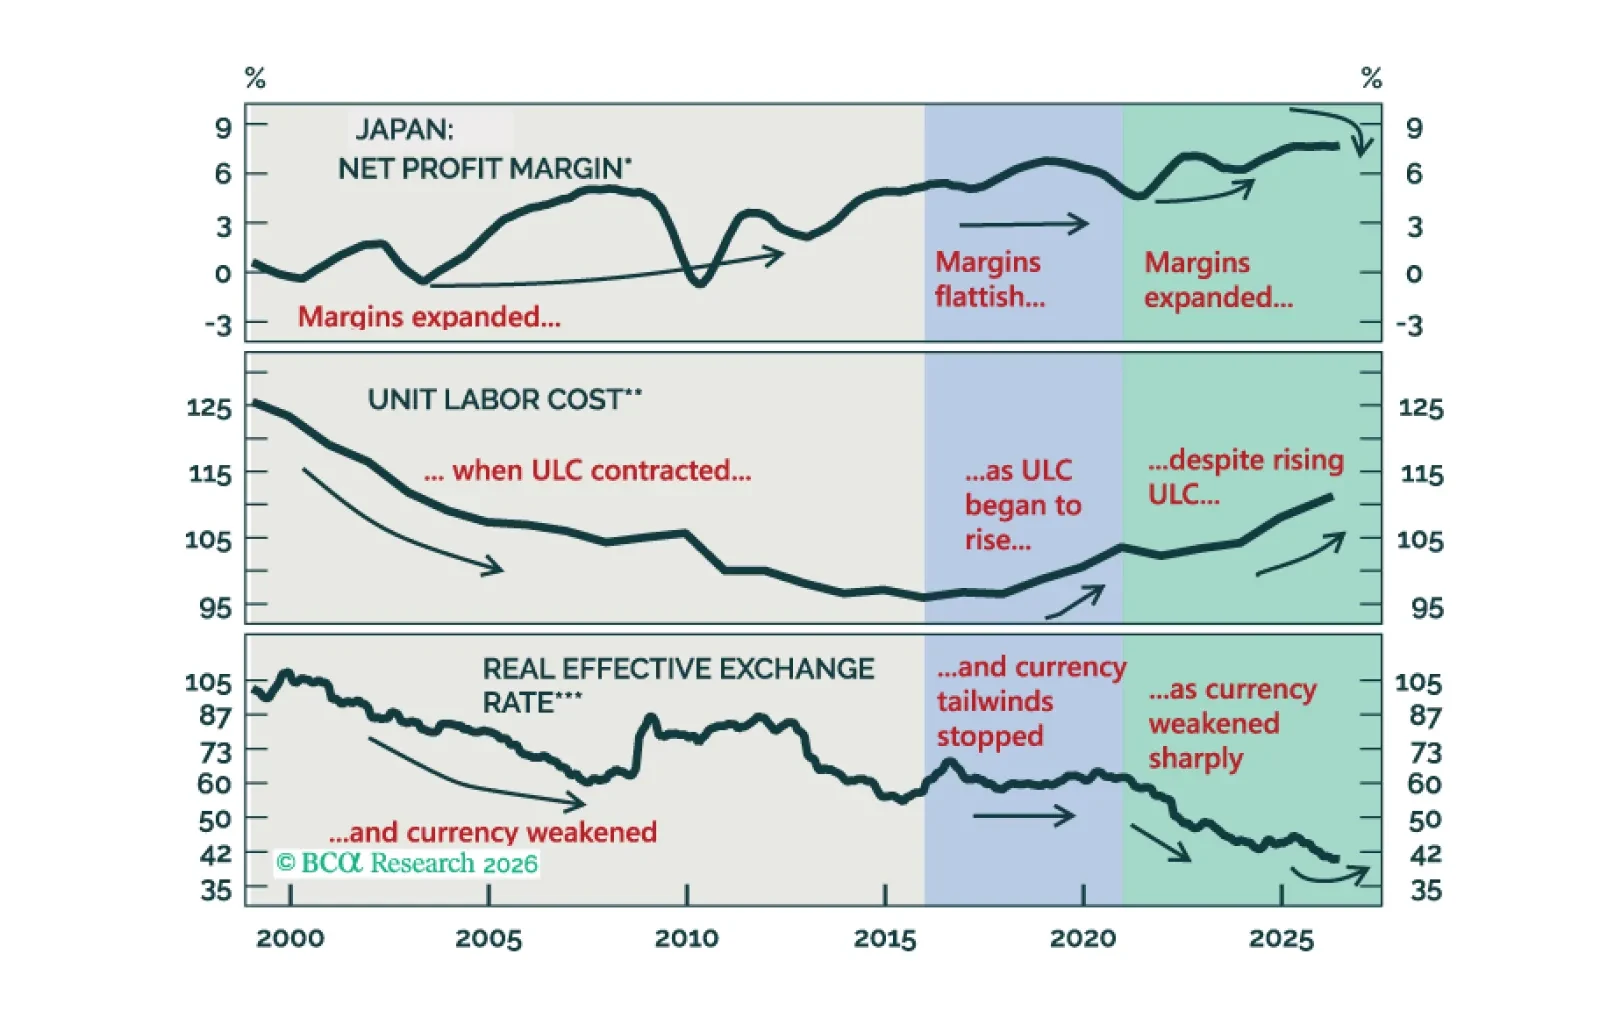
Over the past 10 years, Japan’s profit margin expansion has been driven neither by advances in labor productivity nor by operational efficiency gains, but by massive currency devaluation and lower depreciation charges. Going forward, higher wages and unit labor costs, as well as currency appreciation, will become major headwinds to margins.
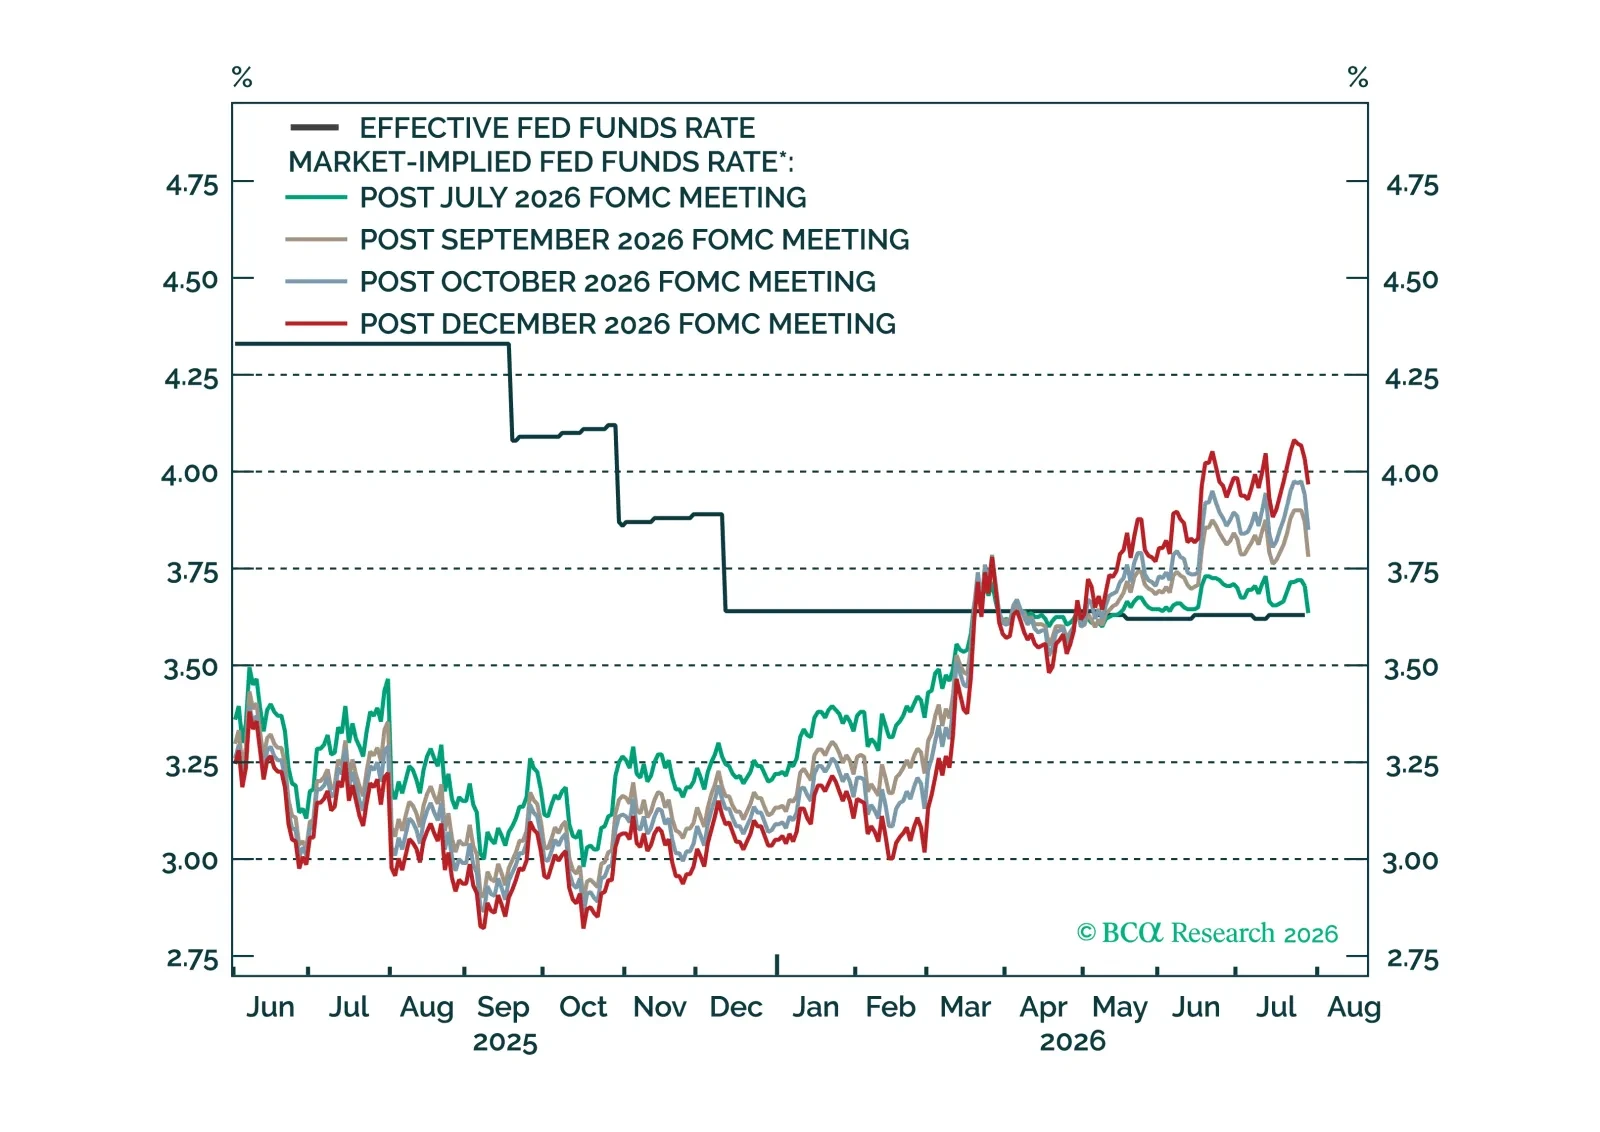
Despite today’s hold, the bar for a rate hike in September remains low and contingent on the next two core CPI reports.


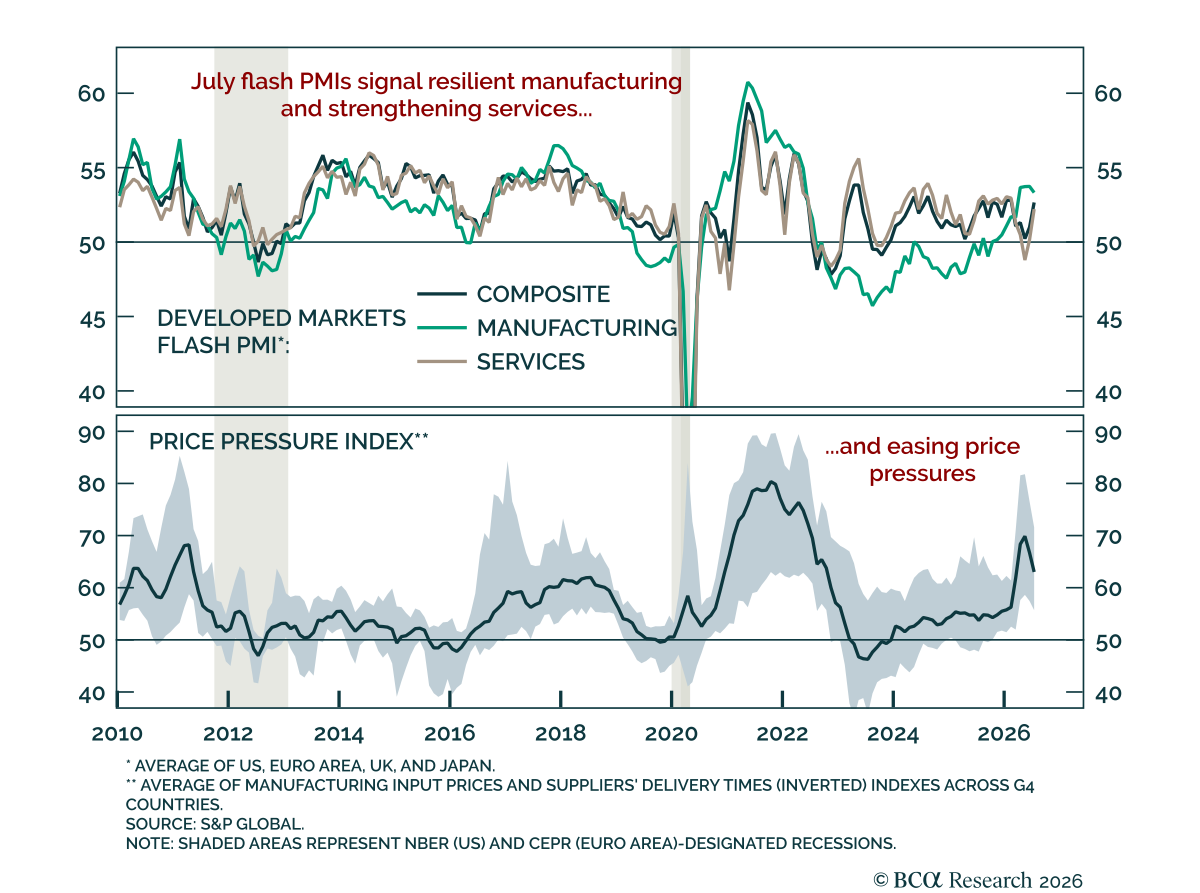
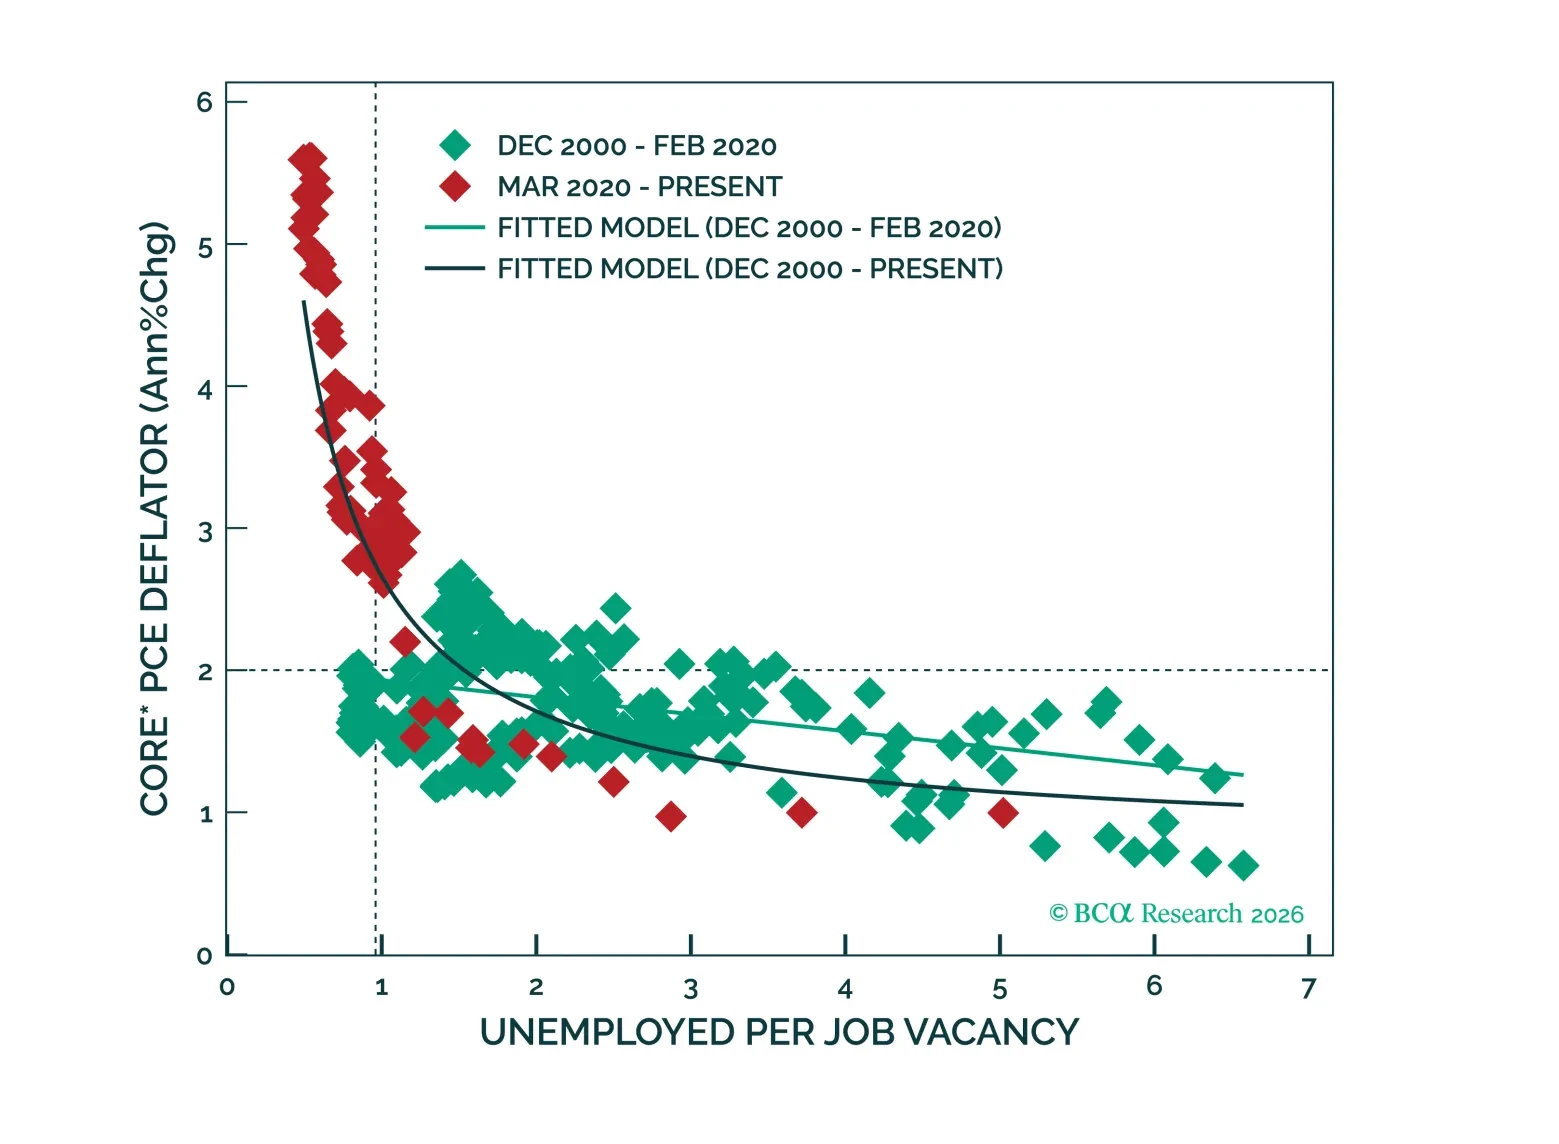
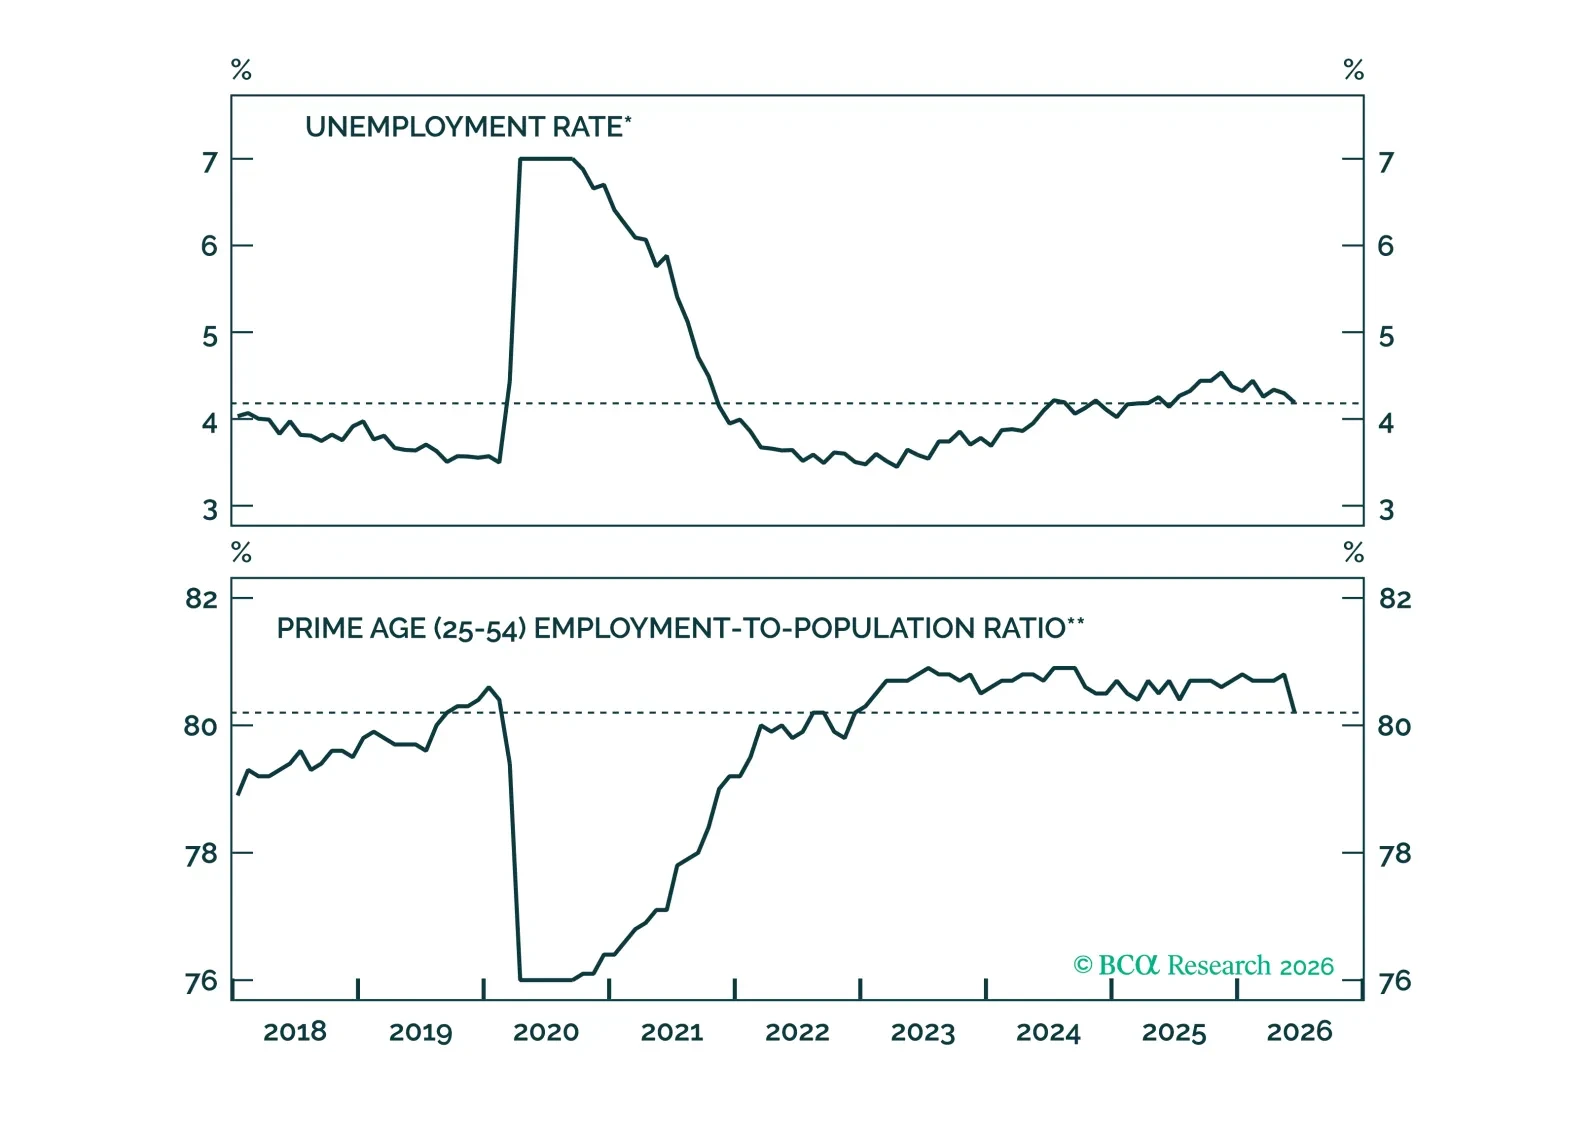
Most Fed and pundit assessments of inflation expectations are overly narrow, focusing too much on long-term market-based measures. We favor a more qualitative approach that asks whether the inflation outlook is influencing household and business decision making.
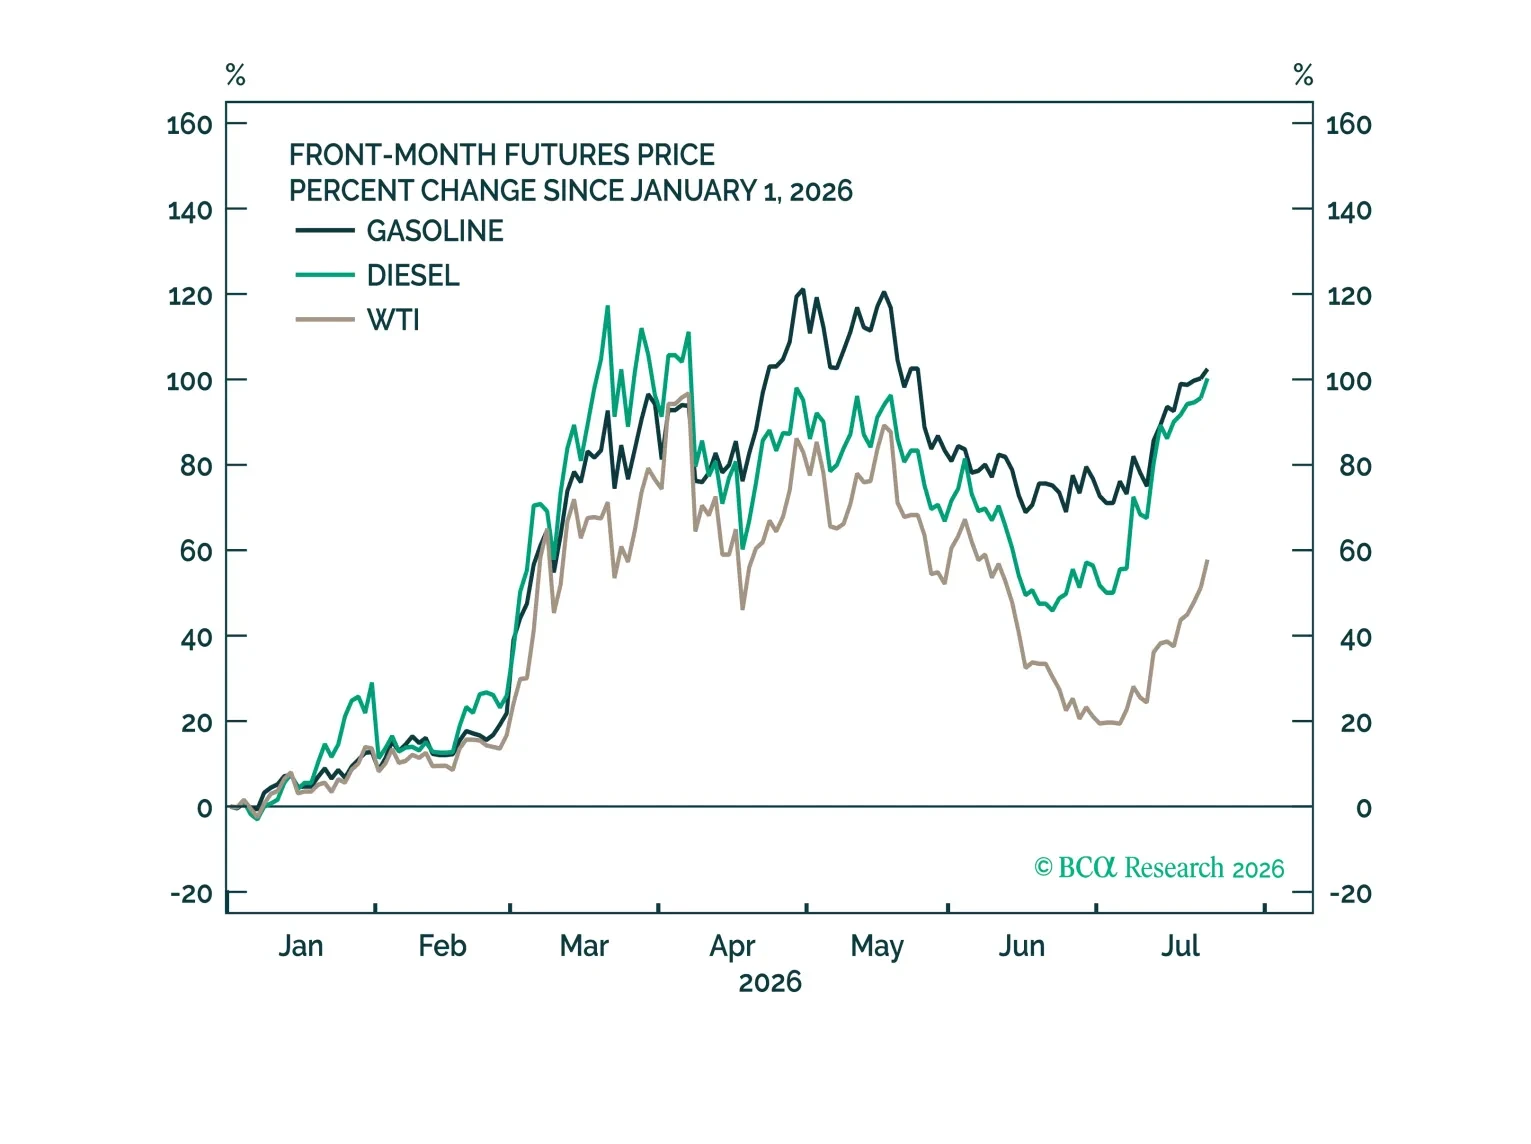
As long as the AI boom keeps booming, all other investment considerations will remain on the back burner. However, if the AI trade fizzles, this would expose deep-seated problems within the global economy, which could very well lead to an economic downturn as early as next year.
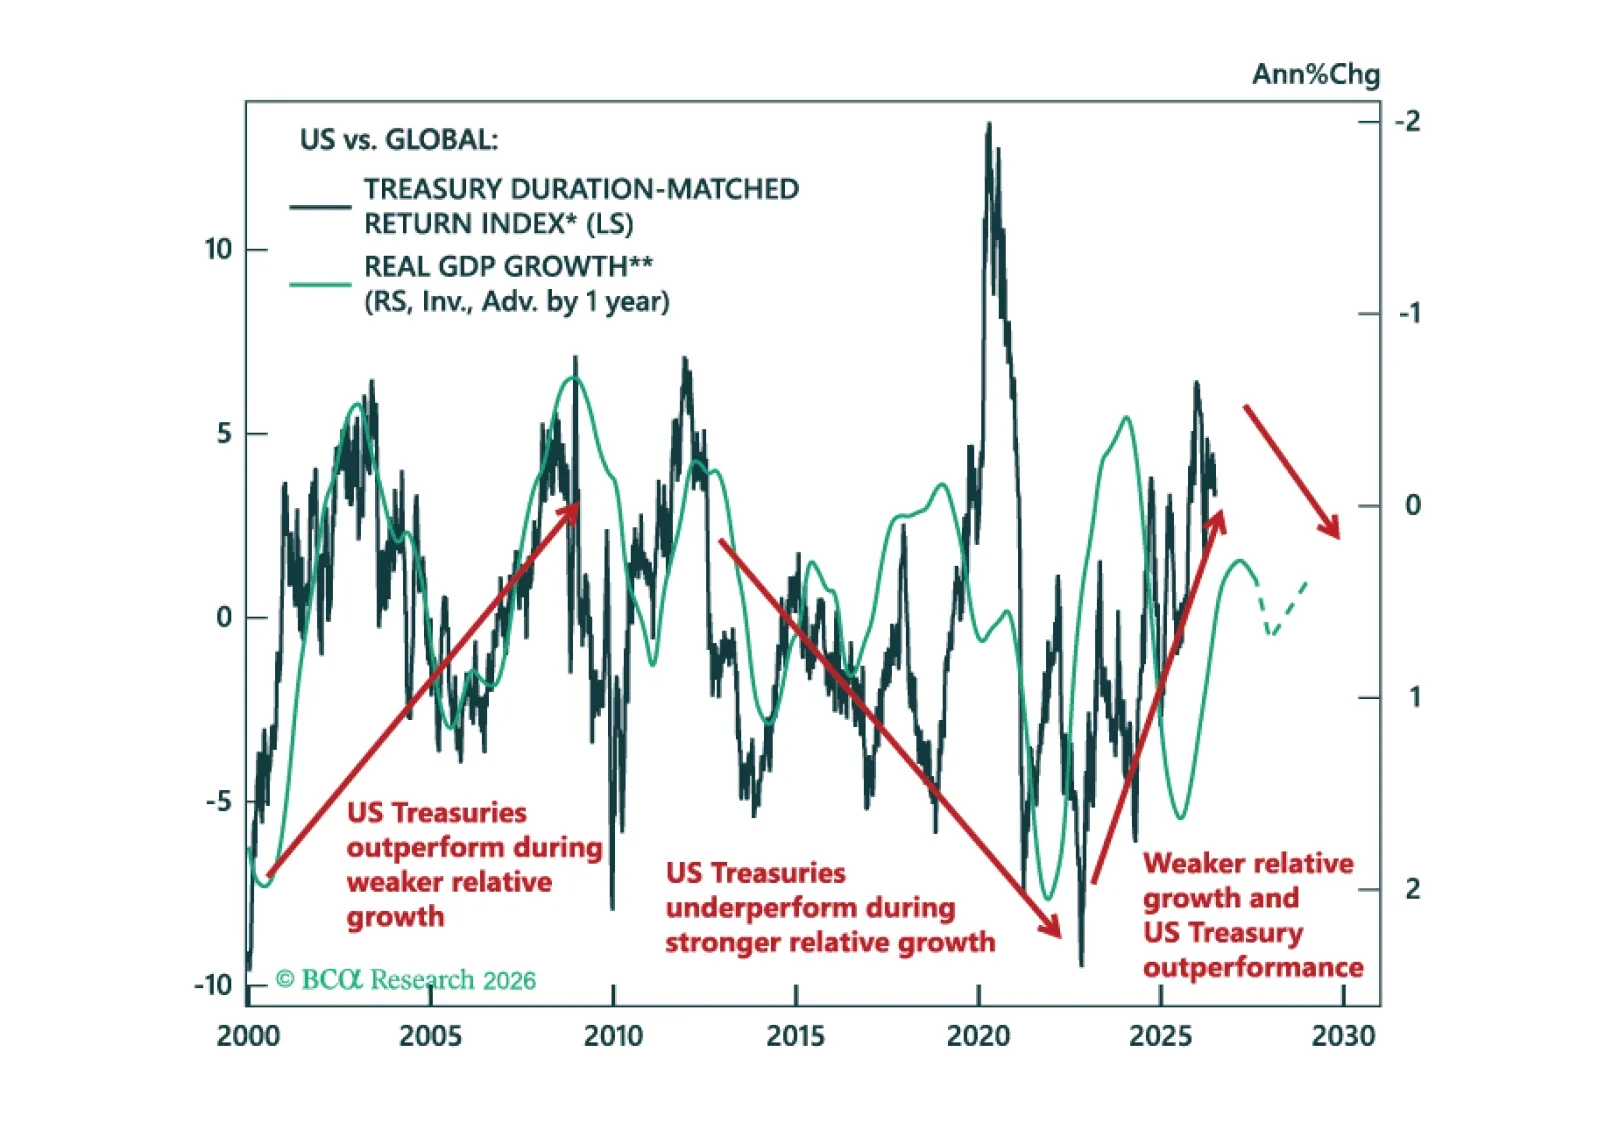
We review our Model Bond Portfolio performance for Q2 and look ahead as fixed income markets move beyond the US-Iran conflict, which is finding its kinetic equilibrium. Valuations and growth differentials are moving against continued US Treasury outperformance.
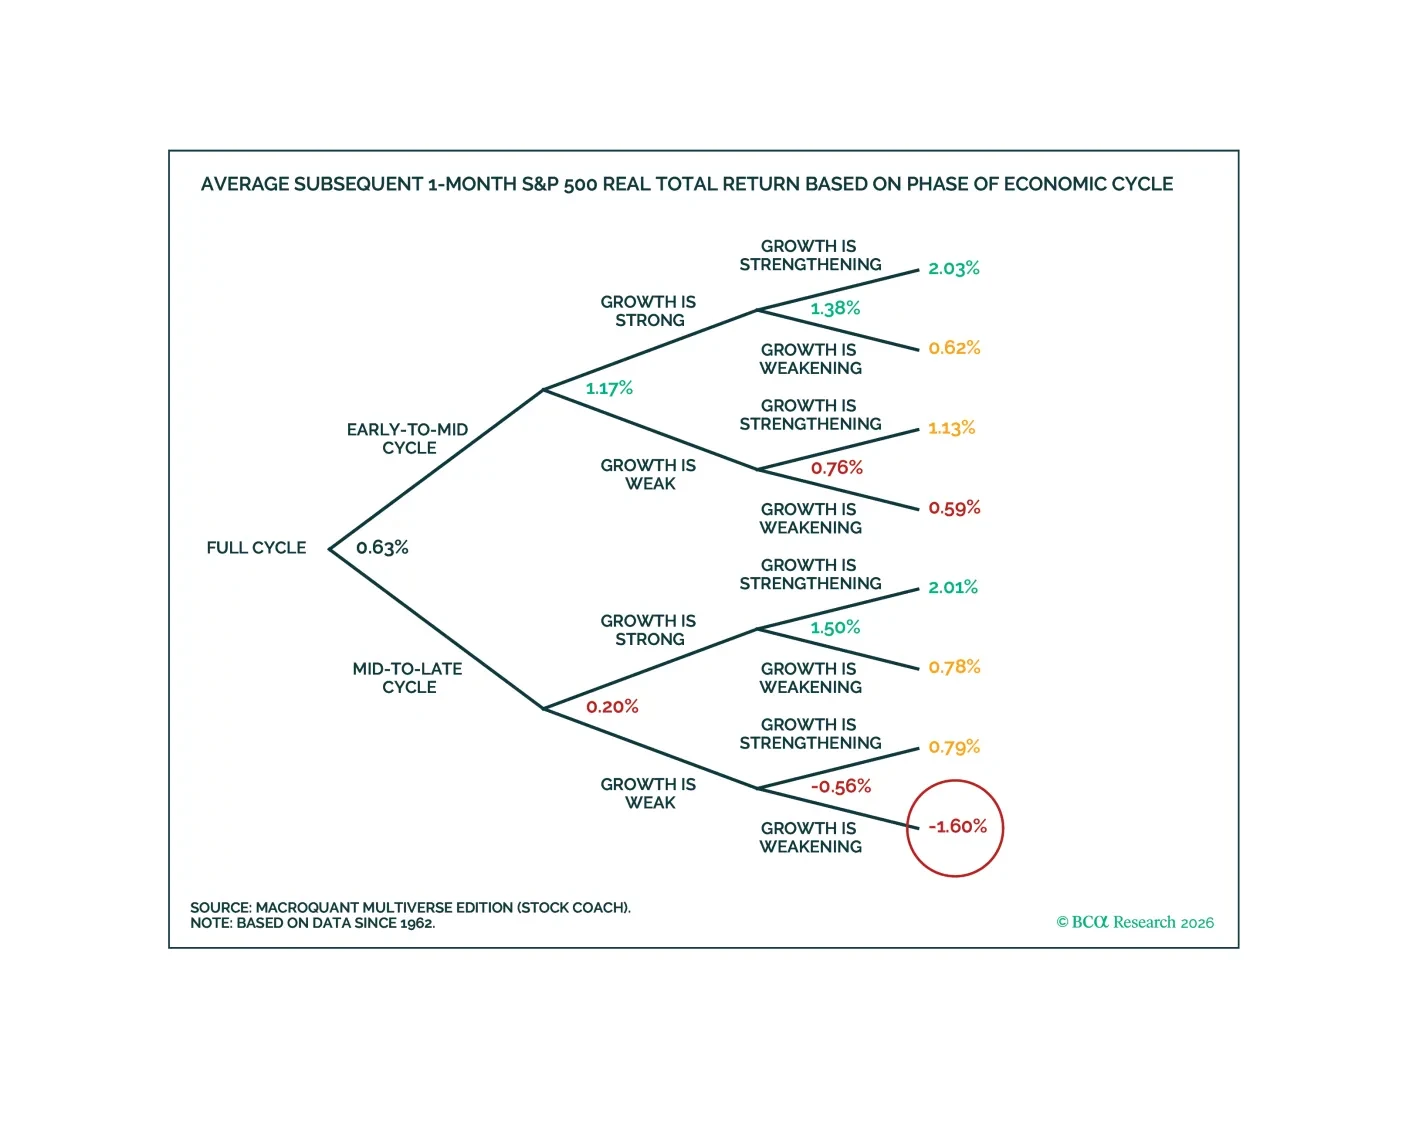
MacroQuant recommends underweighting equities and adopting a benchmark duration stance in fixed-income portfolios. The model is very positive on the US dollar, bearish on gold, neutral on copper, and bullish on oil.