Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Currencies

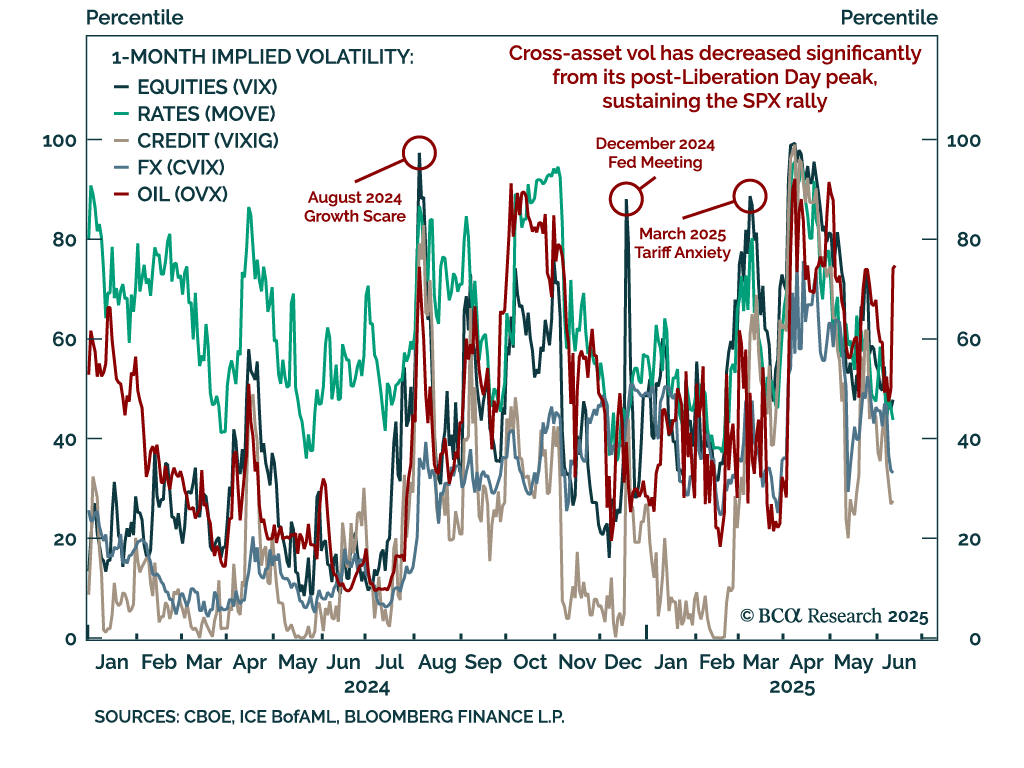
The S&P 500 has breached 6000 and may retest all-time highs, but we would not recommend chasing the rally. Risk assets have shrugged off recession fears, with stress indicators like the VIX, SKEW, and VVIX still subdued, signaling limited demand for…
Our Global Asset Allocation strategists remain underweight US equities and the dollar, as fiscal policy overtakes tariffs as the key market driver. The “One Big Beautiful Bill” may avoid worst-case scenarios, but rising US yields are already weighing on…

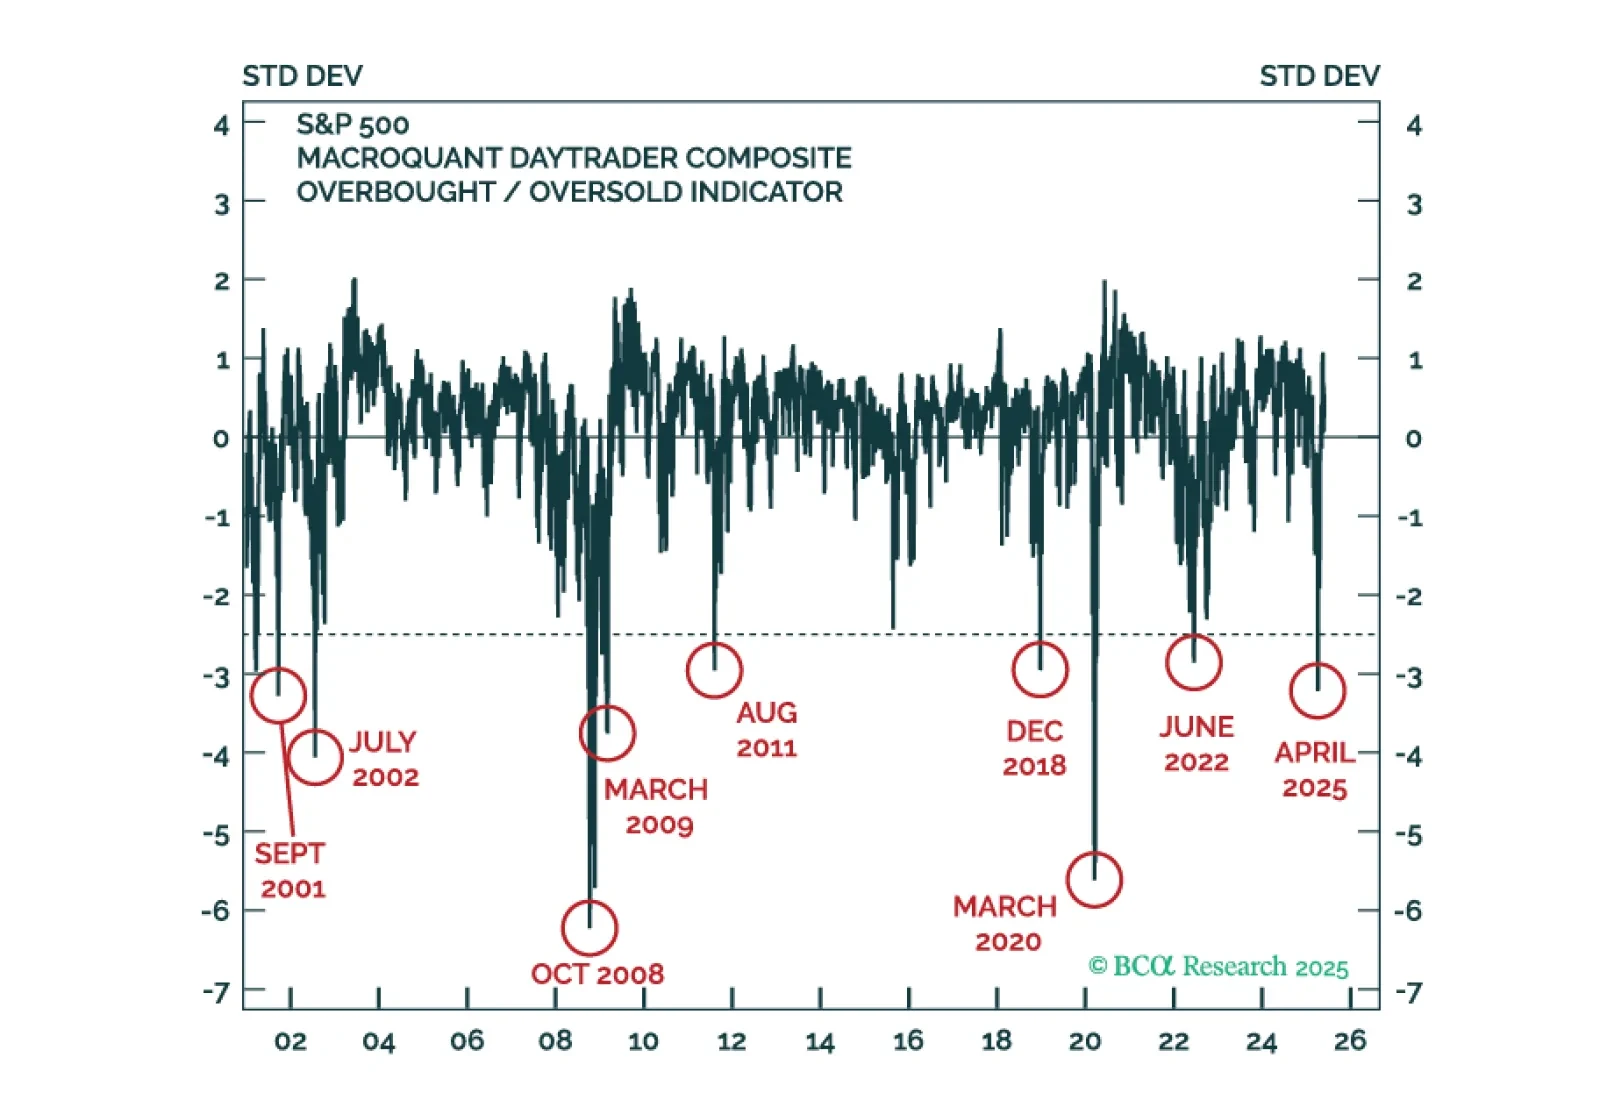
MacroQuant warns that US equities are pricing in very little economic risk. The model is shunning equities and recommends a large overweight to cash.
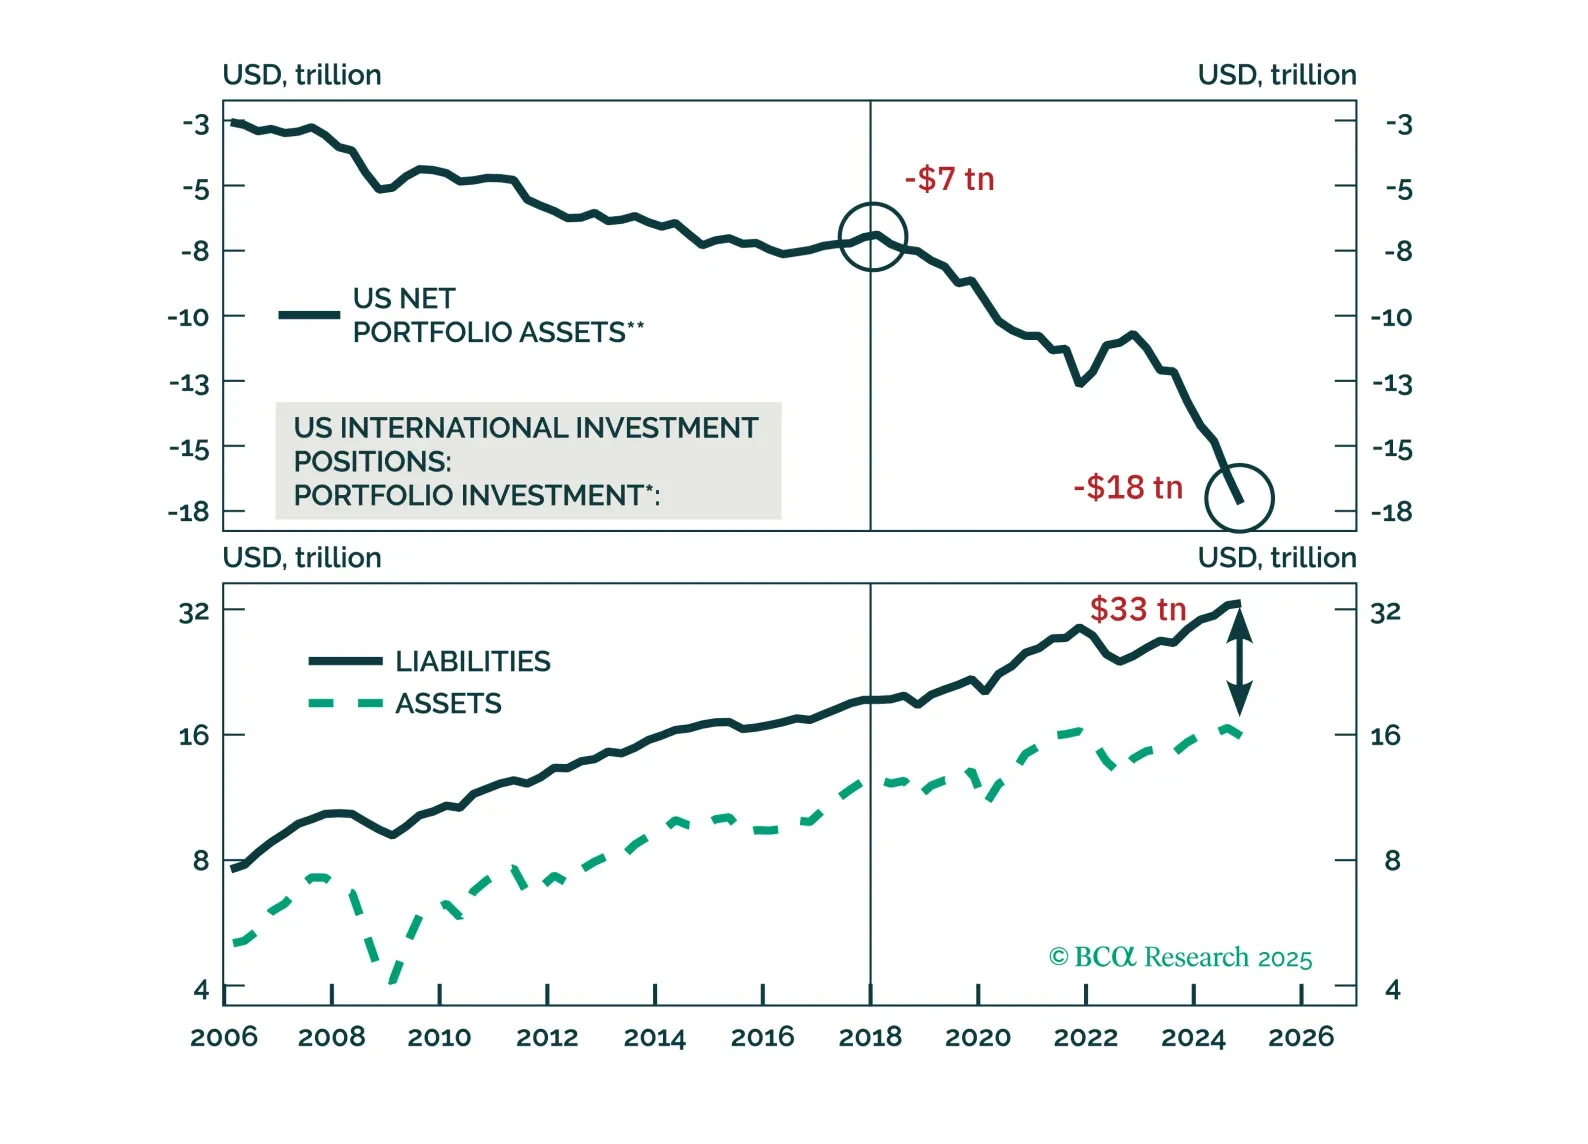
MacroQuant warns that US equities are pricing in very little economic risk. The model is shunning equities and recommends a large overweight to cash.

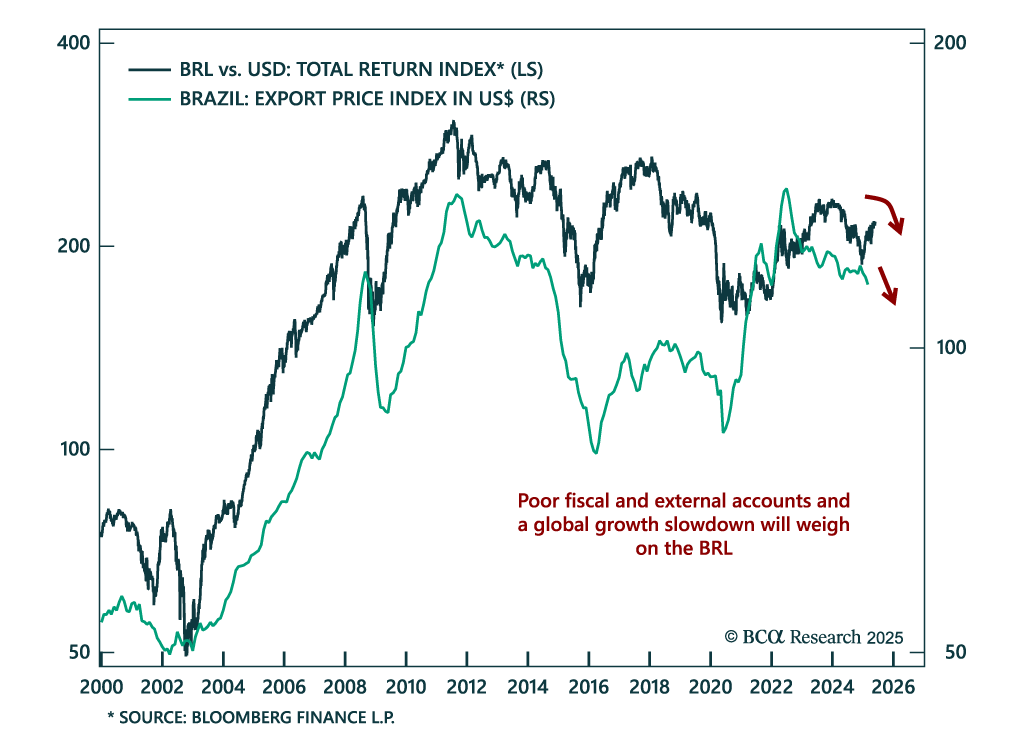
The most recent Brazilian data surprised positively, but underlying economic troubles will spoil the party for the country’s financial markets. Wholesale inflation came in at -0.49% in May relative to last month, while the unemployment rate fell from 7%…

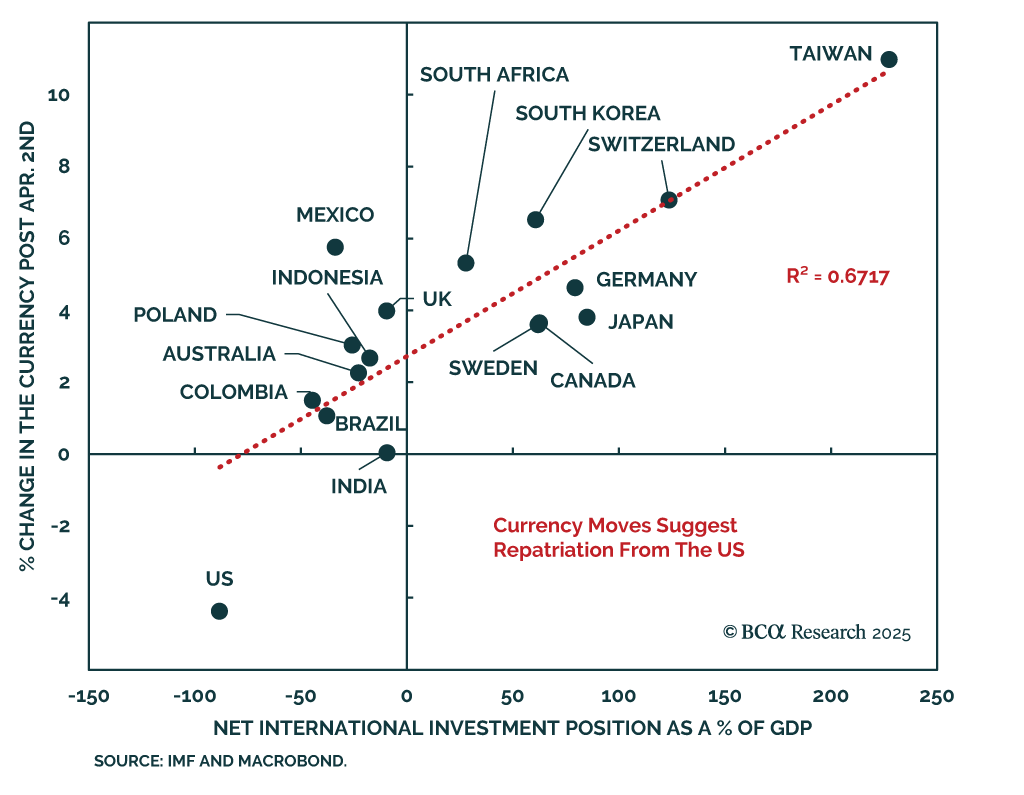
Global currency markets have entered a new era. This implies that the framework for analyzing exchange rates must also change. We introduce a new framework for analyzing EM currencies and classify them into resilient and vulnerable categories. Finally, we are adding more EM domestic bonds to our portfolio and making many changes to our currency trades.
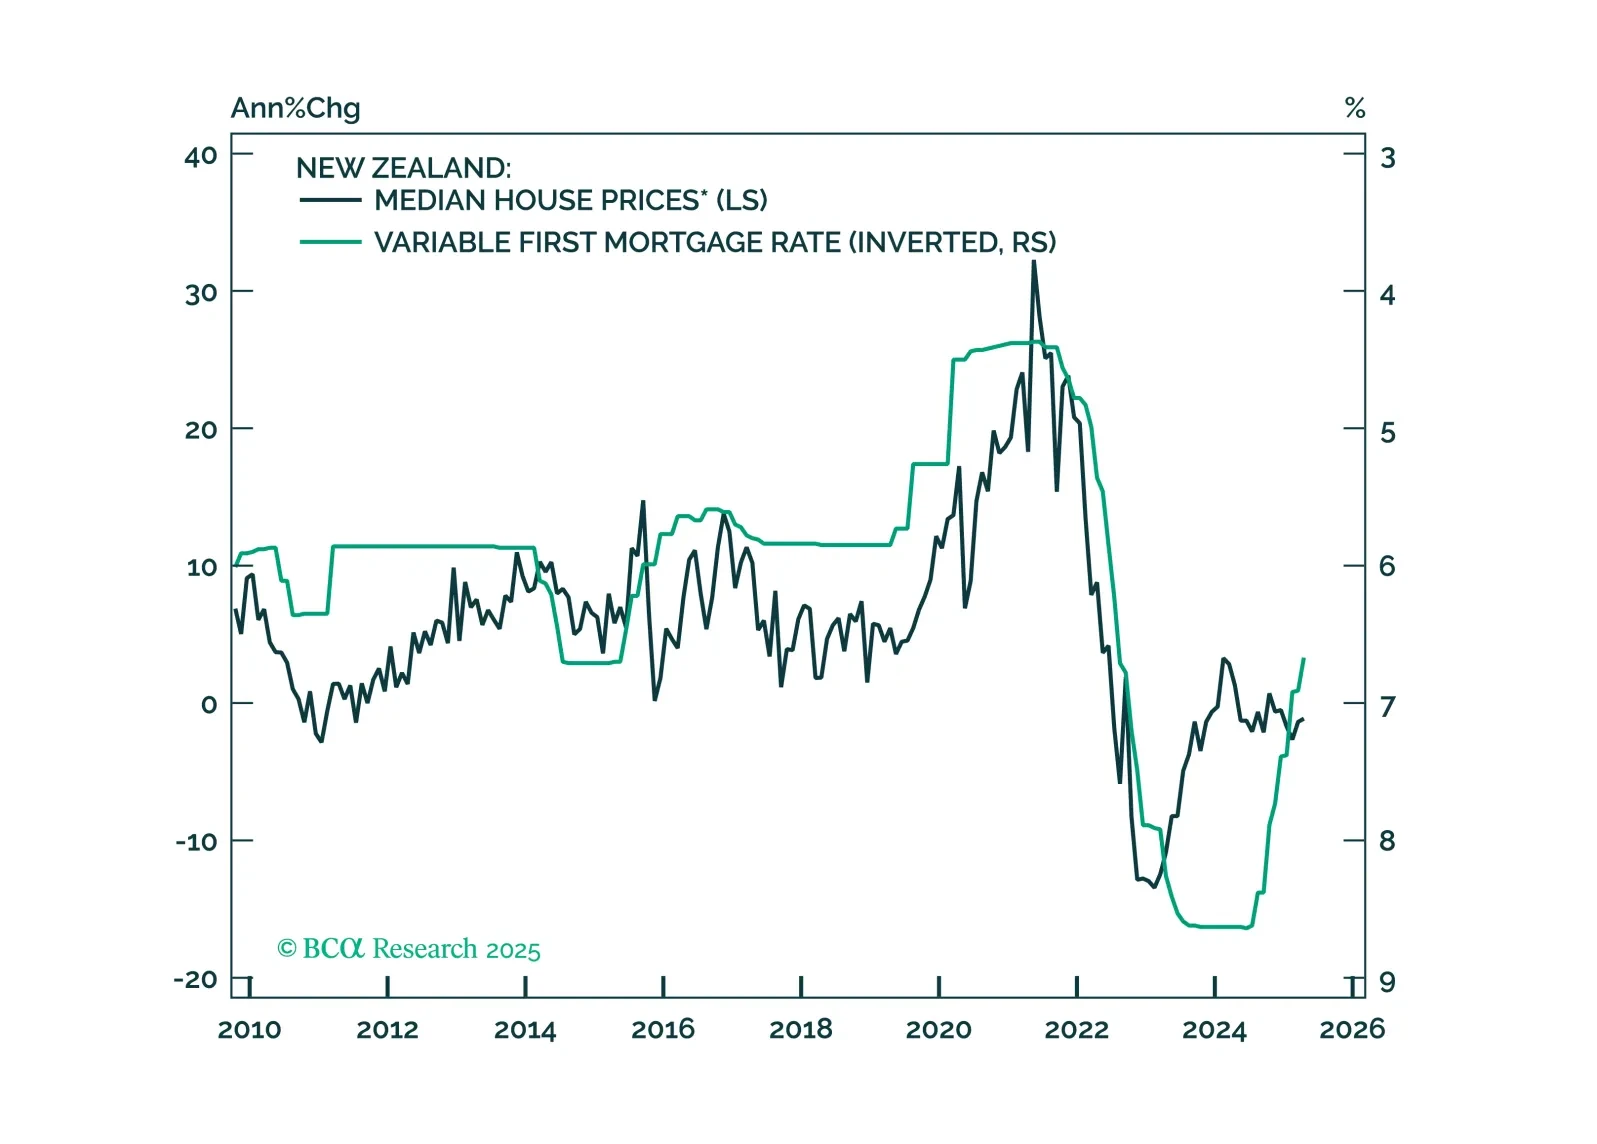
This Insight looks at the implications of the RBNZ’s rate cut on New Zealand assets. 
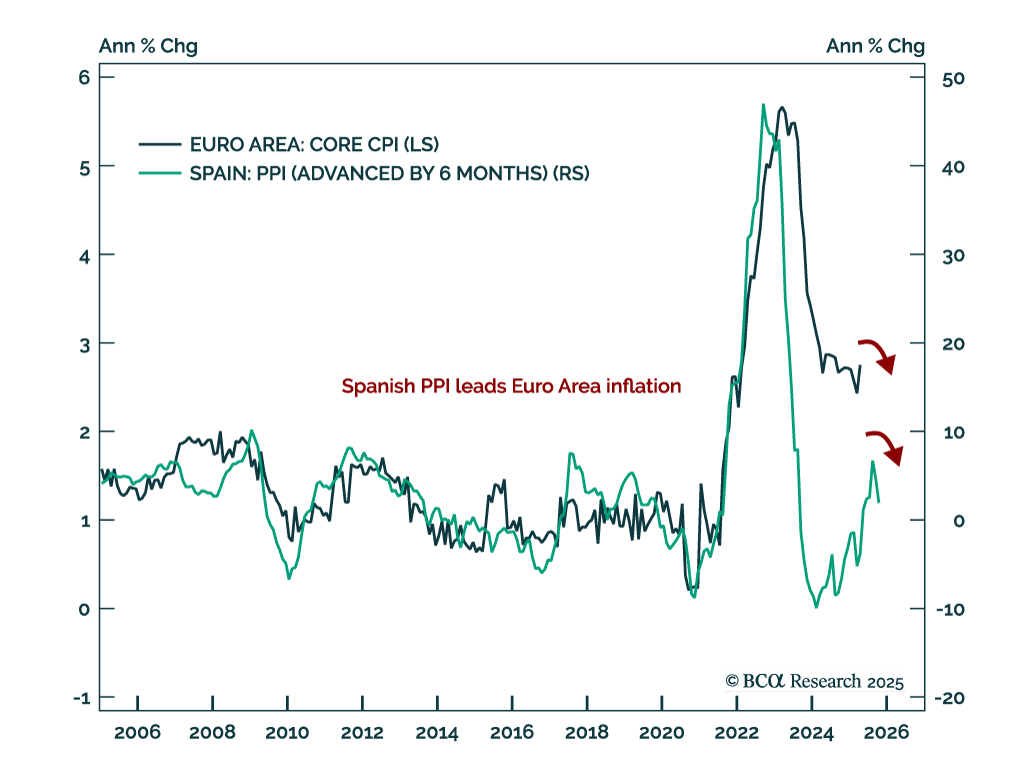
Producer prices in Spain surprised to the downside, foreshadowing a relapse in Euro Area inflation and cementing the ECB’s dovish stance. The Spanish PPI index fell to 1.9% in April, continuing the disinflation trend from the last period while recording the…

Right now, the major stock and bond markets are more ‘anti-fragile’ than fragile, and the Joshi rule recession indicators signal that a US recession is not imminent. This justifies a neutral, or default, tactical weighting to both stocks and bonds until a major market does become fragile, or until recession risk elevates. The one major price trend that is fragile is the 65-day selloff in the US dollar, which justifies a tactical overweighting to the dollar.
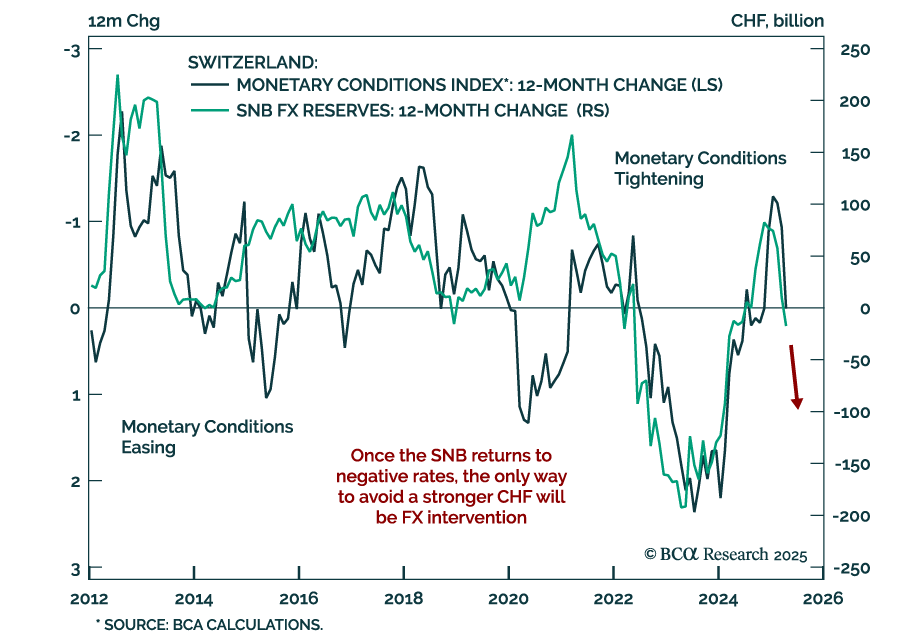
Swiss National Bank will have to resort to negative interest rates and FX intervention before year-end. Swiss inflation fell to 0% year-over-year in April, or the lower end of the SNB’s 0%-2% target range, and the continued strength in the Swiss Franc…