Latest from BCA Research

Asset class expectations show mixed shifts from 2024, with Real Estate seeing substantial upgrades and Private Equity benefiting from Venture Capital improvements. Private Credit return expectations decline from 2024 but remain relatively attractive. Infrastructure shows varied dynamics across sub-strategies, with Value-Add offering strong return potential. Within Hedge Funds, Long-Short Equity shows higher tactical returns while Multi-Strategy leads strategic projections.
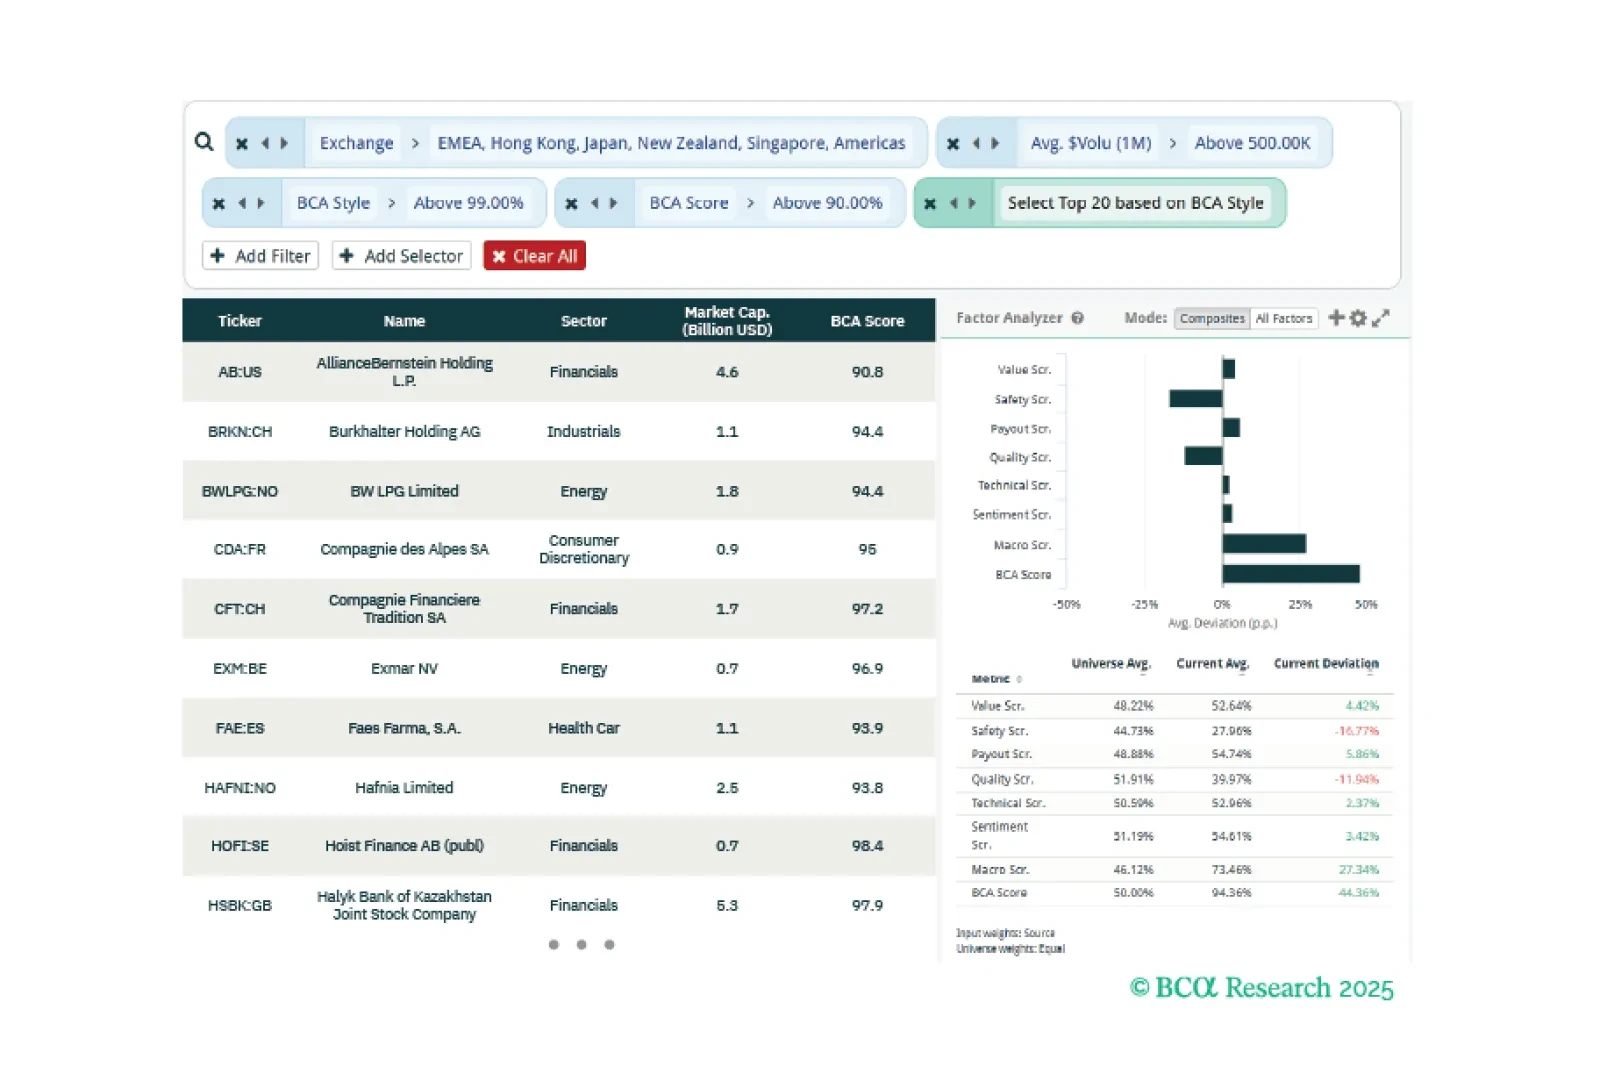
This week, our three screeners explore global small-cap value stocks, European equities, and BCA’s nuclear energy themed equity baskets.
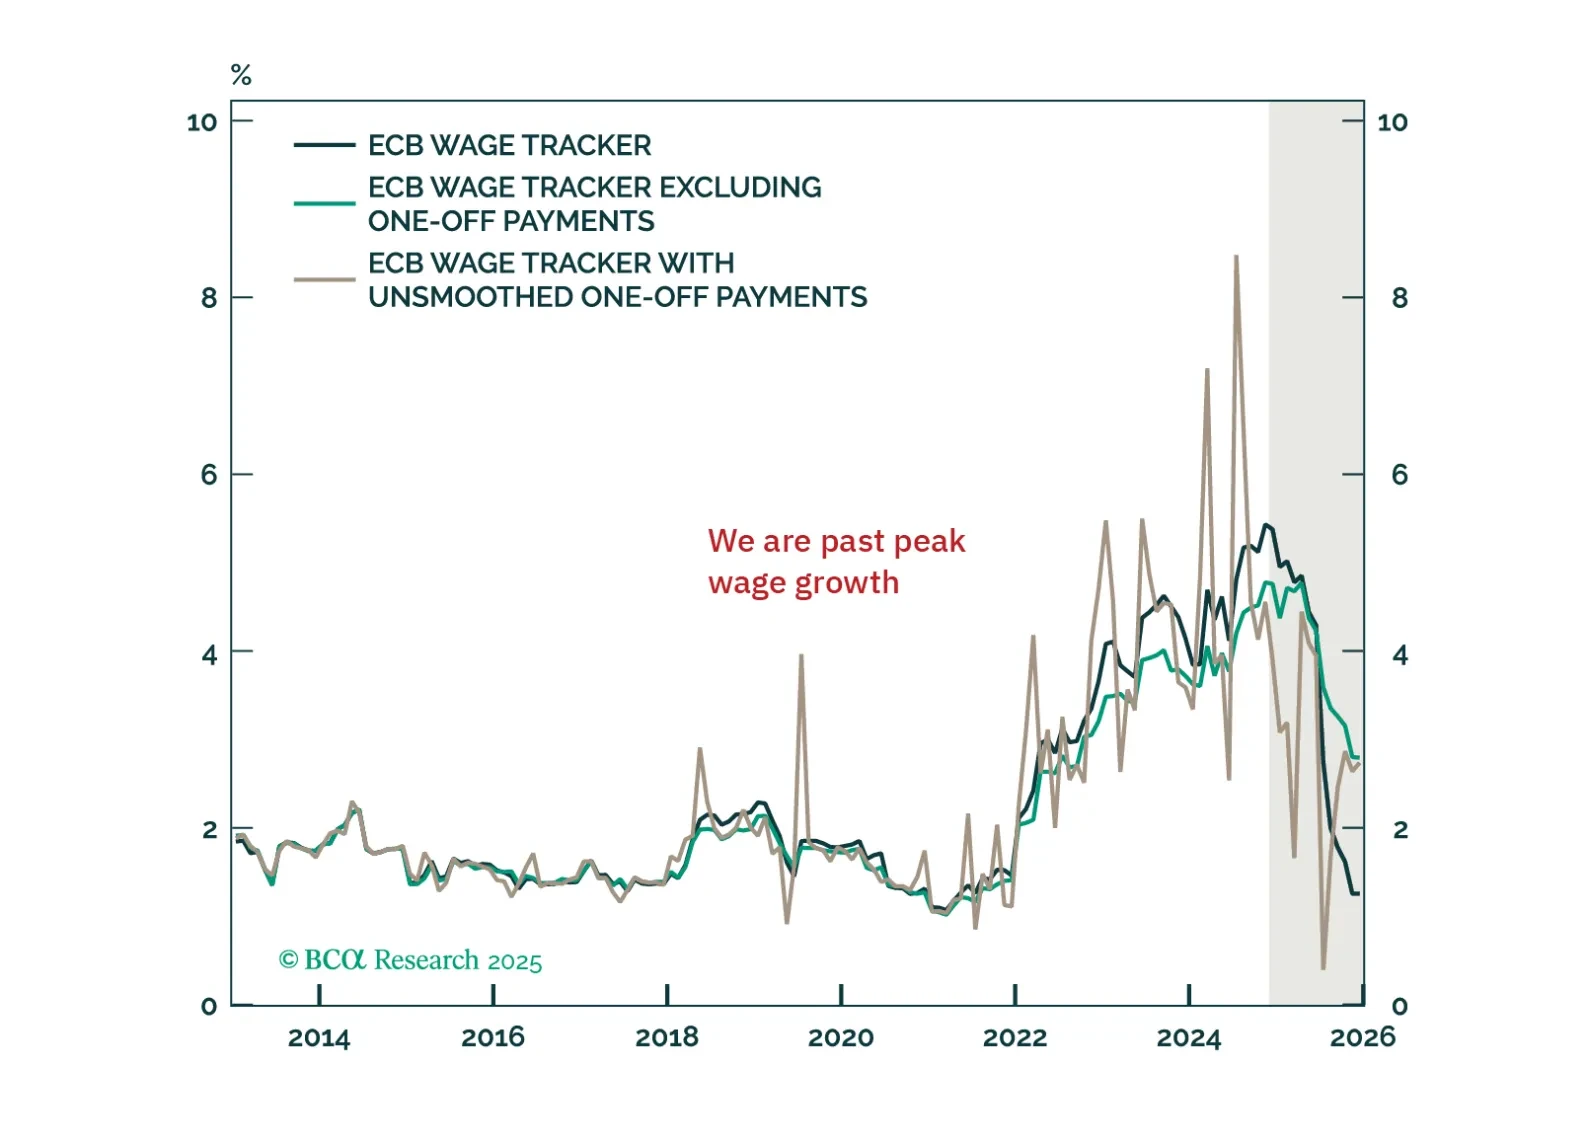
The ECB cut its deposit rate to 2.75%, as was widely anticipated. President Christine Lagarde did not provide any fireworks, but the Governing Council’s message was clear: Policy is restrictive, and inflation will fall further. As a result, if we combine our economic forecasts for the Eurozone with Frankfurt’s data dependency, we continue to expect the ECB’s deposit rate to settle below 2%. Consequently, German bond yields have downside, and the euro has yet to bottomed.
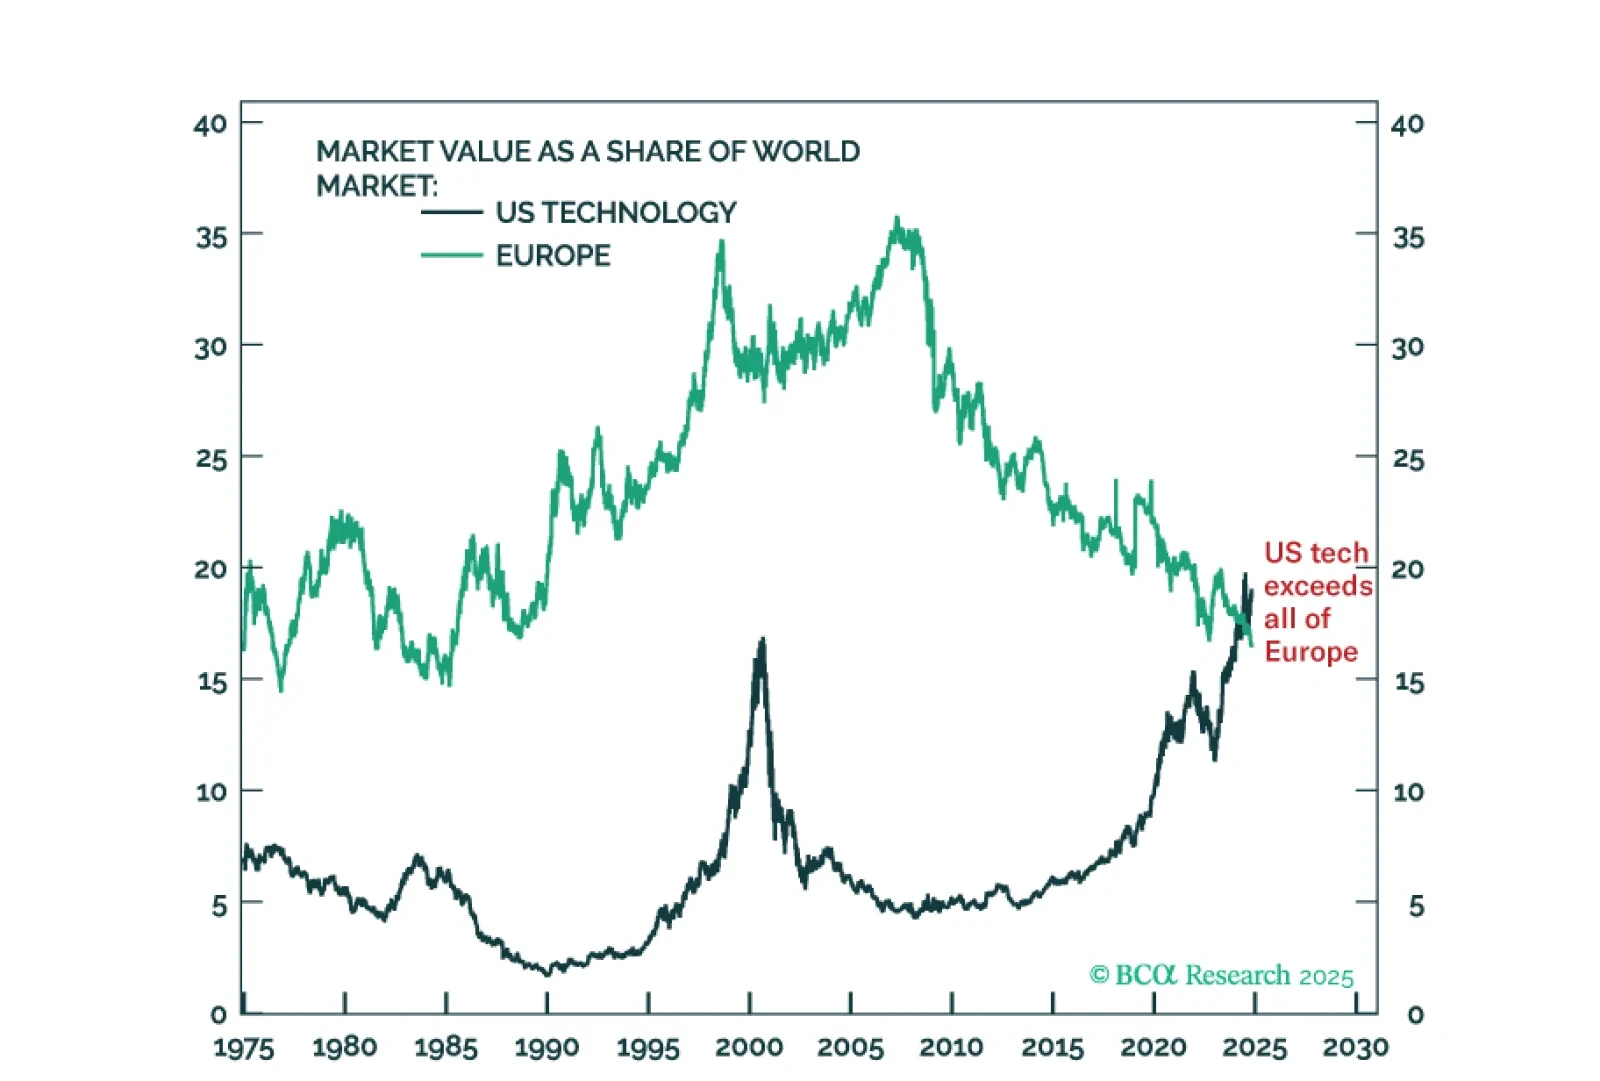
US tech stocks as a share of world stock market capitalisation is at an all-time high that exceeds even the peak of the dot com mania in 2000. At the other extreme, Europe’s share in the world stock market is at a 50-year low. While I am optimistic about the potential of generative-AI, I am not as manically optimistic as the market. And while I am concerned about the current malaise in Europe’s economy and politics, I am not as depressingly concerned as the market. For me, the AI mania combined with Europe’s current malaise is a 50-year mispricing… and opportunity. Plus: go tactically short coffee.
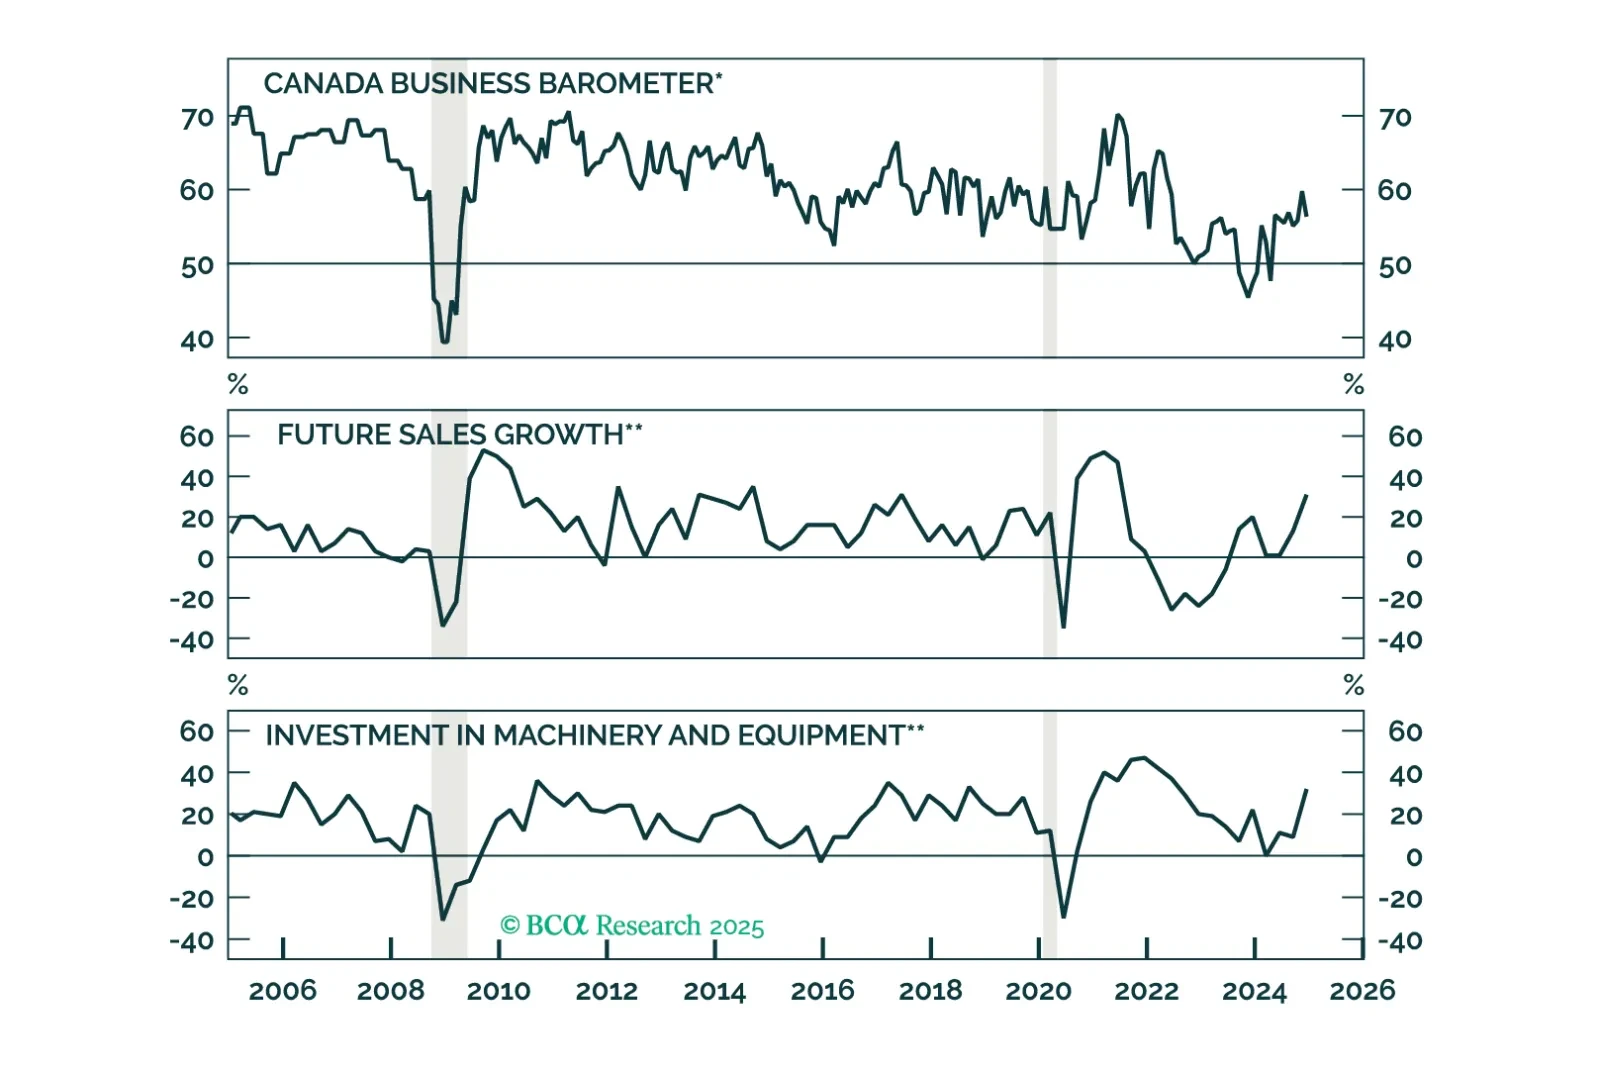
This Insight looks at what investors should do with CAD and fixed-income assets, given the rate cut by the Bank of Canada today.
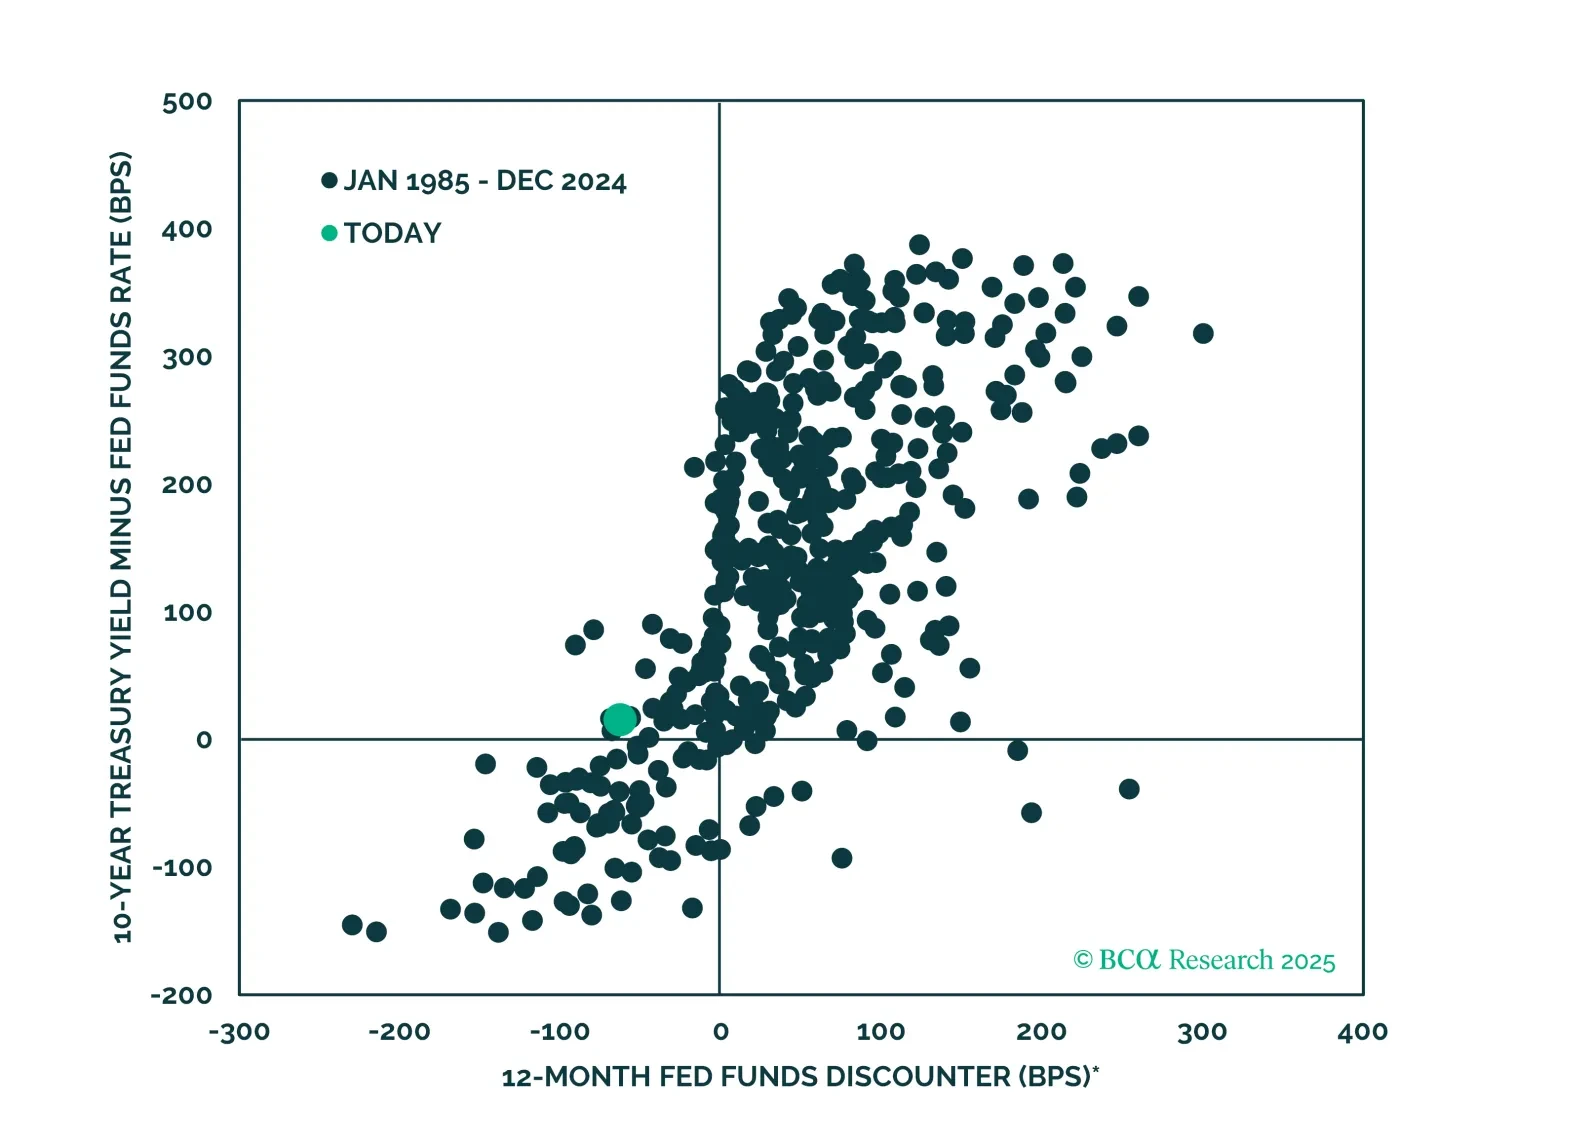
Jay Powell didn’t say much at this afternoon’s FOMC press conference, and monetary policy will continue to take a back seat to fiscal for the next few months.