Latest from BCA Research
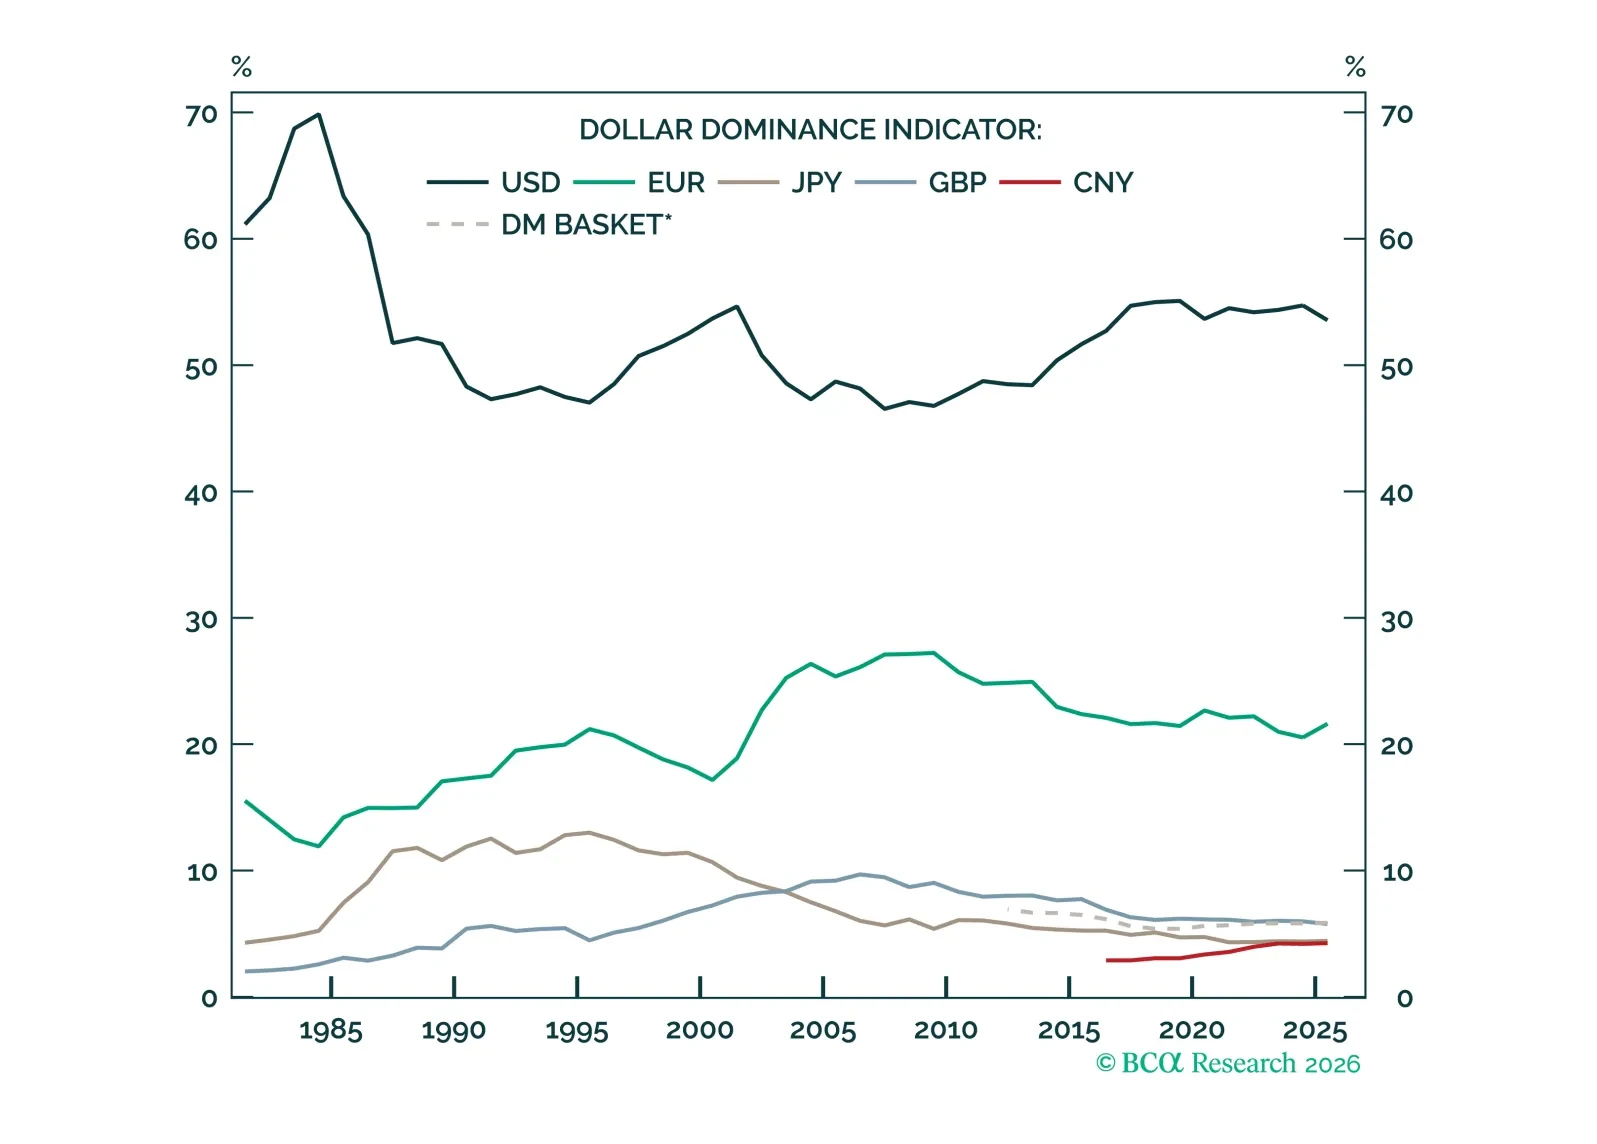
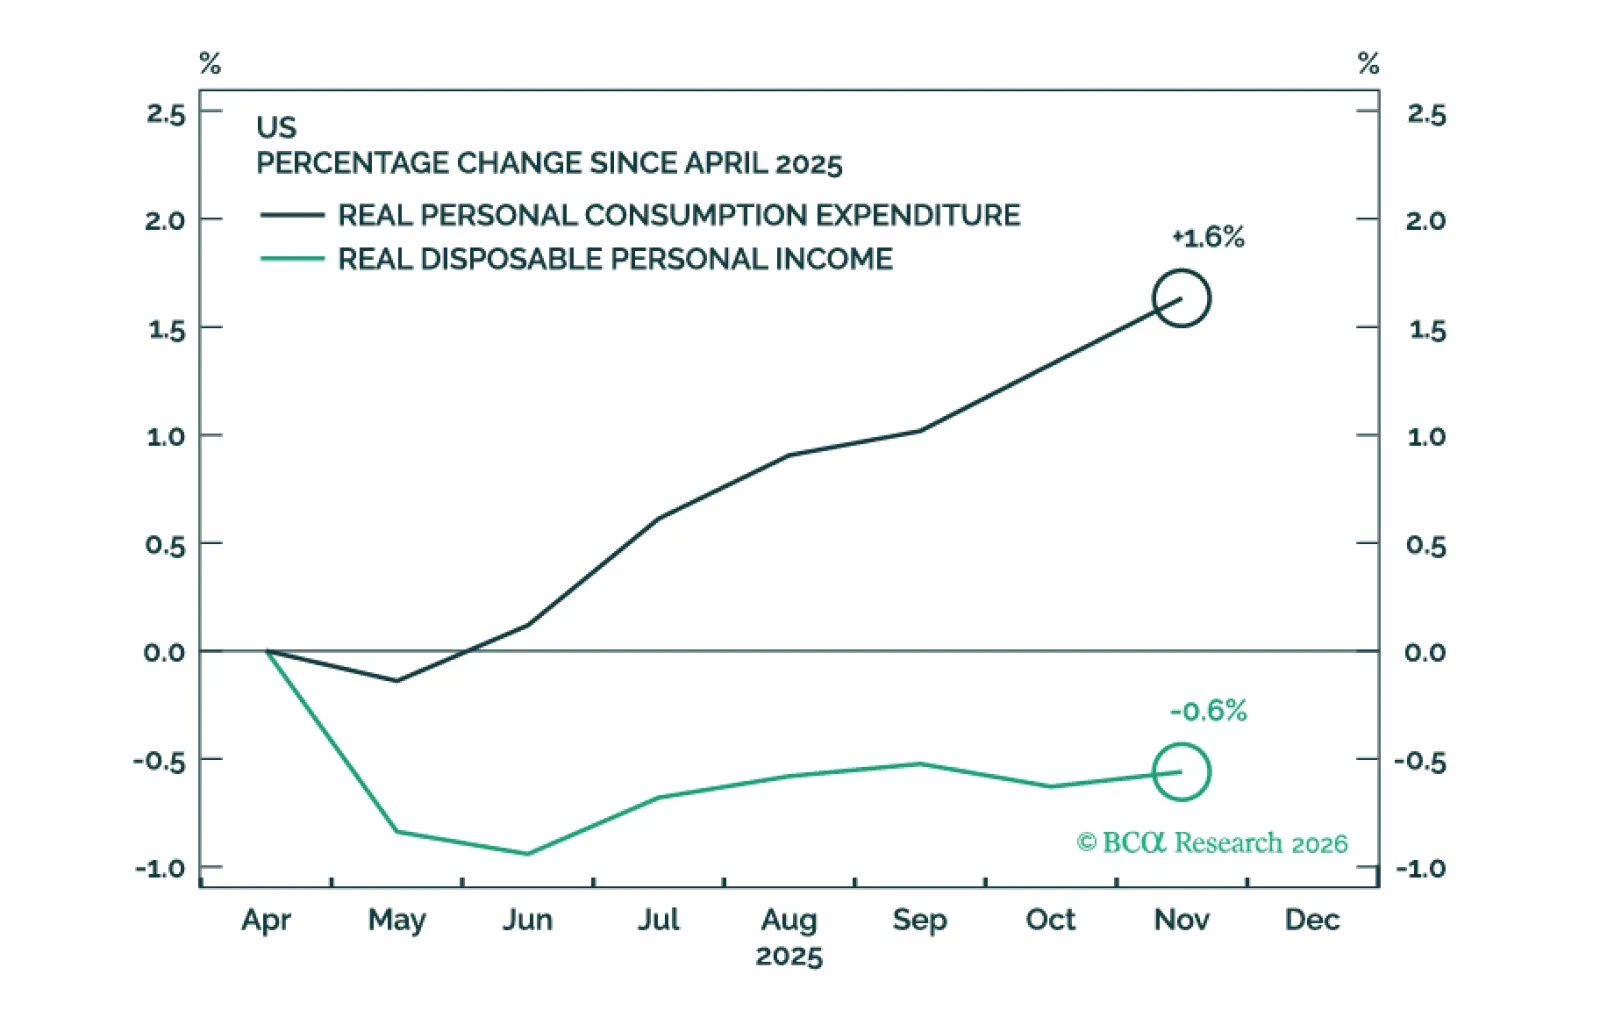
Recent economic data have been reasonably firm. We will cut our 12-month US recession probability to 40% from 50% if the Supreme Court strikes down President Trump’s tariffs. This would take our scenario-weighted year-end 2026 price target for the S&P 500 to 6375 from 6200.
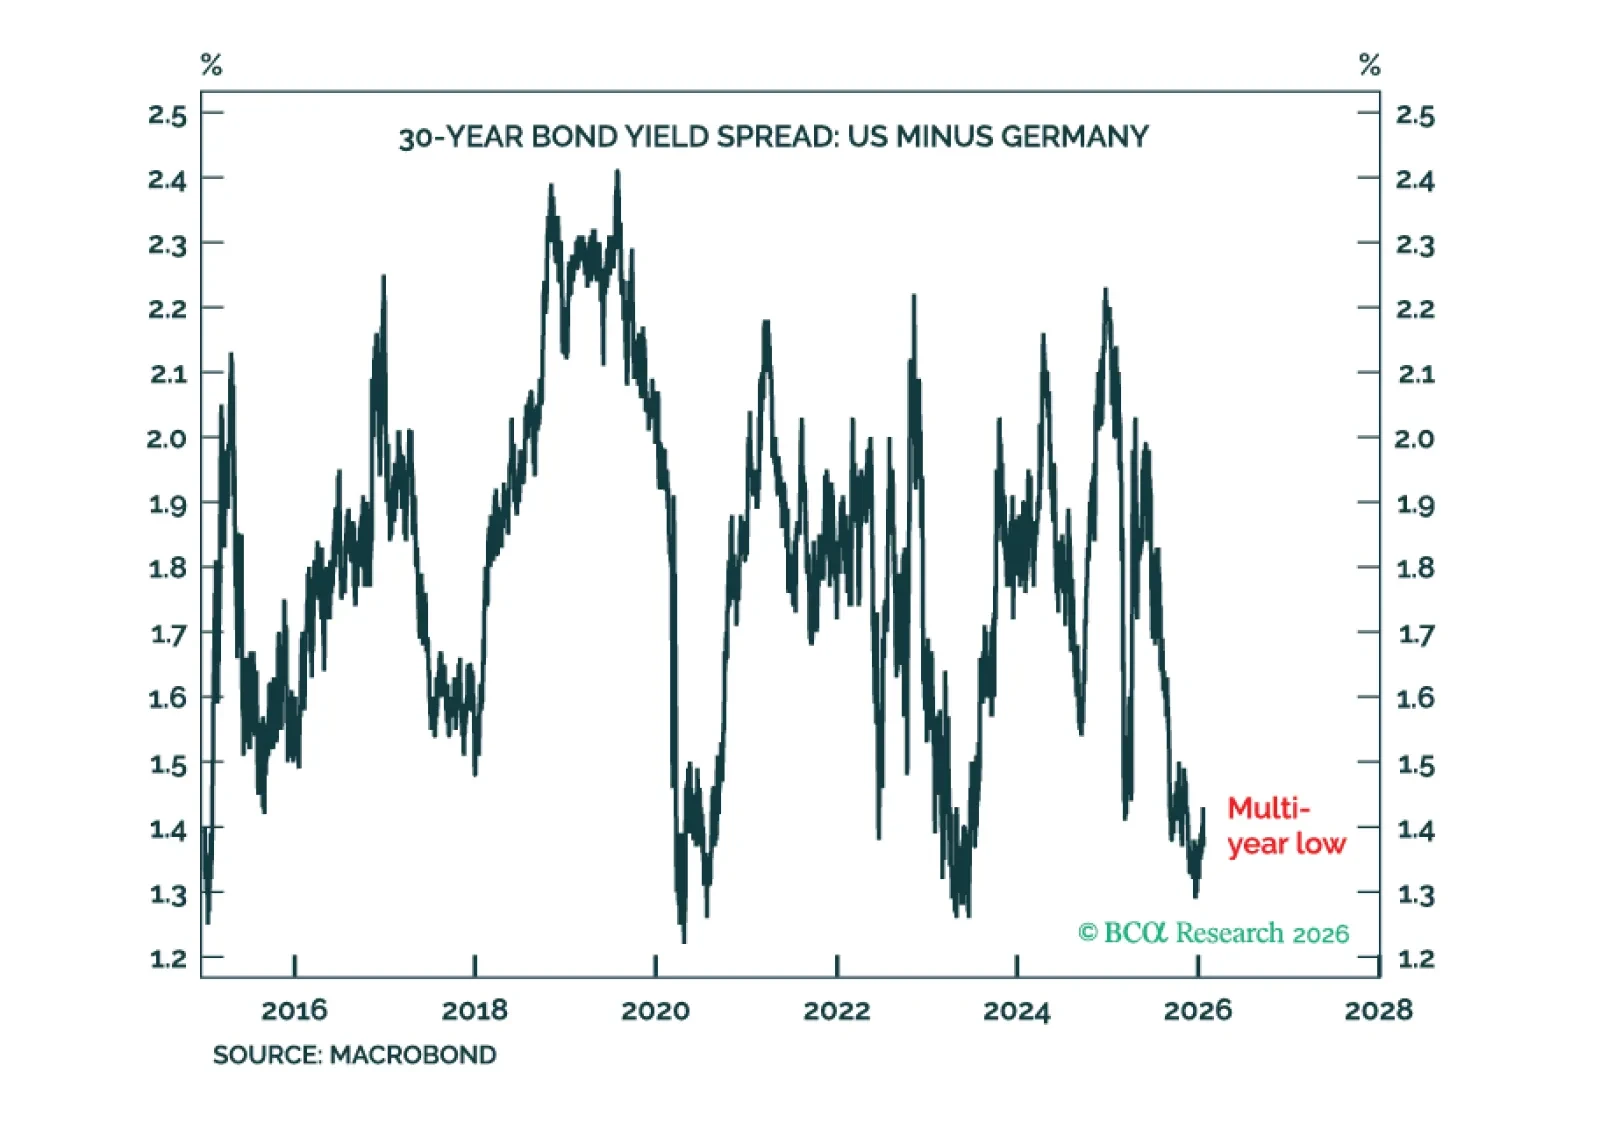
US Treasury yields require a higher premium for both geopolitical risk and inflation risk, but higher bond yields are not necessarily bad for stocks.
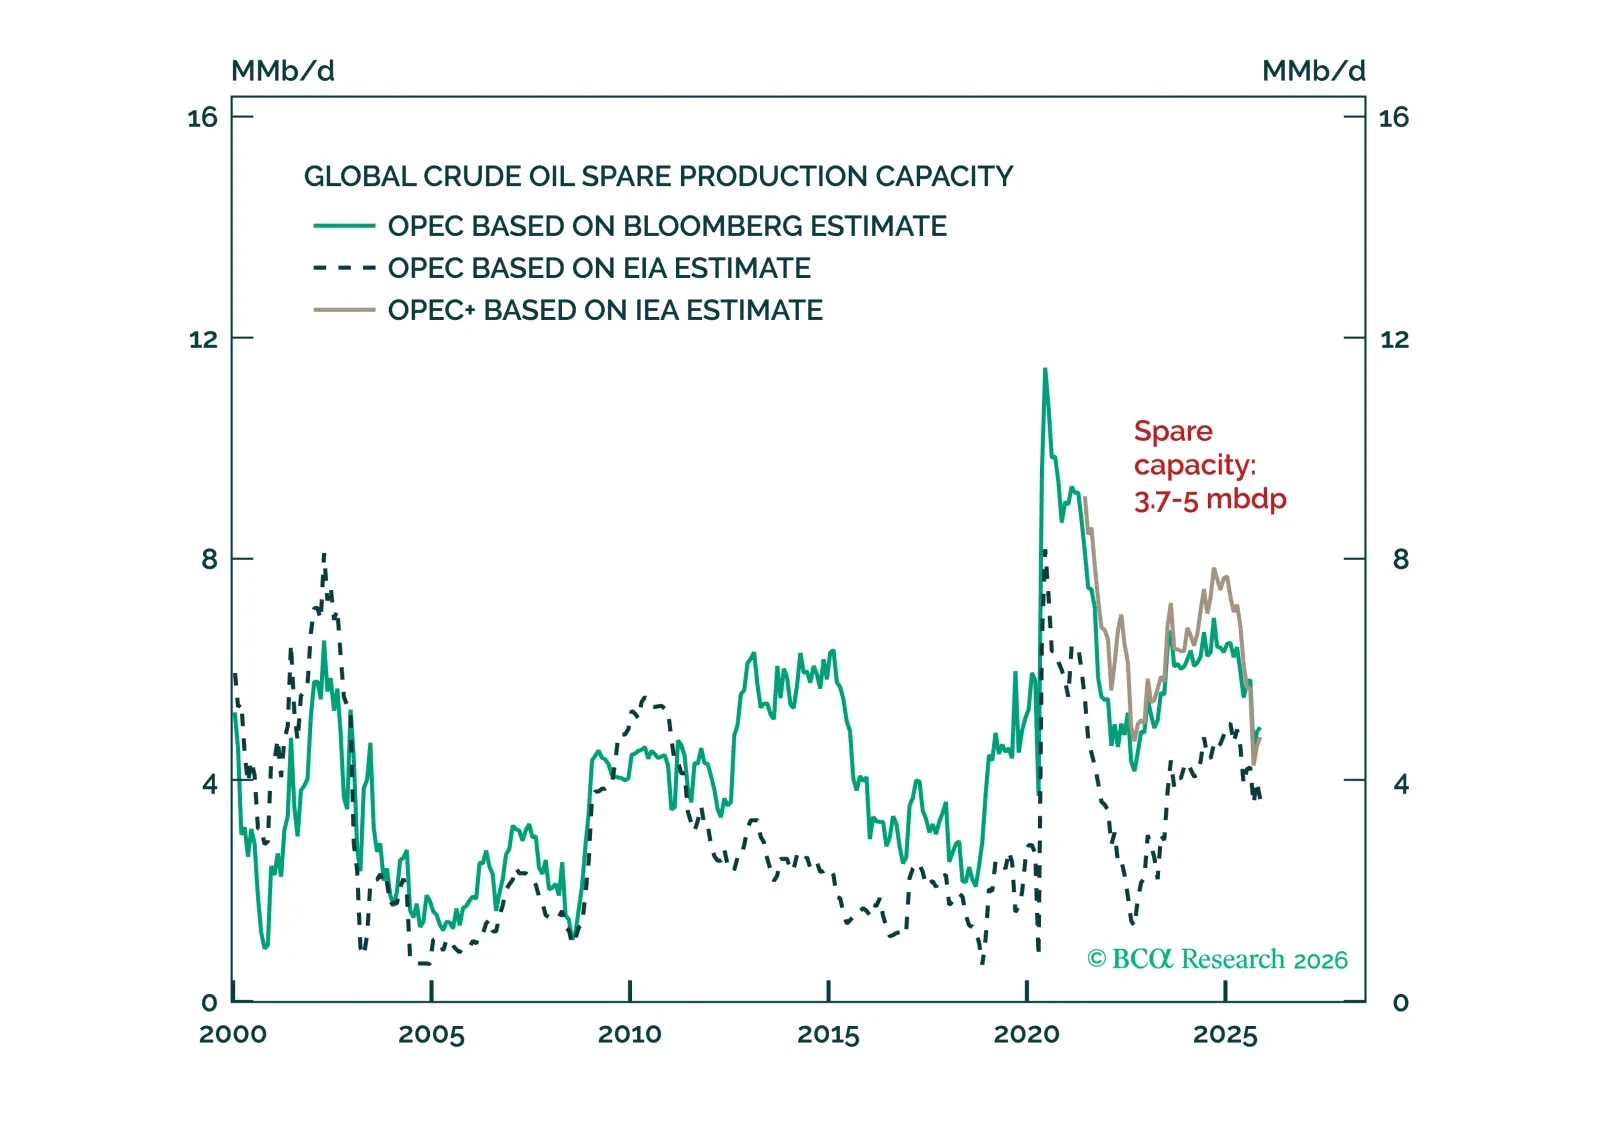
Our top five "Black Swan" risks this year are familiar but all too realistic in the current climate. Investors should stay overweight US equities and EM-ex-China until some hurdles are cleared.
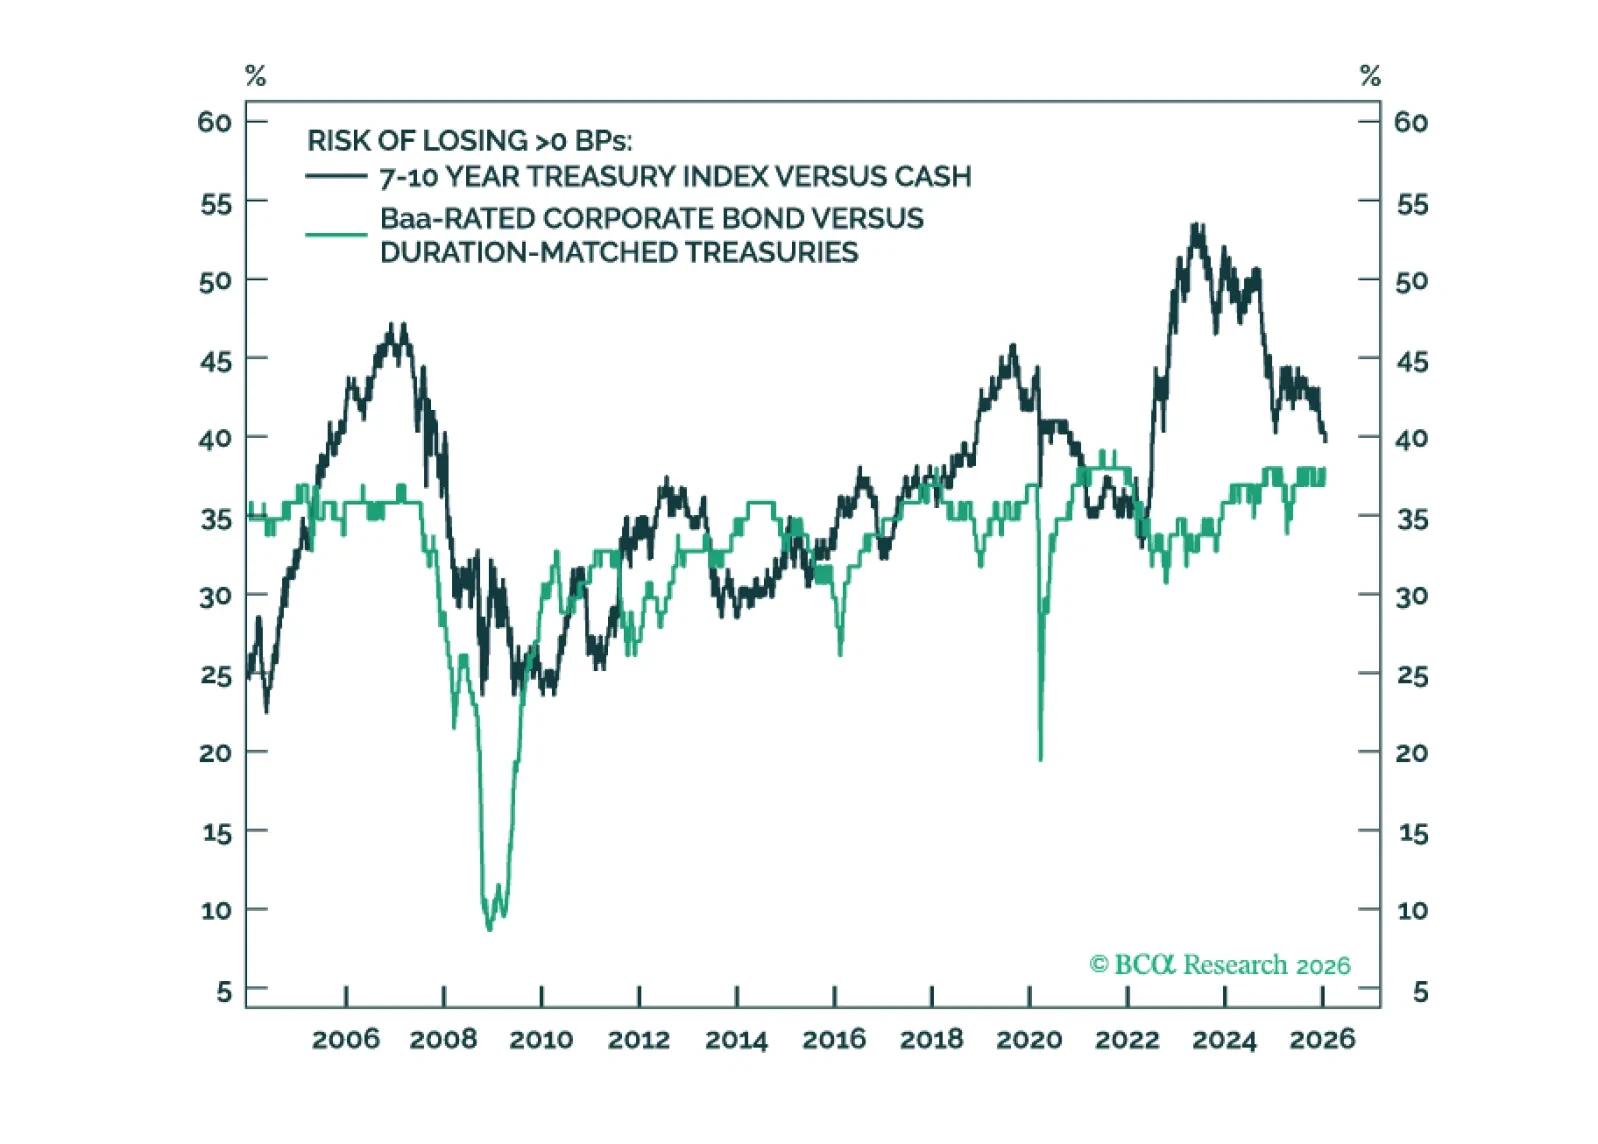
The 10-year Treasury term premium is now competitive with Baa- and Ba-rated credit spreads. Even without term premium compression, duration carry trades could outperform credit carry trades in a low rate vol environment.
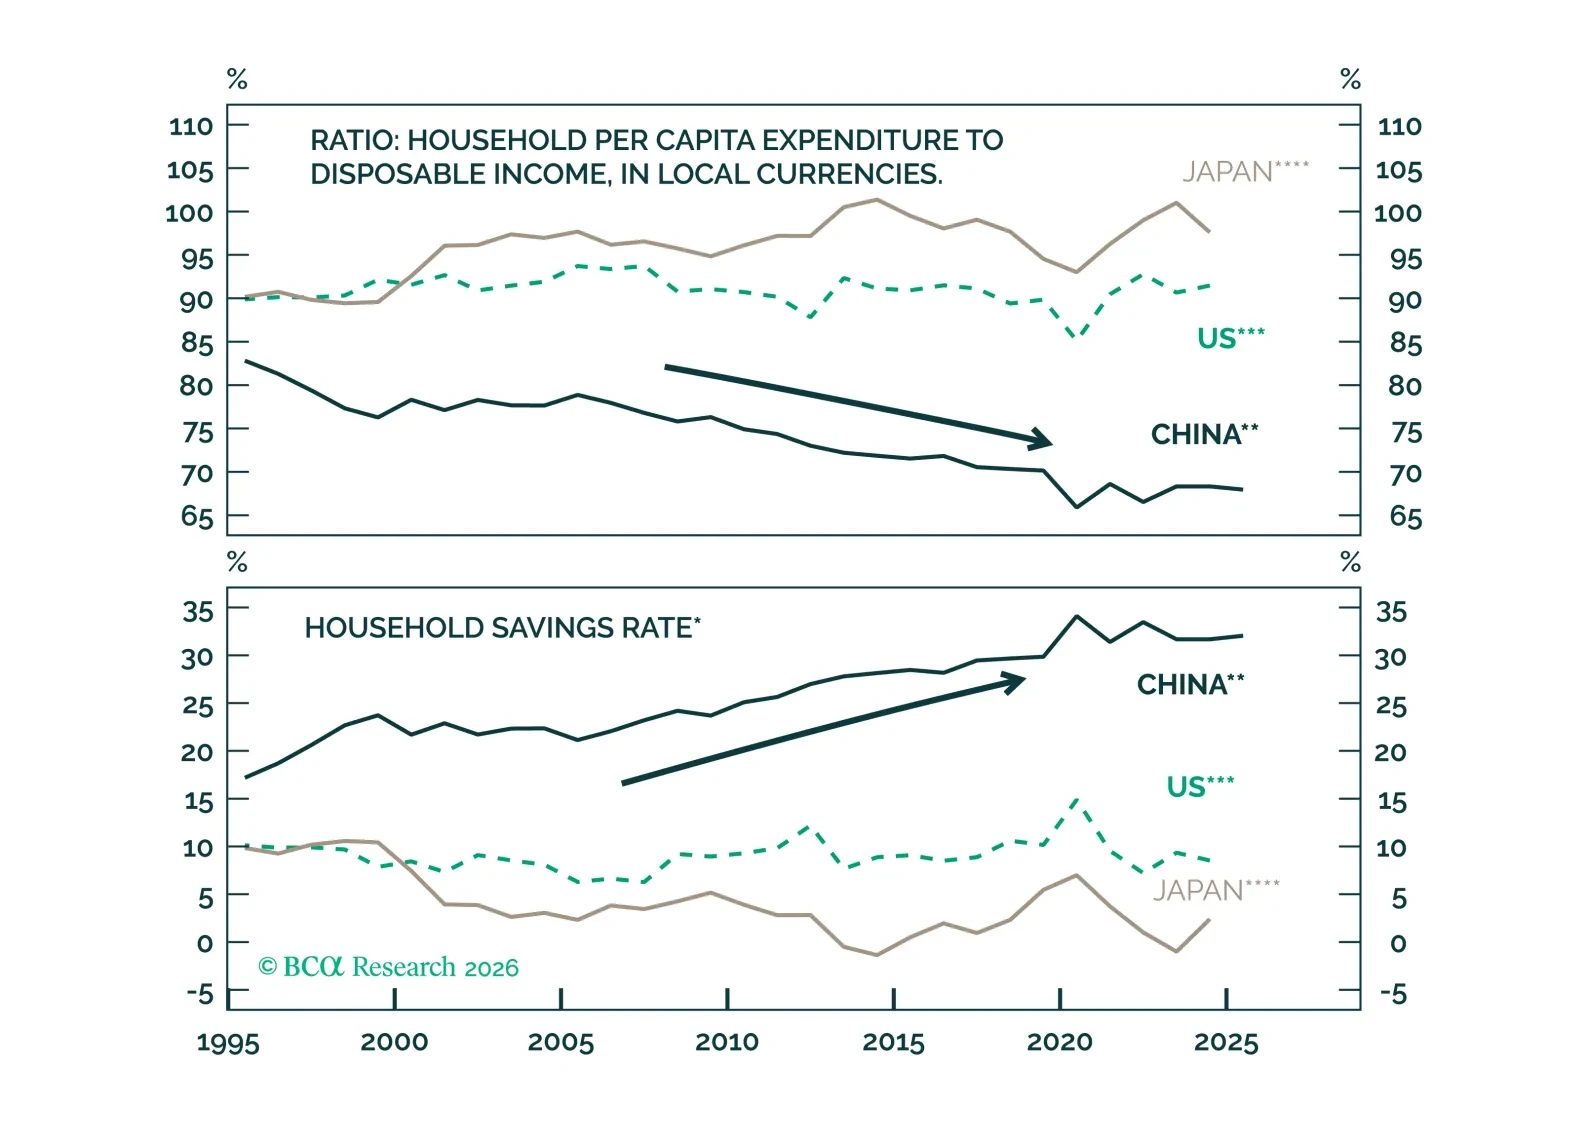
Our clients know that we have been very generous when it comes to analyzing President Trump’s policy choices and negotiating style. In our view, ascribing preferences to the man is a poor analytical framework. President Trump goes into every situation trying to maximize his gains, only adjusting his expectations and preferences as constraints become clear. As such, focus on constraints, not stated preferences. Where does Greenland fit in this paradigm?
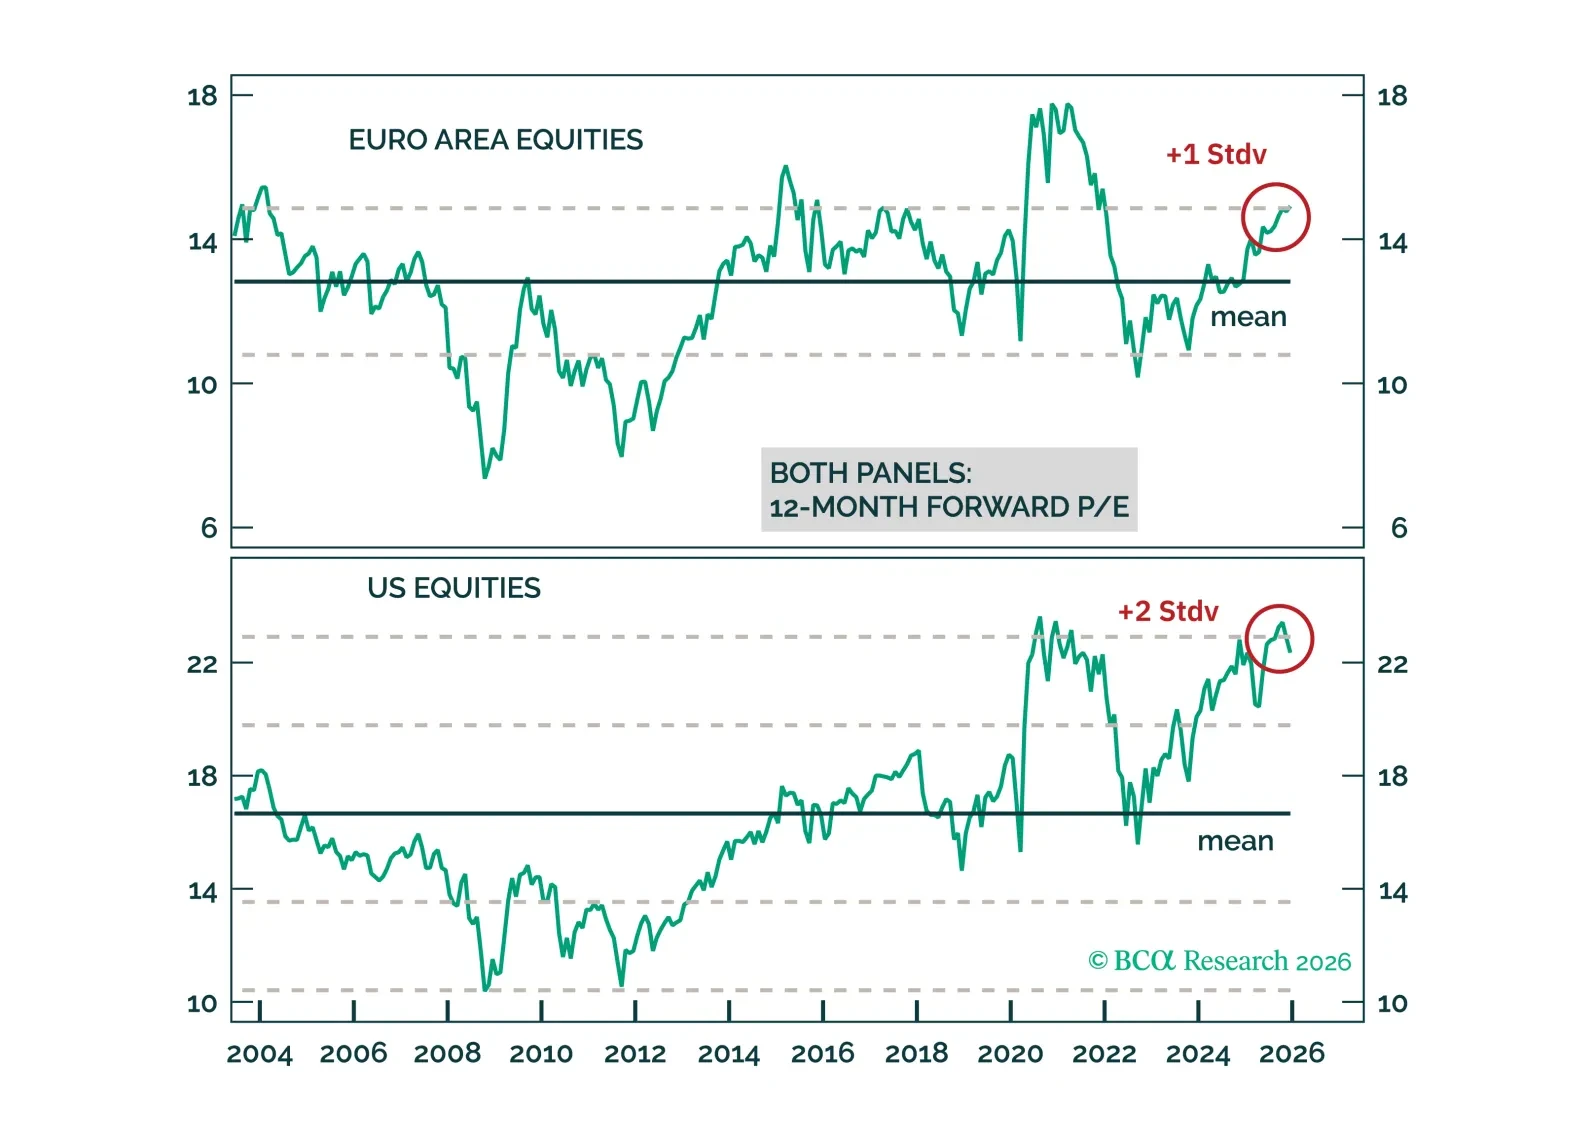
Europe is in a geopolitical sweet spot. Exaggerated fears of Russian military aggression and abandonment by the United States, as well as increased competition from China, create a geopolitical imperative to stimulate, reflate, and reform. Taken together with fading cyclical headwinds, it suggests that European risk assets can continue to outperform US ones on a cyclical investment time horizon. Remain long European stocks, in particular industrials, and EUR/USD.
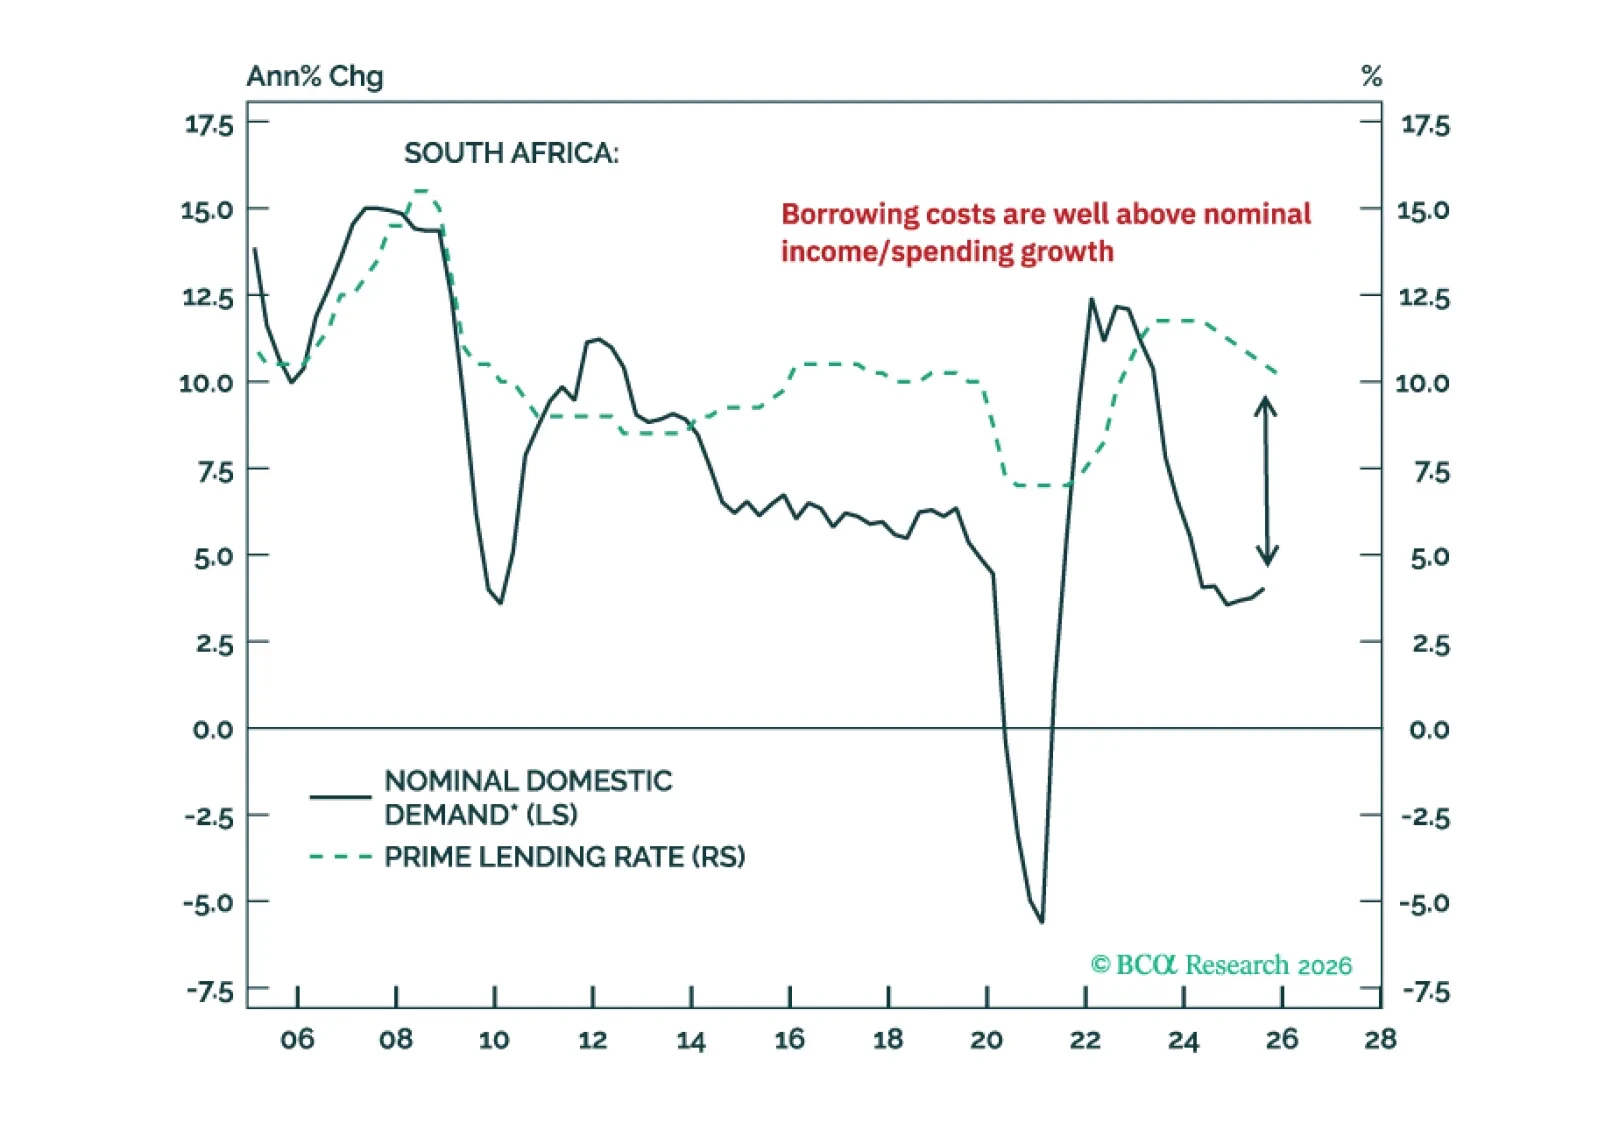
The precious metal bonanza has not resolved the South African economy’s plight. Nor did it improve its public debt sustainability issues. Investors should brace for a reversal in South African stocks, bonds, and the currency.
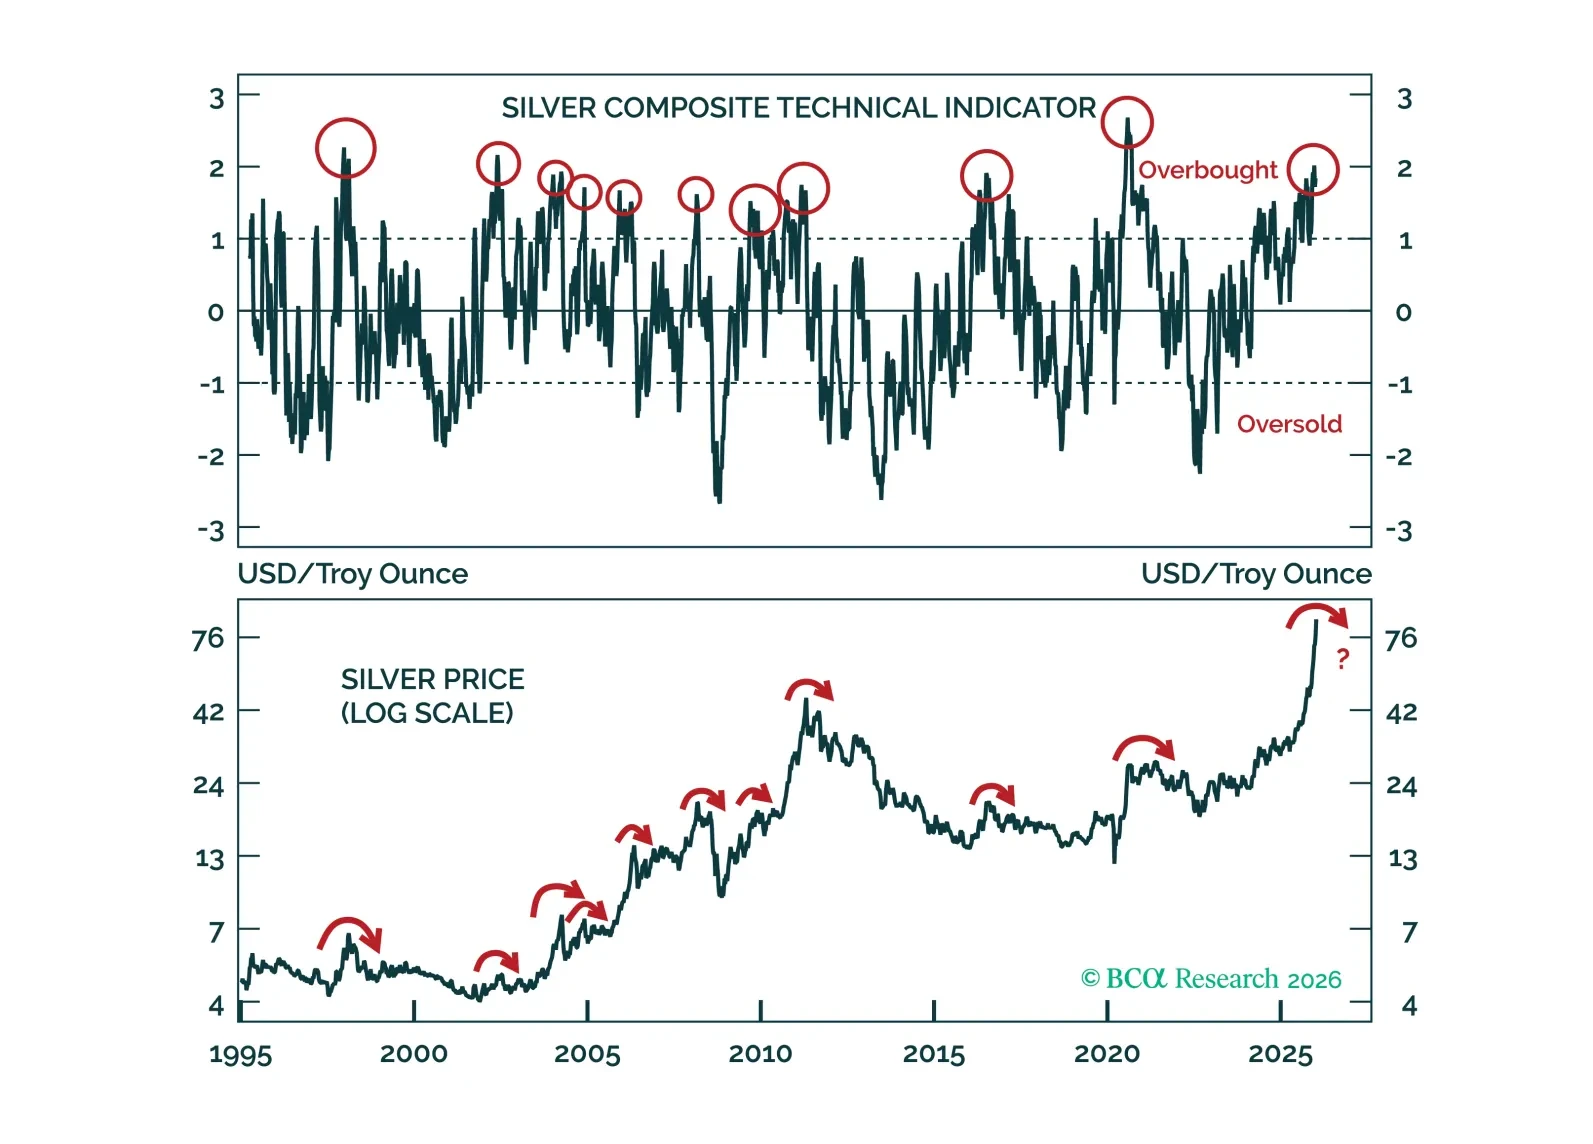
After silver's parabolic surge, we assess the rally's vulnerability by examining its weakest links. We conclude that silver is ripe for a pullback.