Latest from BCA Research
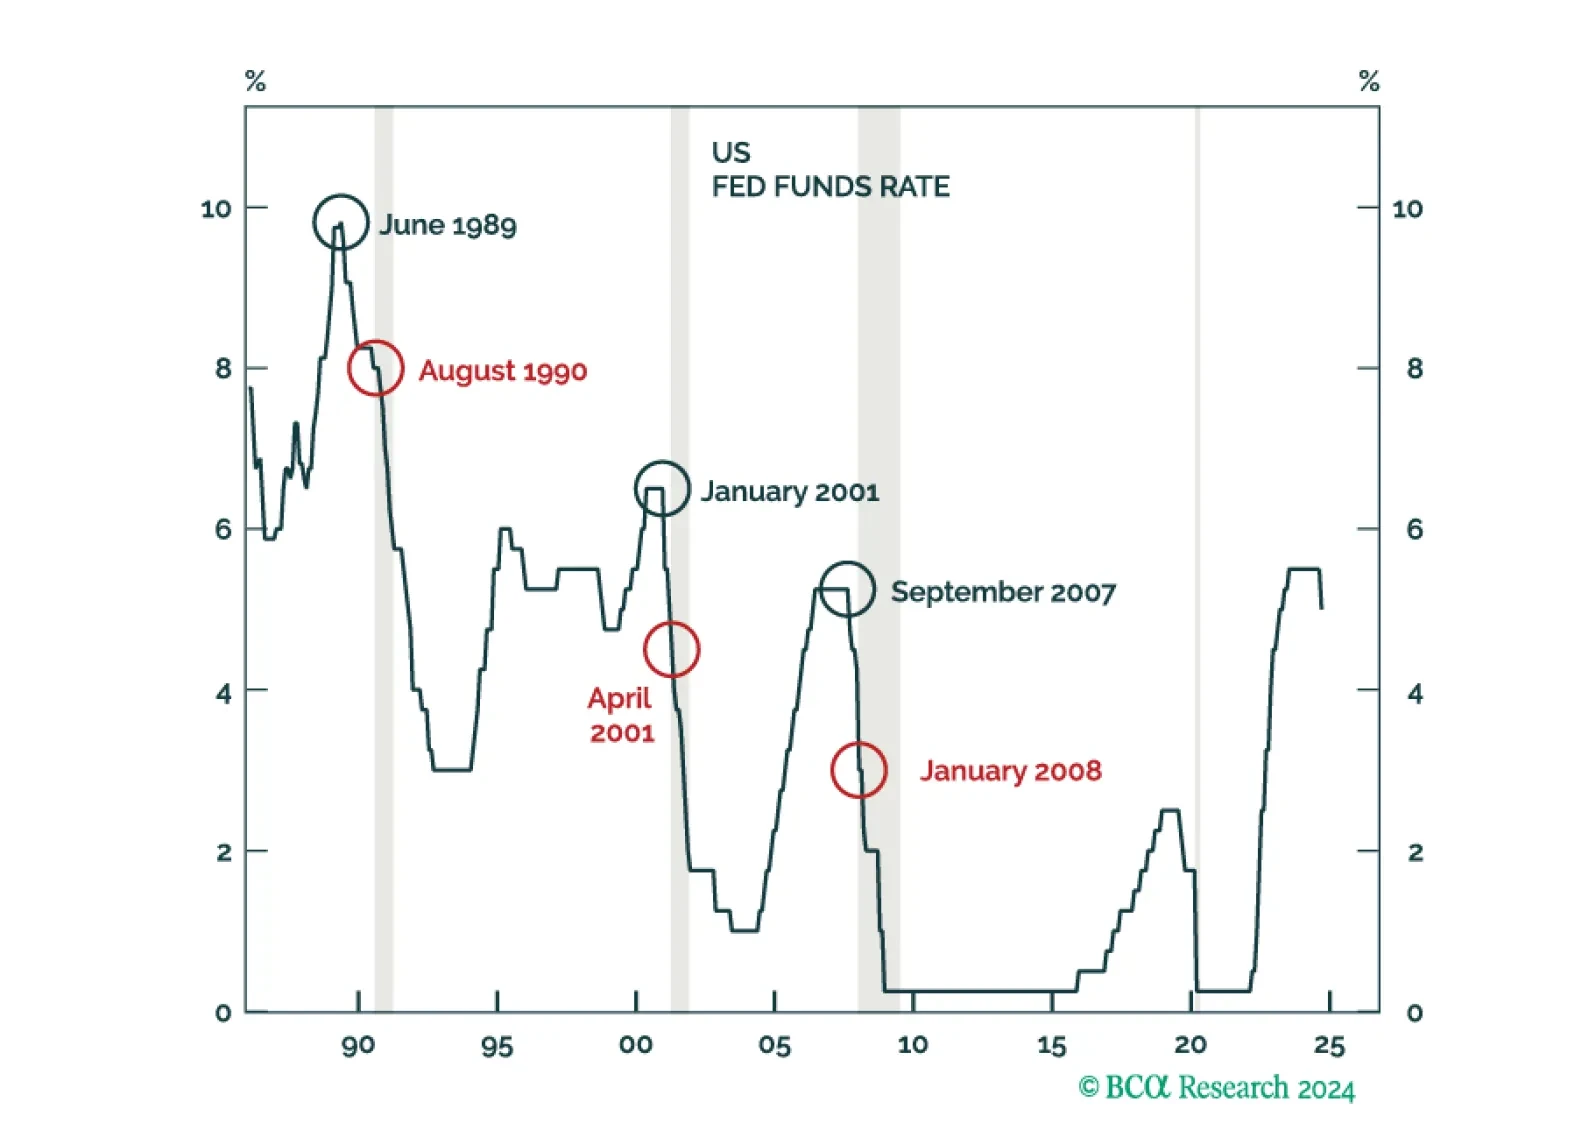
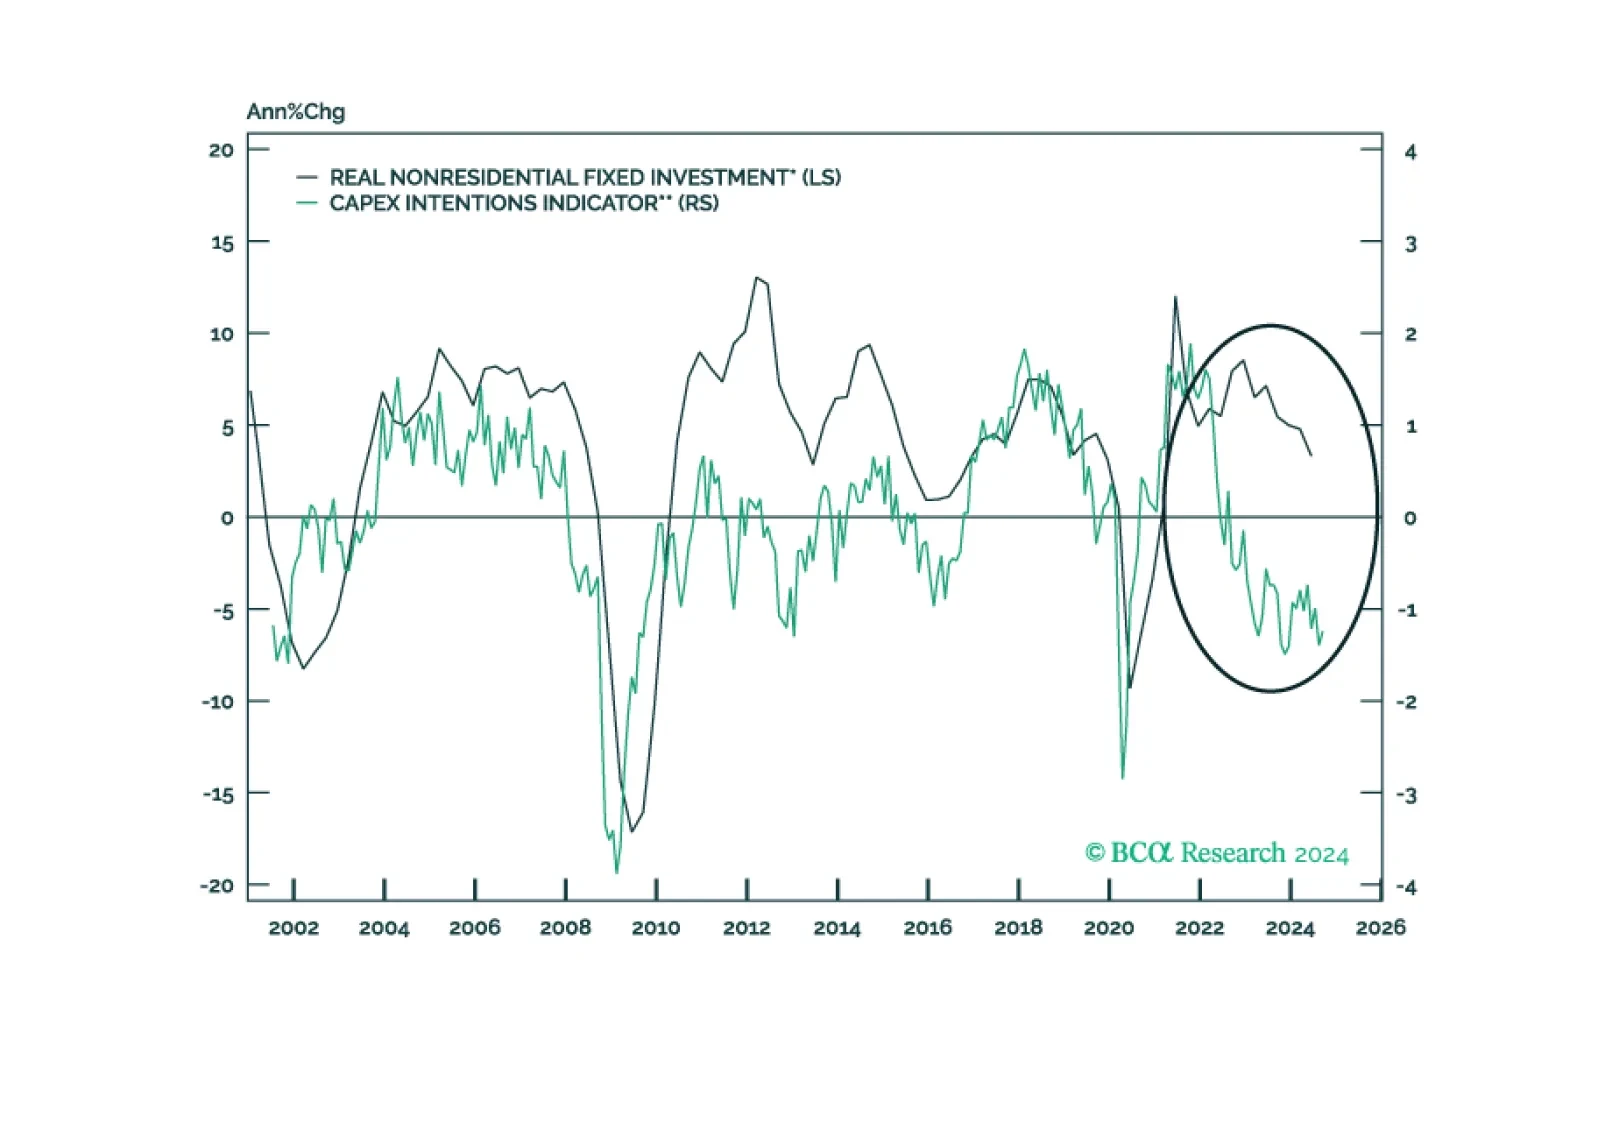
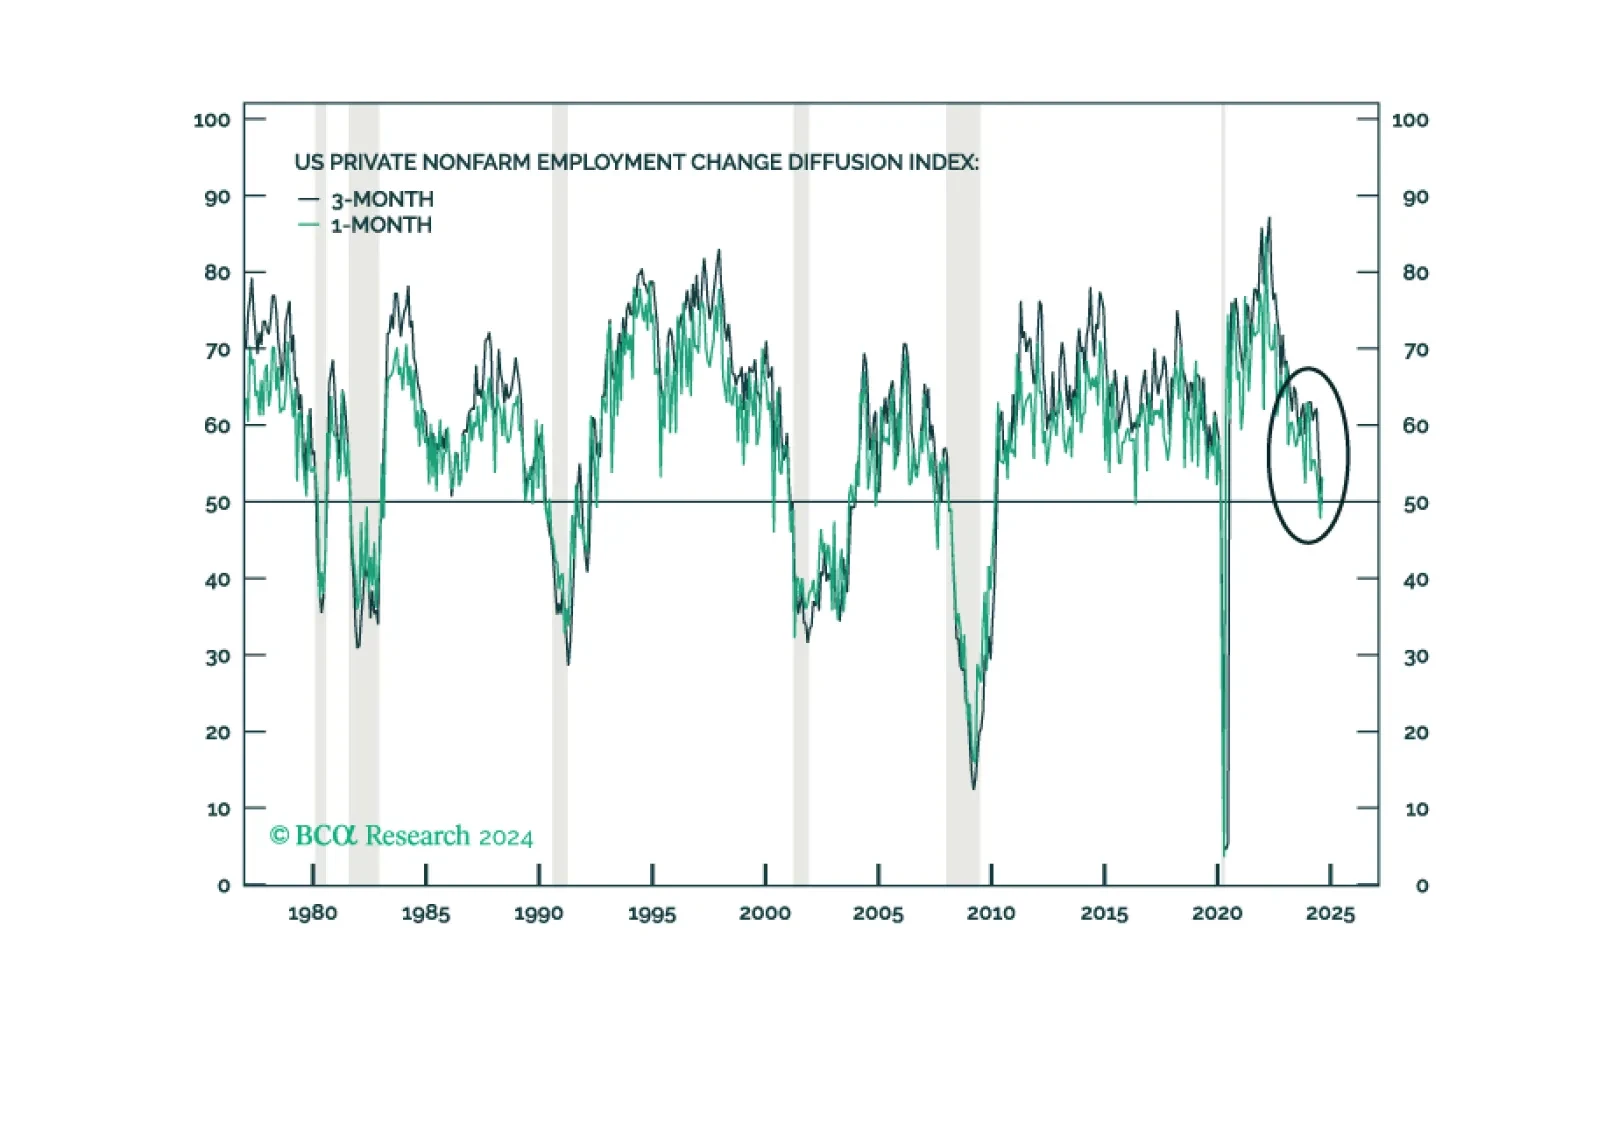
After resisting the consensus narrative in 2022 that a US recession was imminent, and then predicting an immaculate disinflation for 2023, the Global Investment Strategy team has joined the dark side and is now expecting a recession to start in the US within the next six months. Accordingly, we recommend that investors underweight stocks and overweight government bonds.
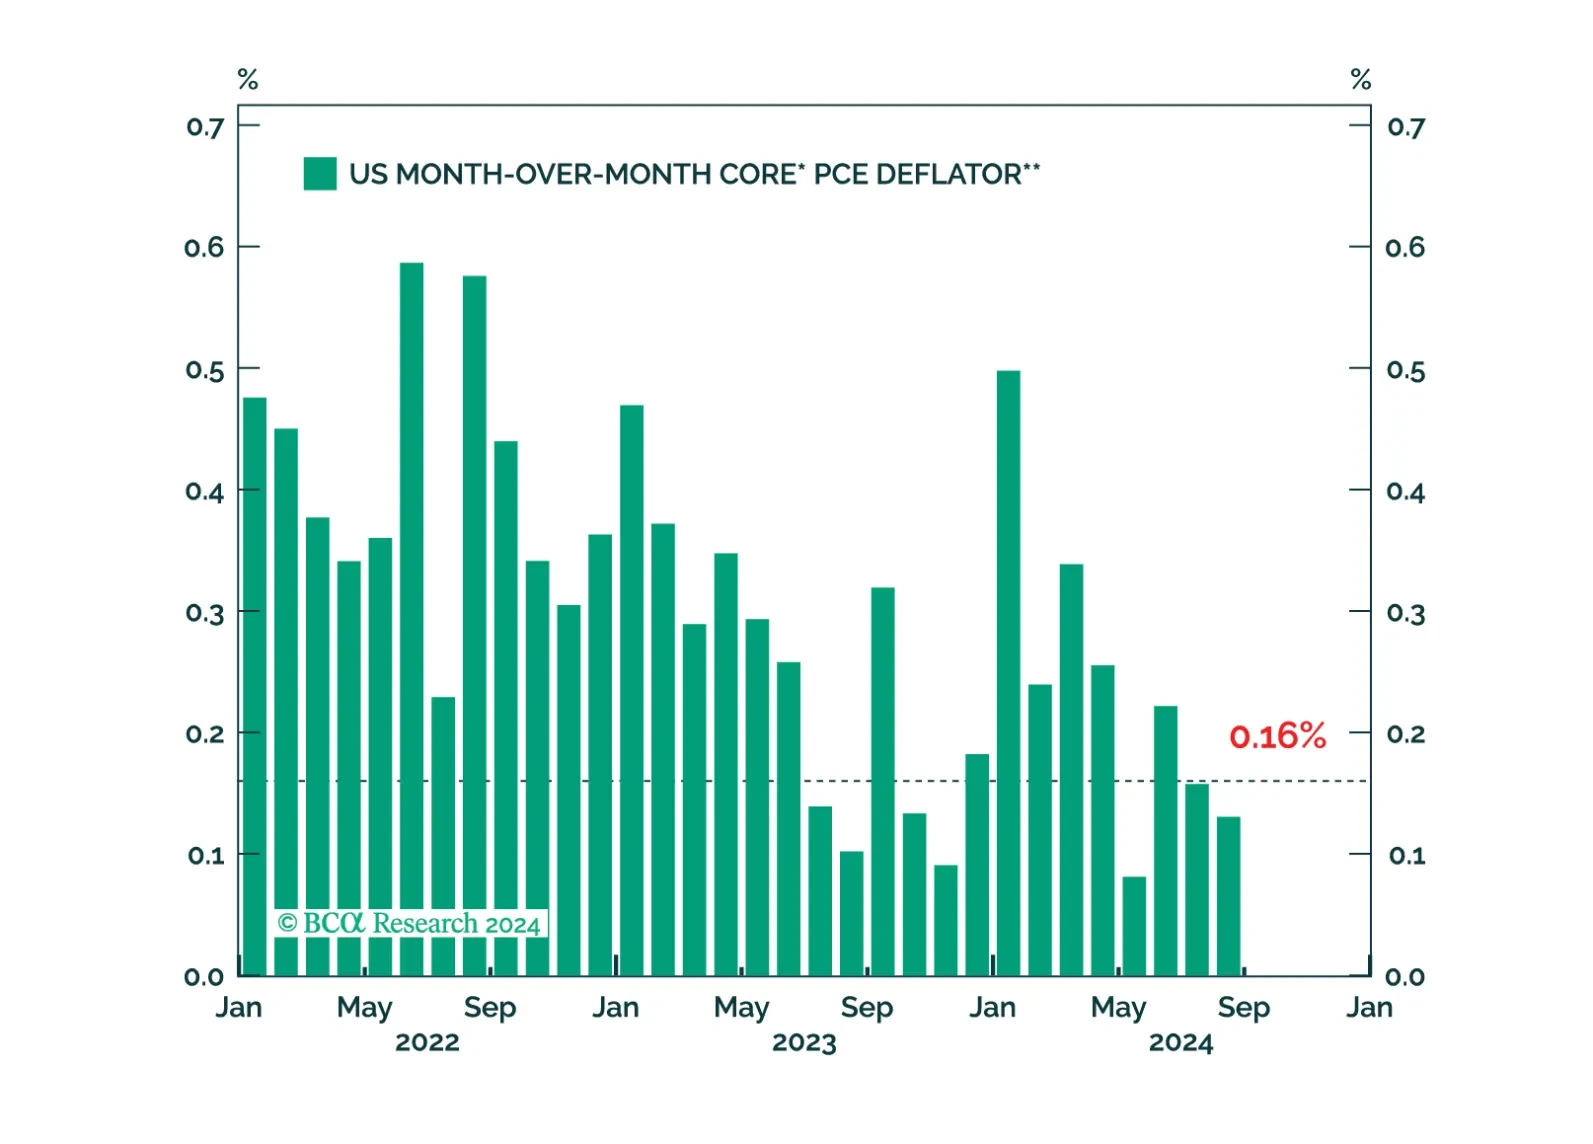
We consider the possibility that lower interest rates could lead to an increase in household borrowing, prolonging the economic recovery.
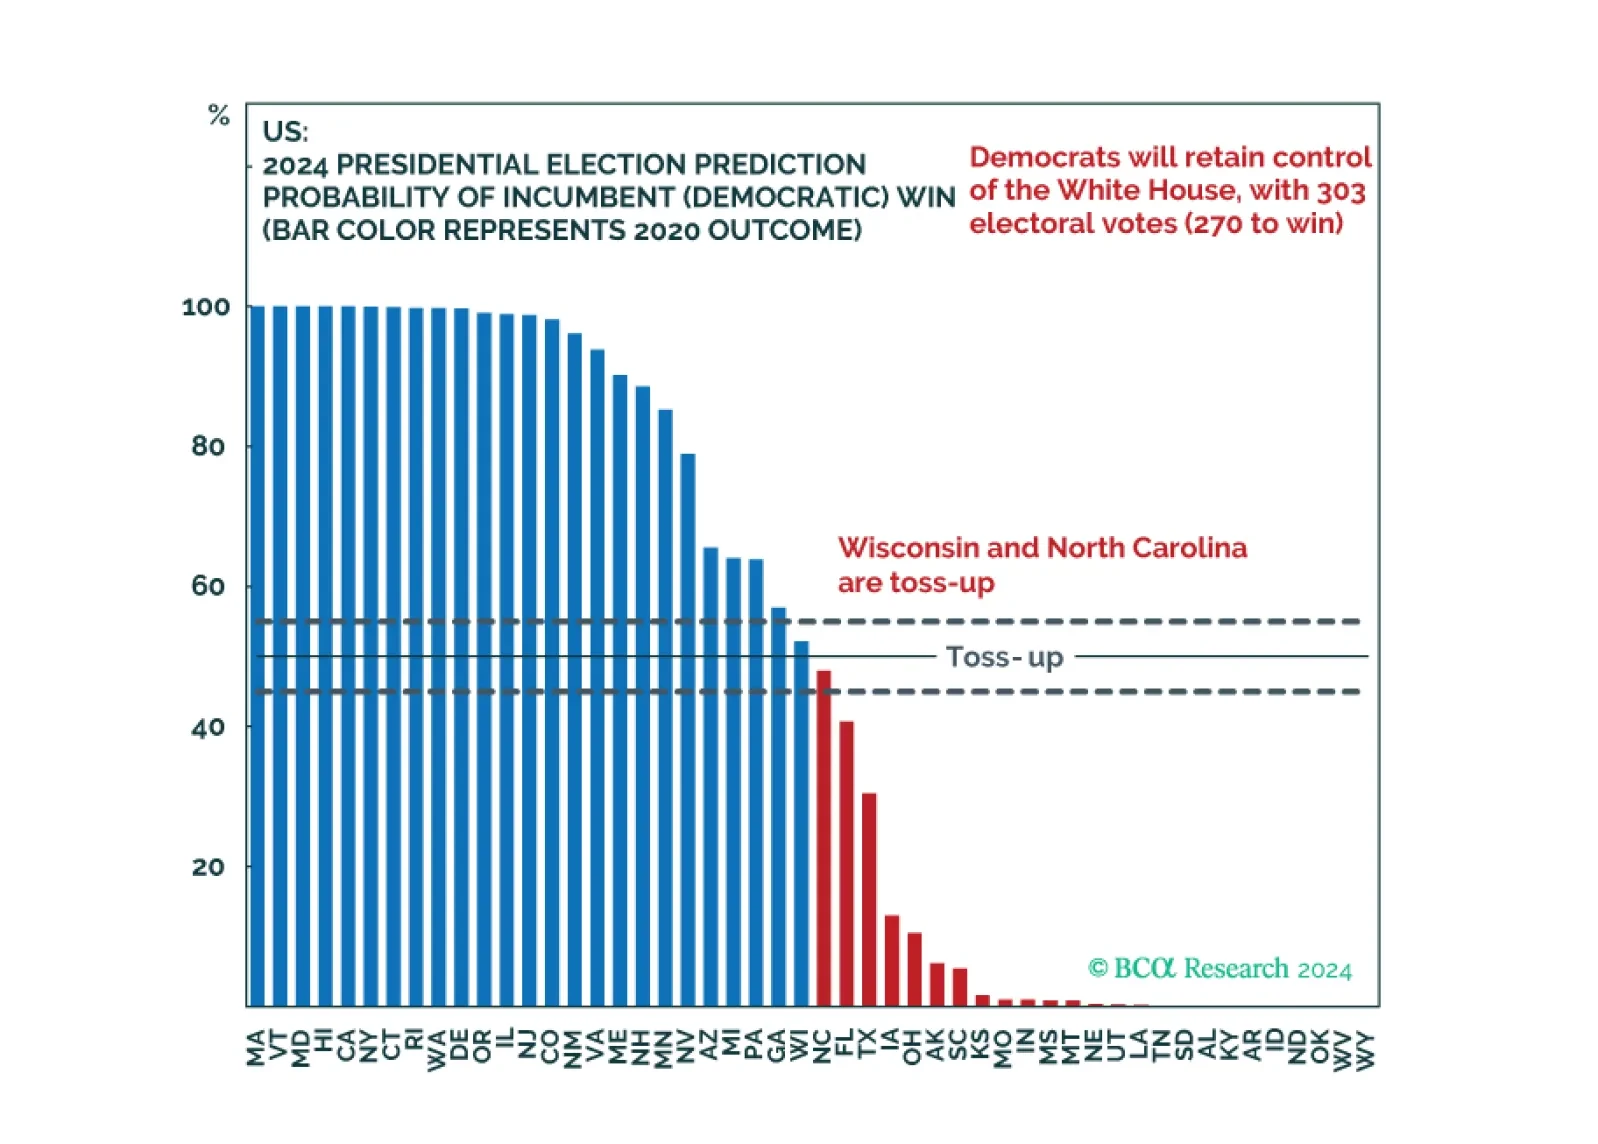
Our quant model shows Democrats winning the election at a 56% probability, with 303 electoral college votes. But swing state economies are slowing and Democrats’ odds in Michigan fell. Trump can win with Georgia, Michigan, plus one other state. Neither the Fed nor China’s stimulus should reduce one’s odds of a Republican upset.
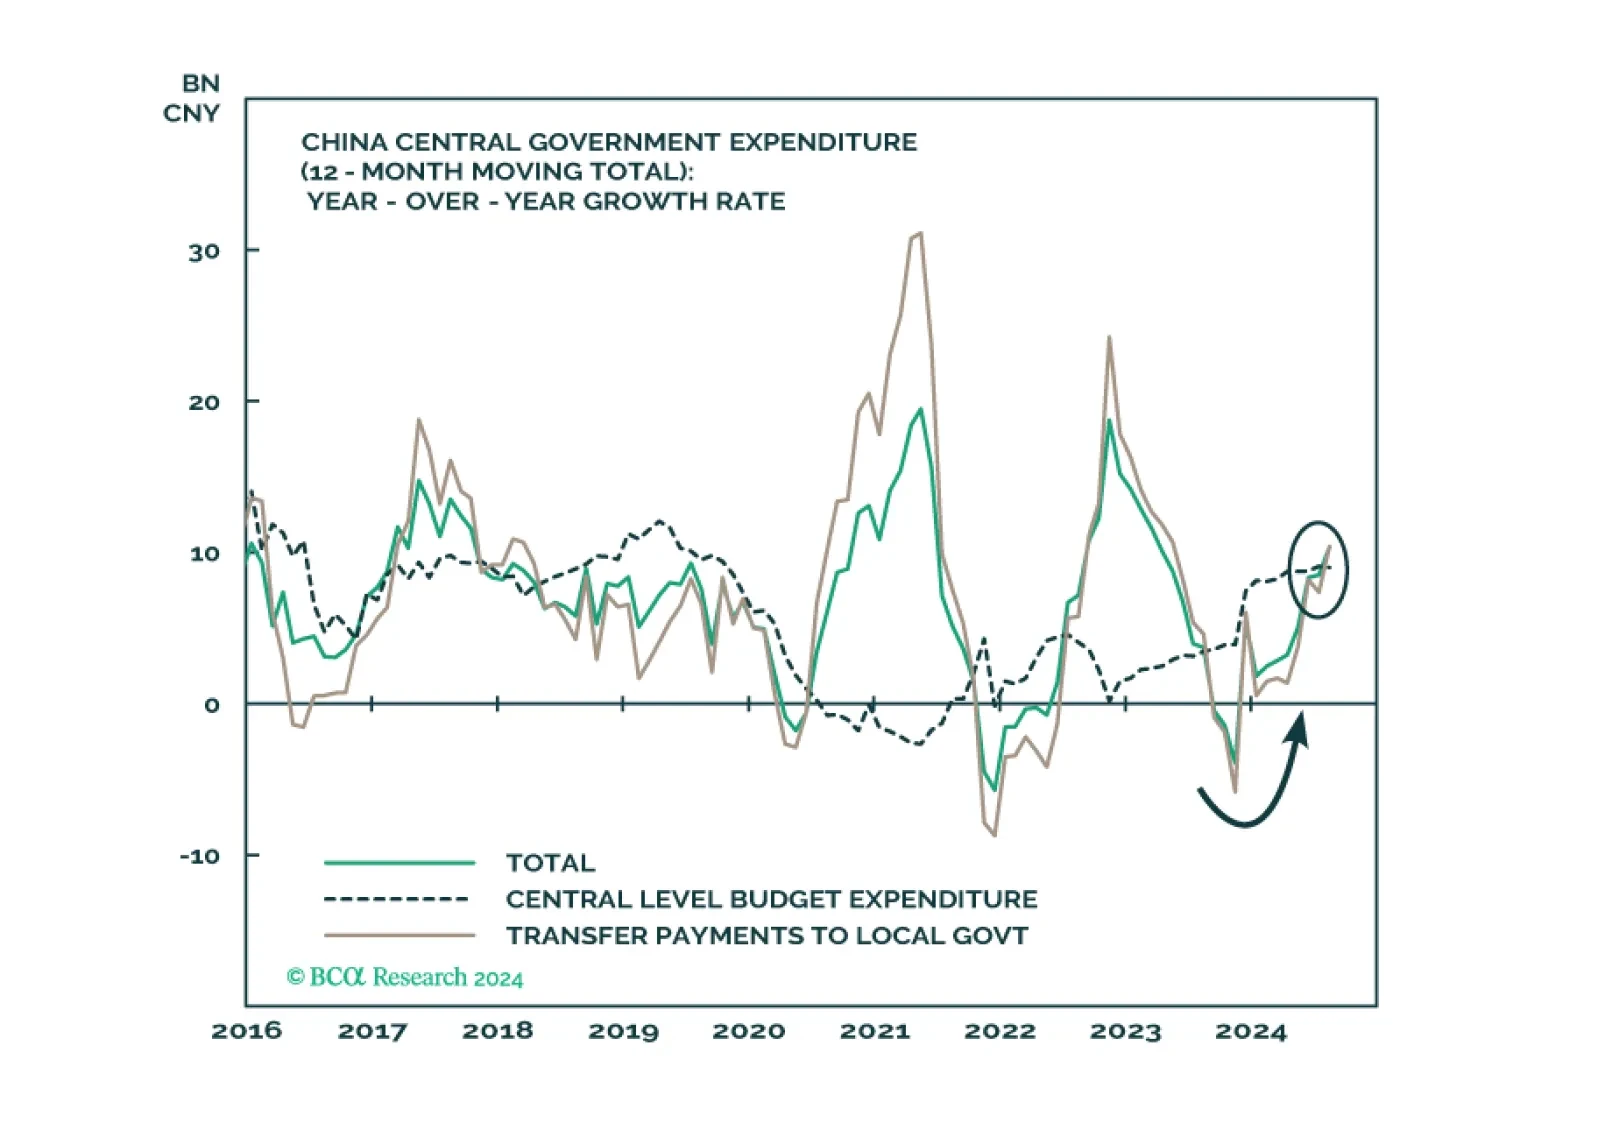
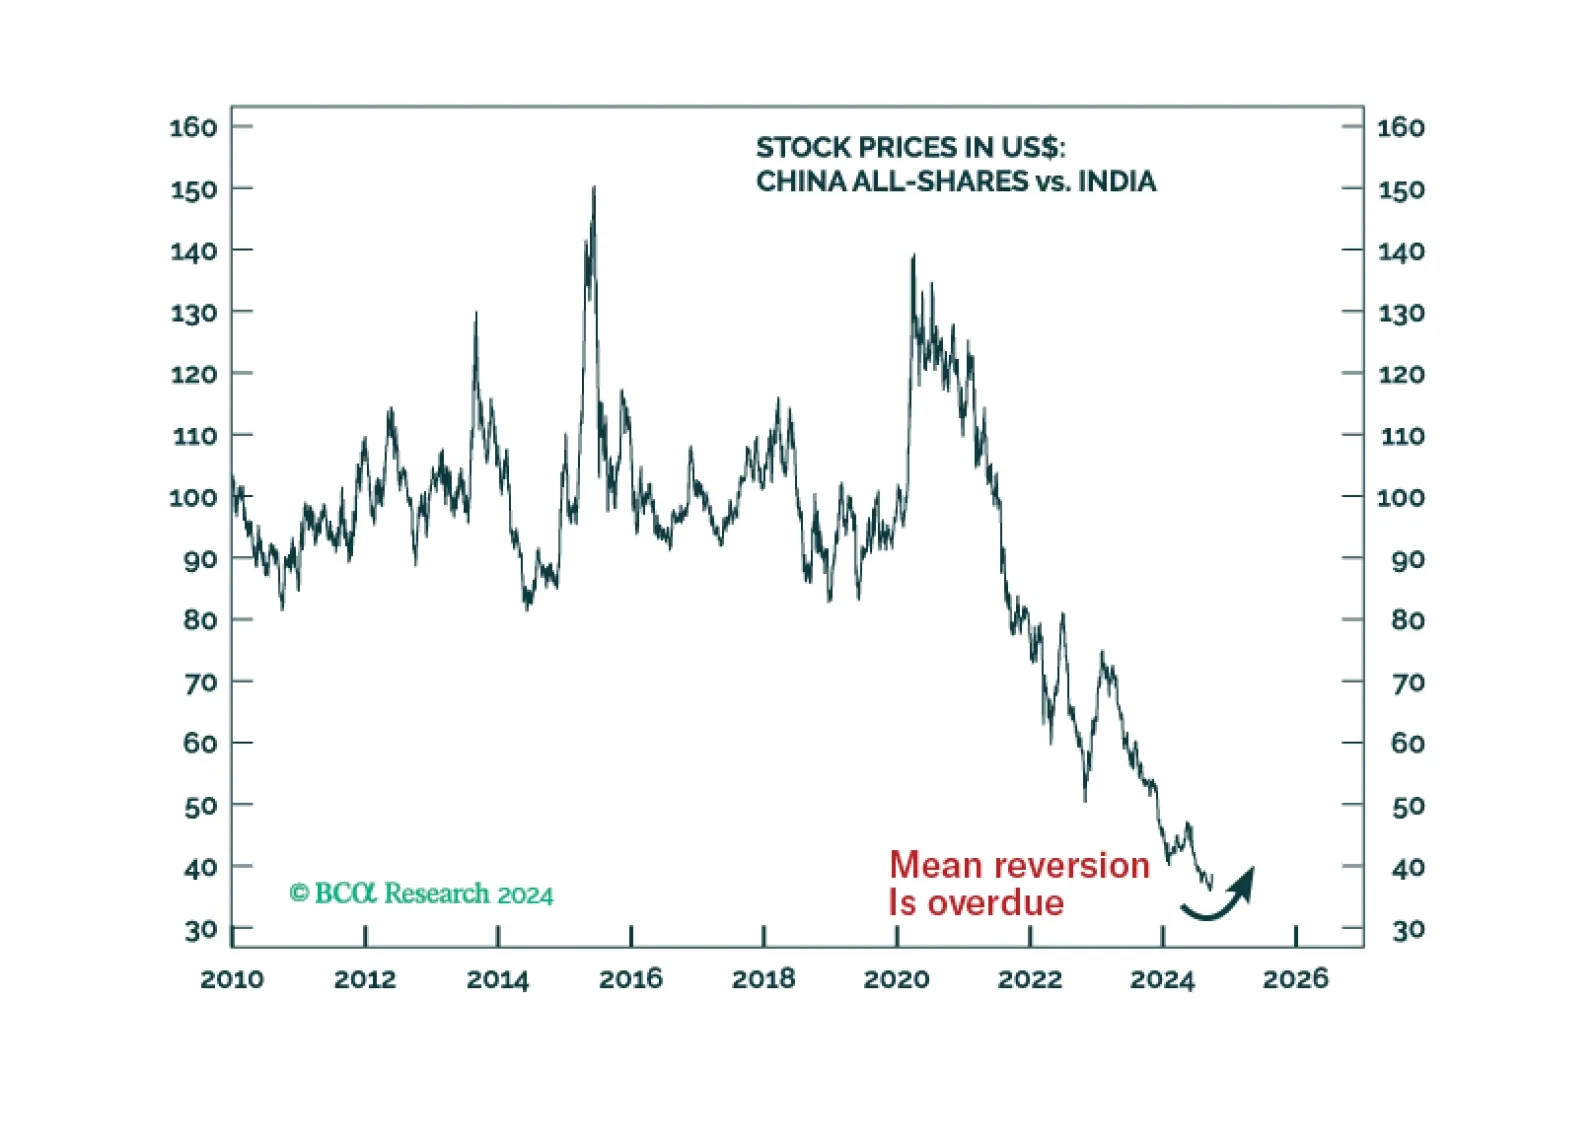
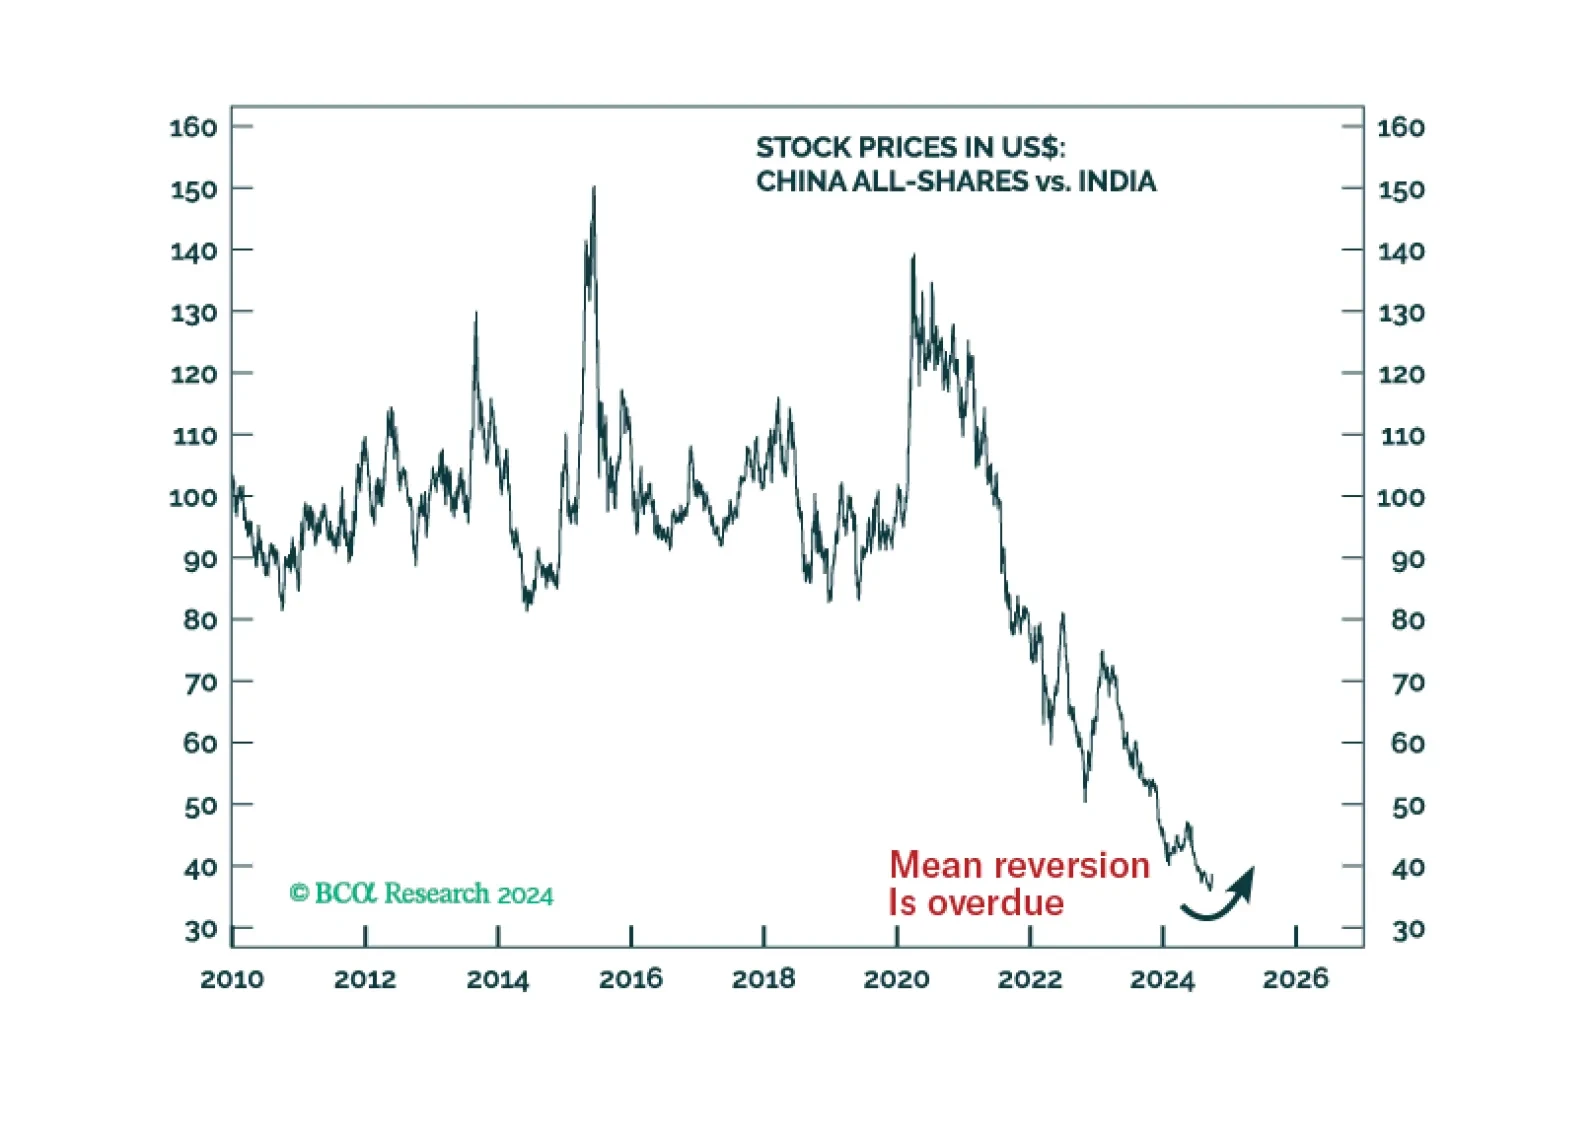
Markets are rallying on Fed rate cuts and China stimulus but there will also be October surprises ahead of the US election, which Trump could still win. Russia’s conflict with the West is escalating and the Middle East is destabilizing further. Investors should favor US bonds but they should add some risk in emerging markets in response to China’s policy turn.
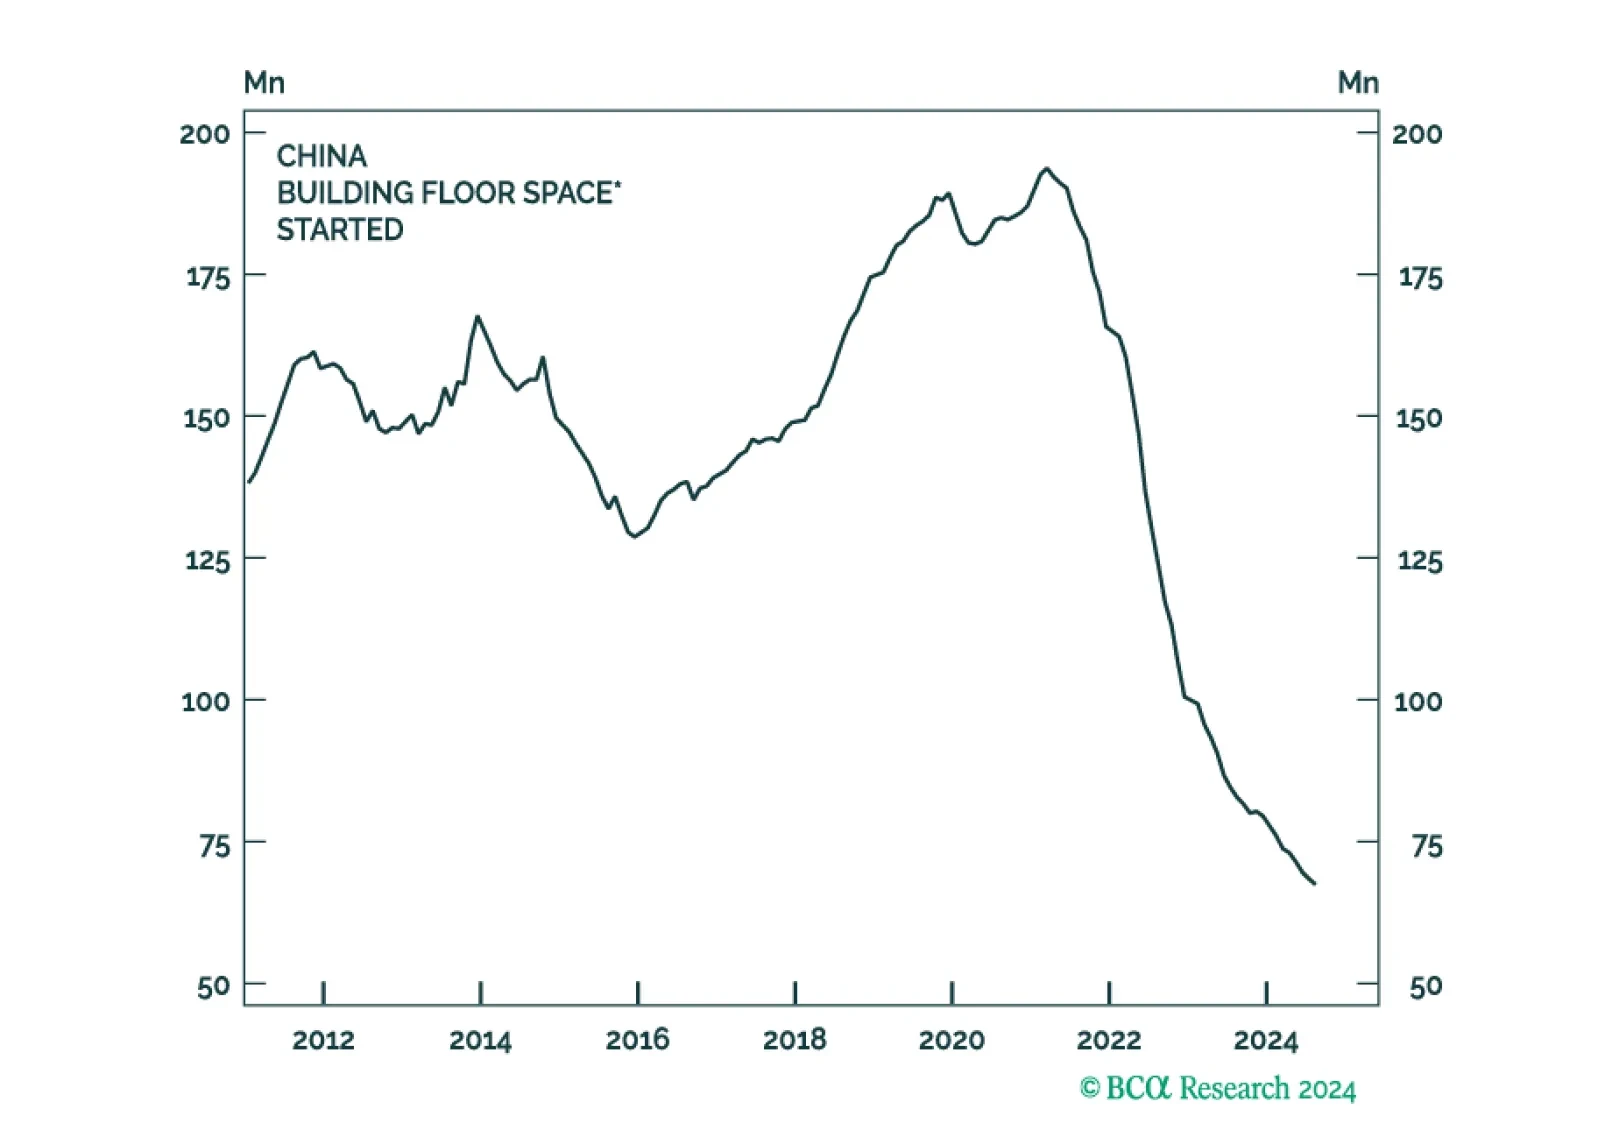
The Chinese government had no choice but to act this week. Housing starts are down 65% from their peak.
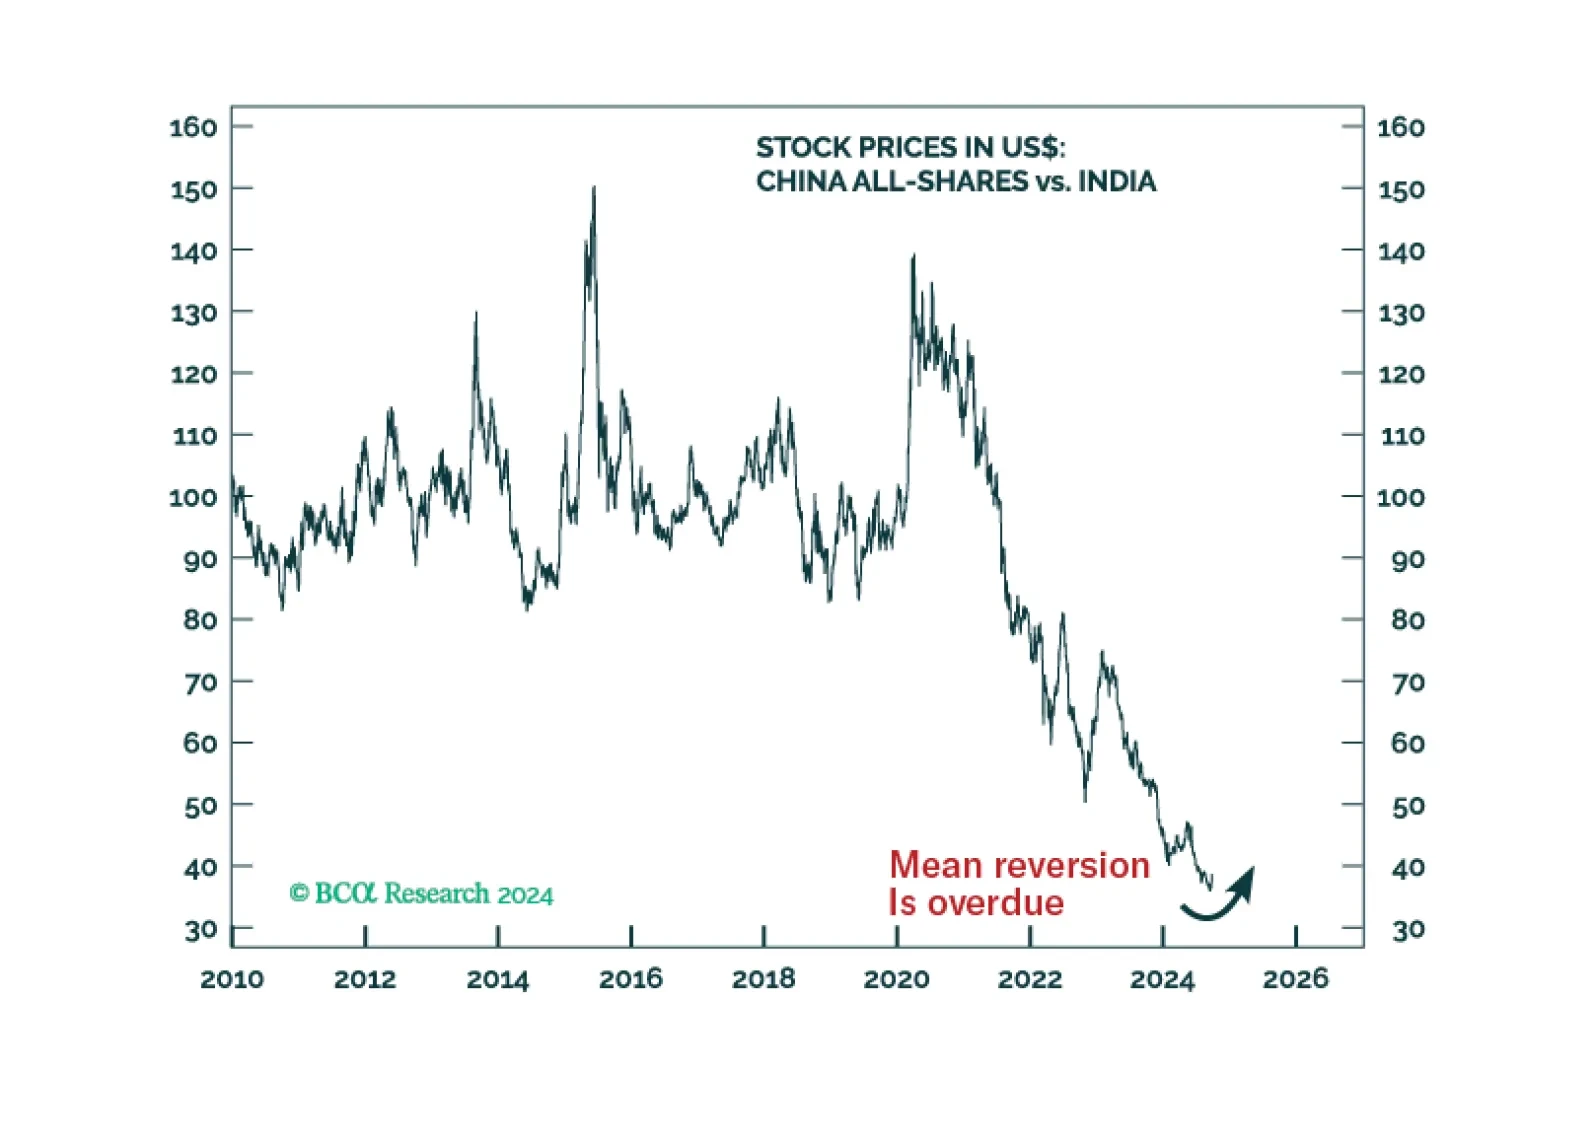
The adrenaline from the recent policy stimulus might be sufficient to produce a window of outperformance for Chinese equities and China-plays in financial markets. However, this adrenaline will not extend to China's real economy. Net-net, we are upgrading the allocation to EM in a global equity portfolio from underweight to neutral.