 Equities
Macro, fundamental, and quantitative analysis translated into actionable equity views across sectors, factors, themes, and baskets.
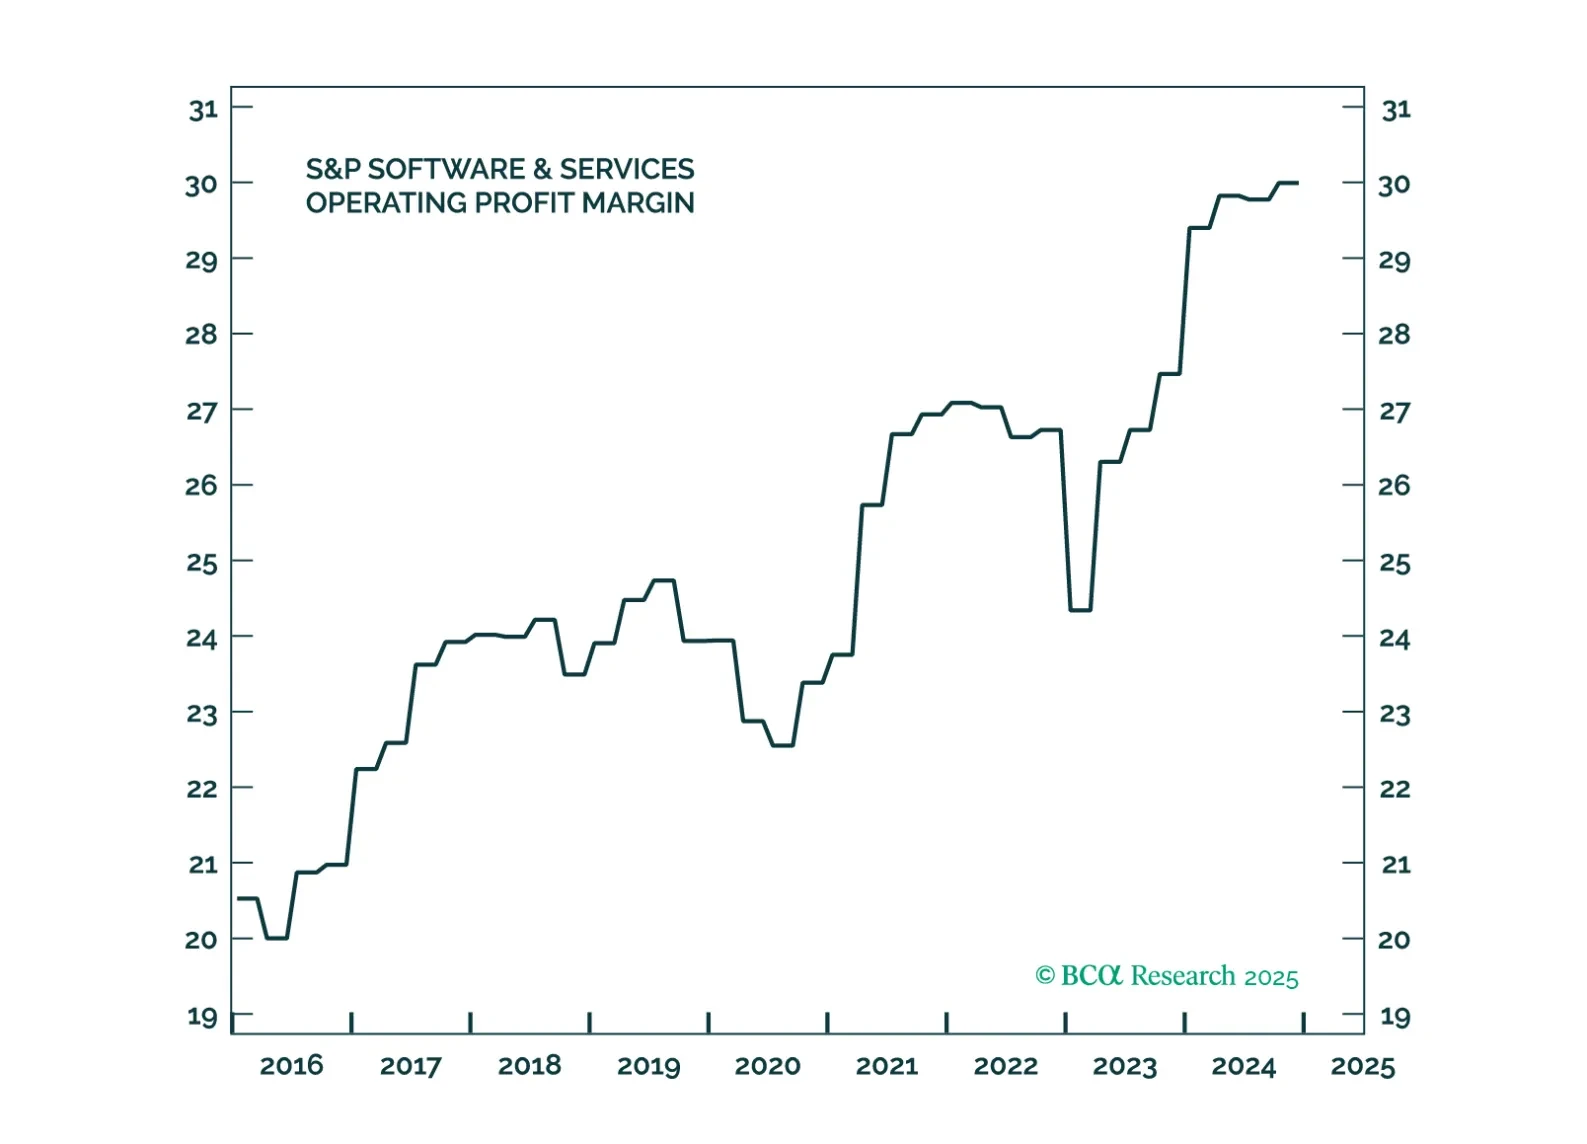
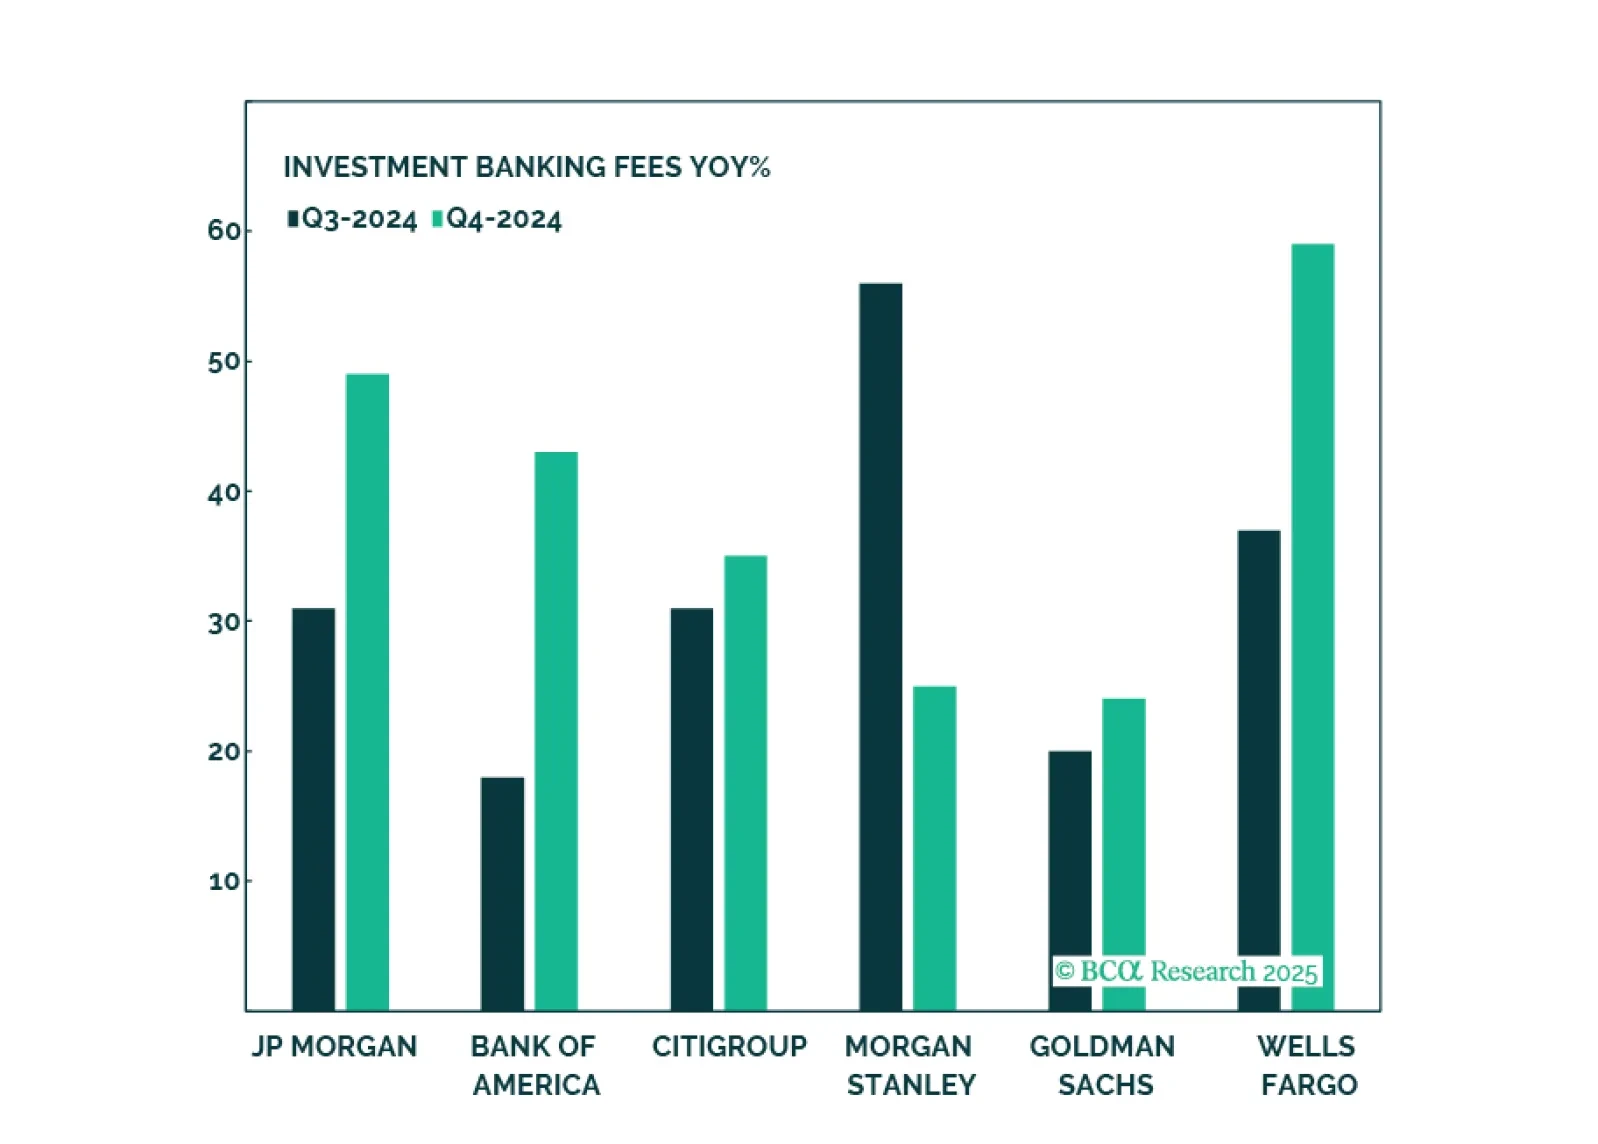
Banks have had an amazing run, and while such strong performance is unlikely to repeat, there is still oomph left in the trade thanks to a more favorable regulatory environment, stronger demand for loans, a steeper yield curve, and a strong pipeline of capital market activity. Key risks are further tightening of monetary policy and an increase in bad loans. We reiterate our overweight on Capital Markets, Diversified Banks, and Regional Banks.
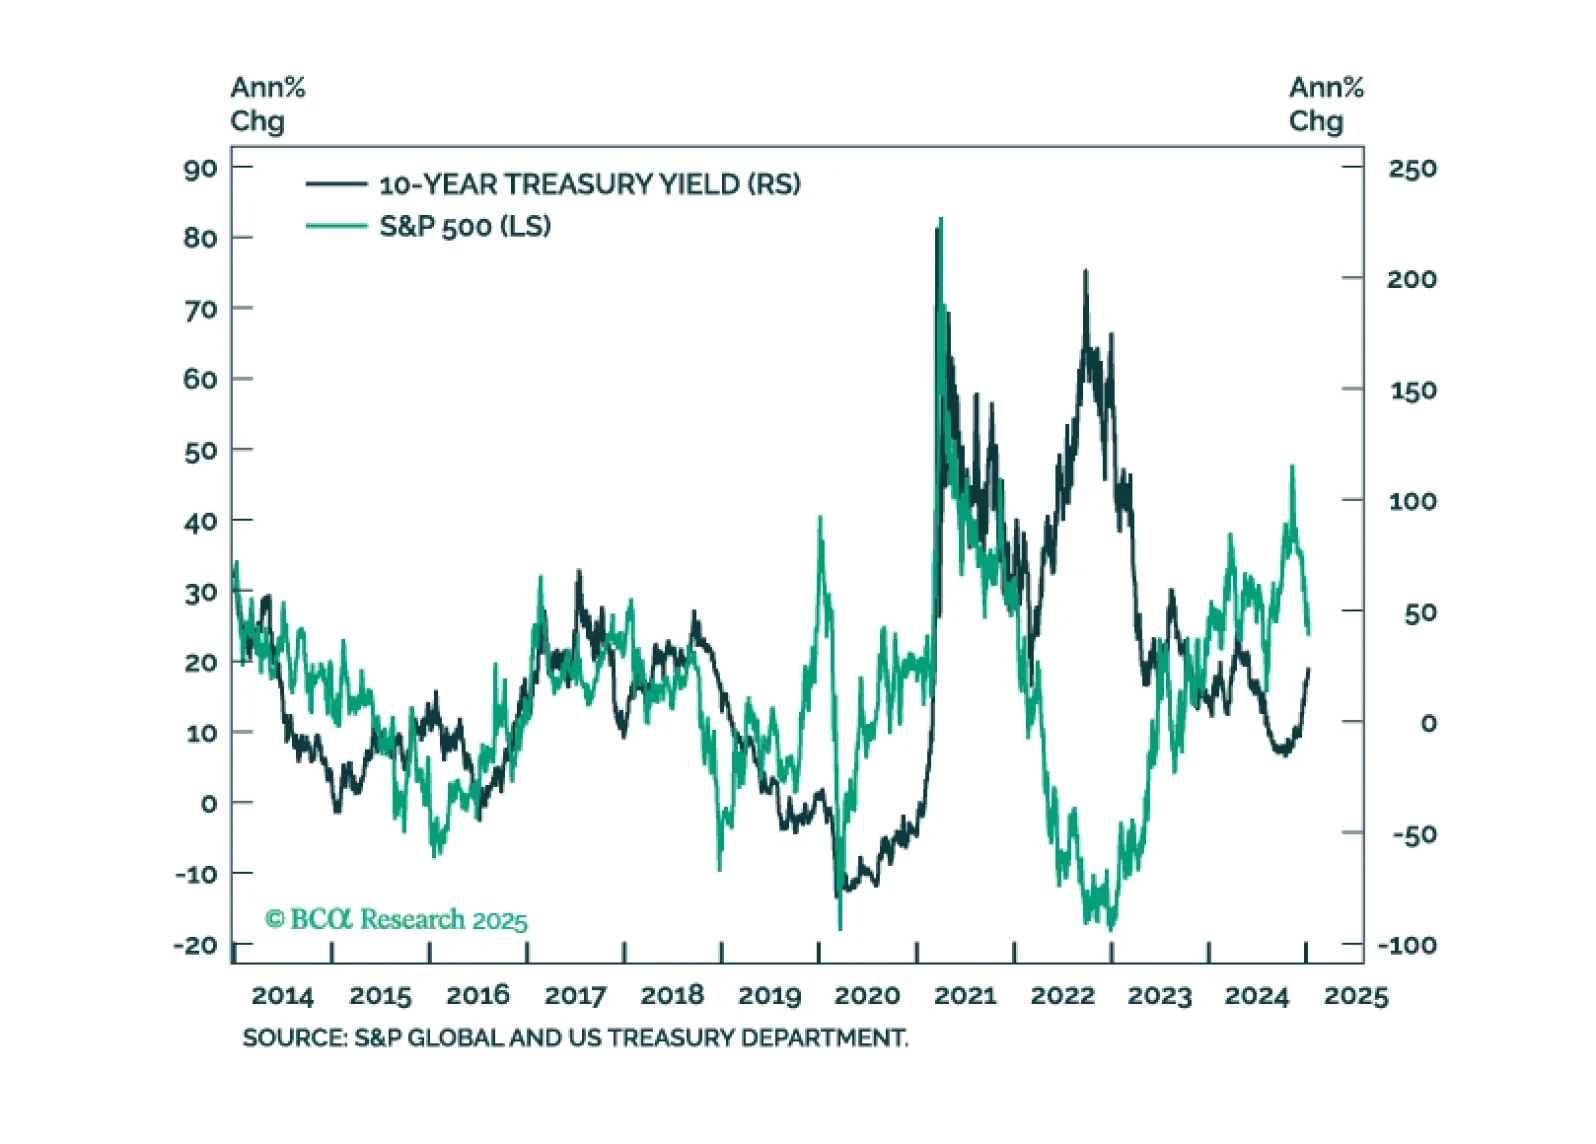
In this first presentation of 2025, we start with an overview of the 2025 outlook webcast polls, and a brief post-mortem of the 2024 market performance. Then, we shift gears and examine what is behind the recent surge in bond yields and its implications for equities. We also review market technicals and positioning and conclude with a list of trades to prepare our portfolio for continued moves in yields.
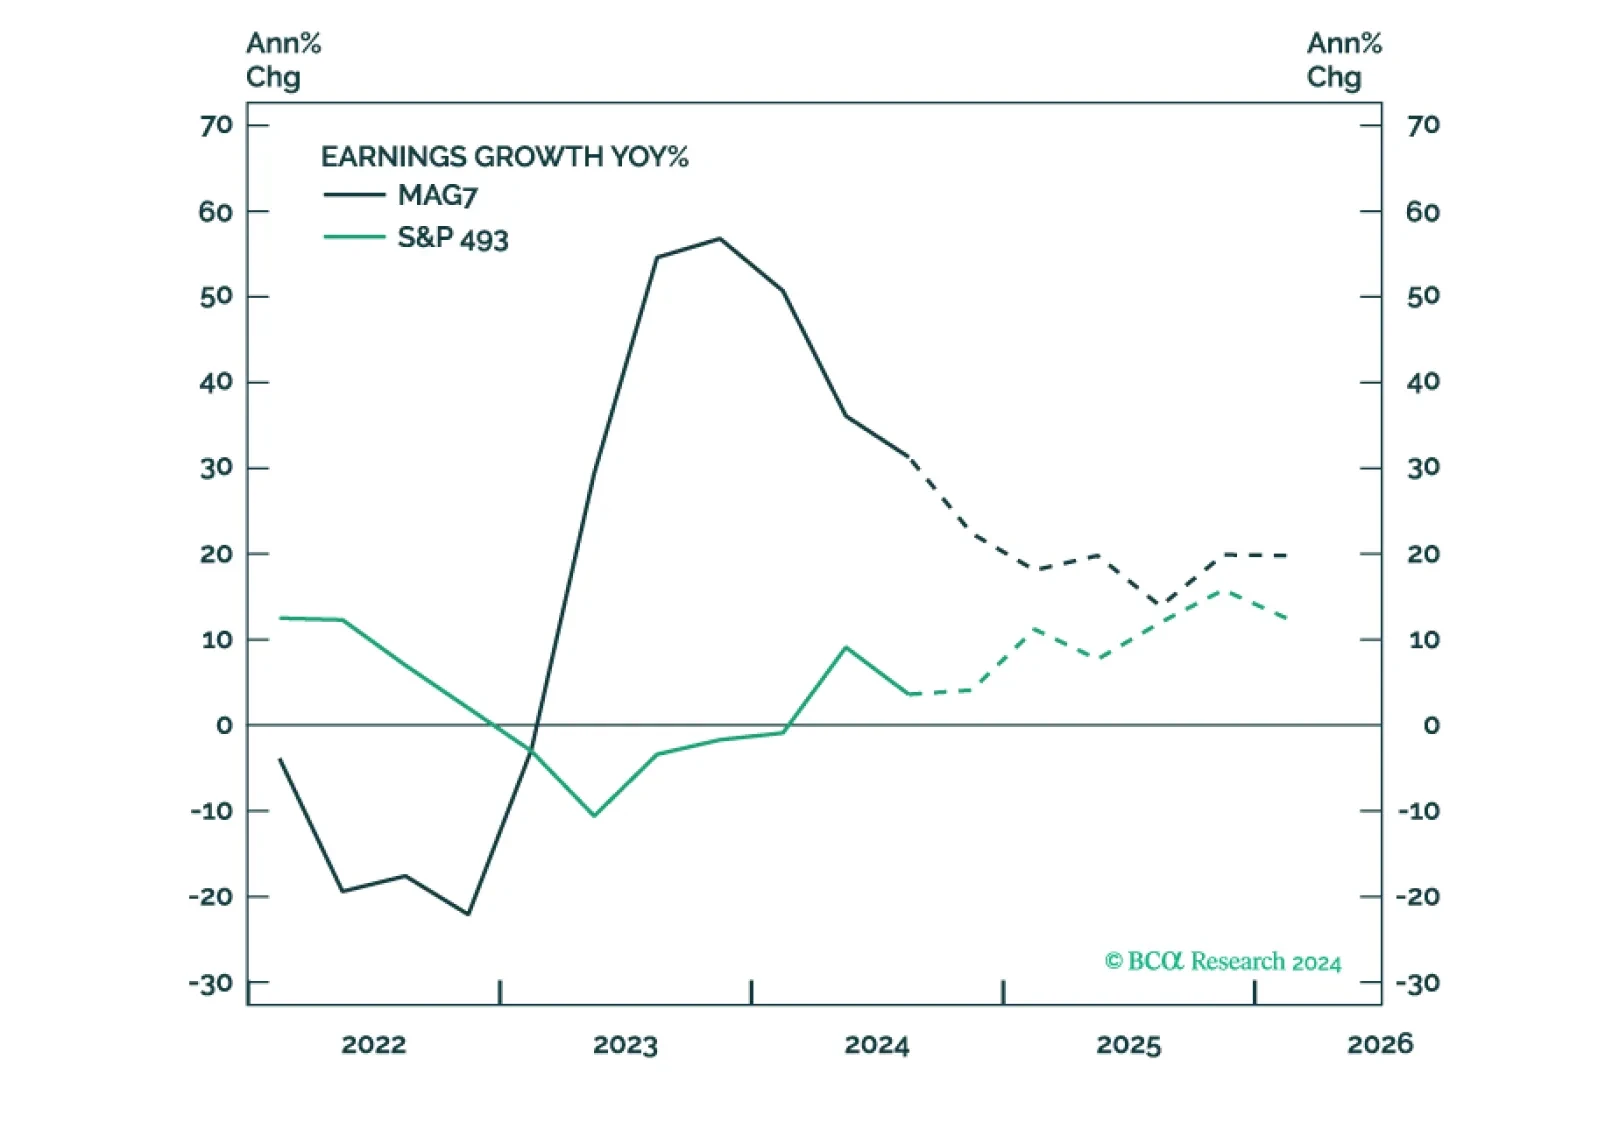
Trump's policies aim to support domestic producers and will be pro-growth and inflationary, at least initially. This environment is supportive of equities. Earnings will likely be strong, but elevated valuations make equities prone to a correction. Earnings growth broadening will translate into performance broadening – the S&P 493, Cyclicals, Value, Small and Mid are likely to outperform.
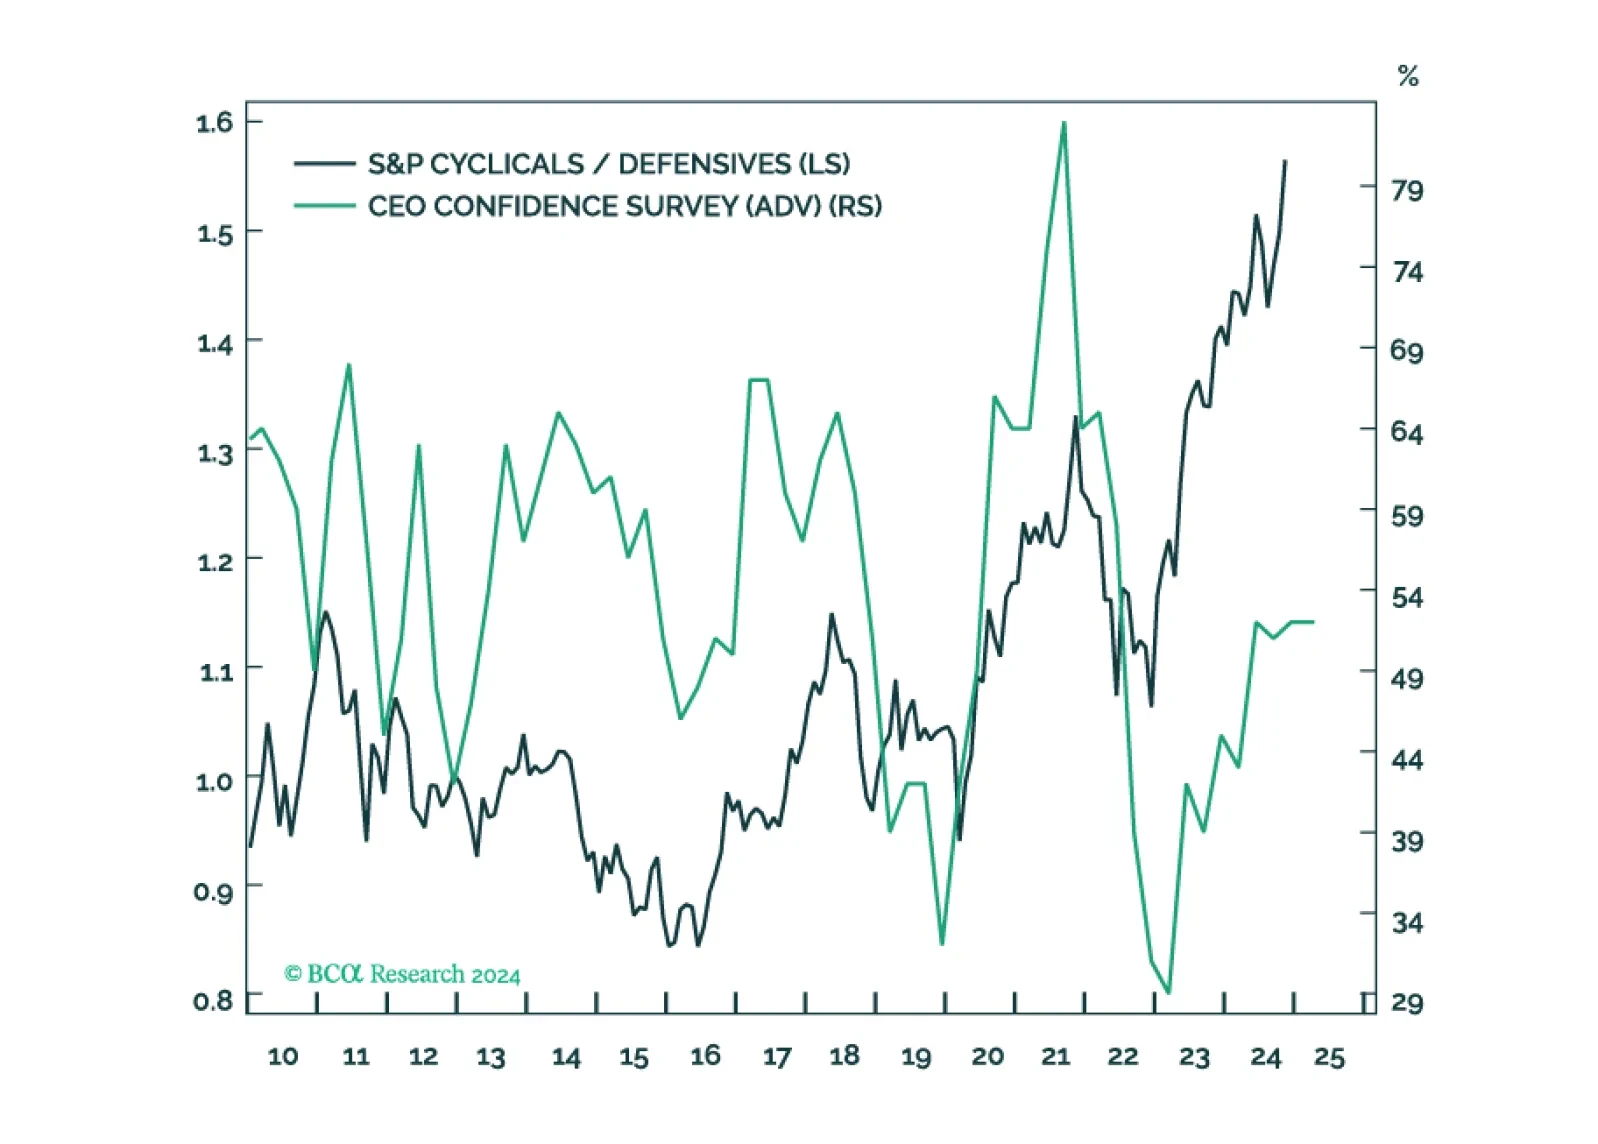
This week, we send you a Style Chart Pack without a front section. We are currently working on the 2025 outlook, which will be released on December 9.
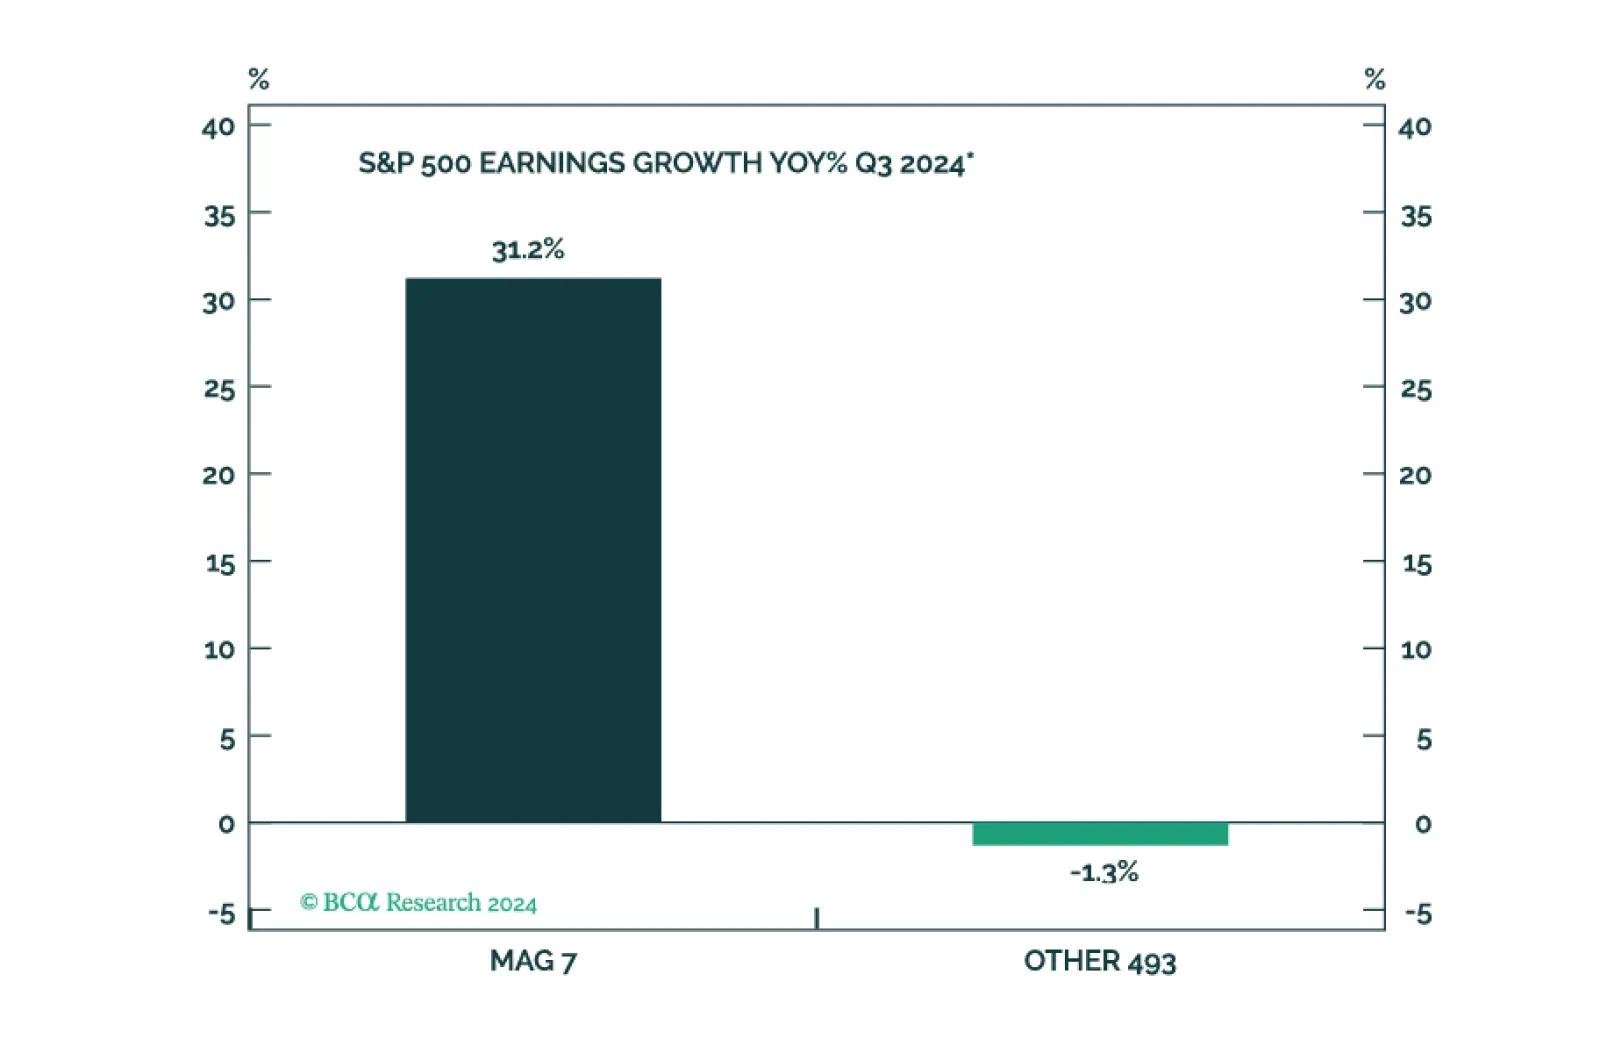
The earnings season was good but failed to assuage investor concerns that earnings growth remains concentrated. Tepid earnings and sales beats were somewhat concerning. However, based on company commentaries, the US economy remains sound. While challenges remain, such as slowing global growth, a strong dollar, and weakness among lower-income consumers, companies see them as surmountable. The market expects earnings growth to broaden in 2025. We concur as long as there are no major disruptive events.
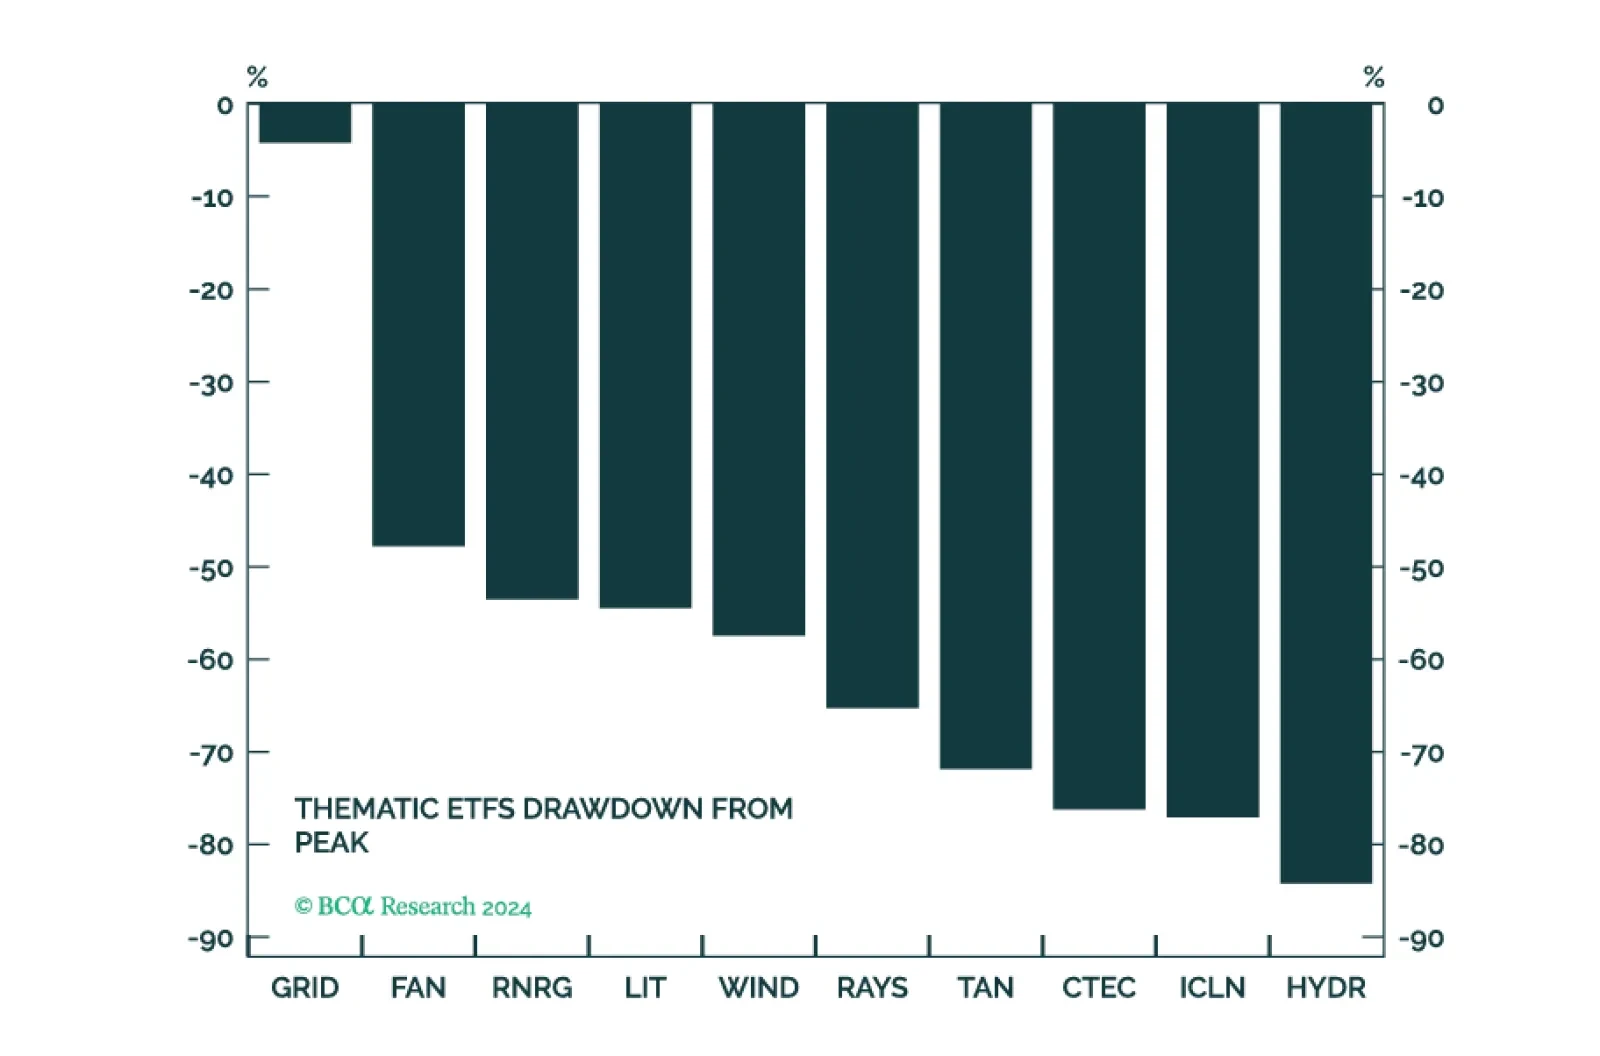
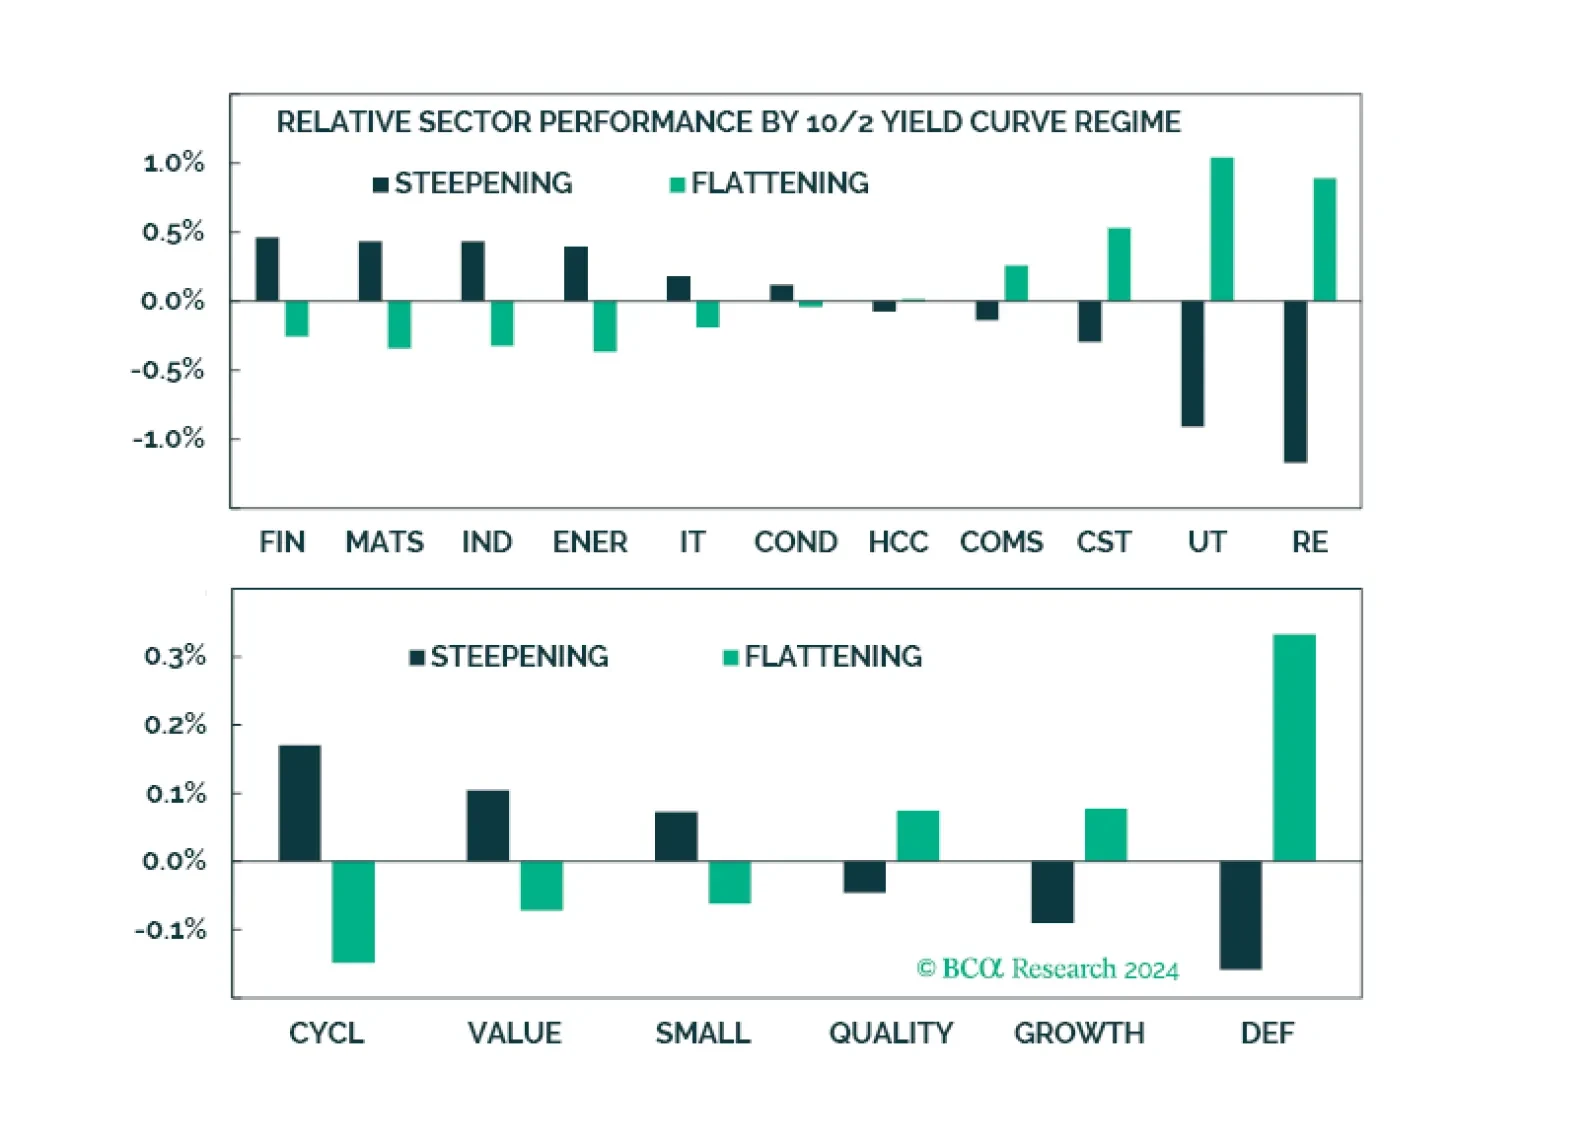
The market is celebrating the prospect of deregulation, lower taxes, and Fed rate cuts, for now ignoring the dangers of wider budget deficits, inflationary pressures, and trade wars. The rally can continue into the year-end and reduced uncertainty, seasonality, and positive momentum will benefit recent laggards such as Small, Value, and Cyclicals. We downgrade Energy from overweight to underweight. We downgrade Telecoms and Consumer Staples to underweight. We upgrade Insurance from underweight to overweight. We upgrade Utilities to overweight.