 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
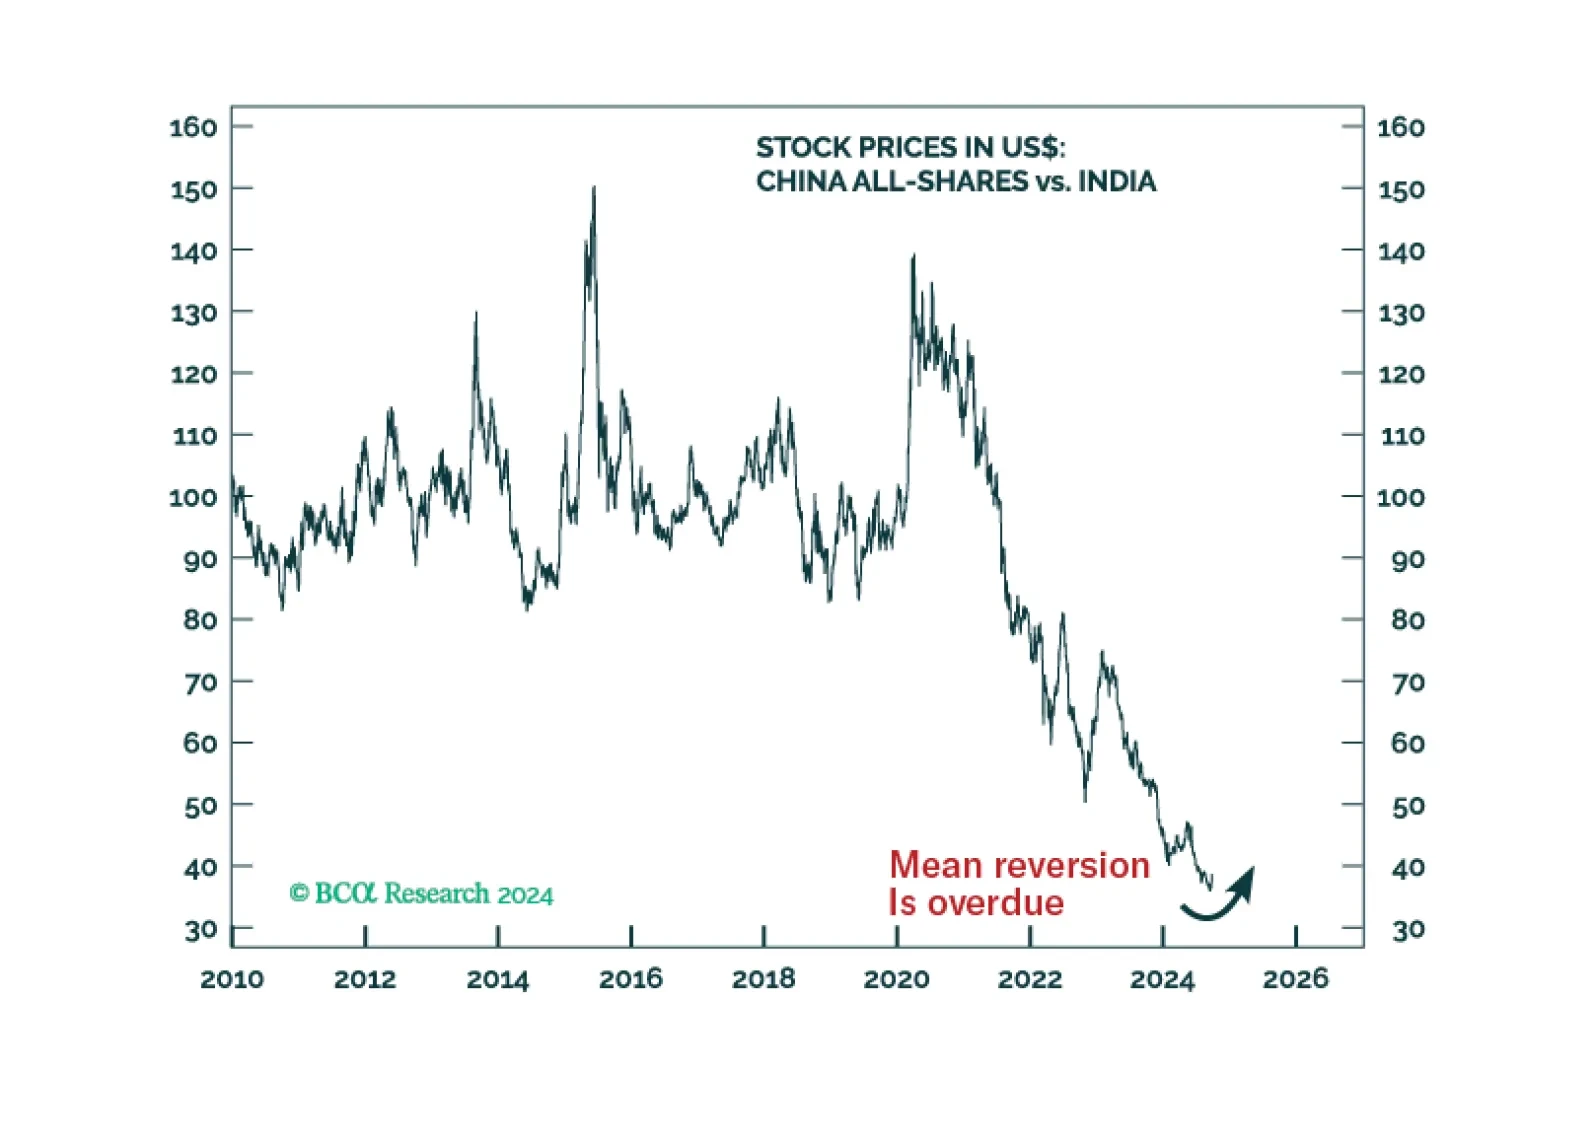
The adrenaline from the recent policy stimulus might be sufficient to produce a window of outperformance for Chinese equities and China-plays in financial markets. However, this adrenaline will not extend to China's real economy. Net-net, we are upgrading the allocation to EM in a global equity portfolio from underweight to neutral.
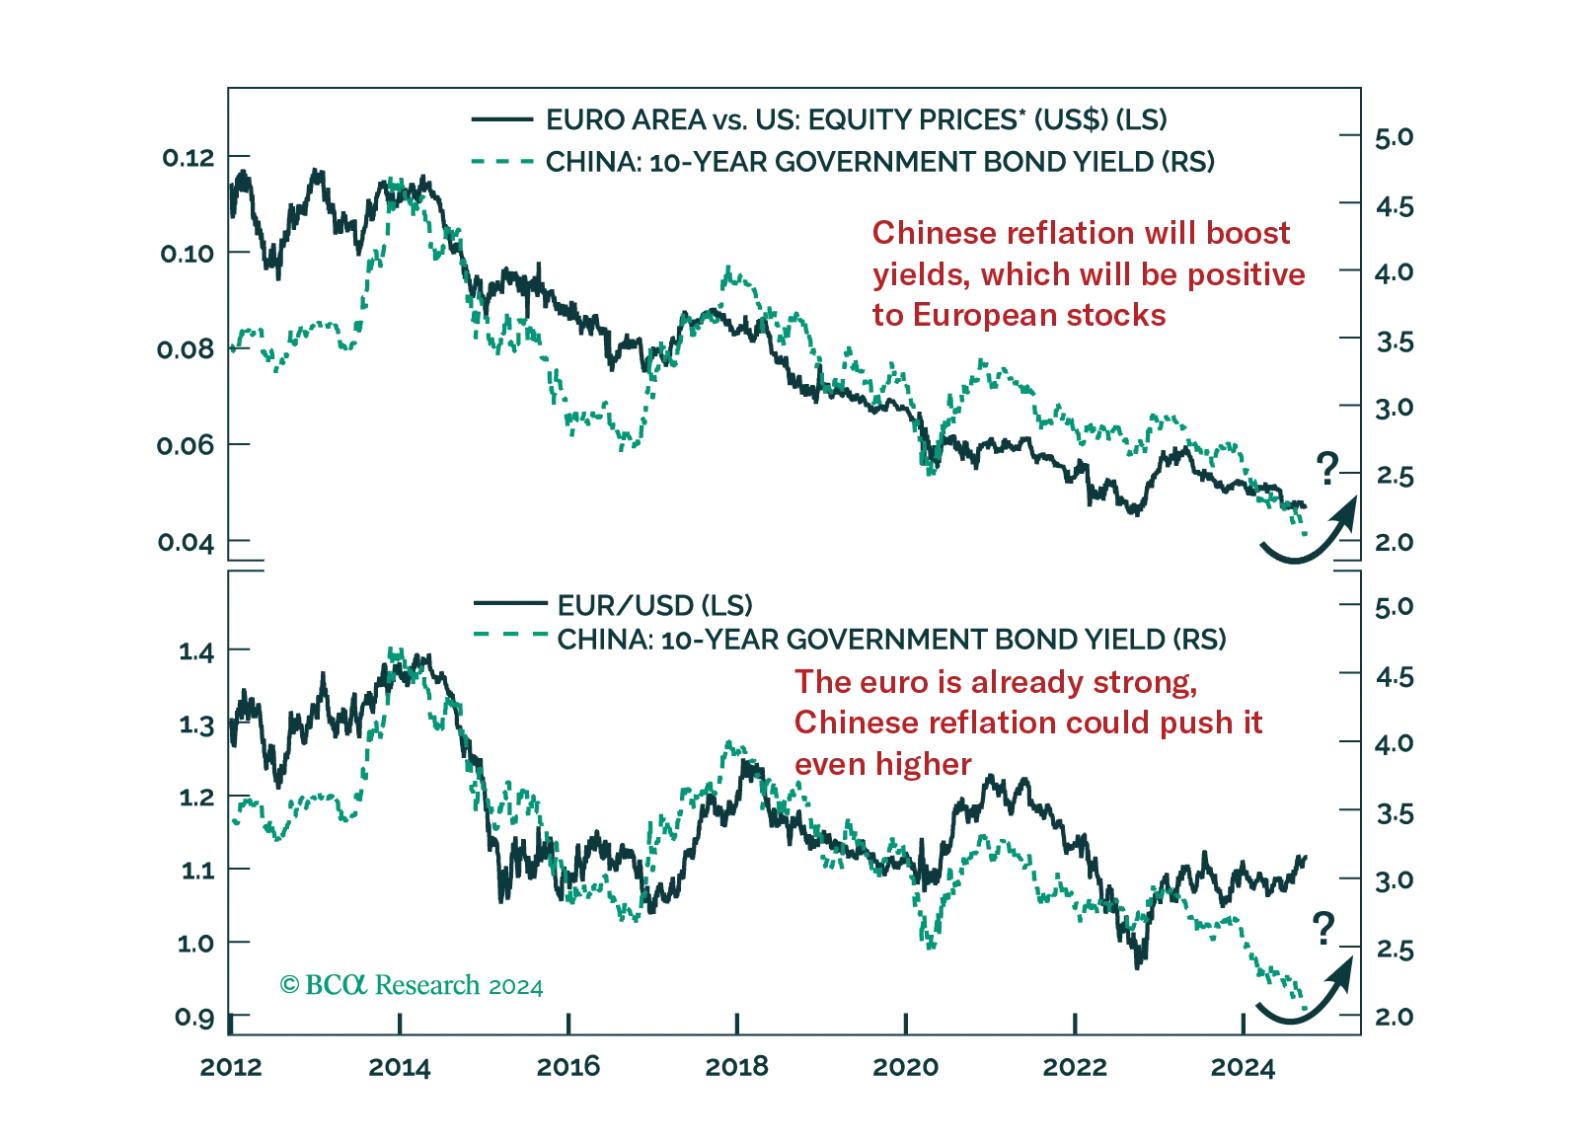
China’s Politburo announcement is likely to lead to a repricing of China’s growth in the near-term. Read how investors can hedge against this potent threat to our defensive investment stance.
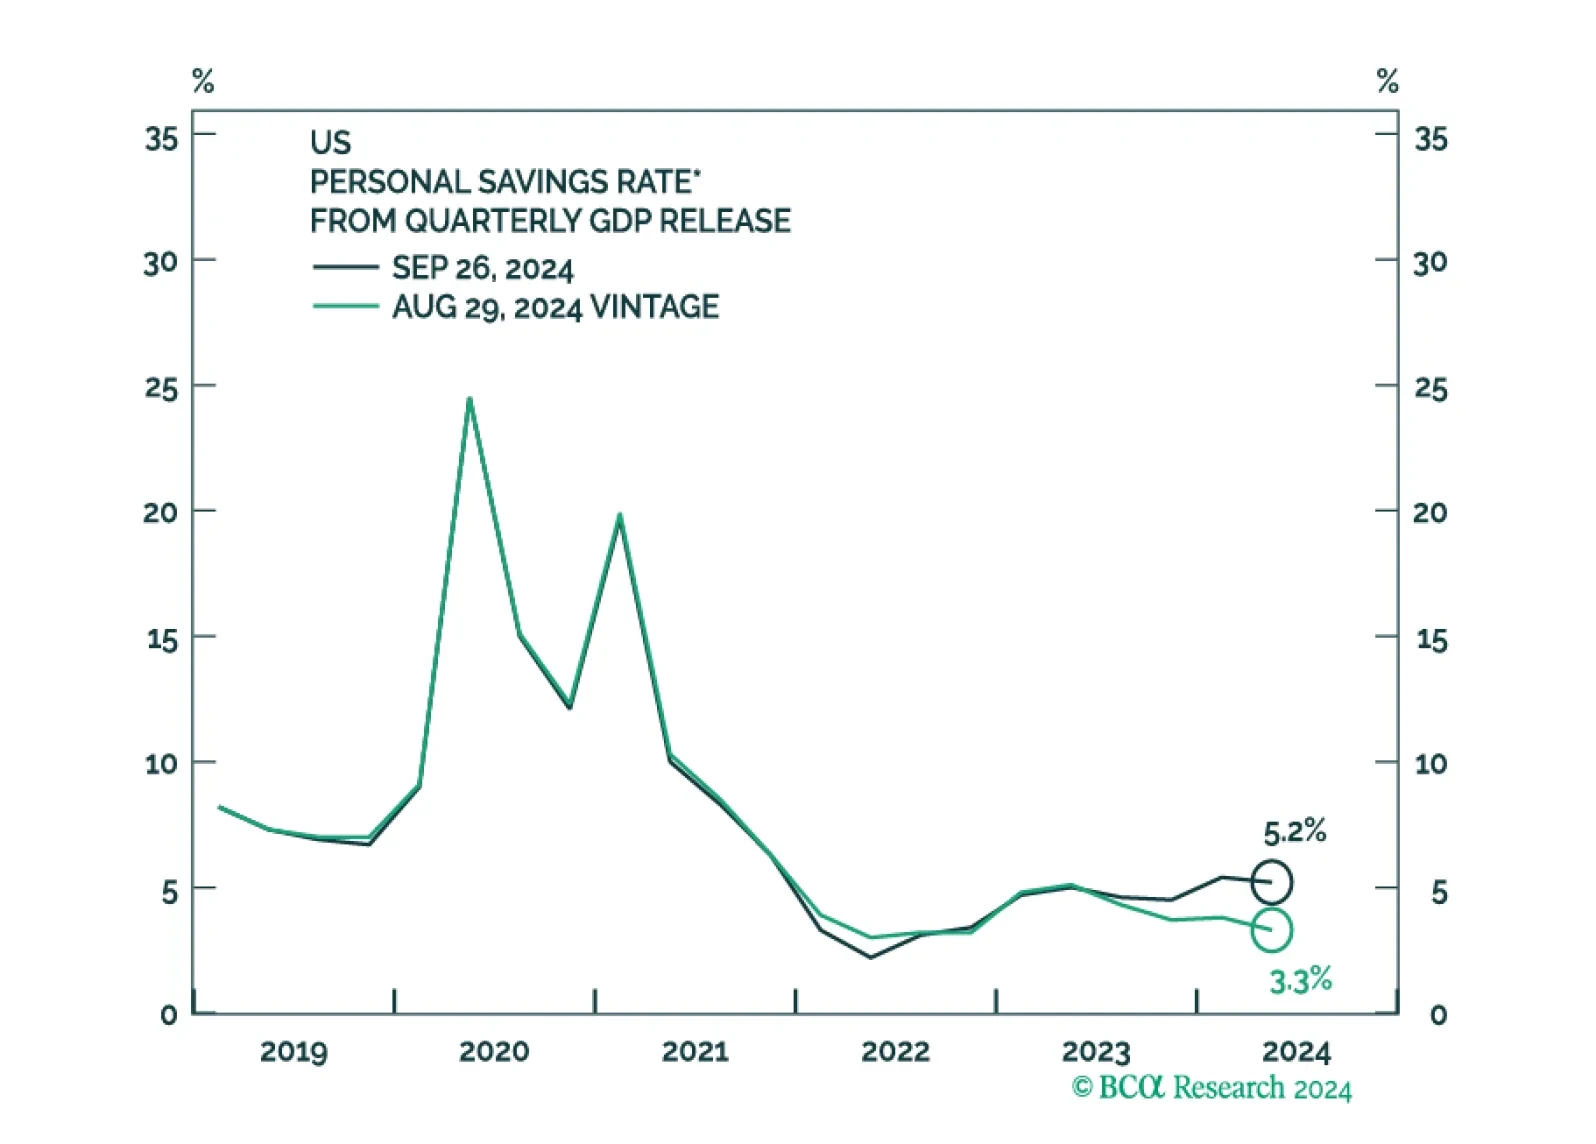
In my view, the revisions resolve a big puzzle that has developed over the past two years, which is how employment growth could have been so strong while personal income growth was so weak. Well, as it turns out, income growth was quite strong too.
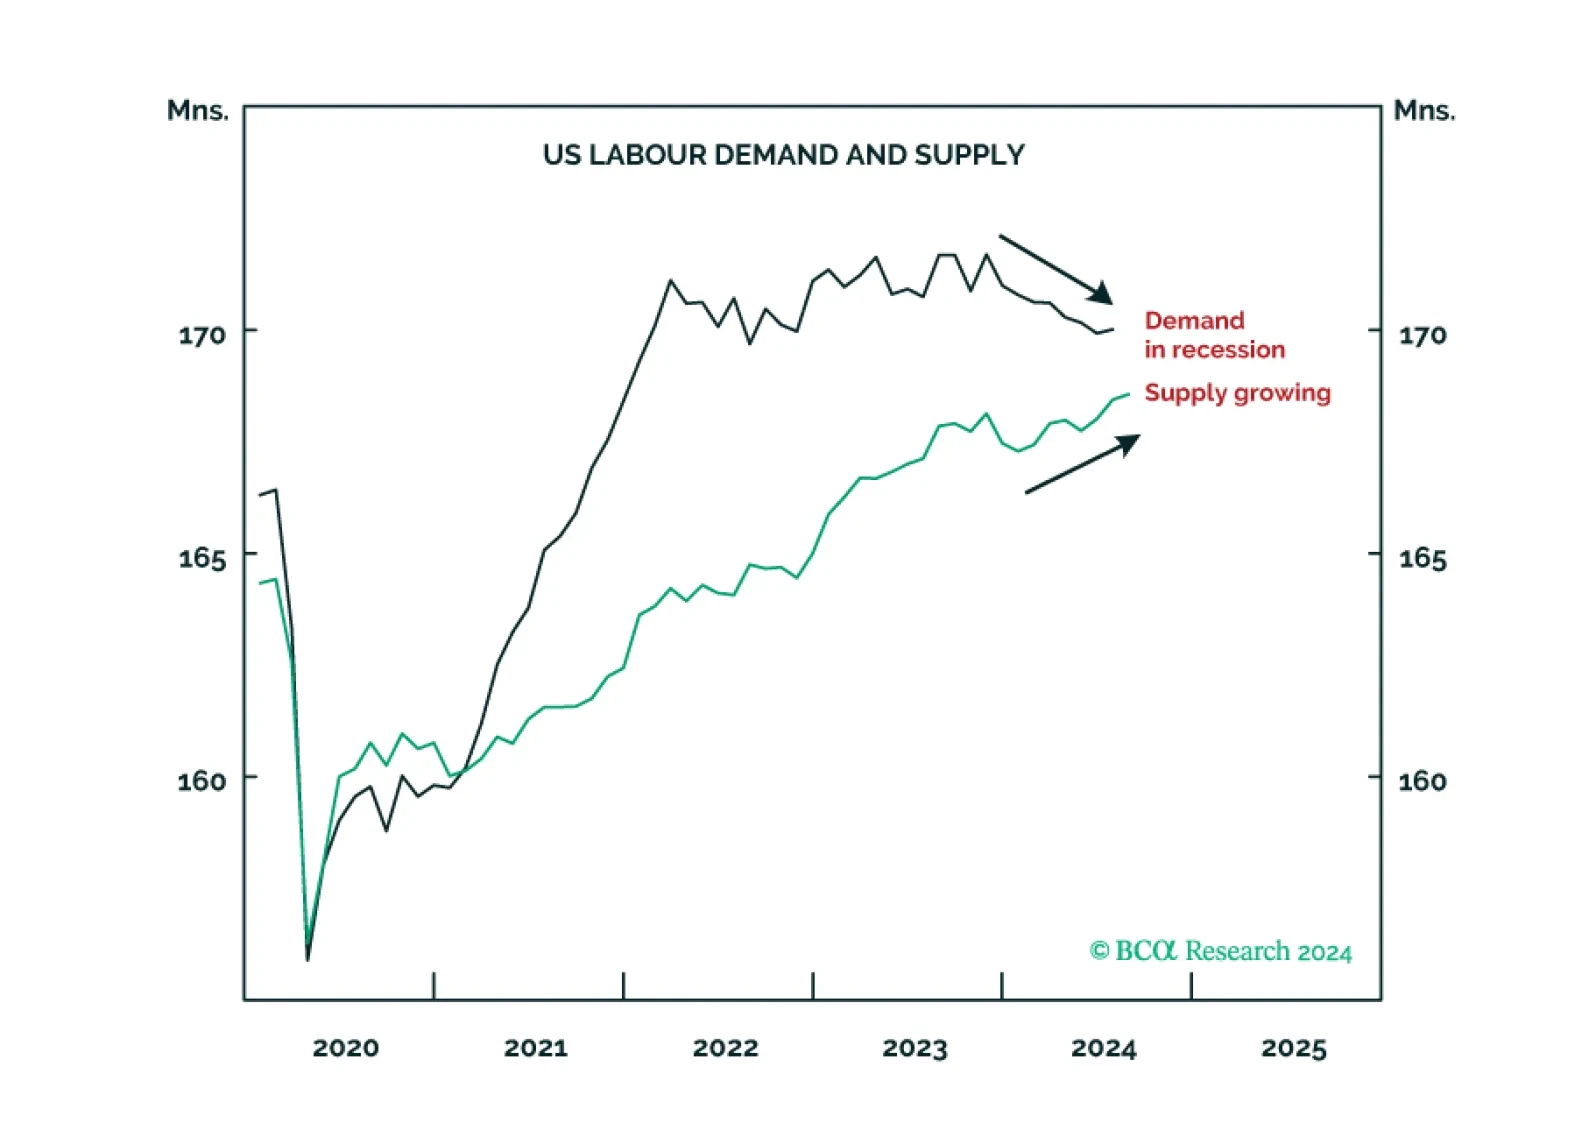
Just like the market for Oasis 2025 reunion tour tickets, the US labour market is ‘supply-constrained’. This means the US will not go into a GDP recession in the next few months and has a good chance of cheating one for longer. Without a GDP recession, there is unlikely to be an economy-wide profits recession. This leads to three recommendation changes on a cyclical (12-month) horizon which we highlight. Plus: the tactical rally in Chinese stocks can continue.
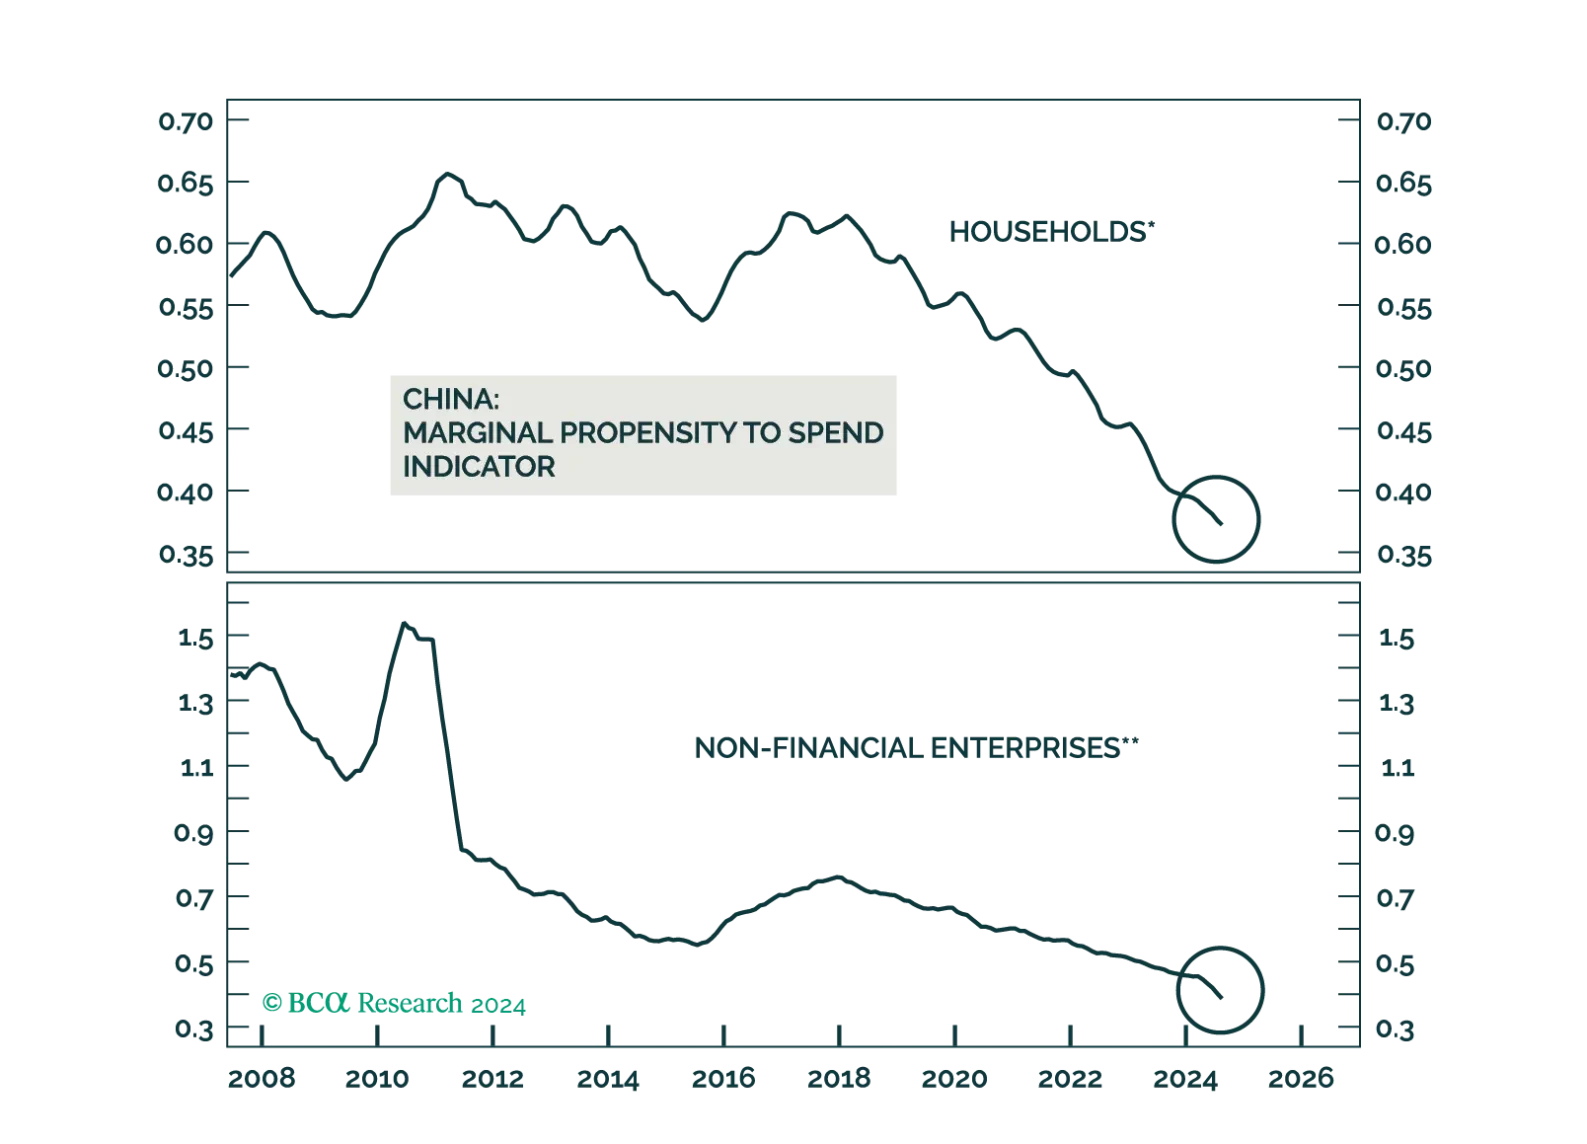
We believe the PBoC’s recent policy stimulus might bolster investor confidence, potentially stabilize onshore Chinese equity prices, and provide modest support to offshore stocks. However, they are unlikely to significantly boost economic growth in the mainland.
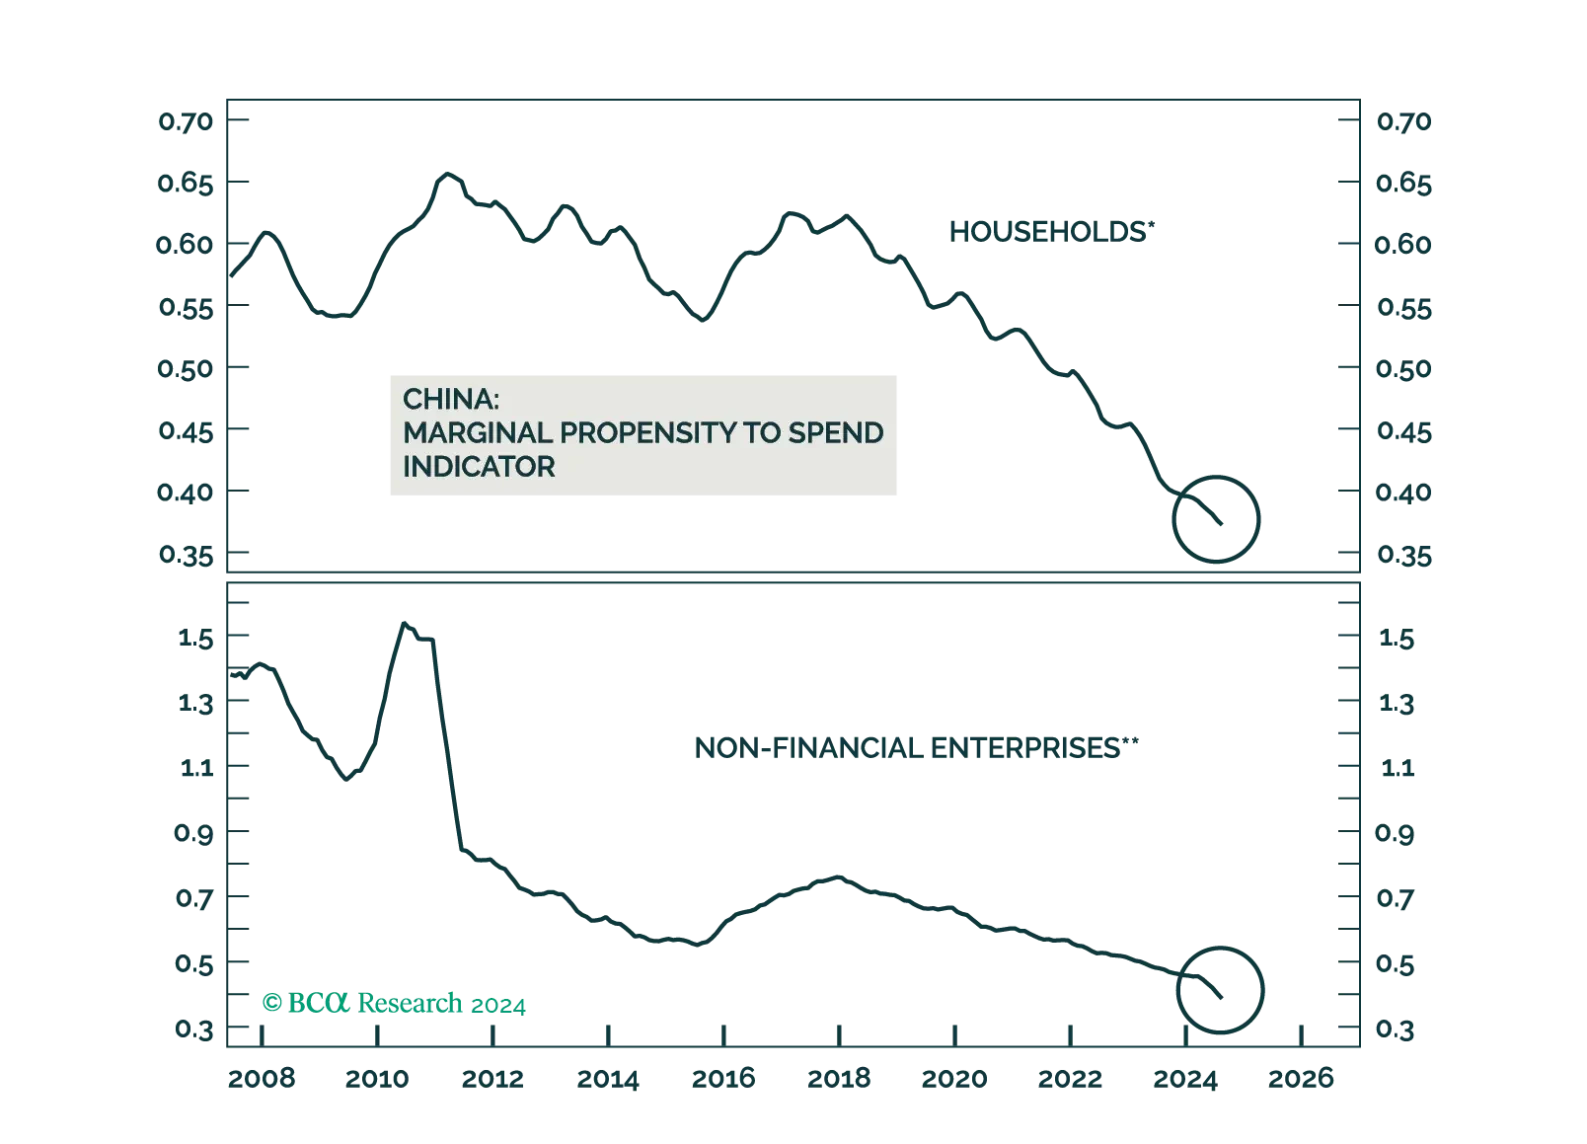
We believe the PBoC’s recent policy stimulus might bolster investor confidence, potentially stabilize onshore Chinese equity prices, and provide modest support to offshore stocks. However, they are unlikely to significantly boost economic growth in the mainland.
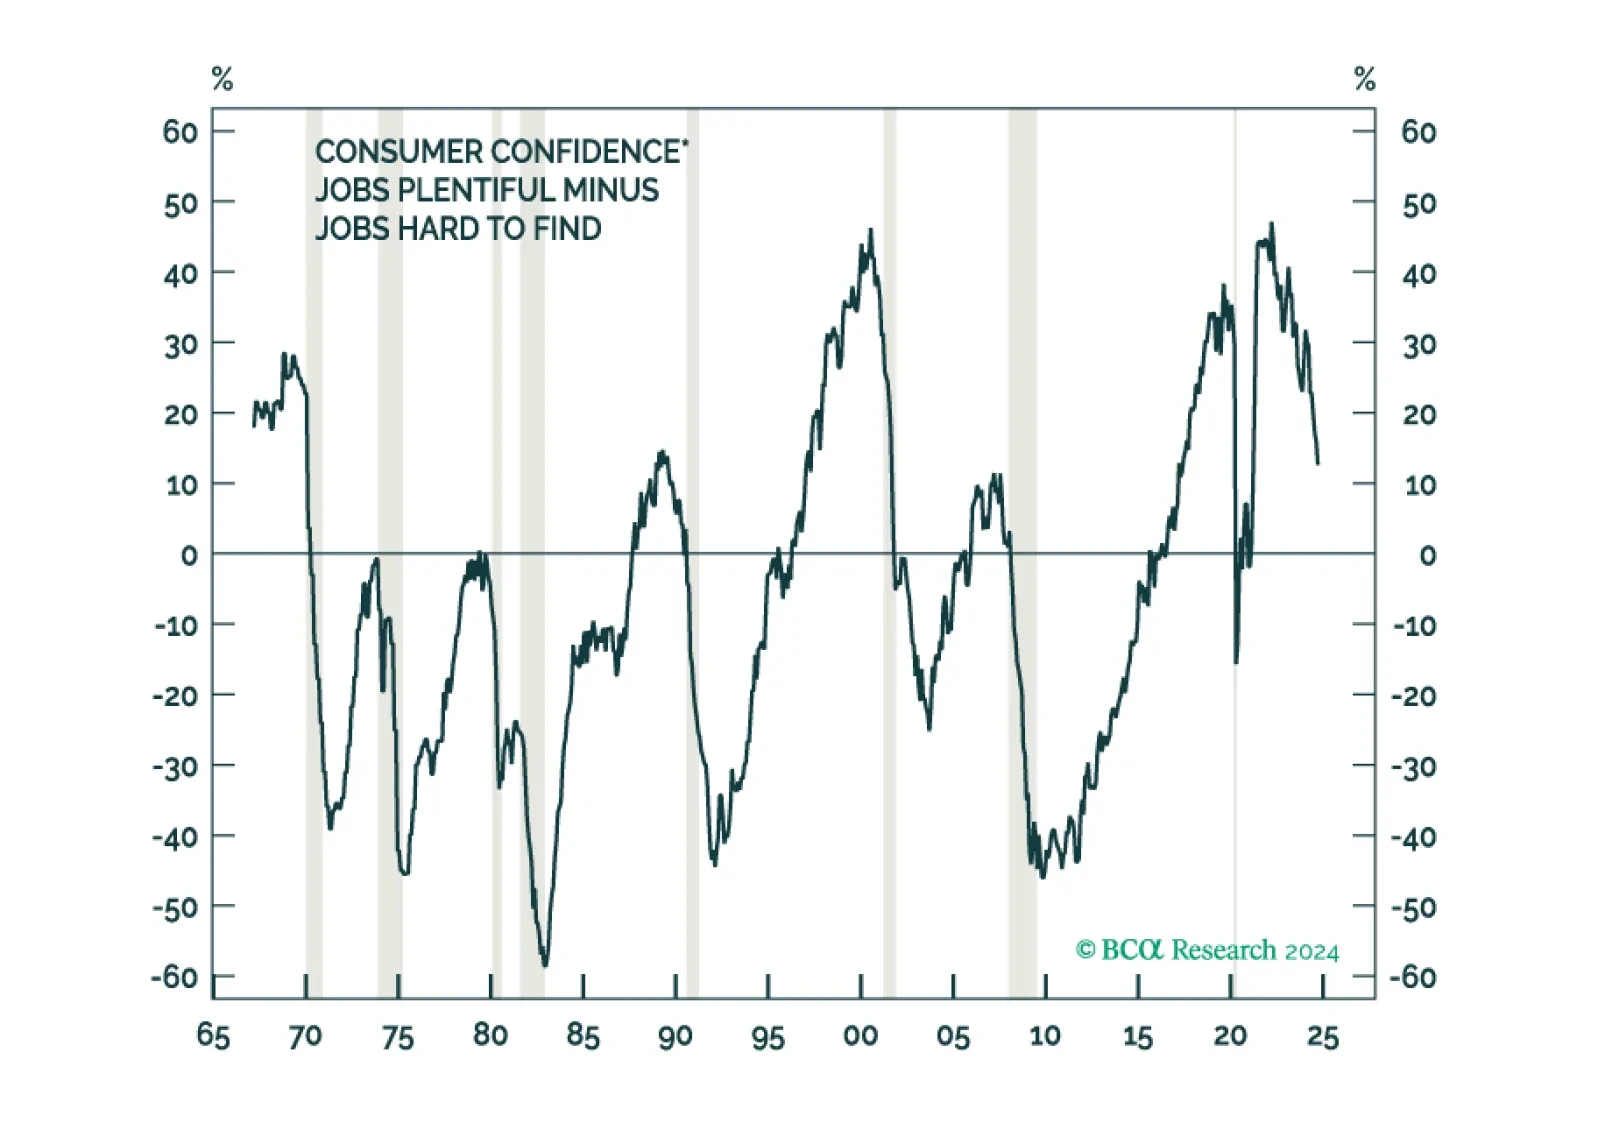
Two days ago, I flagged how the number of people in the US who are working part time but would rather be working full time is rising, which usually only happens in the early stages of recessions.
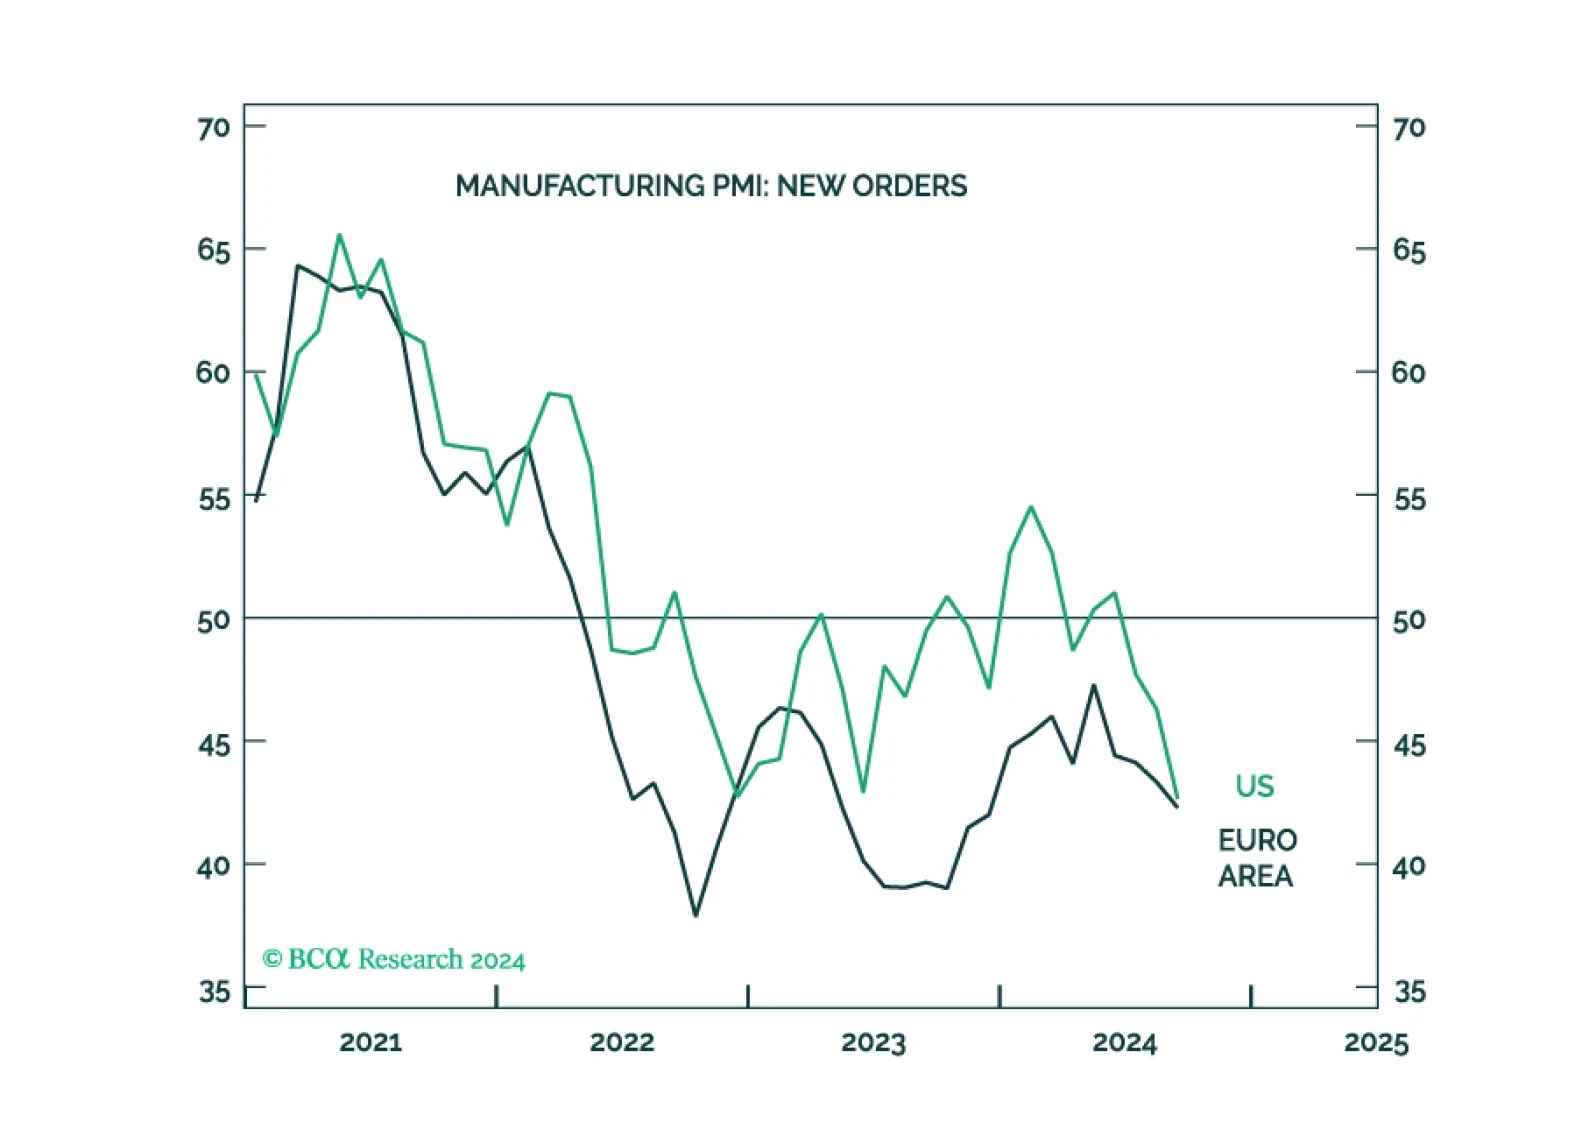
The S&P Global flash PMIs released yesterday showed that the contraction in manufacturing activity accelerated on both sides of the Atlantic in September. The forward-looking new orders component fell to a 9-month low of 42.3 in the euro area and a 21-month low of 42.7 in the US.
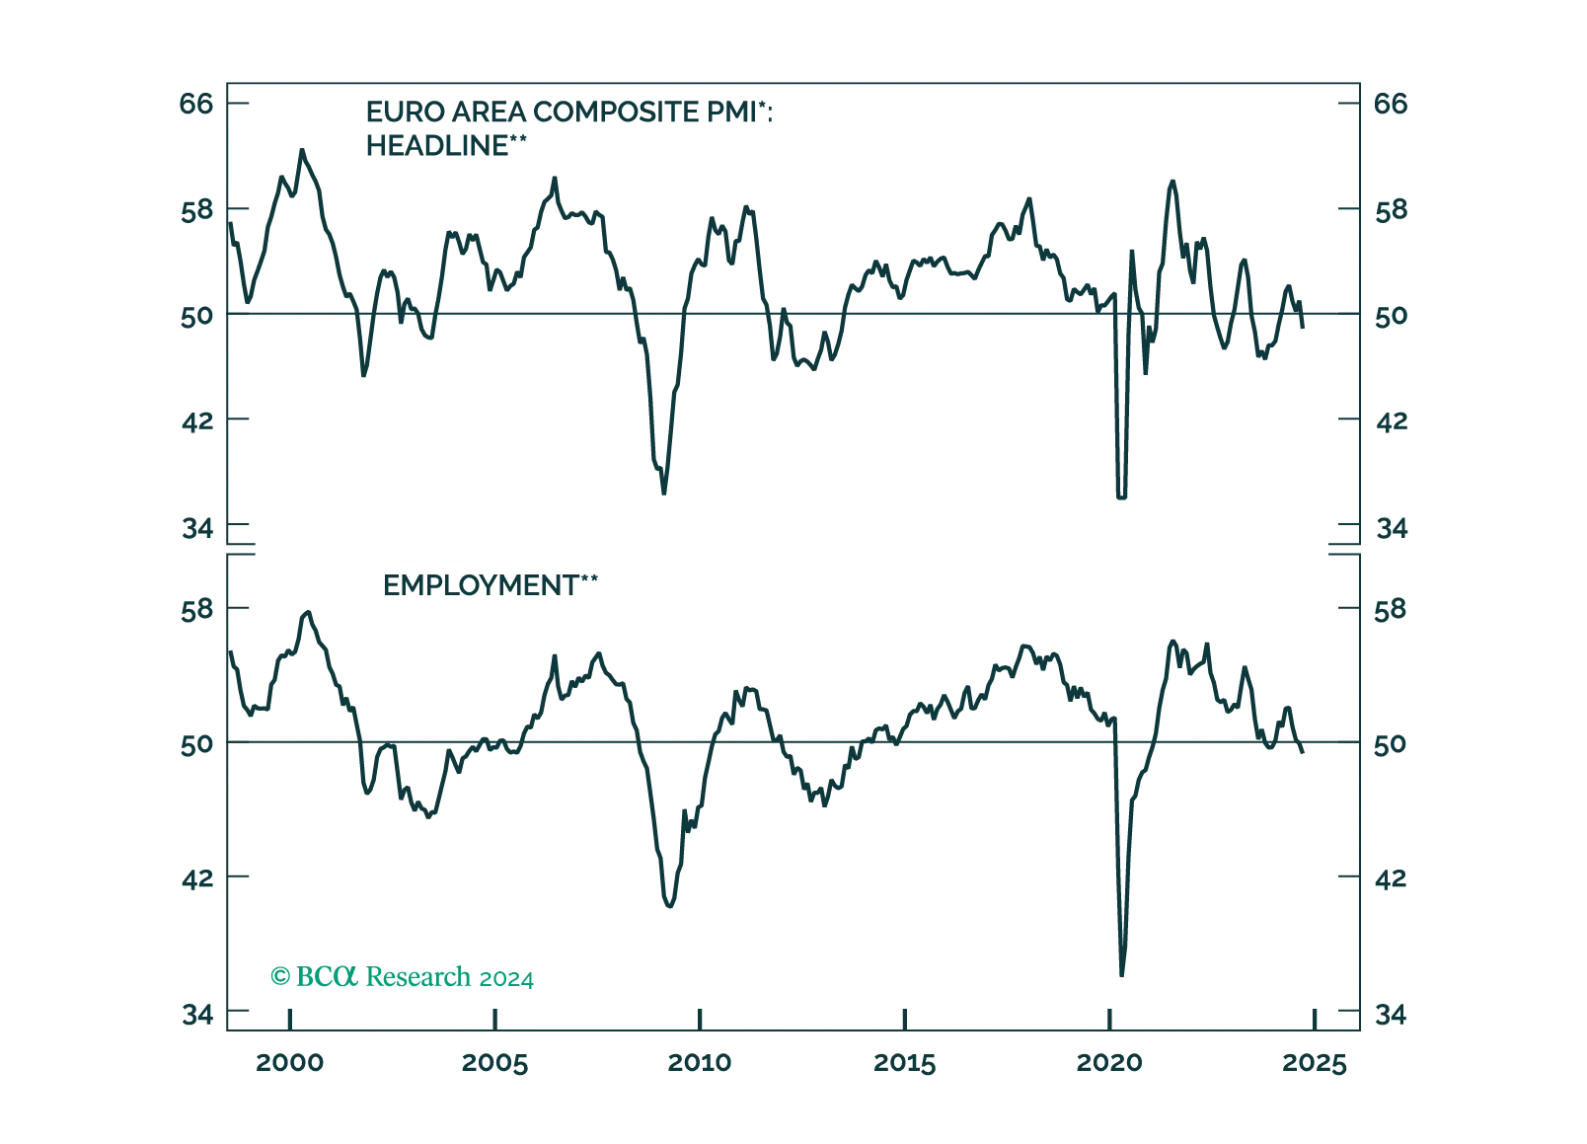
The September Euro Area Flash PMI release confirms that the region's economic outlook is deteriorating. Manufacturing activity is now fully contracting, and the new orders-to-inventory ratio is deteriorating anew. Services activity is losing some of its shine, especially in France, now that the Olympics are over.