 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
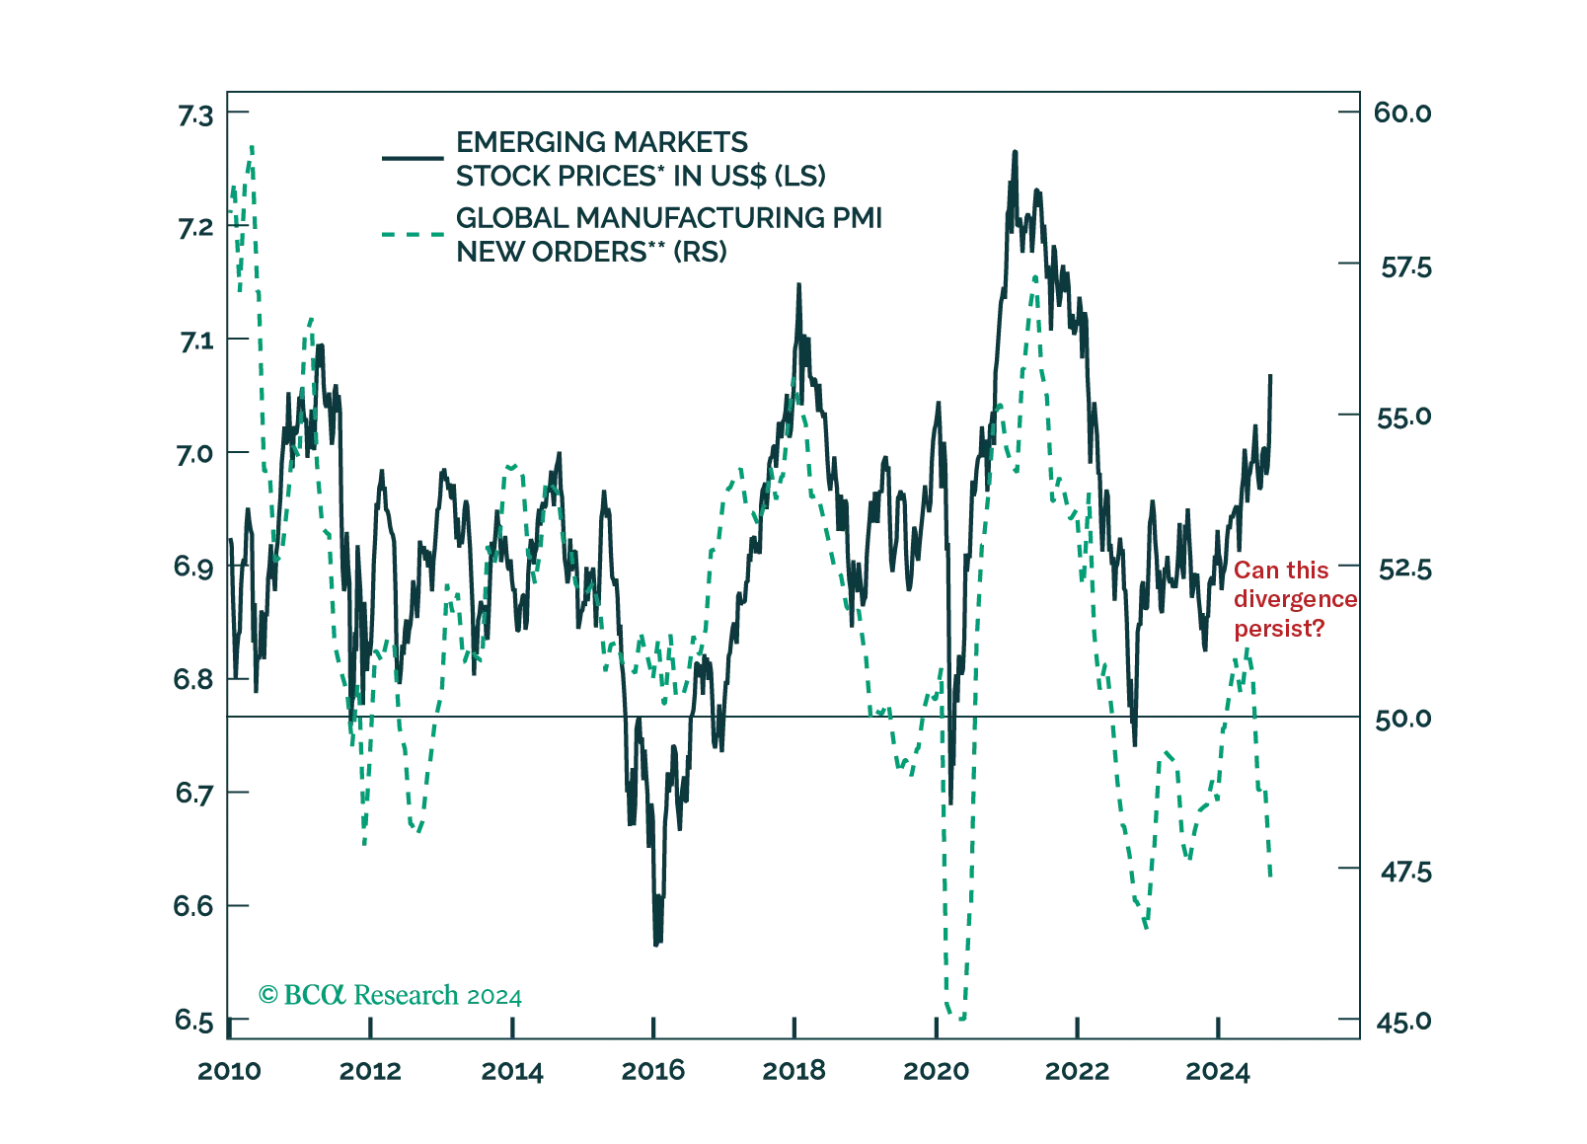
Conditions are not yet in place for going long EM stocks in absolute terms and upgrading their allocation from neutral to overweight relative to global equities. The broad trade-weighted US dollar will likely rebound in the next three-to-four months, and global trade will contract. The recent weakness in the US dollar is driven by the narrative that the Fed’s easing cycle is bearish for the greenback, but we believe this thesis is flawed.
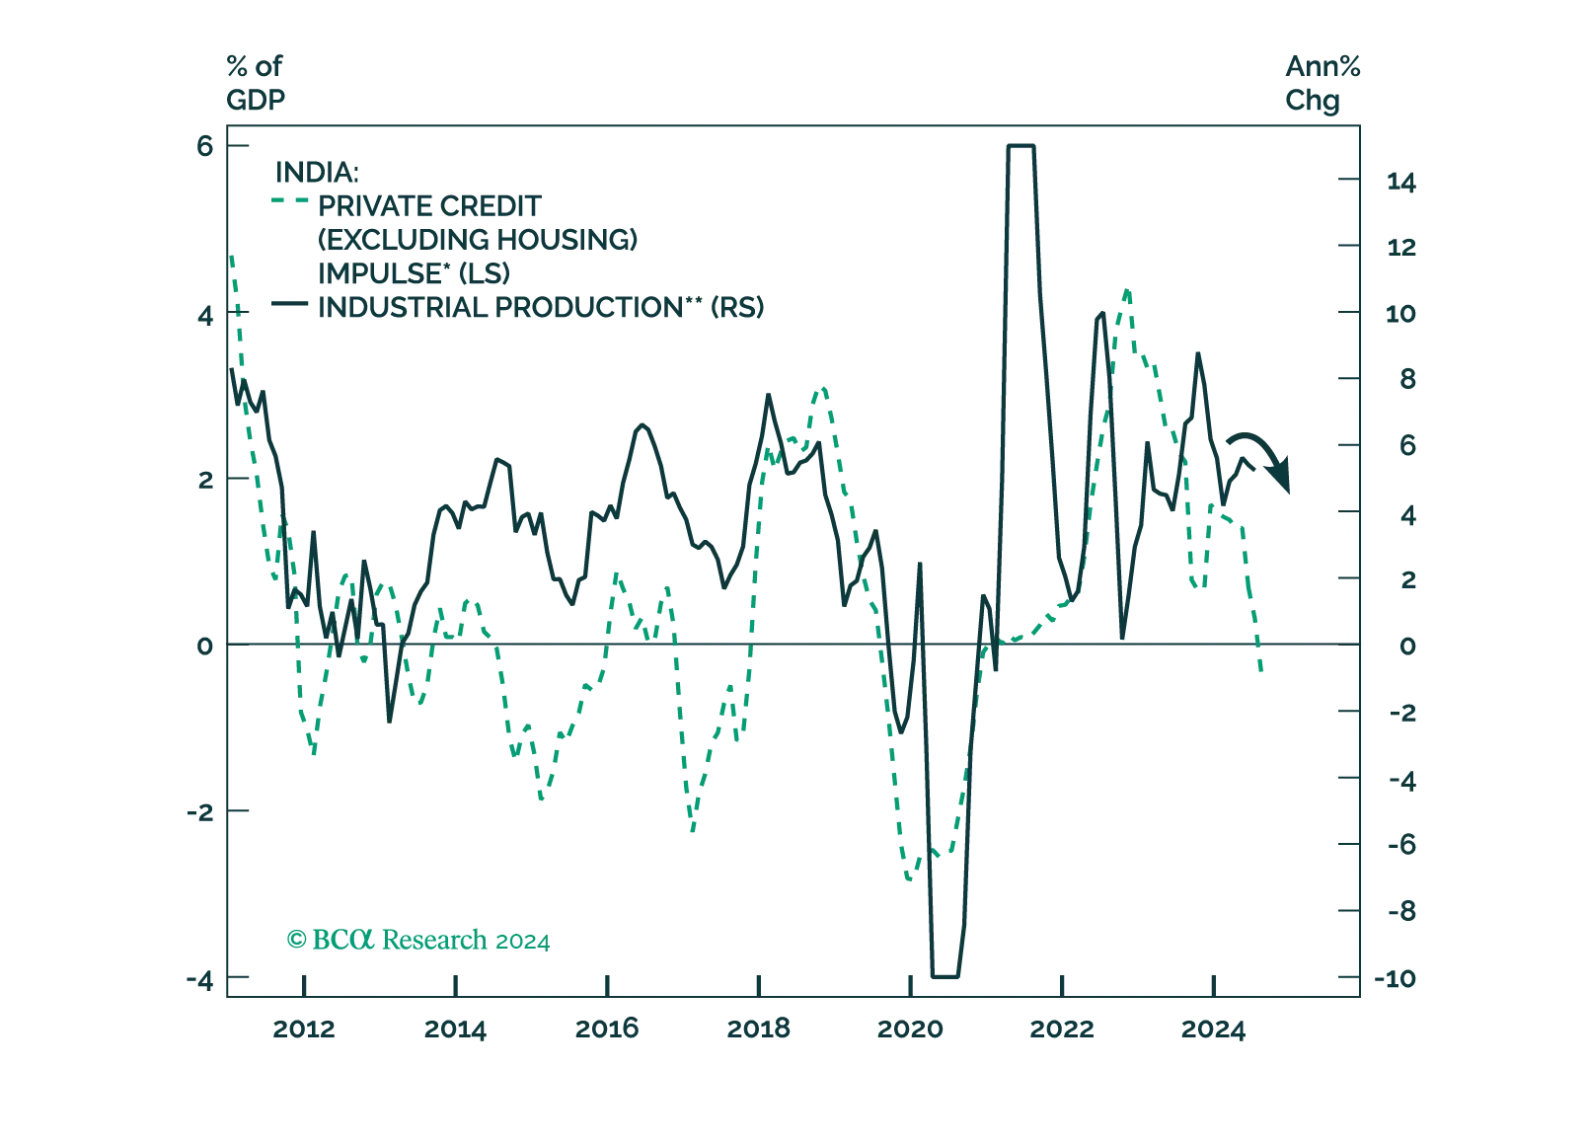
India’s credit impulse has turned negative. Government spending is contracting. The country’s growth will remain subdued; and both drivers of stock prices – profits and multiples – are headed lower at a time when equity valuations are at a record high.
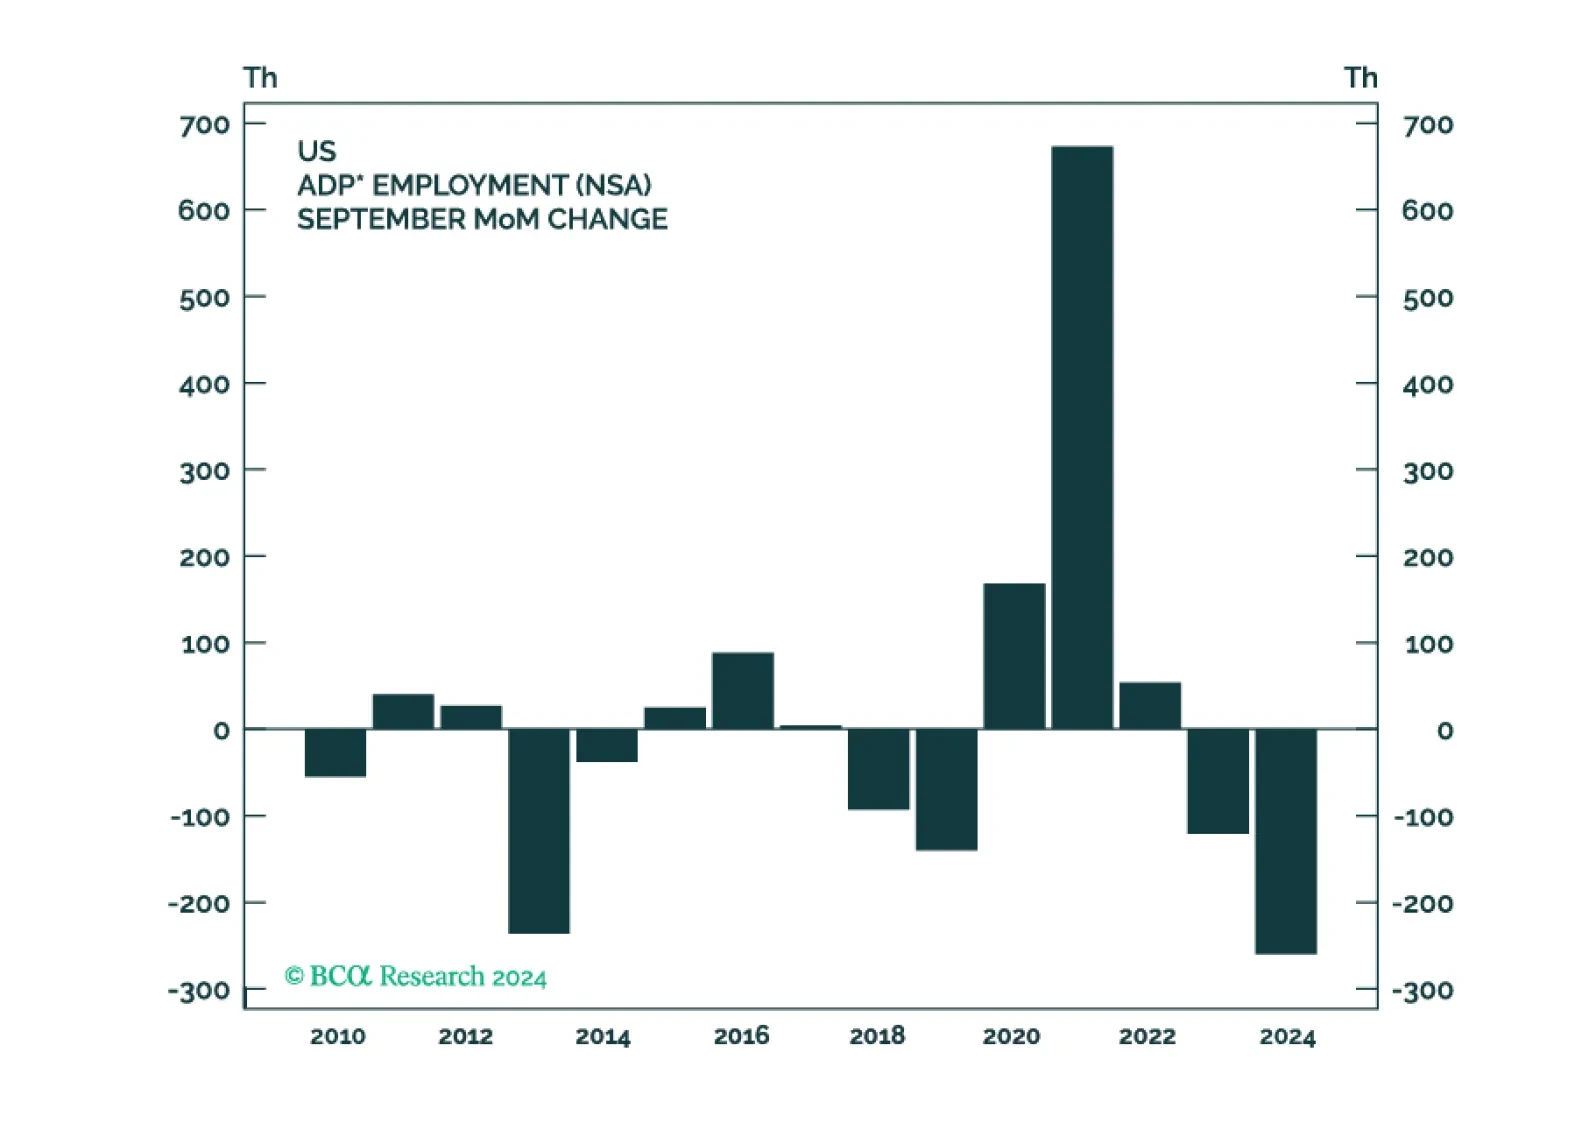
I am not one to dismiss the ADP report. Unlike the establishment survey, the ADP numbers are based on hard data. If the ADP is not a reliable guide to the government’s payrolls estimates, maybe that is because the government’s payroll estimates are not a reliable guide to actual payrolls.
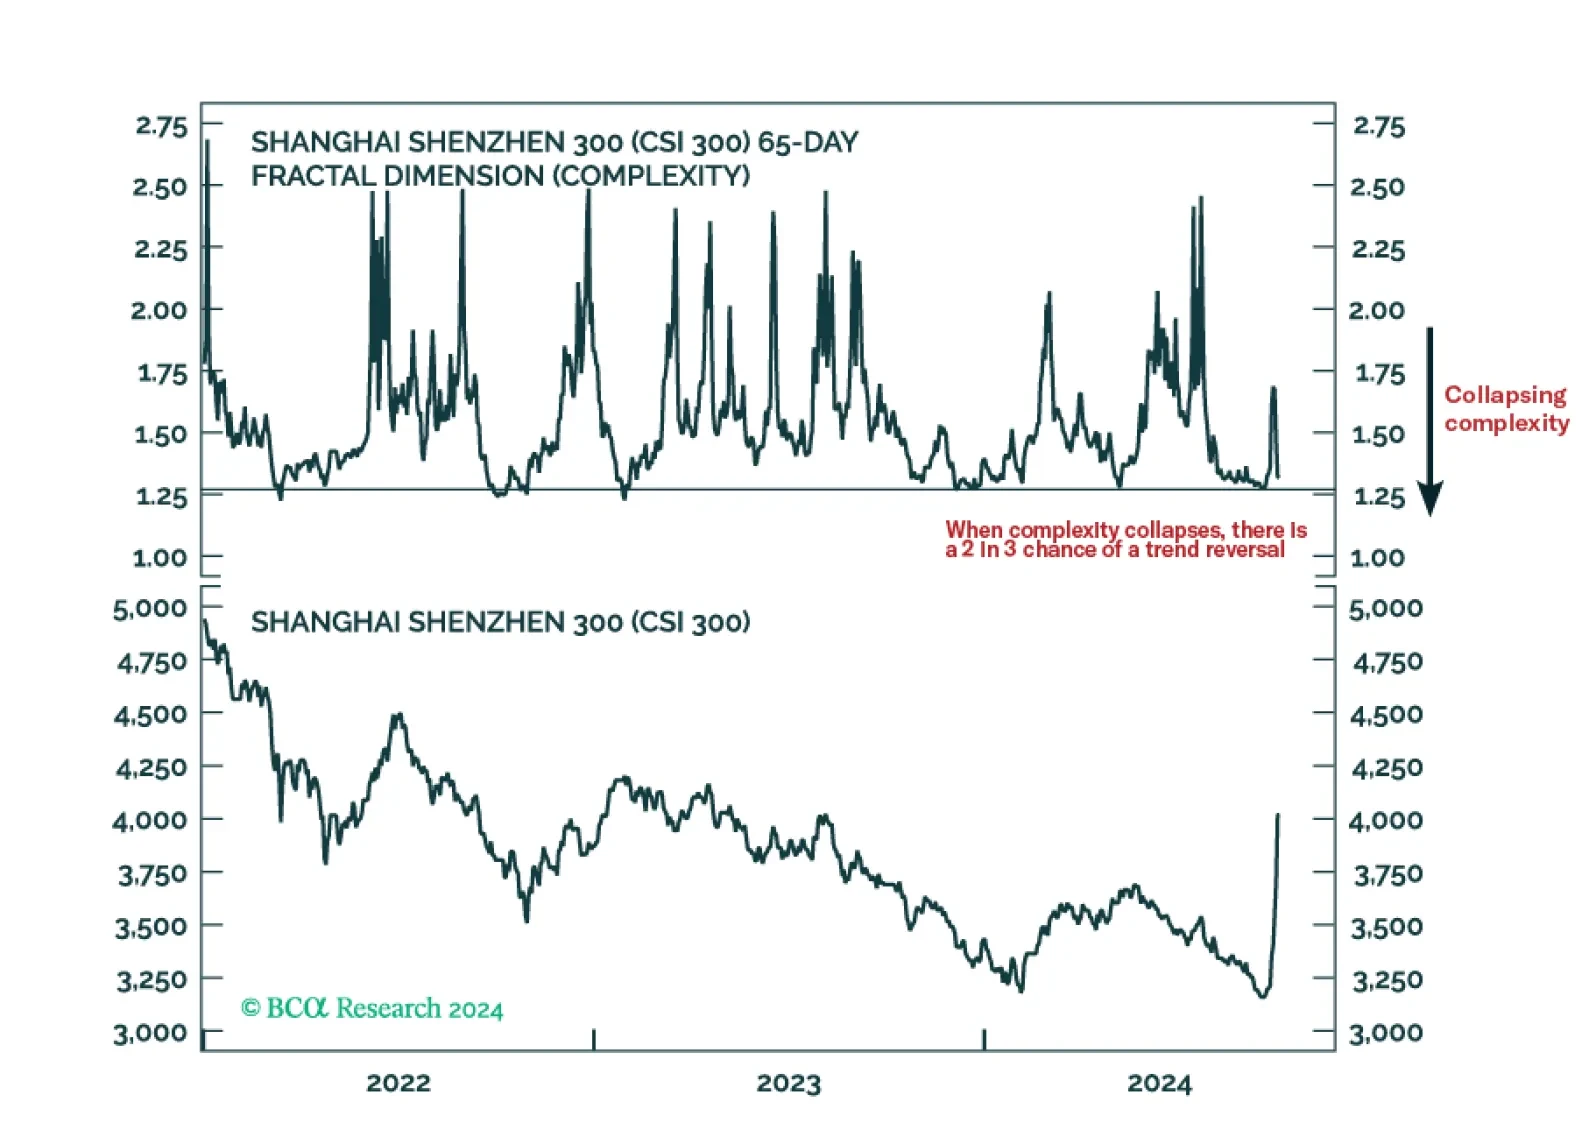
Absent the multi-decade housing and construction boom, China will be unable to generate the monster credit impulses that it did through 2000-20. Hence, the recent melt-up in Chinese stocks and China plays may last a few weeks more but is unlikely to be a rerun of the 2015 episode either in magnitude or in duration. We go through the tactical and longer-term investment implications. Plus, a new recommendation on a 6-month horizon is to go long USD/GBP.

The politically induced selloff in Mexican markets has gone too far. In our view, investor fears about the constitutional changes are largely unwarranted. These reforms will have little to no ramifications for the economy in the foreseeable future, and it is not clear to what extent they can undermine Mexican democracy. Moreover, the market riot is not justified by the country’s decent macro shape. All in all, Mexican markets will resume their outperformance versus their EM peers sooner rather than later.
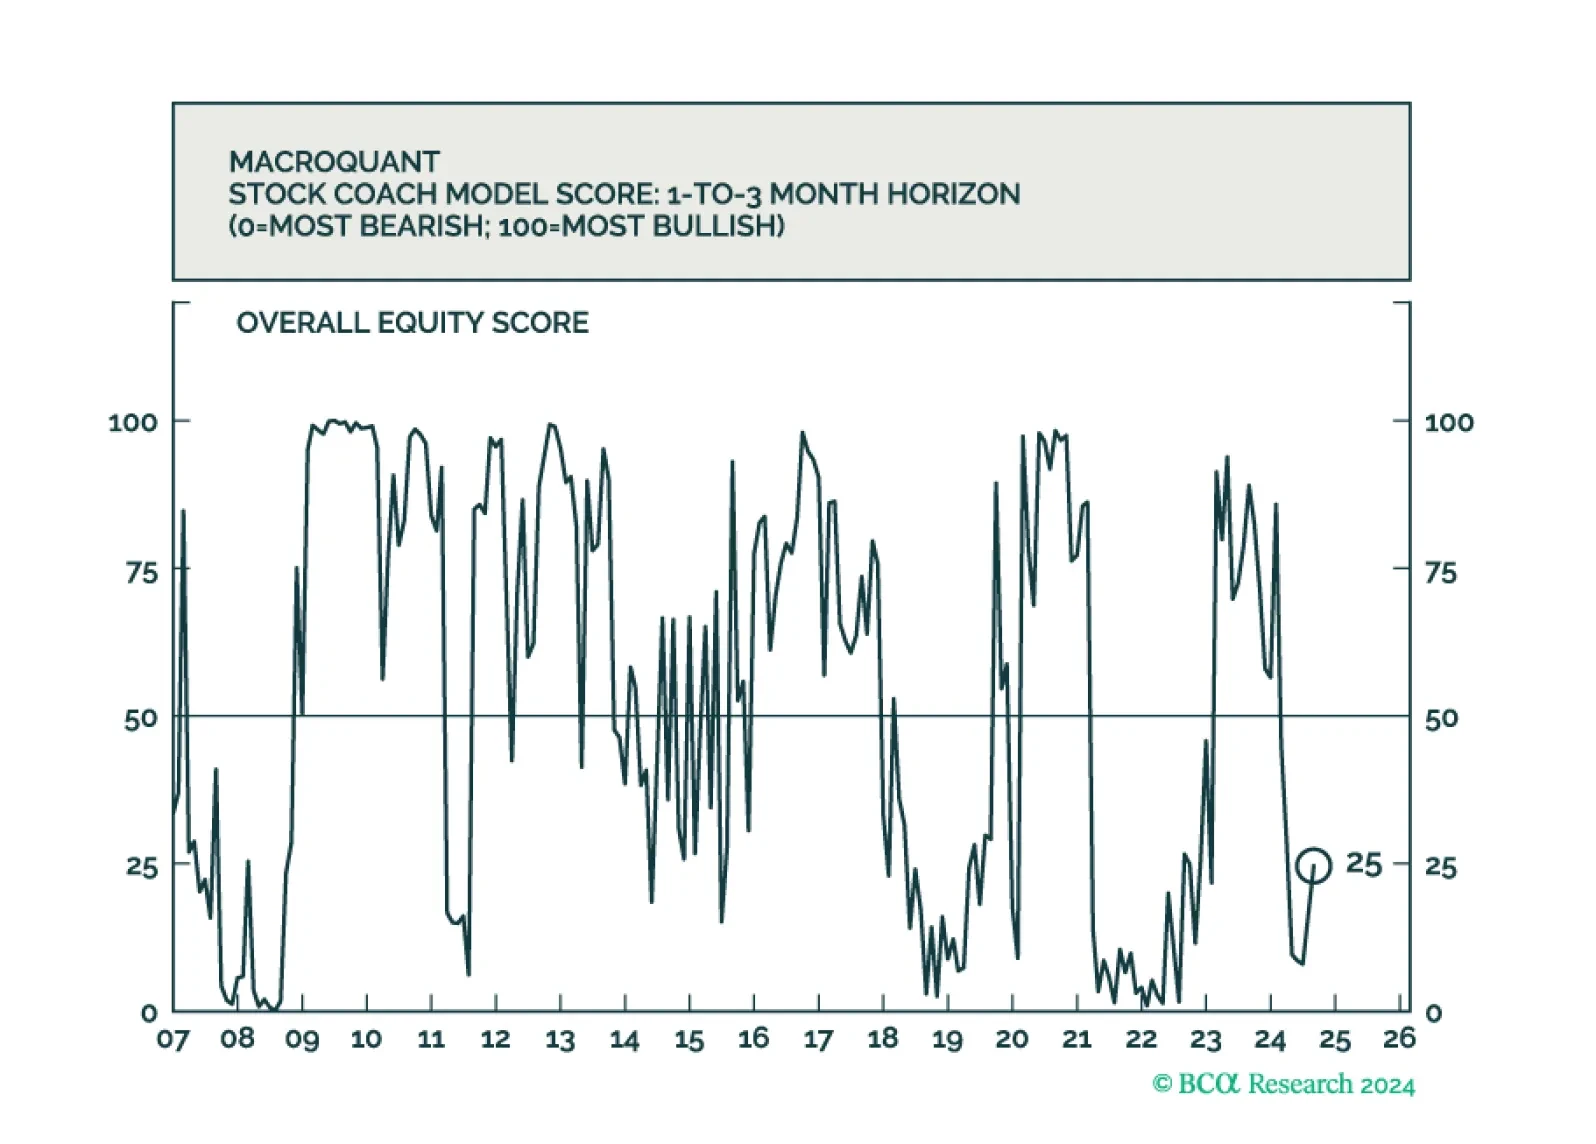
Despite the recent easing in financial conditions and hopes around Chinese stimulus, MacroQuant sees a heightened risk that the US will fall into a recession over the next 12 months. As such, it recommends an underweight to stocks, counterbalanced by an overweight to bonds.
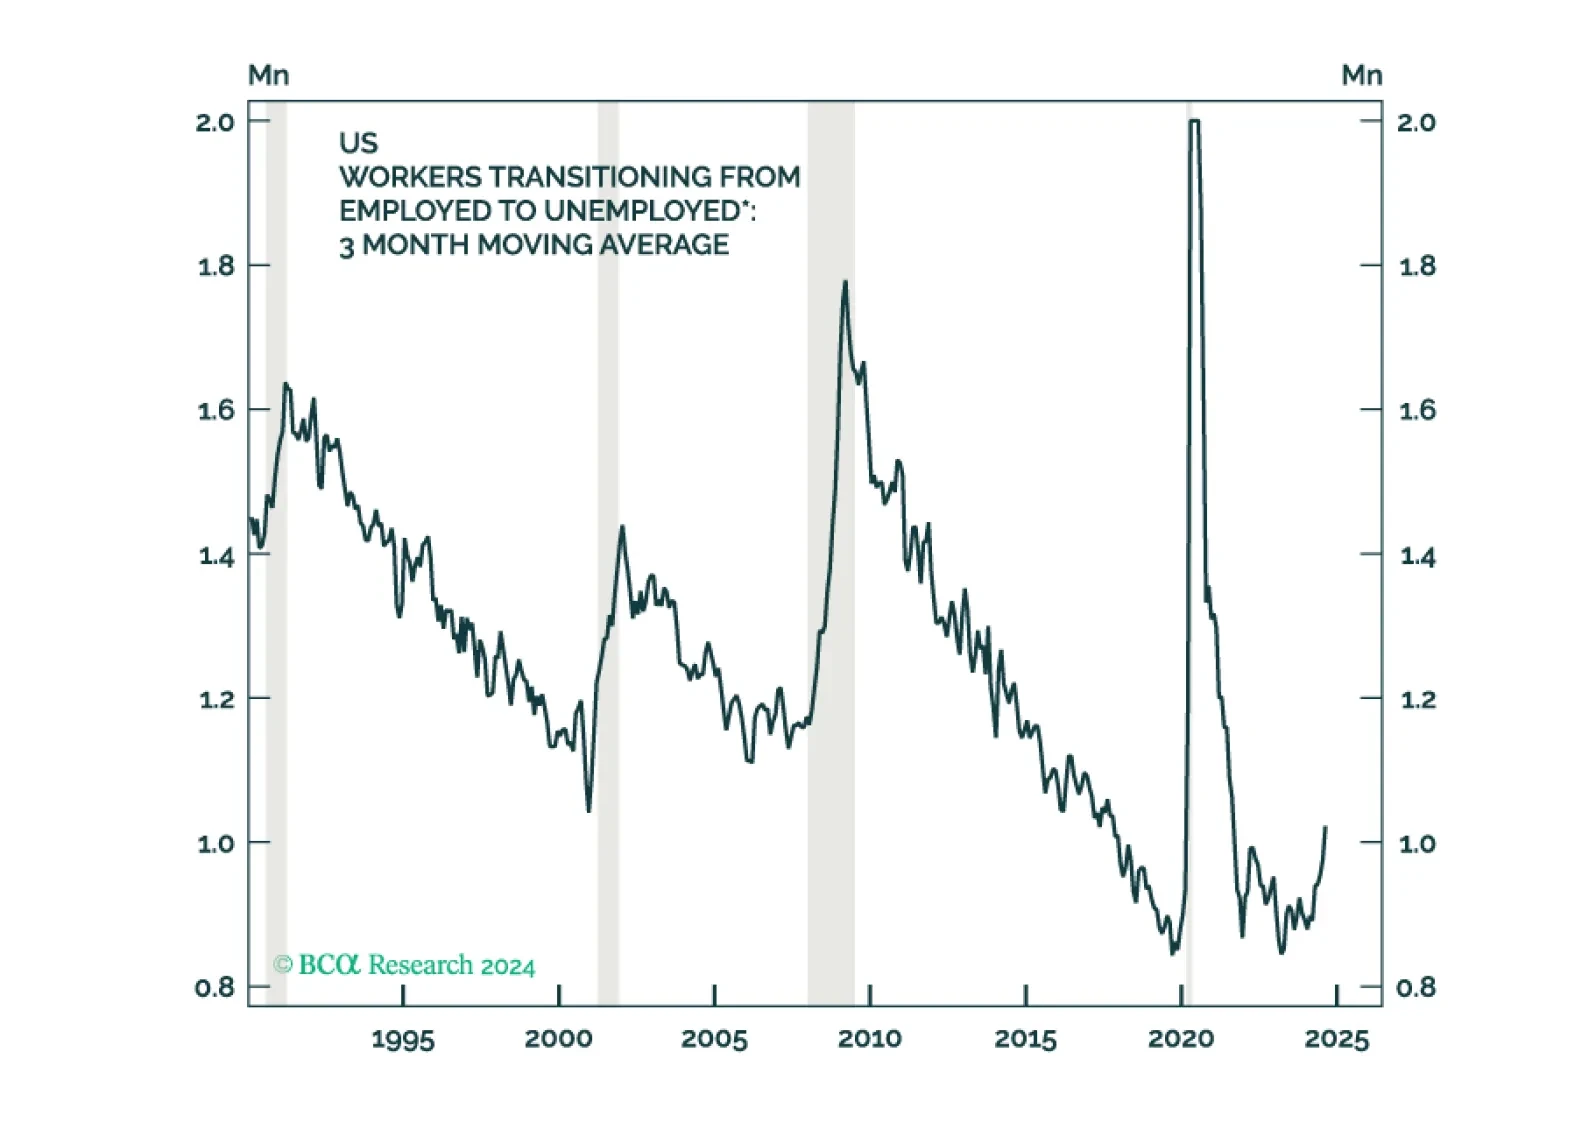
Back in 2022, when Jamie Dimon was predicting an economic hurricane, I was one of the few strategists reassuring clients that the US was not at imminent risk of a recession.
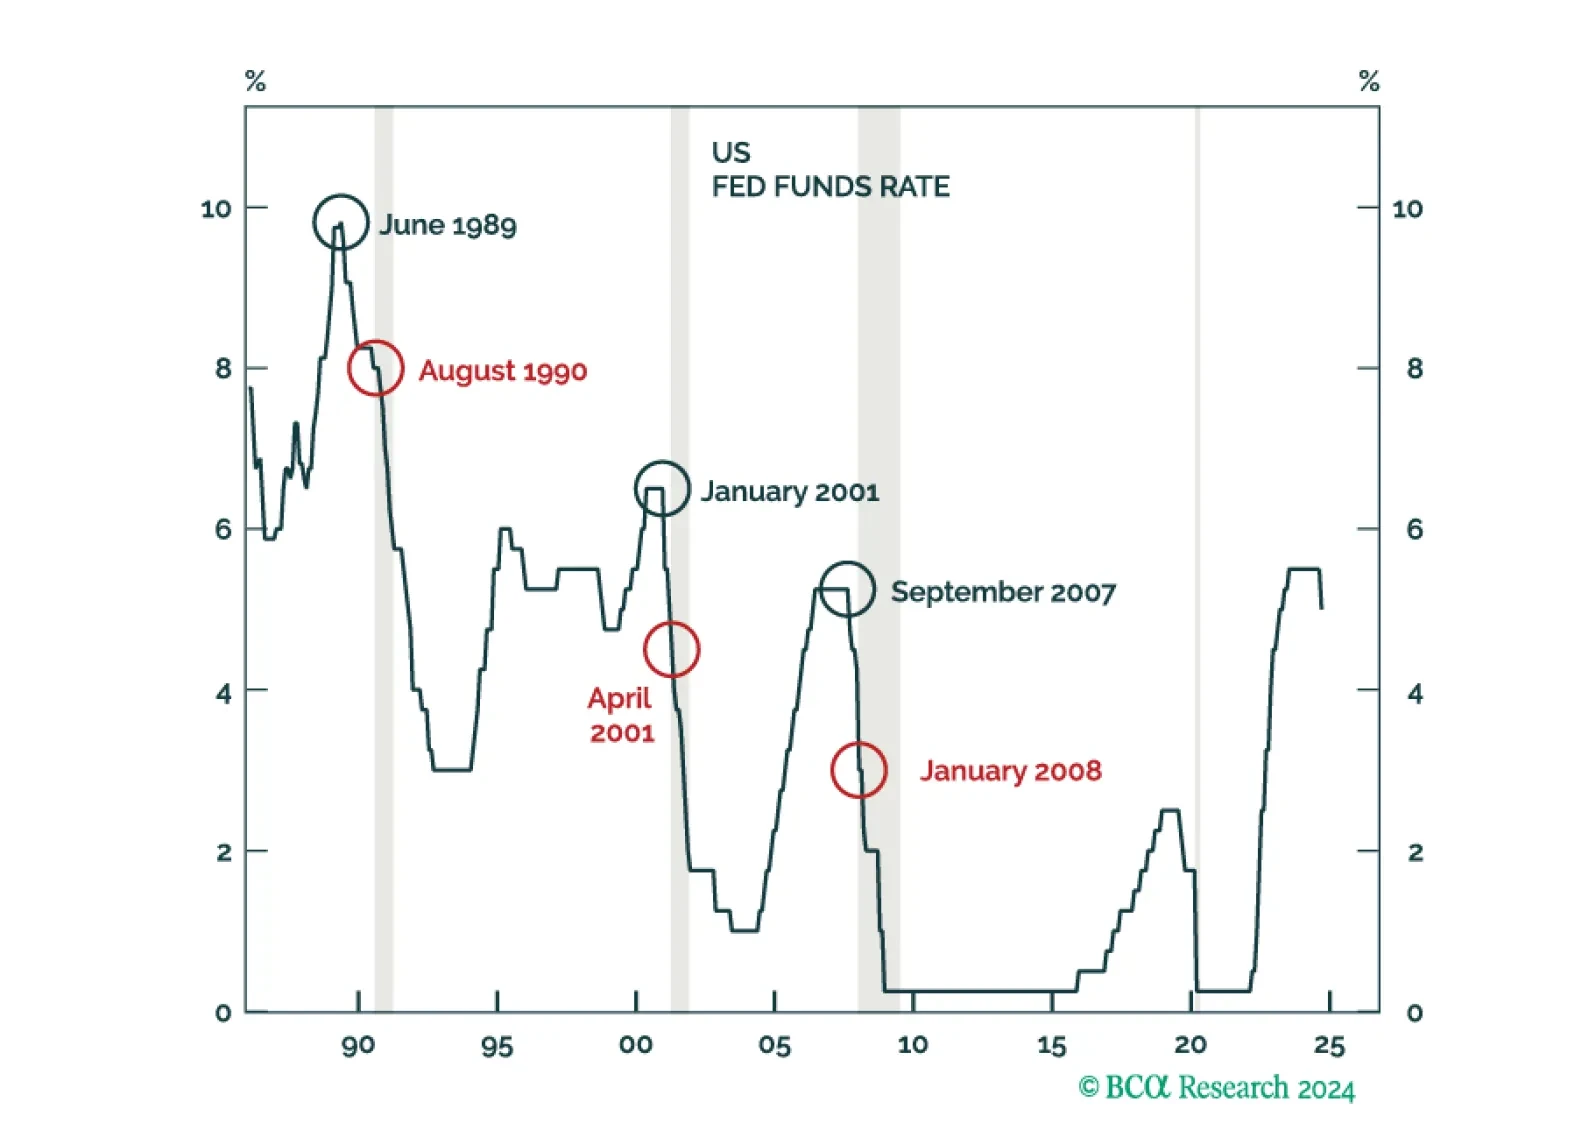
After resisting the consensus narrative in 2022 that a US recession was imminent, and then predicting an immaculate disinflation for 2023, the Global Investment Strategy team has joined the dark side and is now expecting a recession to start in the US within the next six months. Accordingly, we recommend that investors underweight stocks and overweight government bonds.
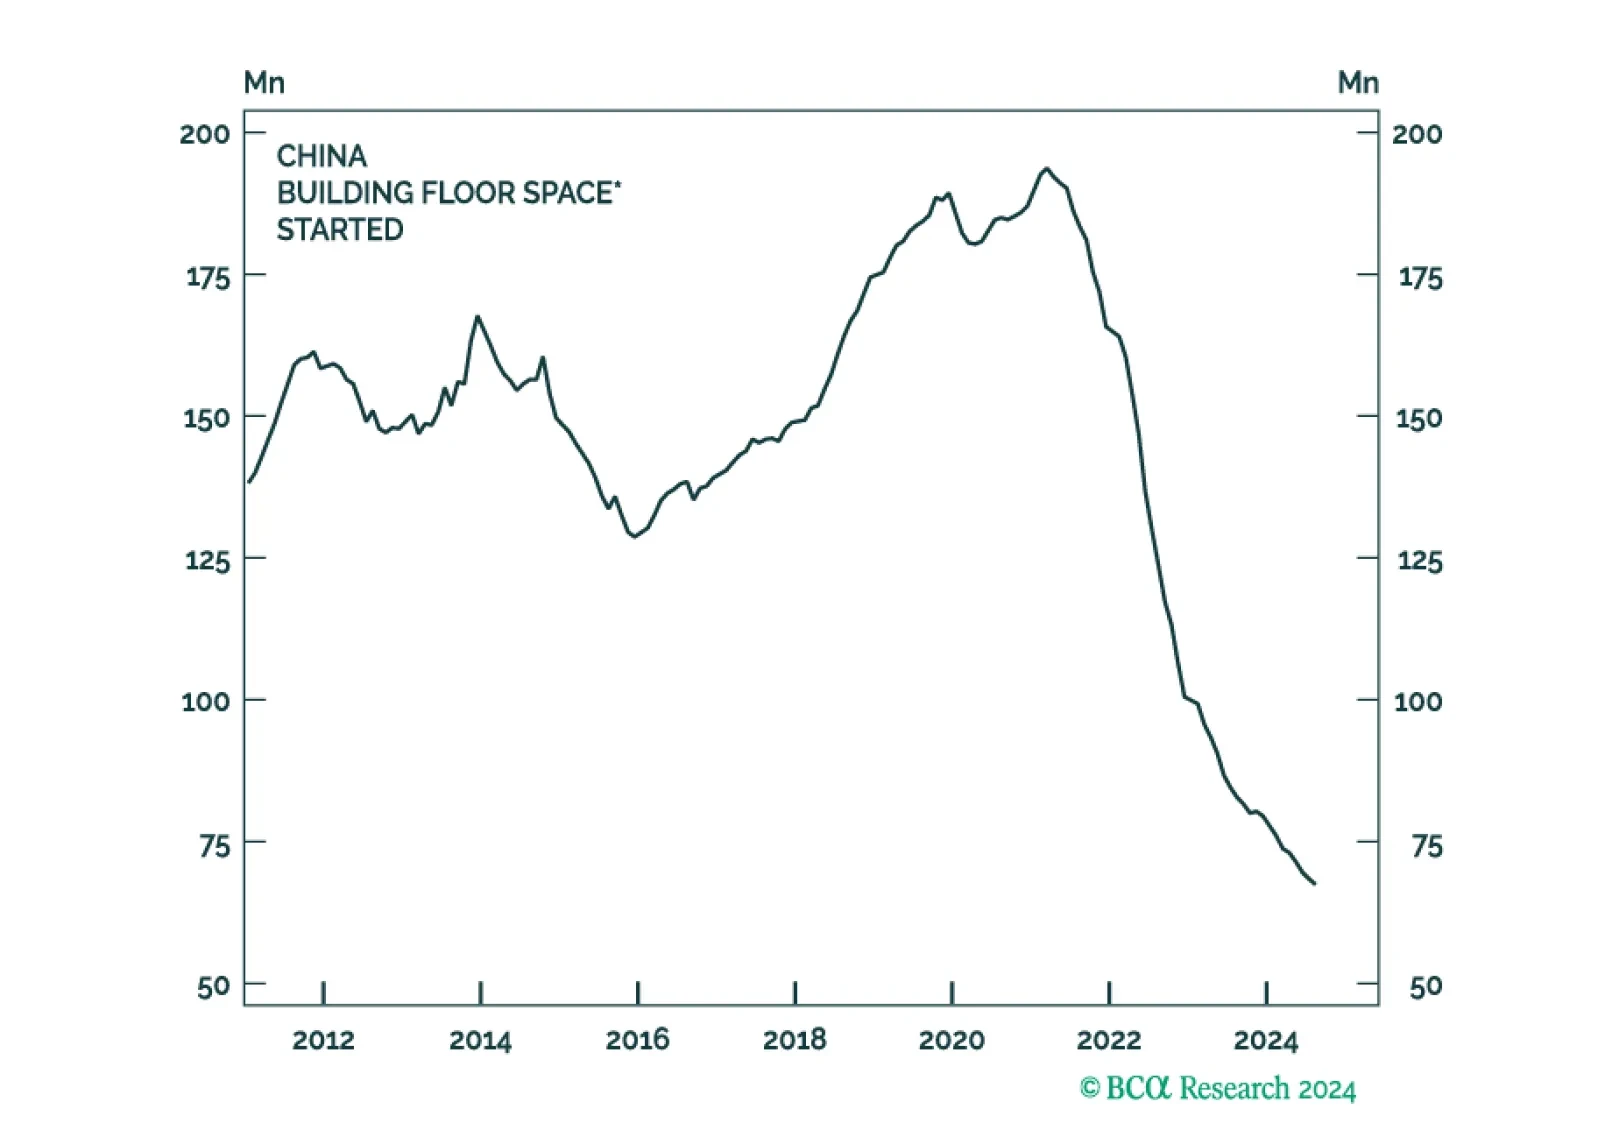
The Chinese government had no choice but to act this week. Housing starts are down 65% from their peak.