Skip to main content

Monetary Policy

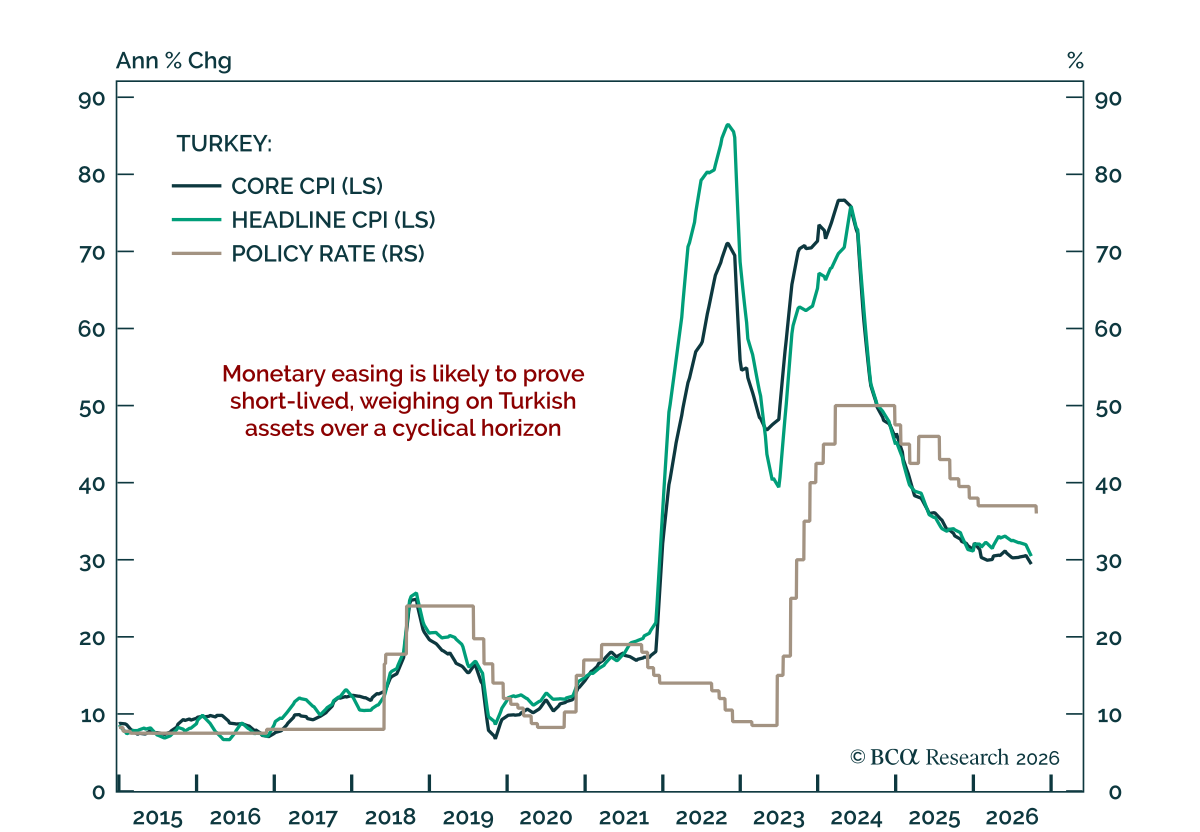
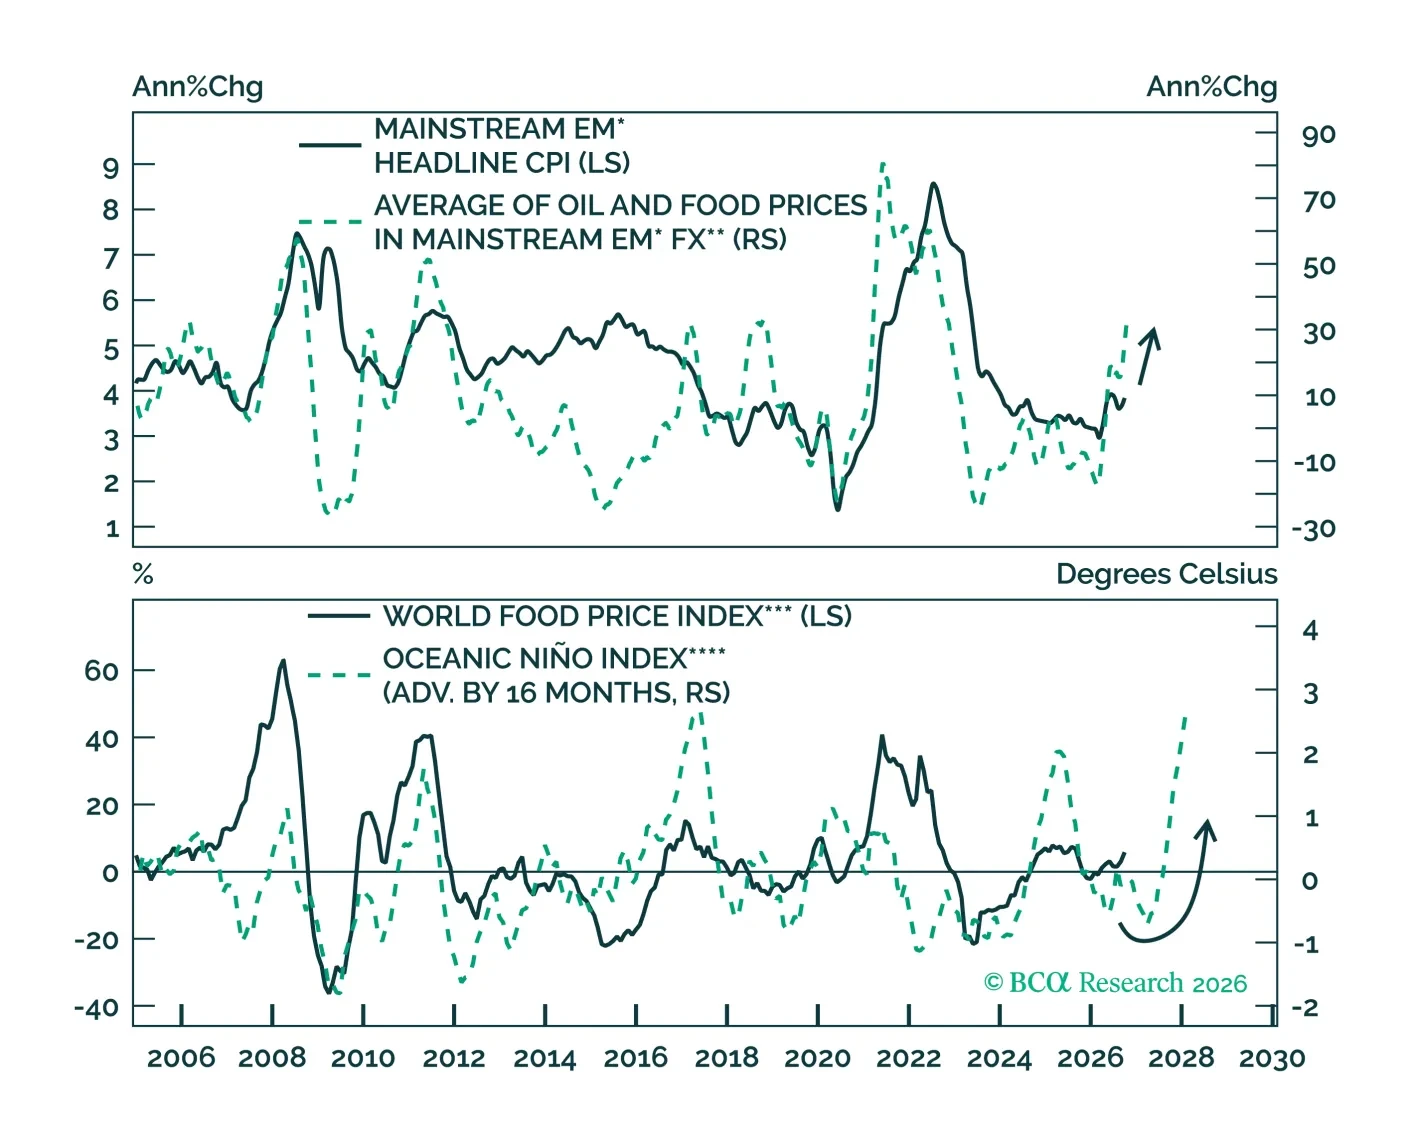
The Central Bank of Turkey cut its policy rate from 37% to 36% as inflation fell below 30% for the first time in about 5 years. Our Emerging Markets strategists believe that the slowdown in inflation and attendant monetary easing will be temporary. Weak…
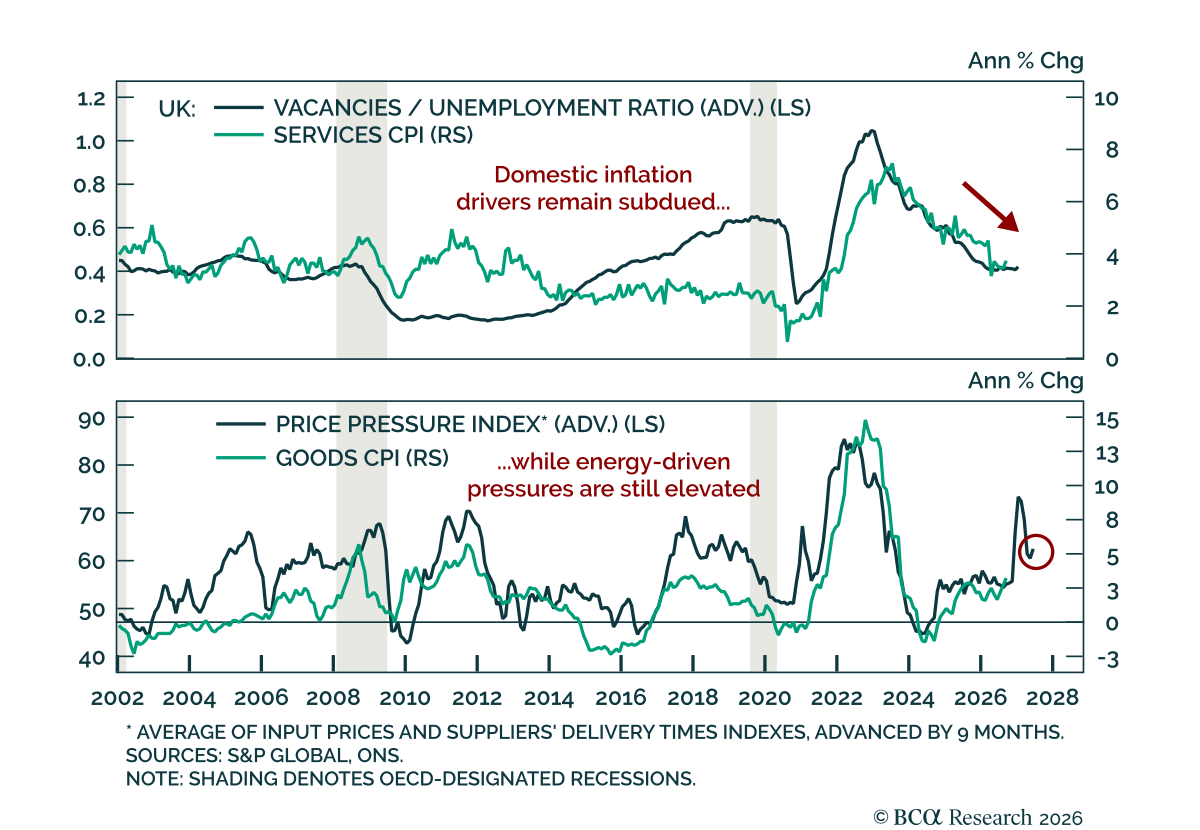
Hot September UK CPI will support BoE hawkishness in the near term, but investors should expect a dovish surprise over the next 12 months. Headline UK CPI rose to 3.5% y/y from 3.1%, which was above consensus. Core CPI rose to 2.8% from 2.6%, in line with…
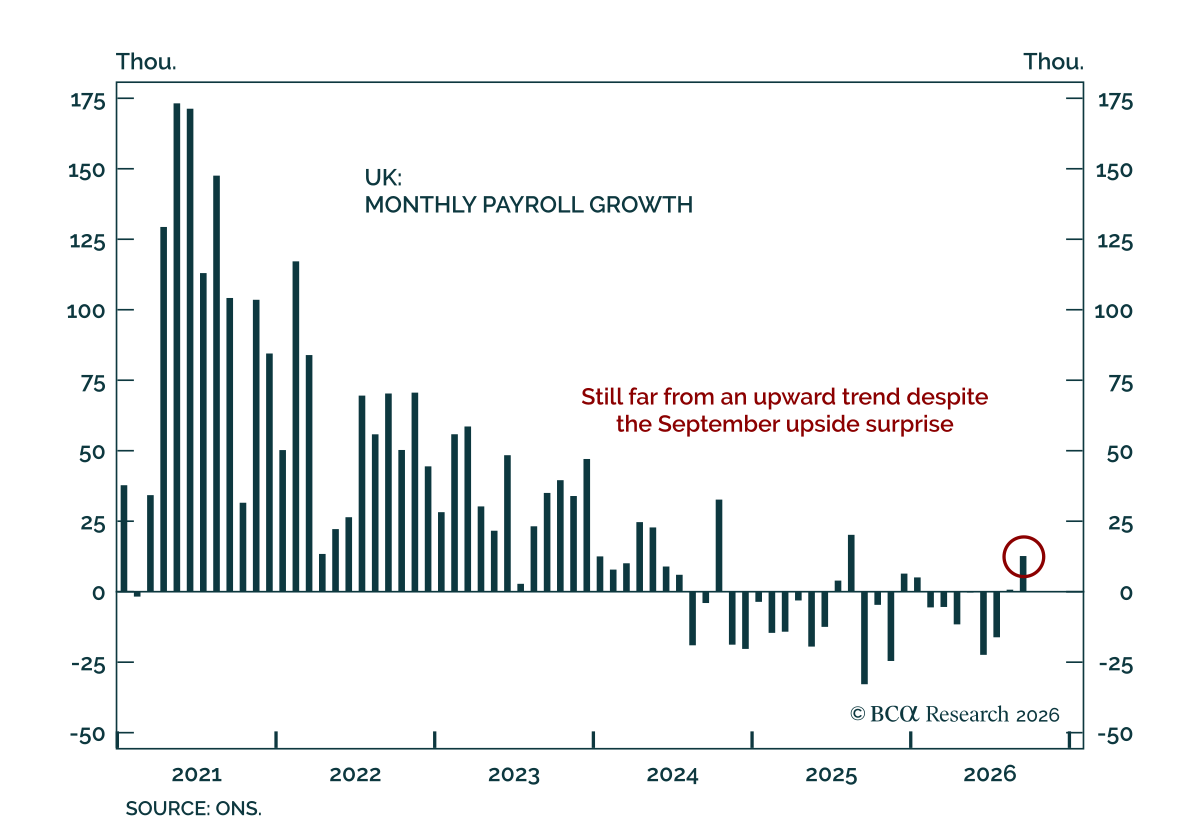
Despite a stronger-than-expected employment report, the BoE is unlikely to hike as much as markets anticipate. Payrolls rose by 13k in September against an expected decline, and August’s initially reported decline was revised to a gain. The unemployment rate…

EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
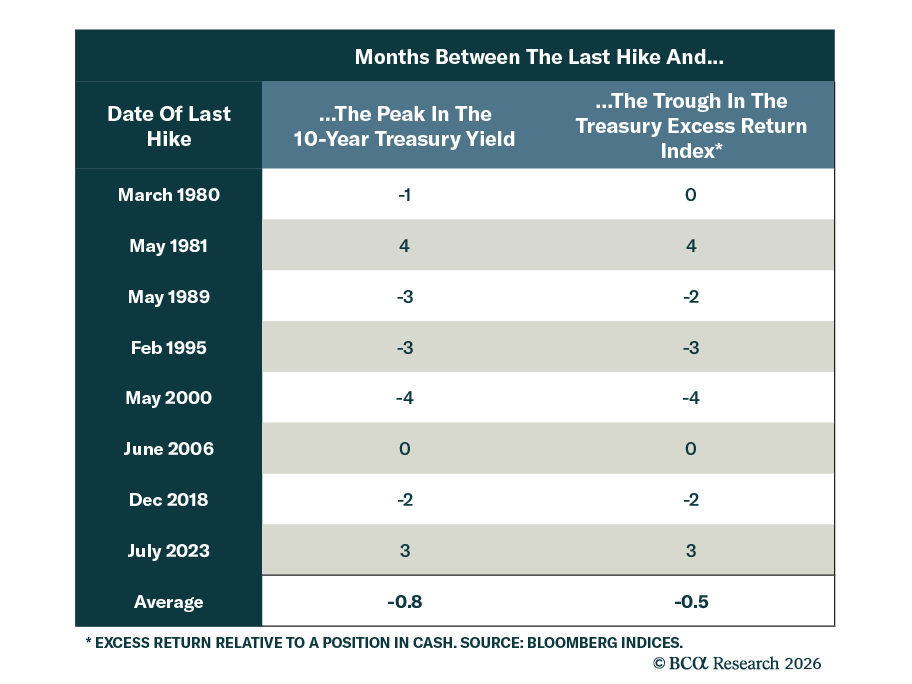
 

Investors should shift to a long duration stance in response to a further shift lower in inflation and/or a material tightening in financial conditions. Global government bond yields have surged since late August, and many investors are wondering whether a…
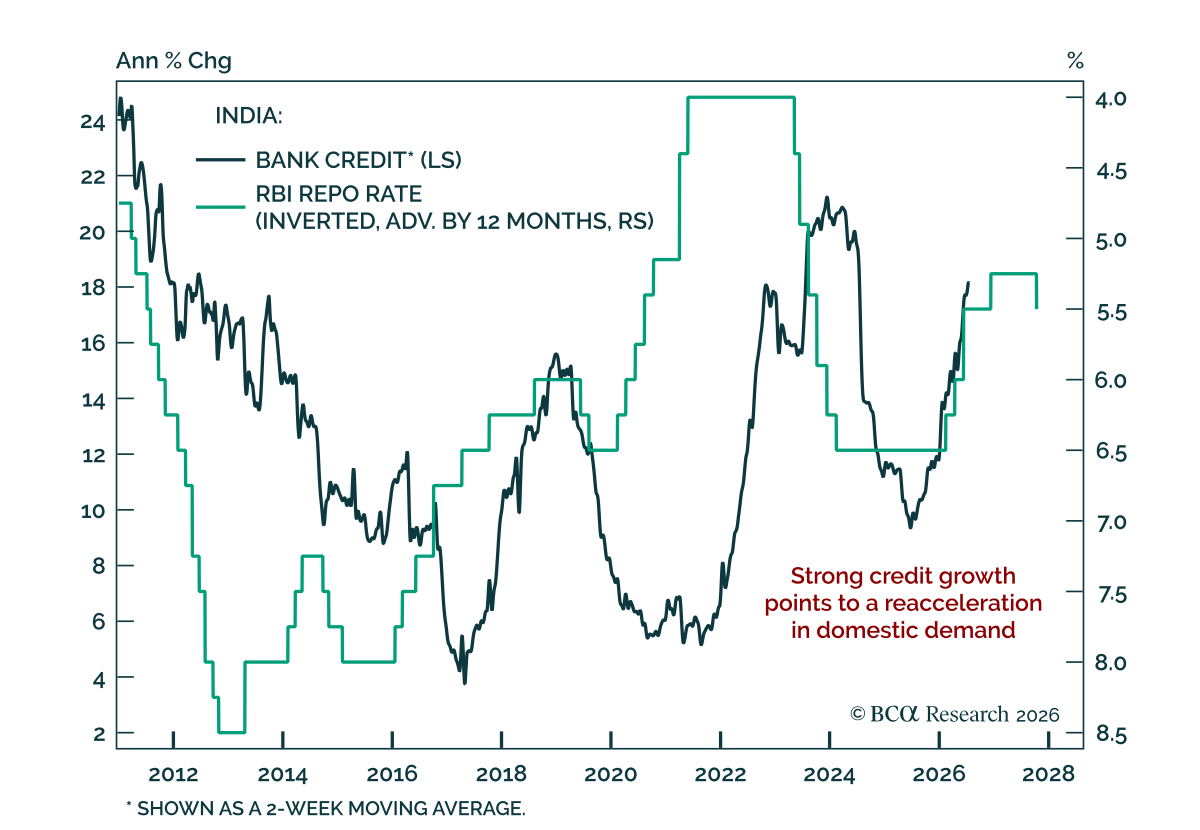
The RBI raised its repo rate to 5.50% amid expectations of reaccelerating inflation and a weakening INR. Our Emerging Markets strategists expect the reacceleration in inflation to be temporary, as the Indian economy has absorbed much of the shock from energy…
Our GeoMacro strategists remain bullish on equities and and long-term bulls on bonds. They caution investors against treating the recent rise in yields as a reason to turn defensive. Our colleagues held both calls over the past month. The equity call proved…

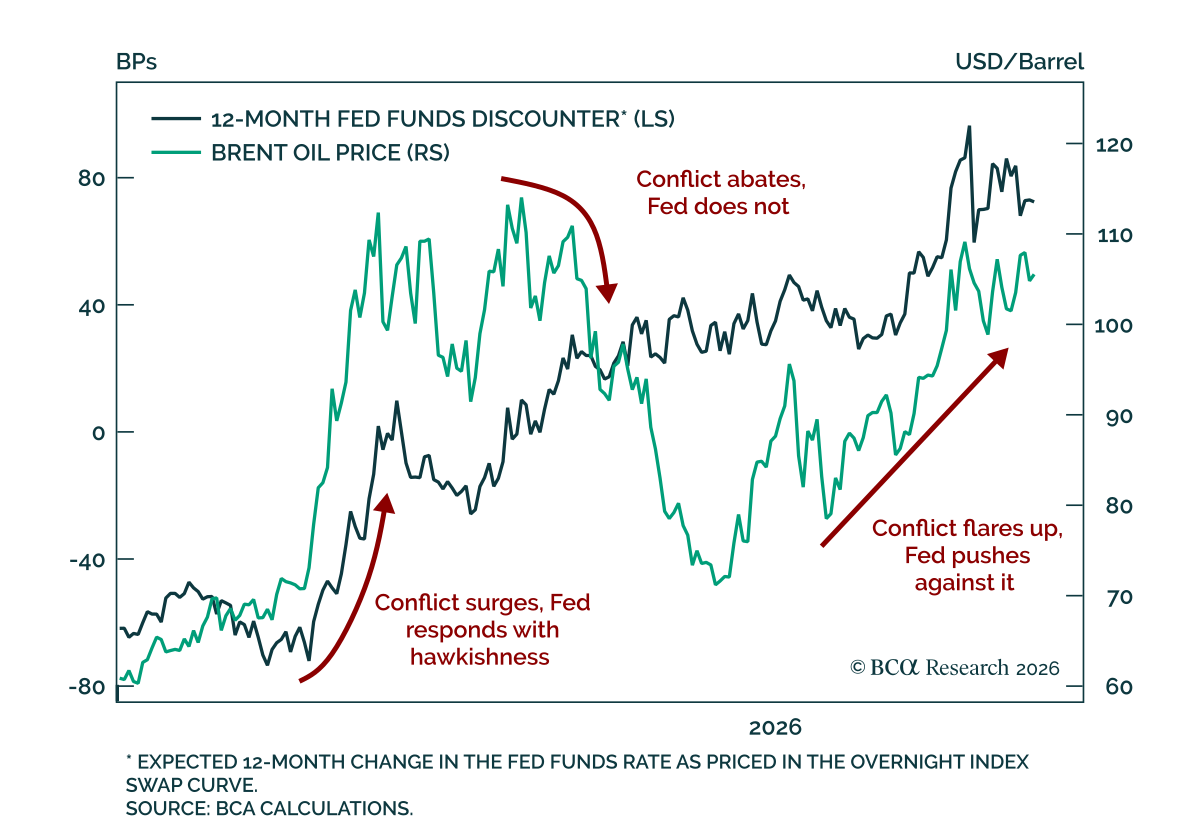
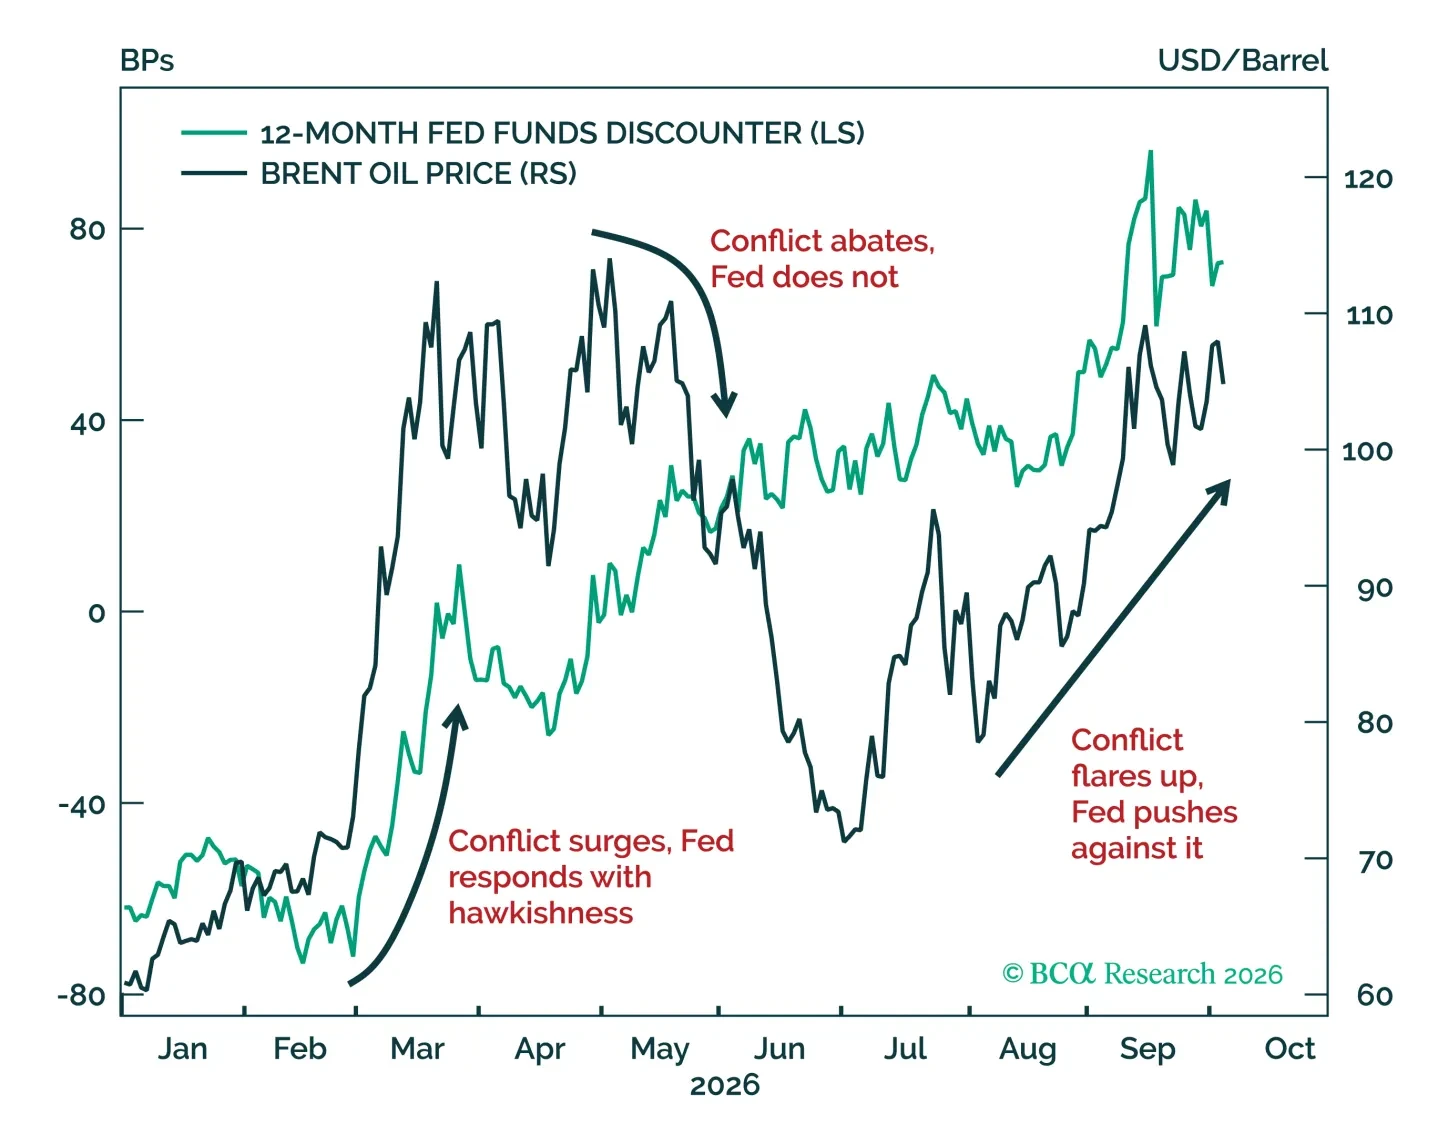
Long-dated bond yields rose another 48 bps since our last missive, quite a move in just a month. And yet, equities have remained resilient. This suggests that the move in bond yields is due to sanguine economic forces, not fiscal profligacy or inflation fears. In addition, the war in Iran is subsiding, partly because the Fed itself has conspired against it. Will President Trump restart the conflict regardless? Perhaps, however, the constraints are mounting against the White House foreign policy. We remain bullish on equities and reaffirm our view that investors with a long-term horizon should be nibbling at the current level of yields.

To make sure that our bearish clients are happy, we pivot to the risk of higher tax rates in the US. Specifically, we try to answer the question of when markets price higher tax rates.
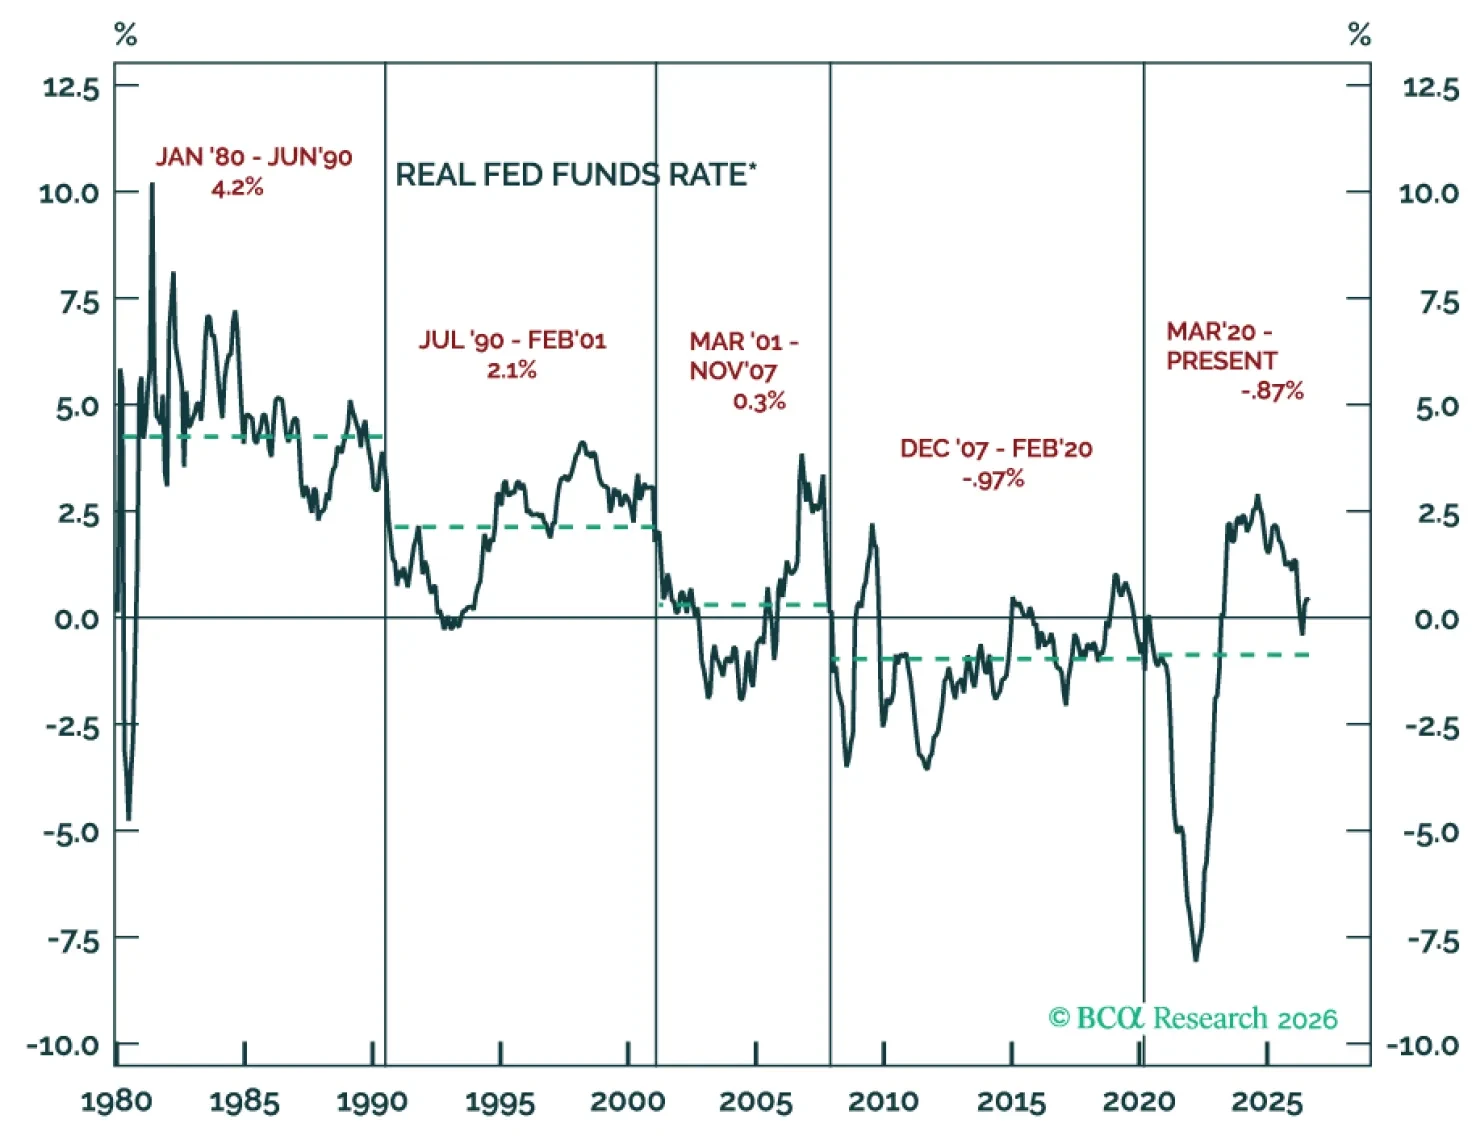
Rising rates don’t halt bull markets but real yields exceeding the economy’s potential long-run growth rate could. That relative level could lead to a stock-bond collision if it persisted long enough to slow the economy.
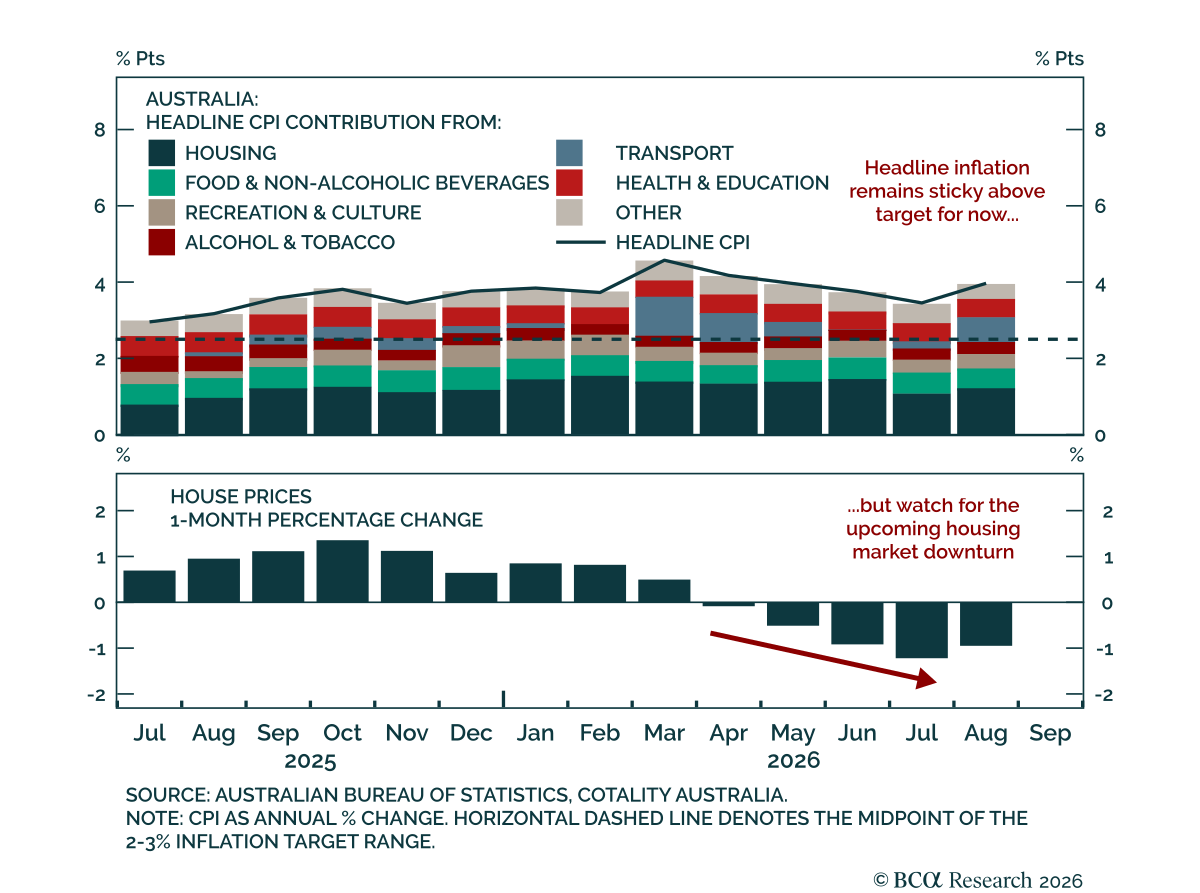
Australia's August CPI shows no sign of re-accelerating core inflation, suggesting a less aggressive RBA tightening than currently priced. Headline CPI rose less than expected in August, to 4.0% y/y from 3.5%, lifted by higher fuel prices in the transport…