Japan
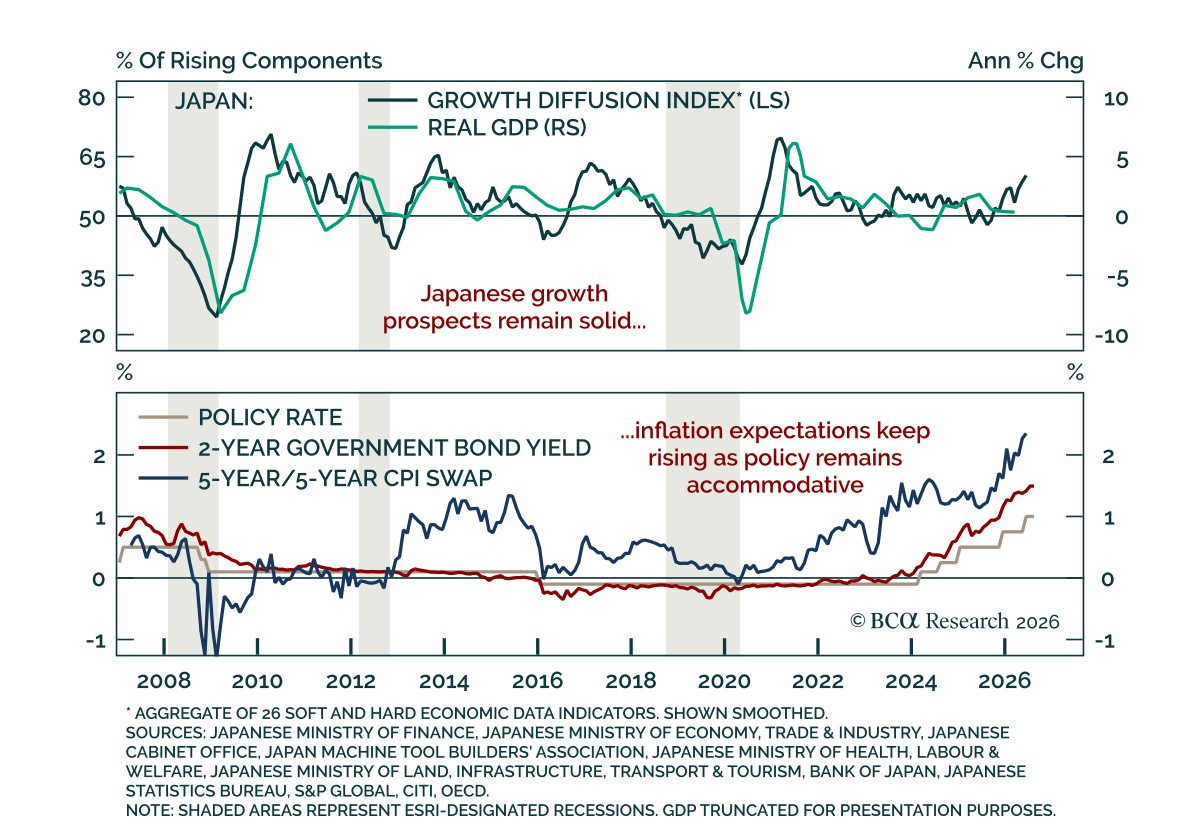

Over the past 10 years, Japan’s profit margin expansion has been driven neither by advances in labor productivity nor by operational efficiency gains, but by massive currency devaluation and lower depreciation charges. Going forward, higher wages and unit labor costs, as well as currency appreciation, will become major headwinds to margins.
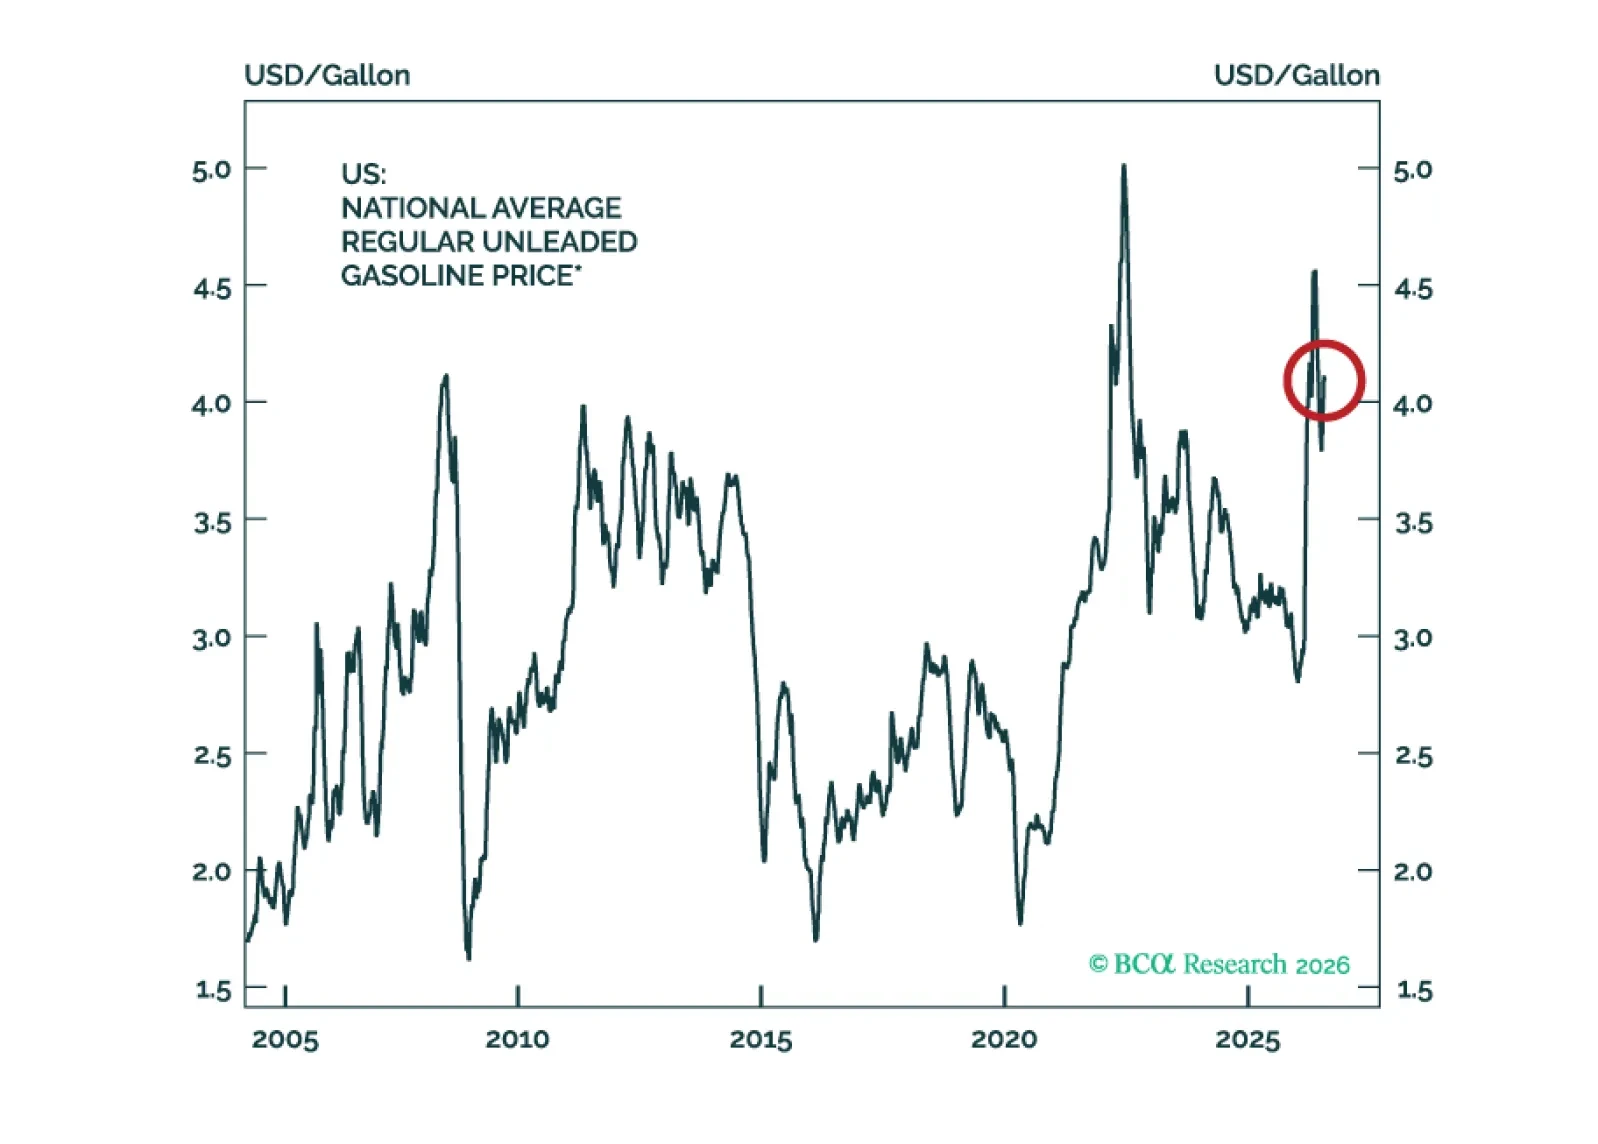
Section I outlines BCA’s views on the US-Iran conflict, Europe’s near-term outlook, the currency and bond selloffs in Japan and the early days of the Warsh Fed. In Section II, Roukaya, Matt, and Artem argue that the worst of gold's downturn is likely behind us. Real rates and the dollar — which have reasserted themselves as gold's primary drivers — are set to shift from headwinds to tailwinds for the metal.

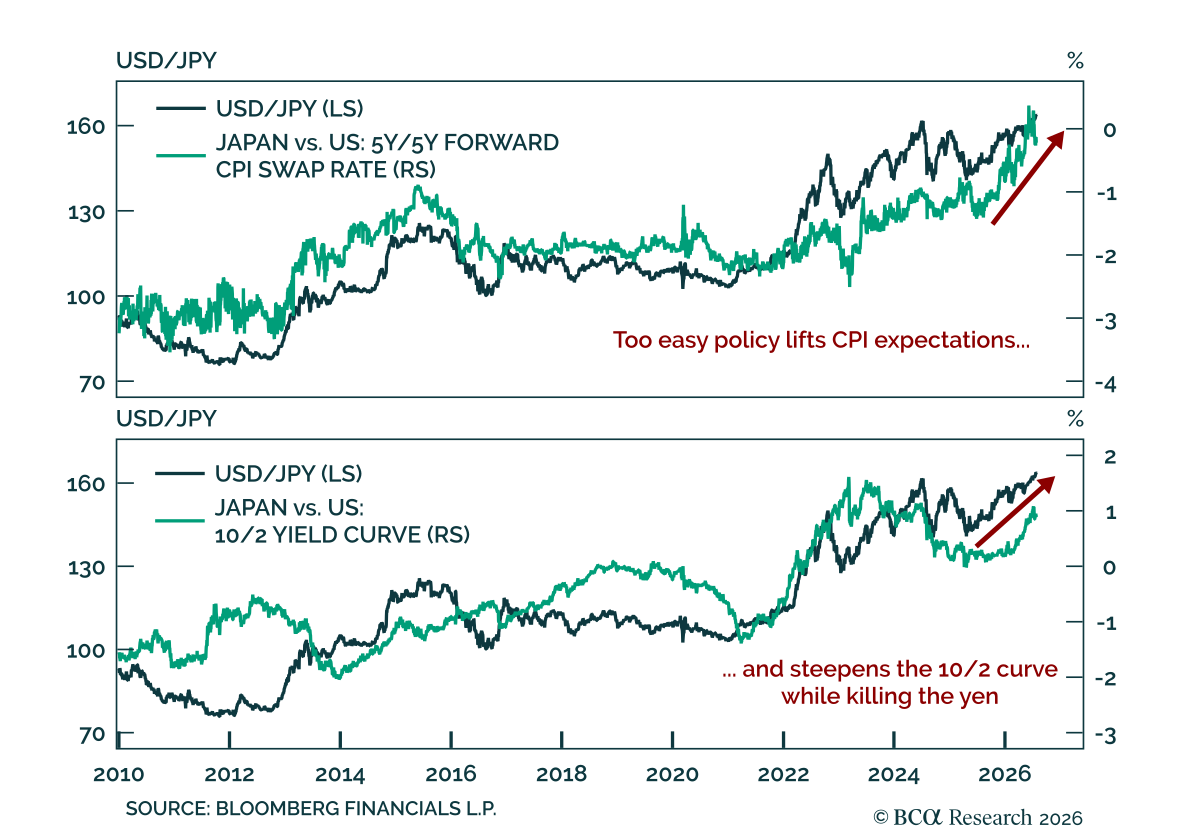

Yen weakness and rising JGB yields aren't a fiscal crisis; they're a market pricing an overheating economy and a BoJ falling behind the inflation curve. We lay out why the endgame is near, and what to watch before buying the yen this winter.


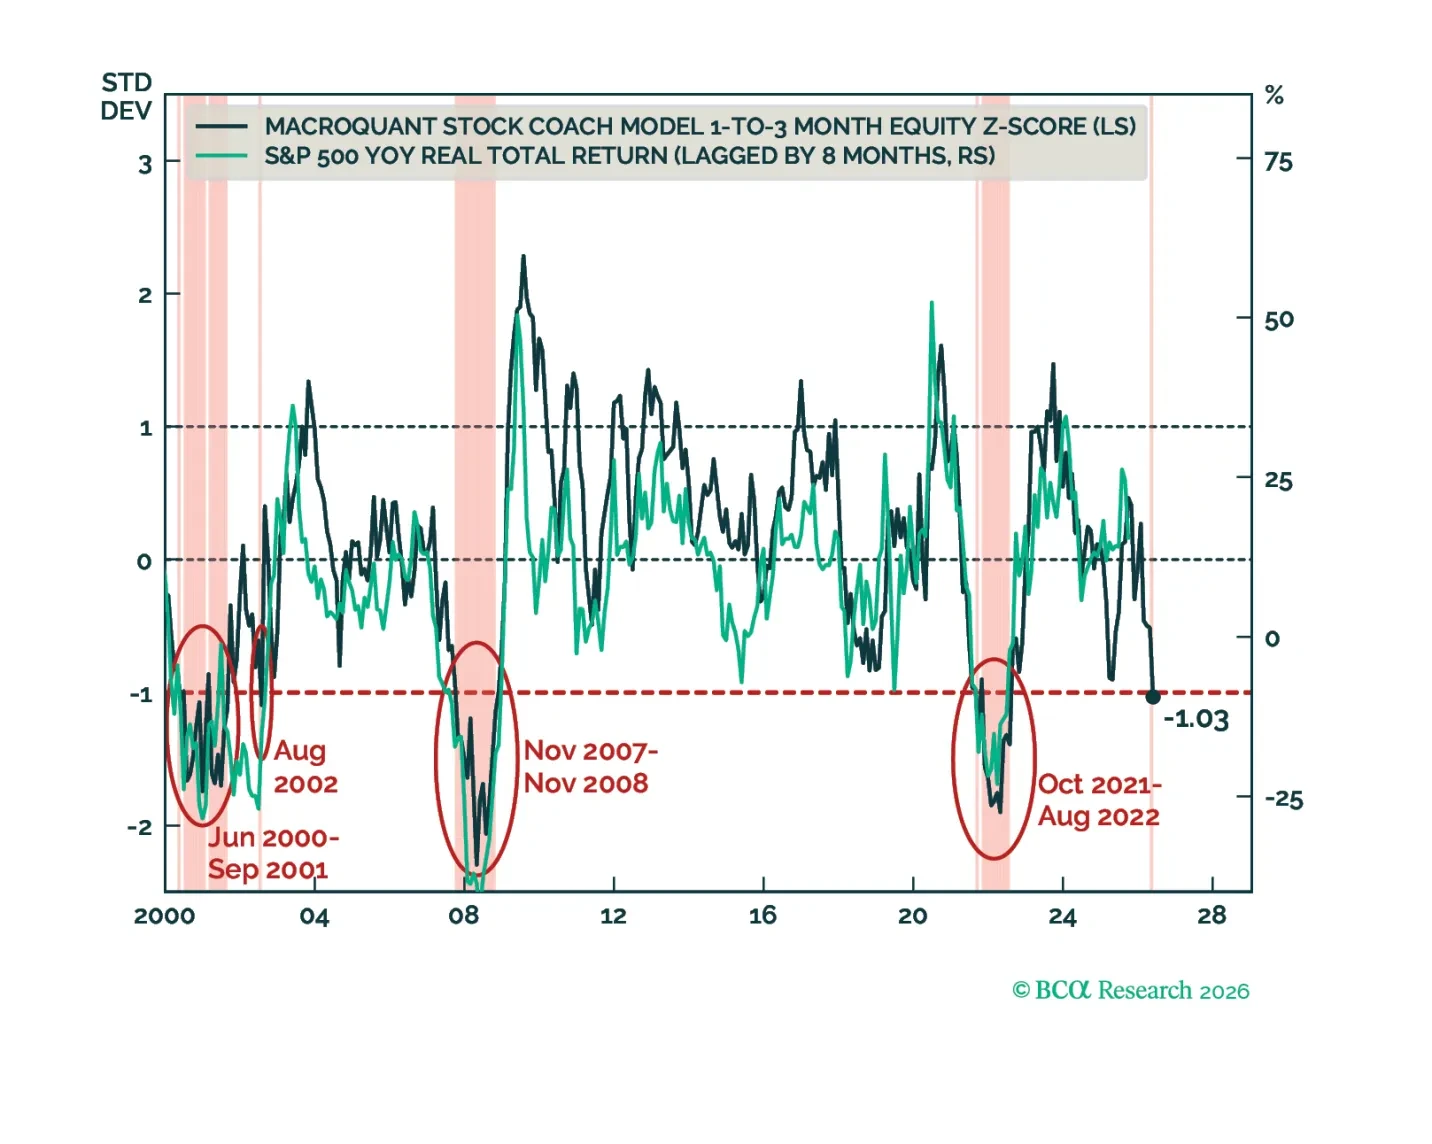
The equity bull market is getting long in the tooth. Bonds should perform well once economic growth begins to slow. The dollar will strengthen over the coming months before resuming its downtrend. While crude has likely found a near-term floor, we favor metals over energy in the long run.