Inflation/Deflation

Results of the New York Fed’s Survey of Consumer Expectations showed an uptick in medium- and long-term inflation expectations in February. Specifically, the three-year ahead measure rebounded from a record low of 2.4% to 2.7% and the five-year ahead gauge…
The US employment situation report sent a mixed signal on Friday. While total nonfarm payrolls rose by 275 thousand jobs in February, exceeding the 200 thousand expected, the previous two months’ numbers were revised lower by 167 thousand jobs (see Indicator…
Japanese equities and government bonds sold off on Monday and the yen strengthened following the release of the revised Q4 GDP report showing the economy expanded by an annualized 0.4% q/q in Q4 2023 versus earlier estimates of a 0.4% contraction. A…
According to BCA Research’s European Investment Strategy service, last week’s ECB meeting confirmed their long-held view that the most likely date for the first ECB rate cut would be June. The ECB continues to acknowledge that the European economy is soft and…
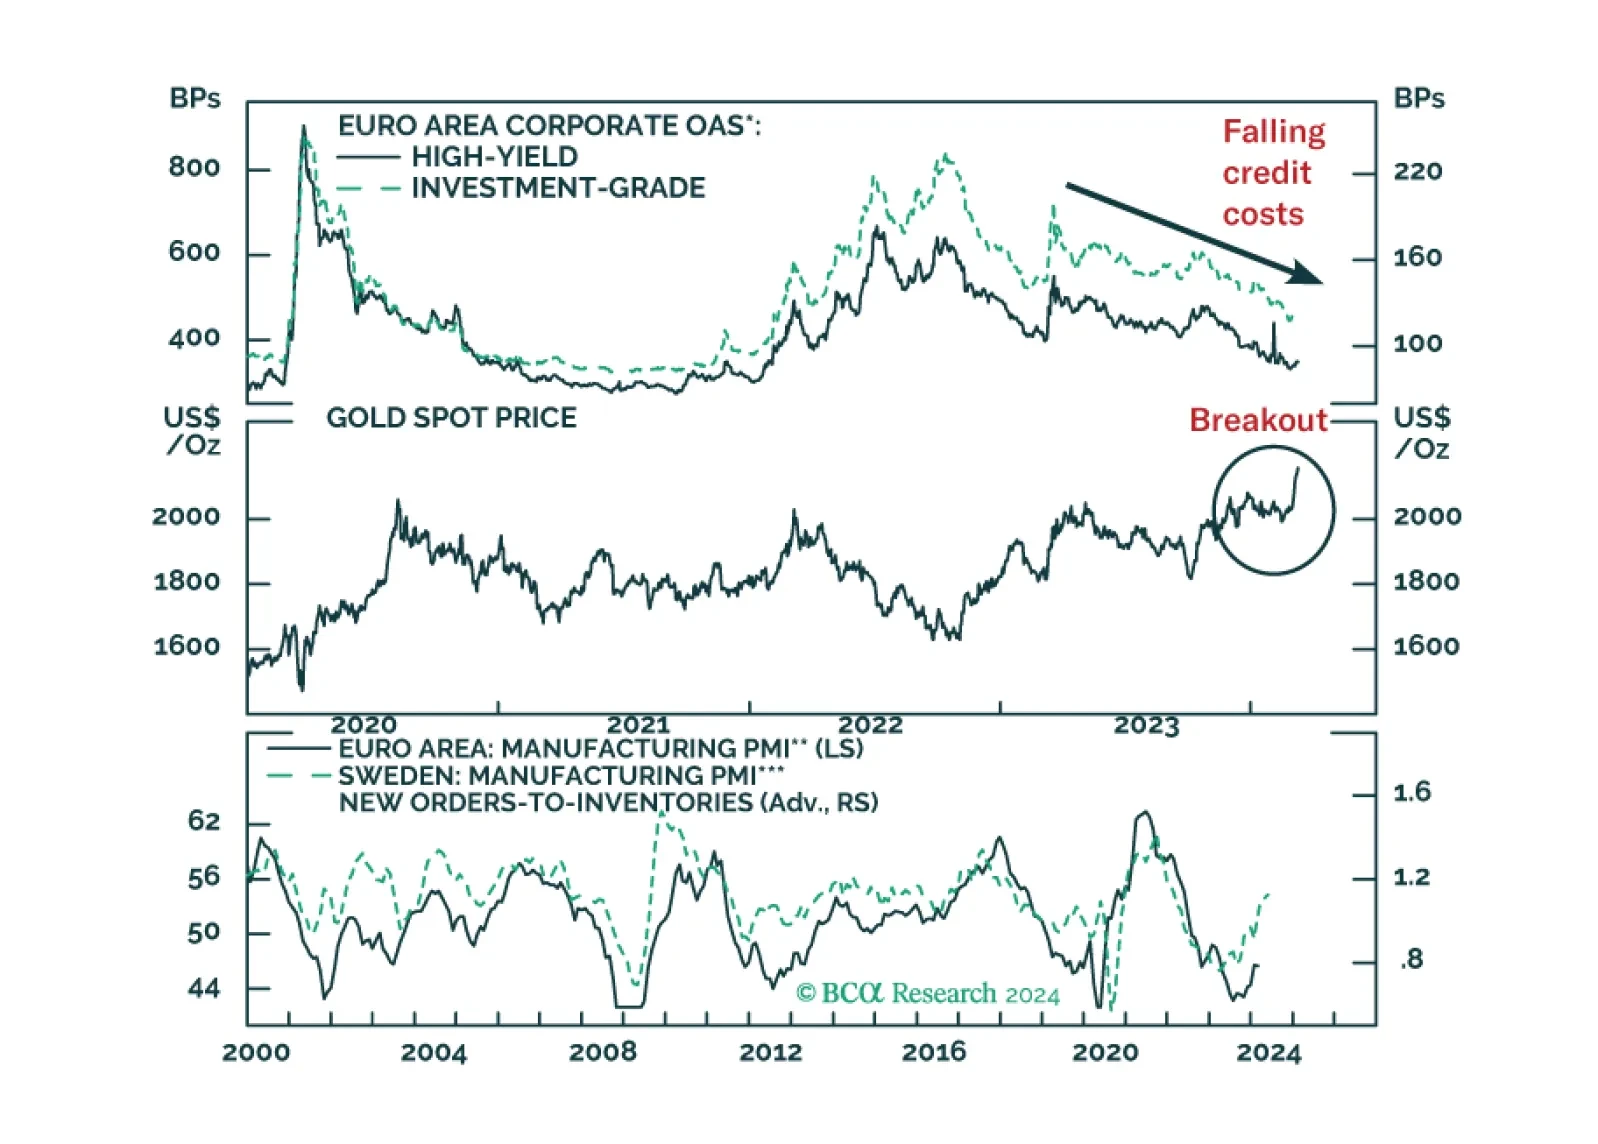
We are pushing back the anticipated start date for a Eurozone recession and assessing how it affects our equity stance.
As we discussed in a recent Insight, the krone is the top pick for our Foreign Exchange Strategy team. The krone upgrade is one of the most significant changes in our colleagues’ attractiveness ranking model. Norway has the perfect storm of sticky inflation,…
Our Emerging Markets Strategy team posits that the South African economy is heading into a recession later this year. The South African government refrained from announcing any stimulus measures in its recent budget proposals. The fiscal plan for 2024-25…
According to Factset, analysts are forecasting S&P 500 earnings and revenues to grow by 11.0% y/y and 5.0% y/y respectively in 2024 (an acceleration from 0.9% and 2.8% in 2023). Information technology and communications services (broadly-defined tech) are…
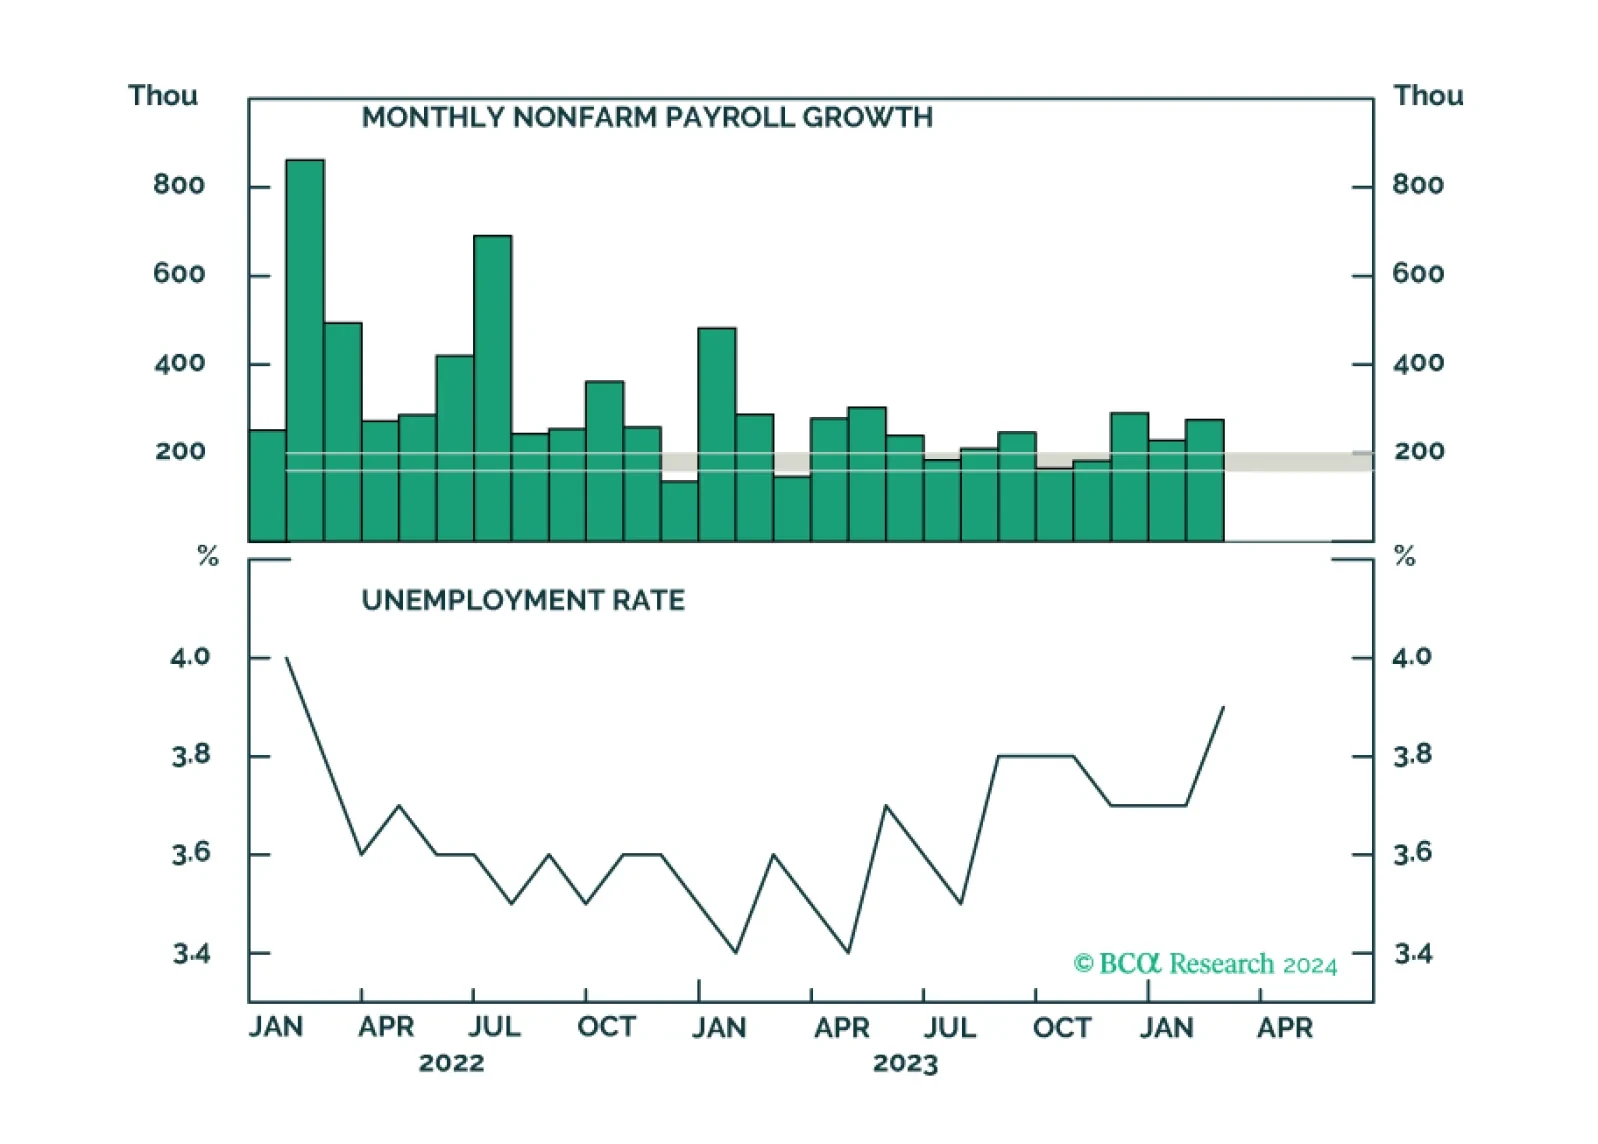
We update the indicators in our duration checklist following this morning’s employment report.
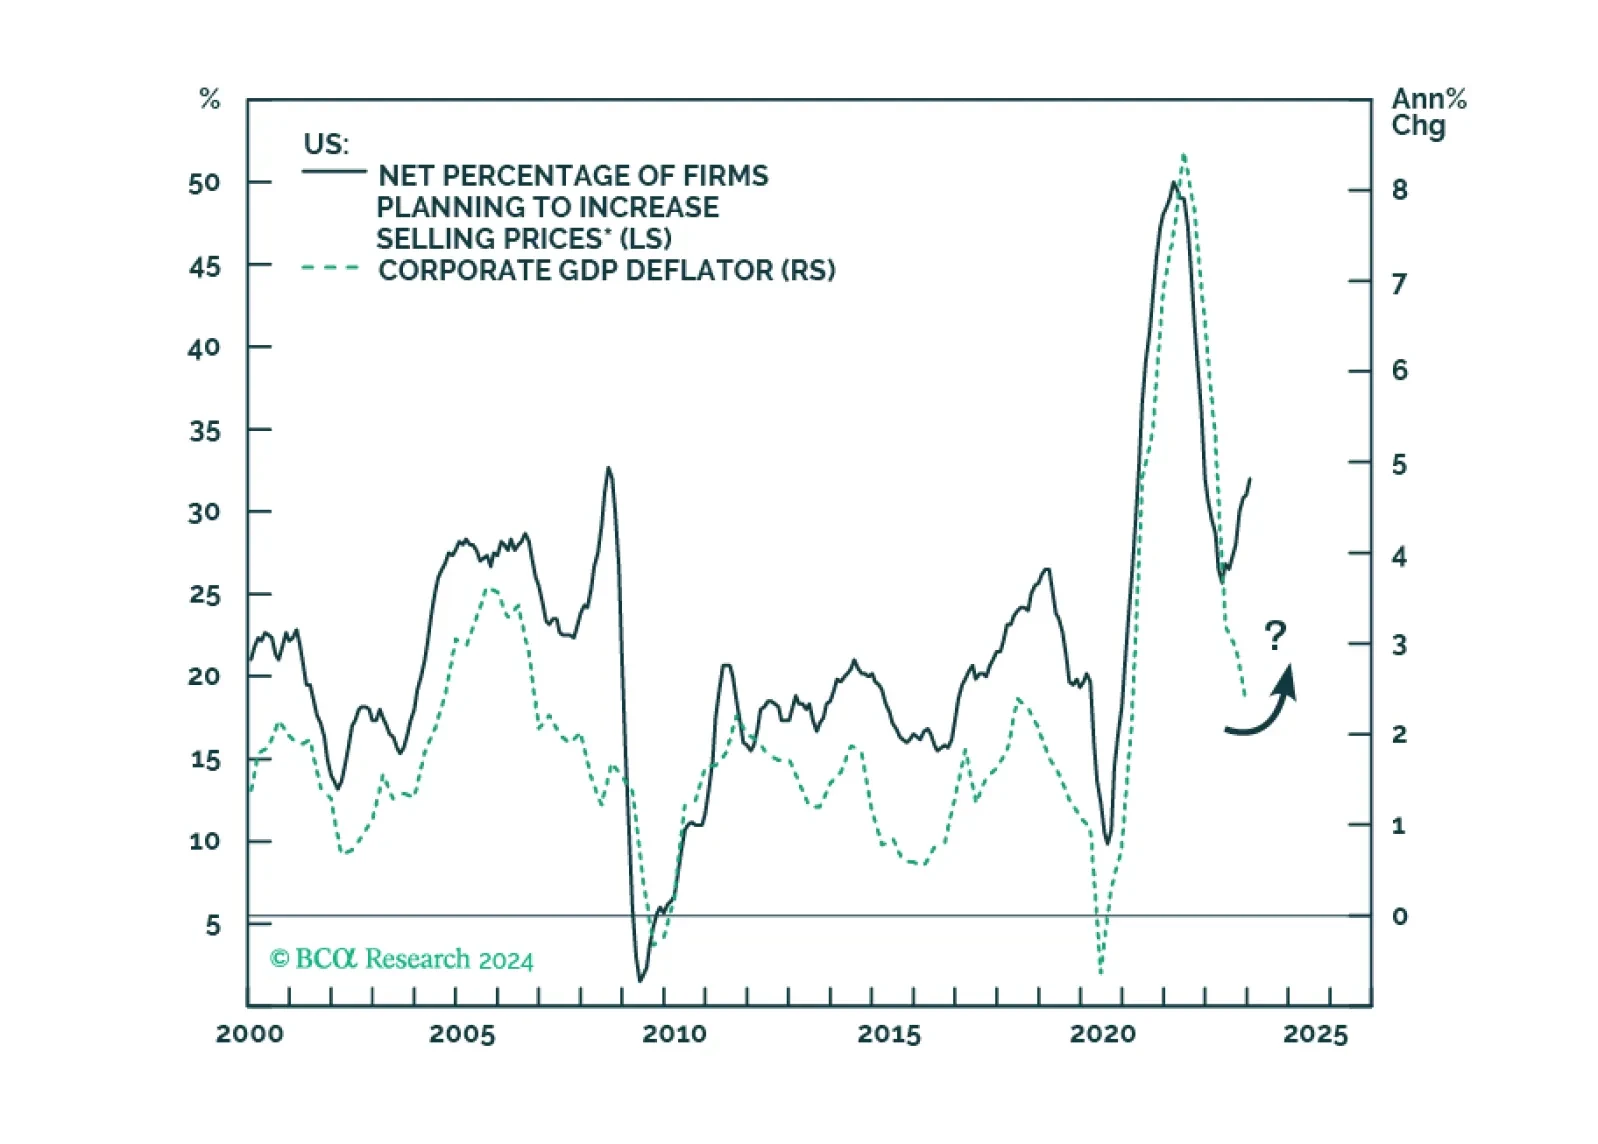
Presently, our four high-conviction themes are: (1) the US dollar will rally as US growth continues to outpace the rest of the world; (2) US equities will continue to outperform EM and European stocks until a major sell-off occurs; (3) a US profit margin squeeze is imminent; (4) EM domestic bonds and sovereign USD bonds are due for a setback.