Gov Sovereigns/Treasurys
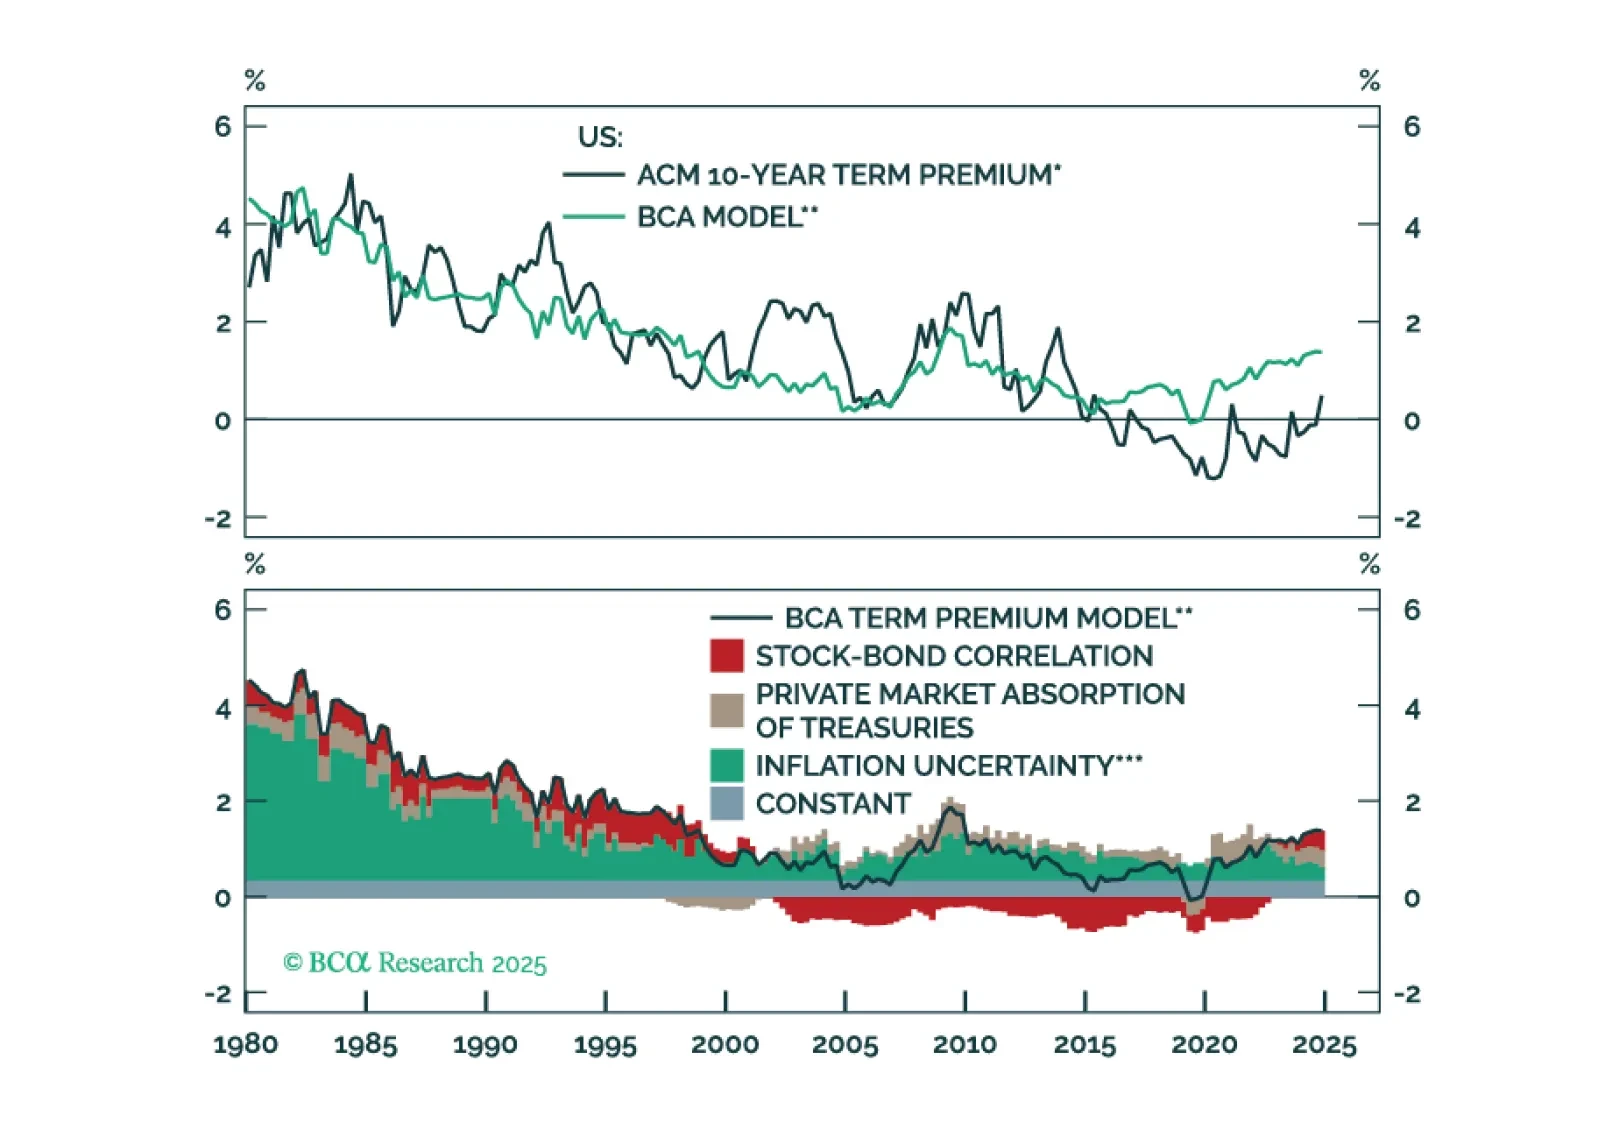
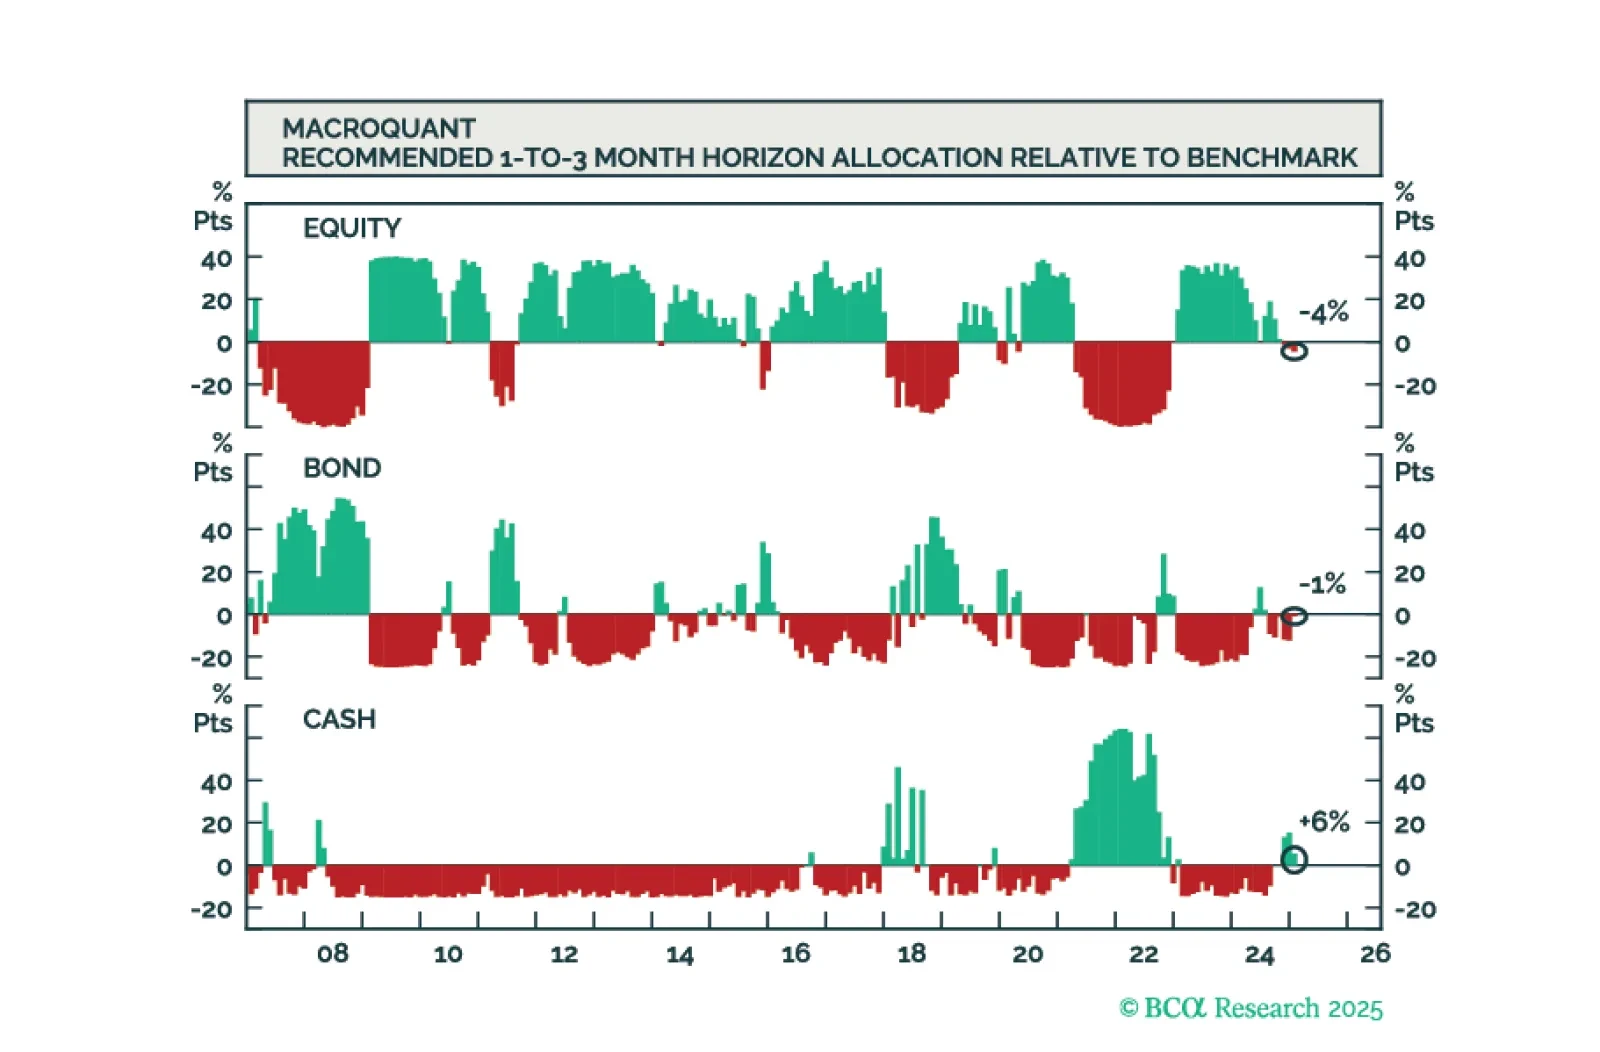
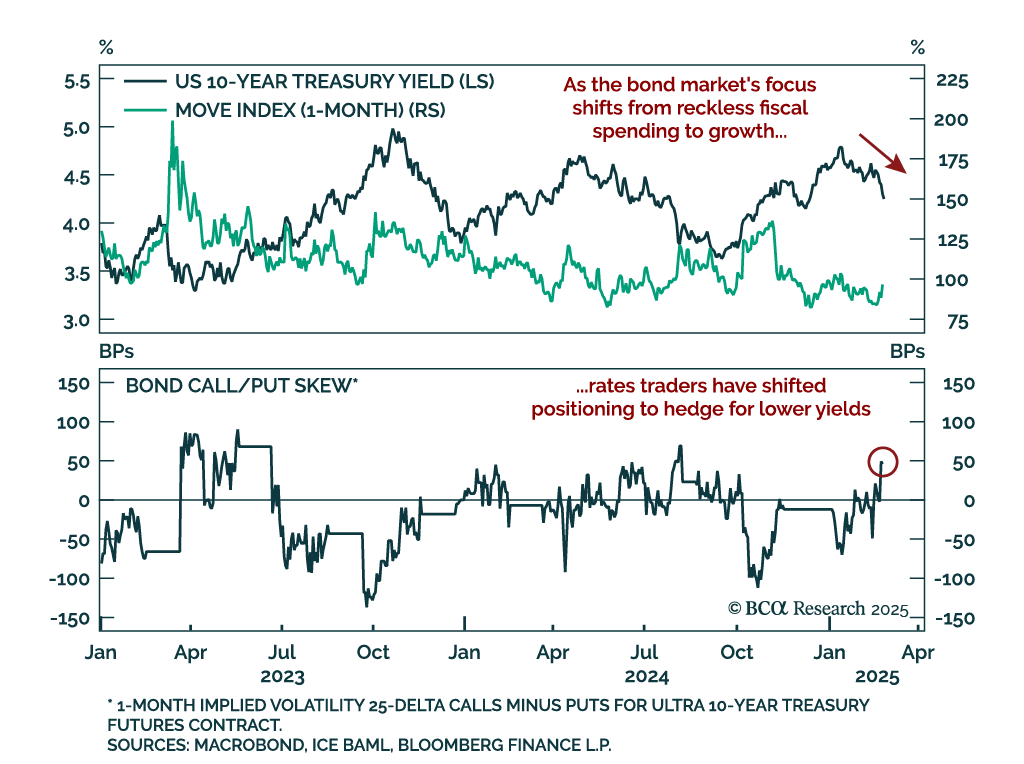
We attempt to model the term premium in this report with inflation uncertainty, the stock-bond correlation, and “Private Treasury Absorption.” Using our model, we estimate the fair value for the US term premium is 89 basis points above the current level. We also find that fiscal concerns are overrated as a term premium driver and instead, the hedging properties of bonds are more important. Over the cyclical horizon, we continue to recommend an above benchmark duration, given our expectations of an economic slowdown. However, if our term premium estimates are correct, US Treasuries still do not have a high enough risk premia to warrant a large structural allocation in a multi-asset portfolio.
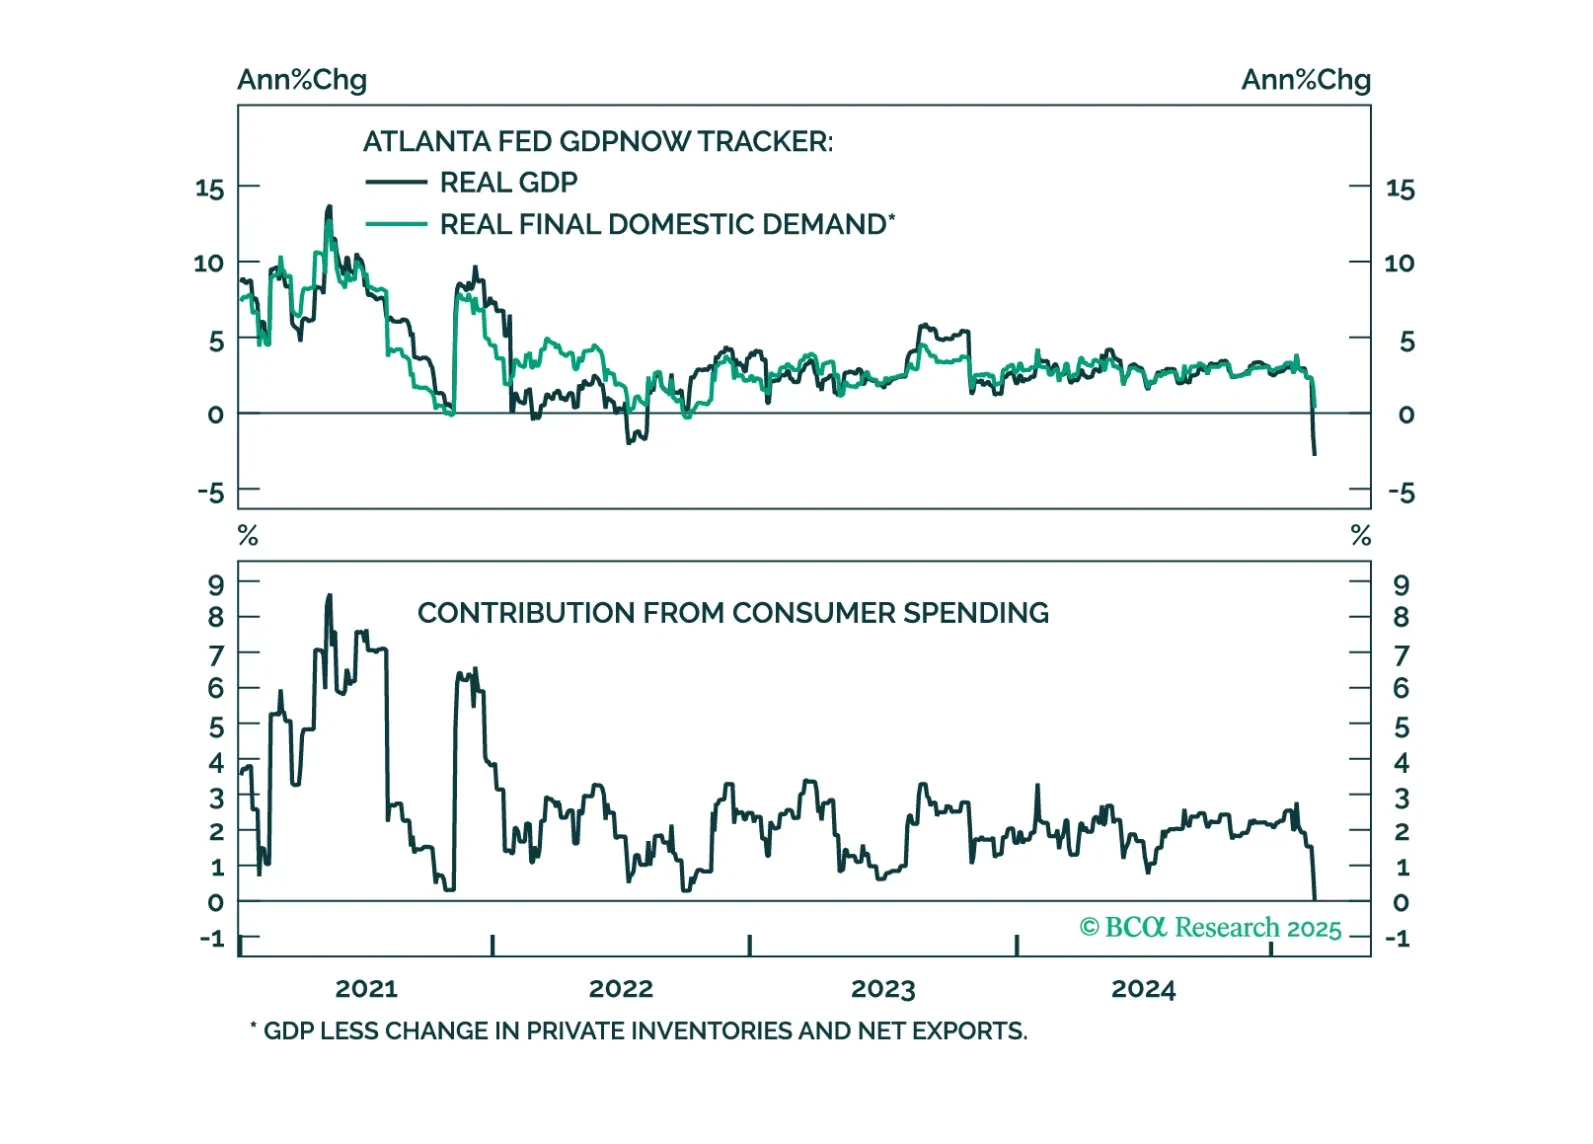
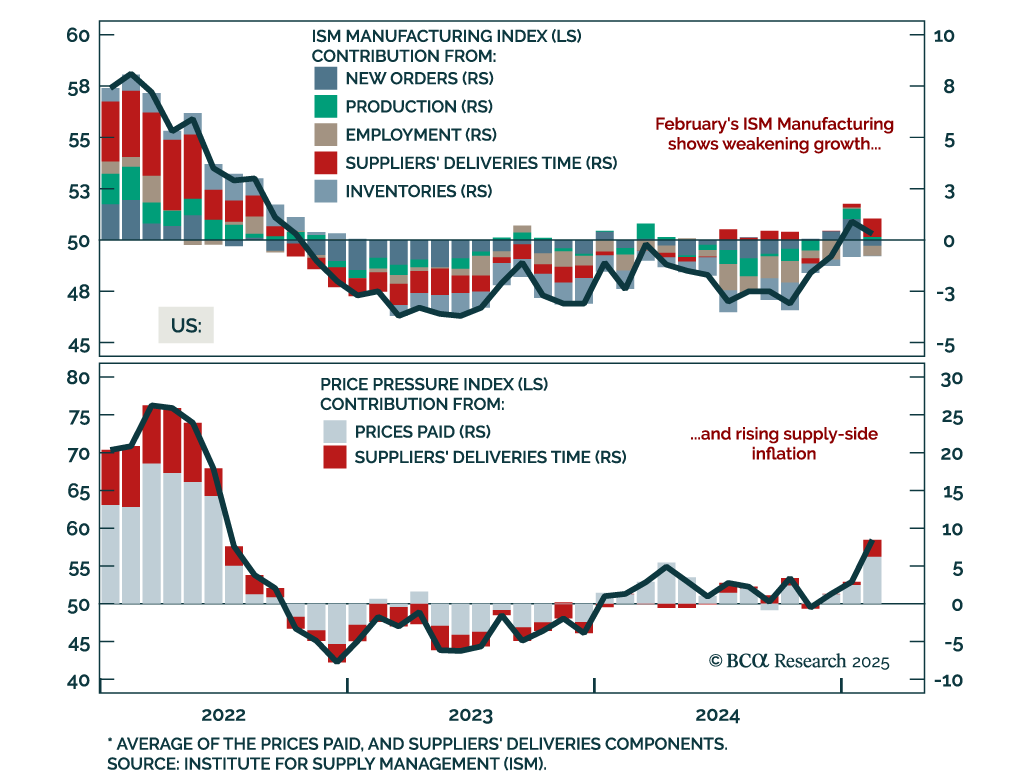
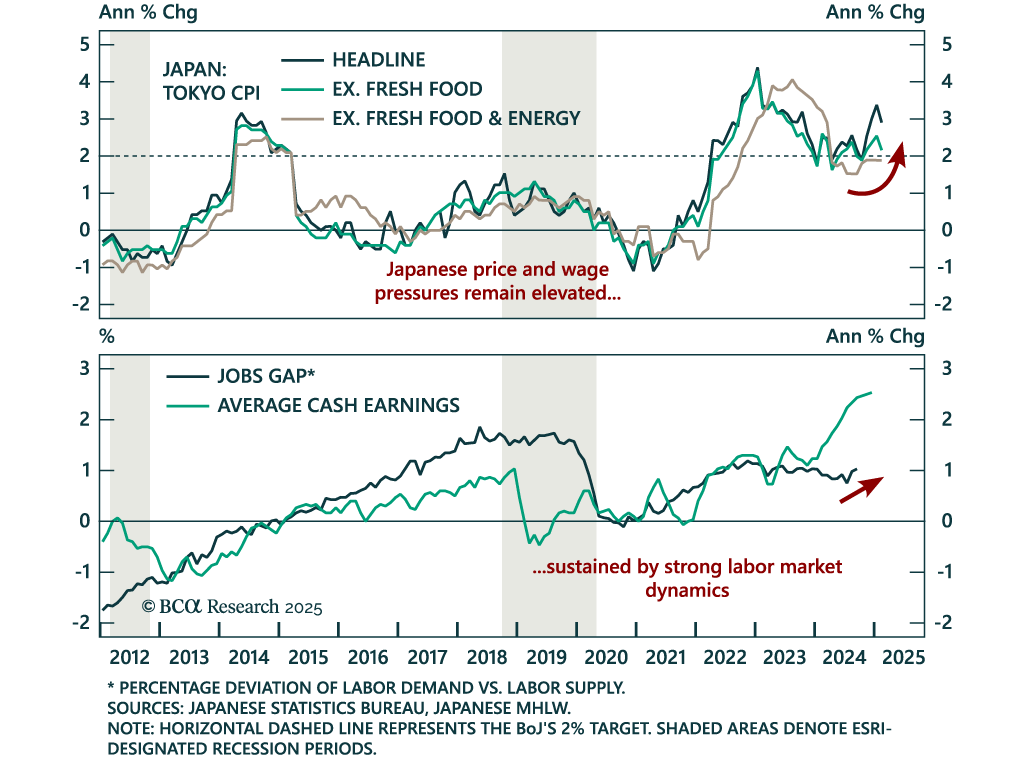
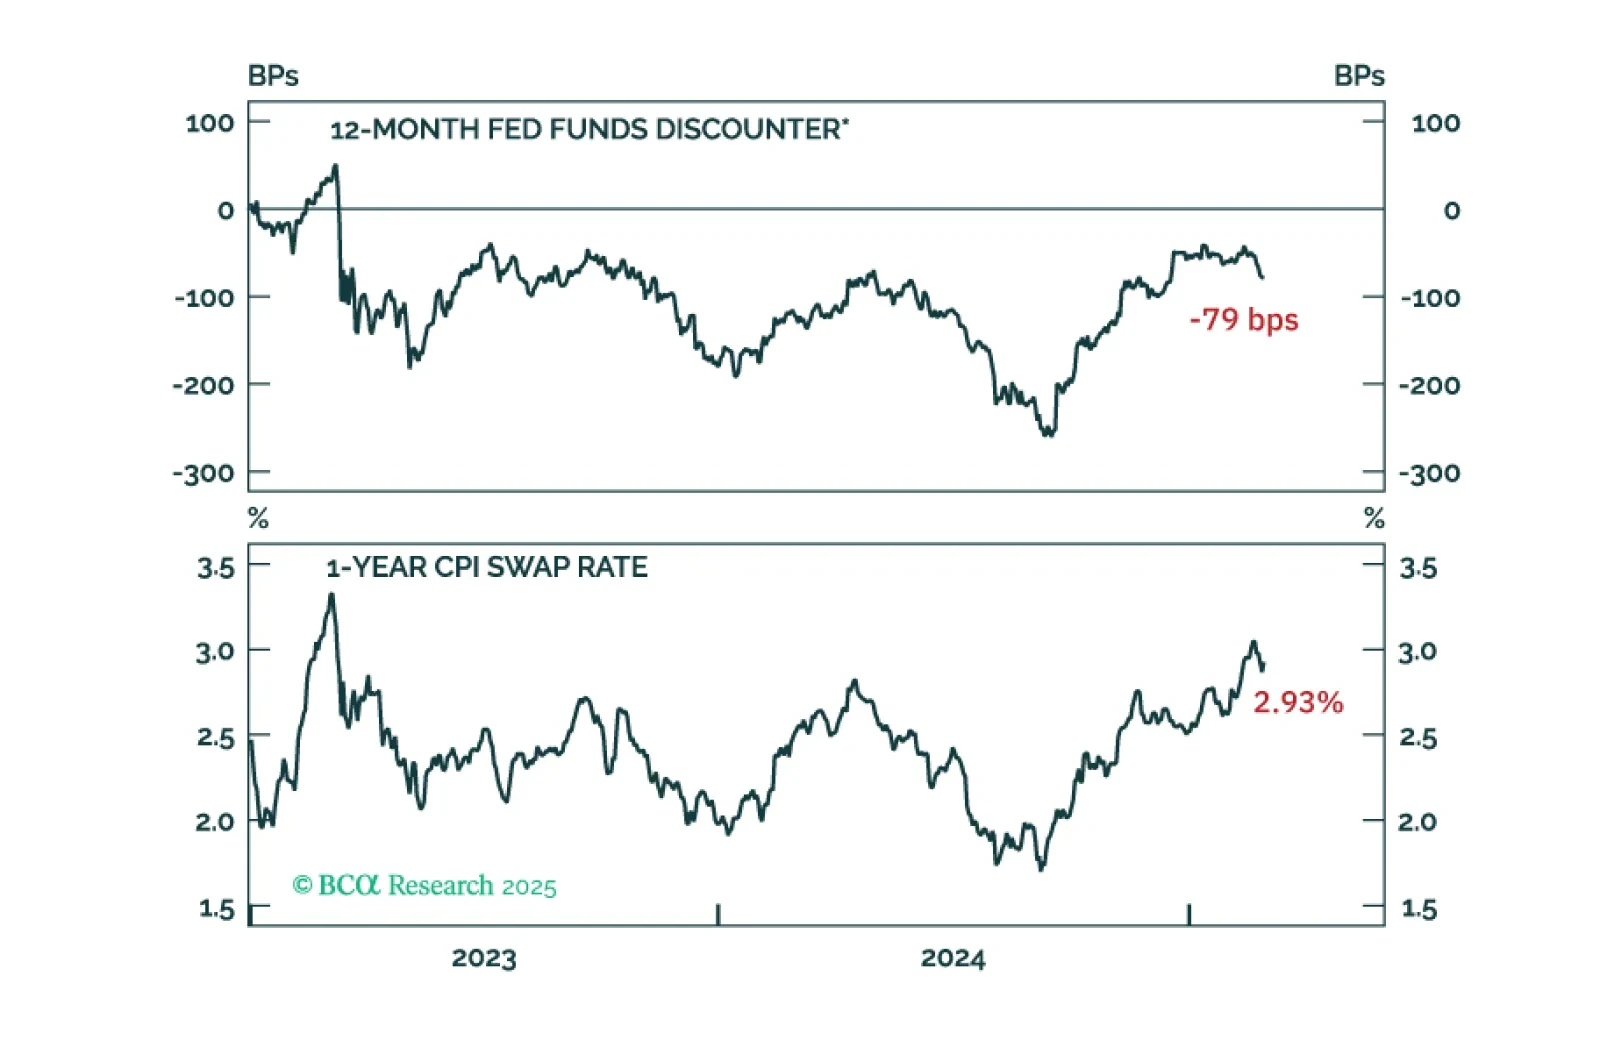
Core PCE inflation was tame this morning, but with large tariffs looming we anticipate loftier inflation readings in the months ahead.
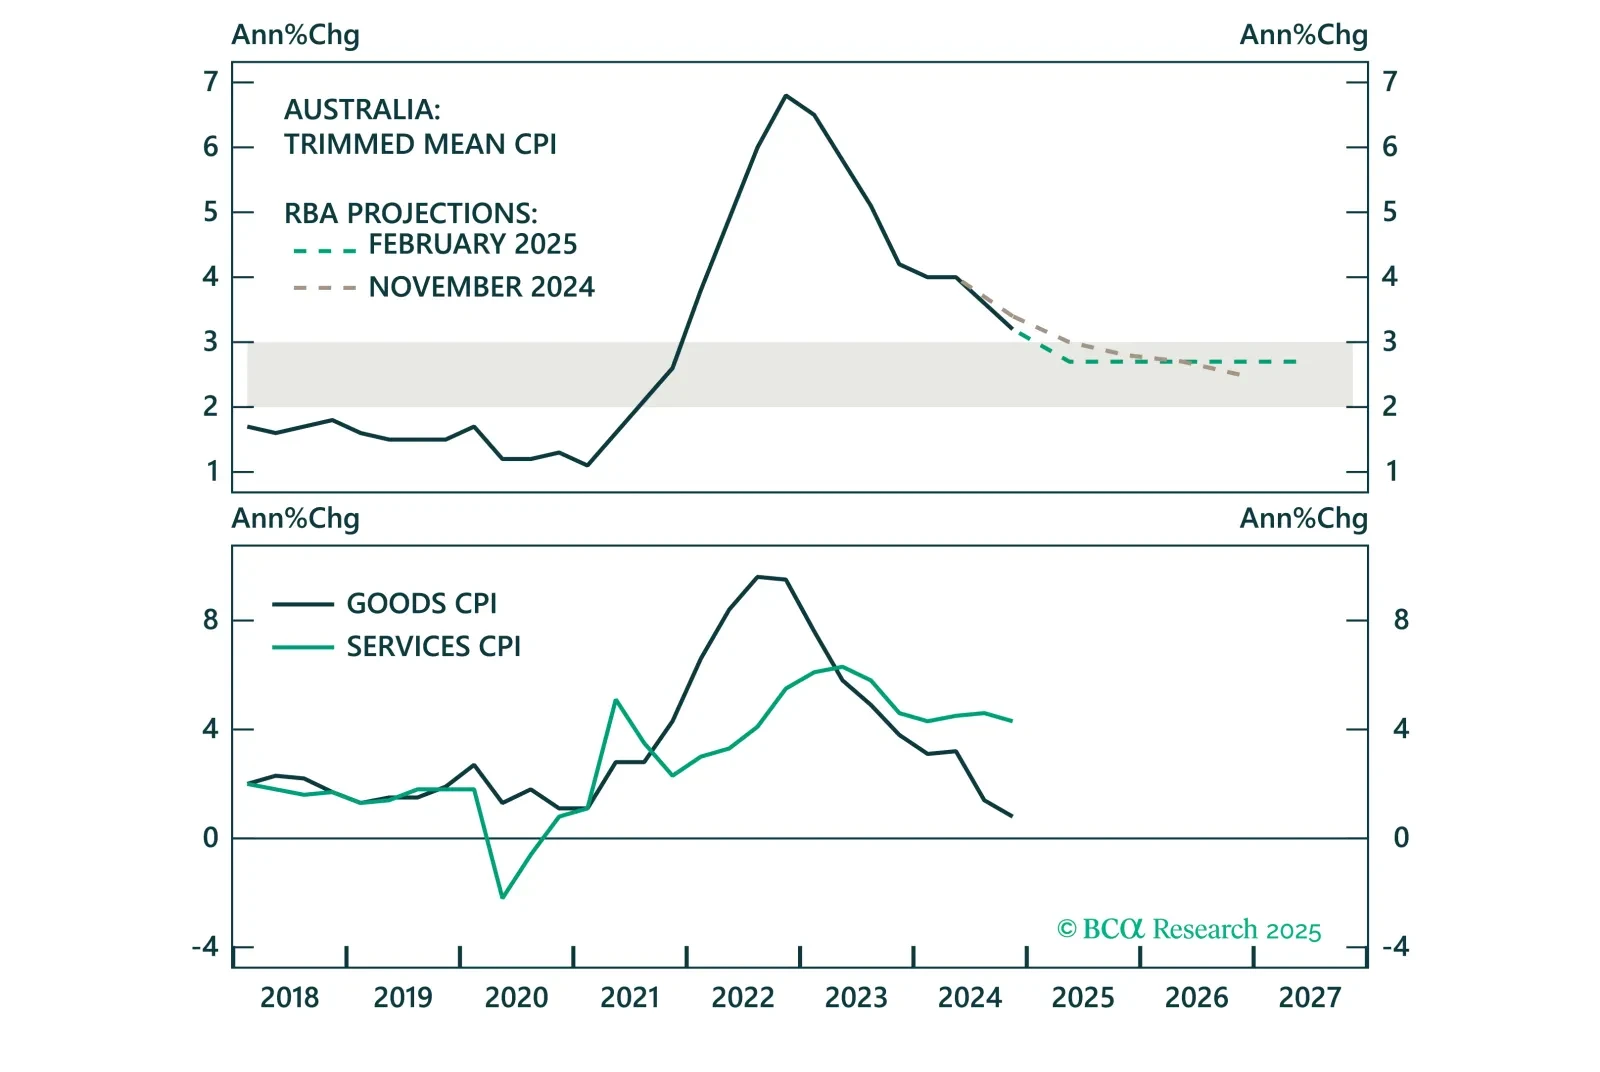
Overnight, the RBA cut the cash target rate for the first time since 2022, marking the beginning of the policy easing cycle in Australia. However, the RBA will proceed cautiously with further rate cuts, given a tight labor market and still elevated services inflation. This will keep Australian government bond yields elevated versus global yields, benefitting the Australian dollar.
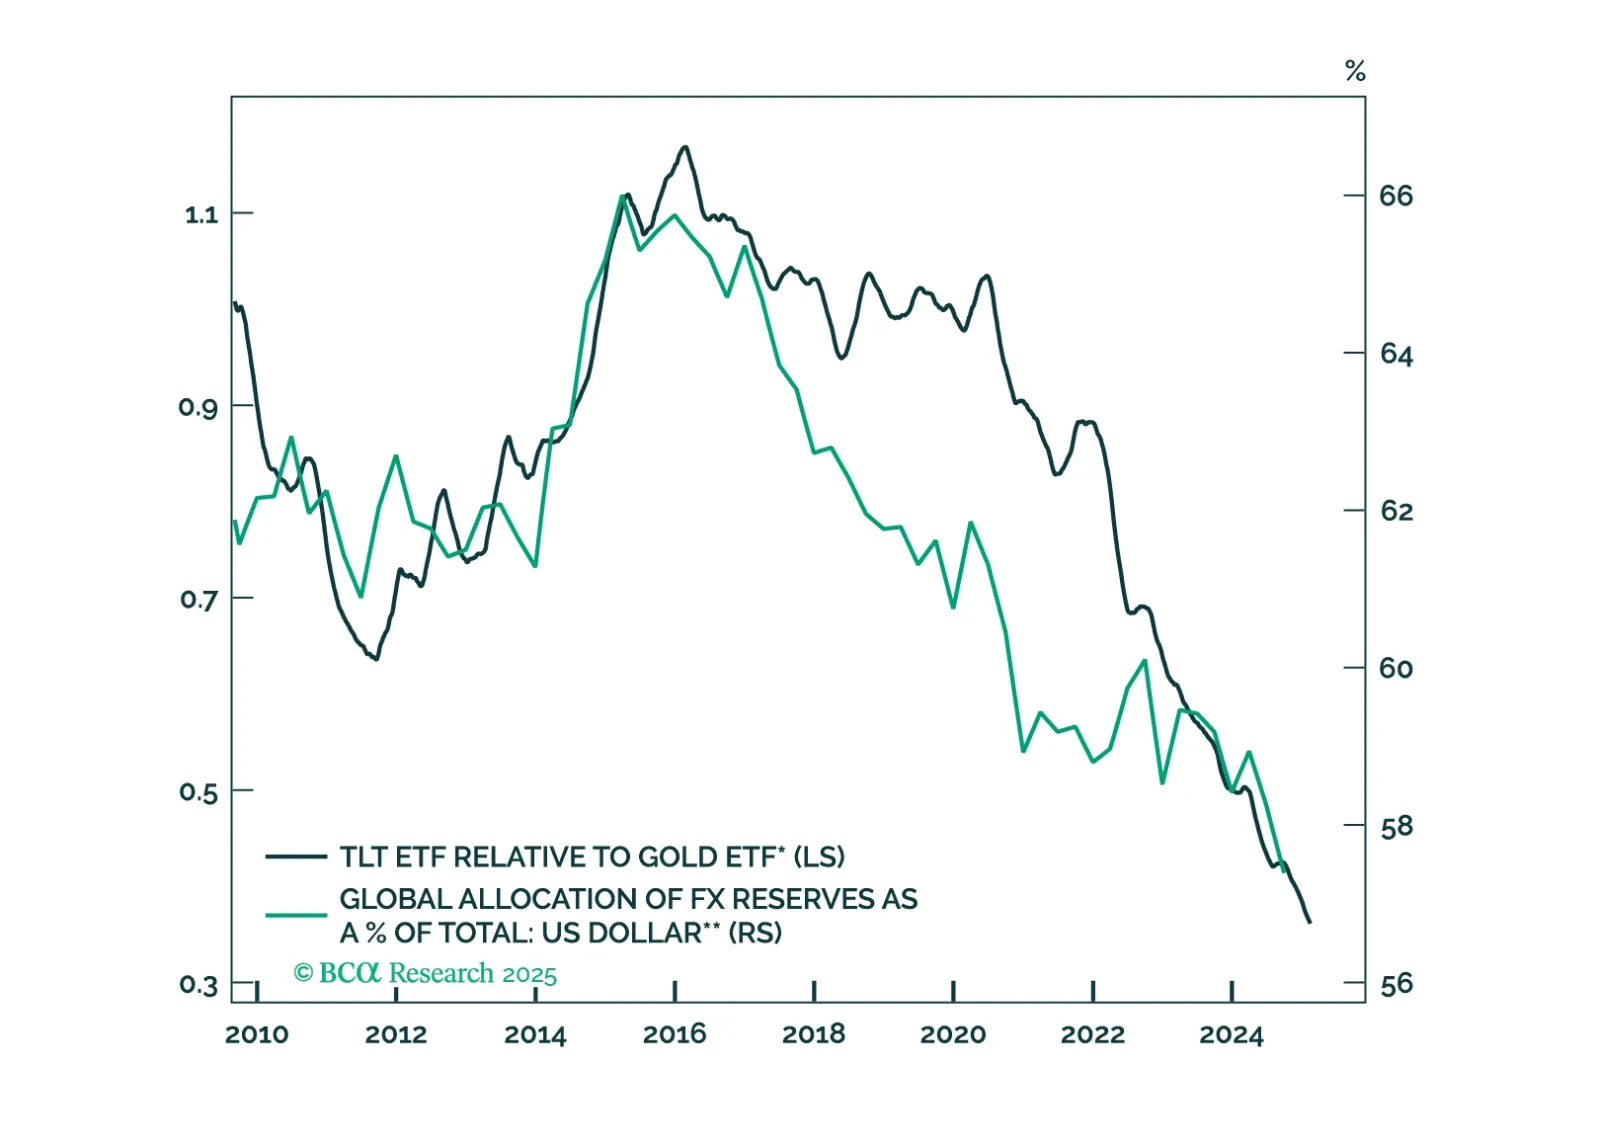
In lieu of all the geopolitical and economic news in media, this report looks at where next the dollar is likely to trend in the next one-to-three months. Our view is down, though on a cyclical horizon (six-to-twelve months), we would not be short the dollar, for now.