Economy
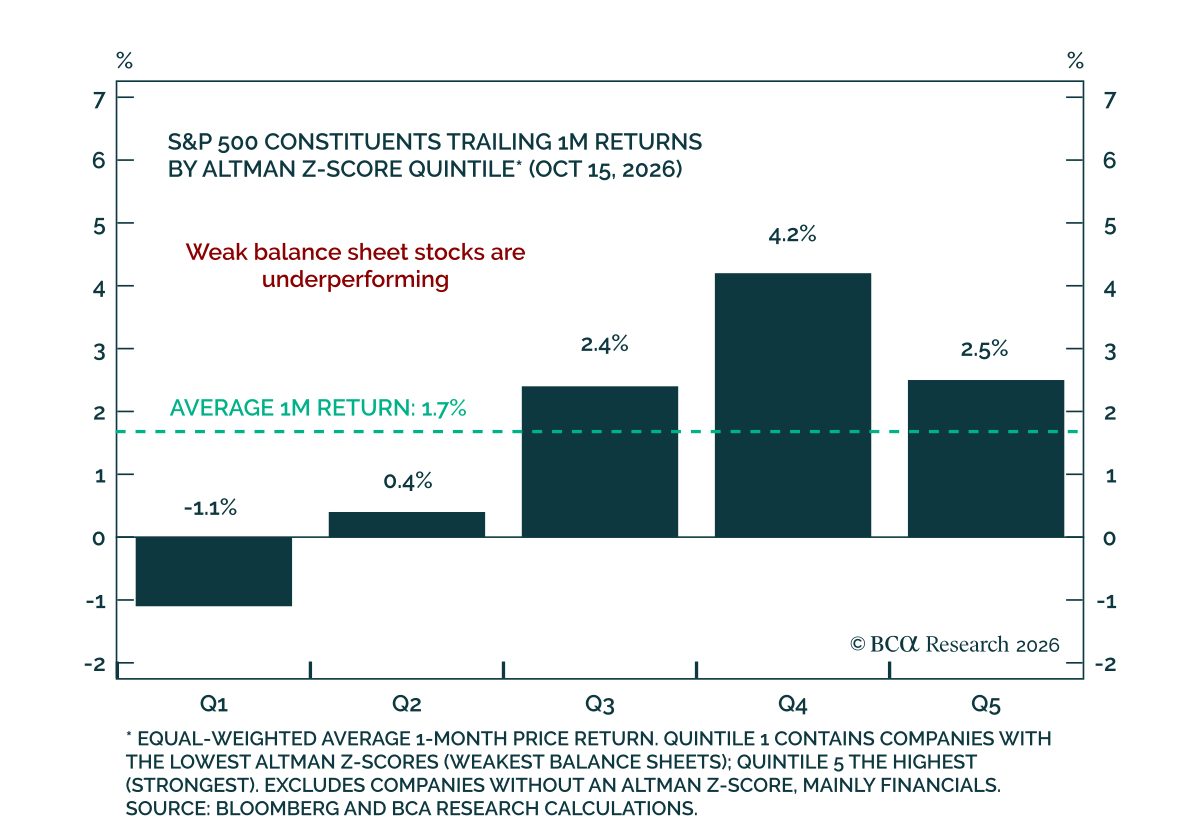
Our US Equity strategists recommend fading wider credit spreads. Investors should lean into quality ahead of Q3 earnings, rather than de-risking. Credit spreads have widened as Treasuries have sold off, punishing stocks with weak balance sheets. But the…
Credit spreads have widened as bond risks intensified, pressuring weak-balance-sheet companies. But the stress is narrow and valuations have already compressed, so equity risks look manageable. Rather than de-risk, we would lean into quality: large over small caps, quality capex, and defensible Tech margins, and look to Q3 earnings for confirmation.
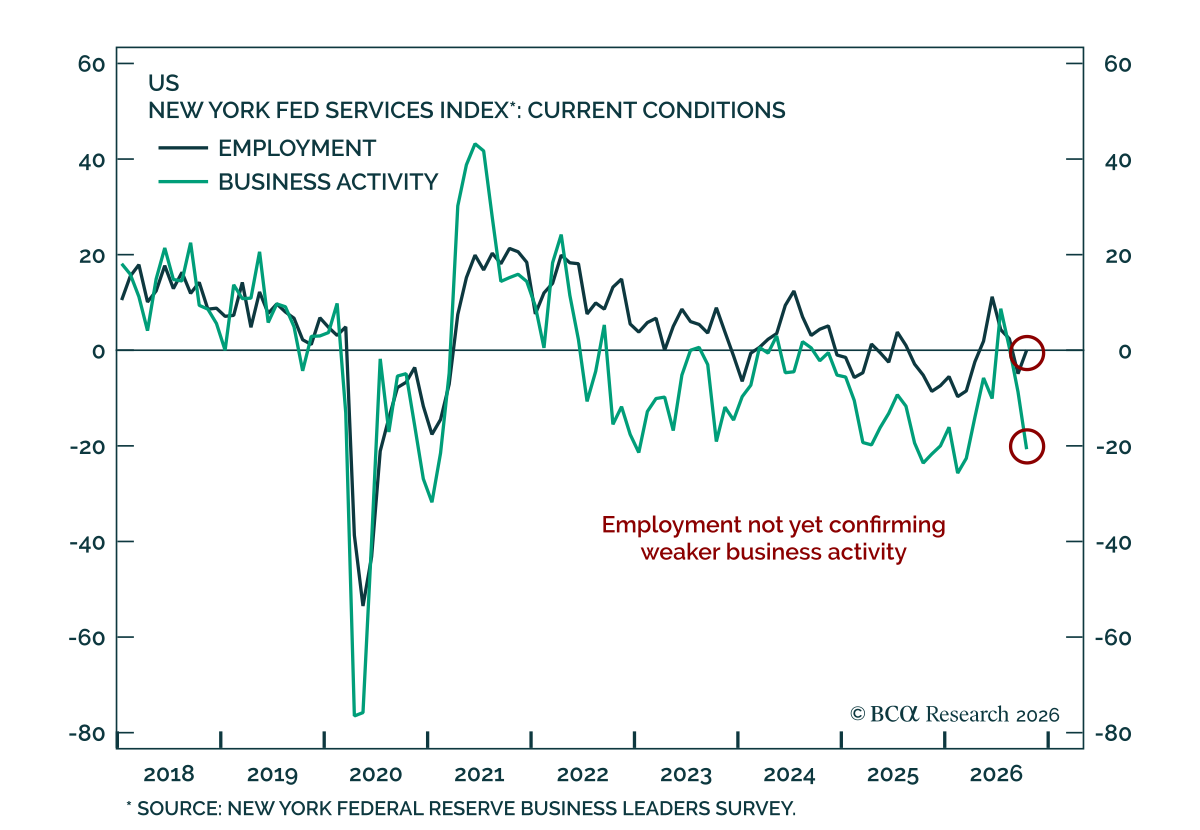
The New York regional Fed services index fell in October, but hiring stayed steady. The overall business activity index declined from -9 in September to -21 in October based on current conditions, and expectations six months ahead declined from 5 to -5. The…
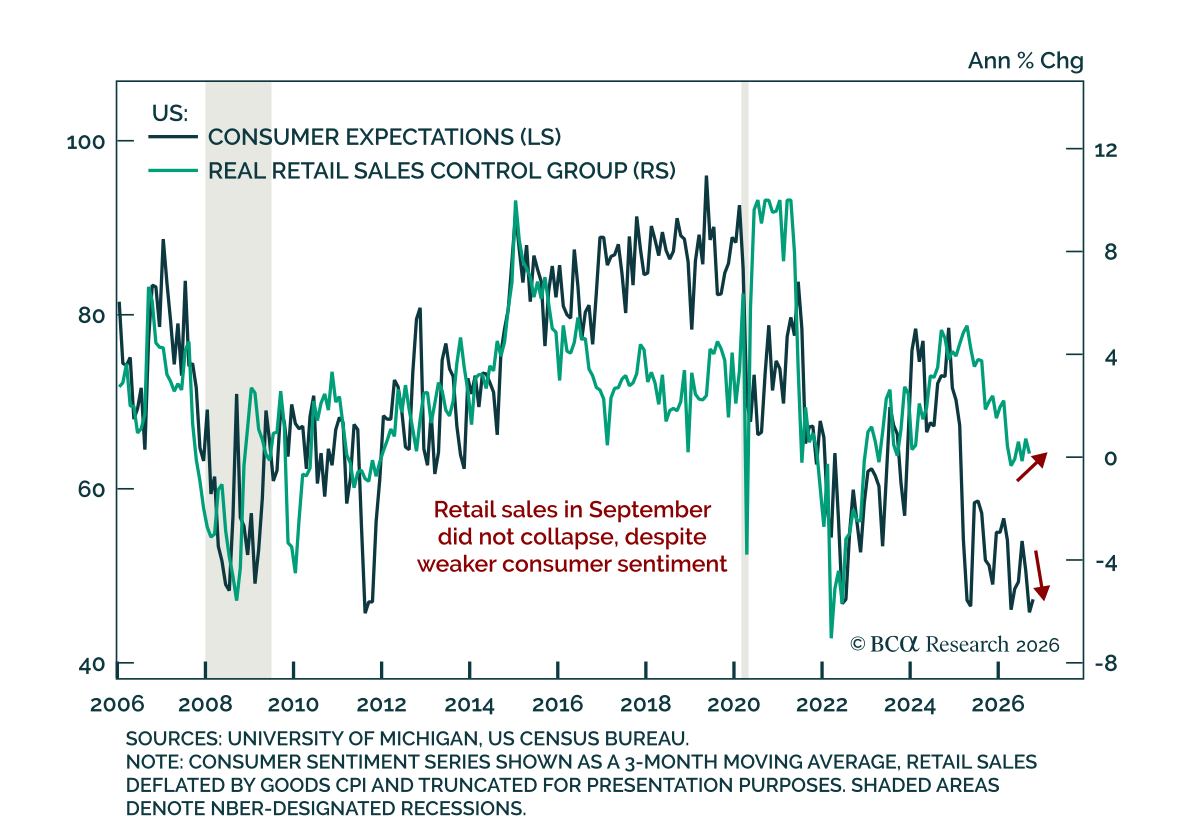
“Core” US retail sales growth was tepid in September, but meaningfully stronger than confidence measures implied. Headline sales rose 0.8% m/m, a slowdown from August but above consensus expectations. The core measure excluding autos and gas also increased…
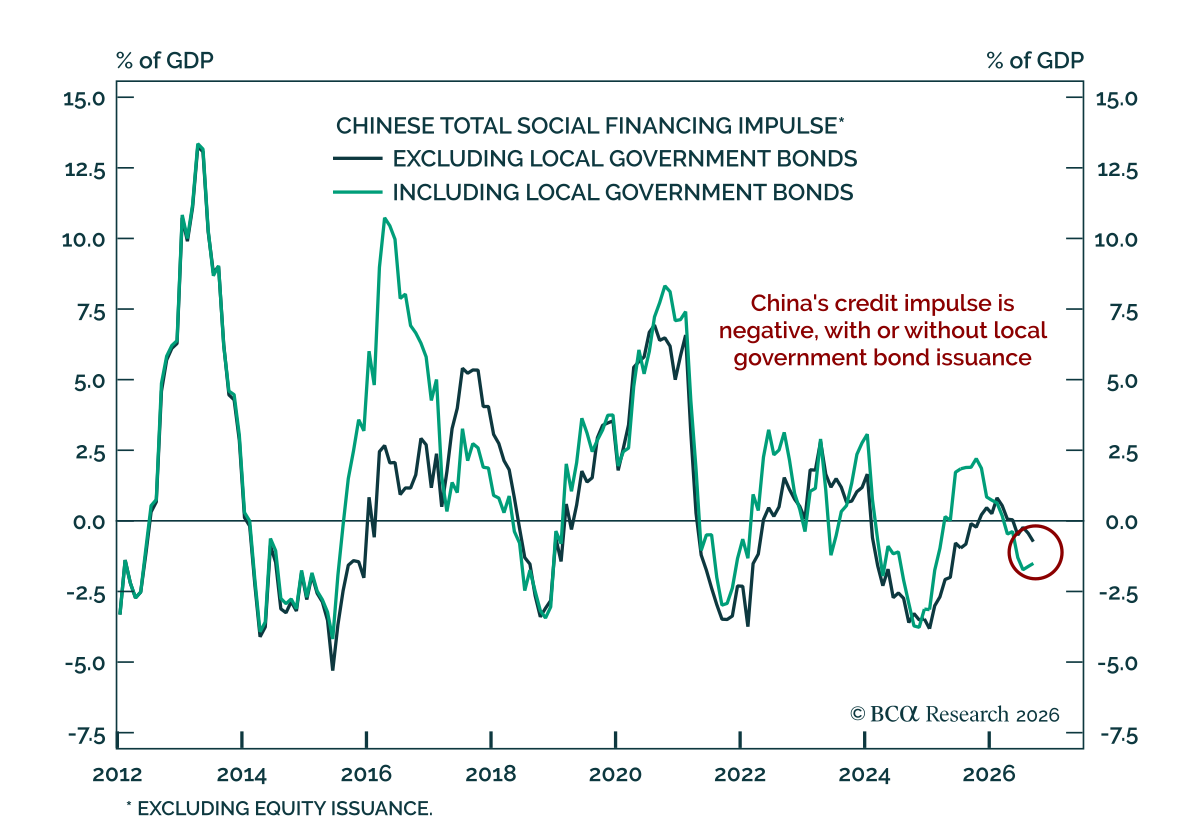
China’s September inflation, trade, and credit data do not point to an improving domestic economy. Producer price inflation accelerated in September, but energy drove most of the increase. Consumer price inflation was unchanged, suggesting that producers…
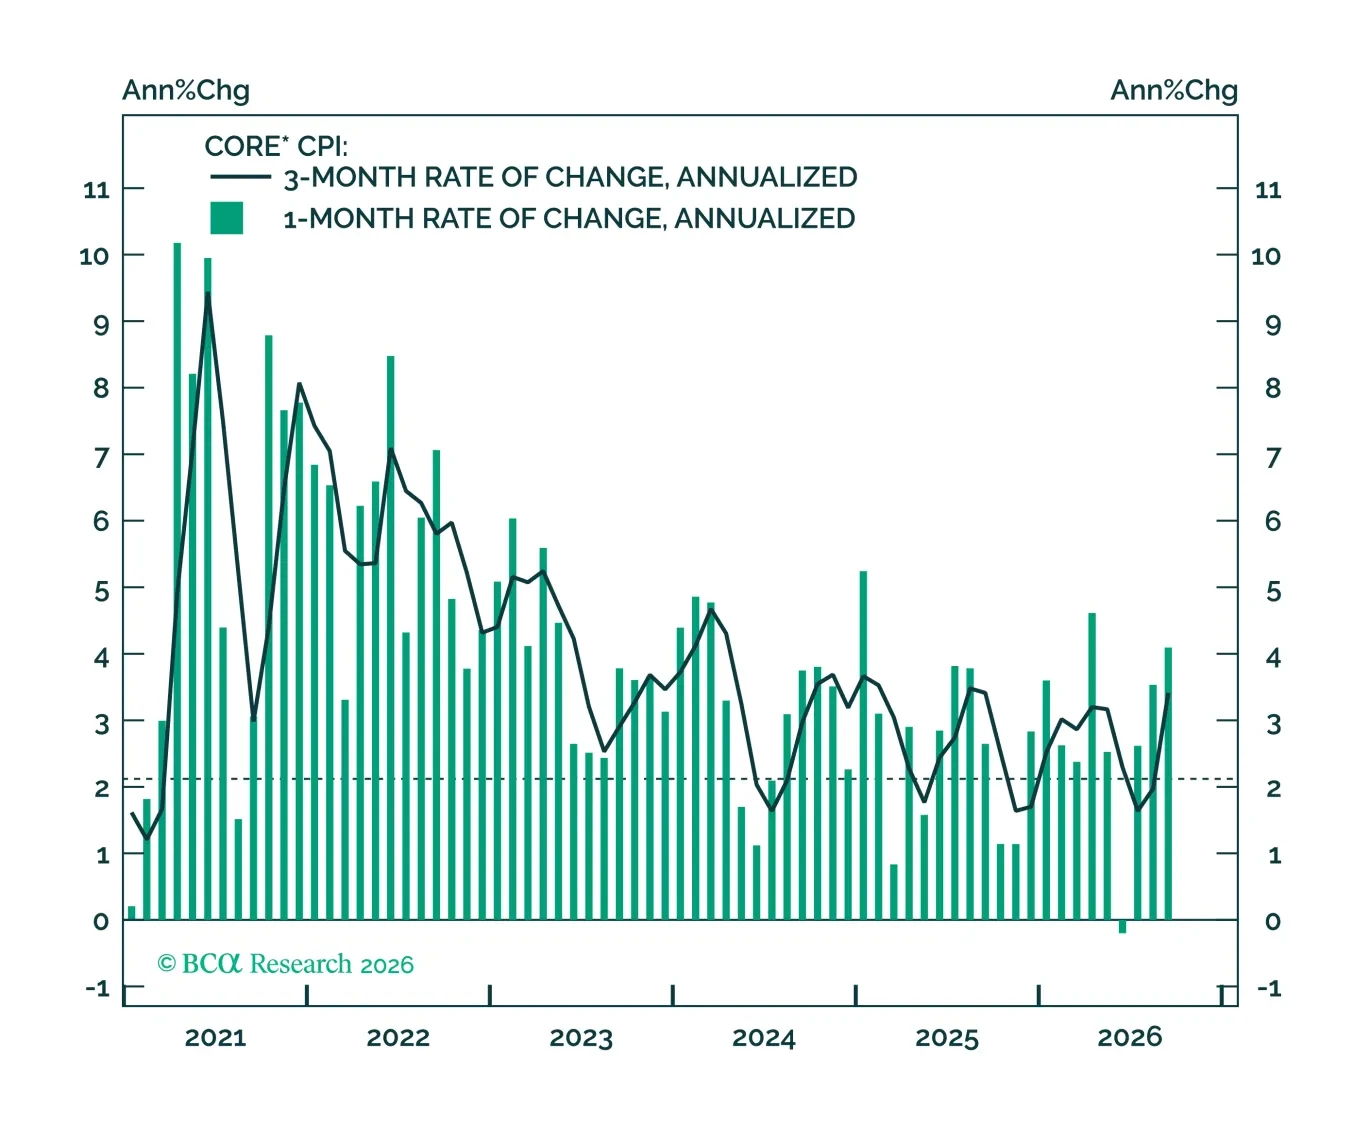
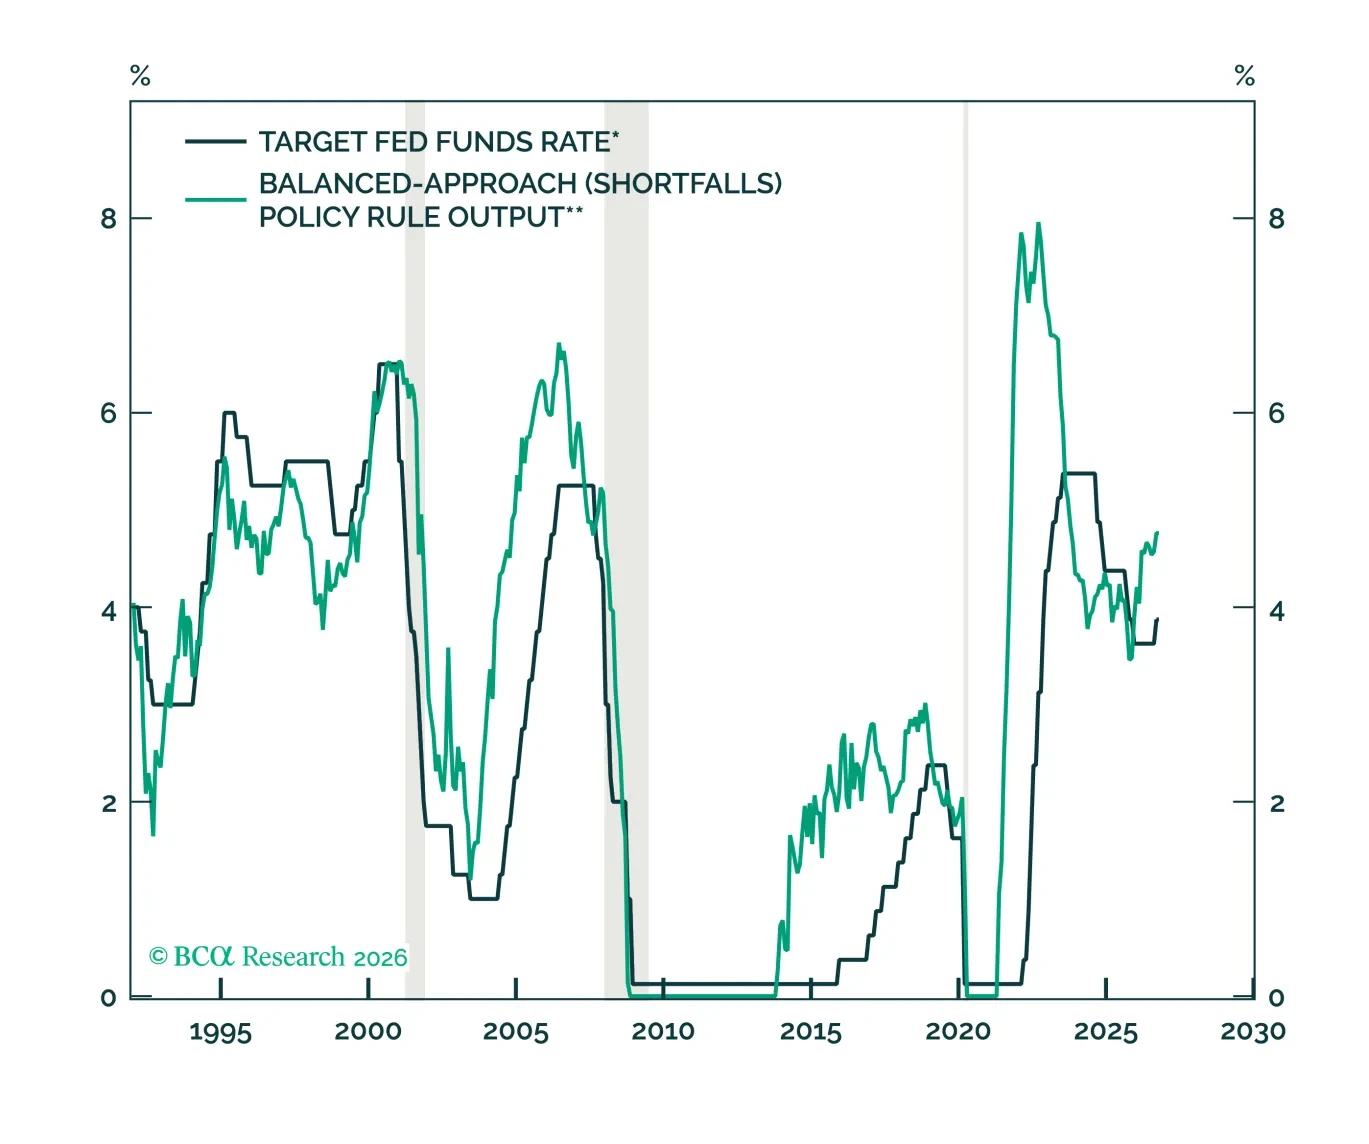
US inflation came in hot for the second consecutive month in September, though probably not hot enough for the Fed to move its next rate hike up to the October meeting.
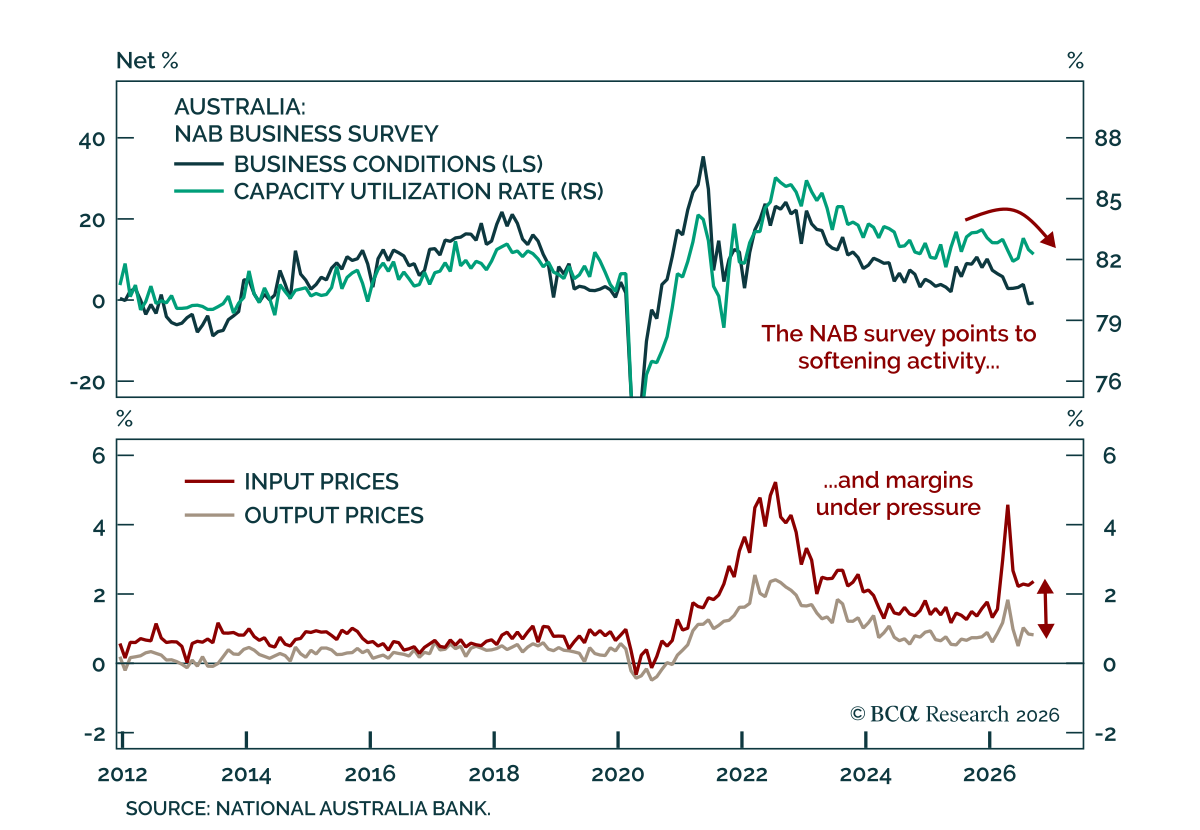
Australia’s September NAB Business Survey signals softening activity that will limit the RBA’s hawkishness. Business conditions held in negative territory at -1, after turning negative last month for the first time since 2020. A modest rebound in profits and…
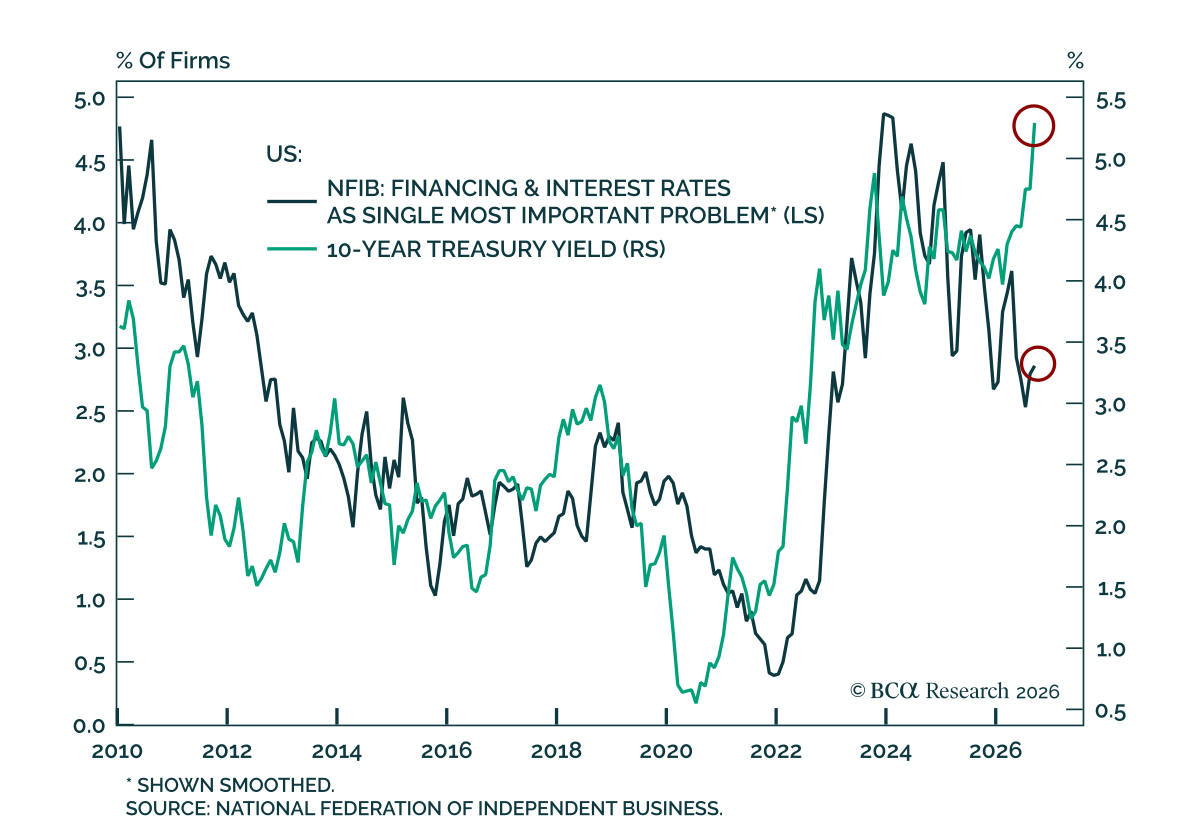
Small businesses are not yet feeling the bite from higher rates. The NFIB Small Business Optimism index ticked down last month, from 98.7 in August to 97.9 in September. The decline was mostly driven by the economic sentiment components of the index. Among…
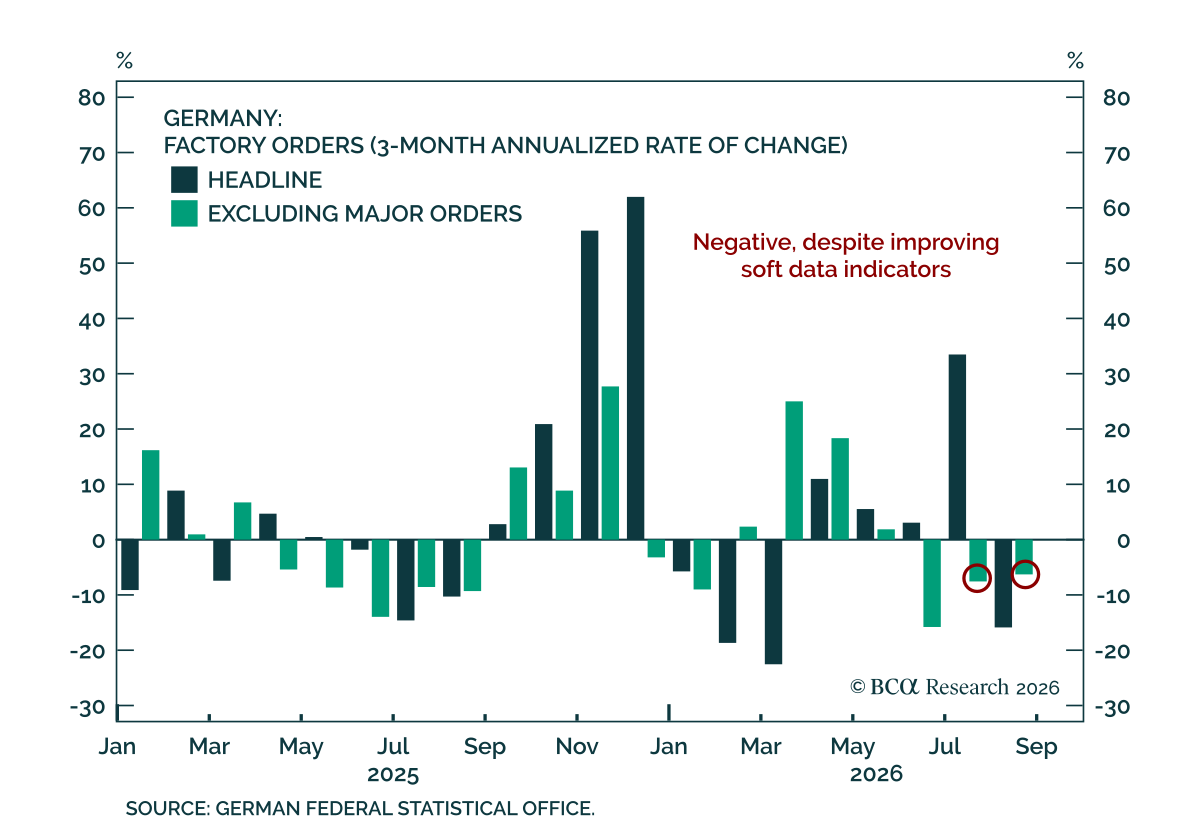
German factory orders plunged in August, continuing a trend of weaker hard data indicators against the backdrop of improving business sentiment measures. Germany factor orders fell 10.6% m/m against an expected 1% decline, following an upwardly revised 3.2%…