Economic Growth
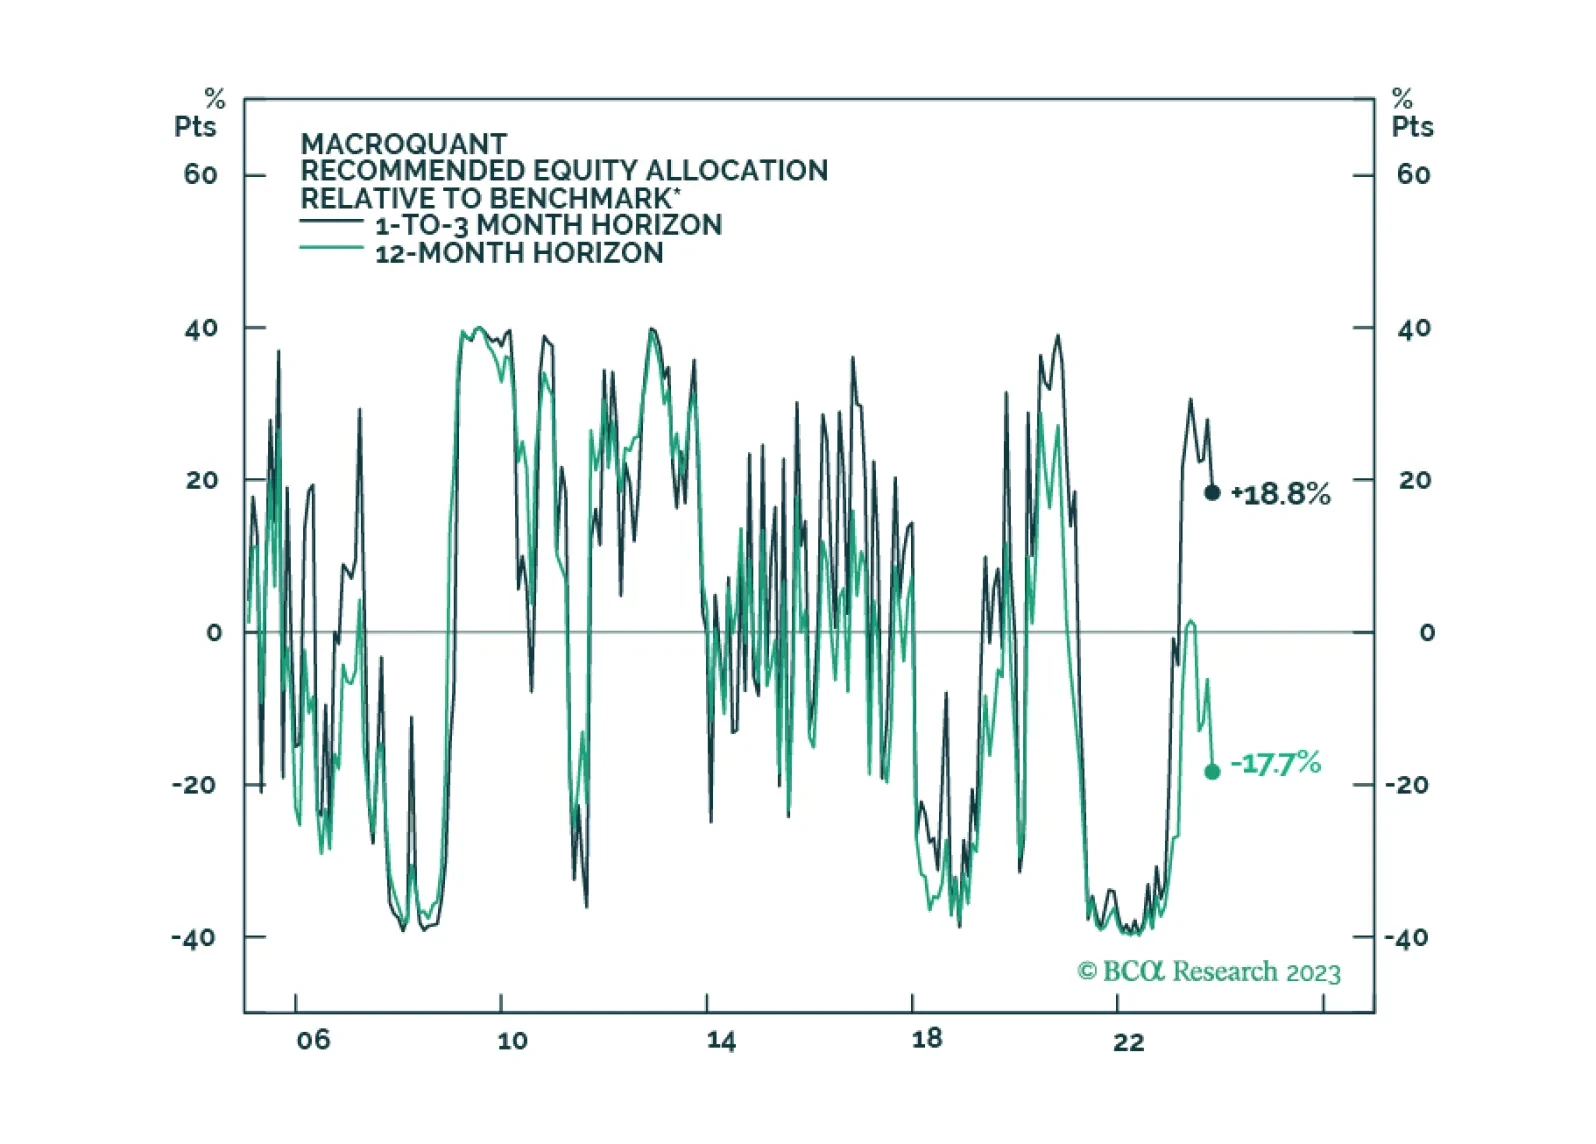
We are approaching another phase transition from boom to bust. Stocks should rally into year-end, but investors should look to reduce equity exposure early next year while increasing bond exposure.

The October update of the Global Manufacturing PMI sent a pessimistic signal about the industrial cycle. The headline index declined from 49.2 to 48.8, indicating a faster pace of deterioration. In particular, the Output, Employment, and New Export Orders…
As expected, the Bank of England kept its bank rate unchanged at 5.25% at Thursday's MPC meeting with six members voting in favor of the decision and the remaining three preferring a 25bps rate increase. Governor Andrew Bailey stressed at the post-meeting…
The US ISM Manufacturing PMI delivered a disappointing update on factory activity in October. The headline index unexpectedly fell to 46.7, surprising consensus estimates it would remain unchanged at 49.0. In particular, a sharp 4.4-point decline in the…
The broad-based selloff continued in October. Fixed income markets performed particularly poorly as stronger-than-anticipated US economic data generated upside pressure on long-dated bond yields in the US and, to a lesser extent, across other major economies.…
According to BCA Research’s China Investment Strategy service, China's recently introduced debt swap program will help prevent mushrooming defaults, but it will not lead to an acceleration in growth. In August, the Ministry of Finance permitted 12 heavily…
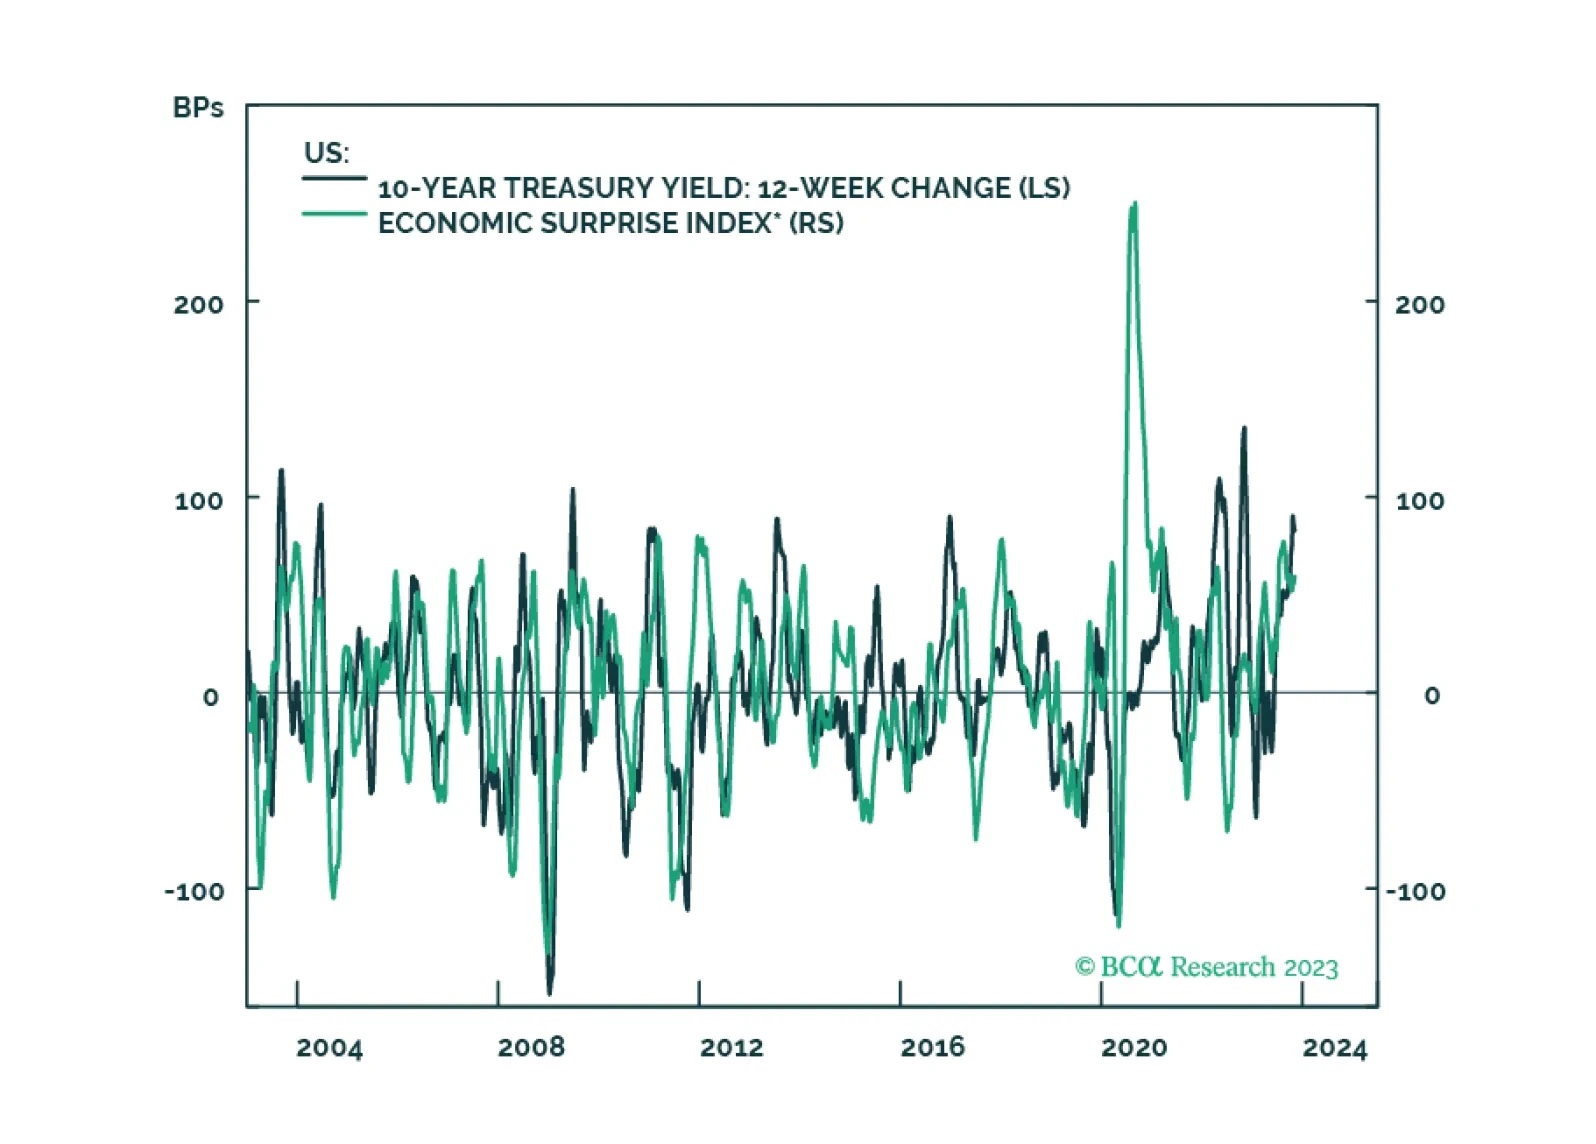
High interest rates will eventually cause growth to slow. Signs of stress are already starting to show. Stay cautiously positioned.
The US Employment Cost Index (ECI) unexpectedly accelerated in Q3, rising by 1.1% q/q versus anticipations the pace of increase would remain unchanged at 1.0% q/q. A pickup in wages and salaries drove the increase. On an annual basis, the ECI slowed from 4.5%…
China's industrial profits delivered a positive signal over the past couple months. Total profits expanded on a year-on-year basis in both August (+17.2% y/y) and September (+11.9% y/y). Rebounding industrial profits is typically a favorable development for…
In a recent Insight we highlighted that the S&P 500's year-to-date rally is narrow in breadth and that the equal weighted index has erased all its year-to-date gains. This is also true in the case of the Euro Area where the MSCI price index is still up by…