Skip to main content

Asset Allocation

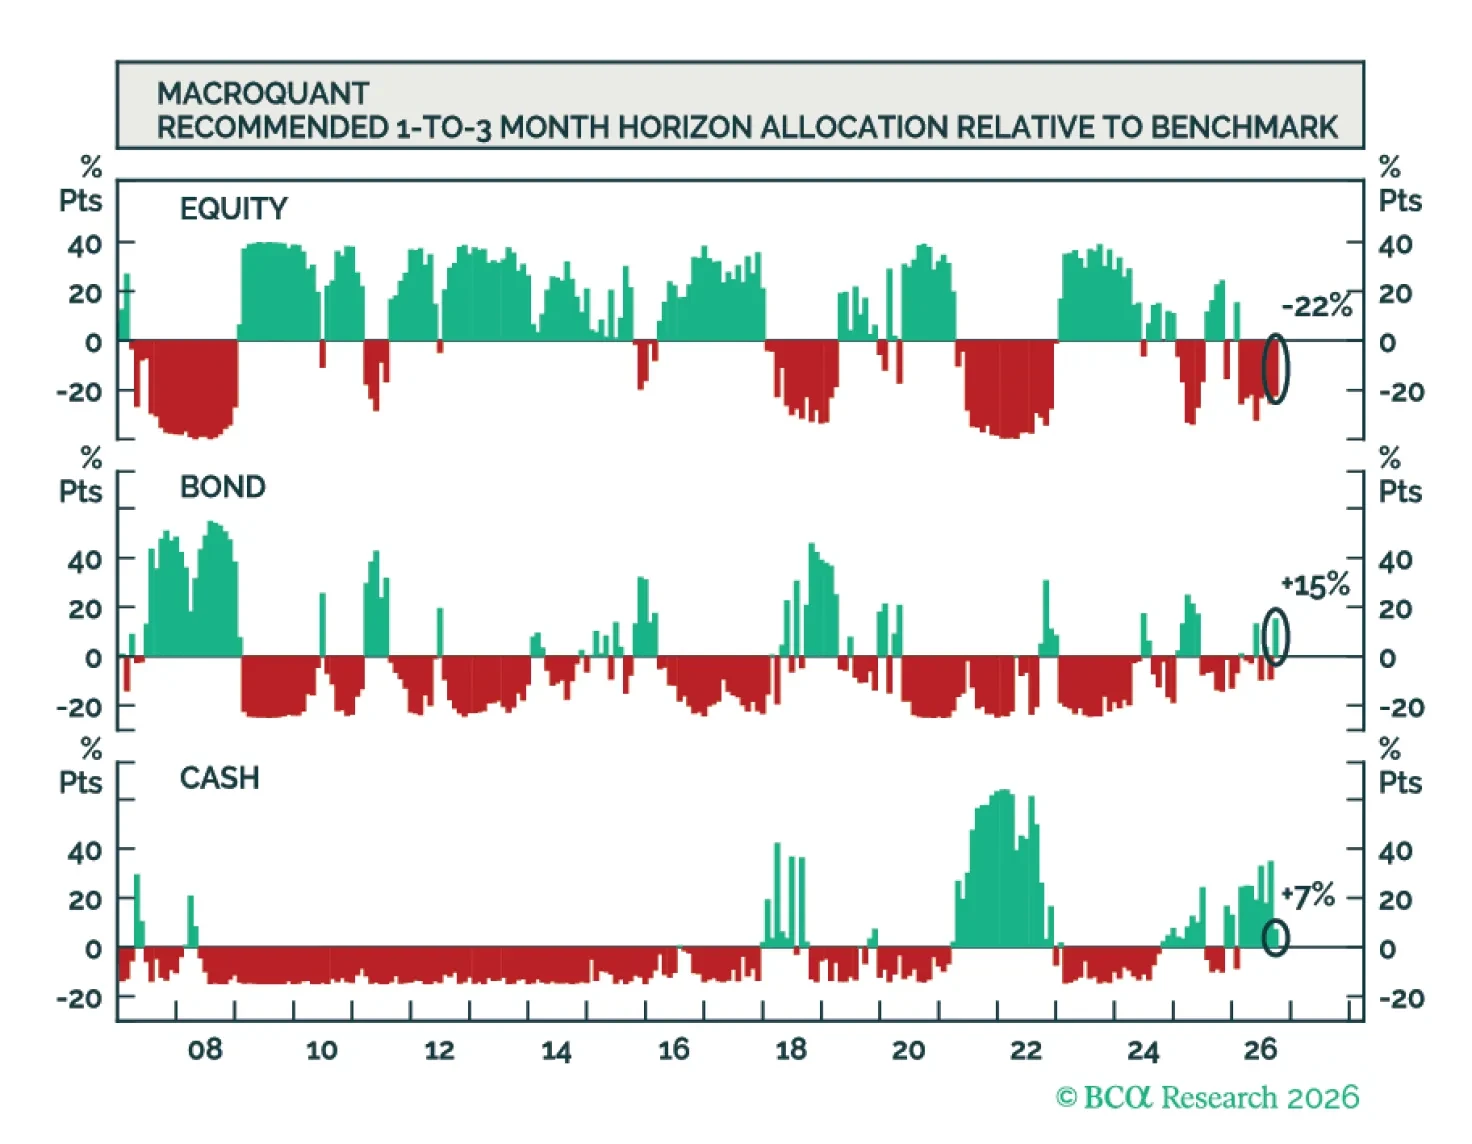
MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.
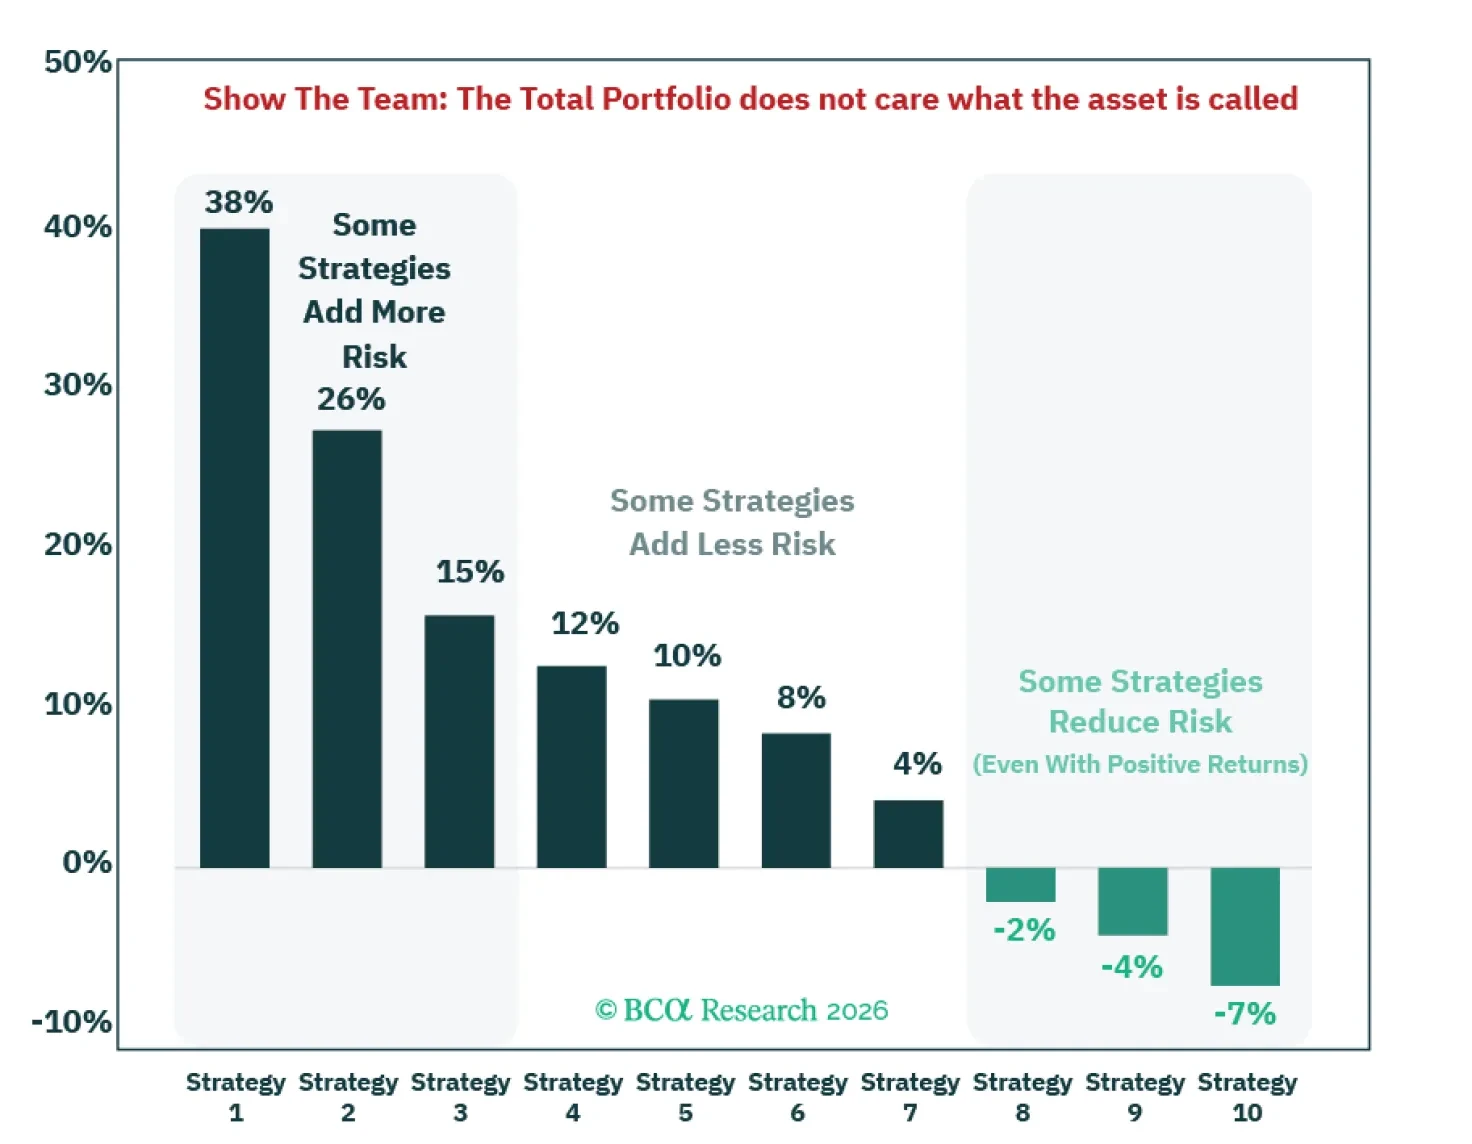
The Total Portfolio Approach stumbles really on one thing: the team. Everyone says it, but nobody has prescribed the fix. We provide three logistical principles that close the gap. And they work for SAA investors too.
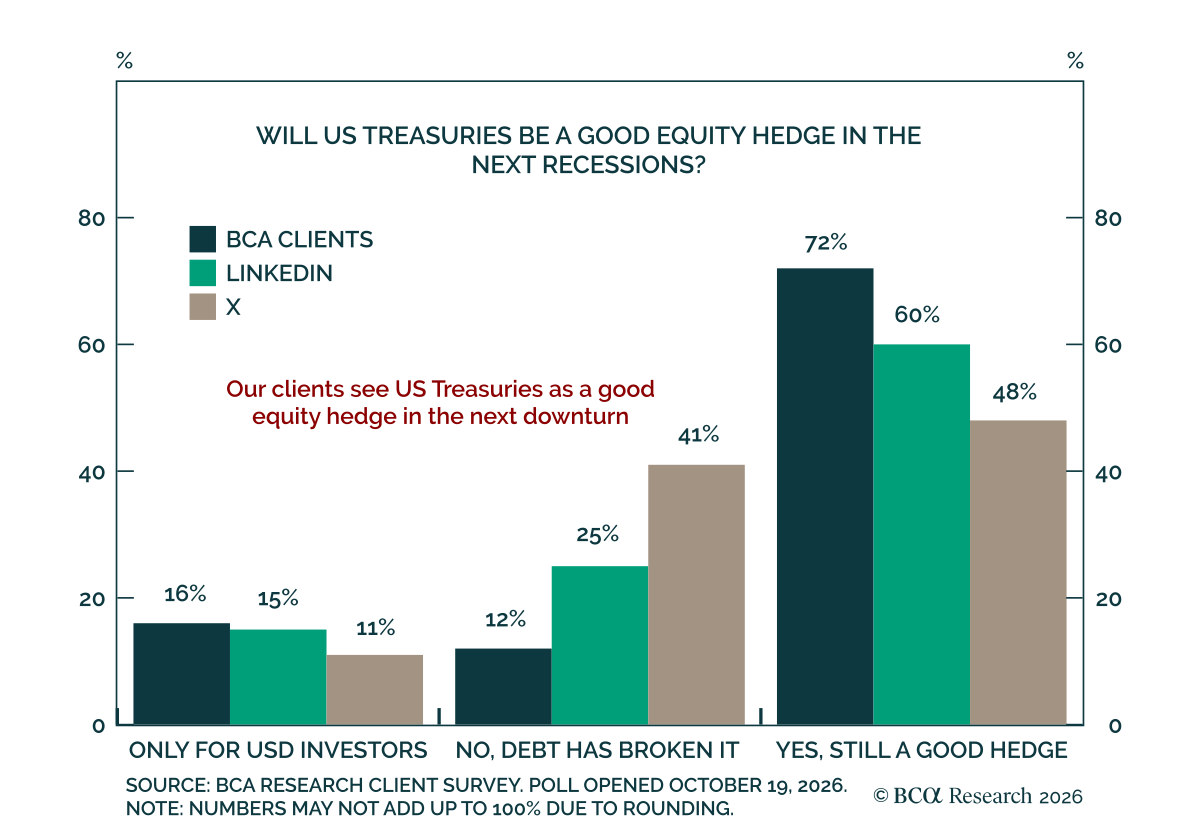
An overwhelming share of BCA clients expects US Treasuries to be a good hedge against equities in the next recession. In last week's poll, we asked our clients if they think US Treasuries will be a good hedge against equities in the next recession. 72% expect…
The median BCA strategist has downgraded equities from overweight to neutral on a 12-month horizon in a global portfolio. The downgrade is more a reflection of our low conviction in the previous overweight than a change in our broader outlook. Two factors…
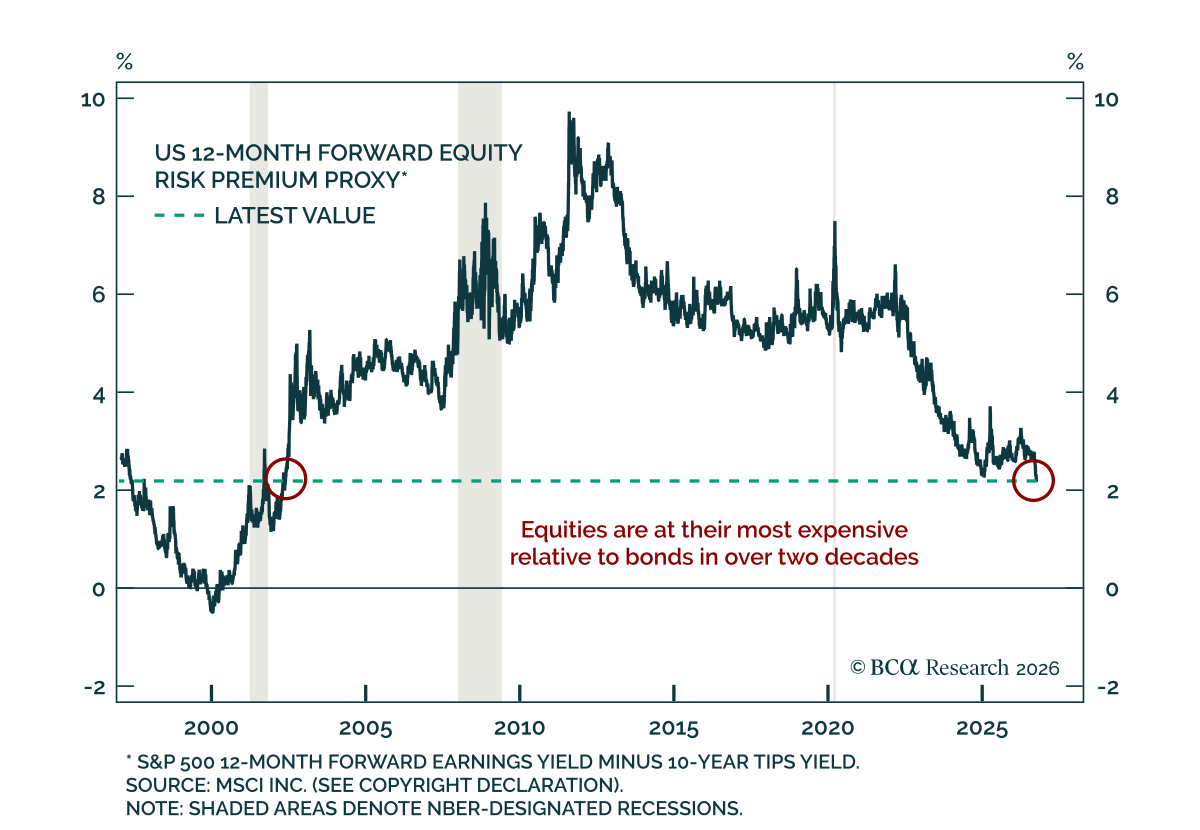
Relative to bonds, equities have become the most expensive in over two decades. Investors often examine P/E ratios in isolation, but equity valuations should take the prevailing level of bond yields into consideration. In a world with low risk-free rates of…
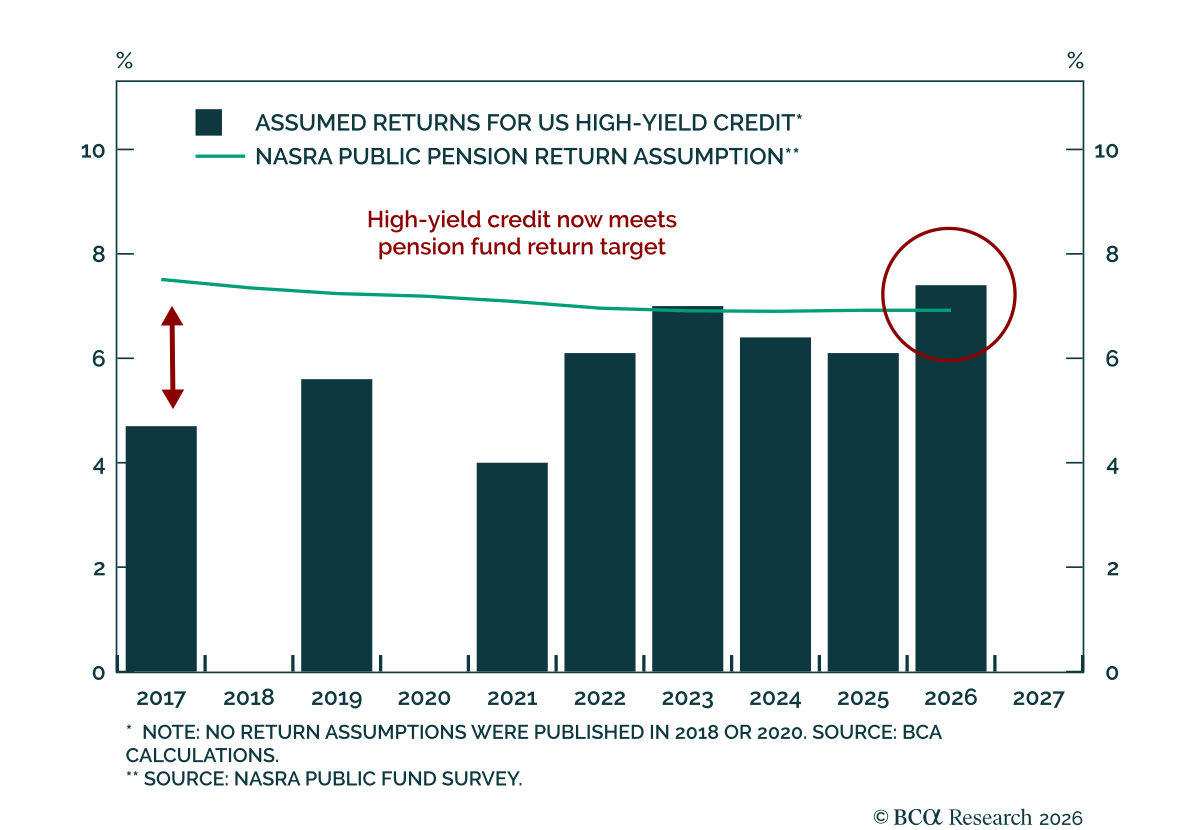
Our Portfolio Construction strategists maintain their overweight to high-yield credit, both within their public asset allocation and versus Private Credit. Higher government bond yields have reset the opportunity set. BCA's capital market assumptions project…

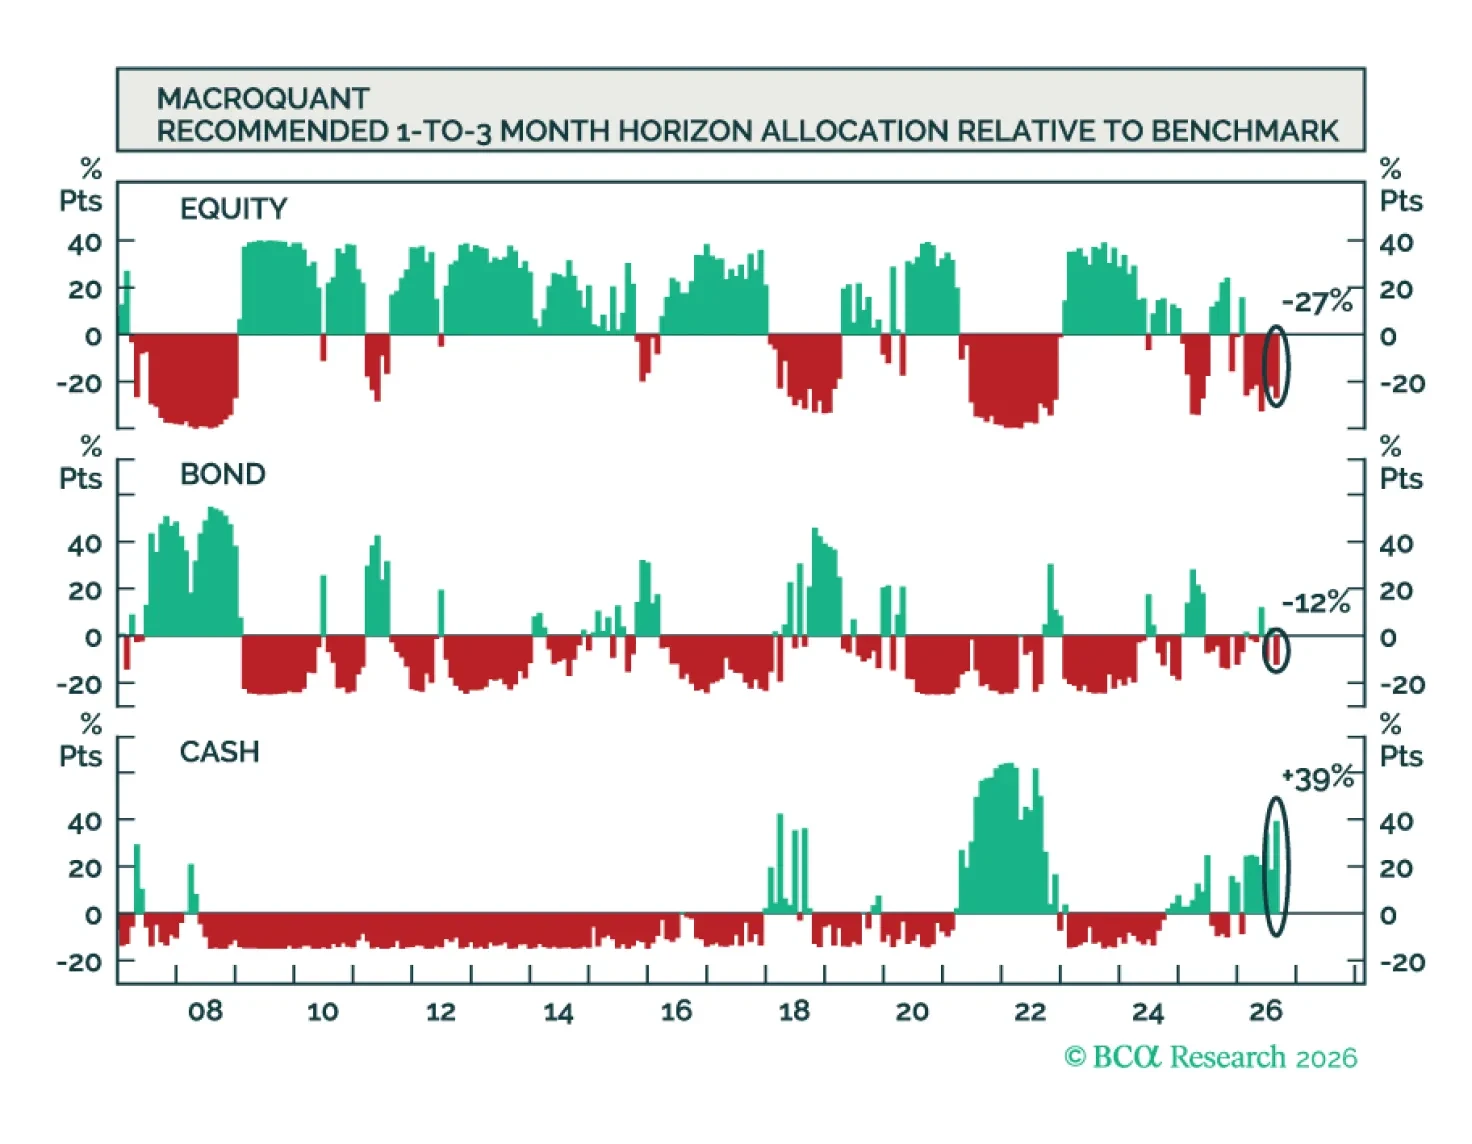
MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.
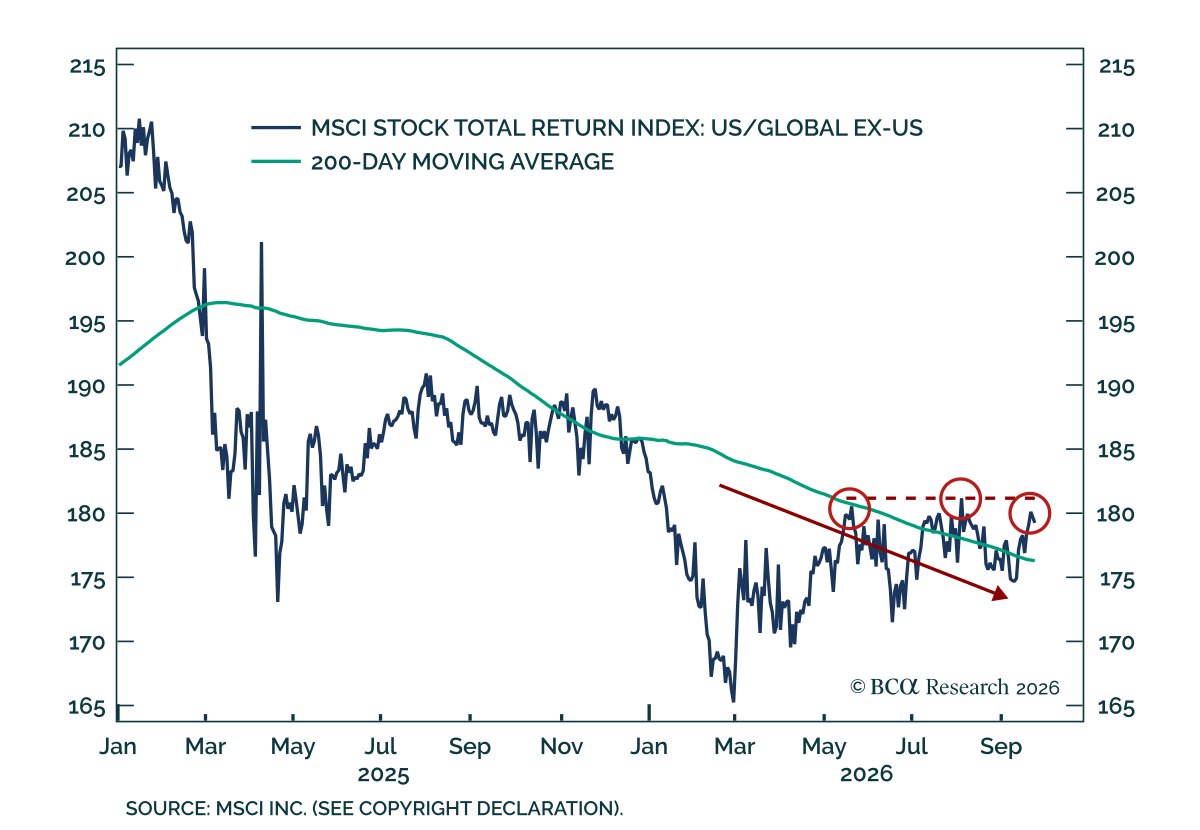
The consensus among BCA's strategists remains overweight equities and neutral across bonds and cash on a 12-month horizon. Within equities, the US moves to underweight relative to MSCI ACWI on a 12-month view; on a 3-month horizon, we remain overweight.…
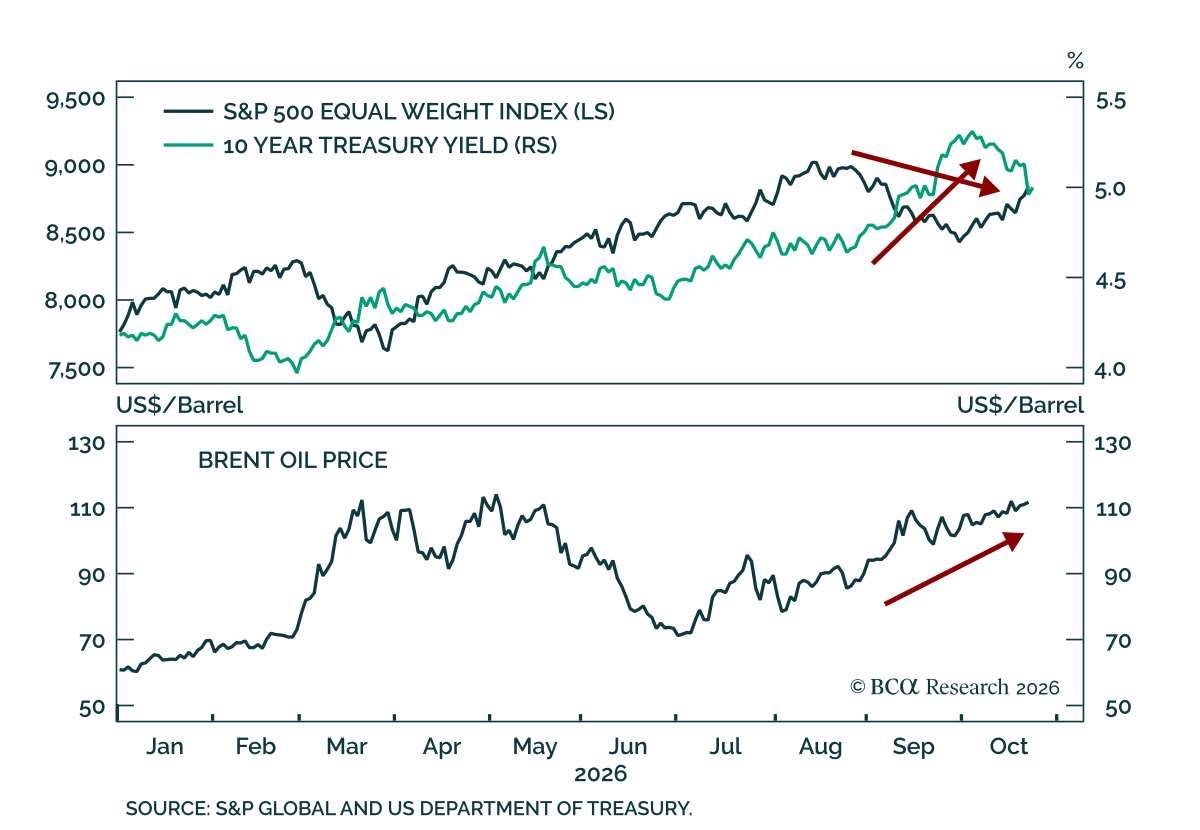
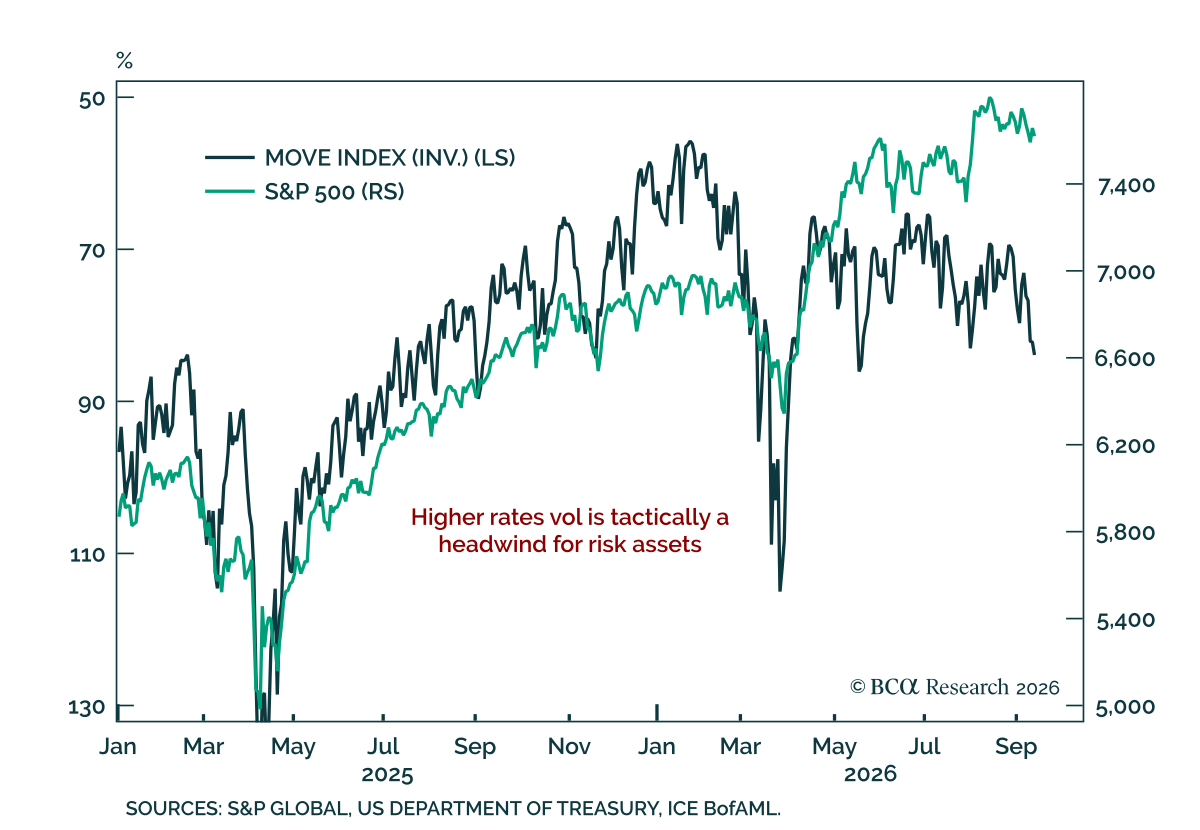
Higher bond yields are becoming a more important risk for equity markets, but the implications depend on whether Fed tightening remains mild or develops into a genuine hiking cycle. At our September Views meeting, our US Bond strategists outlined two…
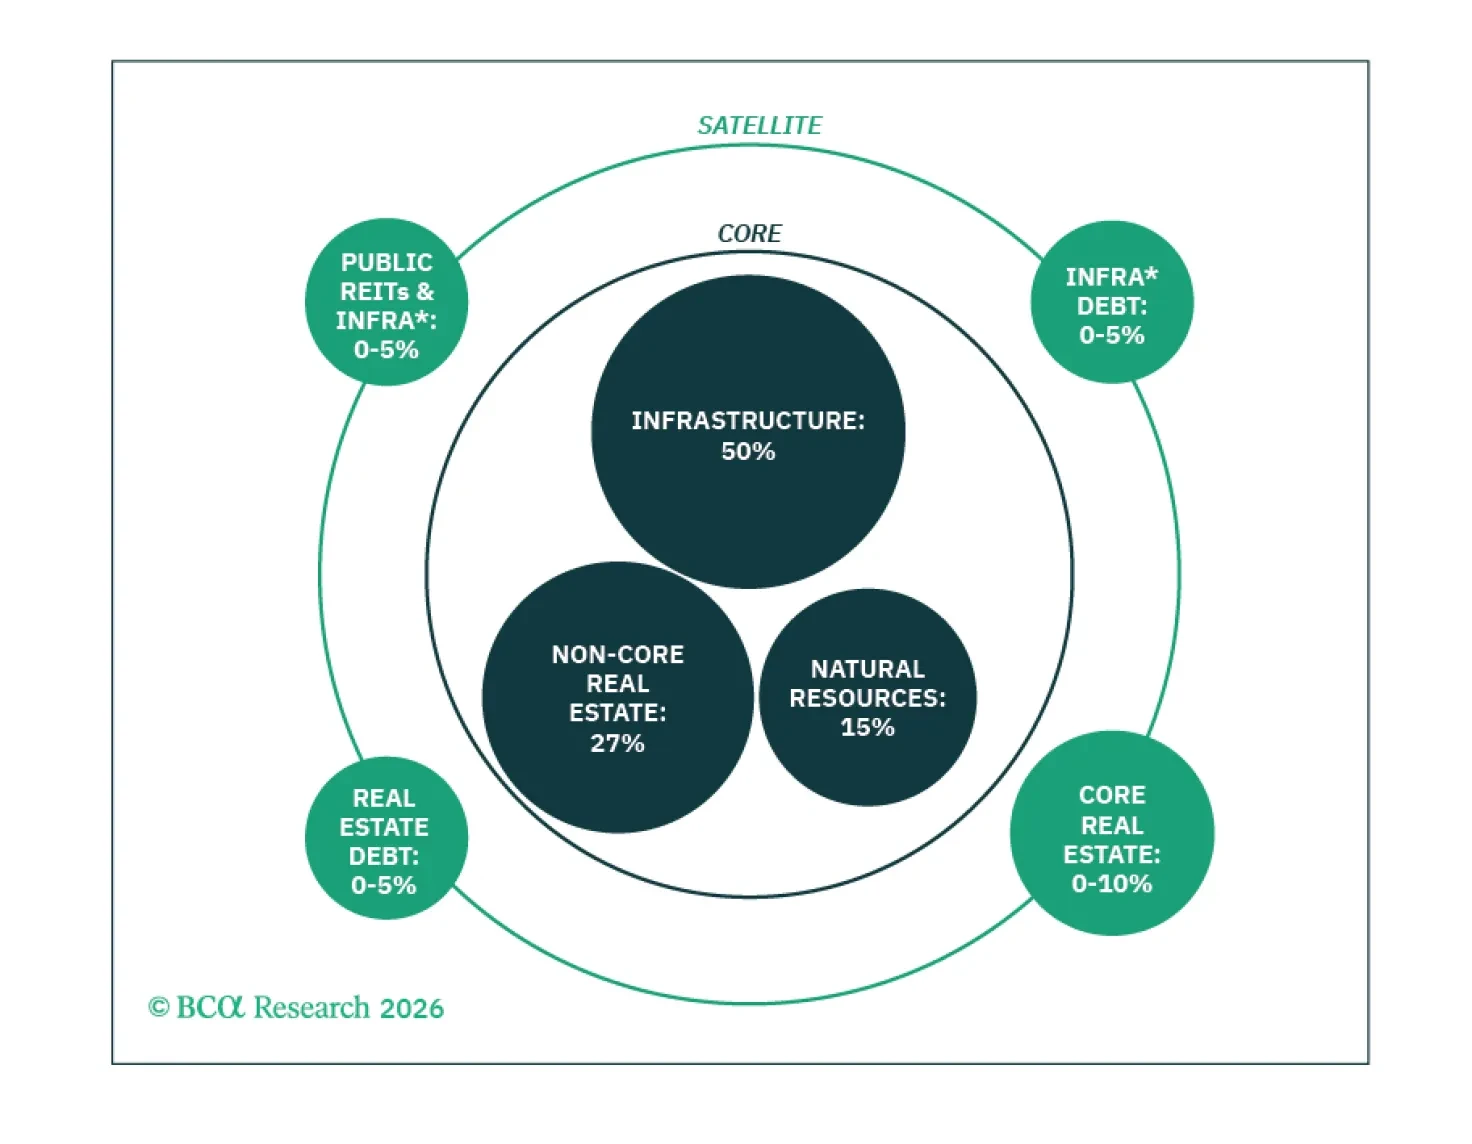
Special Report

Real Assets remain underweight in investor portfolios, a gap the 2020s bond bear market has exposed. We provide specifics on constructing a portfolio that supplies more than diversification, it delivers return. The specific weightings may not fit every investor, but the three core principles behind them can.