メインコンテンツにスキップ
メインコンテンツにスキップ

医療

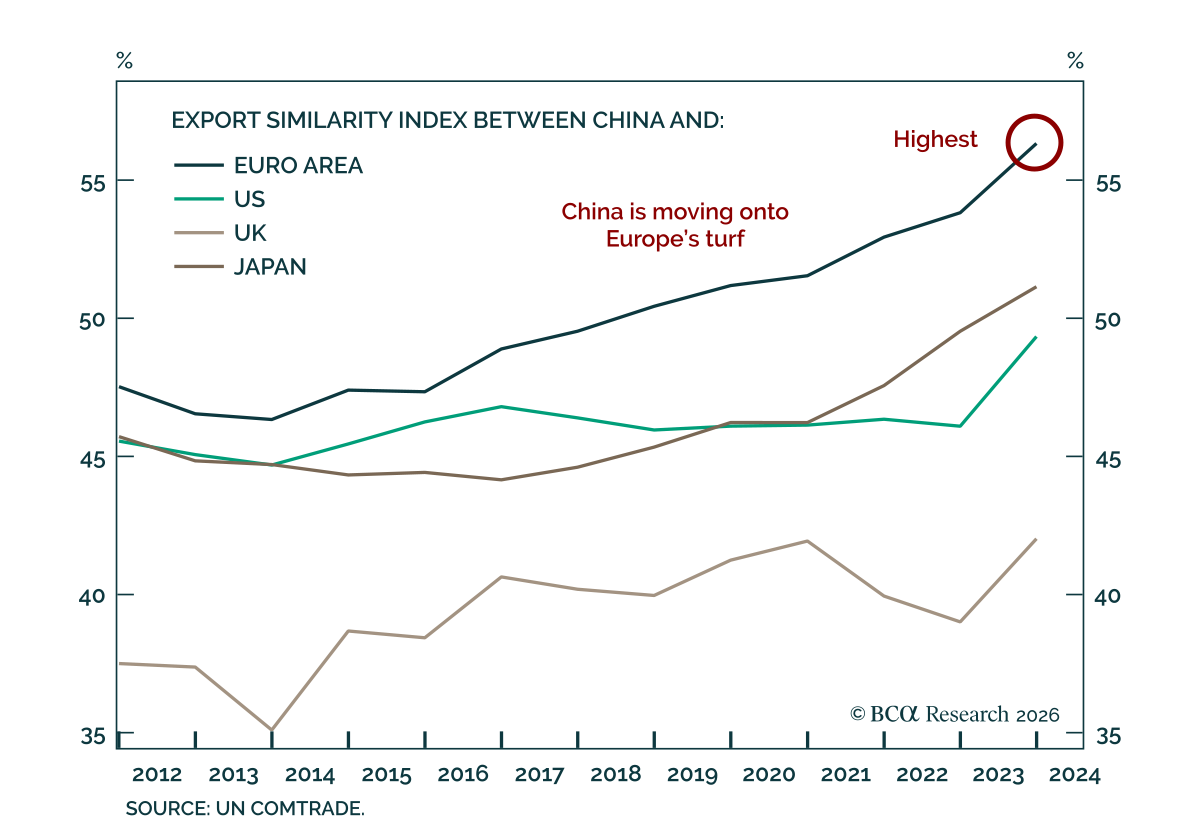
中国の産業の付加価値化の進展は欧州に構造的な挑戦をもたらしている。当社の Chart Of The Week は Chief European Strategistである Jeremie Peloso によるものである。China shock 1.0 は概して欧州に利益をもたらした。中国は安価な労働力と低付加価値財を供給し、欧州の輸出企業に世界人口の約6分の1に相当する市場へのアクセスを提供したのだ。 China shock 2.0…
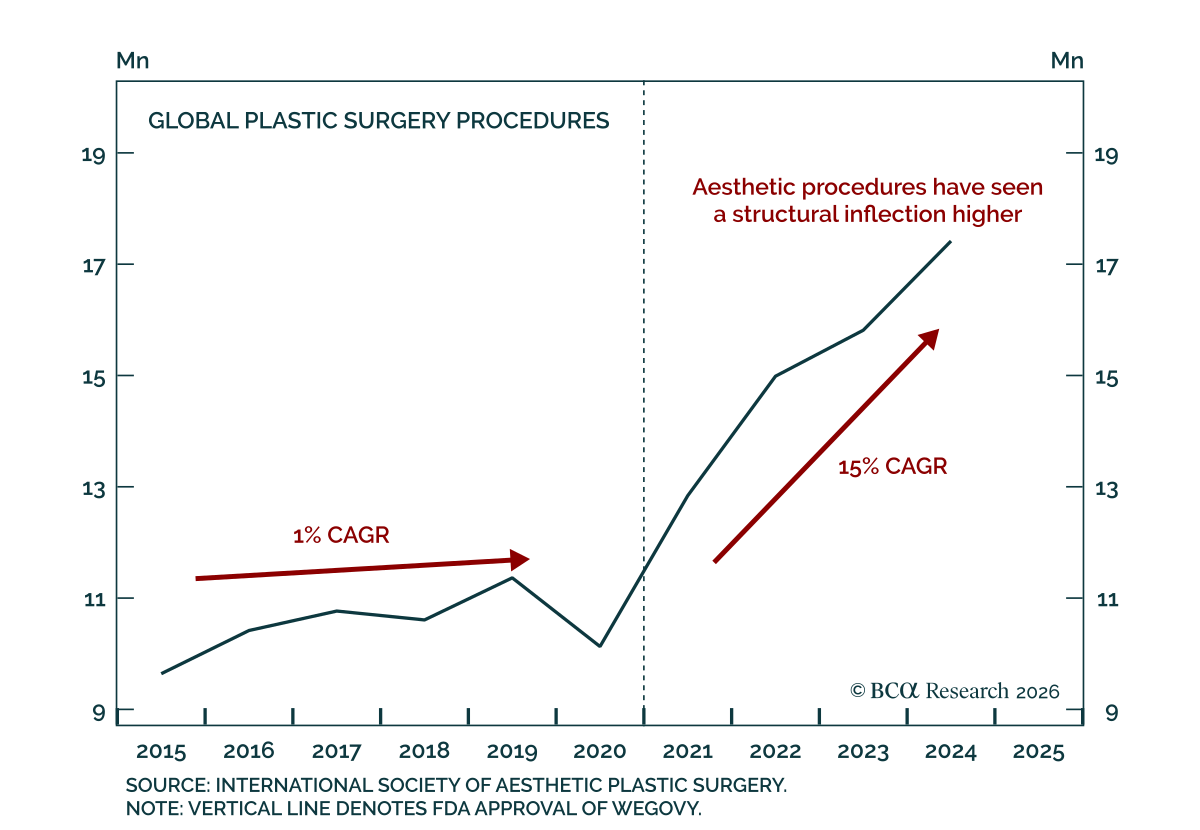
当社の portfolio construction ストラテジストは美容関連テーマをロングで、GLP-1の製造企業、バイオスティミュレーター注入剤、K-Beautyの受託製造業者を重視している。 リモートワーク、オンラインデーティング、人口動態の変化が見た目のプレミアムを高めてきた一方で、GLP-1薬は体重減少を安価かつ容易なものにしたのである。 当社の同僚は市場が普及の行方をなお過小評価していると見ている。 それらの薬の副次的効果である「Ozempic…
特別レポート リモートワークやオンラインデーティングの台頭などの人口動態の変化が美容への需要を高めている。GLP-1sは肥満に対する効果的かつ安価な治療法を提供し、副次的効果である「Ozempic face」により美容施術とスキンケアの需要を構造的に変えた。その結果、恩恵を受けるのは、GLP-1製剤メーカーのロング、バイオスティミュレーター注射剤メーカー、そしてK-Beautyの受託製造業者である。

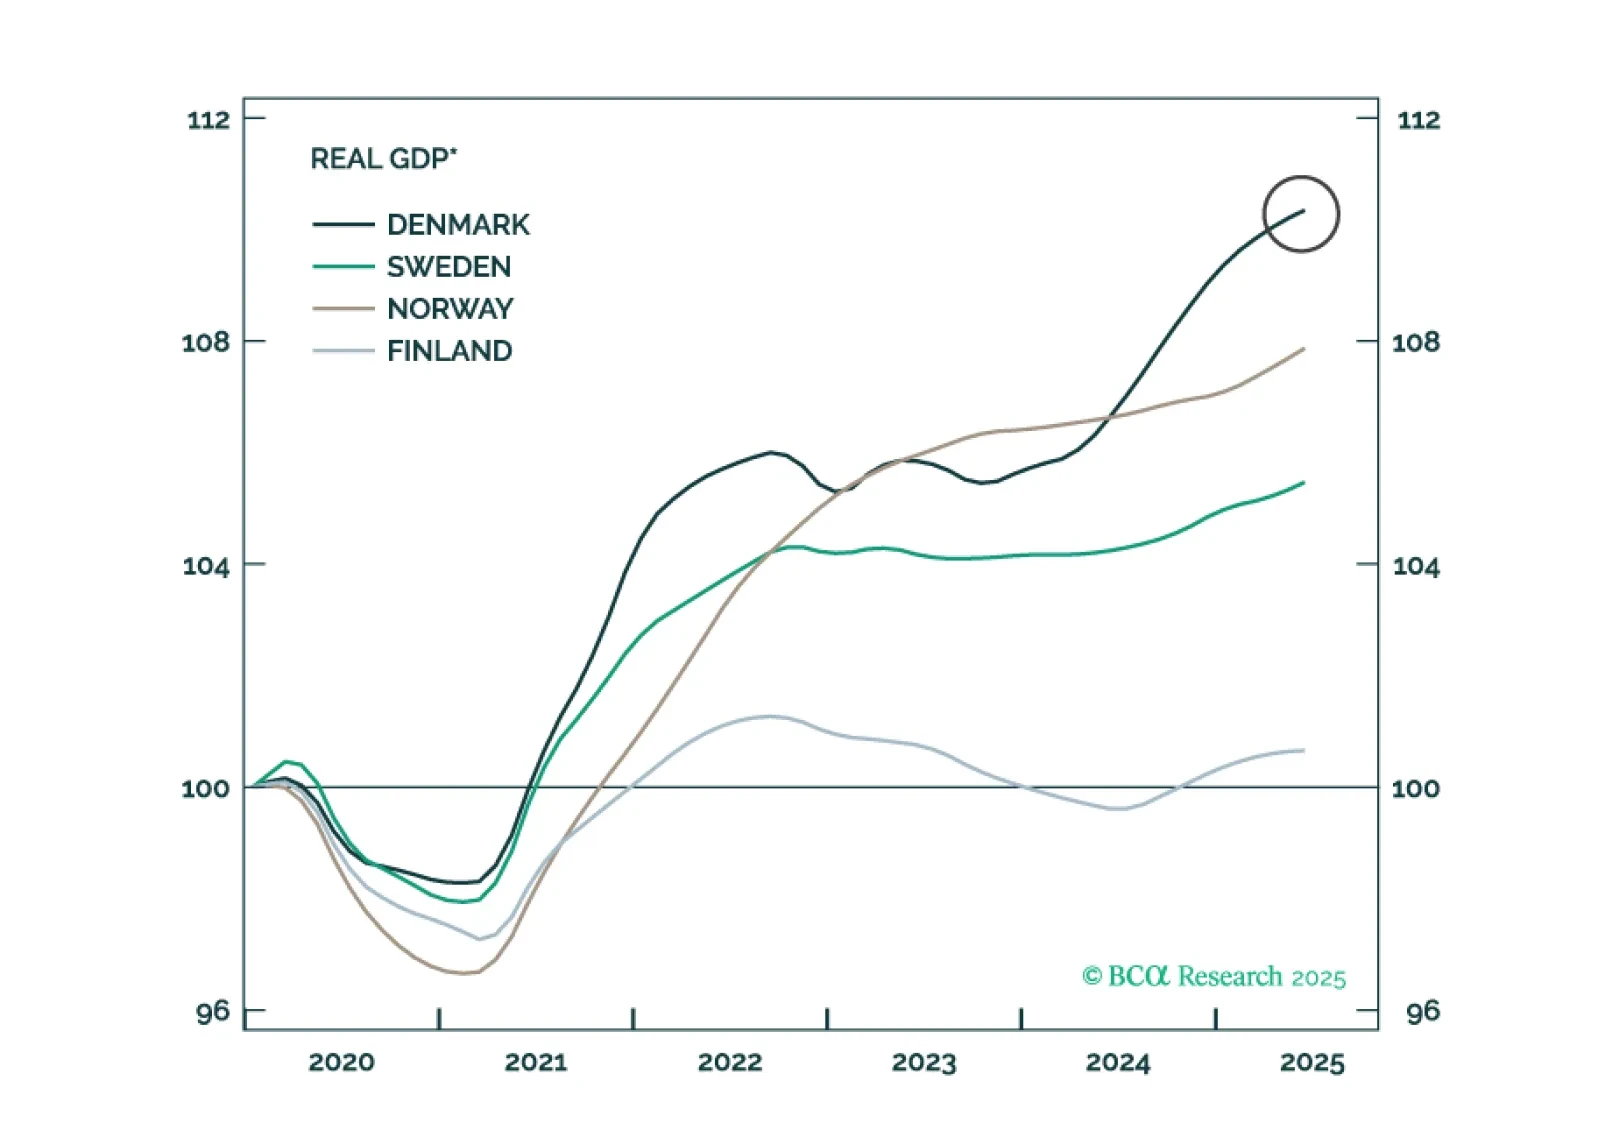
北欧の中央銀行は現在、ポーズモードで足並みを揃えていますが、それぞれの経済は分岐しています。スウェーデンの見通しが改善し、ノルウェーの逆風が強まる中、私たちはスウェーデン株式をオーバーウェイトし、NOK/SEKをショートしています。
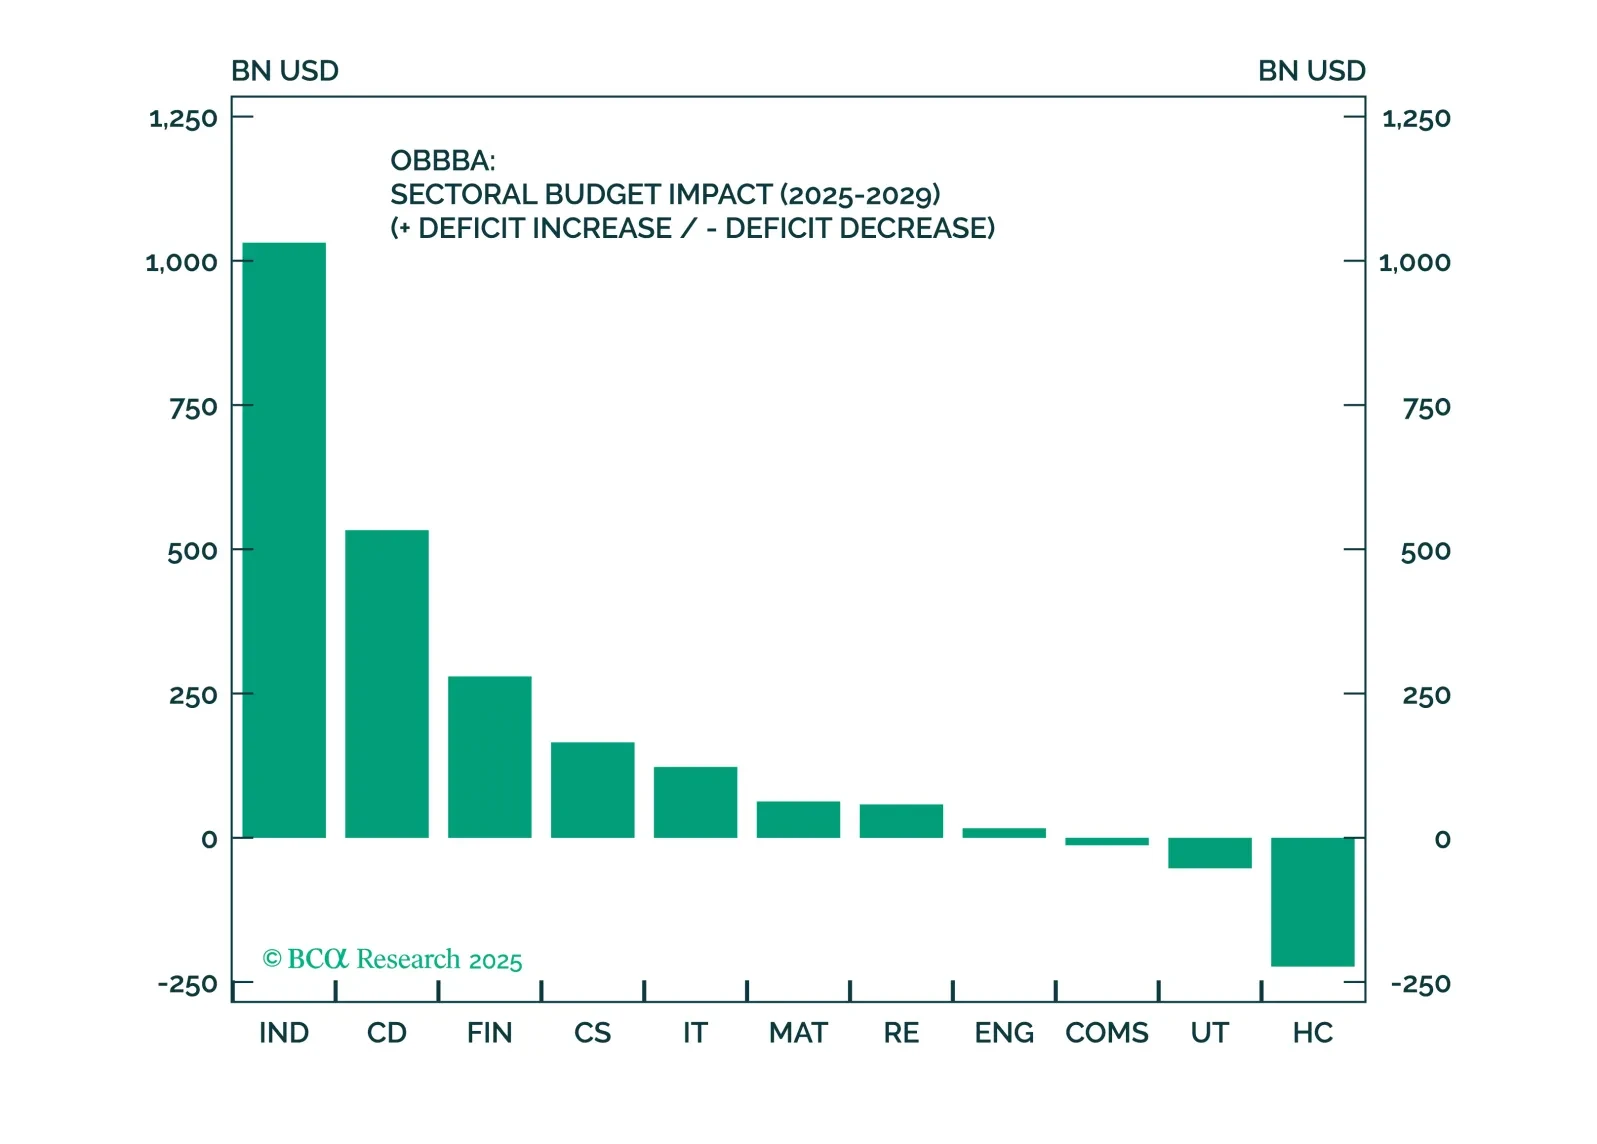
特別レポート

マクロ経済の逆風にもかかわらず、OBBBAは産業株、金融株、および一般消費財株のエクイティセクターを明確に支持しています。これらのセクターにおける十分に構築された、ファクターを意識したバスケットは、財政主導の不確実な環境においてアウトパフォームする良いポジションにあります。
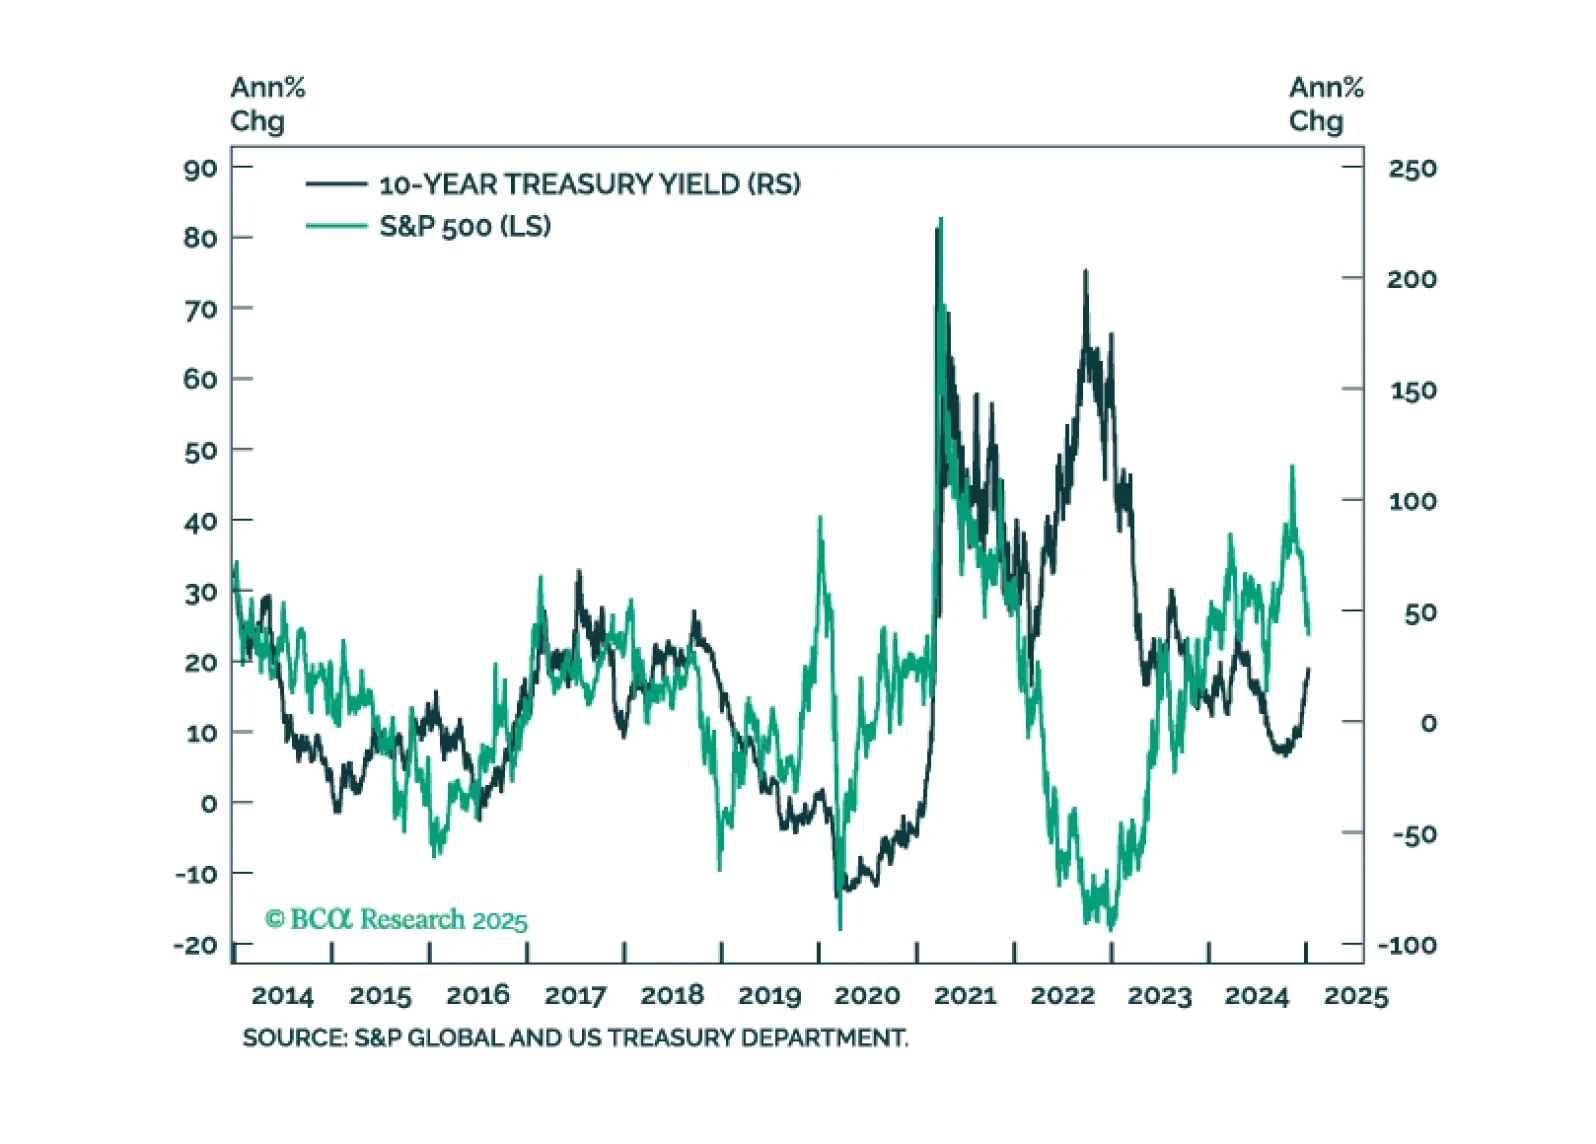
In this first presentation of 2025, we start with an overview of the 2025 outlook webcast polls, and a brief post-mortem of the 2024 market performance. Then, we shift gears and examine what is behind the recent surge in bond yields and its implications for equities. We also review market technicals and positioning and conclude with a list of trades to prepare our portfolio for continued moves in yields.
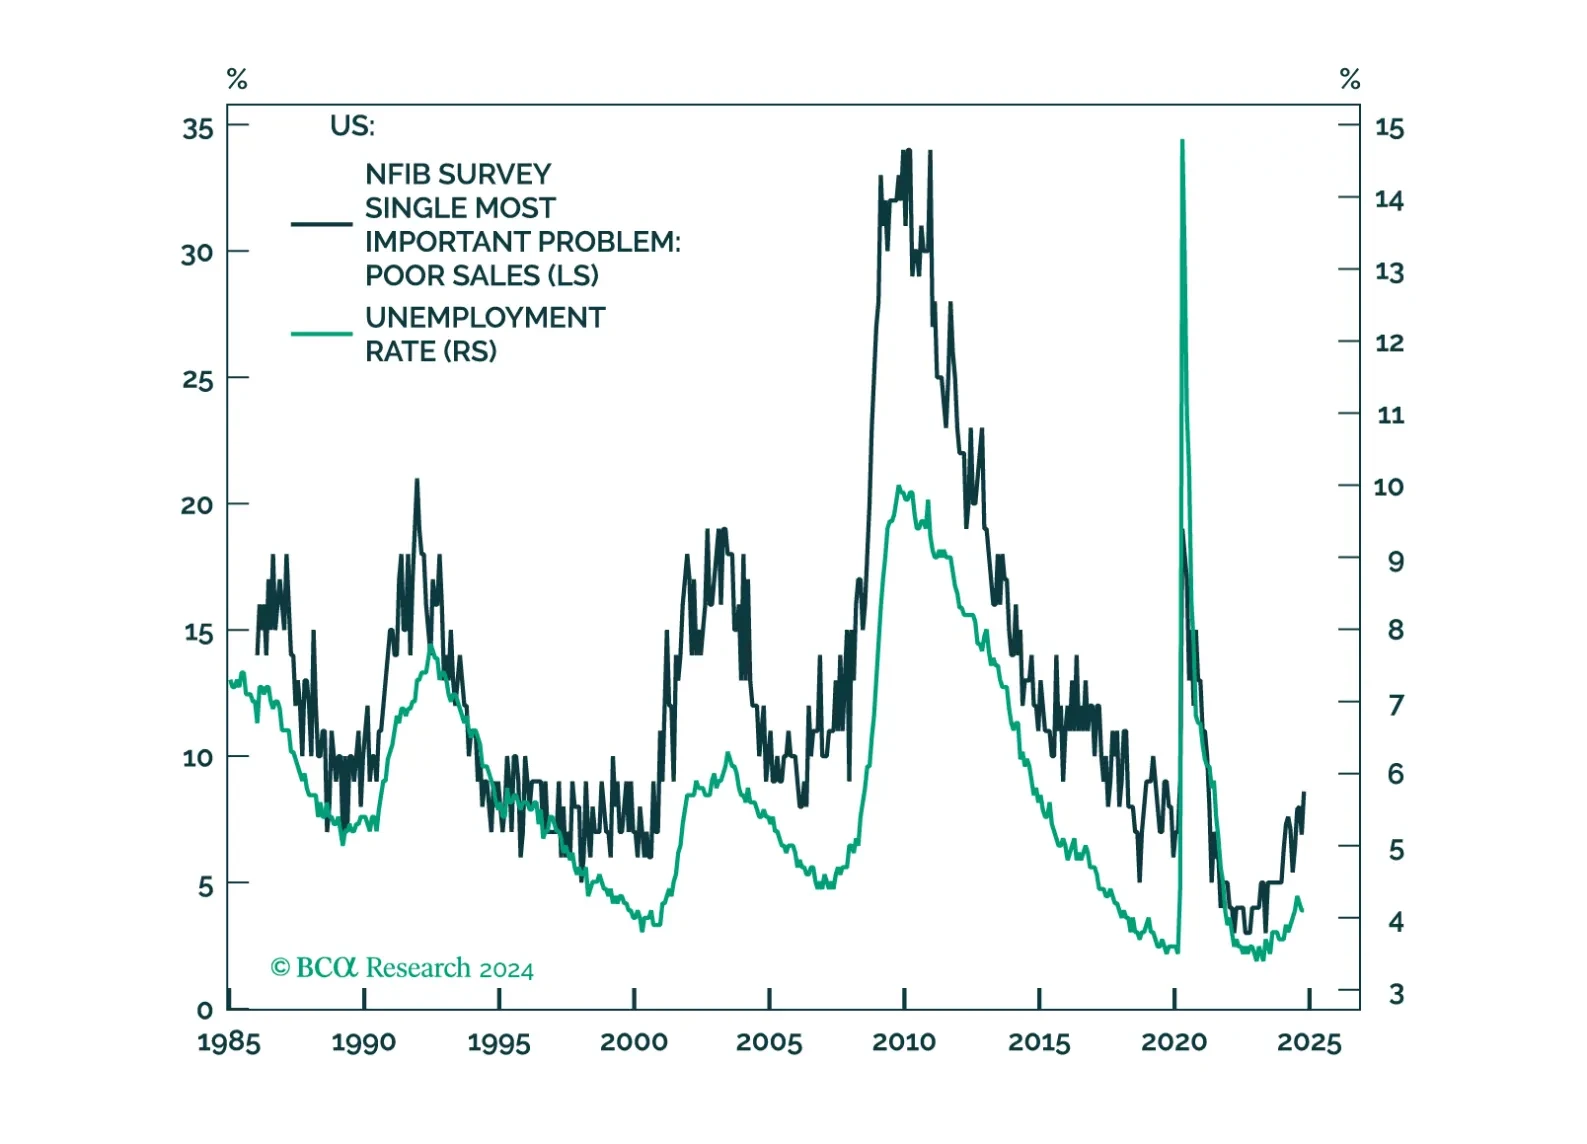
The post-COVID recovery has been one of excesses. Government deficits have ballooned, tight labor markets have led to a windfall of consumer spending, and equity valuations have soared on the back of lofty growth expectations. But these excesses will no longer be sustainable in 2025. Our theme for next year is Thin Is Back In. Government budgets, economic growth, and equity valuations will be leaner than investors expect. We discuss this the reasoning behind this macro view and the asset allocation implications that follow from it.

Our US Equity Strategy colleagues expect Q3 earnings to be strong enough to fuel the soft-landing narrative. Analysts expect S&P 500 earnings growth to be 4.0% year-over-year, with sales growth of 4.0% too. Yet, with average surprises of 5.6% for earnings and…
According to BCA Research’s European Investment Strategy, the low rate of innovation in Europe is a major problem for the economy. Not only does it prevent Europe from standing at the technological frontier, but it also contributes to the low rate of…
Investors are pricing in a soft landing in the US. Notably, we noted that pro-cyclical assets topped the performance ranking in August. At the same time, the S&P 500 is currently trading only 1% below its all-time highs. However, investors are also seemingly…