フランス
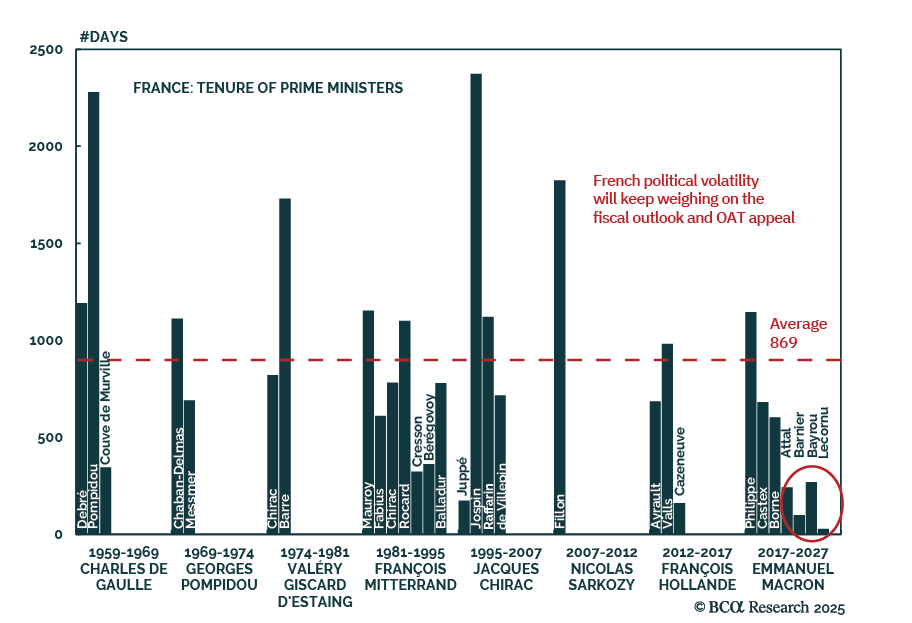
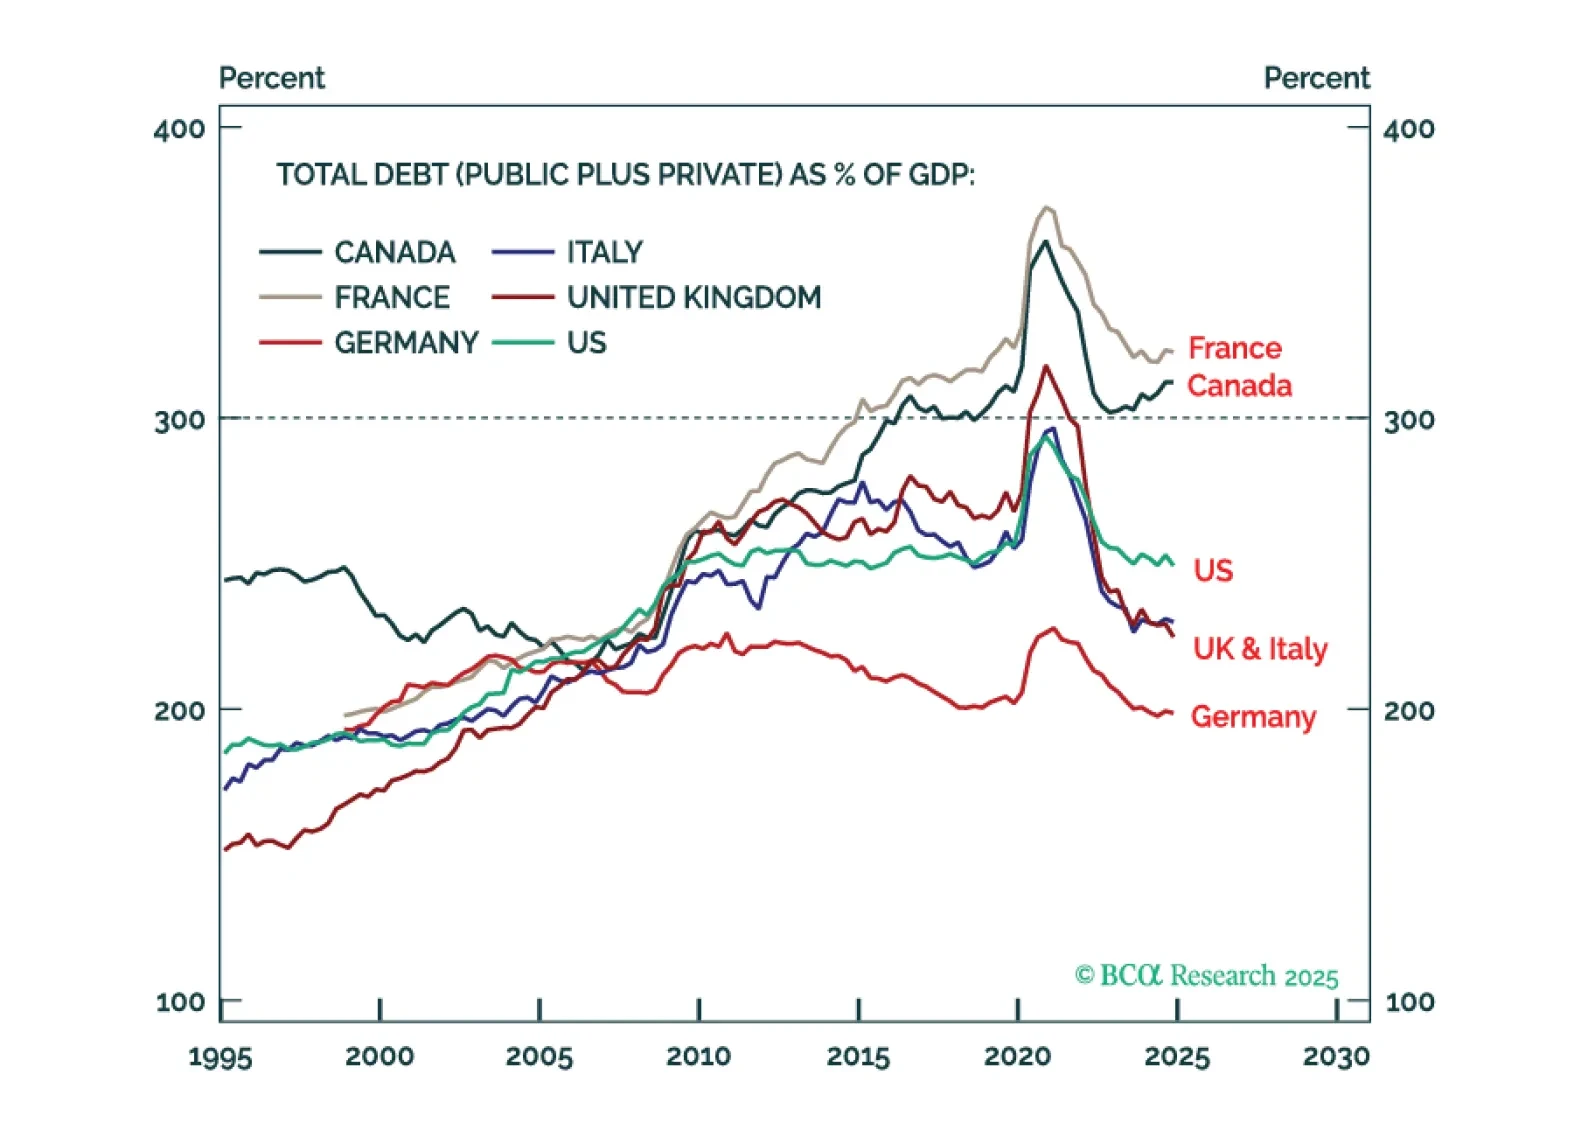
現在、複数の標的に対して債券市場の監視者(ボンド・ヴィジランテ)が動いています:フランス、イギリス、日本。しかし、フランスは以下の有毒な組み合わせにより最も脆弱です:総債務比率が300%をはるかに超えていることに加え、G7で最悪の基礎的財政赤字に加え、政治的停滞(特に、フランソワ・バイル首相が少数政府における9月8日の信任投票で敗れれば、さらに状況が悪化する)。ECB(欧州中央銀行)がフランスを救えない理由とその投資への影響について説明します。加えて、グローバル資産配分のための全く新しい複雑性「ヒートマップ」を発表し、それが世界の通信サービス(WTEL)をアンダーウェイトする新たな戦術的取引につながる理由を解説します。
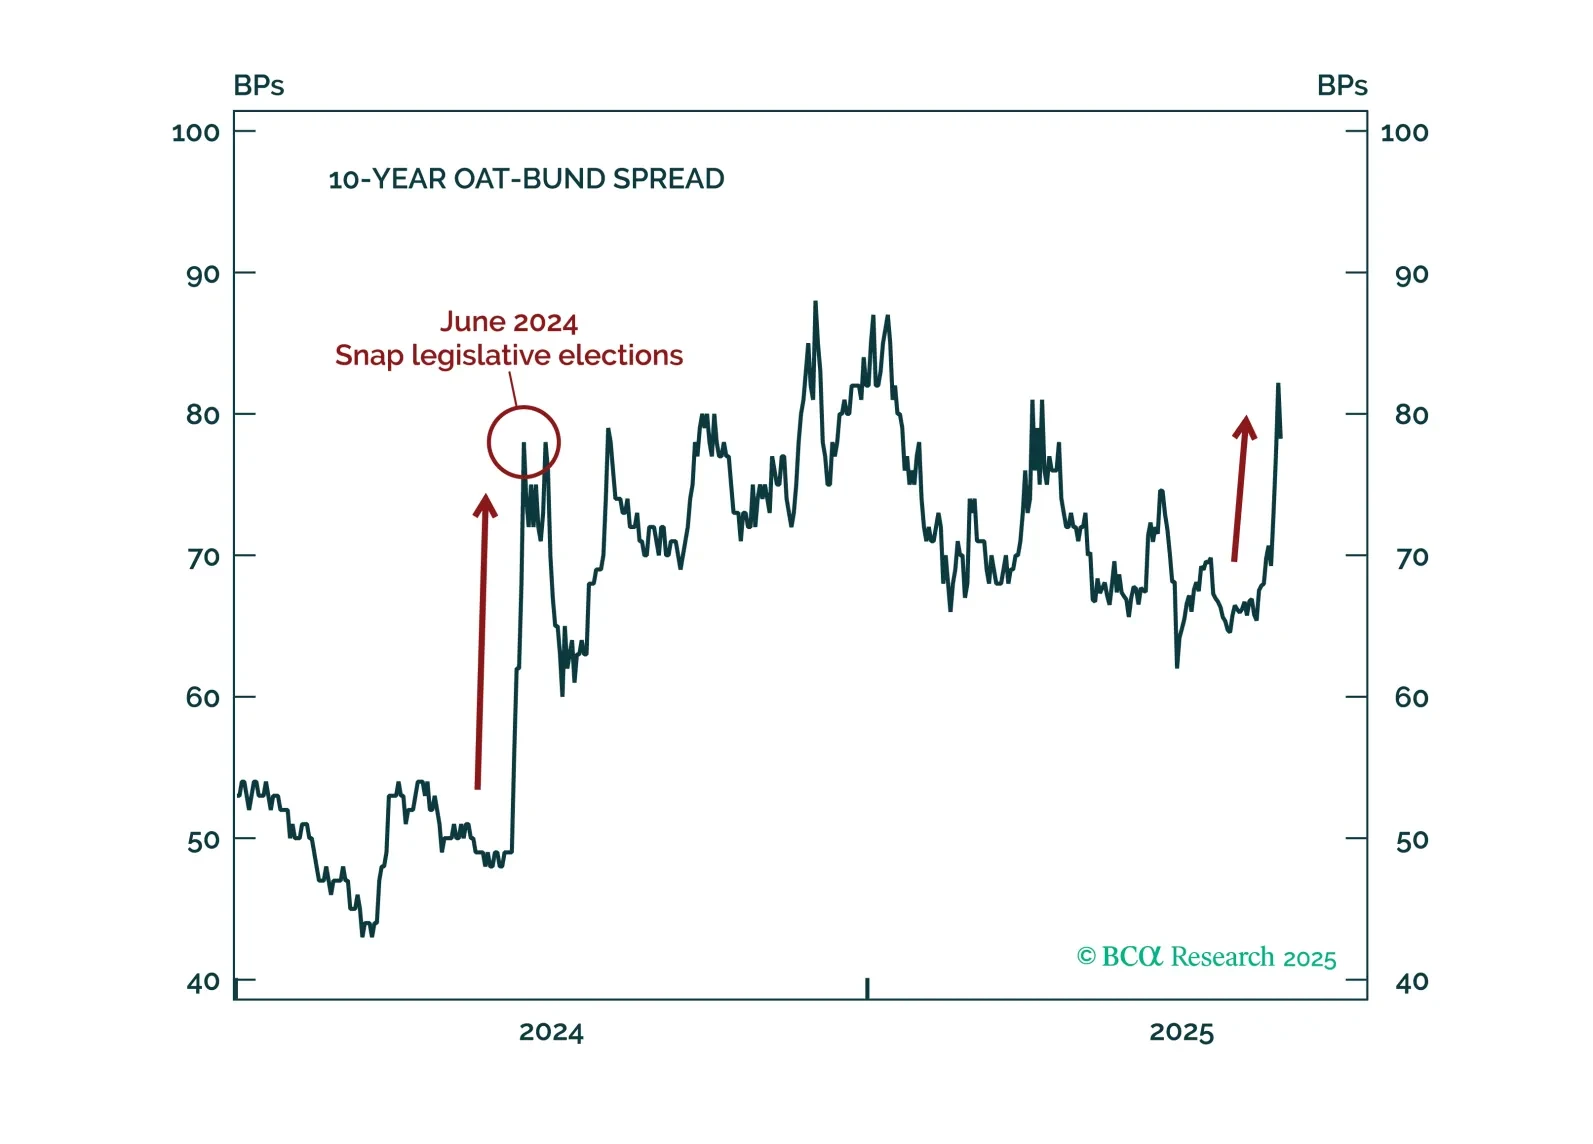
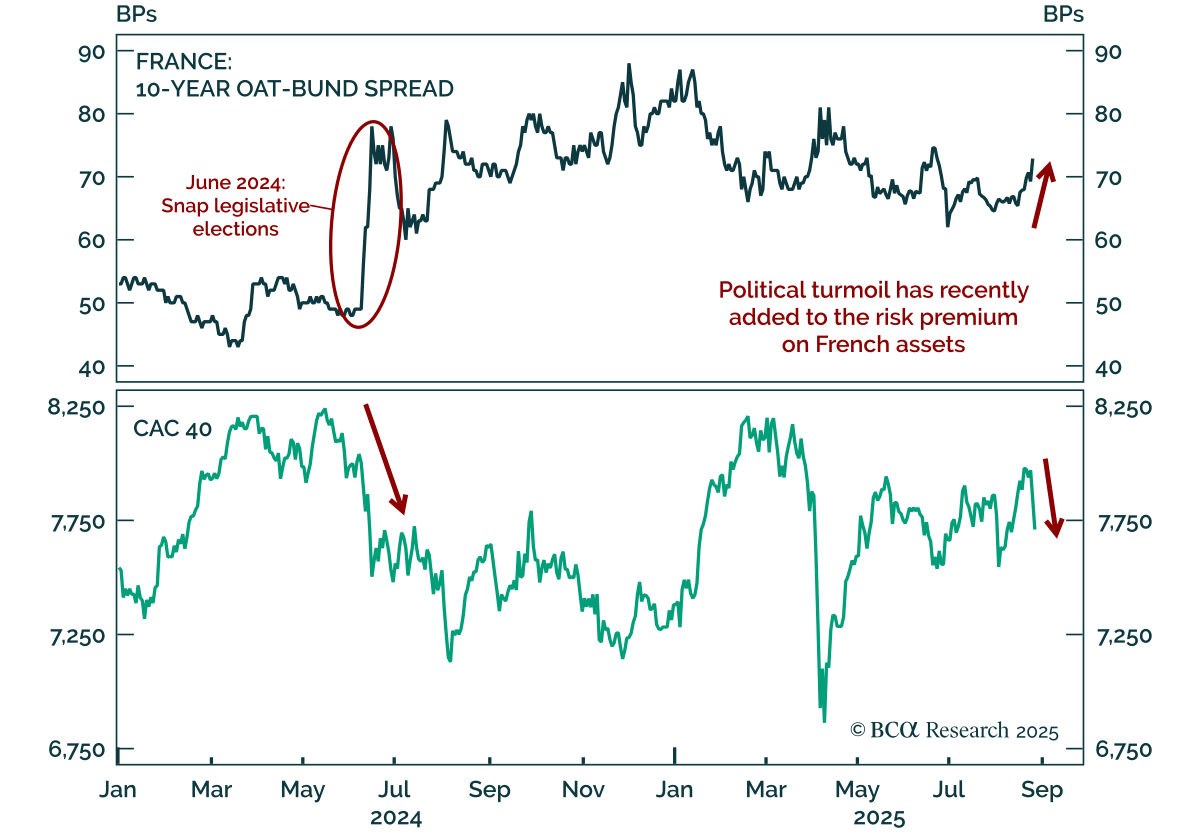
フランスではフランソワ・バイル総理大臣が信任投票に敗れたため、政治的不安定が続く見通しです。新しい総理大臣の任命は、同国の政治的停滞を終わらせることはなく、財政不安をさらに助長するでしょう。投資家はフランスOATを引き続きアンダーウェイトにするべきです。フランス株式、特にフランスの銀行株は、ディップ時に買い増しすることをお勧めします。

今週、私たちの3つのスクリーナーは以下を検討します:地政学的なヘッジとなる安価なイギリス株式、中国に敏感なフランス株式、そして米国のバリュー株および配当を支払う株式。
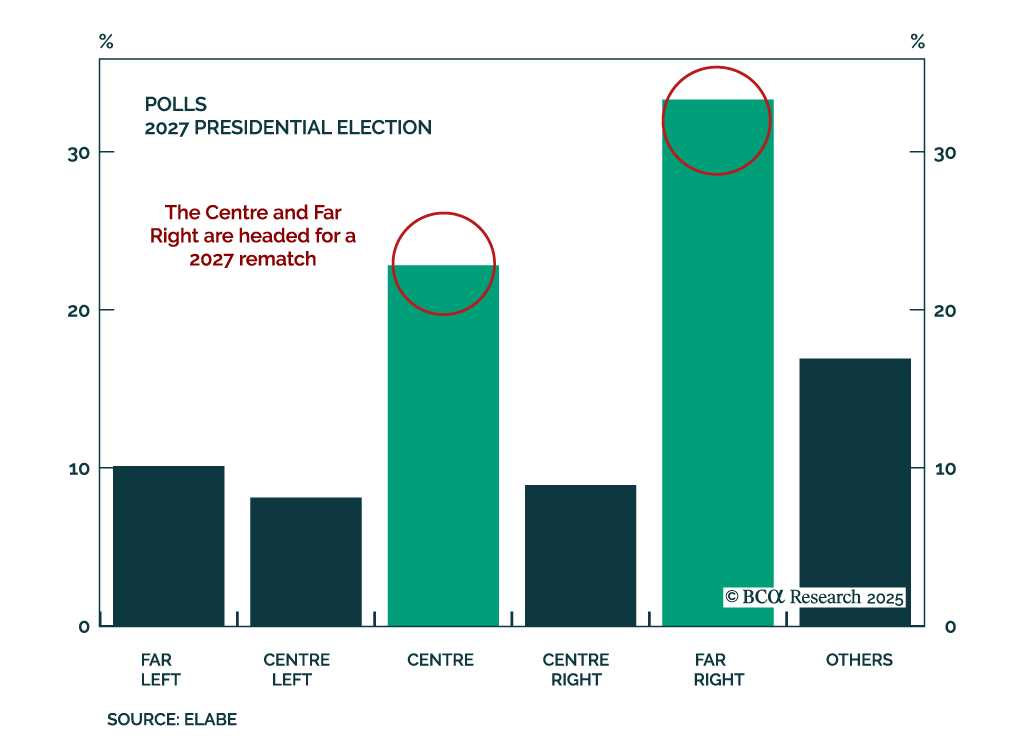
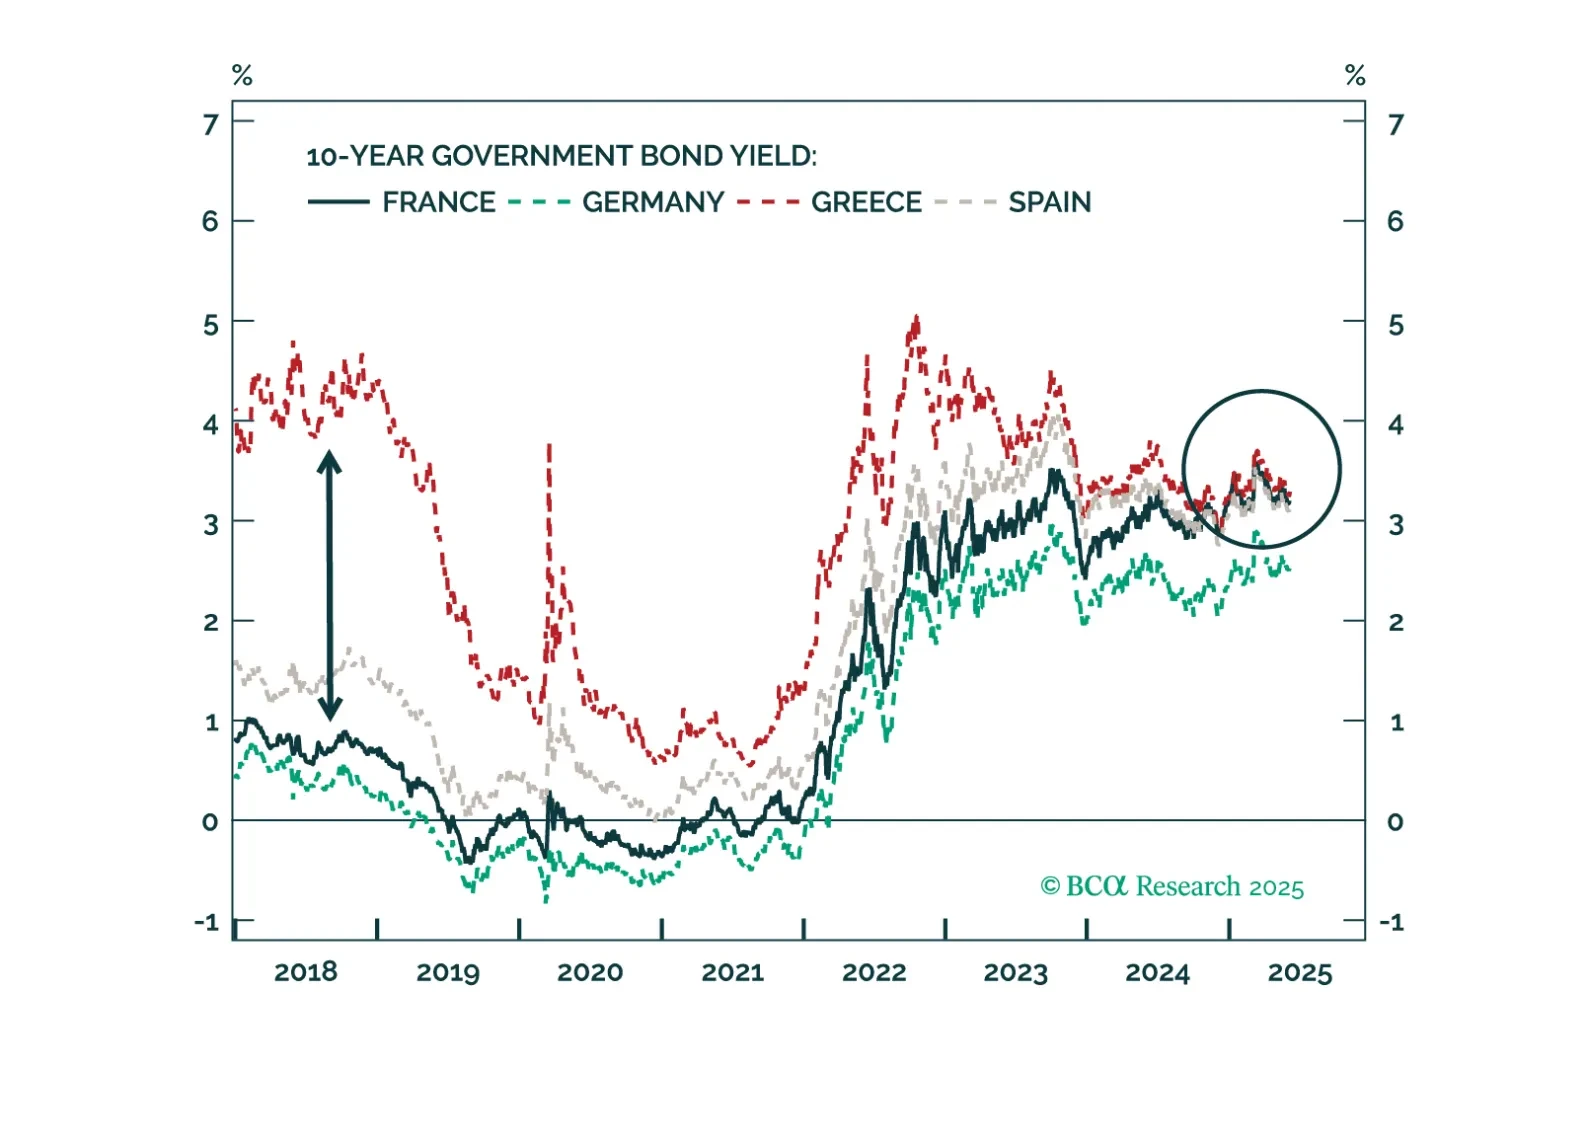
France’s political turmoil is far from over, and fiscal fears are growing. This is not a bond-friendly environment. In contrast, it is a good time to upgrade French equities. As the 2027 presidential race is about to begin in earnest, we make an early call on its outcome.
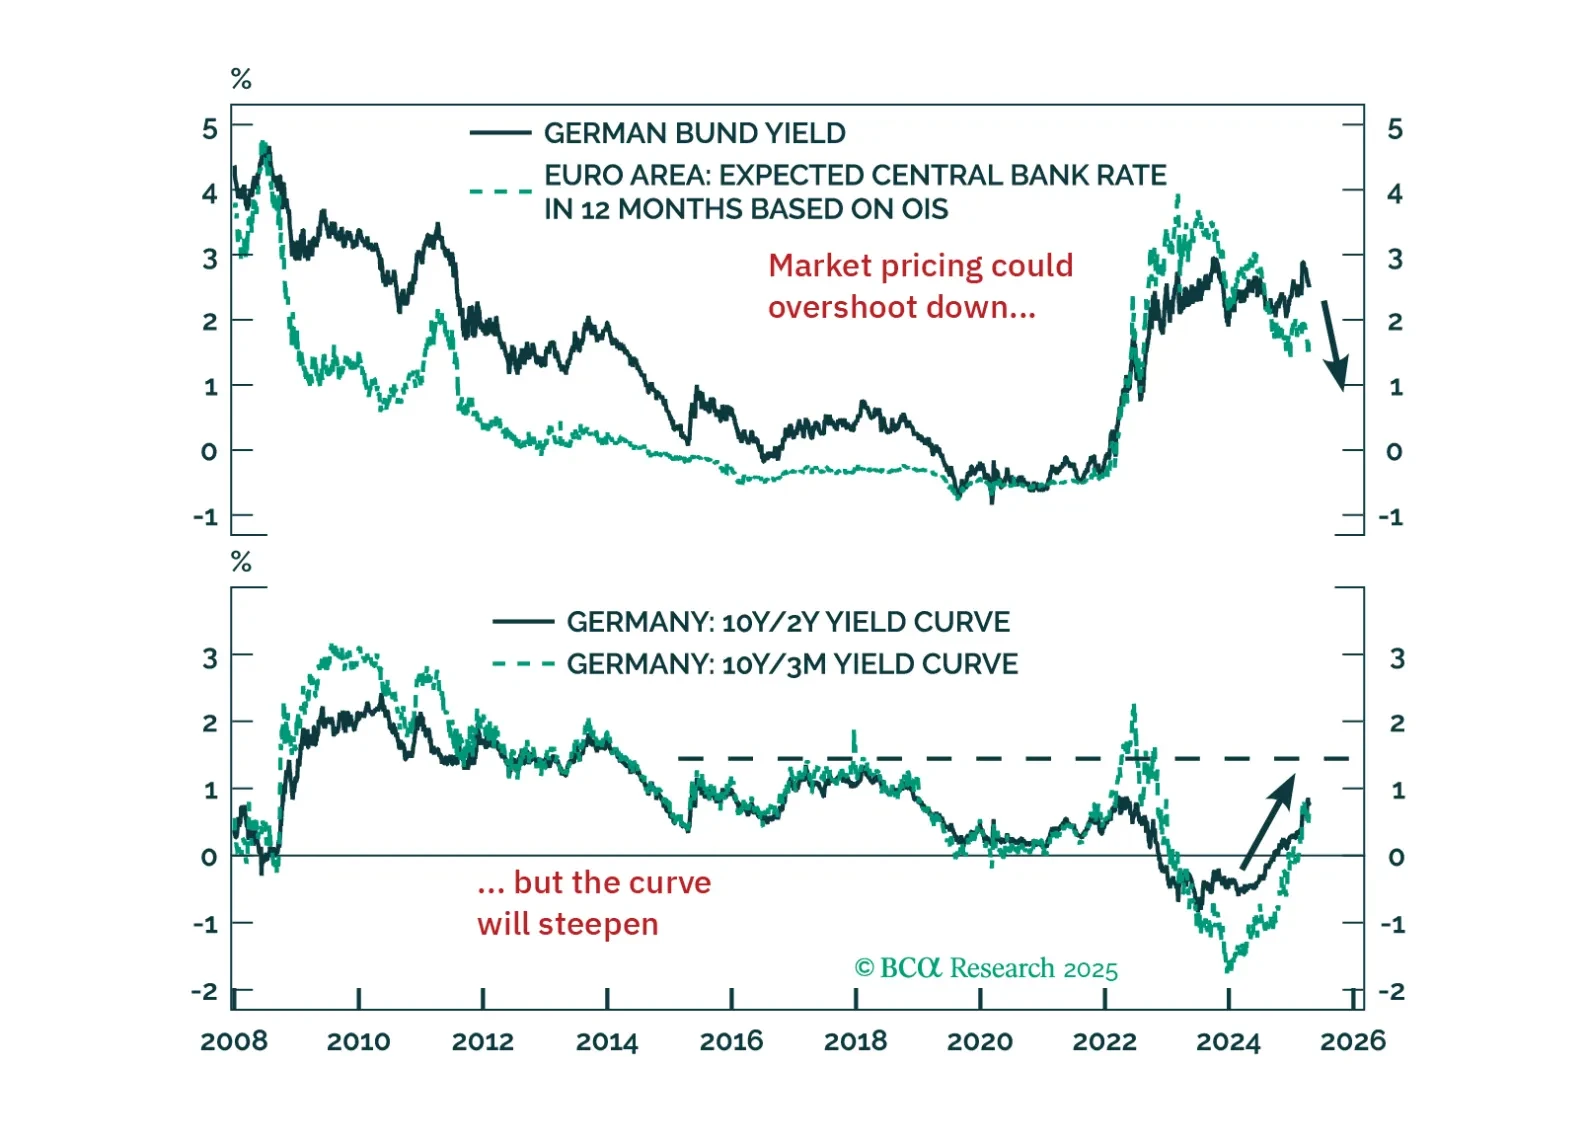
Europe’s deflation problem is getting harder to ignore. This week’s ECB cut is just the beginning — tariffs, the euro’s rally, and softening demand all point to more easing ahead. We explain what it means for yields, equities, and EUR/USD.
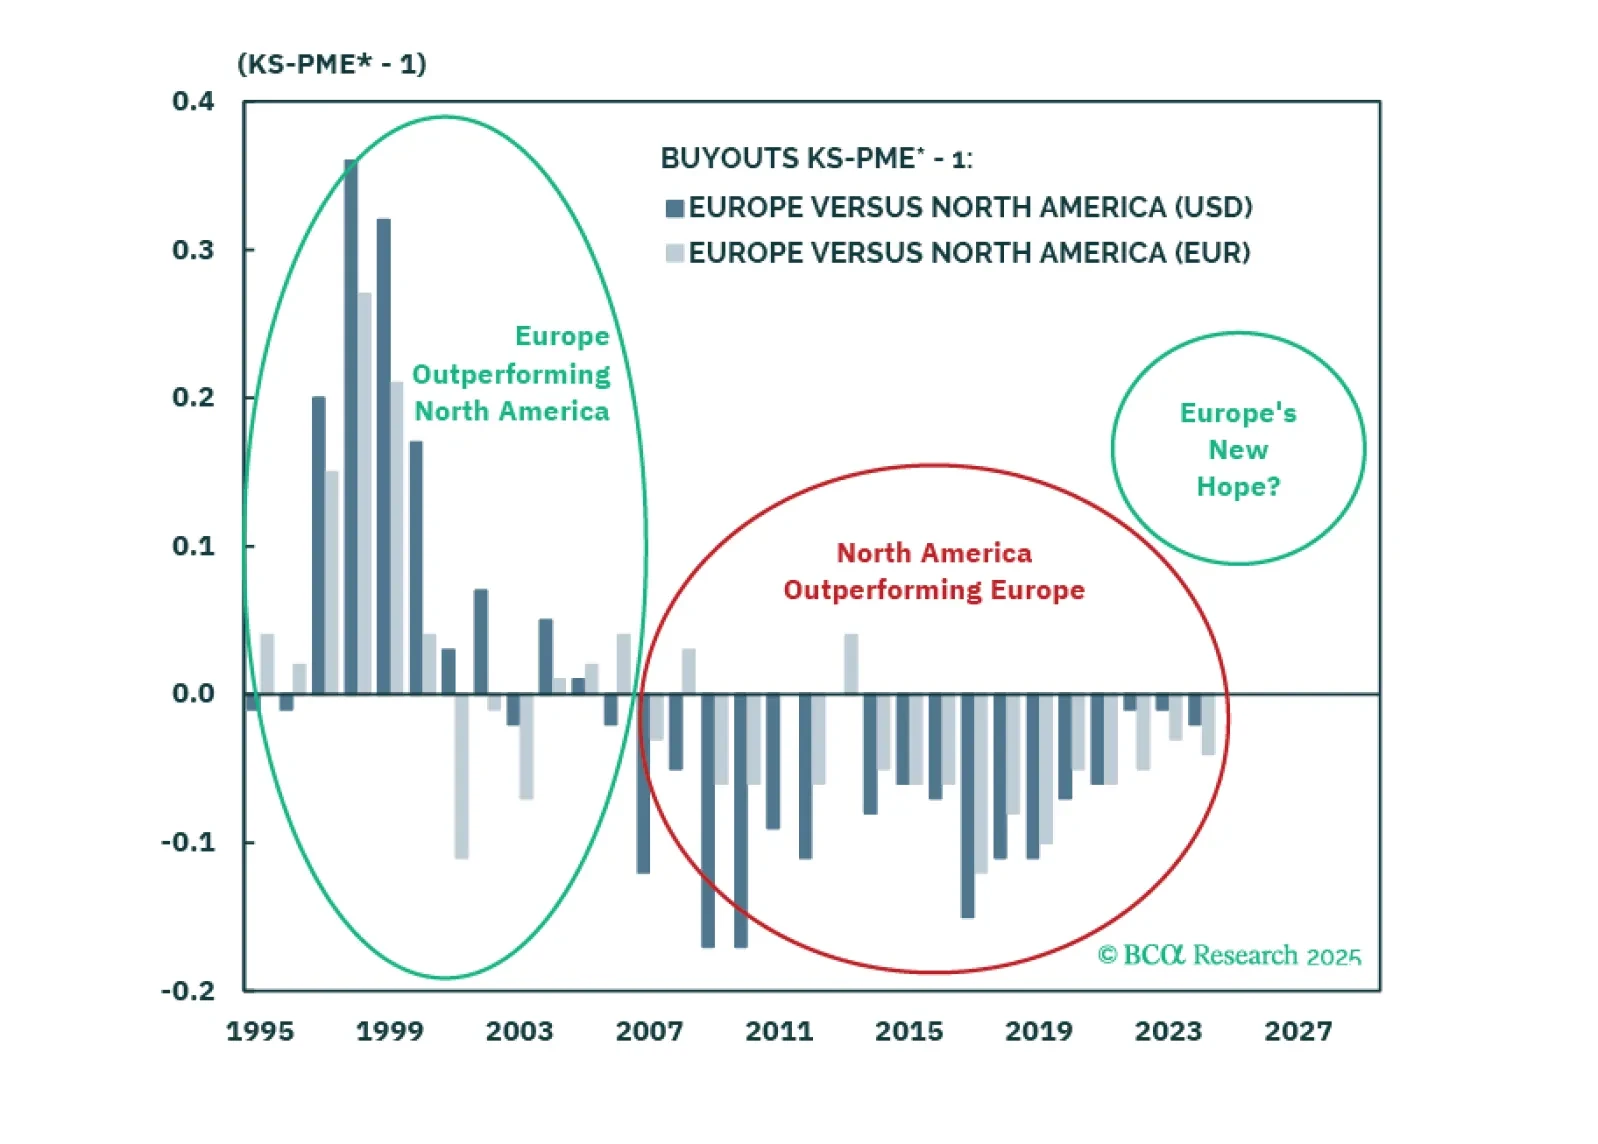
We are at a pivotal moment for Europe, supported by structural reforms and macro catalysts. While expanding credit markets and lower rates favor Private Equity over Private Credit, opportunities vary by segment. Large+ Buyouts are attractive as markets have priced in structural challenges. We downgrade Europe Private Credit, remain neutral on Europe Private Equity broadly but overweight Europe vs. North America in PE portfolios.
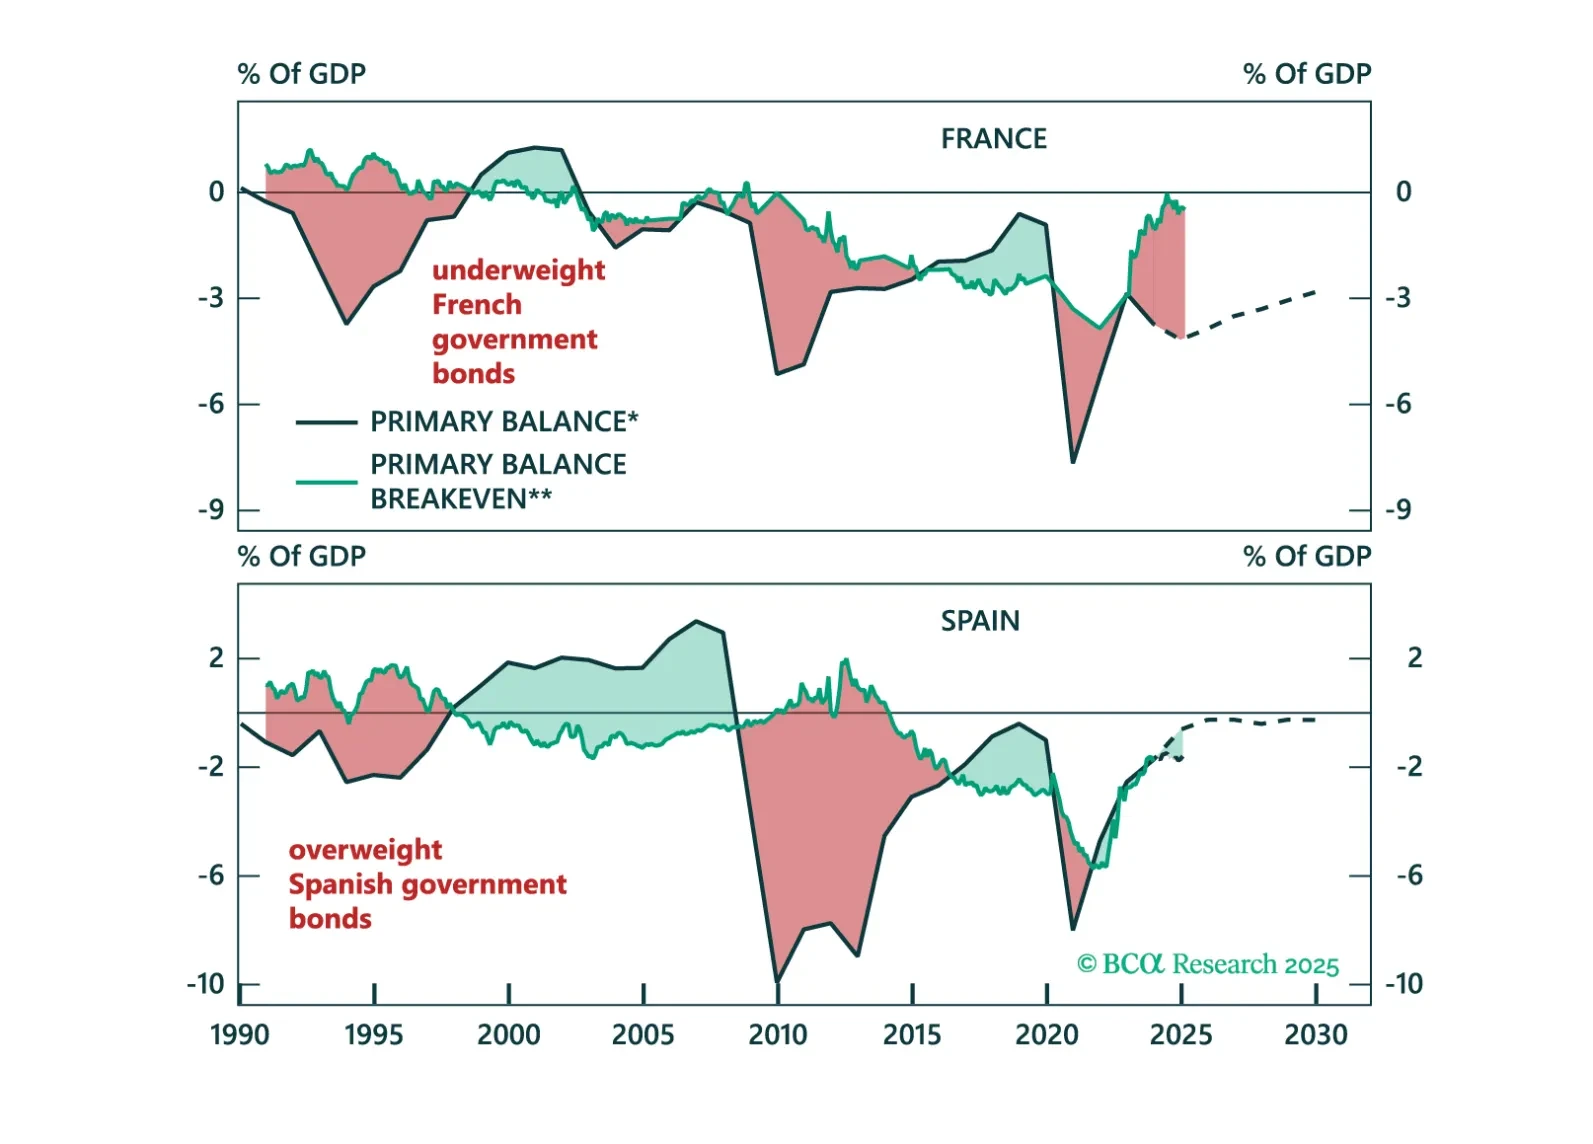
Questions about fiscal risks and their impact on bond markets have become more frequent in client conversations. This Special Report provides a framework to assess a country’s fiscal sustainability and how it affects its bond market outlook. On an individual country basis, Spain has shown a remarkable turnaround in its fiscal sustainability outlook while the fiscal outlook for France continues to deteriorate.