Servicios públicos
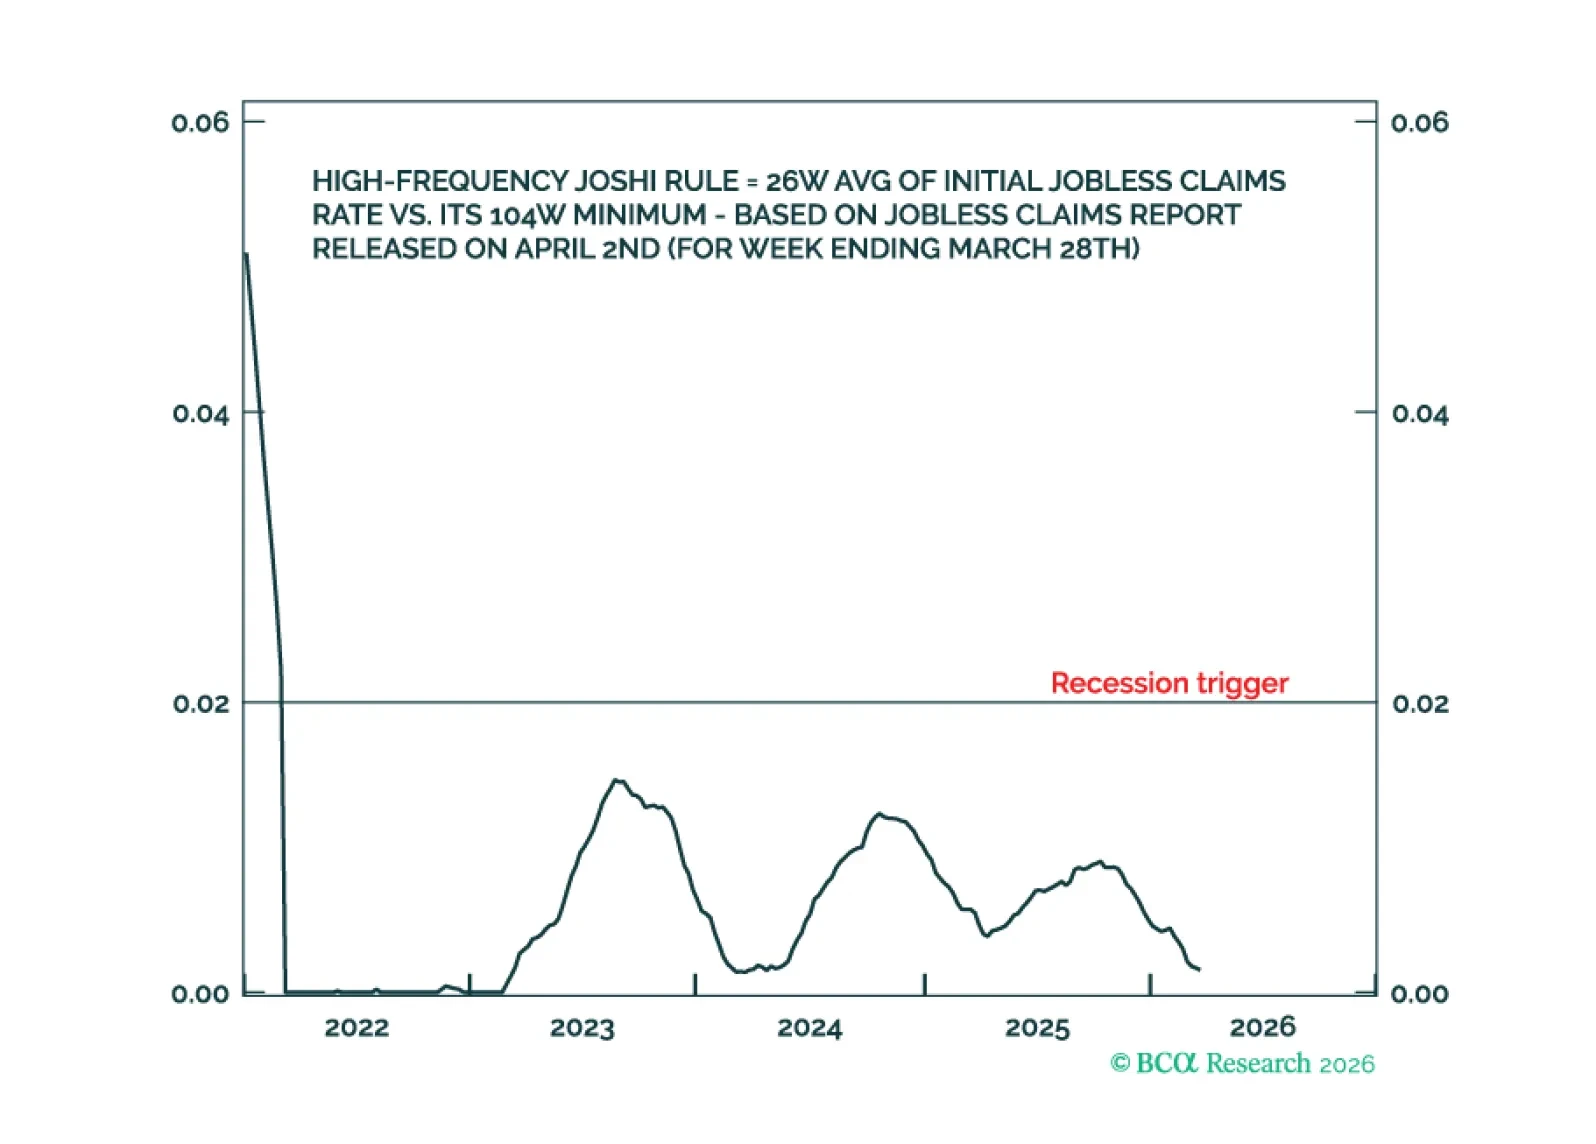
Aunque es probable que el impacto inflacionario del conflicto en Oriente Medio persista, el riesgo de recesión en Estados Unidos está contenido, mientras que el riesgo de recesión fuera de Estados Unidos es más elevado. Analizamos lo que esto significa para la estrategia de inversión. Además, una nueva operación táctica consiste en infraponderar Utilities.

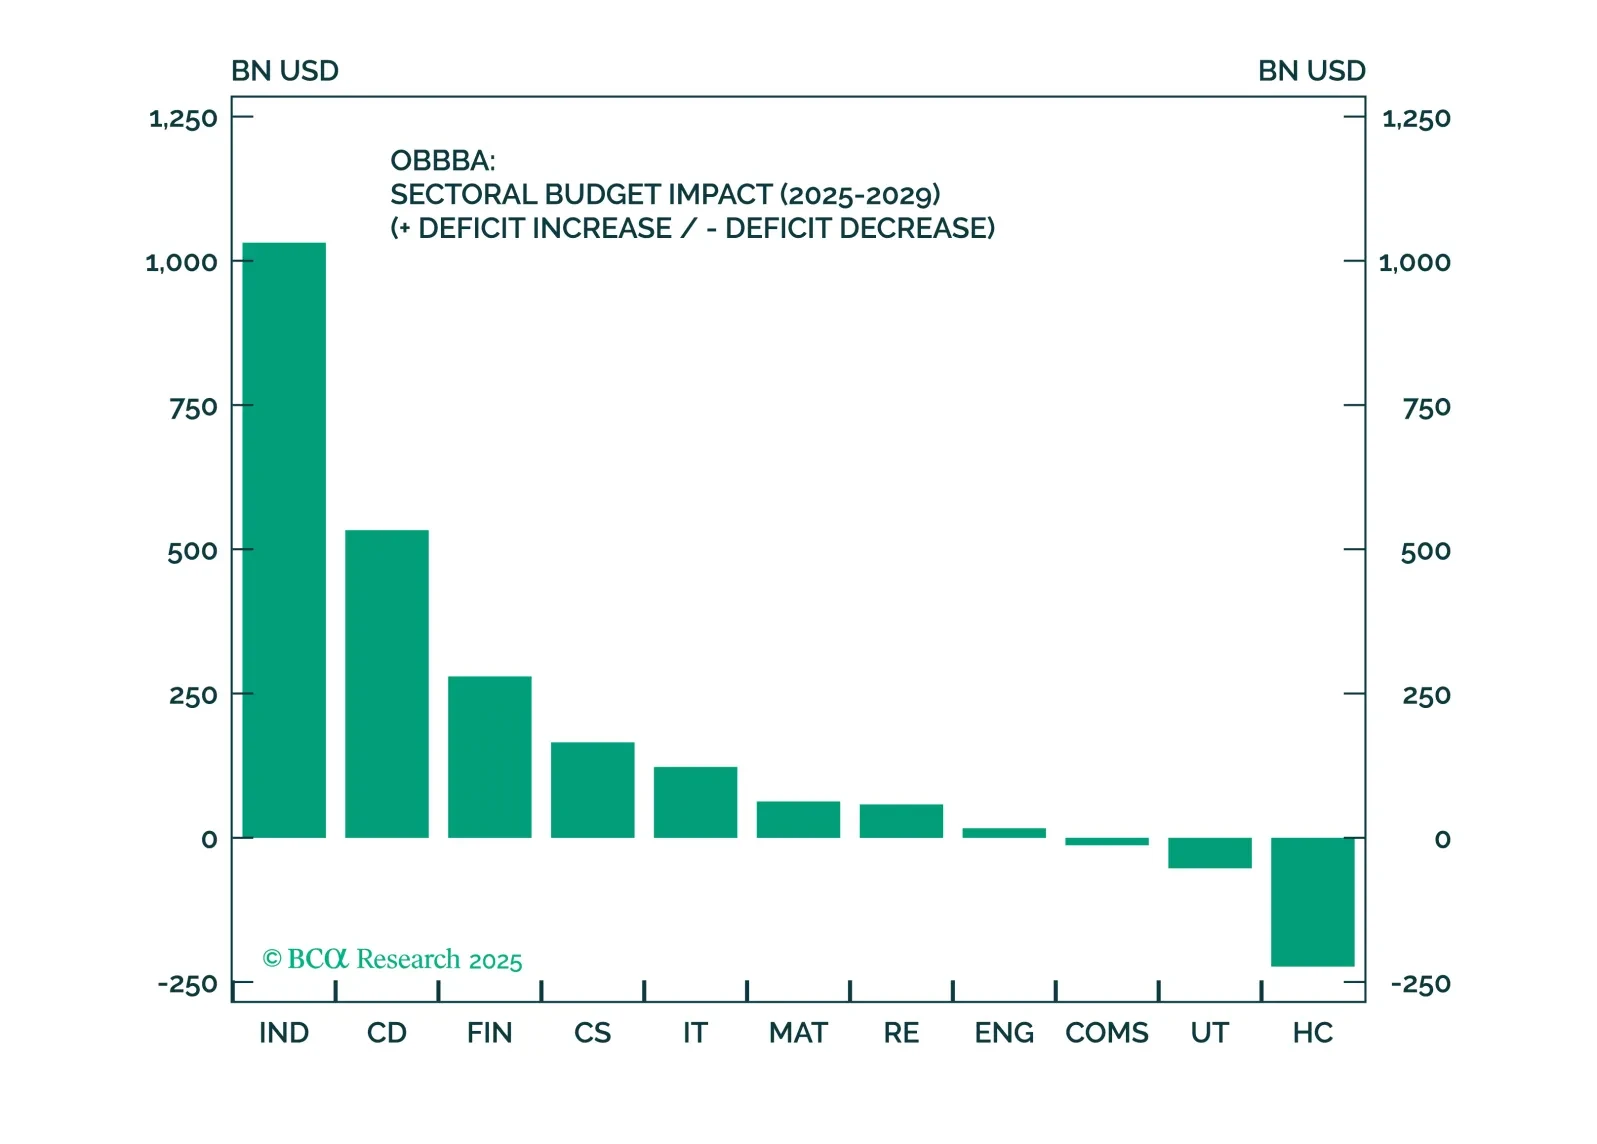
A pesar de los vientos en contra macroeconómicos, el OBBBA claramente favorece los sectores de renta variable de Industriales, Financieros y Consumo Discrecional. Una canasta cuidadosamente construida y consciente de factores en estos sectores está bien posicionada para superar en un entorno incierto impulsado por factores fiscales.


Utilities remain a long-term structural investment theme thanks to the tailwinds from GenAI, EV, and onshoring. However, there is little upside left over the tactical investment horizon as all the positives are priced in. We close our overweight and book profits.
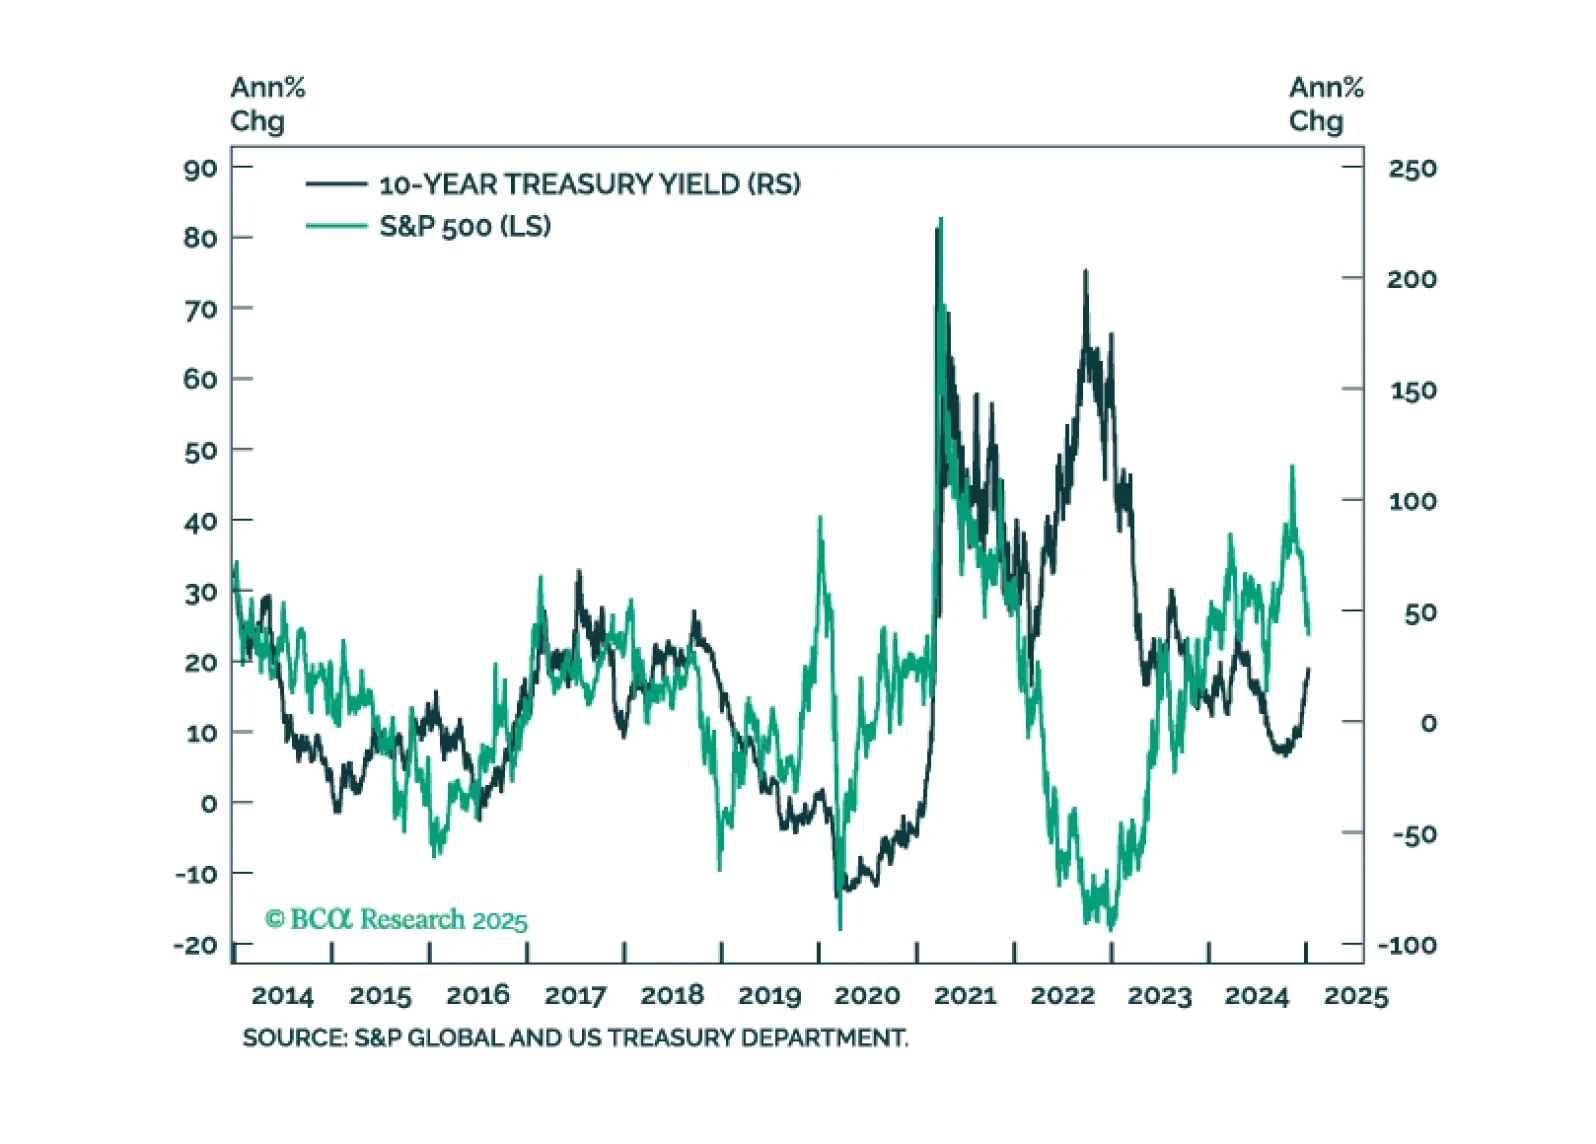
In this first presentation of 2025, we start with an overview of the 2025 outlook webcast polls, and a brief post-mortem of the 2024 market performance. Then, we shift gears and examine what is behind the recent surge in bond yields and its implications for equities. We also review market technicals and positioning and conclude with a list of trades to prepare our portfolio for continued moves in yields.


This Special Report examines the post-pandemic evolution of consumption growth, relative equity sector and subindustry performance and recent commentary from consumer-facing companies to assess the likelihood that softer spending among lower-income households will spread to middle- and upper-income households.