Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Países Desarrollados
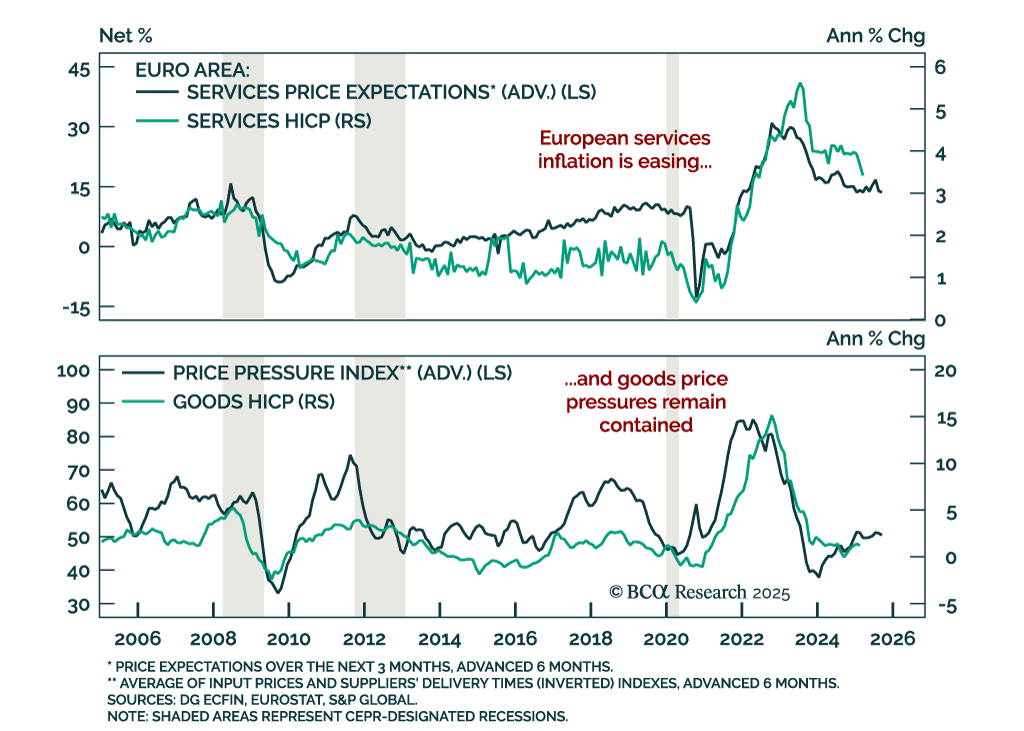
Eurozone inflation is cooling steadily, supporting our tactical overweight in German bunds versus European equities and increasing the odds of an April ECB cut. Headline HICP eased to 2.2% y/y in March from 2.3%, while core came in cooler than expected at…
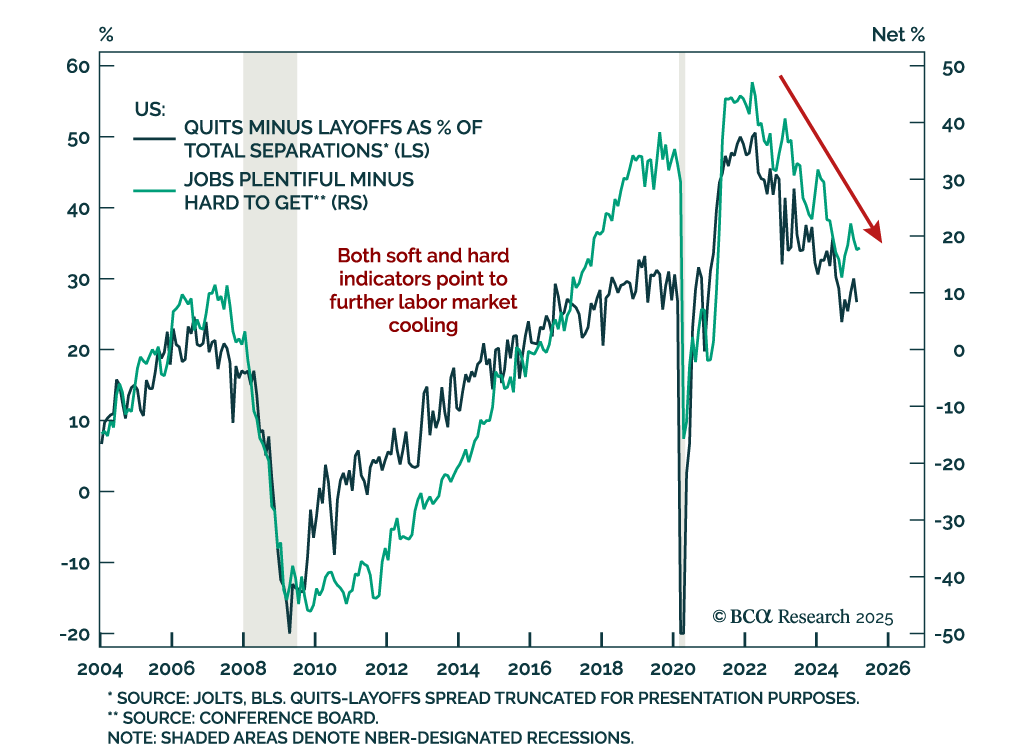
Labor market data continues to cool, reinforcing our overweight in government bonds and above-benchmark duration stance. February job openings fell to 7.6m, below expectations. Declining quits and rising layoffs signal that labor market slack is increasing.…
Our Global Fixed Income strategists recommend maintaining an underweight allocation to corporate credit versus government bonds in global fixed income portfolios. Within corporates, they are neutral on the US, UK, Japan, and Australia, and underweight on…

Going into April, MacroQuant recommends a modest underweight on stocks, offset by an overweight on bonds and cash. While MacroQuant is modestly bearish on stocks, we suspect that the downside risks to equities may be greater than what the model assumes.

De cara a abril, MacroQuant recomienda una ligera infraponderación en acciones, compensada por una sobreponderación en bonos y efectivo. Aunque MacroQuant es modestamente bajista en acciones, sospechamos que los riesgos a la baja para las acciones podrían ser mayores de lo que el modelo supone.
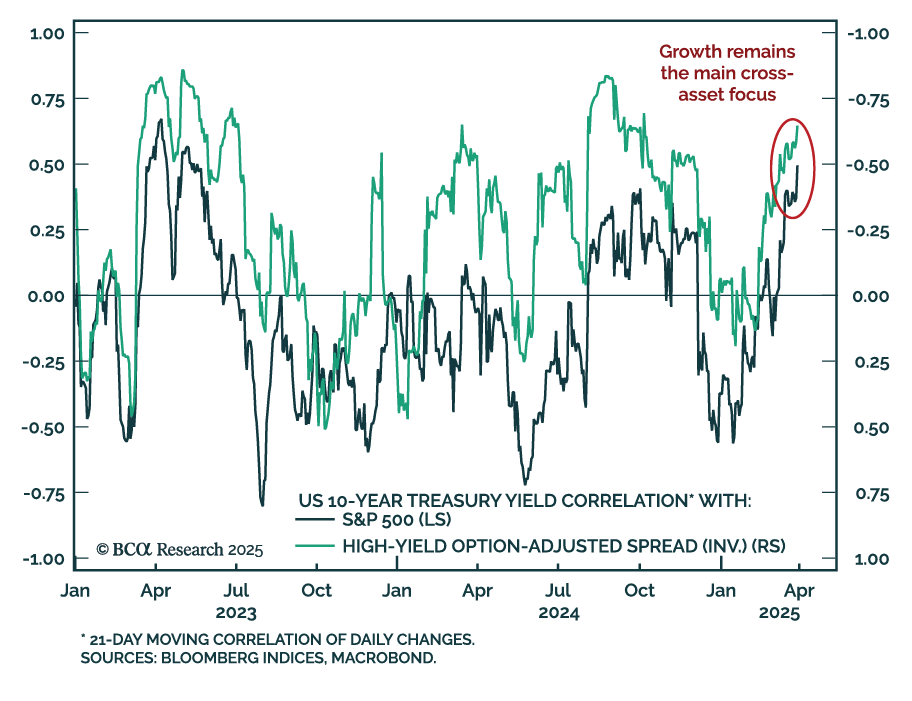
Markets are responding to the growth drag of stagflation, not the inflation impulse, reinforcing our defensive stance. Despite rising short-term inflation pressures in the US, risk assets and bond yields continue to move together, with the stock–bond yield…
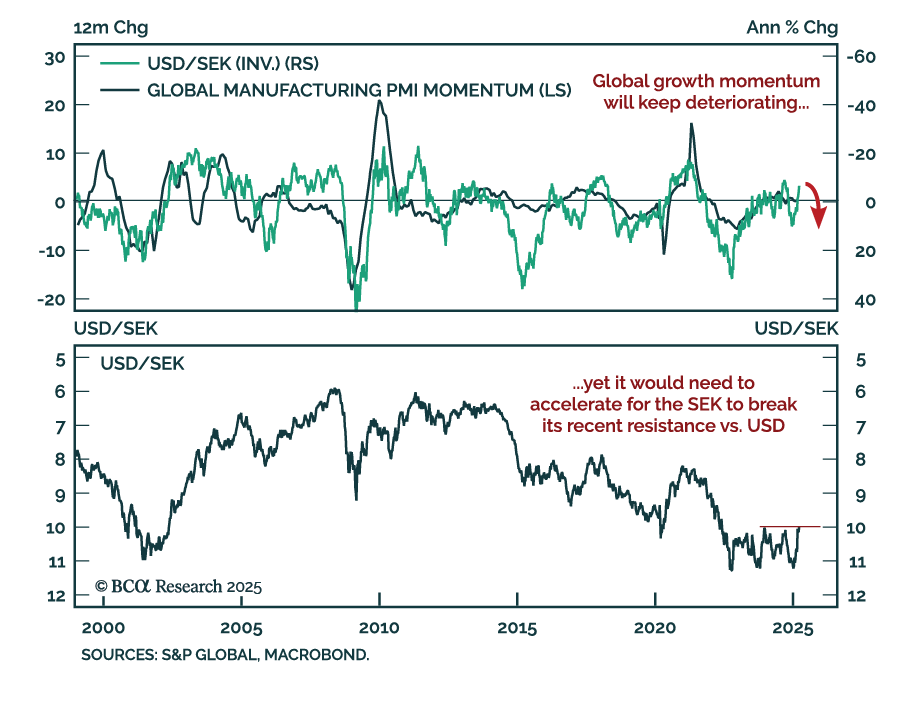
The SEK’s sharp rally is losing steam as local data weakens and EUR strength looks stretched. After appreciating more than 10% against the USD year-to-date, the krona is now showing signs of fatigue. Recent Swedish data has disappointed, with the Economic…
Our Private Markets & Alternatives strategists remain structurally positive but cyclically underweight on Multi-Strategy Hedge Funds. While these funds have delivered consistent alpha and valuable diversification, current market conditions offer more…

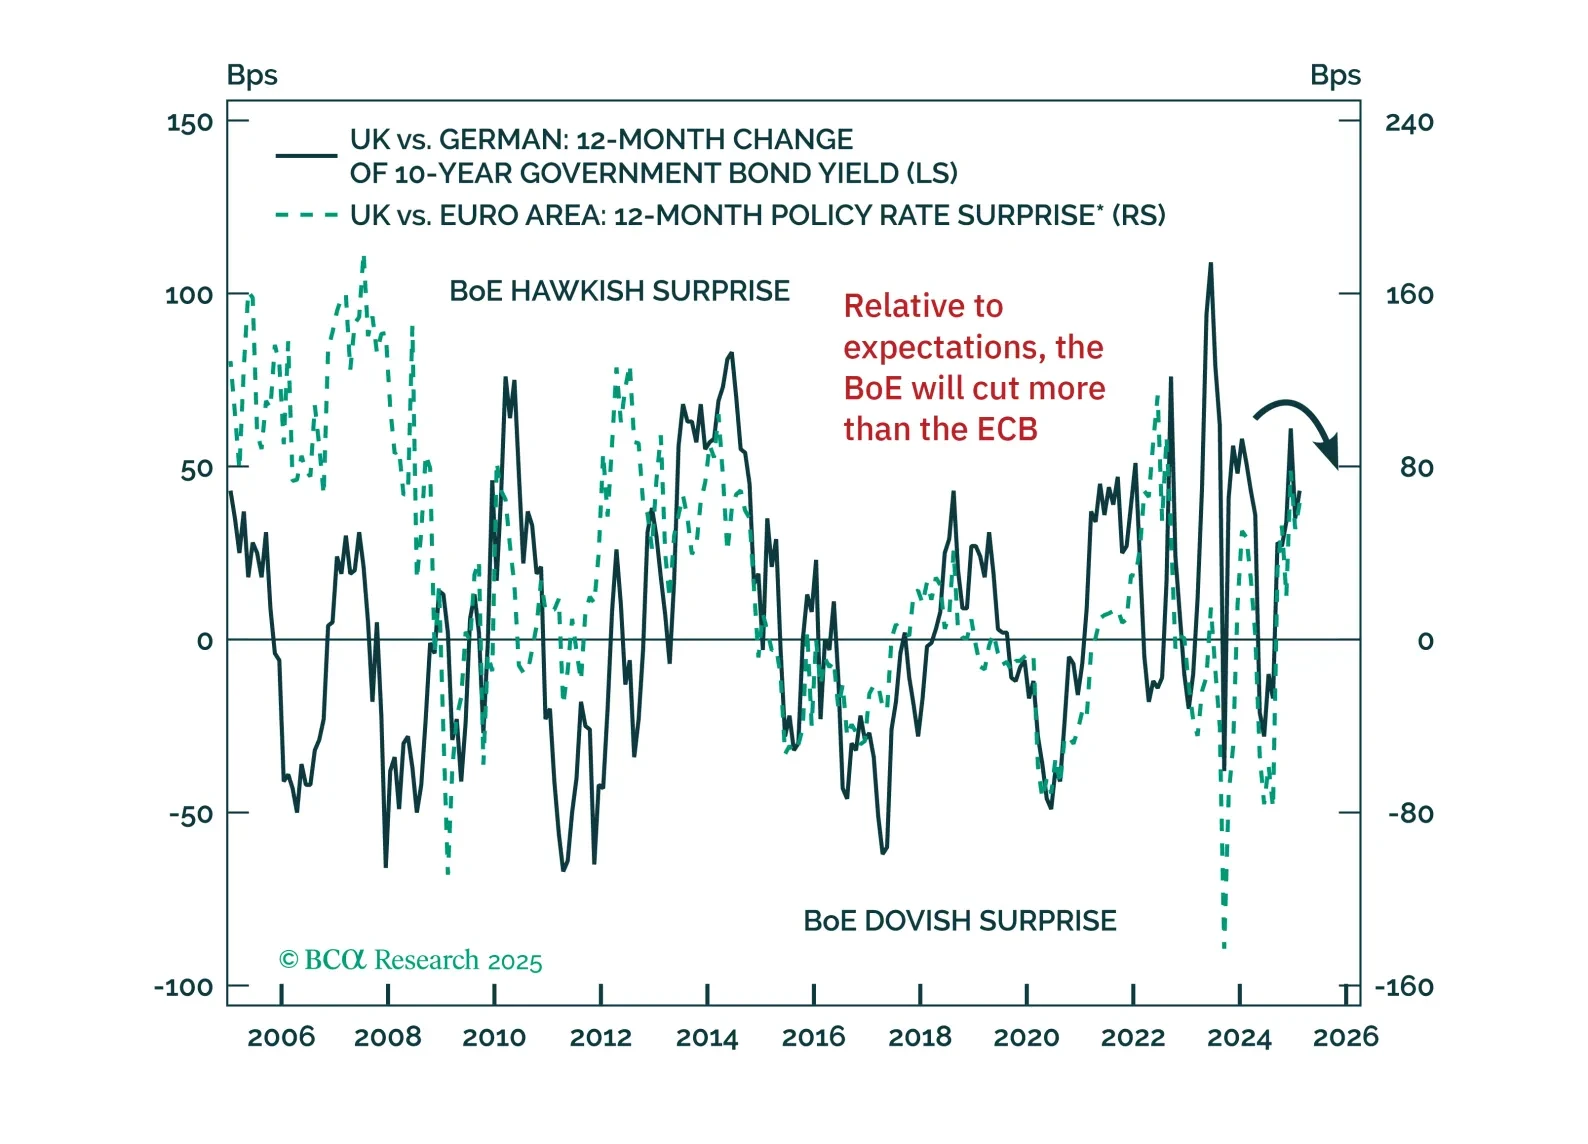
With economic headwinds building and fiscal dynamics shifting, bond markets are at a turning point. Our latest note outlines why German bund yields are set to decline and why UK gilts are poised to outperform — and how to position accordingly.
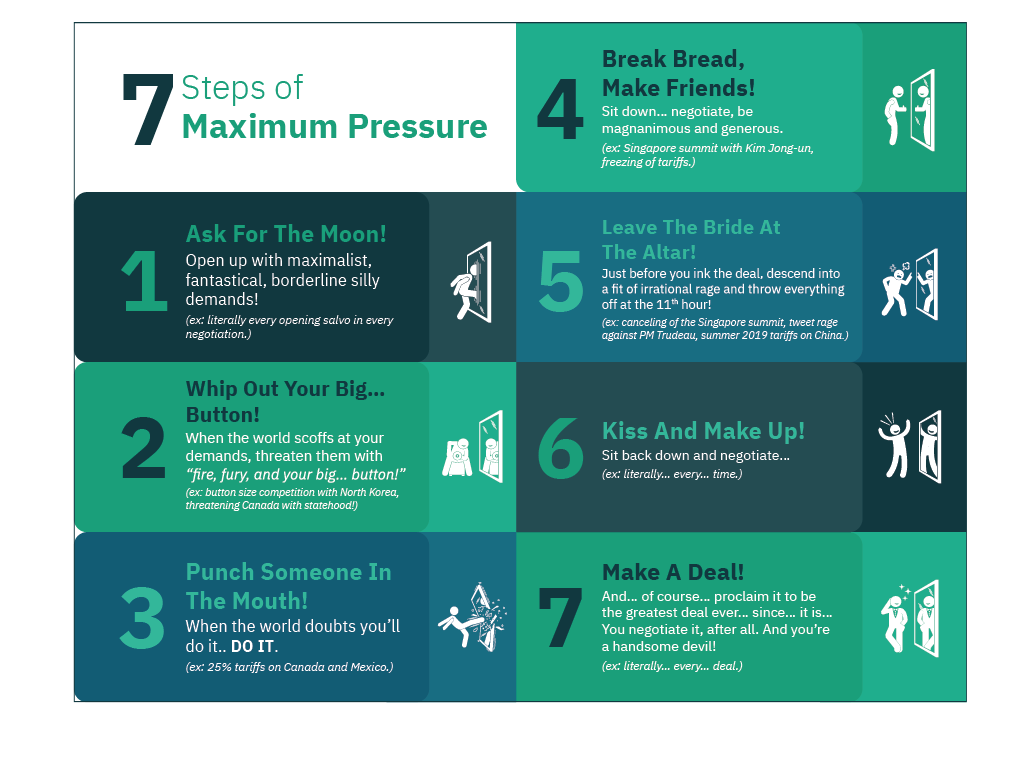
Markets may be bracing for April 2, but the real surprise could be how unsurprising it ends up being. Our Chart Of The Week comes from GeoMacro Chief Strategist Marko Papic, who sees the looming tariff salvo as the peak of de-globalization panic. With Beltway…