Fiscal Policy
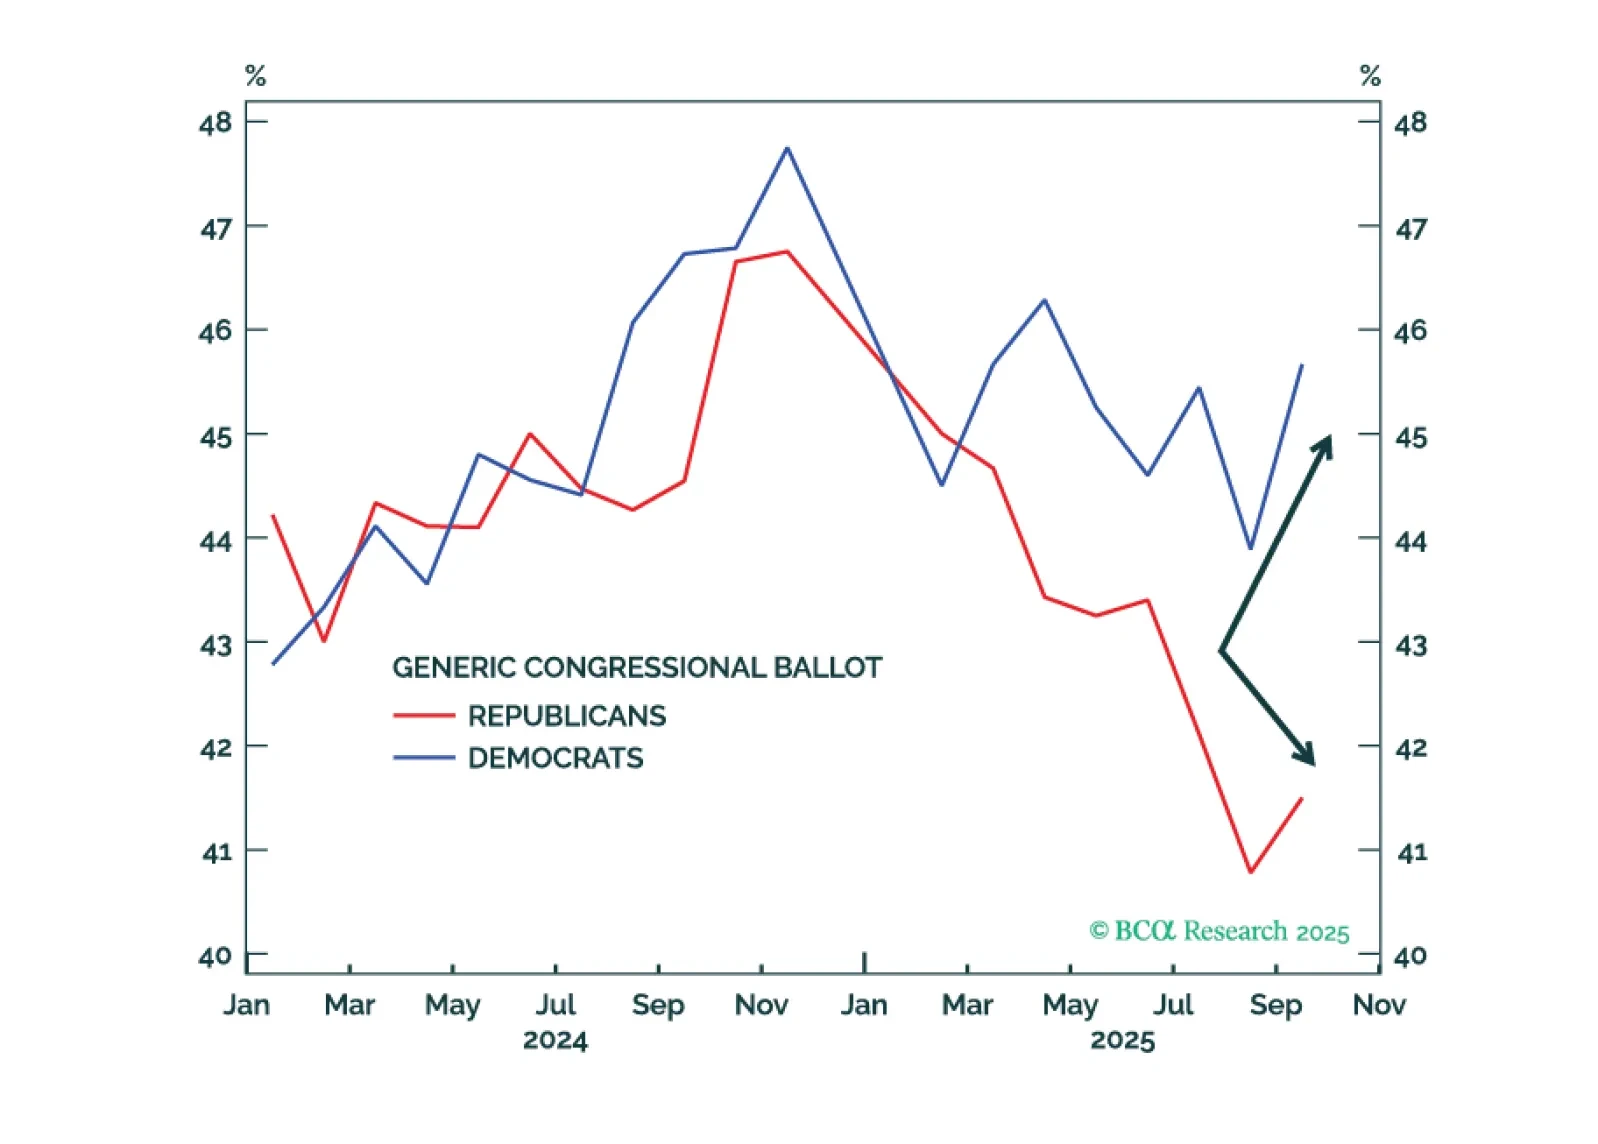
Damos una probabilidad de un tercio de un cierre del gobierno federal. Probablemente no ocurrirá antes de noviembre. En el peor de los casos, los cierres del gobierno solo causan volatilidad temporal en el mercado.
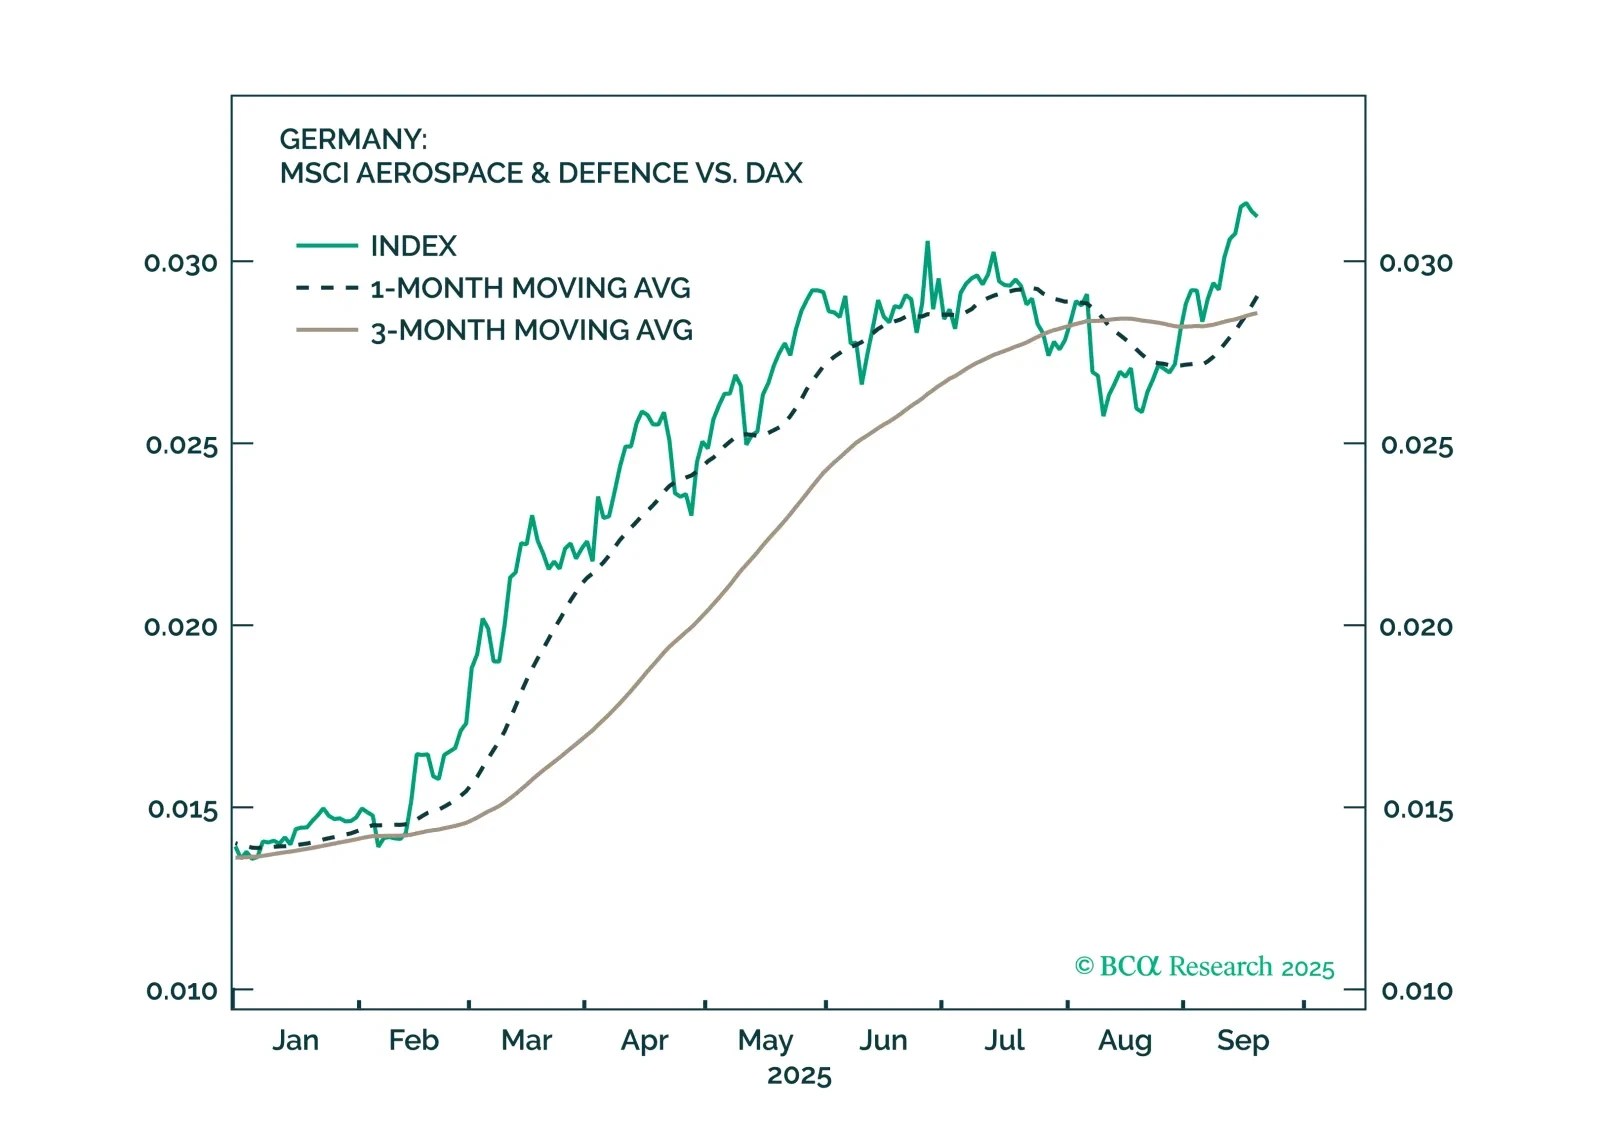

La flexibilización de la política de Indonesia impulsará la demanda interna, pero aumentará la inflación. El déficit por cuenta corriente se ampliará y la rupia se debilitará. Manténgase en posiciones cortas en la rupia y reduzca la ponderación de acciones indonesias, bonos locales y crédito soberano en sus respectivas carteras de mercados emergentes.
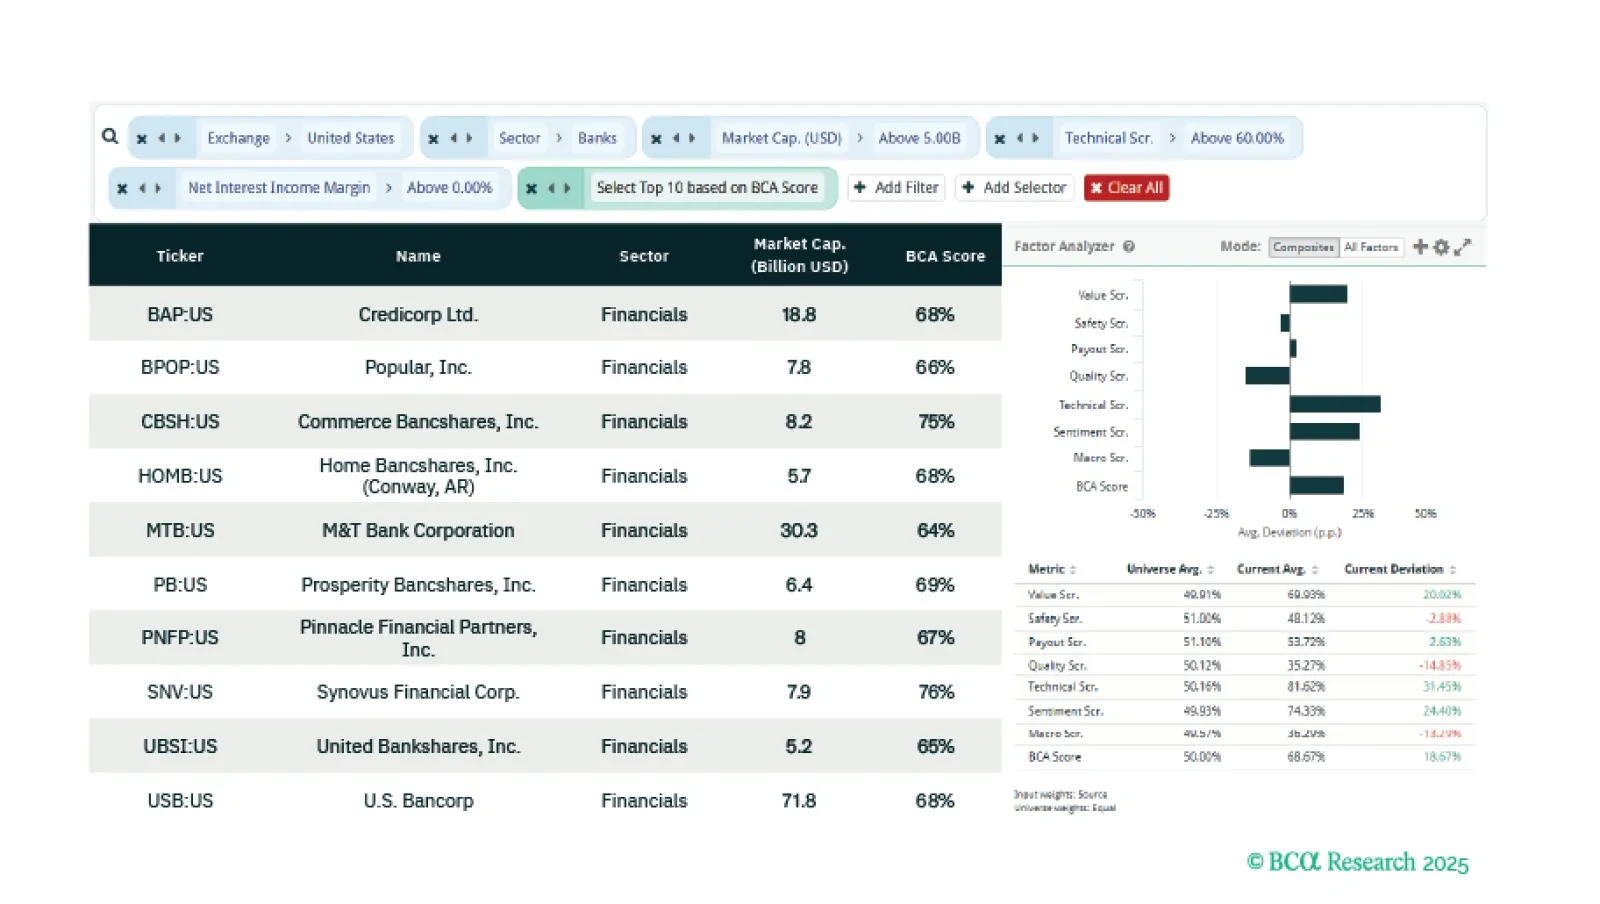
Esta semana, nuestros tres analistas identifican: Oportunidades de equidad en bancos de EE. UU., acciones que se benefician de una mayor incertidumbre fiscal en EE. UU. y una cesta global de acciones de Valor y Técnica.
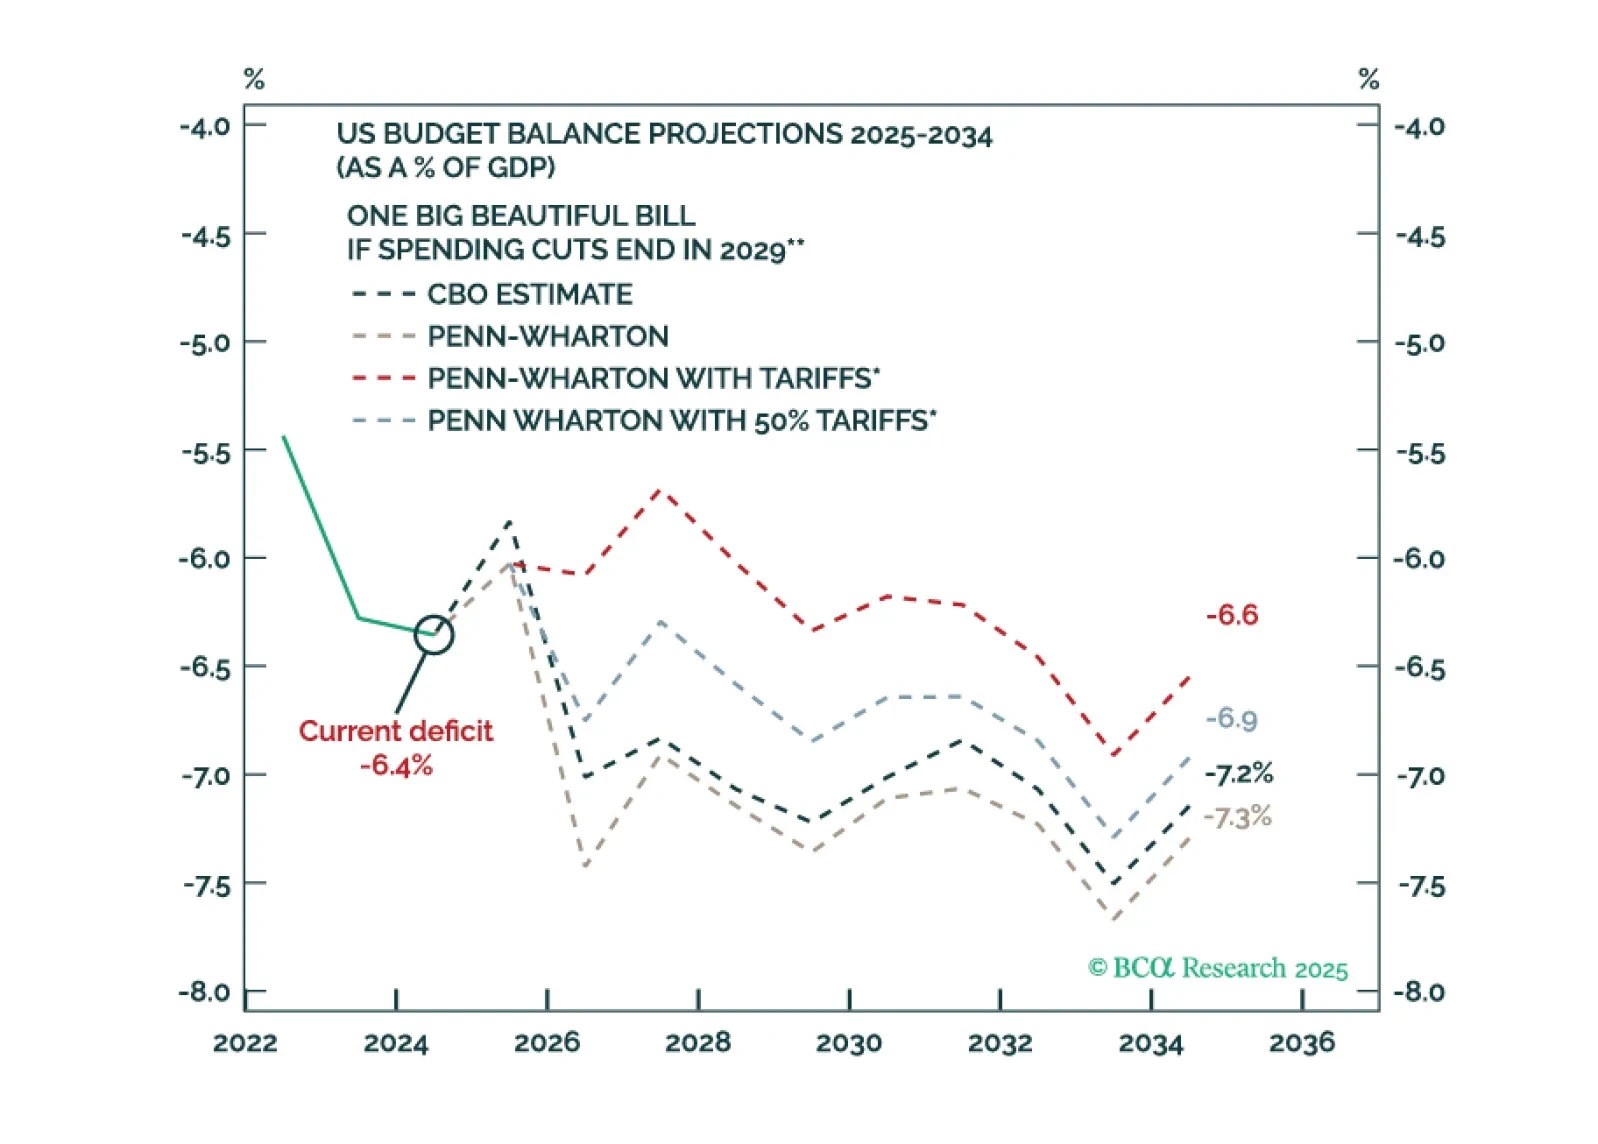
Bond market volatility will spike again in the near term. The Fed is committed to an easing cycle yet the Trump administration’s signature fiscal policy action will stimulate the economy. Tariffs are supposed to keep the budget deficit contained but they are inflationary.
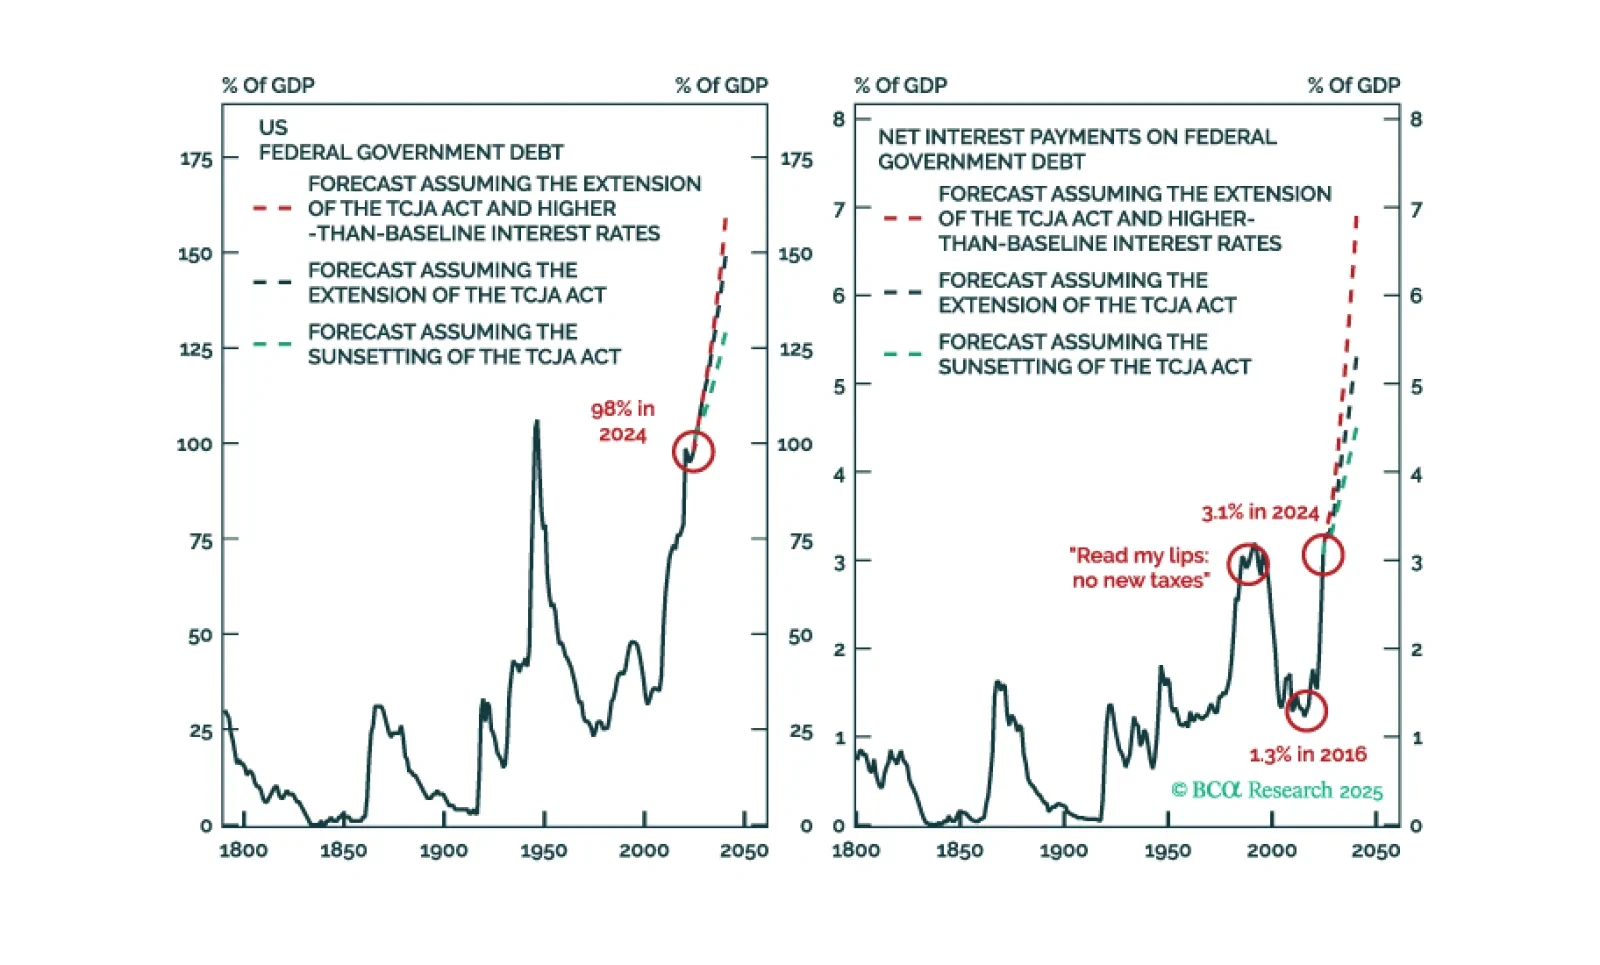
Fiscal policy, not tariffs, is now driving markets as Congress advances the One Big Beautiful Bill. The Senate cannot afford to remove the spending cuts in the bill, as they risk sparking a bond market riot. Even with this more modest bill, US interest rates are already pressuring housing and labor markets. US assets are also losing their defensive tilt. Better opportunities for both equity and fixed income investors are available internationally. We conserve our defensive stance but do not want to be dogmatic. Sentiment is more cautious than last year, and the US economy is not showing signs of imminent collapse. We remain underweight the US dollar and US equities. Upgrade Communication Services and downgrade Consumer Staples. Upgrade the CNY and EM currencies to neutral.
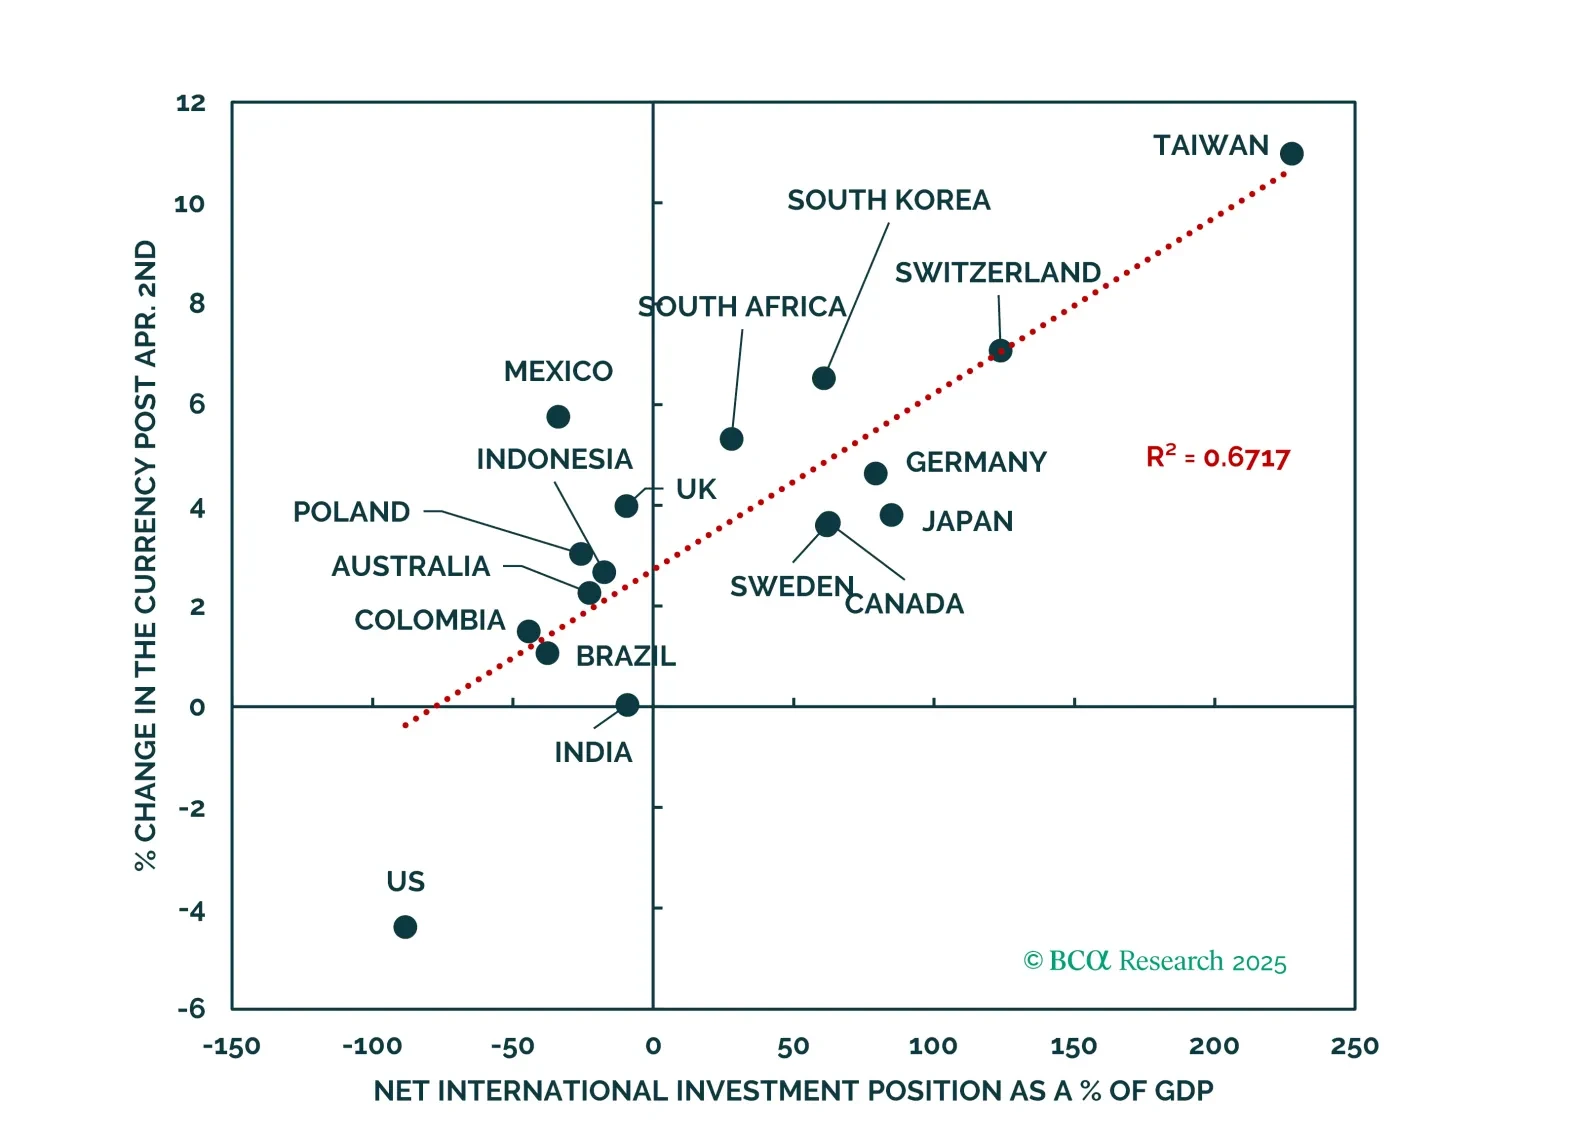
Rising bond yields may present an even greater danger to the global economy than the trade war. With equity valuations no longer discounting much economic risk, investors should position themselves defensively.
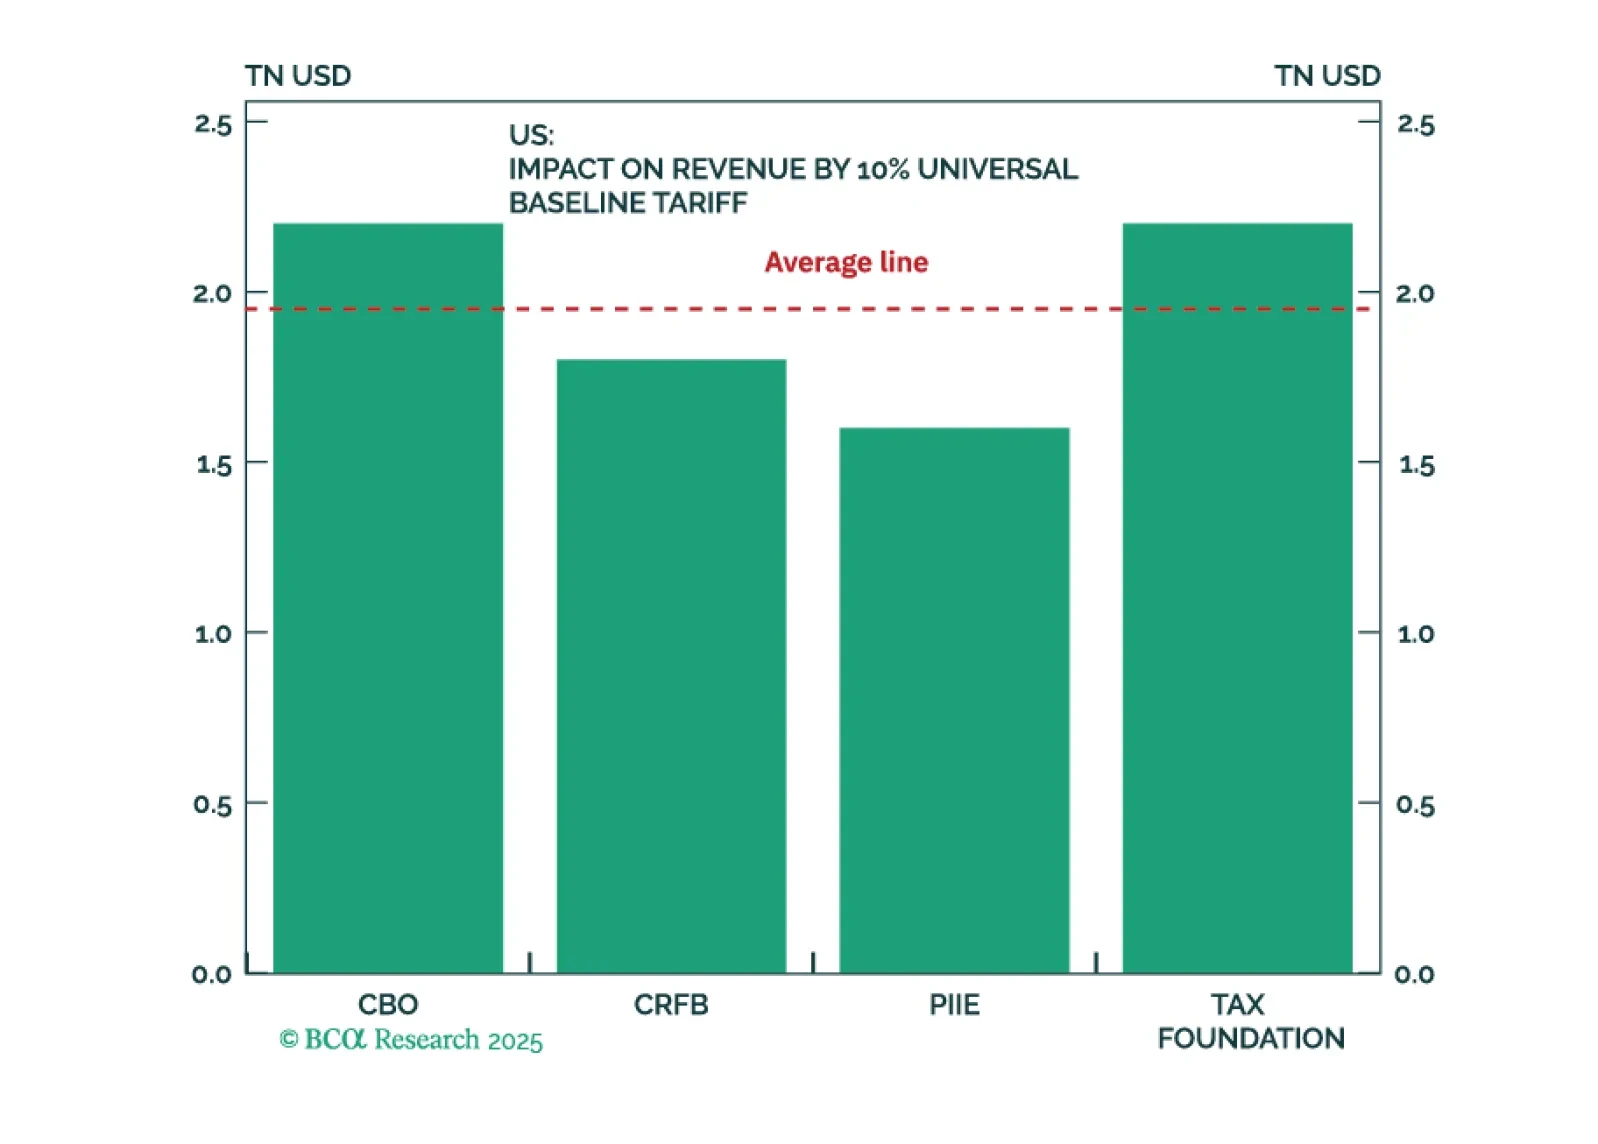
Trump’s signature bill is surprising to the upside with budget deficits, as predicted. Some version is guaranteed to pass – but higher bond yields and inflation will weigh on the economy and stock market.
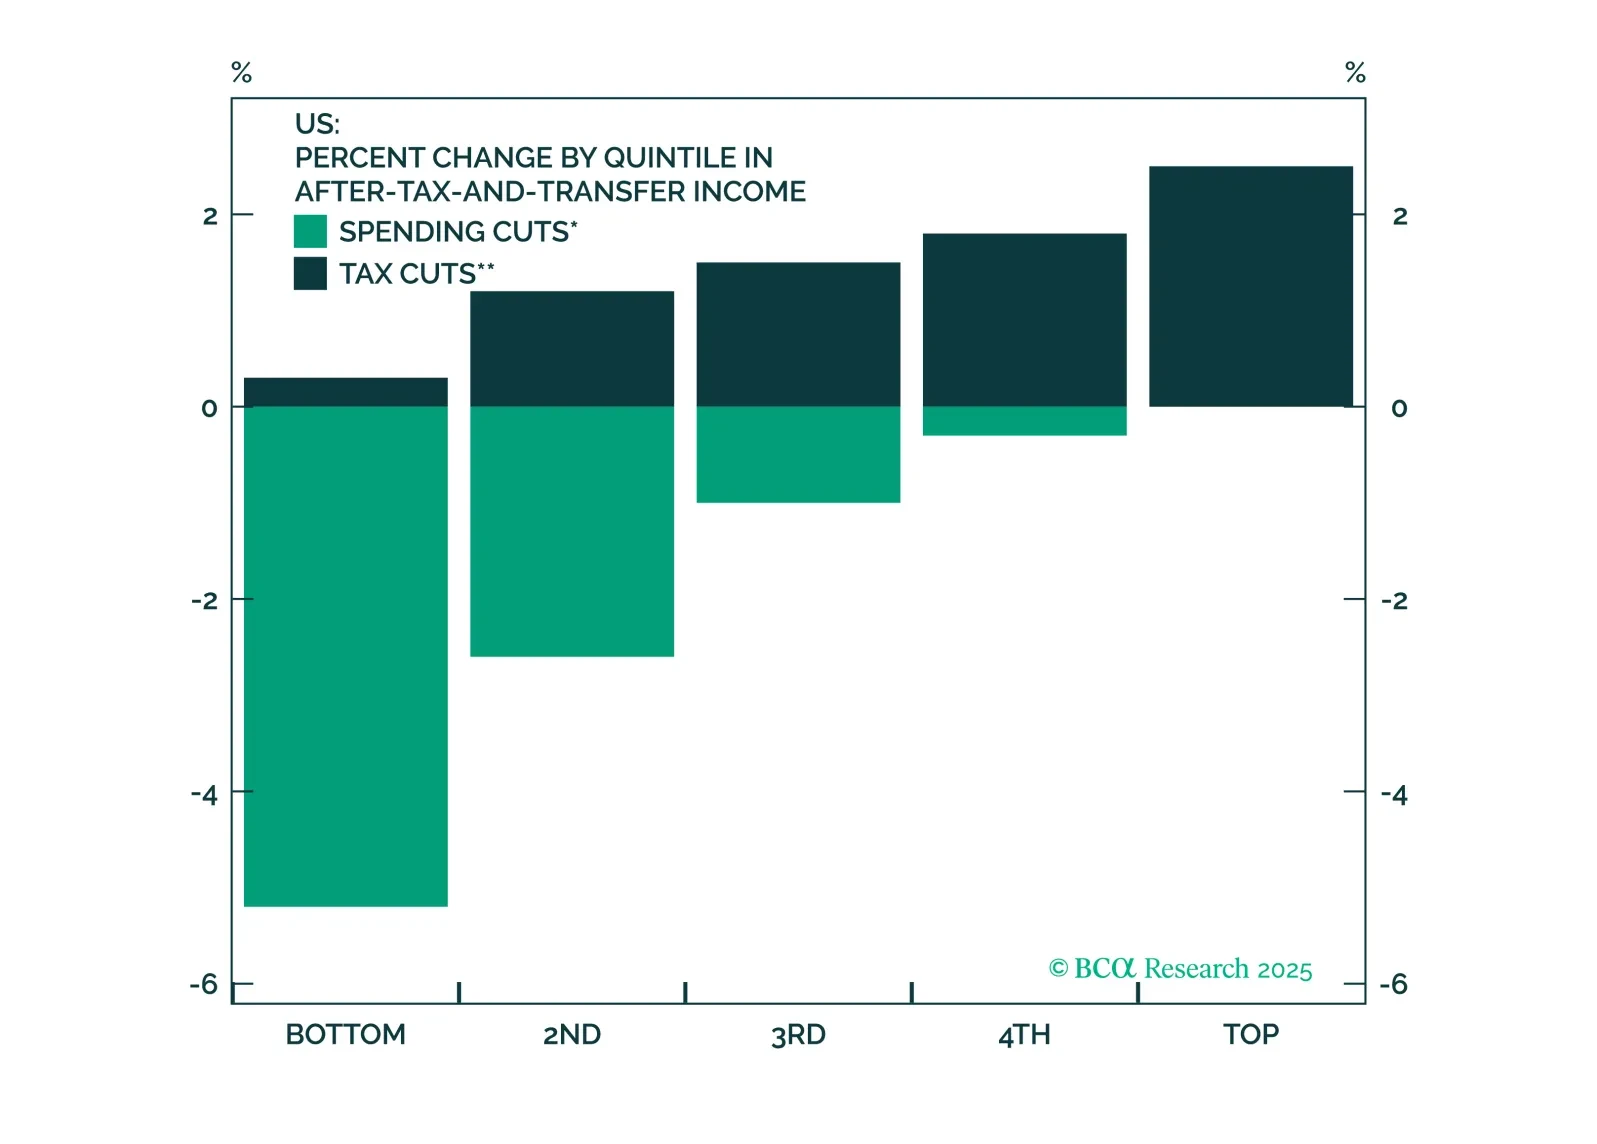
Stocks will continue to struggle in the second quarter as President Trump tries to implement tariffs. Tax cuts will only temporarily dispel growth fears, if at all. Middle Eastern instability will add oil price surprises to an environment that is looking fairly stagflationary.
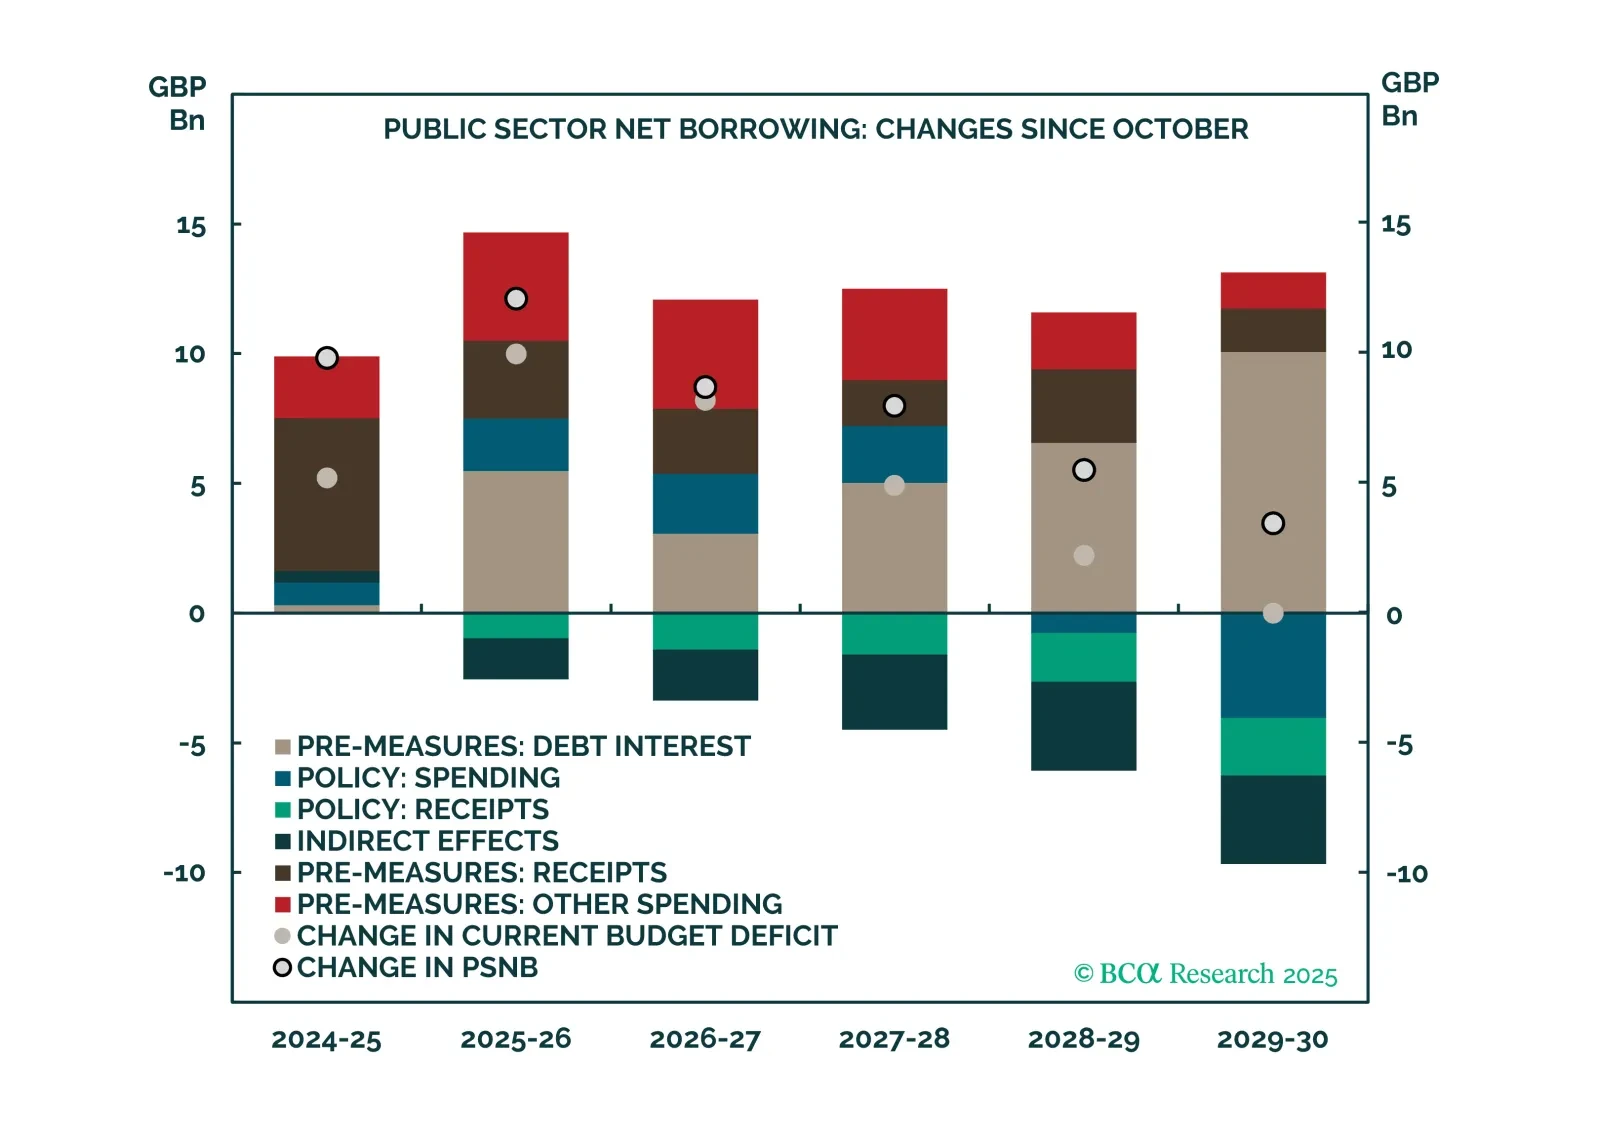
This report is a quick take on our views on UK bonds and FX, given the recent budget.