Saltar al contenido principal

Estados Unidos

Our Chart Of The Week comes from Melanie Kermadjian, from our Global Investment Strategy team. The S&P 500 has been in a bull market for nearly five years and is currently up 2.5% YTD. A lot has been thrown at the US stock market so far this year, yet for the…
Our Emerging Market strategists published a follow-up piece to their Bessenomics note where they assess the new Treasury Secretary plan’s impact on markets. Lower interest rates are central to Bessenomics. The Trump administration is expected to pressure the…
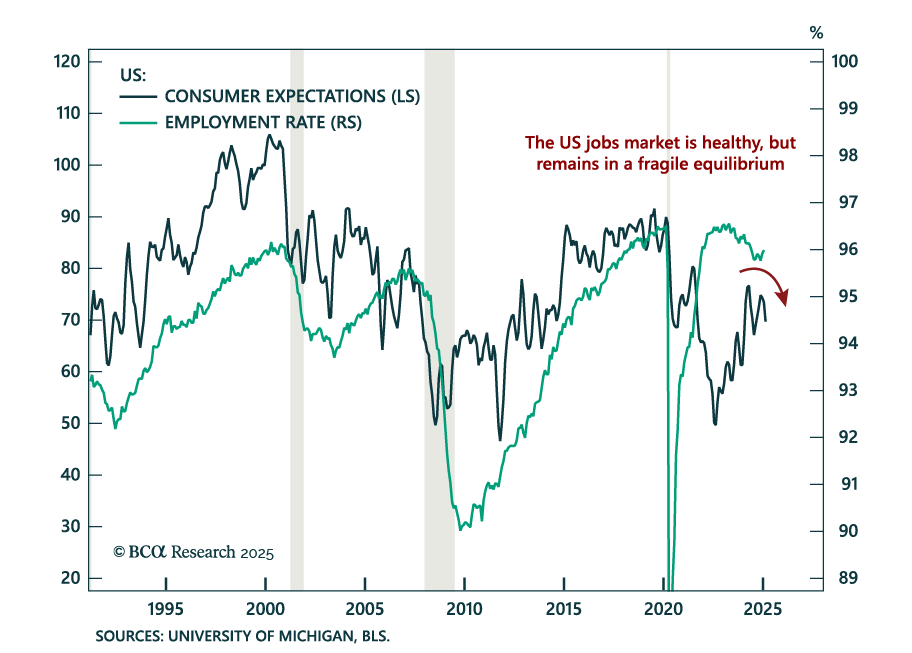
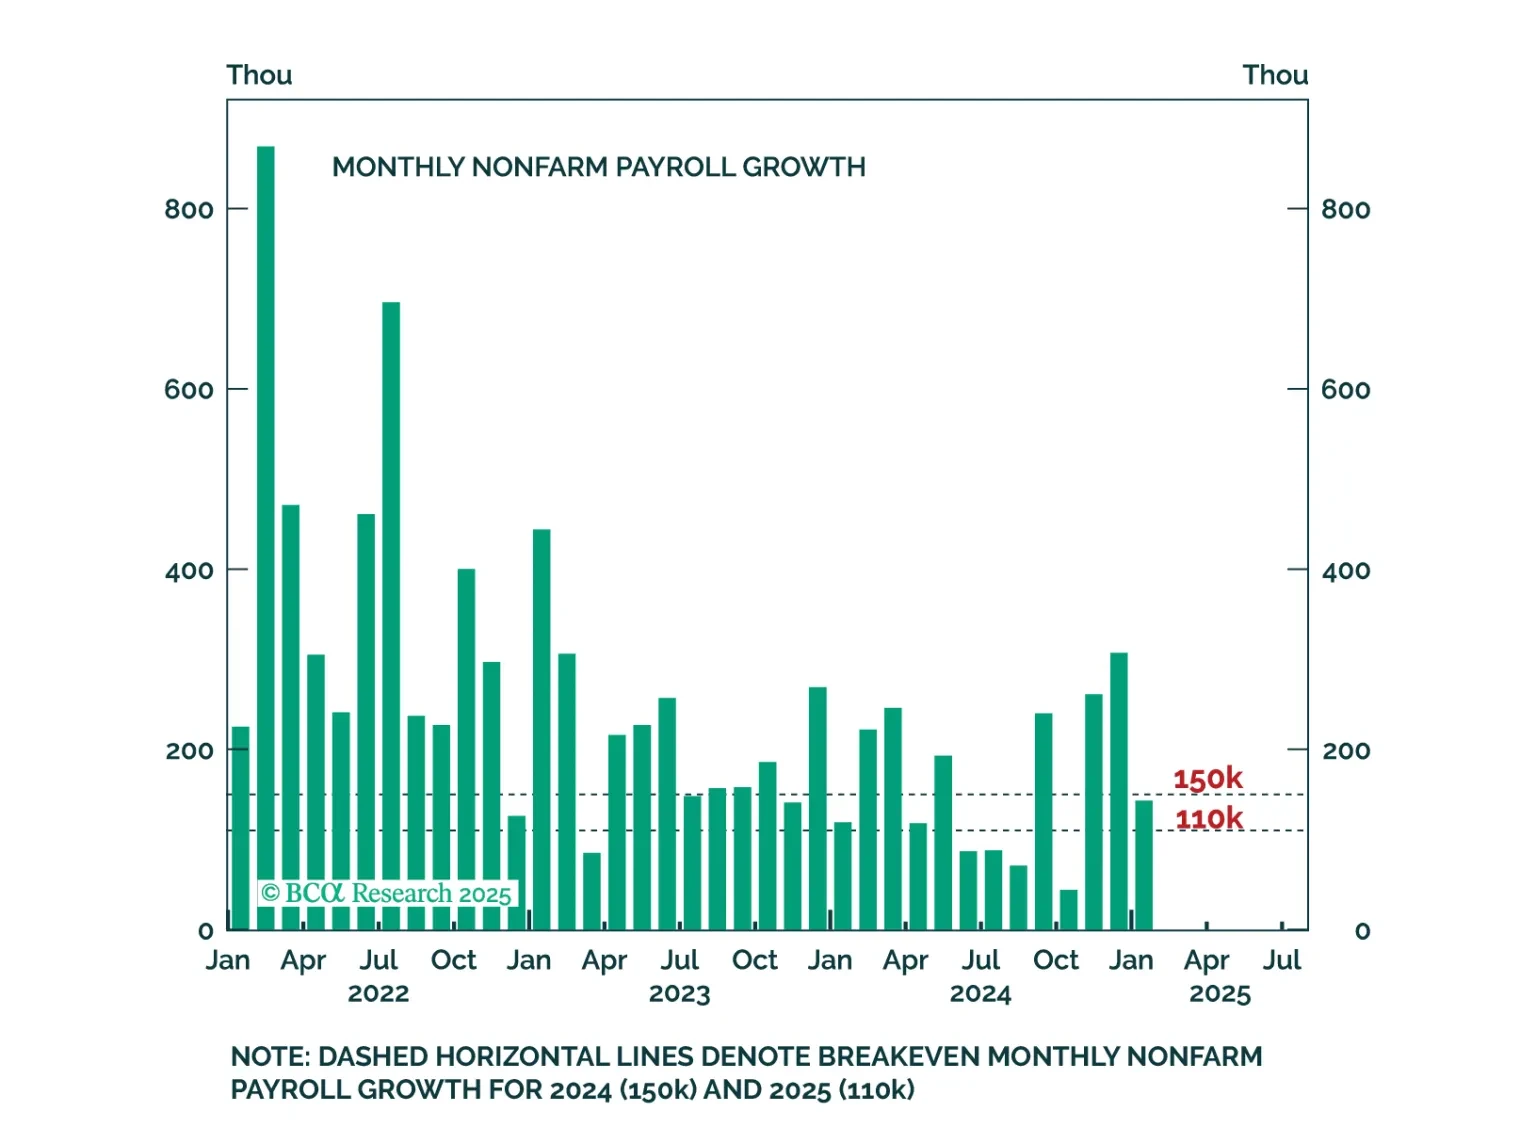
The January US jobs report was solid, reflecting a healthy labor market. Payrolls rose by less than expected at 143k, down from an upwardly-revised 307k in December, leaving the 3-month moving average at 237k. The unemployment rate ticked down 0.1% to 4.0%…

Some thoughts on this morning's employment data and Treasury Secretary Bessent's recent attempts to talk down the 10-year Treasury yield.
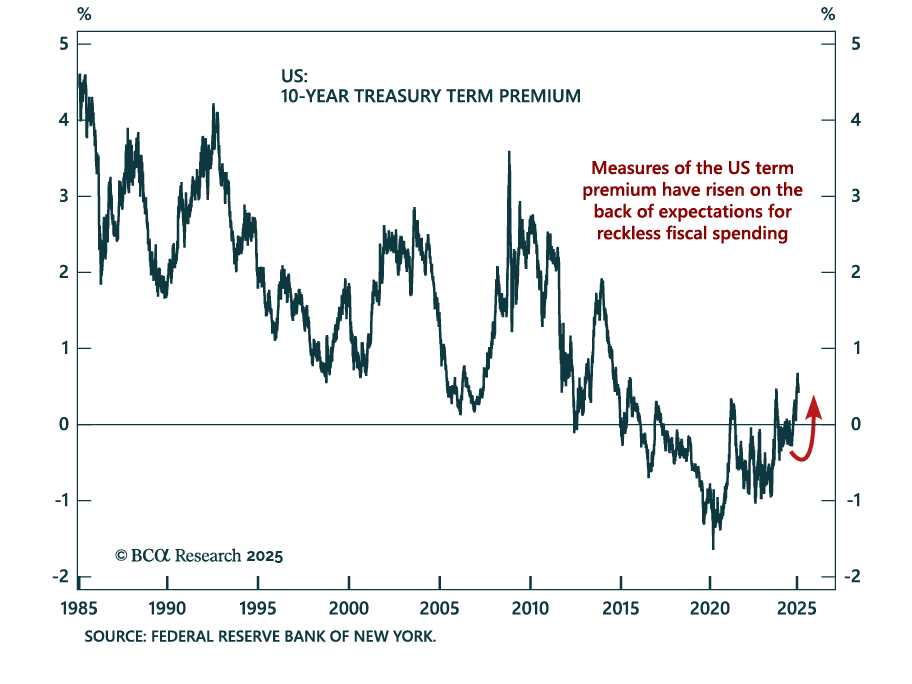
Treasury Secretary Scott Bessent commented that one of the Trump administration’s priority was lowering 10-year bond yields. Bessent’s 3/3/3 plan, boosting growth to 3% from deregulation, increasing US oil production by 3 mmb/d, and slashing the budget…
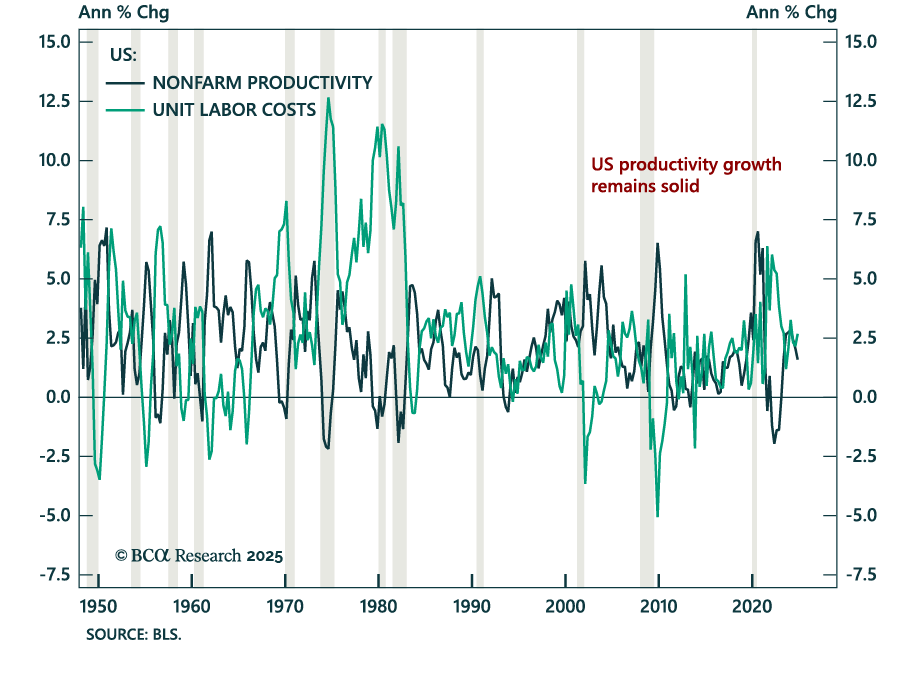
Preliminary nonfarm labor productivity for Q4 came in line with estimates, decreasing to 1.2% annualized growth from an upwardly-revised 2.3%. Unit labor costs growth was lower than expected, but still jumped to 3.0% from a downwardly revised 0.5% in Q3.…
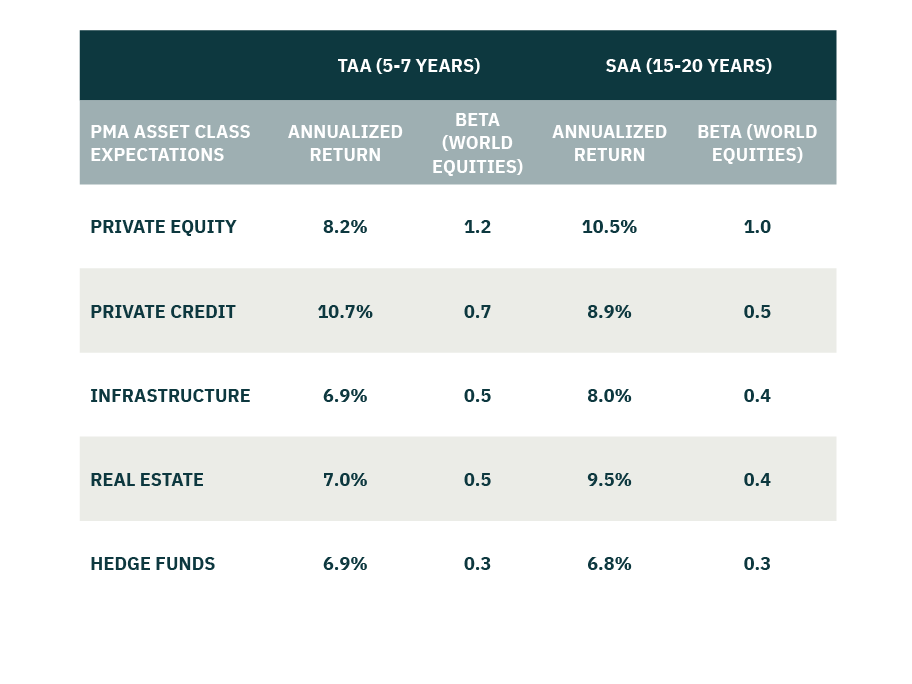
Our Private Markets & Alternatives strategists published their 2025 capital market assumptions (CMAs). The 2025 edition features several enhancements such as deal-level projections, refined methodologies, and expanded coverage. Private Equity return…

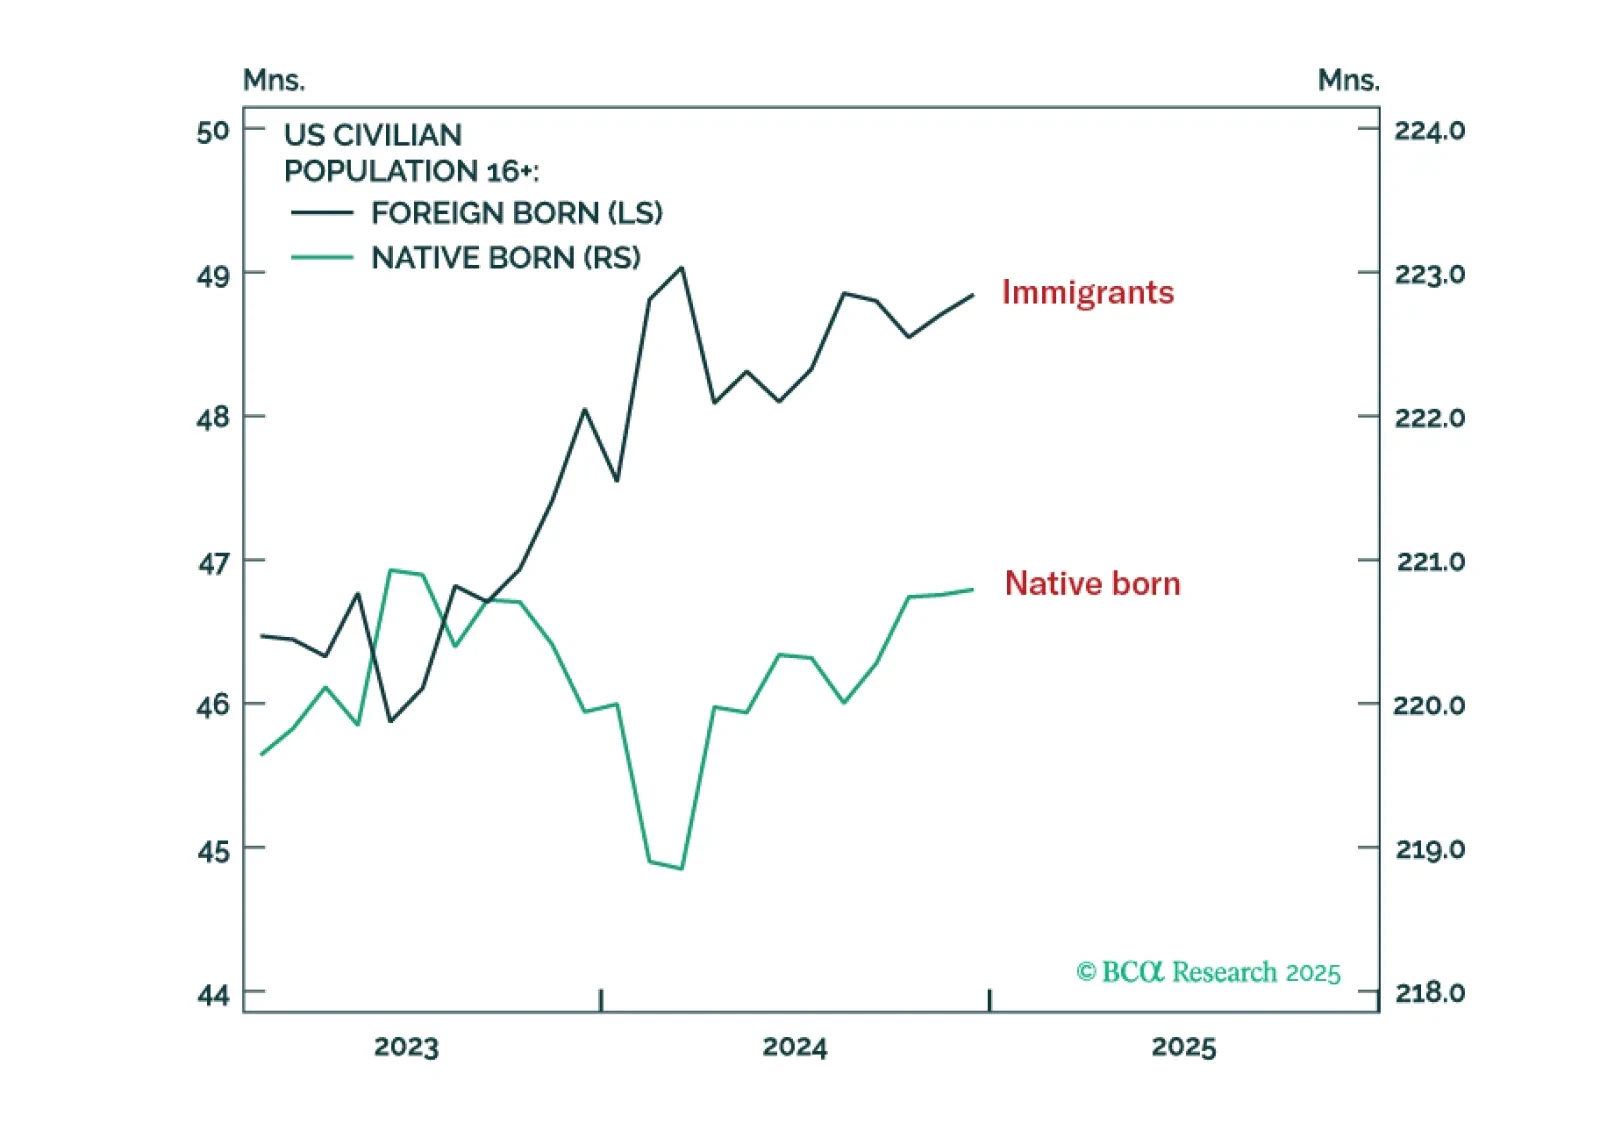
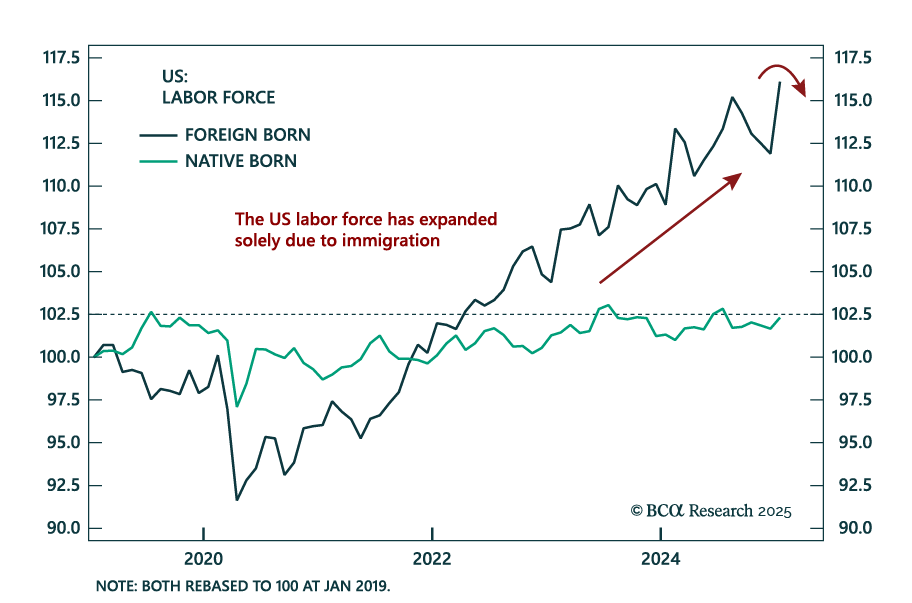
All the growth in the US labour supply since mid-2023 has come from immigration. This means if net immigration comes to a grinding halt, as Trump wants, it will hurt economic growth as well as keep the labour market supply-constrained. An increase in productivity growth could save the day, both to maintain growth and to kill inflation. Yet hopes that AI is about to usher an imminent and sustained boost to productivity growth are misplaced. Hence, expect a slowdown in US growth combined with inflation stuck close to 3 percent, a combination that I call a ‘mini stagflation’. We go through the investment implications. Plus: Tactically overweight Portugal versus Europe.
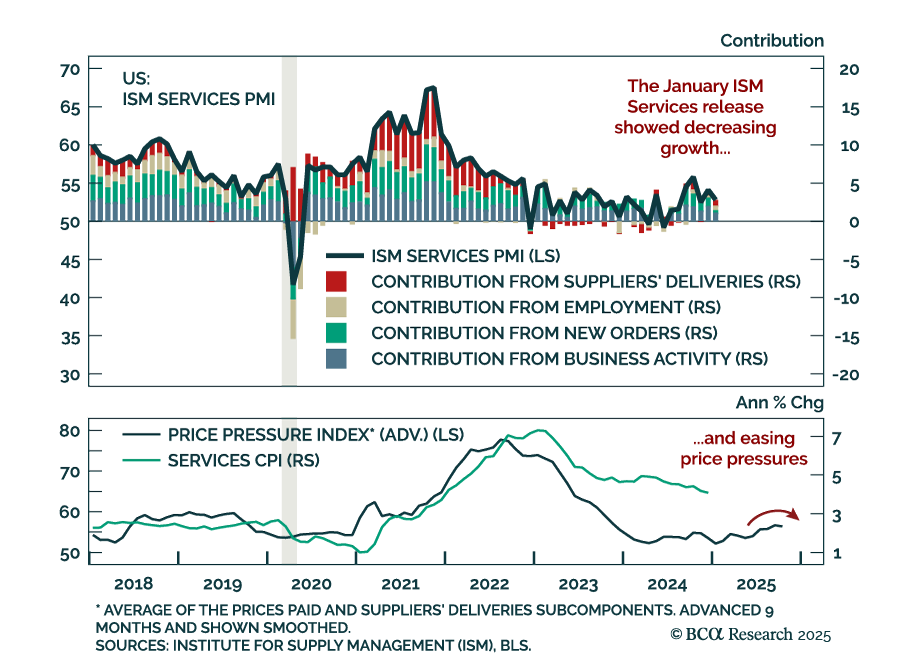
The January ISM Services missed estimates, decreasing to 52.8 from 54.0 in December. The move was driven by activity components, while employment and suppliers’ delivery times increased. Additionally, the prices paid measure decreased, reversing the…
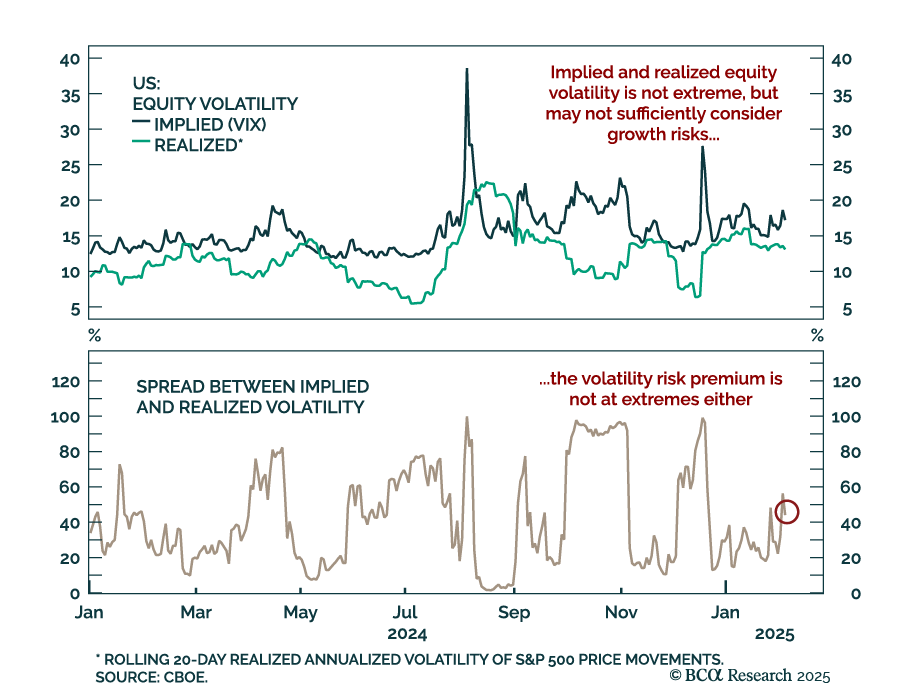
Despite disruptive headlines, equity market volatility remains contained. The S&P 500 has been in a tight range since the last VIX spike, and news of a disruptive, cheaper AI technology has not sustainably brought down US tech stocks. Both implied and…