Sorry, you need to enable JavaScript to visit this website.
Saltar al contenido principal

Economía

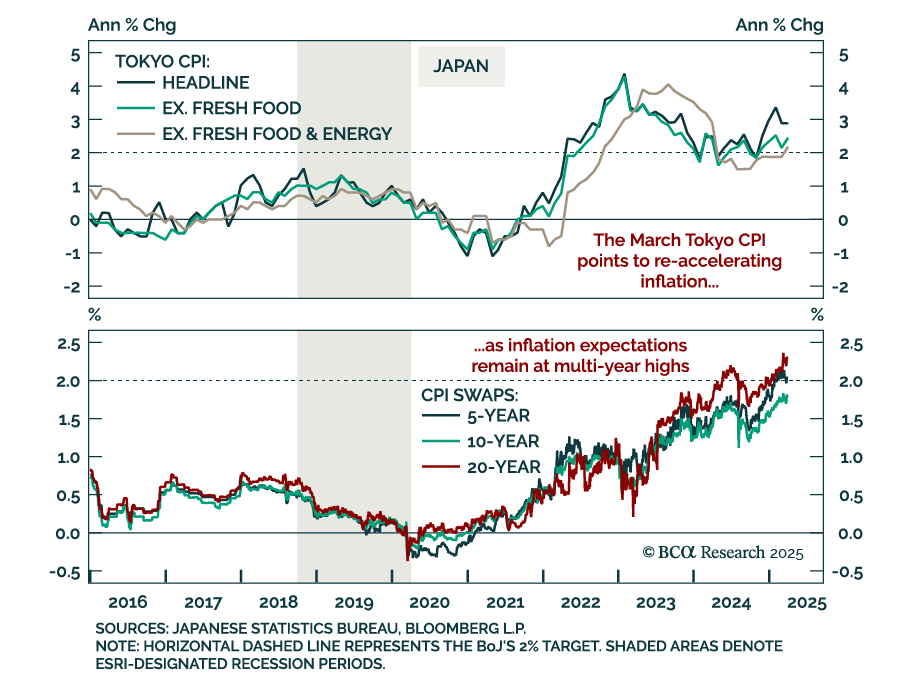
Japan’s inflation pulse remains firm, reinforcing our long JPY stance and cautious view on JGBs. Tokyo CPI for March surprised to the upside, with headline inflation slightly up at 2.9% y/y and “core core” accelerating above the BoJ’s target to 2.2% from…

This morning’s weak consumer spending and strong inflation data reinforce our sense that the US economy is heading toward recession.
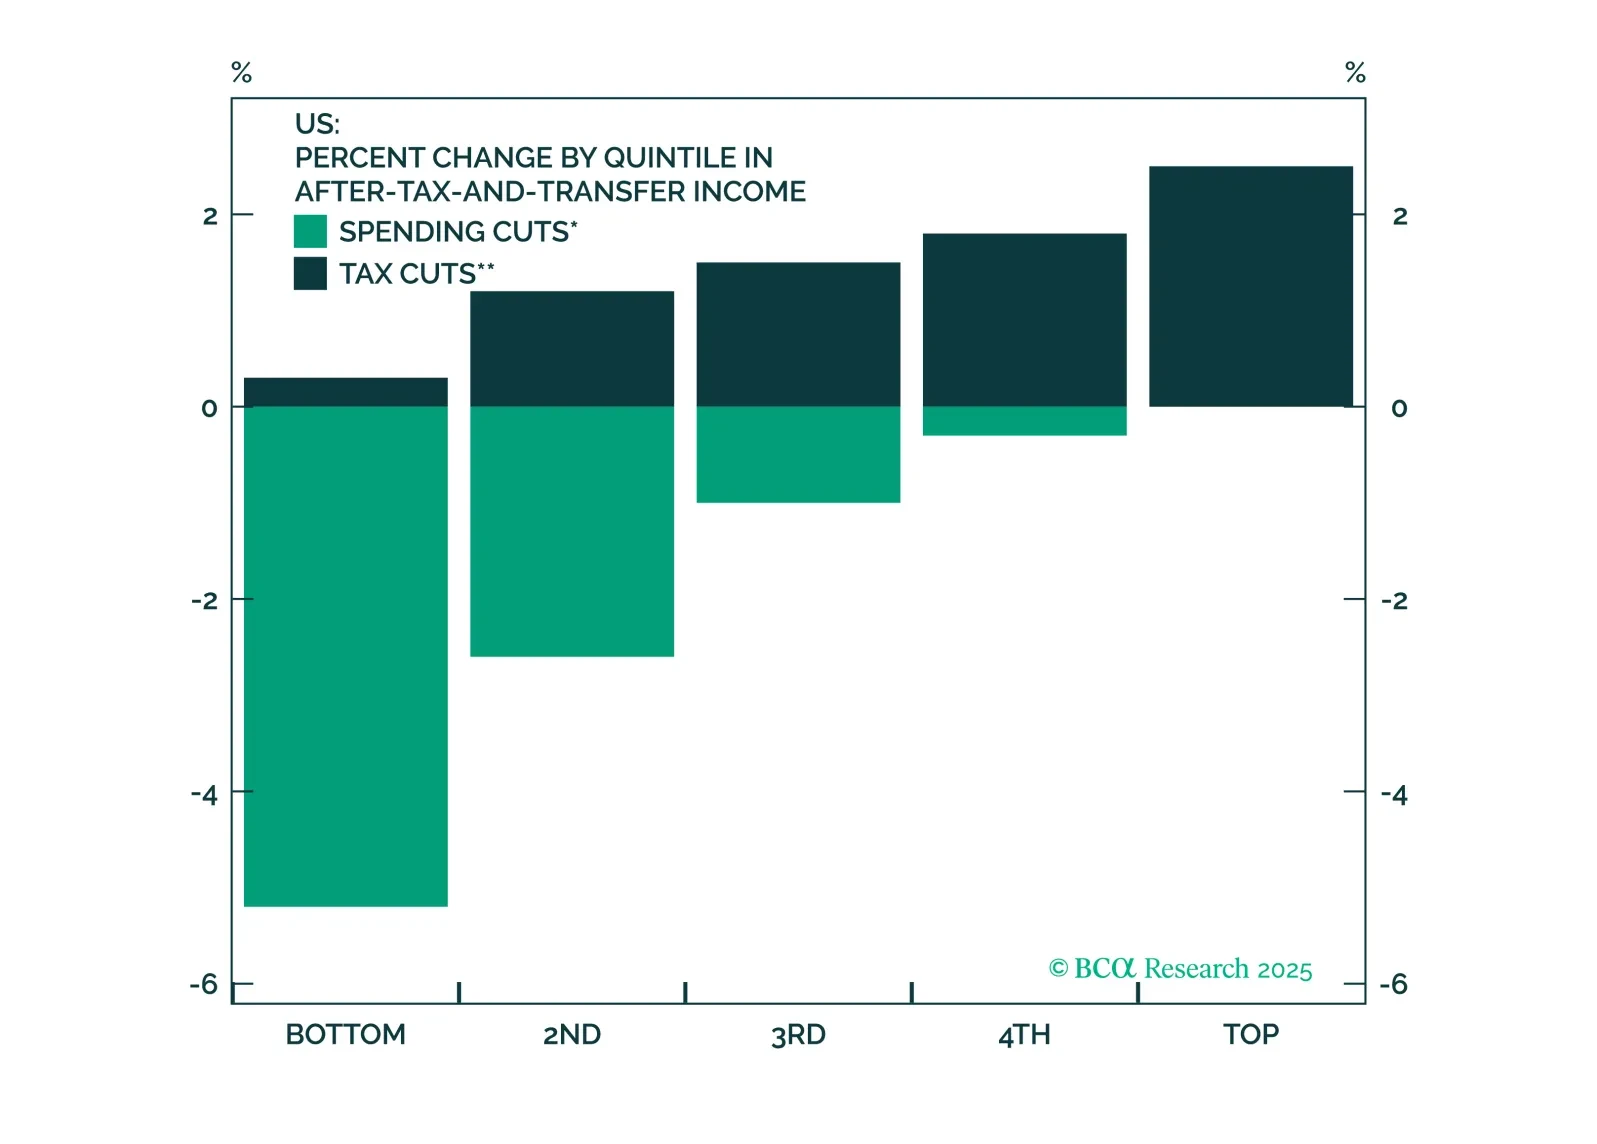
Stocks will continue to struggle in the second quarter as President Trump tries to implement tariffs. Tax cuts will only temporarily dispel growth fears, if at all. Middle Eastern instability will add oil price surprises to an environment that is looking fairly stagflationary.
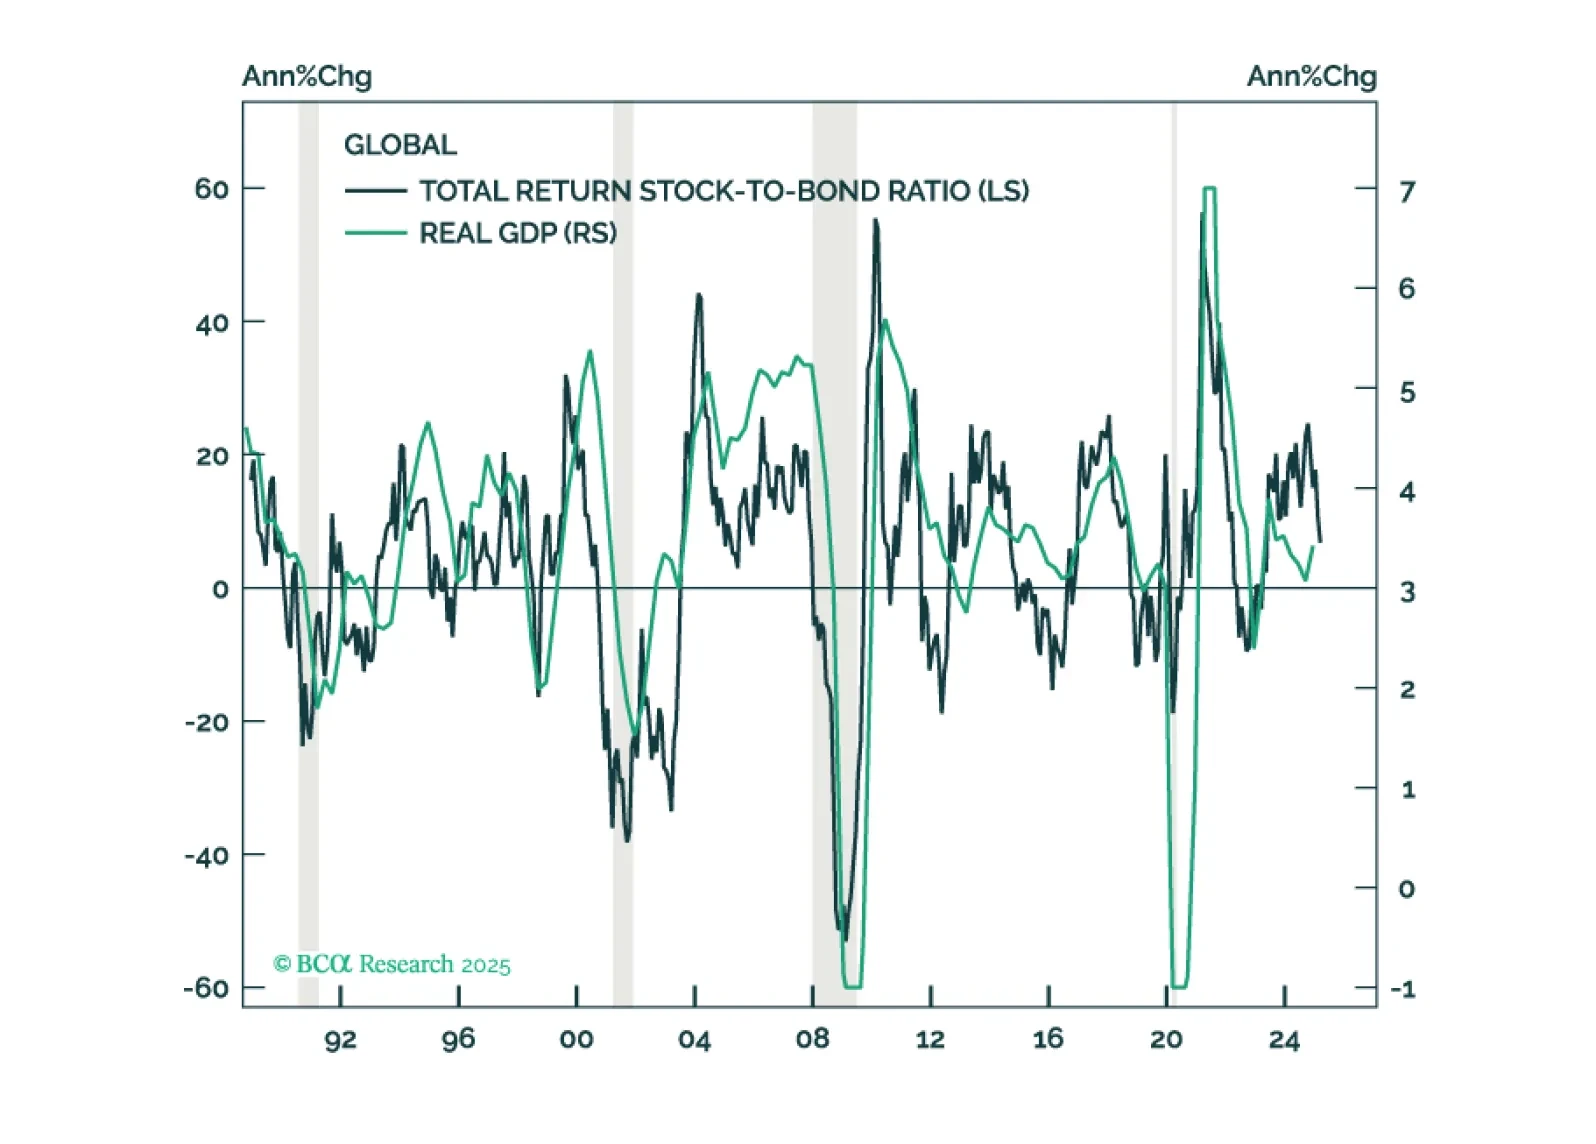
In this Second Quarter Strategy Outlook, we explore the major trends that are set to drive financial markets for the rest of 2025 and beyond.
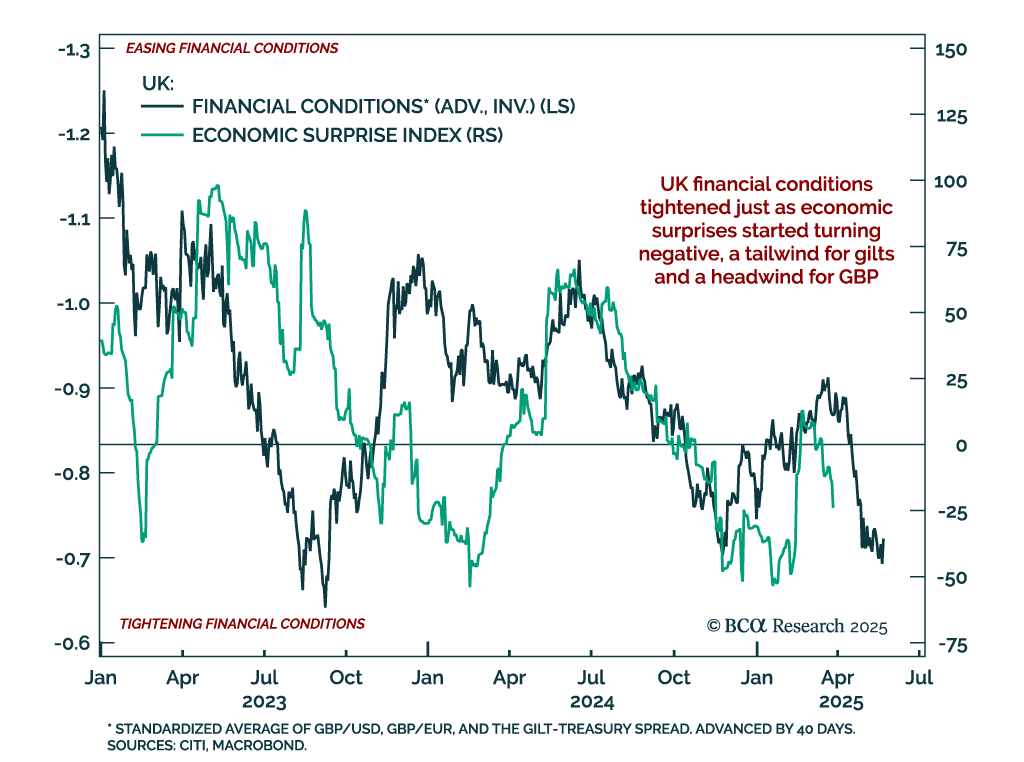
UK financial conditions have tightened just as economic surprises have turned negative, an uncomfortable combination that reinforces our tactical positioning. We remain overweight UK gilts within a global bond portfolio and are tactically short GBP/USD from…
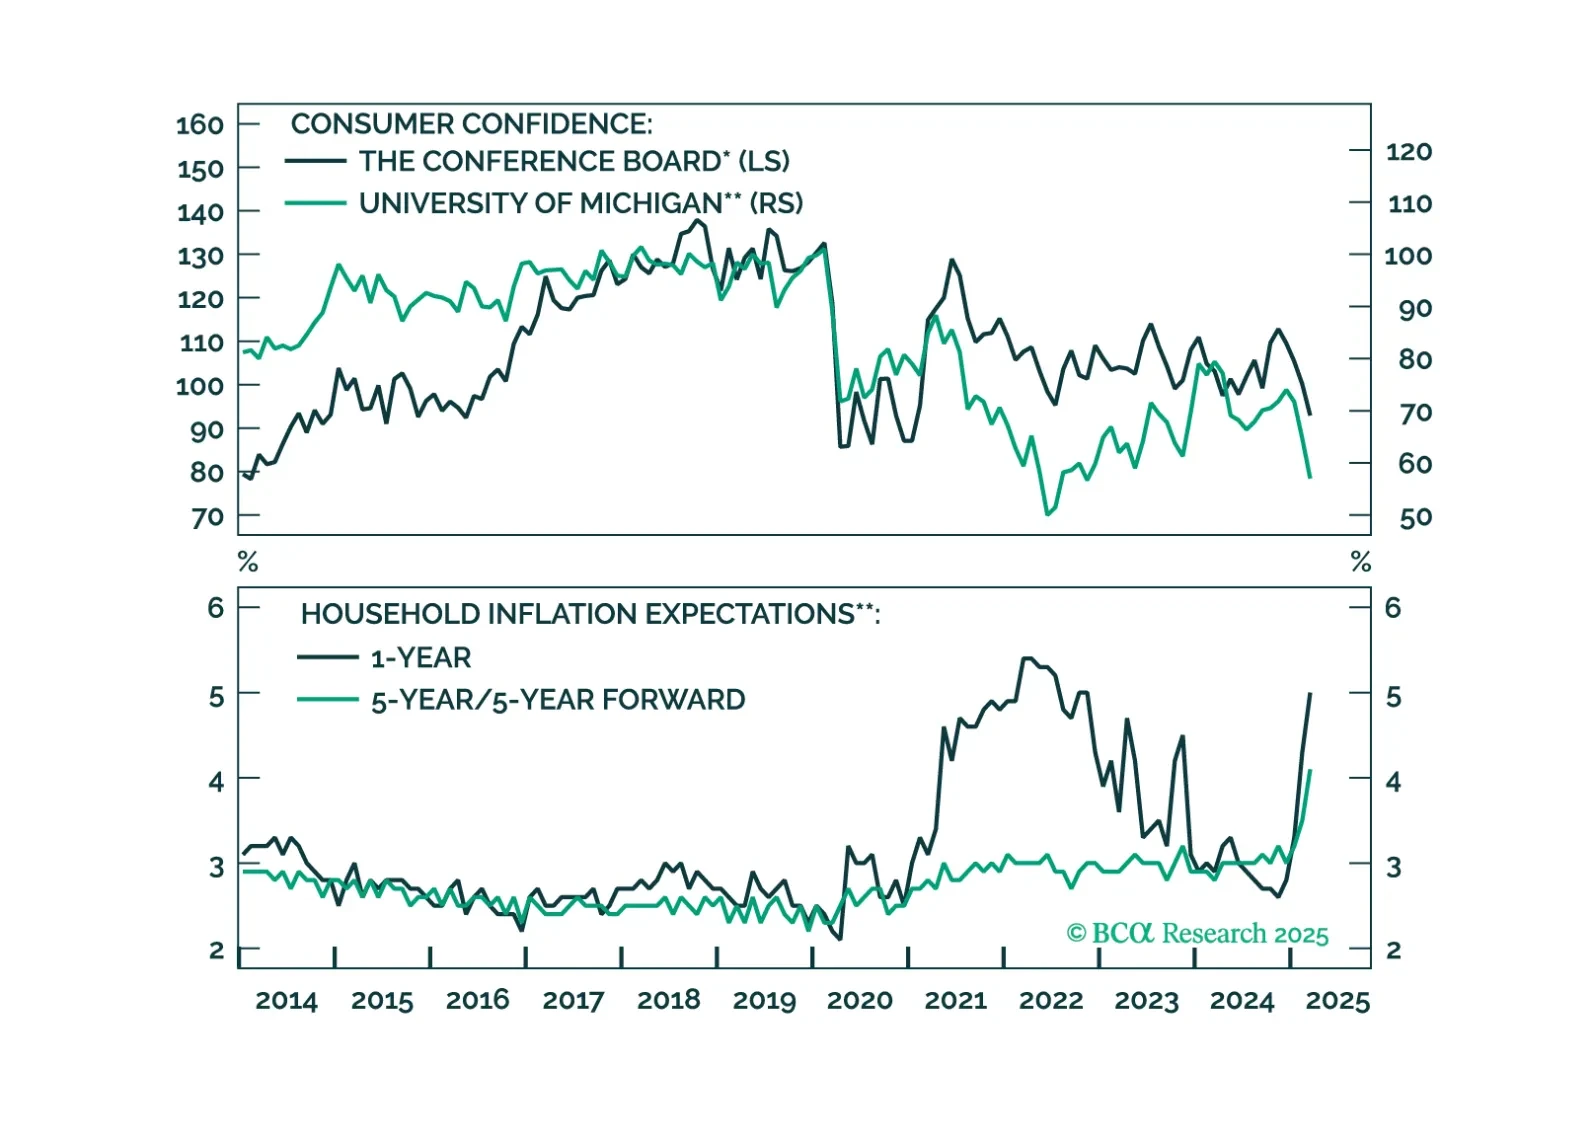
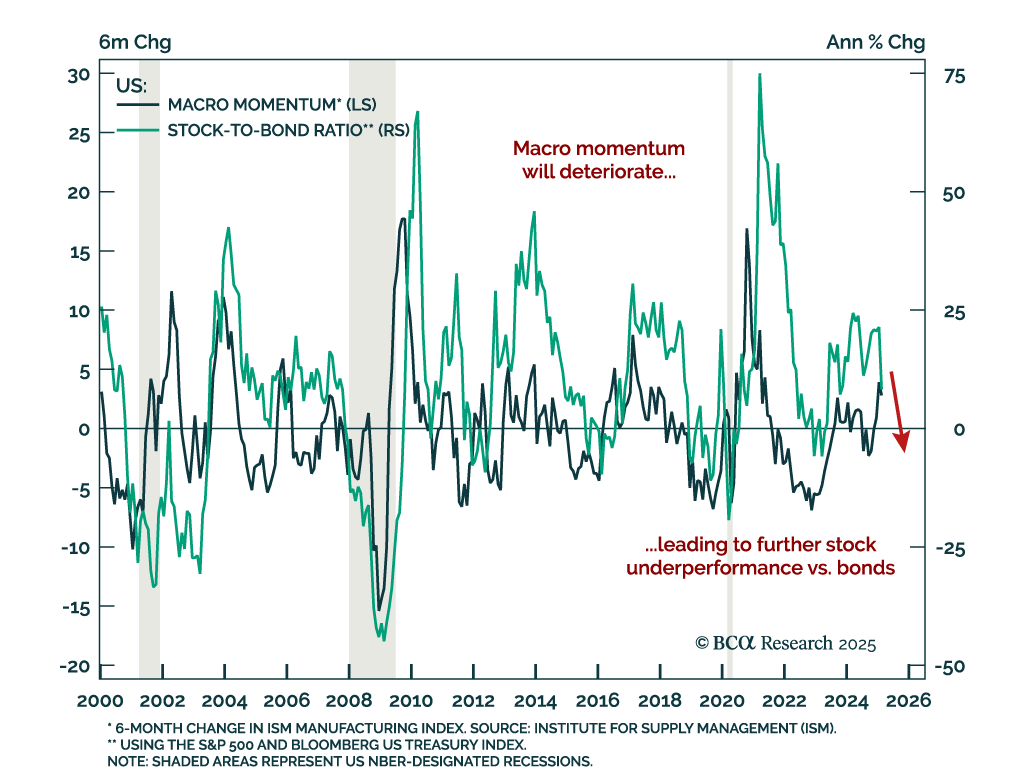
Macro momentum is deteriorating rapidly, and we remain defensively positioned as risks build. Business and consumer confidence have fallen sharply, and while the US post-election period began with optimism, policy uncertainty has since taken over, prompting a…

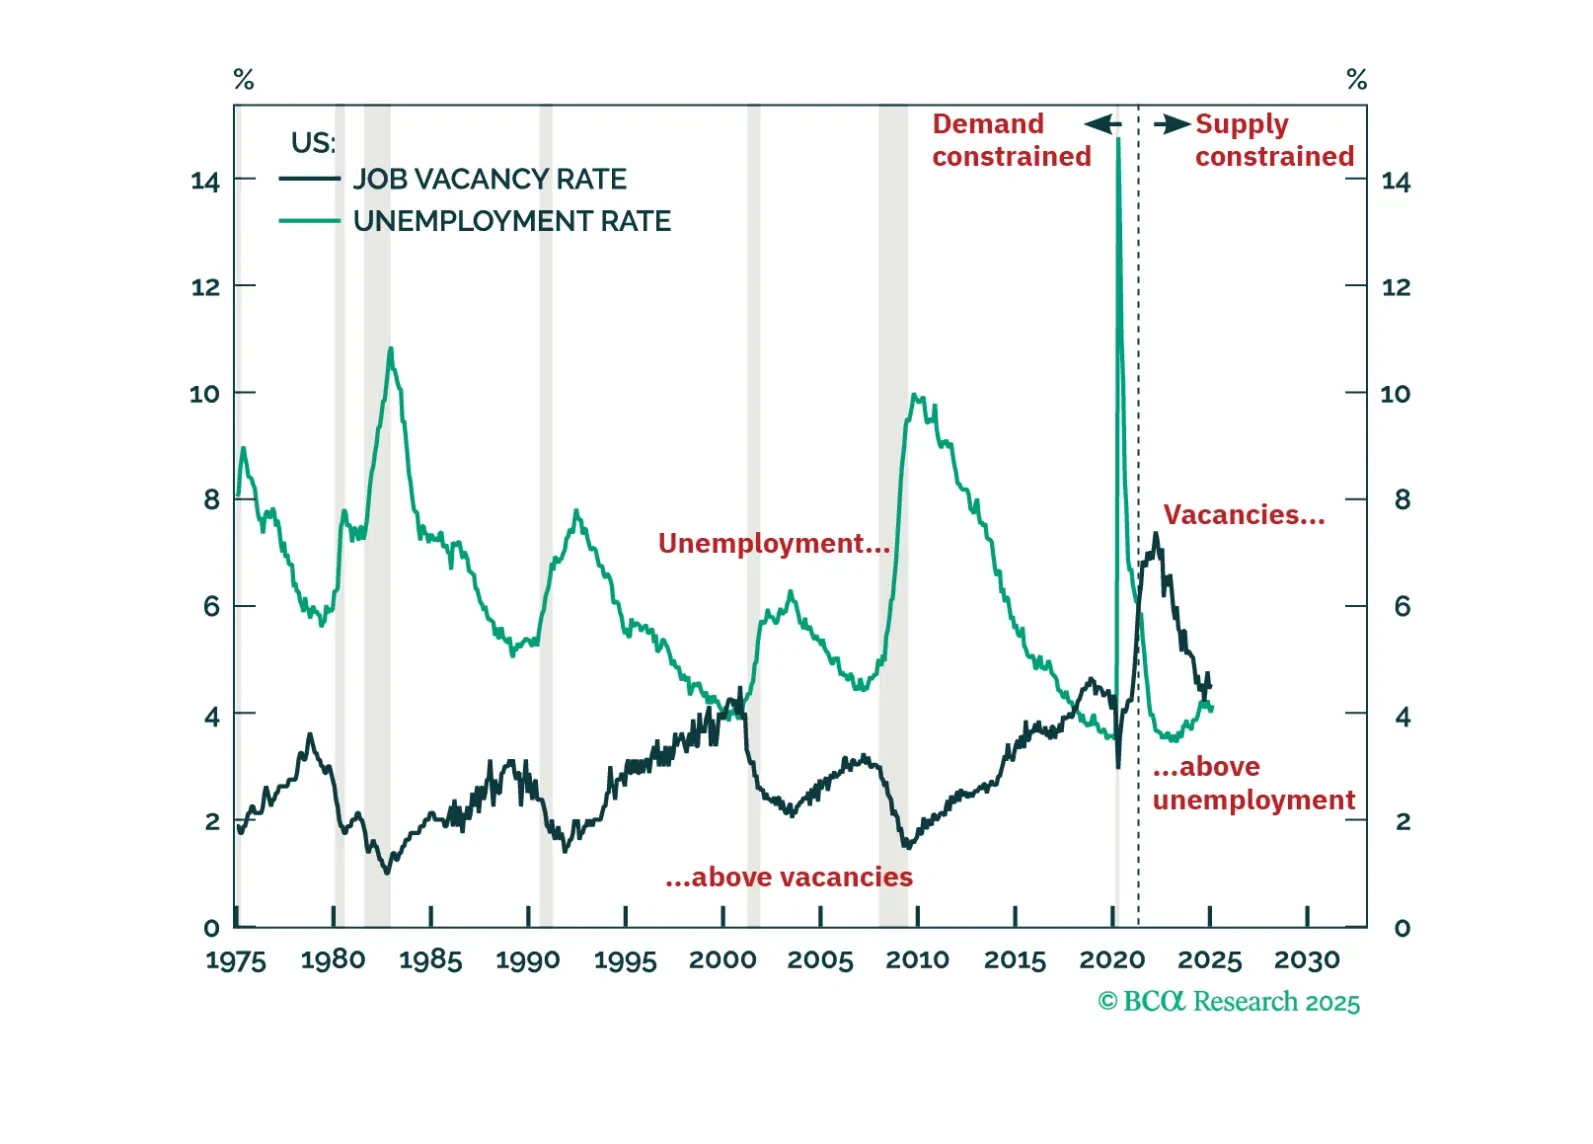
The US economy has never entered a demand-driven recession without labour demand running below labour supply and without the job vacancy rate running below the unemployment rate. Right now though, US labour demand is still running 1.7 million workers above labour supply, and the job vacancy rate is running comfortably above the unemployment rate. This suggests that the labour market is still supply-constrained, and that a demand-driven recession is not imminent. We discuss the investment implications. Plus, more about our ‘trade of the century’: long cotton versus coffee.
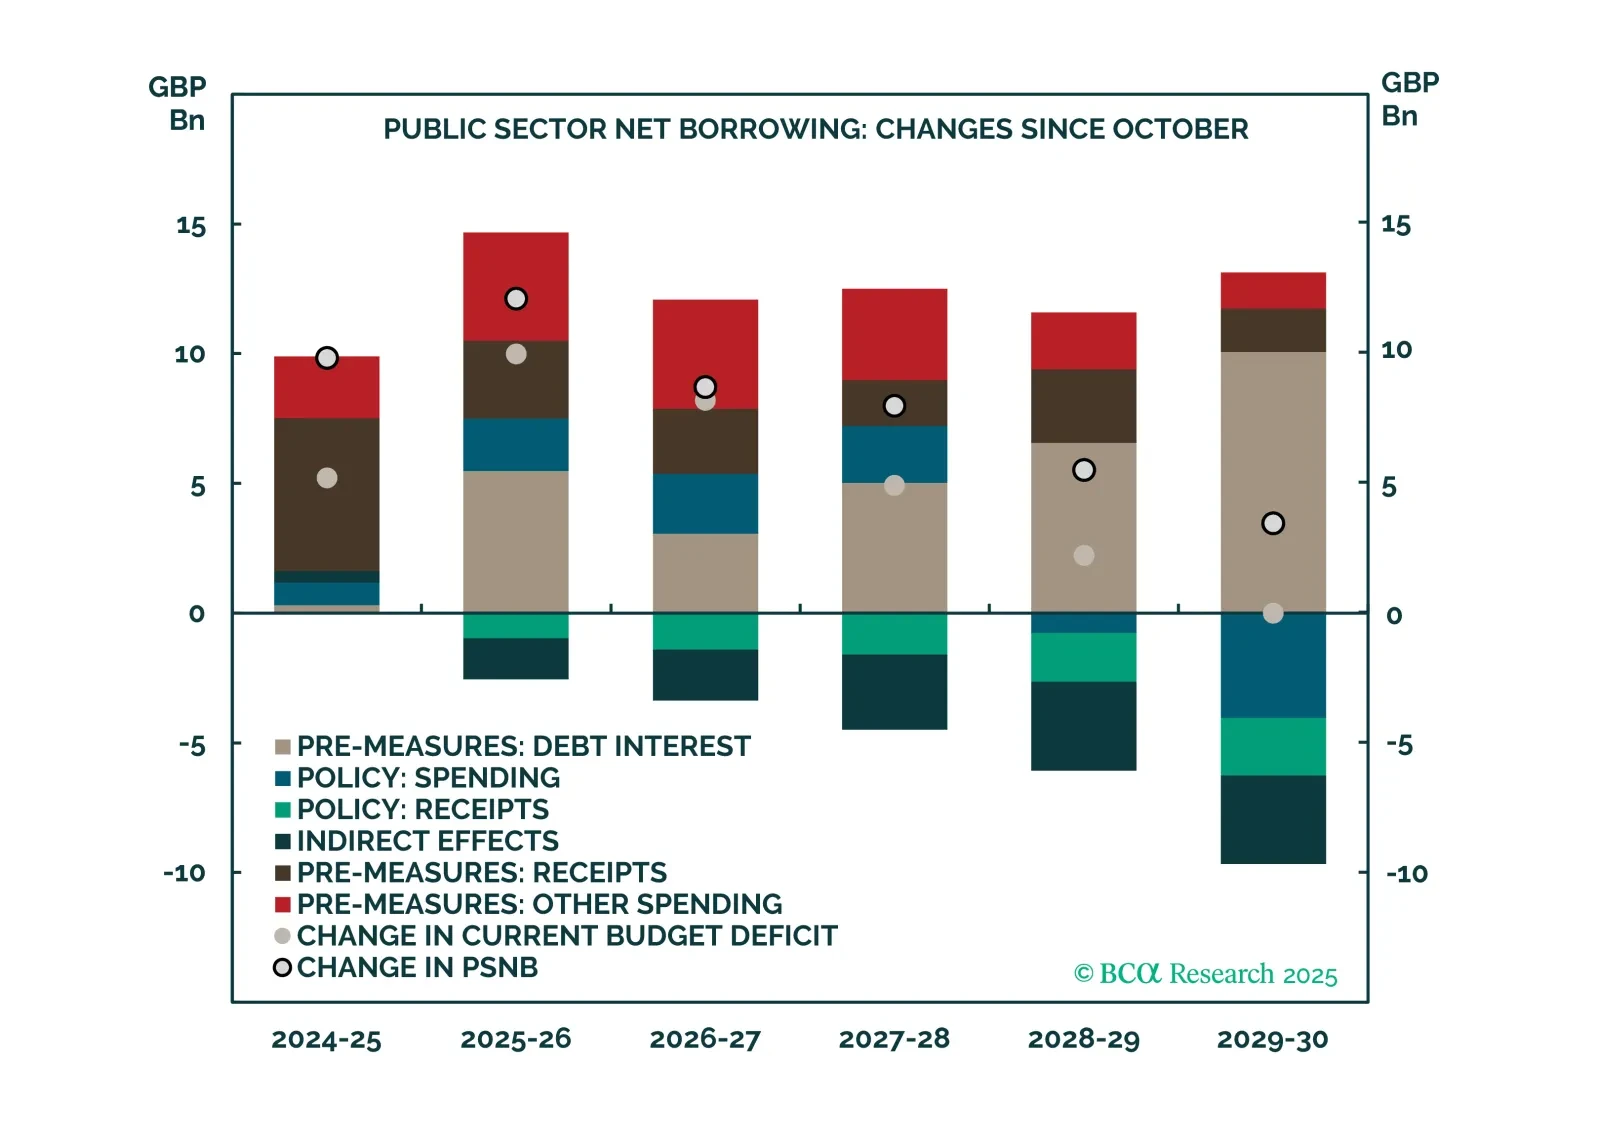
This report is a quick take on our views on UK bonds and FX, given the recent budget.
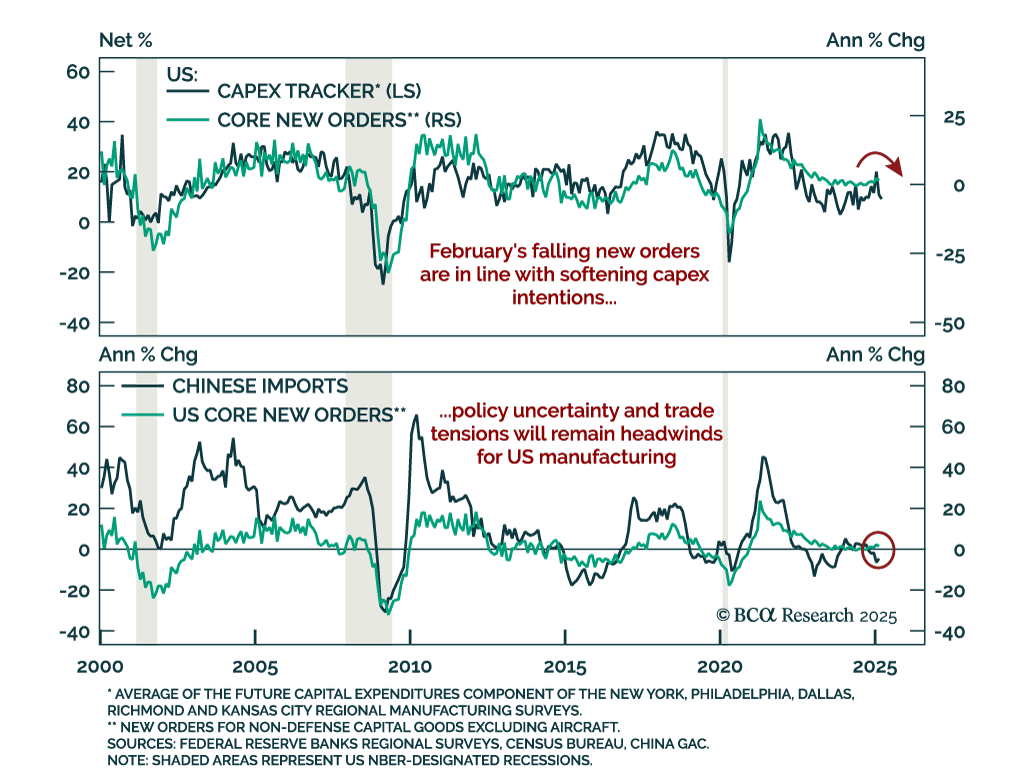
A drop in core capex orders points to slowing business spending and softening global growth. Businesses appear to have front-loaded shipments ahead of potential tariffs while deferring new orders amid policy uncertainty. With hiring and capex plans softening…
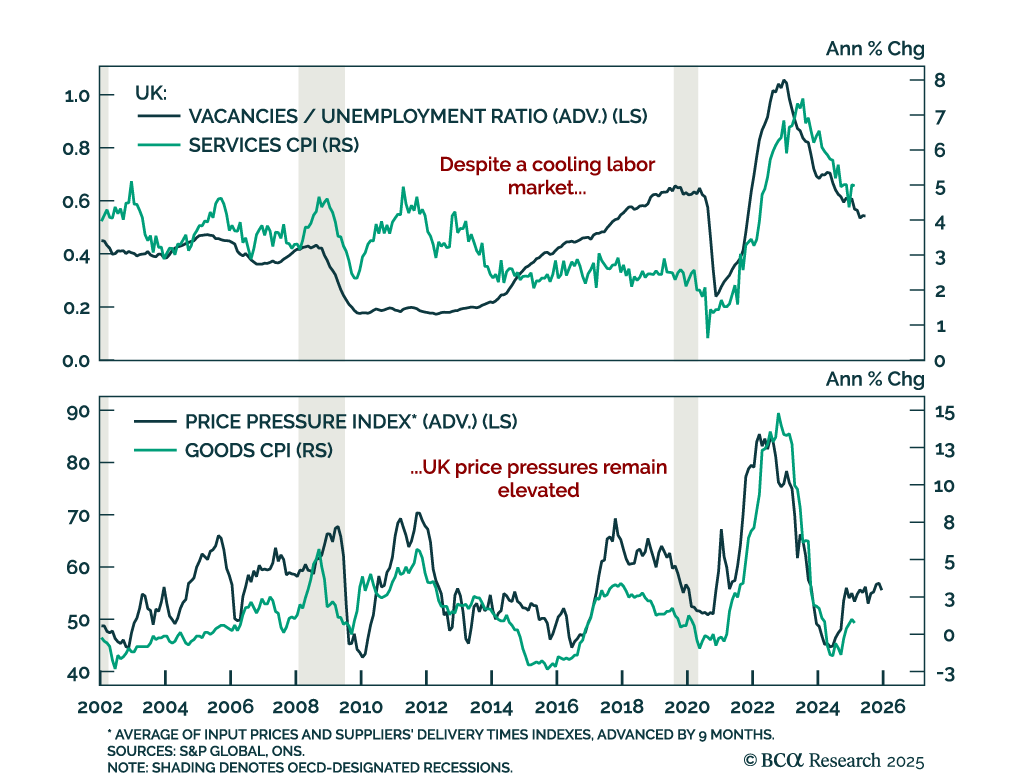
UK inflation came in cooler than expected in February, but lingering price pressures and a still-firm labor market keep the BoE sidelined, for now. Our Global Fixed-Income strategists view the BoE as the most likely DM central bank to surprise on the dovish…