Economy
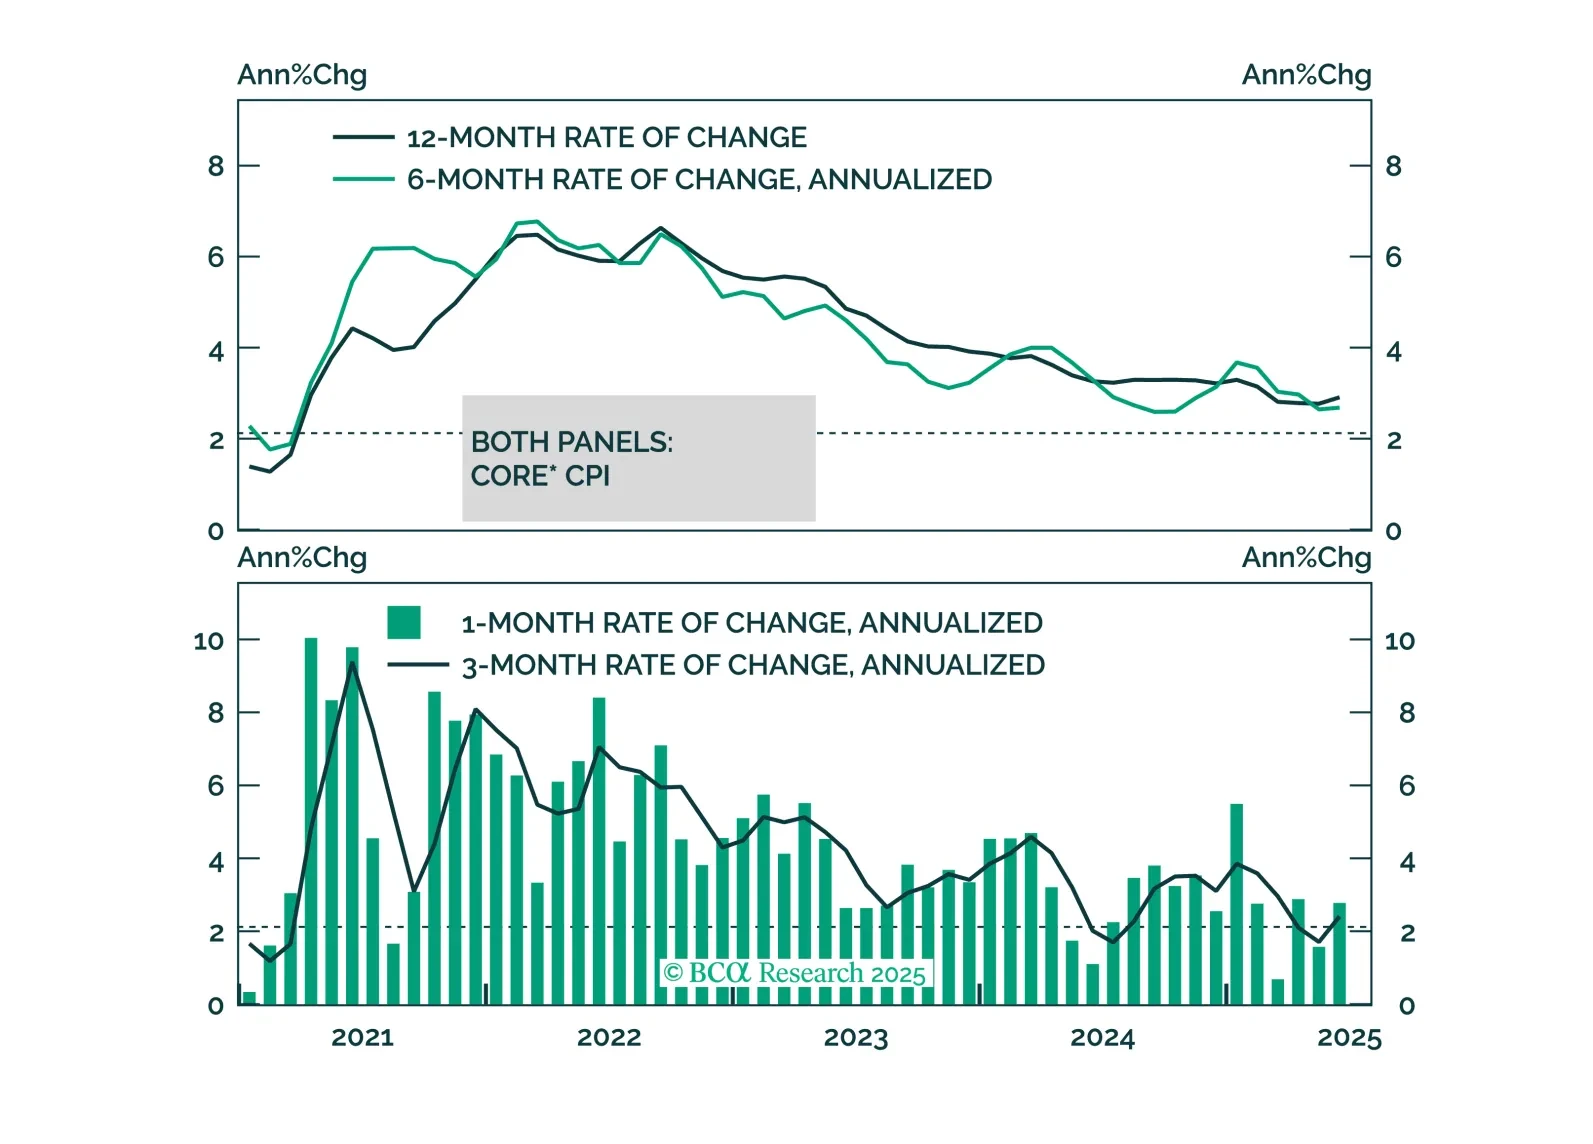
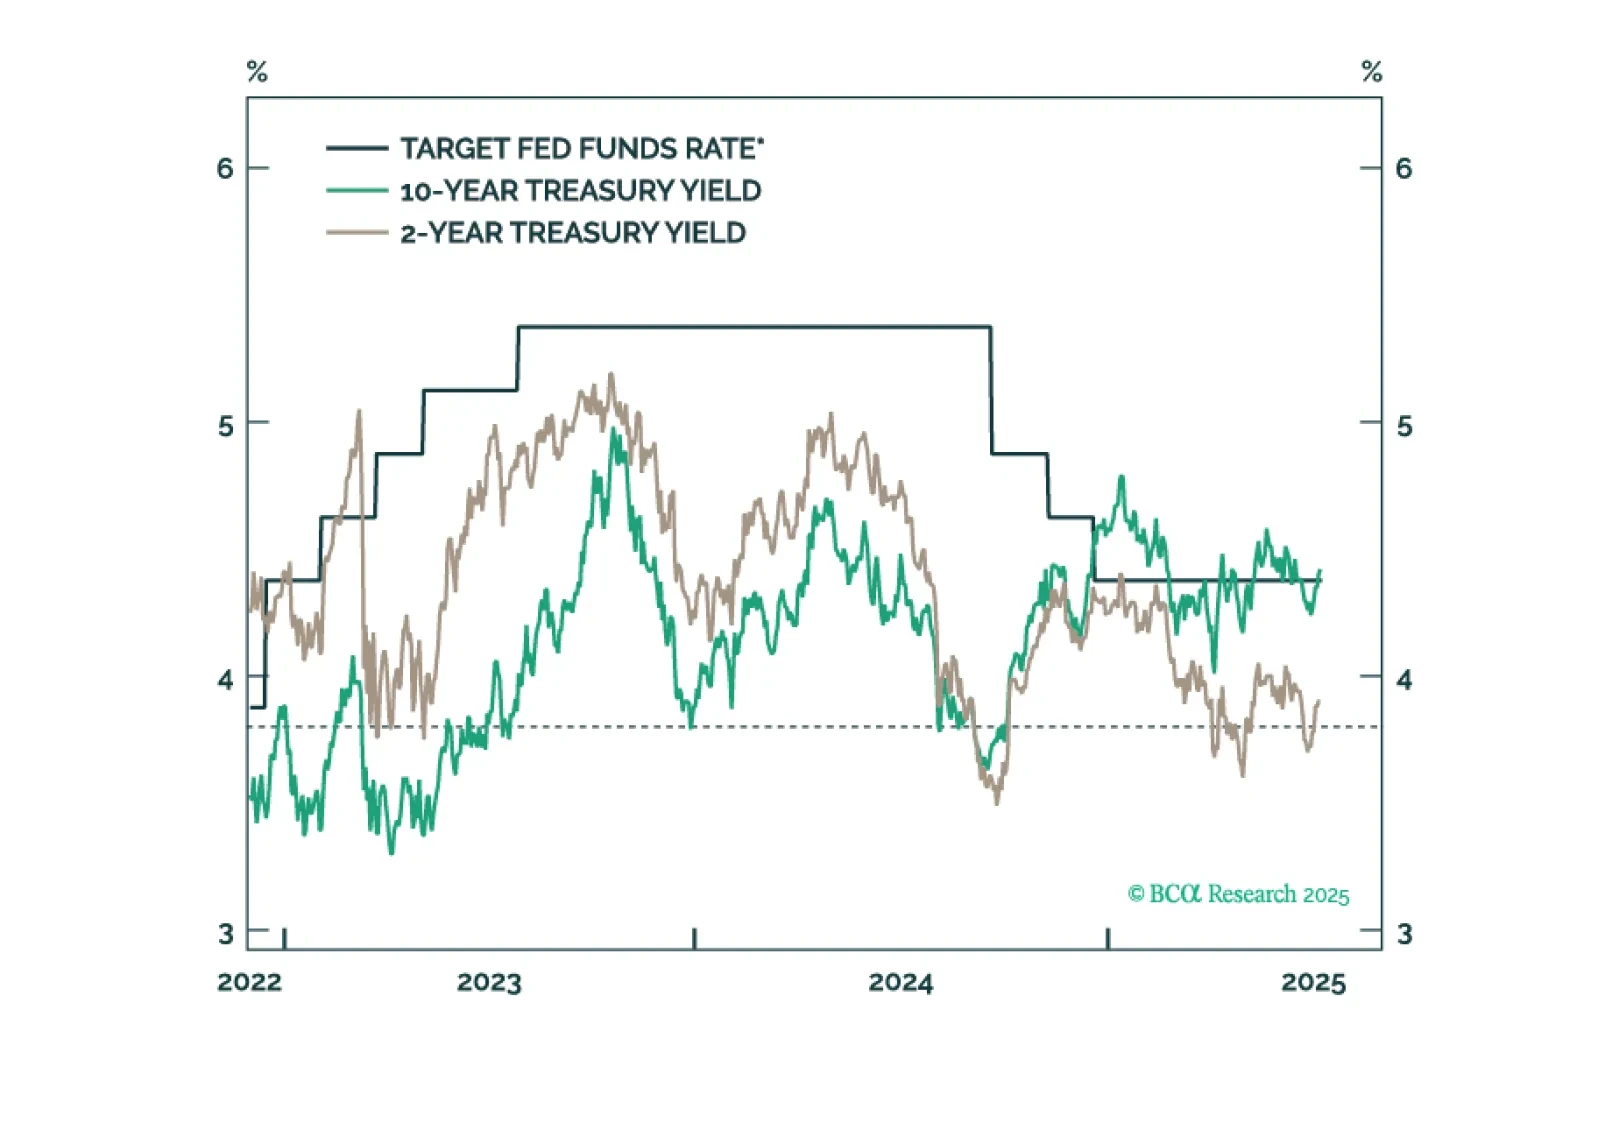
We discuss the implications of this morning’s CPI report and the relative attractiveness of 2/5 Treasury curve steepeners.
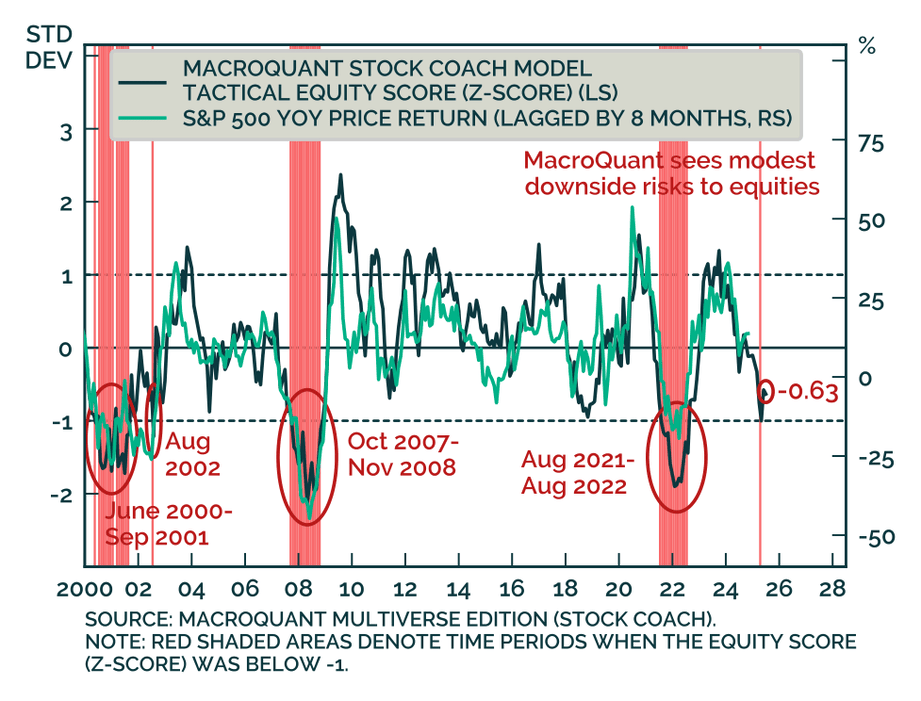
MacroQuant’s equity model points to mild downside risks for the S&P 500, supporting a modest equity underweight. Our Chart Of The Week comes from Chanhyuck Lee, from our Global Investment Strategy team. MacroQuant’s Stock Coach model, which synthesizes equity…
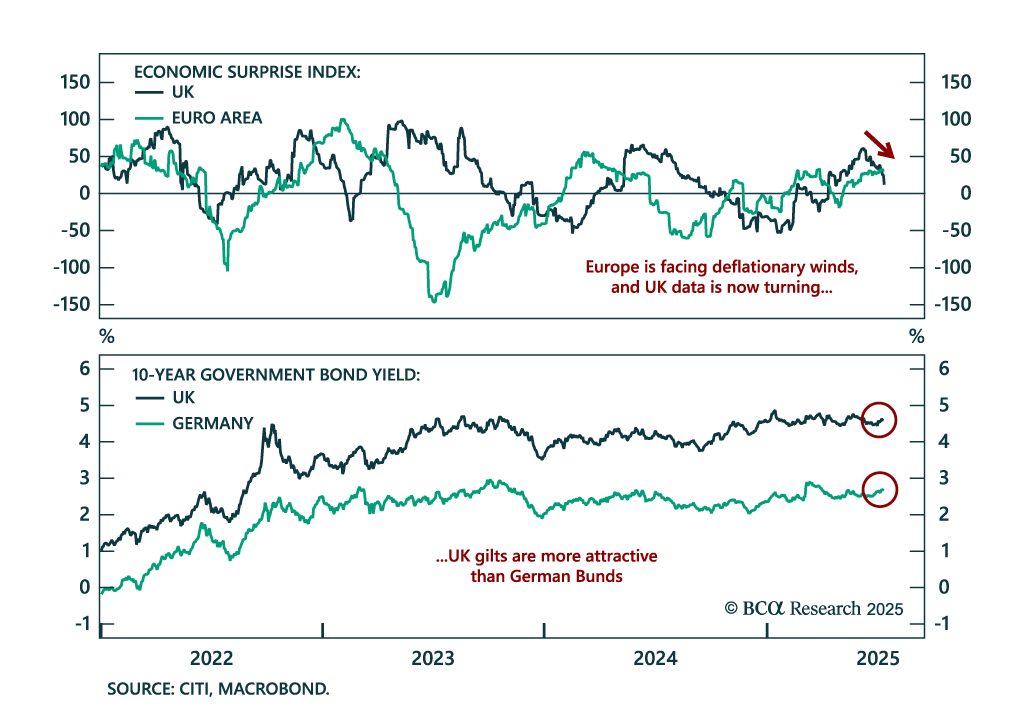
UK growth data continues to disappoint, making the case for a Gilts overweight and a dovish BoE. May GDP fell 0.1% m/m, missing estimates and marking a consecutive monthly contraction after April’s 0.3% decline. Industrial and manufacturing output both…
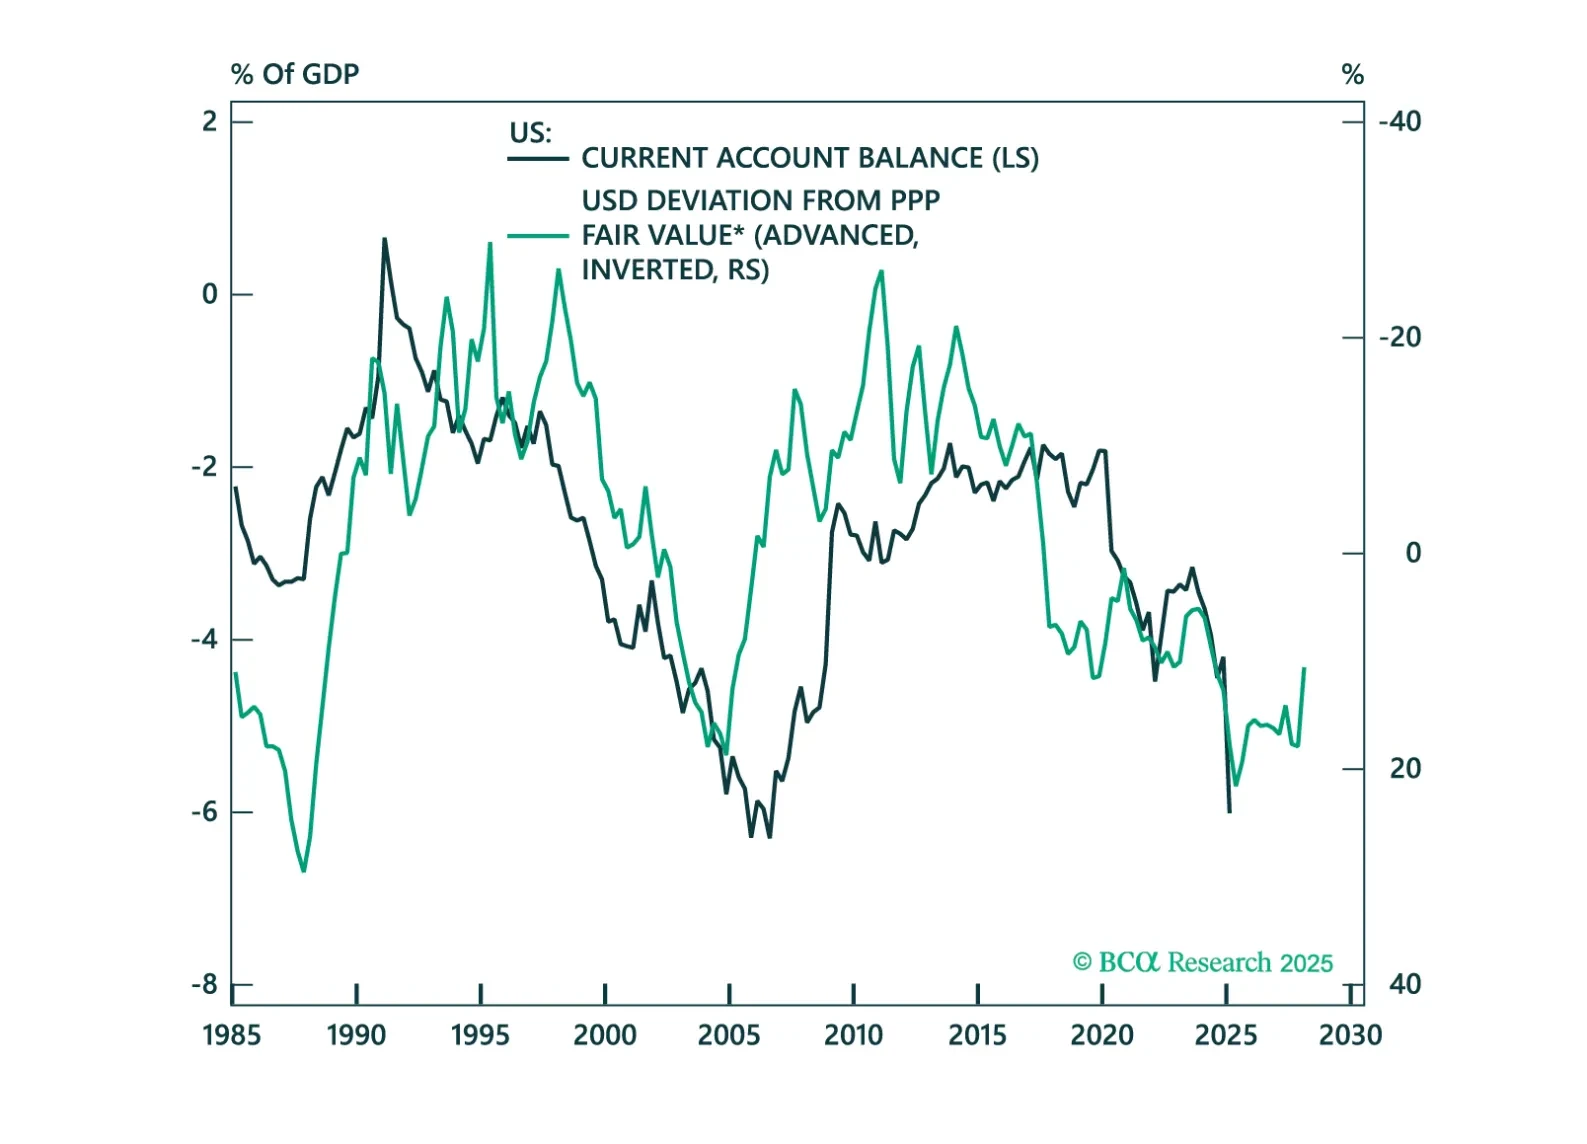
In this chartbook, we look at the balance of payments across DM and EM countries. The US does not fare well, but neither do a few other countries.
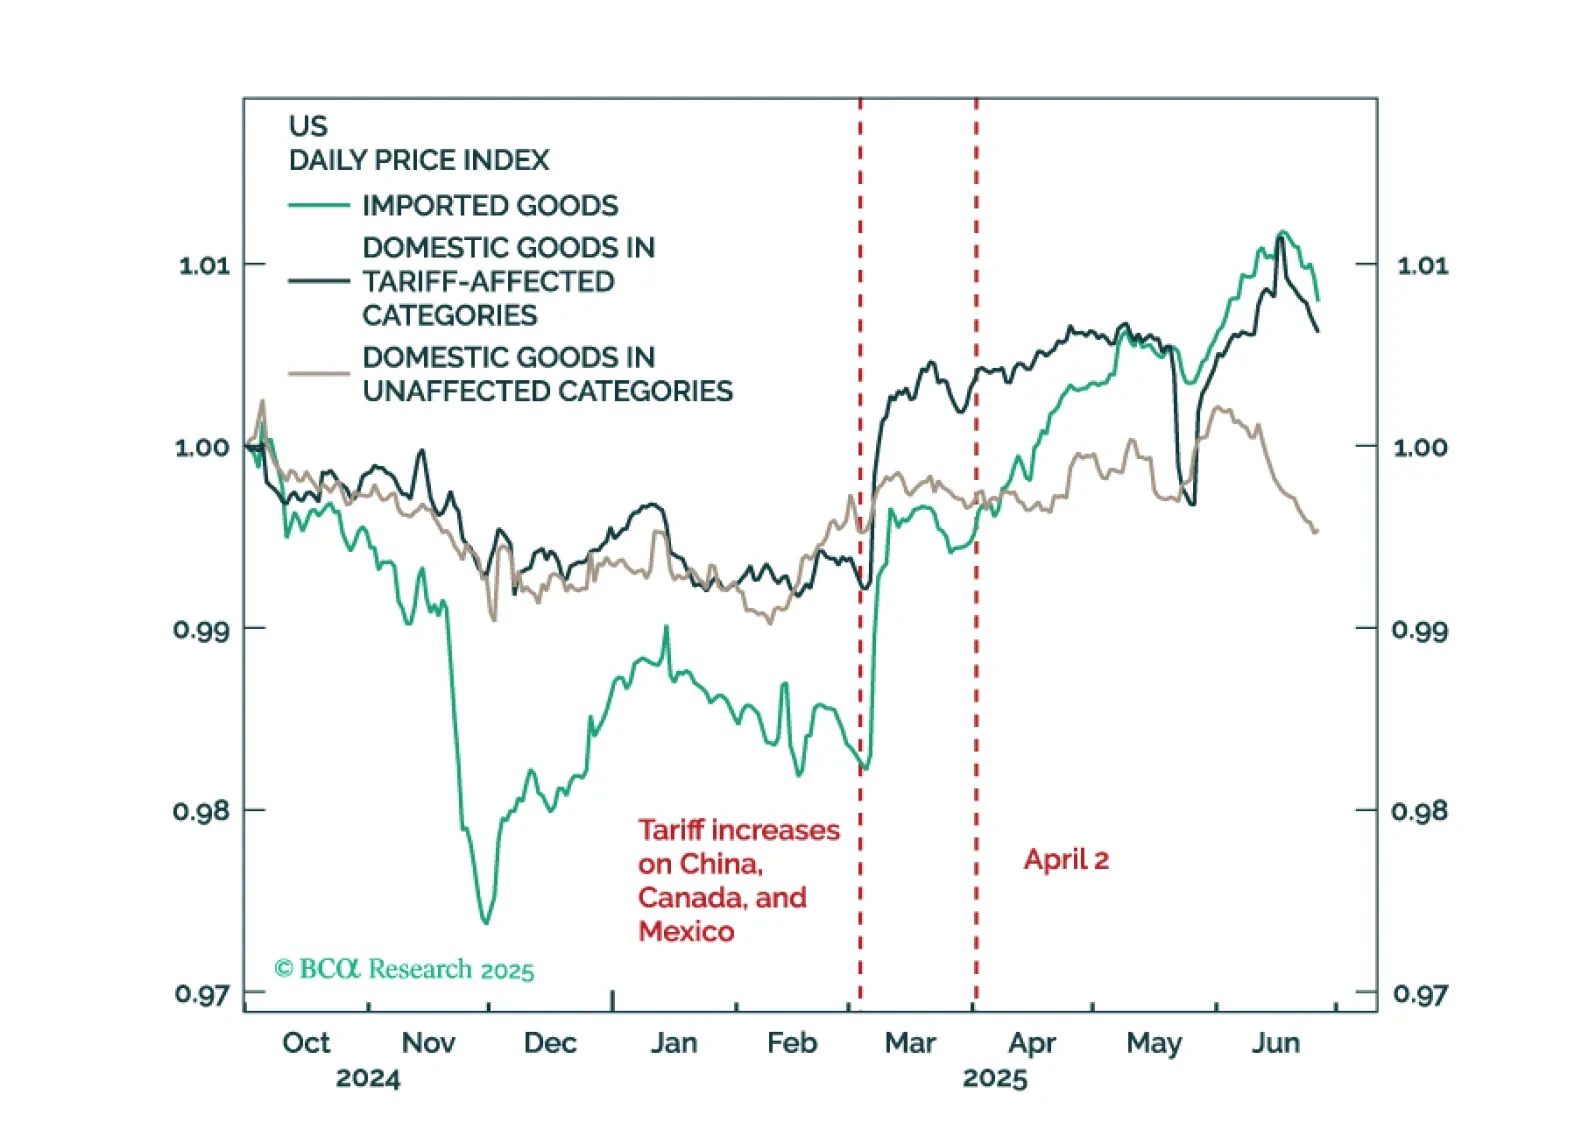
We will abandon our recession call if US economic data show clear signs of stabilization over the summer months. For now, that has not happened. Maintain a modest underweight to stocks but look to get more defensive if MacroQuant’s equity z-score falls below -1.
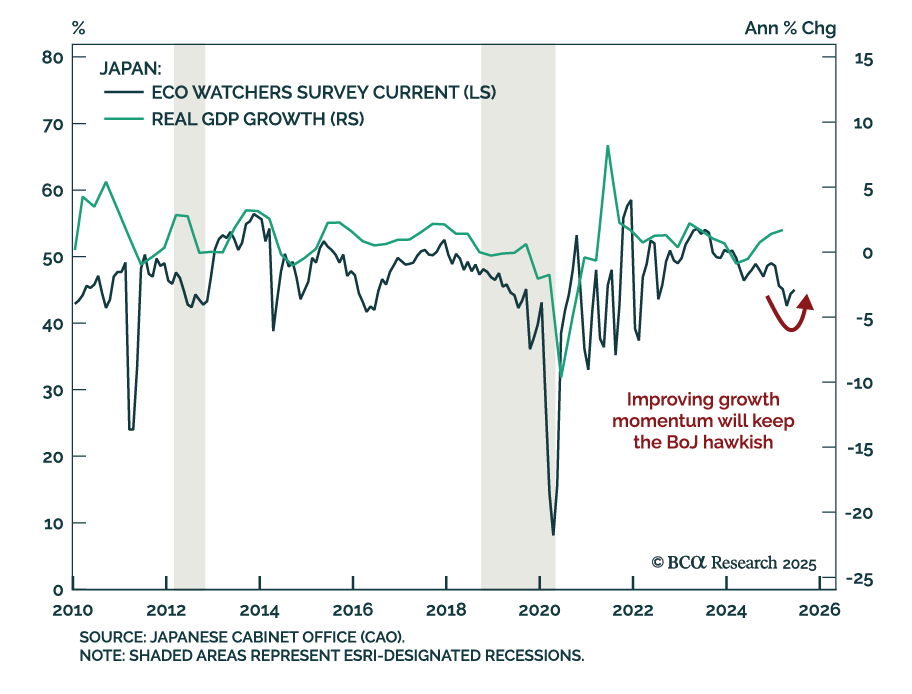
Japan’s improving growth momentum and structural inflation shift support an underweight in JGBs and long JPY positioning. The June Eco Watchers Survey was broadly in line with expectations, with current conditions ticking up to 45.0 and expectations modestly…
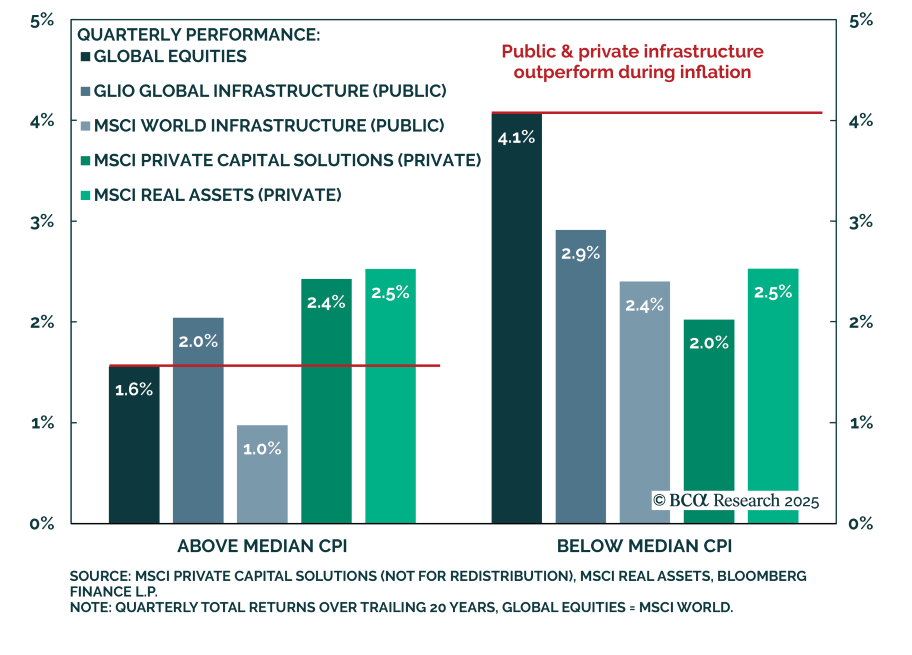
BCA’s Private Markets & Alternatives strategists recommend a balanced allocation across Public and Private Infrastructure, with near-term valuation favoring Public. Structural differences in index construction, sector mix, and regional exposure drive…
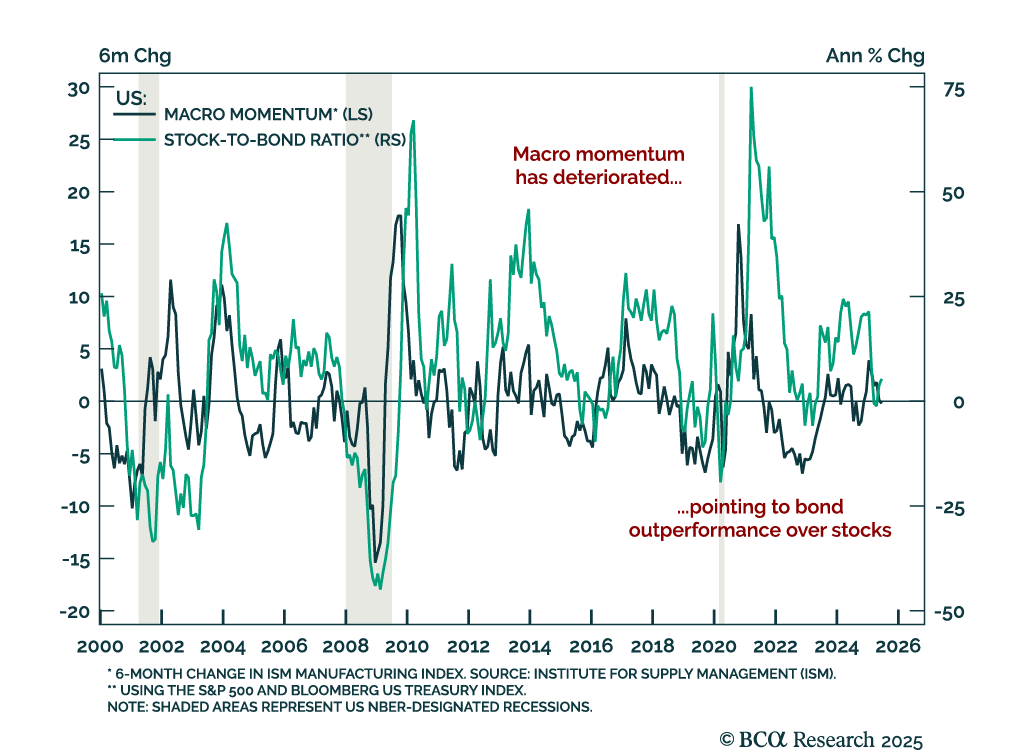
Deteriorating macro momentum supports a defensive asset allocation stance as hard data deteriorates. Last week’s ISM Manufacturing and Services PMIs confirmed that growth is slowing and price pressures are easing from a high level. The ISM Manufacturing index…
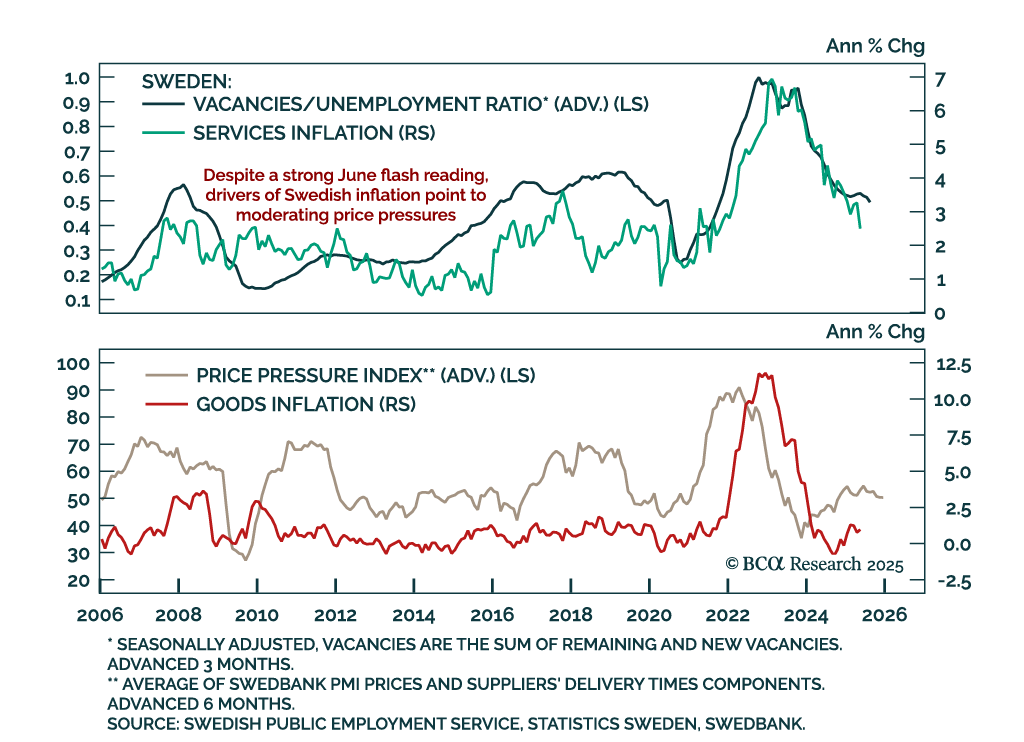
Stronger-than-expected June inflation will likely keep the Riksbank on hold in August, despite soft underlying trends. Headline inflation accelerated more than expected to 0.5% m/m (0.8% y/y), while CPI ex-housing rose to 2.9% y/y and core inflation to 3.3%…