 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
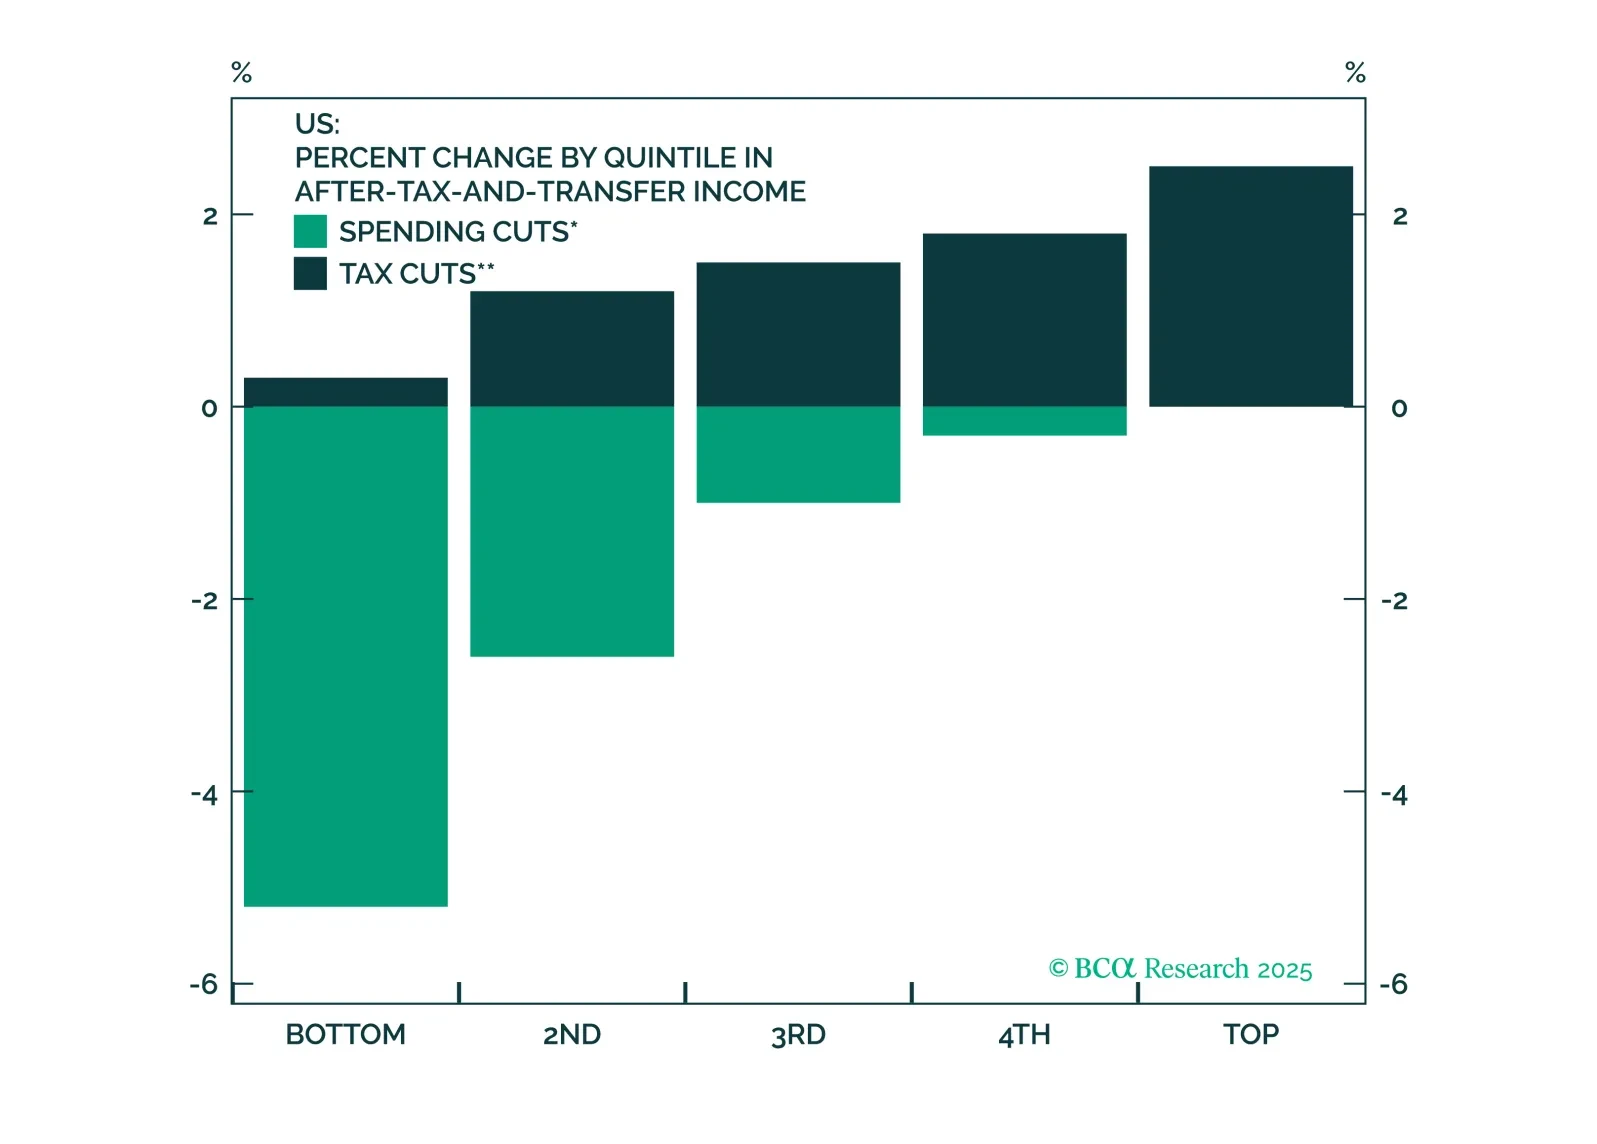
Stocks will continue to struggle in the second quarter as President Trump tries to implement tariffs. Tax cuts will only temporarily dispel growth fears, if at all. Middle Eastern instability will add oil price surprises to an environment that is looking fairly stagflationary.
Clients have asked us repeatedly about our thoughts on the Mar-a-Lago Accord. Our readers know that we believe that the US is constrained by its median voter and the reality of geopolitical multipolarity. As such, the path of least resistance is towards a cheaper USD, which is currently being achieved through an organic macro see-saw of relative fiscal policy. The idea that the US gets to “restructure the global trading system” on its own is, therefore, ludicrous.
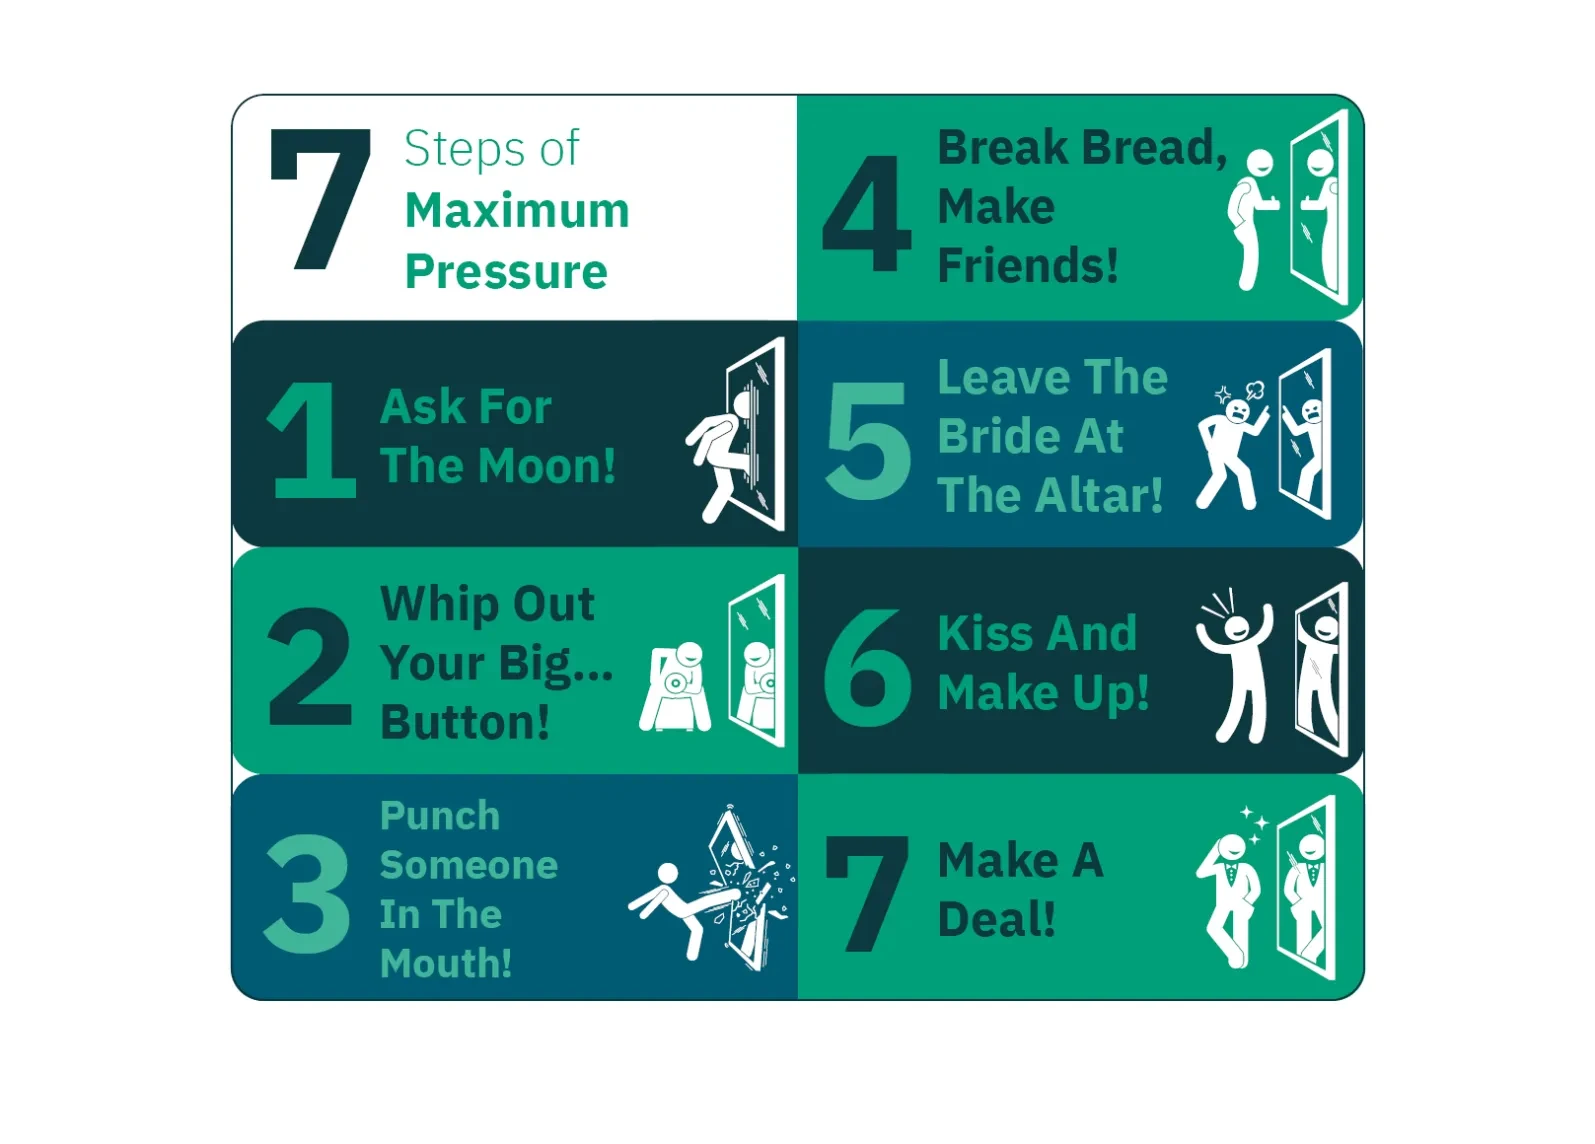
We share with our clients a brief rundown of “Washington, DC” intelligence on the upcoming April 2 tariffs. Most of it is bearish. However, the day may mark “peak de-globalization hysteria.” President Trump is also starting his Maximum Pressure campaign against Iran. That is two such campaigns at the same time, perhaps more than the administration can handle simultaneously.
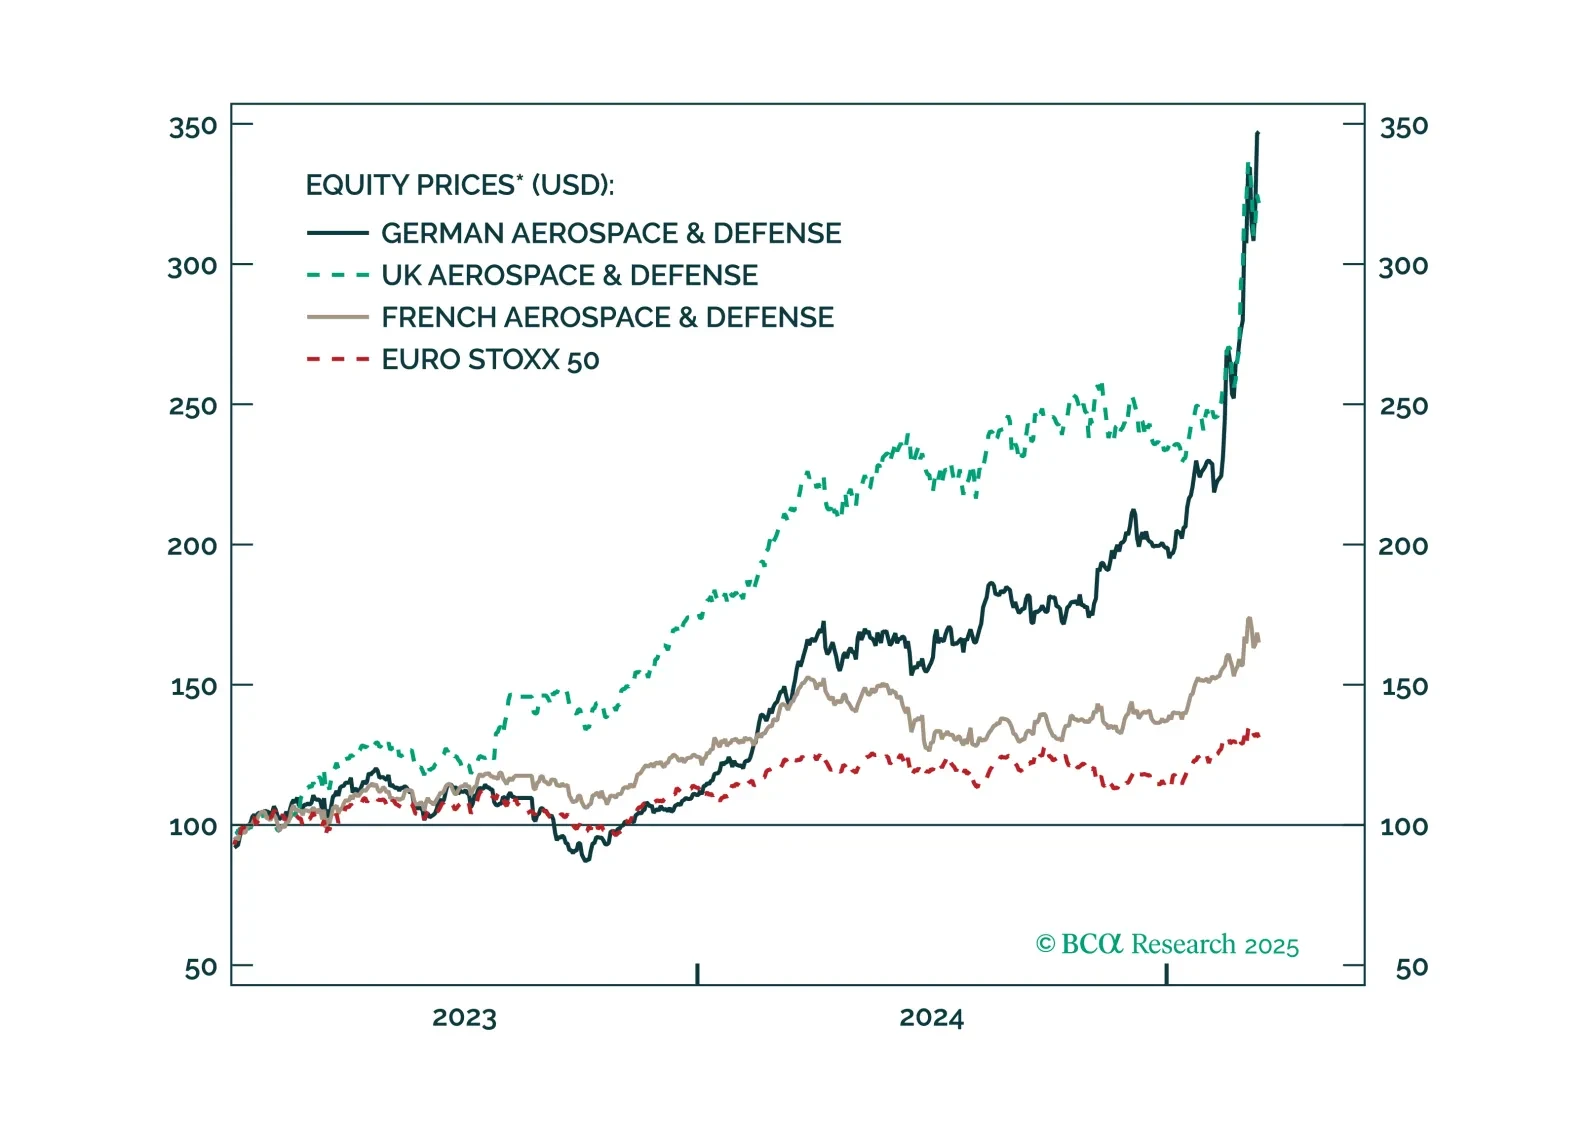
Investors should not chase the rally in European defense names any further. Too much good news has been priced in too quickly.
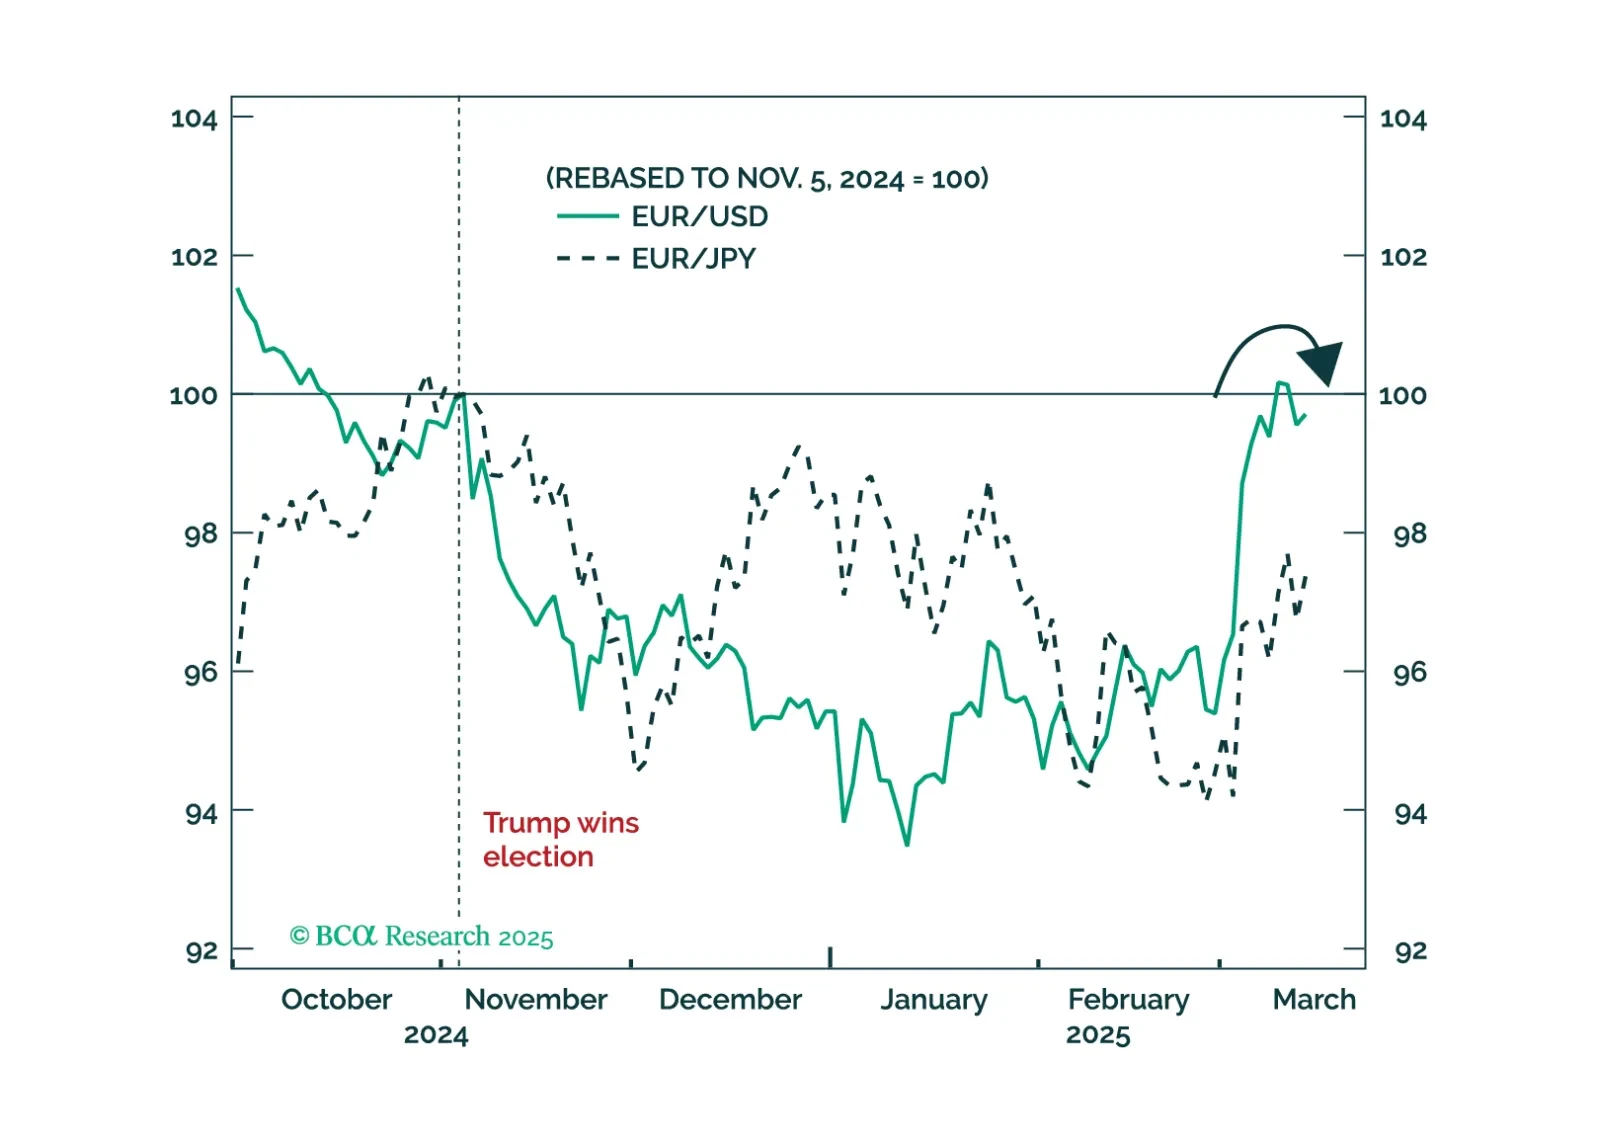
Trump’s foreign policy can be explained by rational US interests, but it requires settling the trade war with allies sooner rather than later. Book gains on EUR-USD for now.
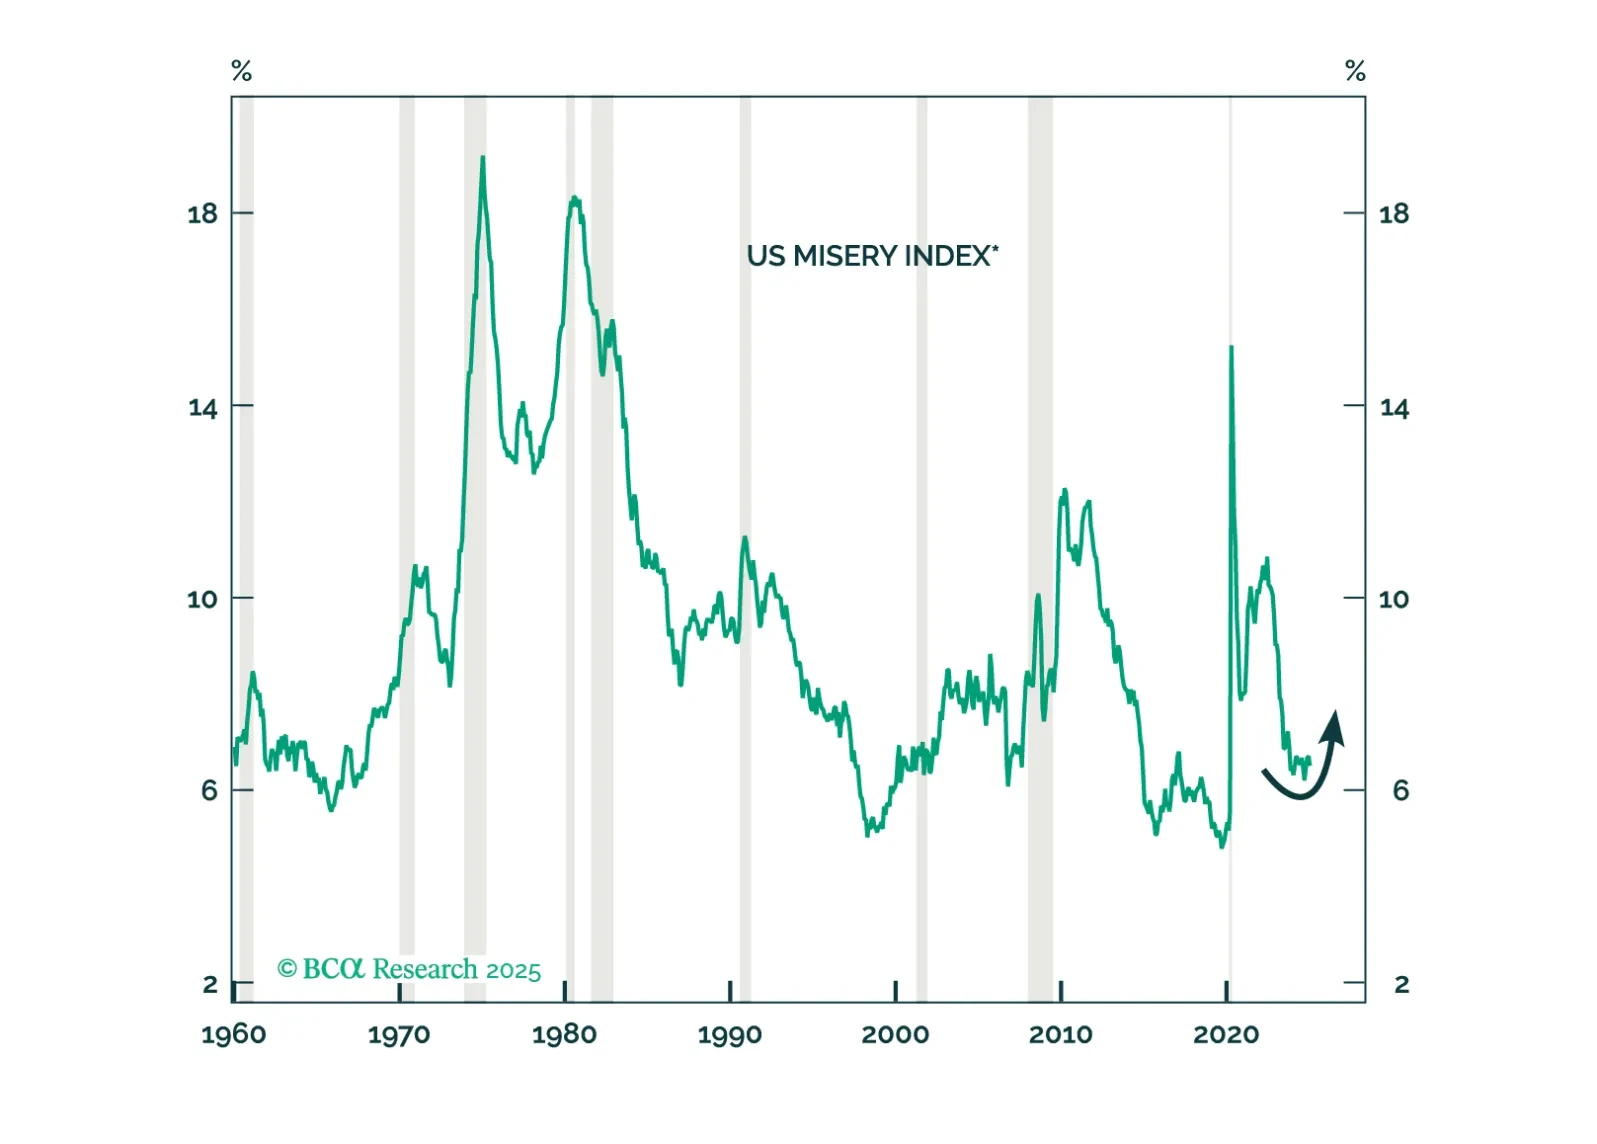
President Trump may not avoid recession. If he does, he faces stagflation, given tariffs, counter-tariff stimulus, and the missing ingredient: an oil price spike.
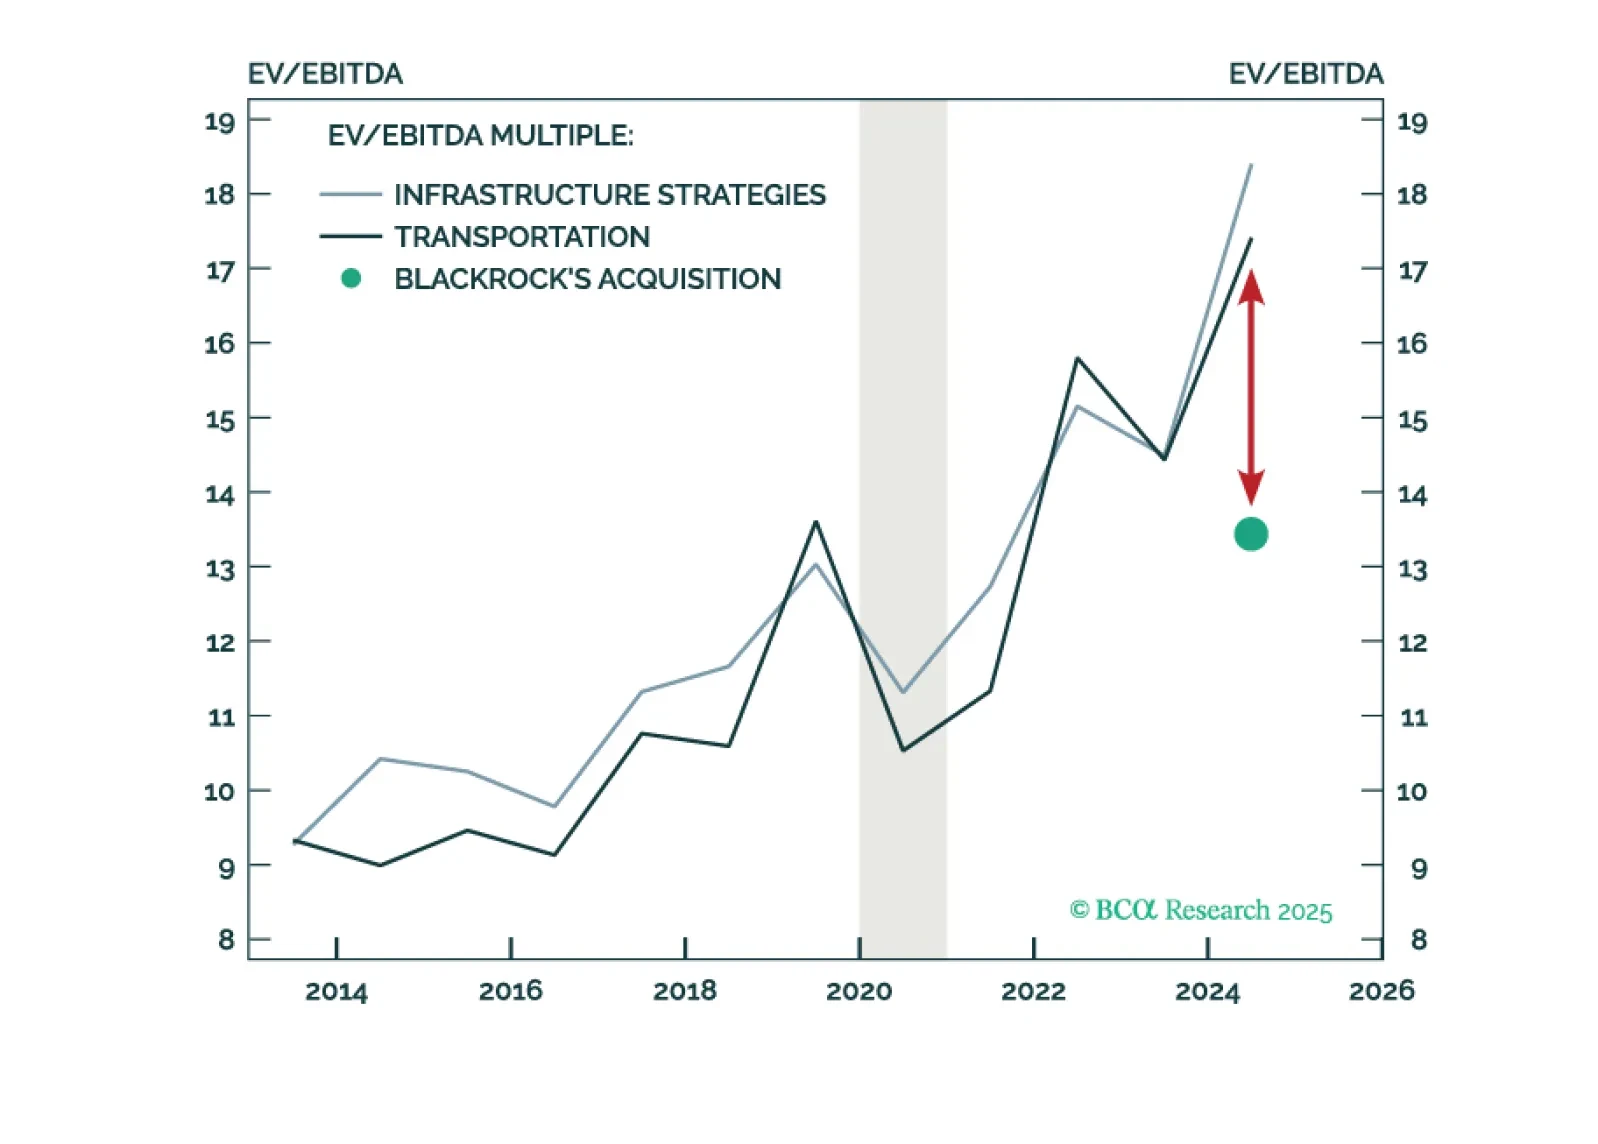
The ports that BlackRock acquired on both sides of the Panama Canal appear to be a bargain in terms of the entry valuation. But are the risks being appropriately compensated? In this prefatory report, we prepare investors for our upcoming Infrastructure reports, which will highlight geopolitical risk factors in this private asset class rarely encountered in others.
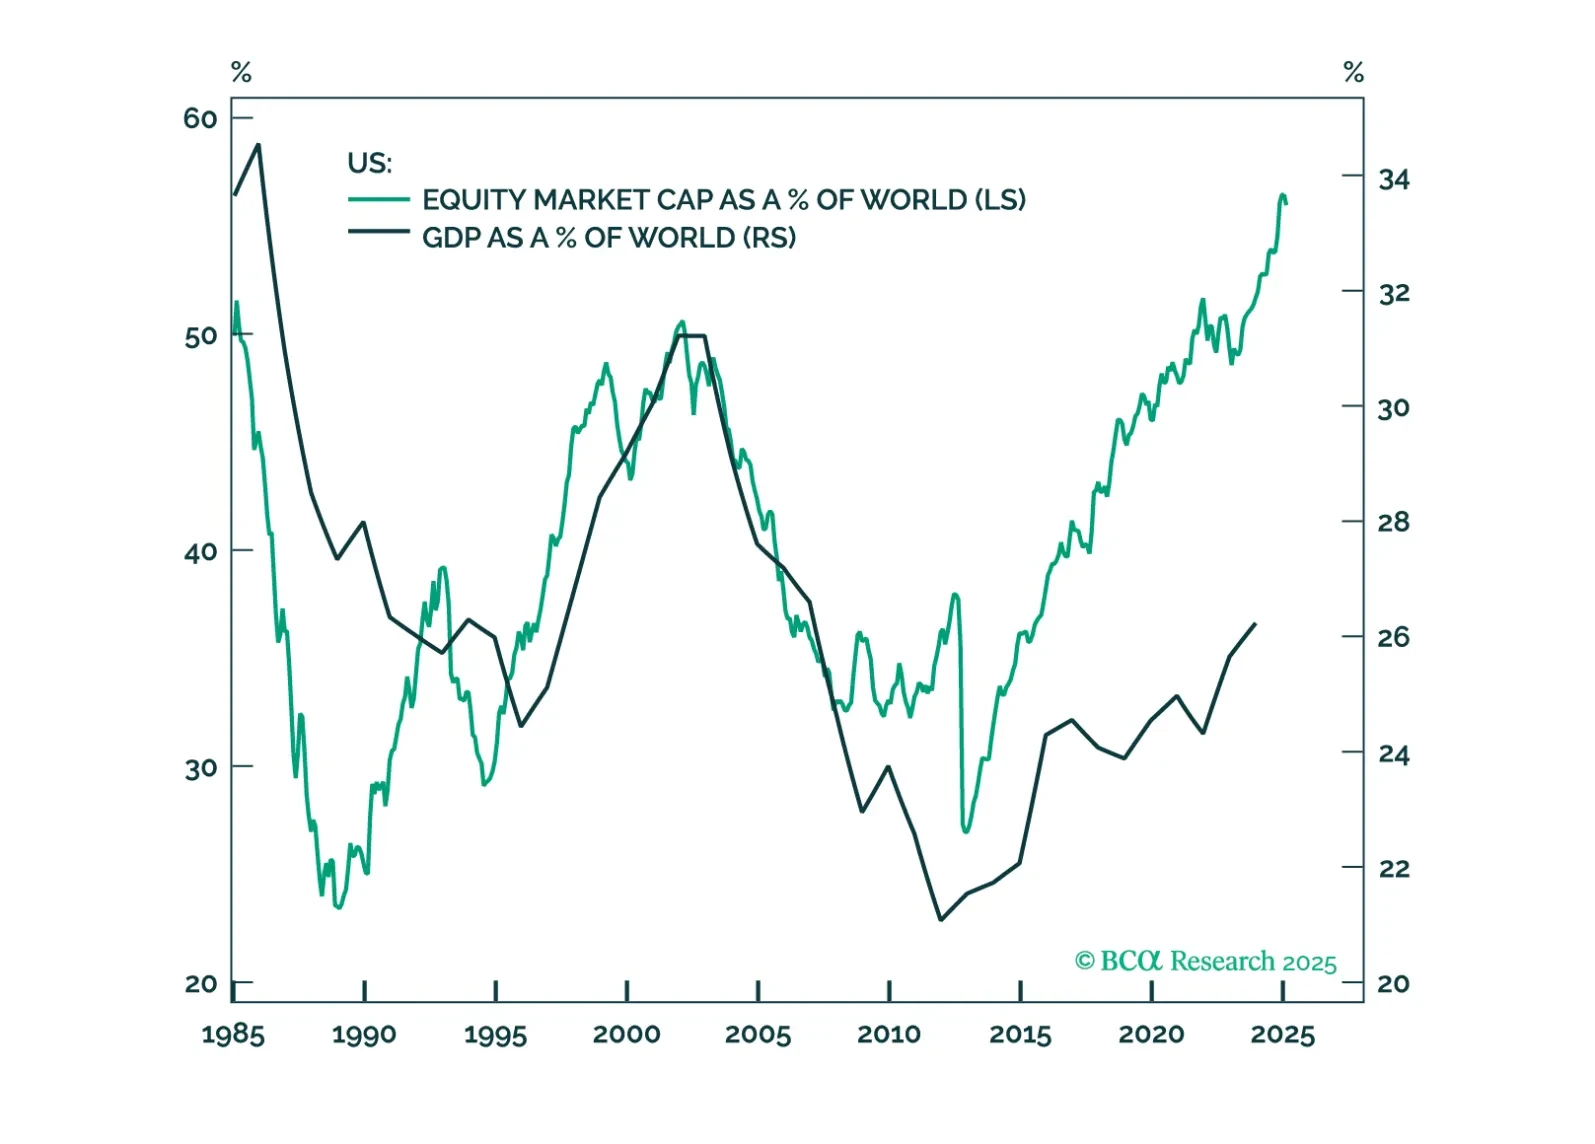
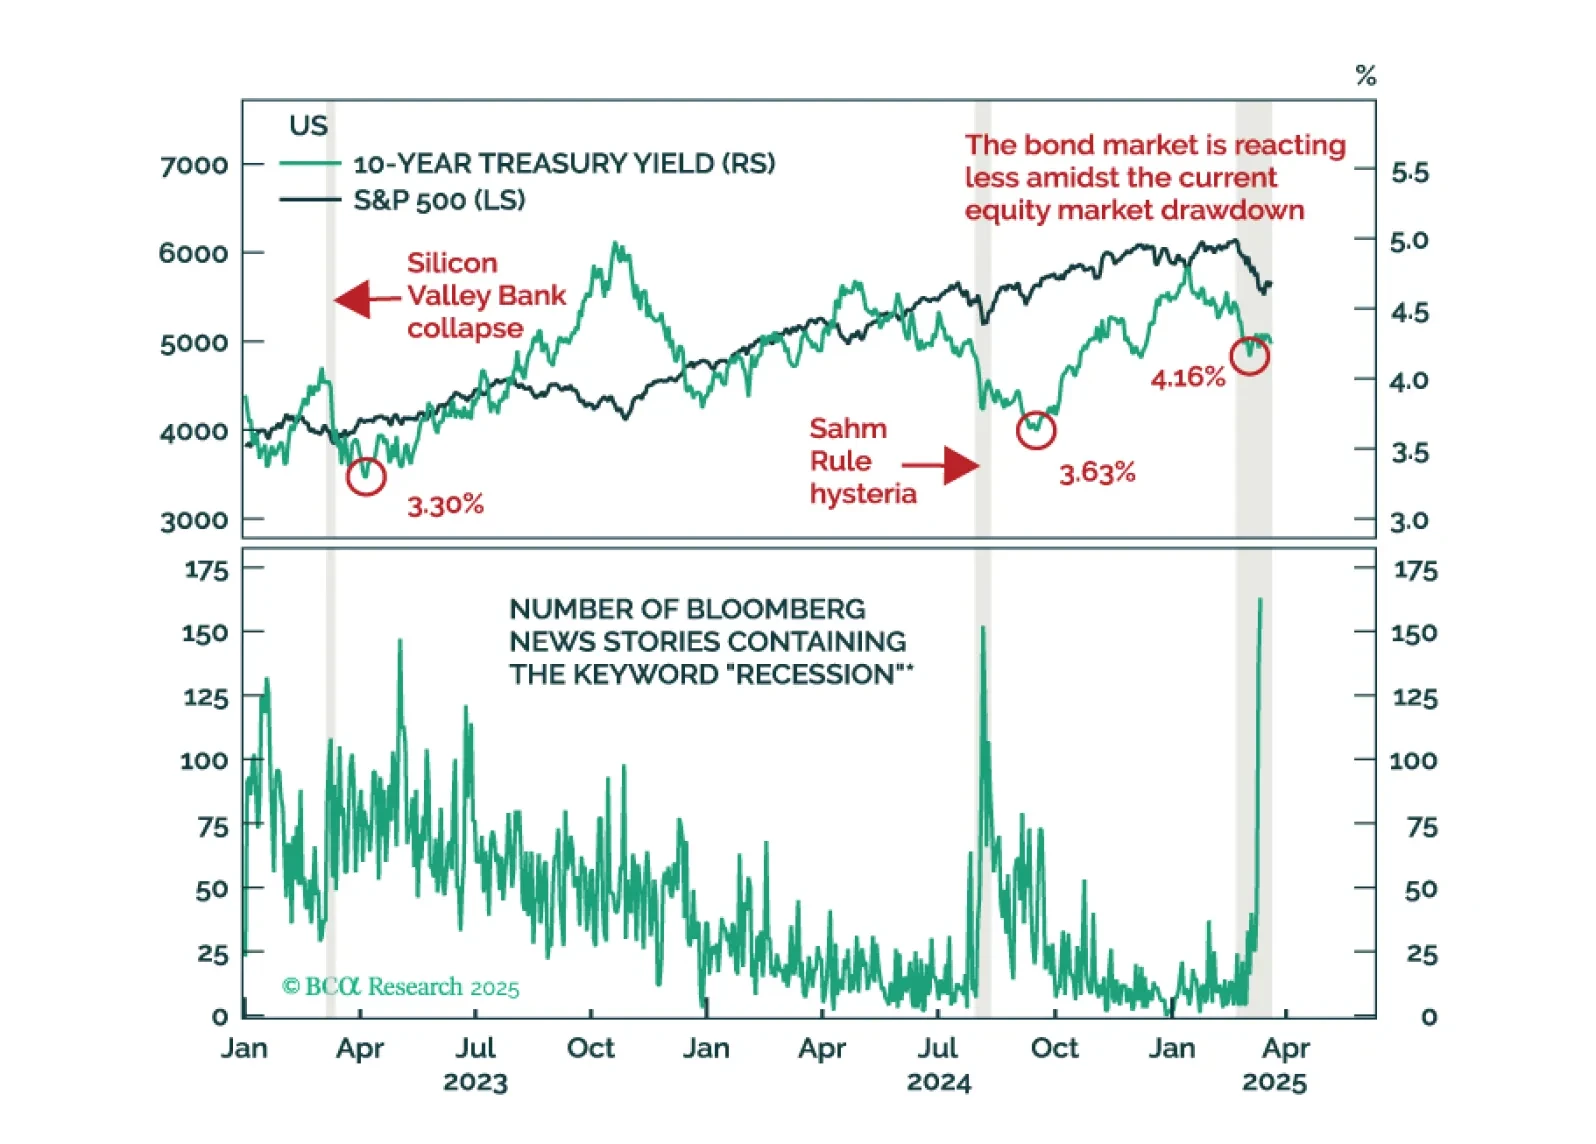
Stock market has continued to sell off as investors try to price President Trump’s trade policy, geopolitical volatility, global manufacturing slowdown, and the apparently cavalier attitude by the White House regarding the risk of a recession. At the same time, it is interesting that the USD and Big Tech have taken a beating – two assets that were supposed to be insulated from the risk of a global trade war. So, what is happening?
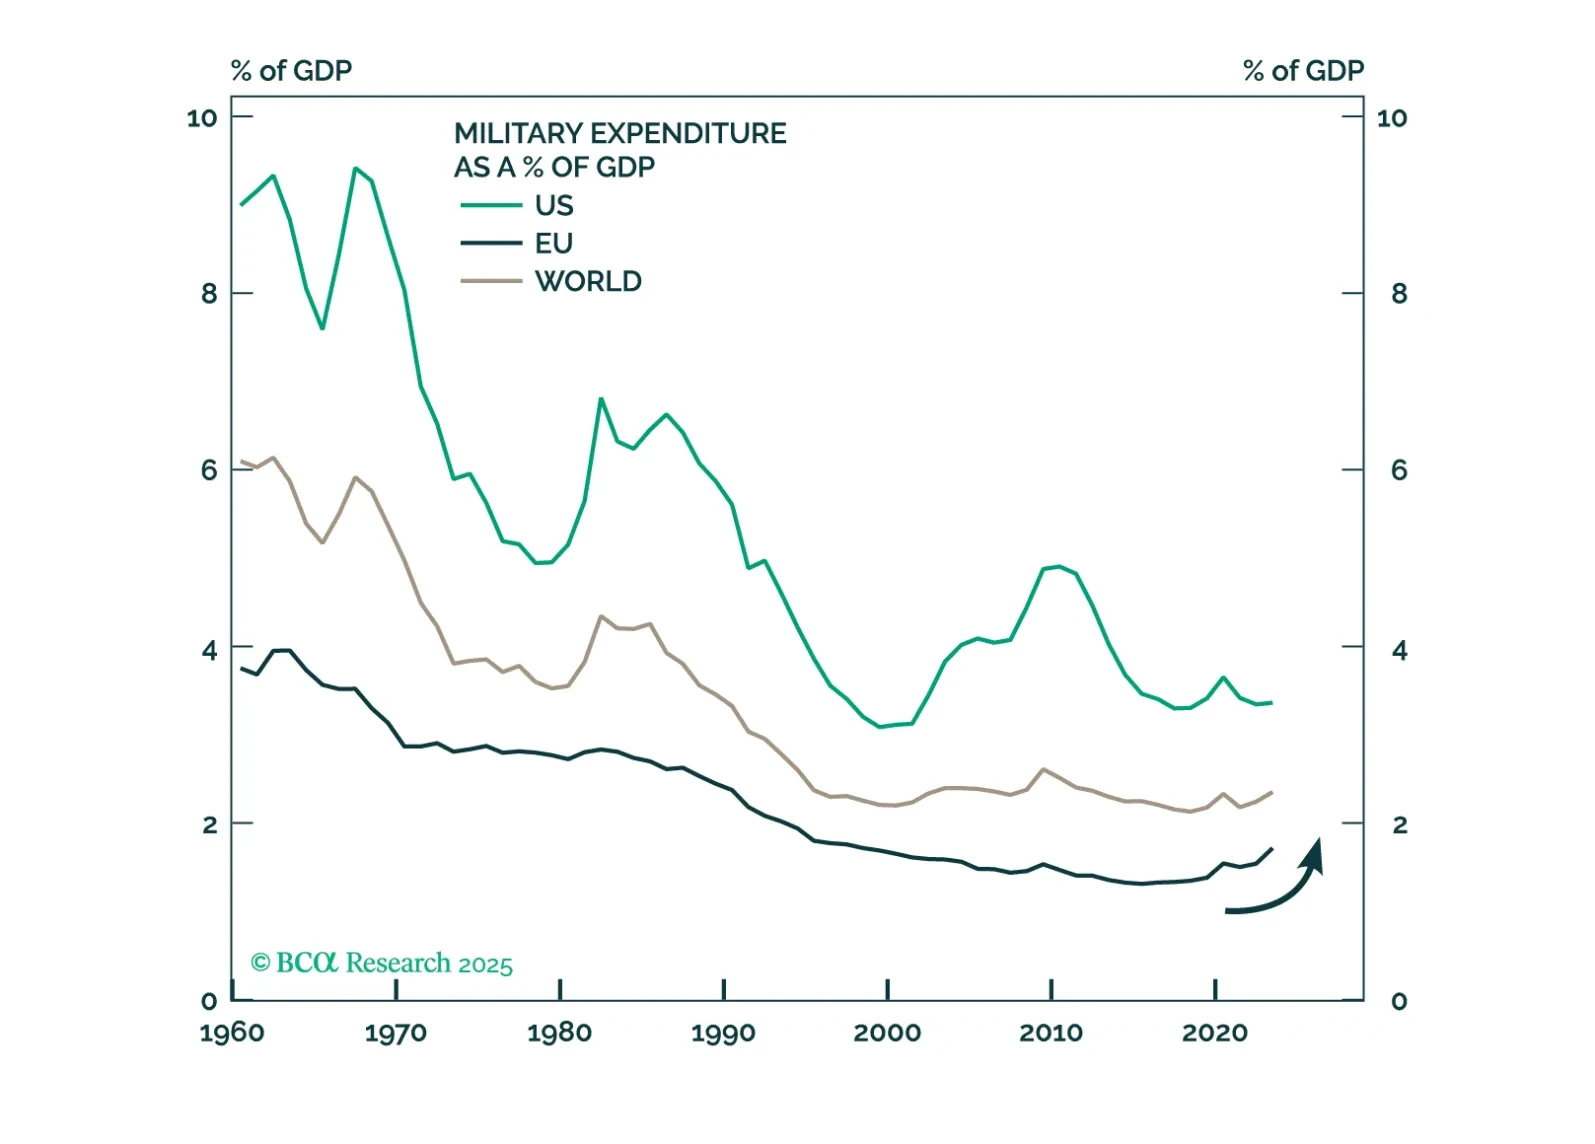
Fears of Europe’s decline due to Russian aggression and shifting US policy are overblown. President Trump’s tough stance on Ukraine is a strategic move to consolidate domestic support, not an abandonment of Europe, while Russia’s threat is exaggerated. As Europe responds with higher defense spending, stronger market integration, and greater political unity, investors should overweight European defense stocks and position for Europe’s broader market outperformance.