 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
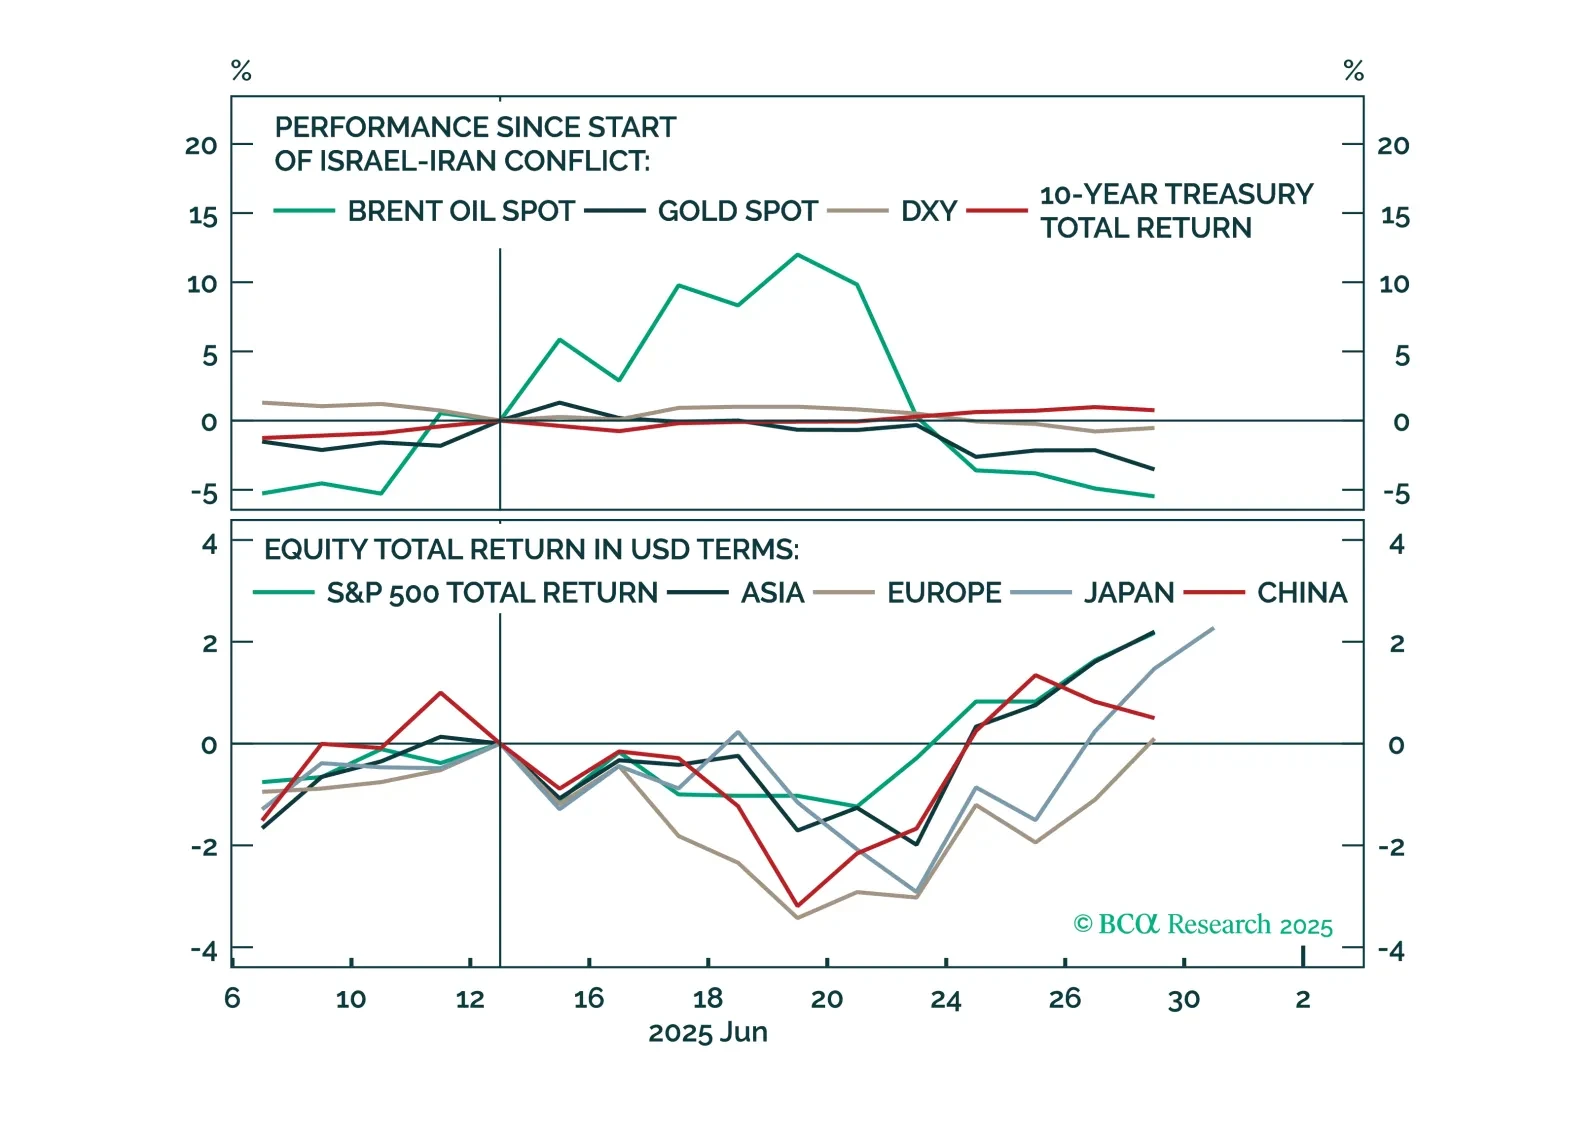
There is a thin line between geopolitical risk and Enlightenment, just ask Europe in the seventeenth century. The Middle East is exhibiting both. Investors are over-indexing on the negative – which has not impacted the investible universe – and ignoring the positives.
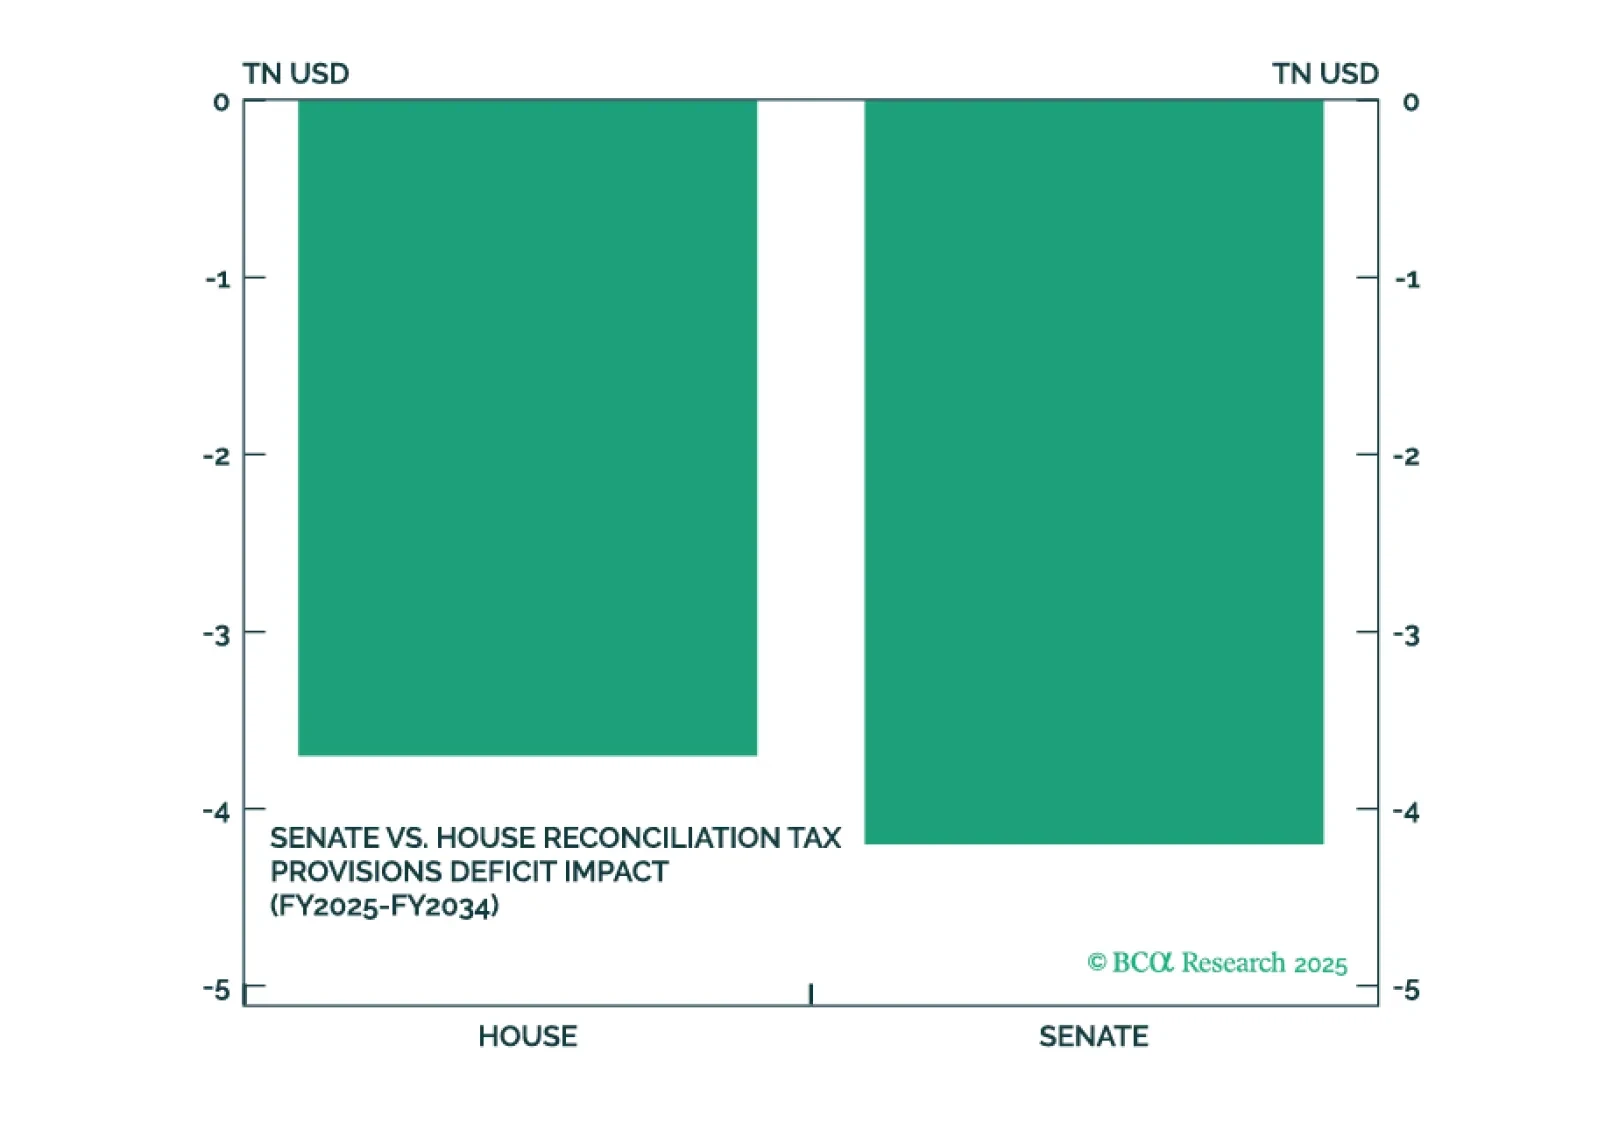
President Trump’s big beautiful bill will pass but faces near-term hurdles and will not tighten the government’s belt. It will combine with renewed tariff implementation to generate near-term risk for both the bond and stock market. The Iran crisis fizzled, saving Trump from a major oil shock that could have derailed his second term.
Since the start of Israel’s military operations against Iran on June 12, we warned clients that there would be an epic opportunity to fade geopolitical risk premium by shorting oil. We did it here, here, and again here. Over the weekend, however, we lost our cool and suggested that there could be more risk premium to fade as Iran and the US danced the dance of re-retaliation following President Trump’s decision to attack Iran’s nuclear sites directly.
President Trump has announced on social media that the US has conducted air strikes against three Iranian nuclear sites, including the hardened (and underground) Fordow that Israel has been unable to penetrate.
Since our last missive on June 15, three trading days have passed. The S&P 500 is up 0.2%, the US 10-year Treasuries yield has declined by 3 basis points, Brent crude is up 2.7%, gold is down by 2%, the JPY is down 0.7%, and DXY is up 0.7%. Our message prior to the start of these three trading days was that there was some more upside to oil prices in the very near term. However, that this upside would not be that impressive. Second, that the S&P 500 should not be shorted. And that the USD and US Treasuries would not be a great hedge, but that gold and JPY would be.
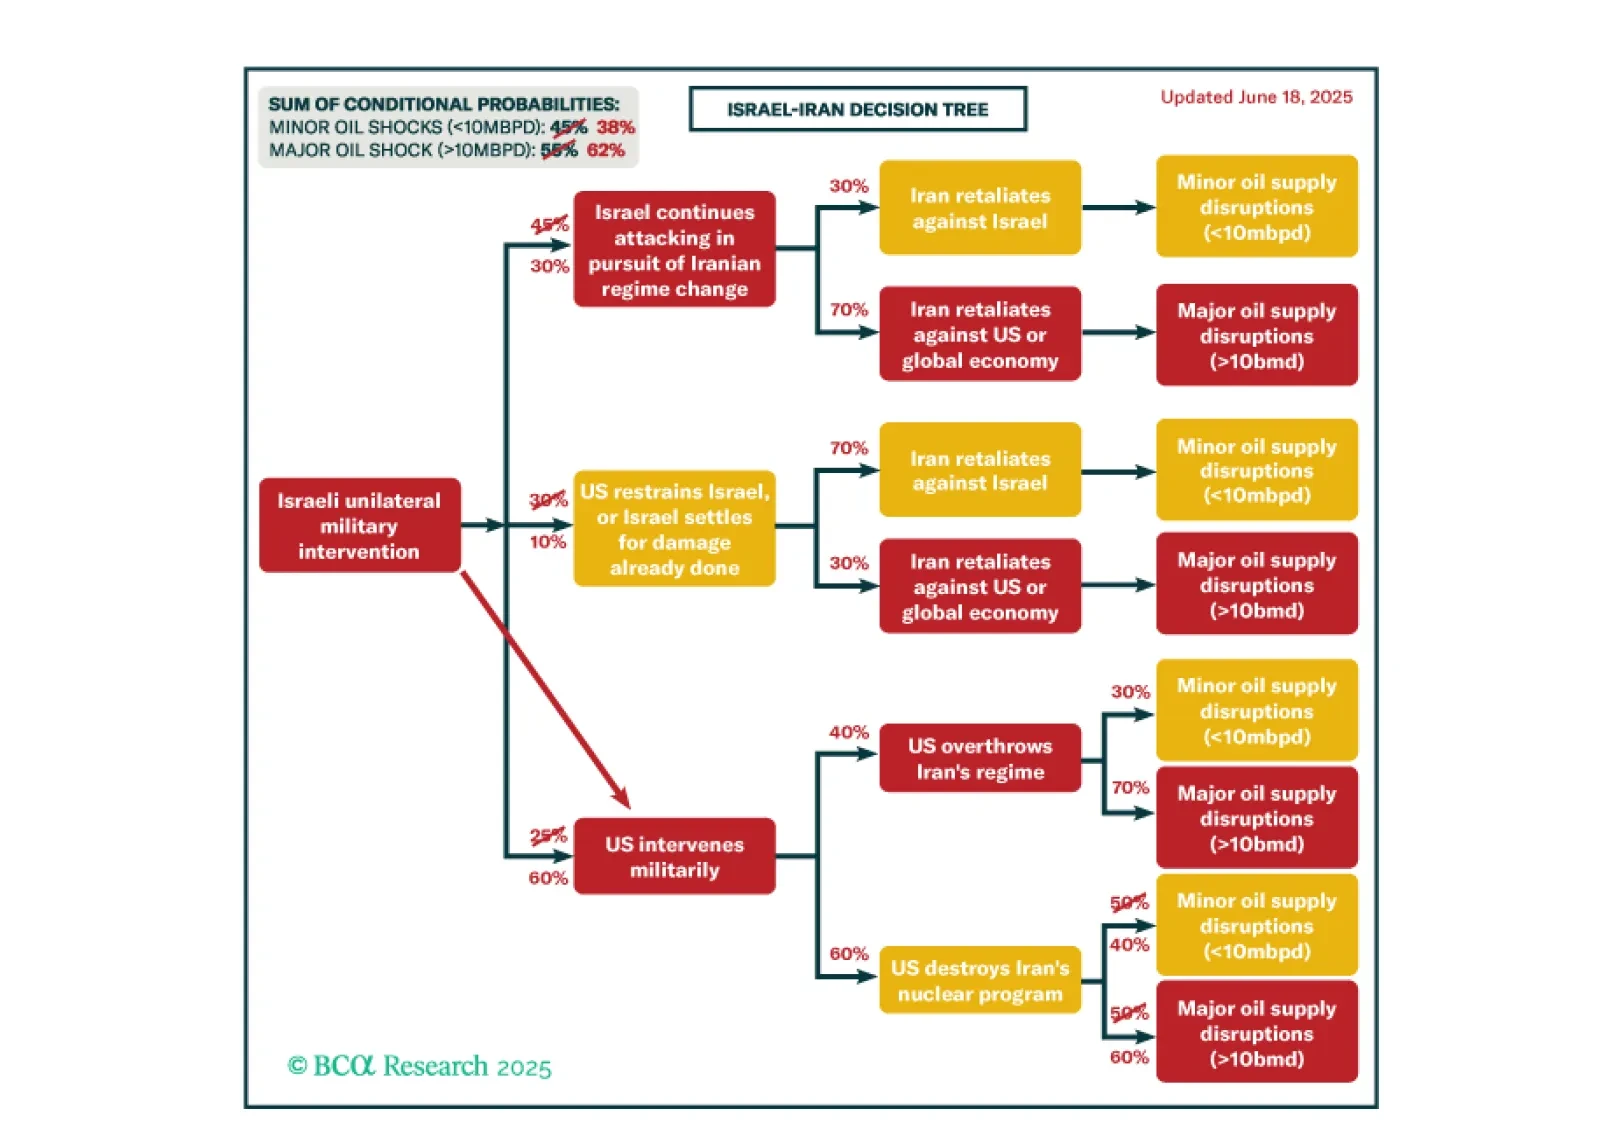
Even if Iran tries to revive talks, the US has an irresistible opportunity to dismantle its nuclear program. Tactically, investors should favor Treasuries over the S&P, defensive sectors over cyclicals, energy stocks over cyclicals, and US stocks over European stocks in the near term.
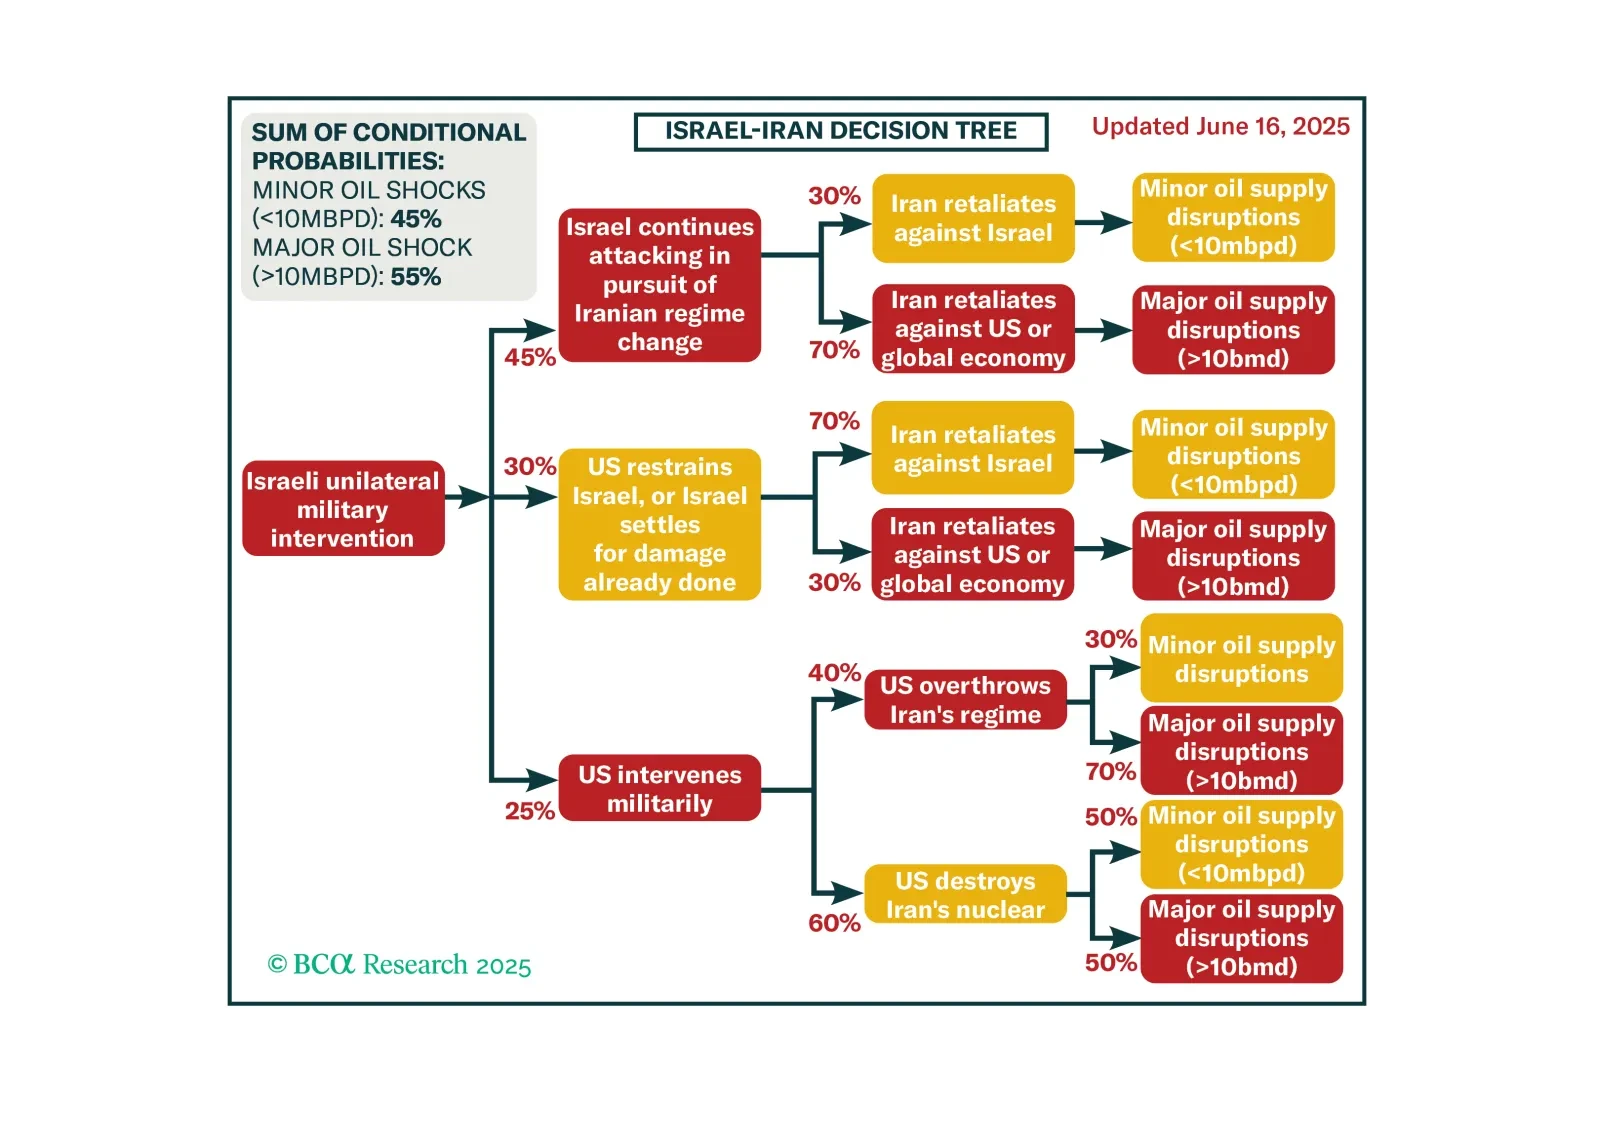
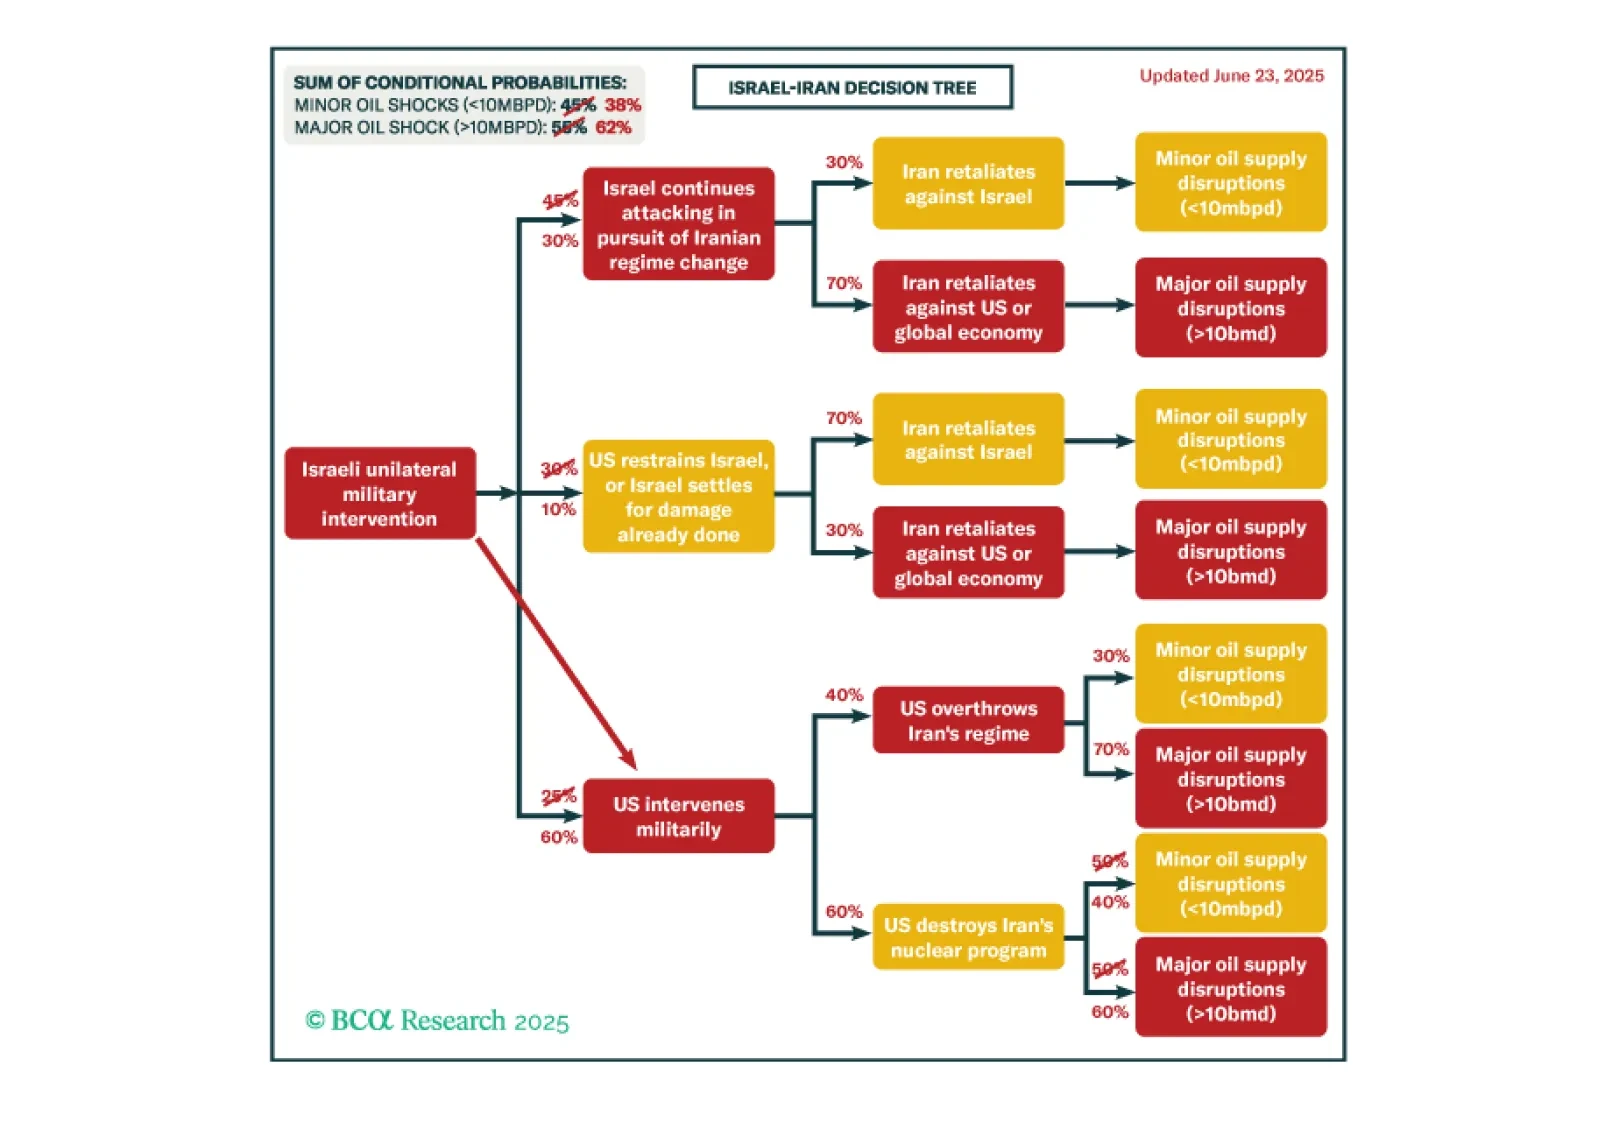
Israel’s attacks on Iran will continue until Iran is forced to strike regional oil supply to get the US to restrain Israel. That may not work. Investors should prepare for a broader economic impact of the conflict.
It has been three days since Israel started its air campaign against Iran. We now have greater visibility into Israel’s targeting, as well as Iran’s retaliation. Israel’s air force has struck almost every single Iranian nuclear program facility, government buildings, research centers, and – most importantly – energy facilities. Most of these targets are expected, but the attacks against Iran’s energy facilities are concerning as they suggest that Tehran may have casus belli to strike back at the energy facilities strewn around the Persian Gulf.
The conflict between Iran and Israel continues. There will be ample time to update our views on the specifics of the kinetic action. Thus far, Iranian retaliation has been confined to Israel, which according to our hierarchy of potential responses, is the least market relevant.