 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
President Trump keeps walking back his tariffs, aligning with our Seven Steps of Maximum Pressure. Investors should expect a lot of back and forth over the next few weeks, including the dreaded Step 5 (“Leave the Bride at the Altar”). Already, Commerce Secretary Howard Lutnick has suggested that the tariff exemptions for electronics – which surged global risk assets today – would not last long. We hesitate to just declare the “all clear” and go outright long but are shifting our posture on global risk assets to neutral.
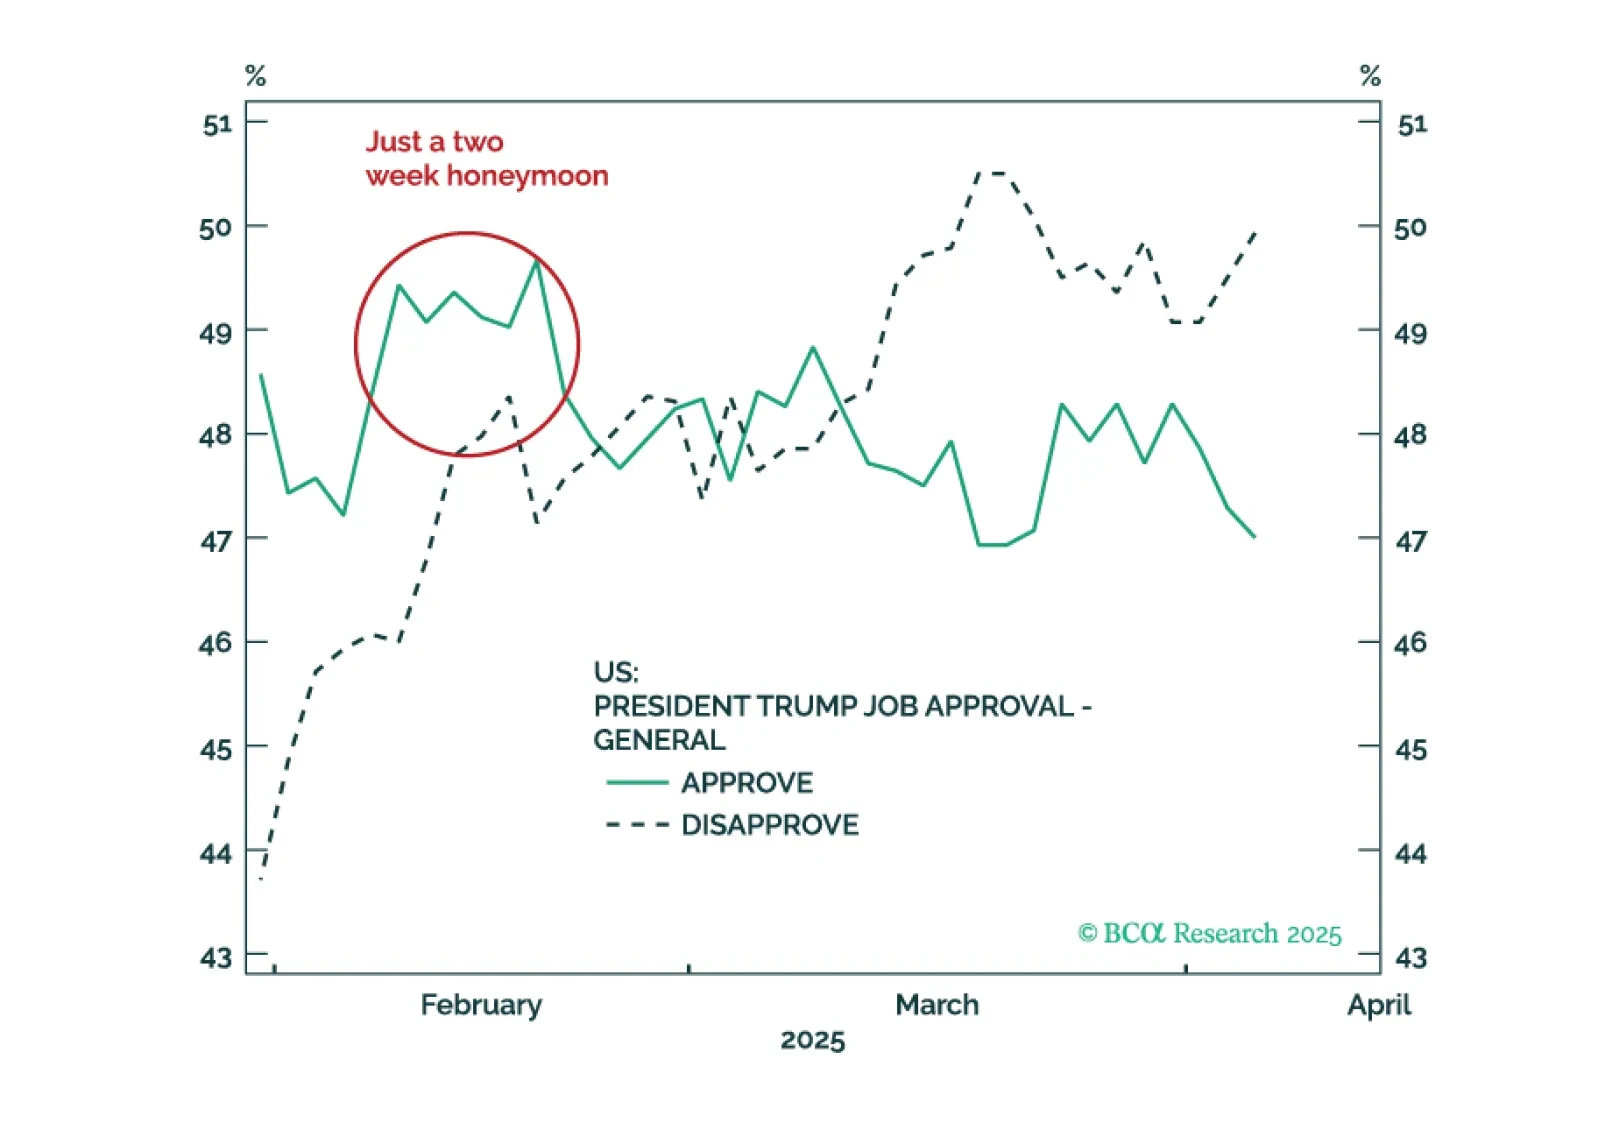
While the market welcomed the pause in Liberation Day tariffs, we believe investors are overly optimistic about the relief from this Trump-driven uncertainty. Even with the pause, current tariff levels remain higher than they were in January. Elevated tariff levels are likely to be inflationary, which could explain the recent spikes in US Treasury yields. Currently, Congress does not have a veto-proof majority to rein in President Trump’s tariff policies, meaning the trade war with China will persist.
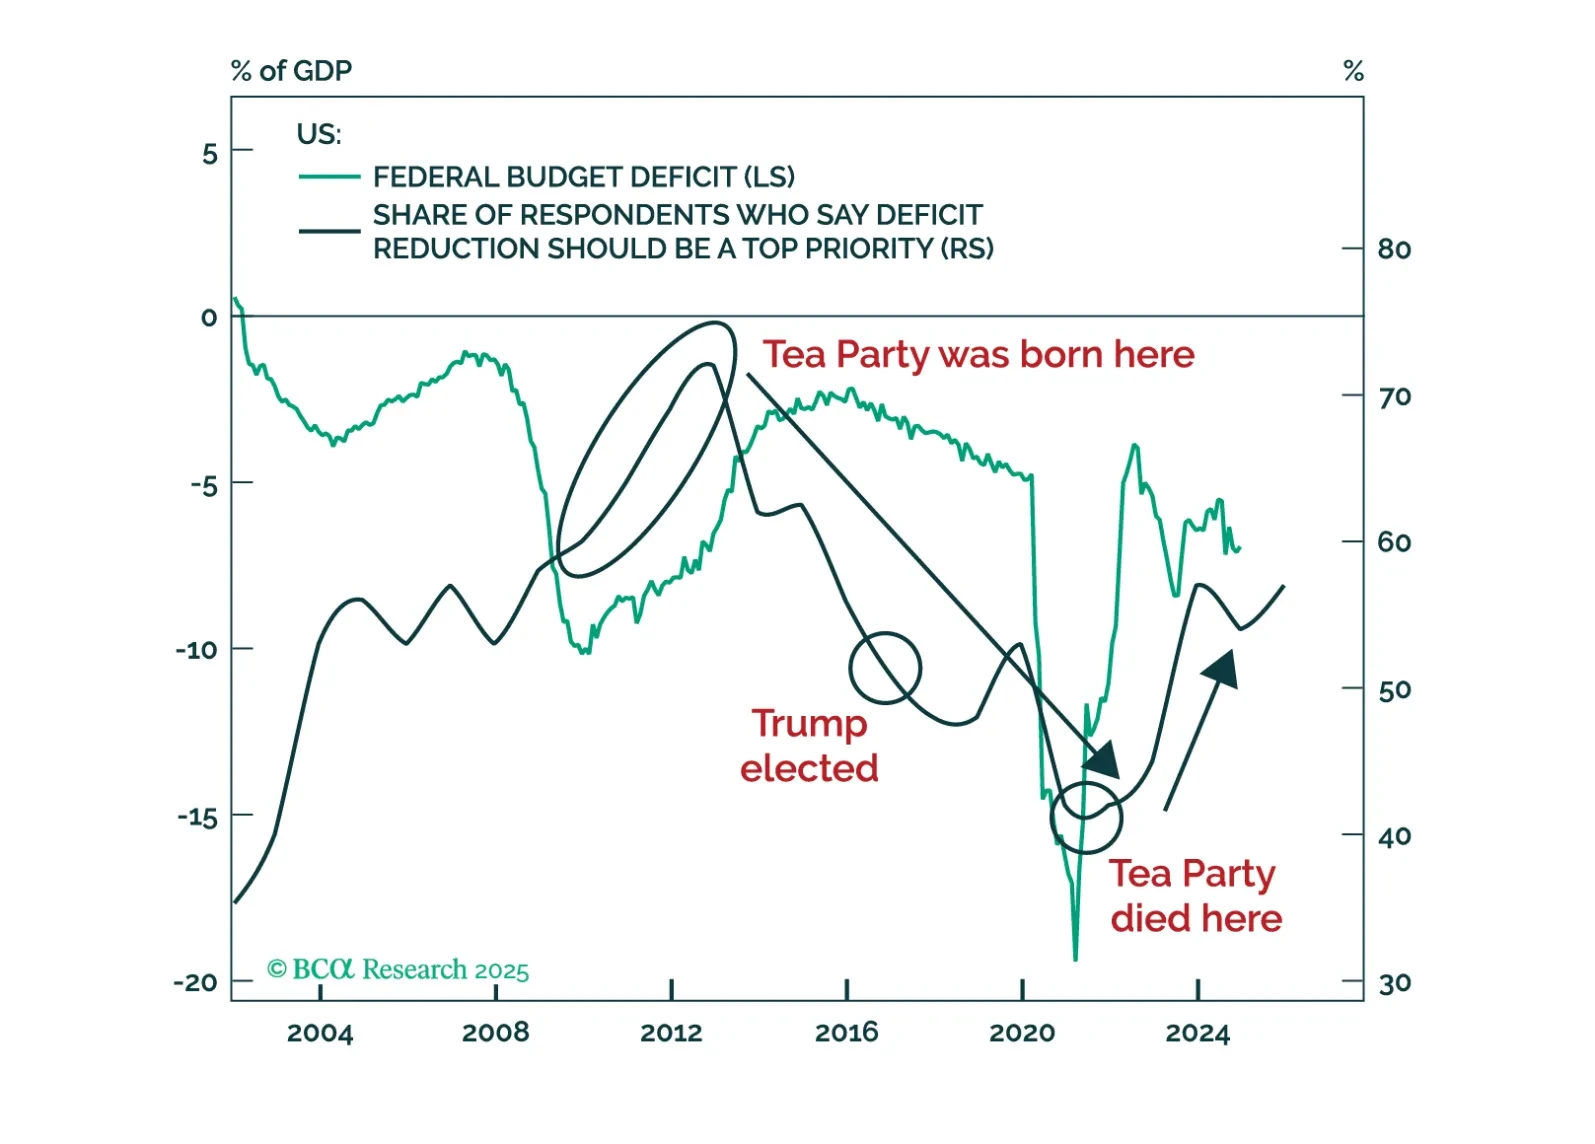
The world is focused entirely on the trade war between the US and… well everyone. This is fair given that there has been no greater market catalyst than Liberation Day since the pandemic. However, we continue to stress that the BIG PICTURE for macro investors is the rotation out of the US. A rotation that started well before April 2, despite the understanding of the investment community that some tariff action would be afoot.
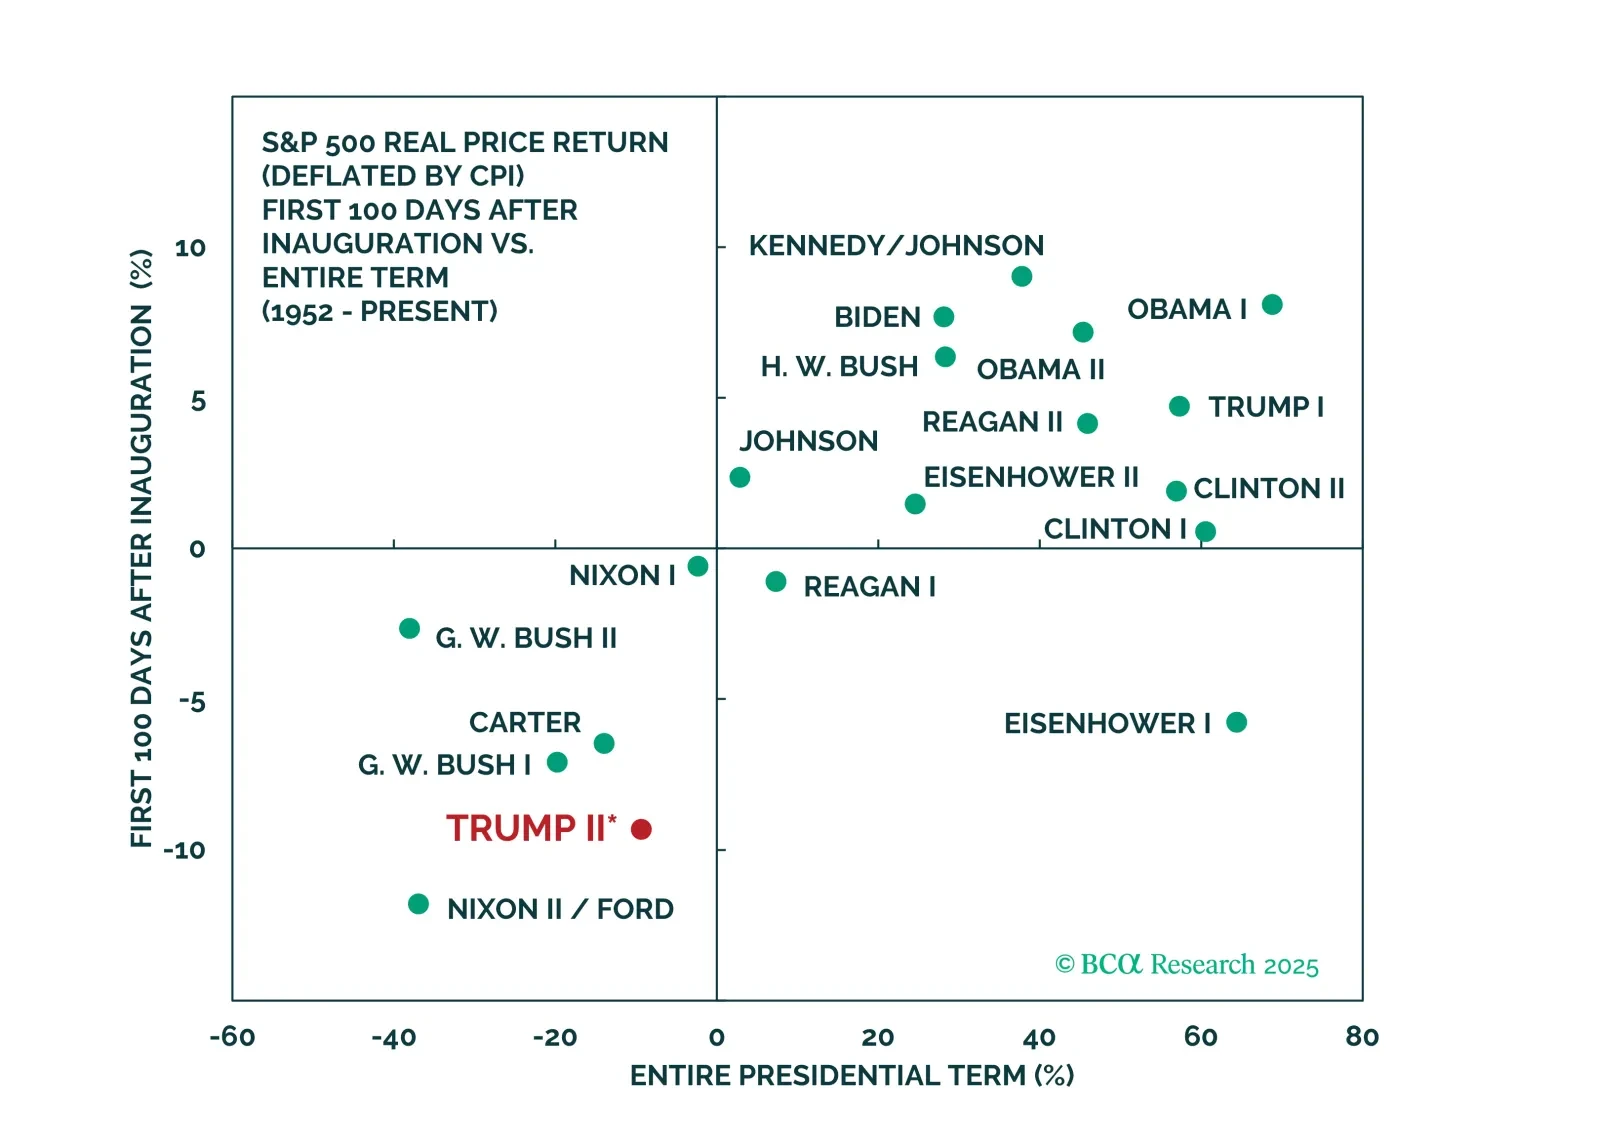
President Trump imposed tariffs on the world in his first 100 days, as we expected. Tariffs may have catalyzed a recession in the US, given the weakness in consumer sentiment and demand. Trump will soon backpedal and grant exemptions to countries that are negotiating, which he will showcase as proofs of his successful trade policy. While he may backpedal on his tariffs on other countries, China is not likely to receive the same treatment due to the US-China strategic competition.
Did you know that the high-quality Japanese zippers you use every day are macro relevant? That is because YKK dared to sue – and win – against President Richard Nixon 10% across-the-board tariffs.
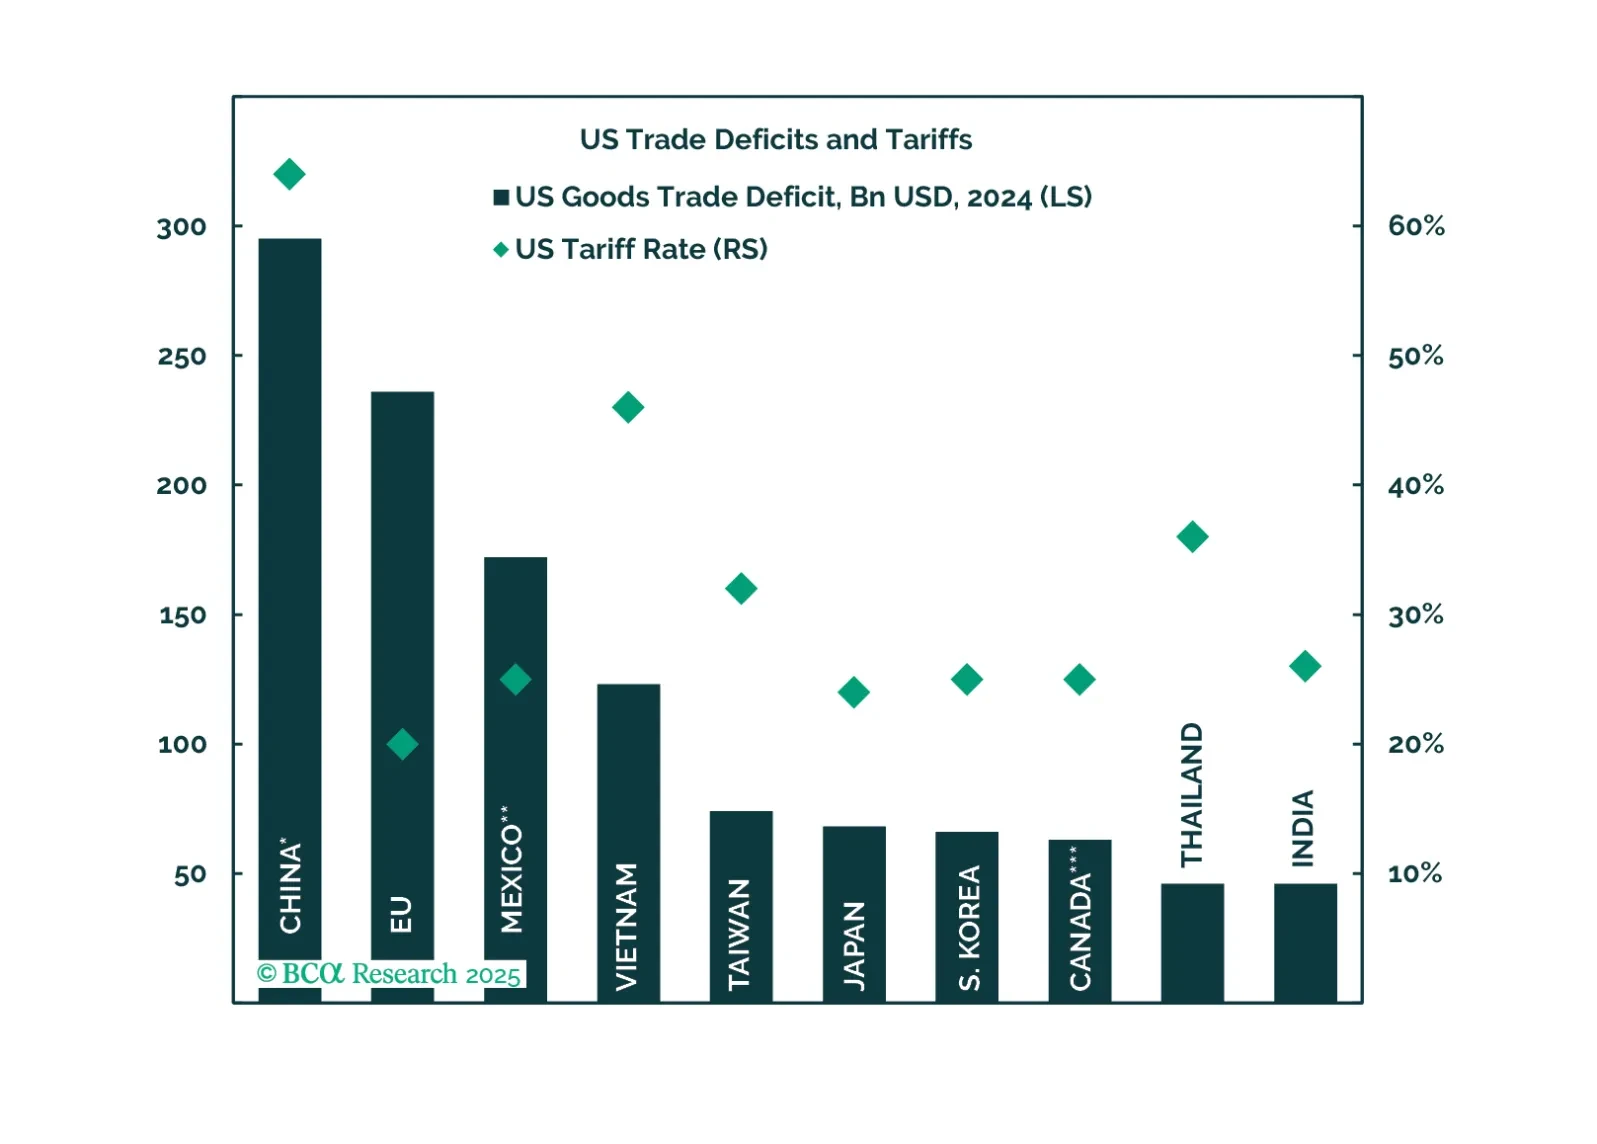
Trump's Tariff D-Day brings a negative surprise to financial markets already anxious over a declining US cyclical economy. Investors should sell risky assets, increase safe havens, and overweight US assets in the near term.
The White House has revealed the plans for Liberation Day. They broadly include: Reciprocal tariffs, on a case-by-case basis. A message from President Trump to other countries to lower their own tariffs and buy US goods. Our take is that April 2 will be remembered – 6-12 months from now – as the peak in “de-globalization” thesis. Markets react to the delta of bad news, not bad news in the absolute.