 CoreMacro
Find out more
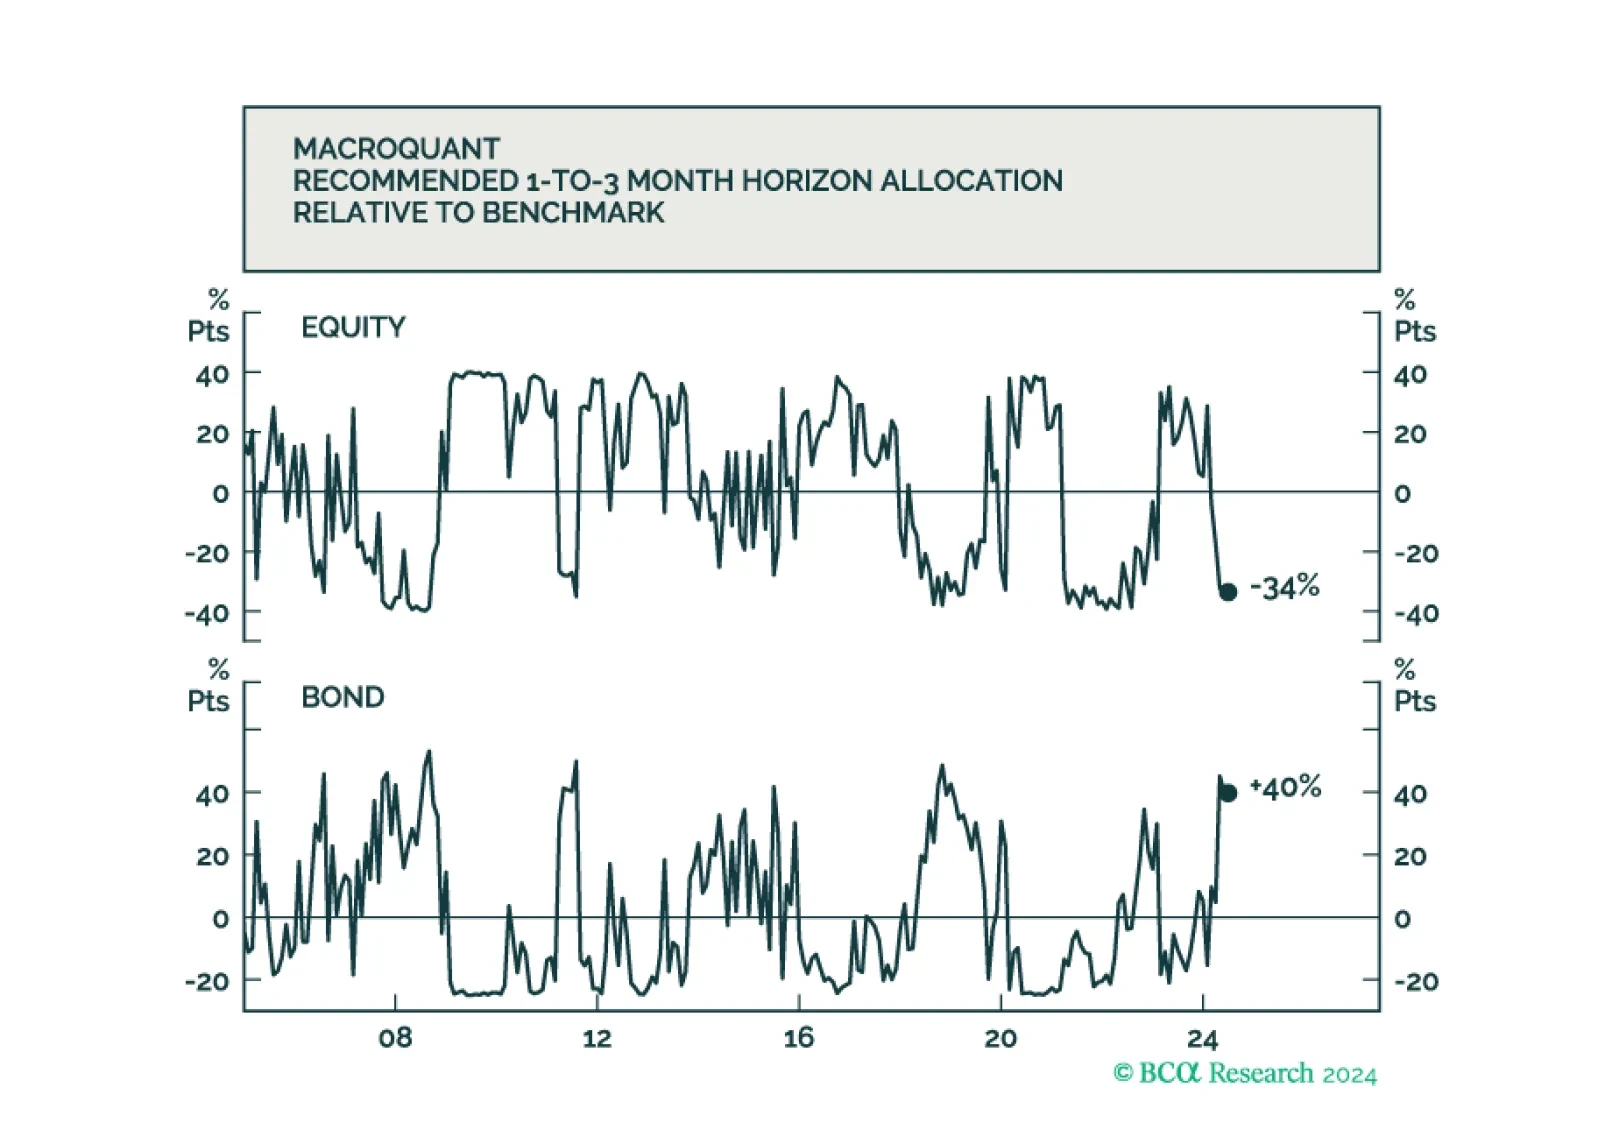
The Global Investment Strategy team downgraded global equities to underweight in late June. The latest reading from our MacroQuant model is consistent with this decision.
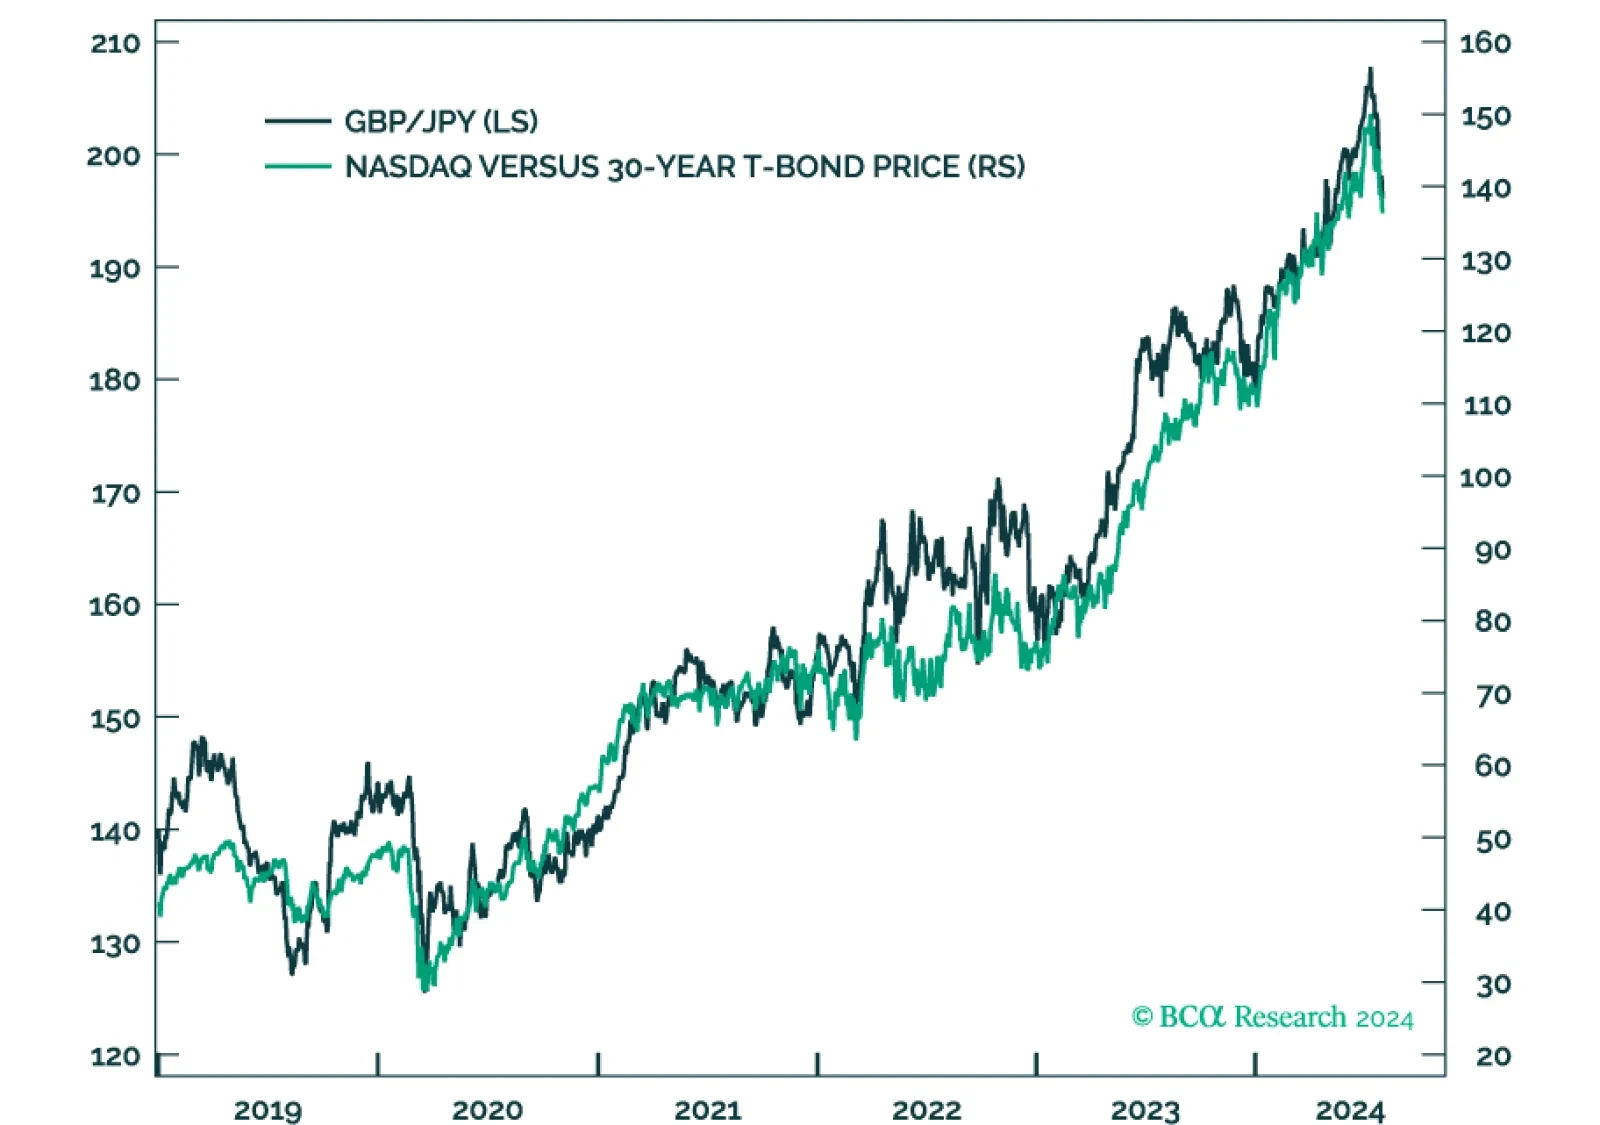
We should fear a recession in the frothy parts of the US stock market much more than a recession in US GDP. And as frothy US tech stocks sell off, an excellent hedge is to go long JPY/GBP or JPY/EUR.
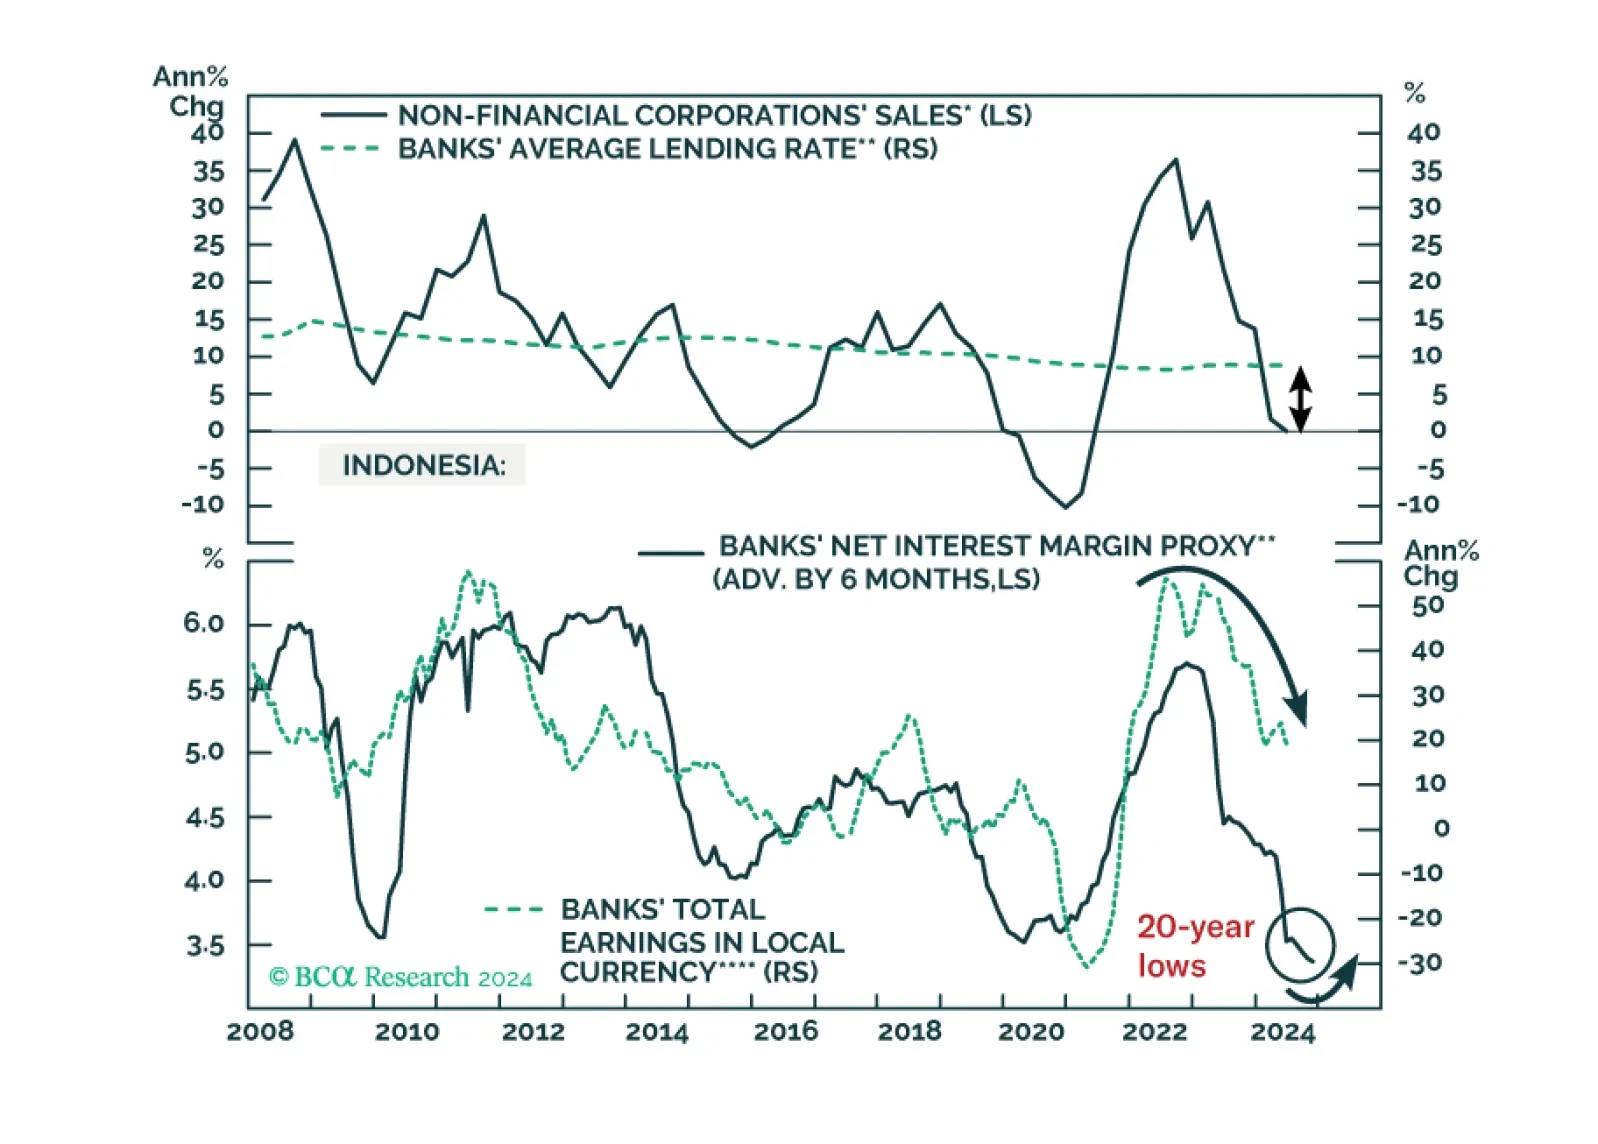
A major slowdown in nominal growth was behind Indonesia’s recent stock underperformance. Dedicated EM equity portfolios should upgrade Indonesian stocks from underweight to neutral. We also recommend a new relative trade: go long Indonesian banks / short EM banks.
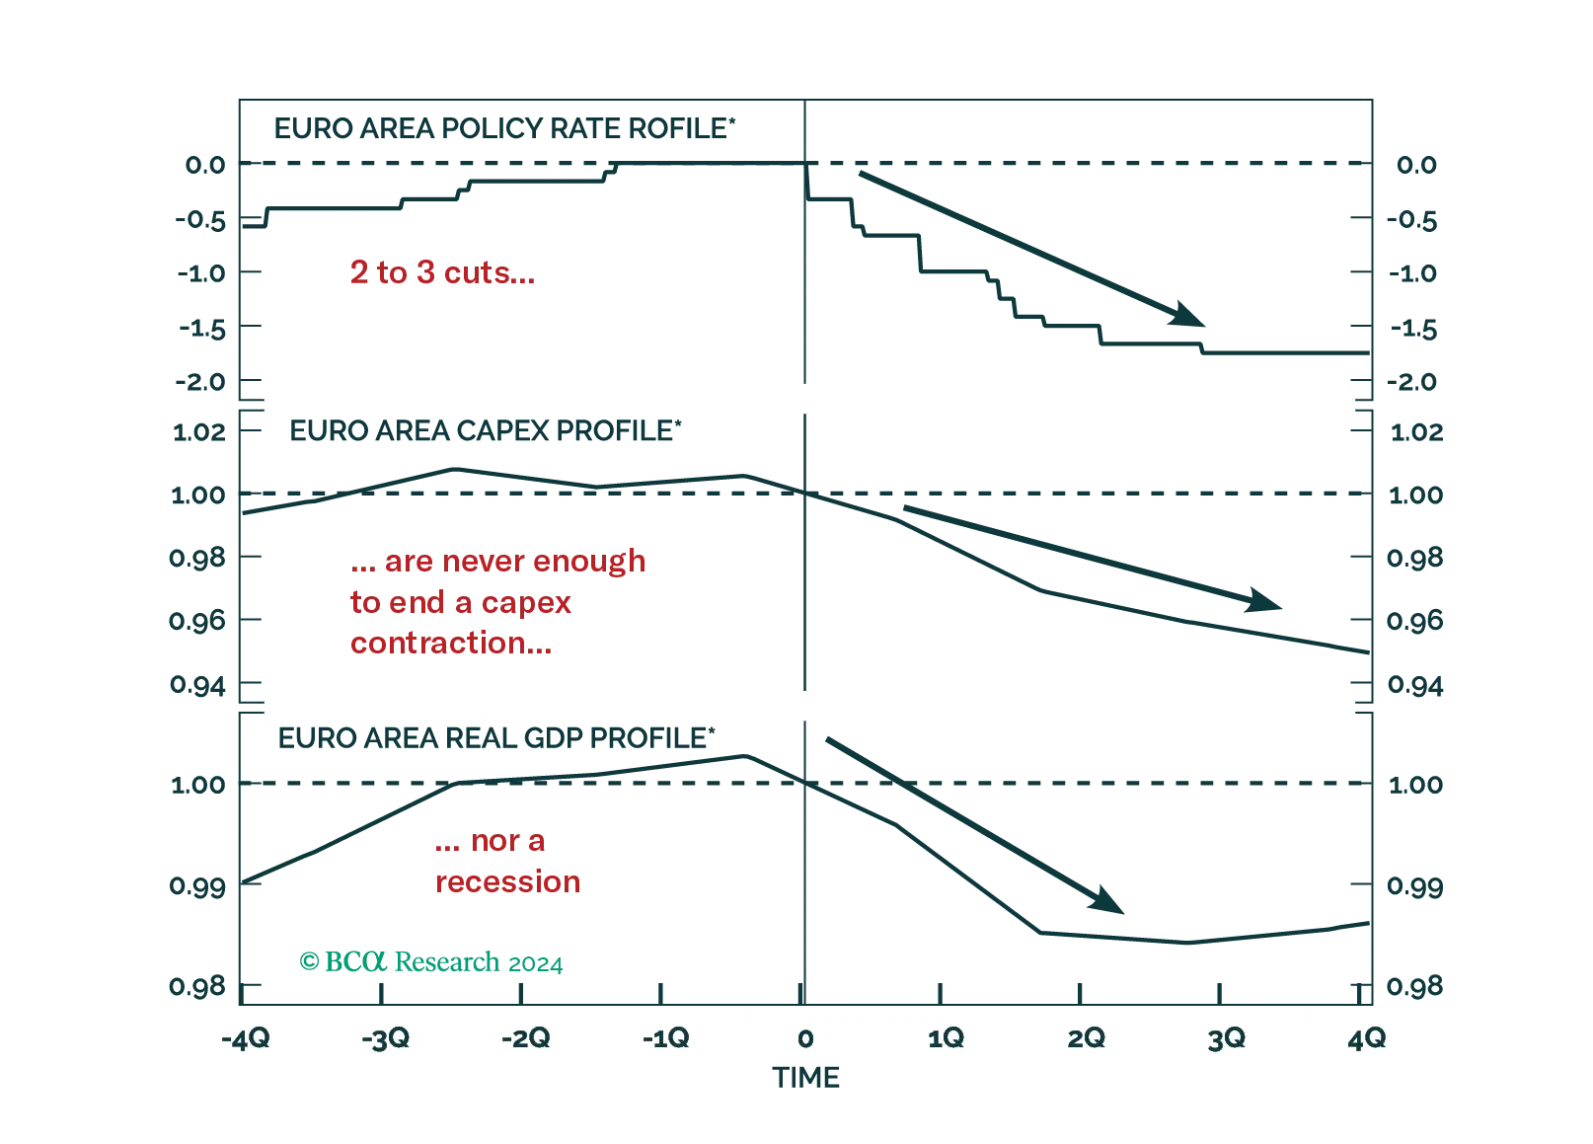
Investors hope that the ECB rate cuts priced into the curve will be sufficient to achieve a soft landing in Europe. History argues against this view, but will this time be different?
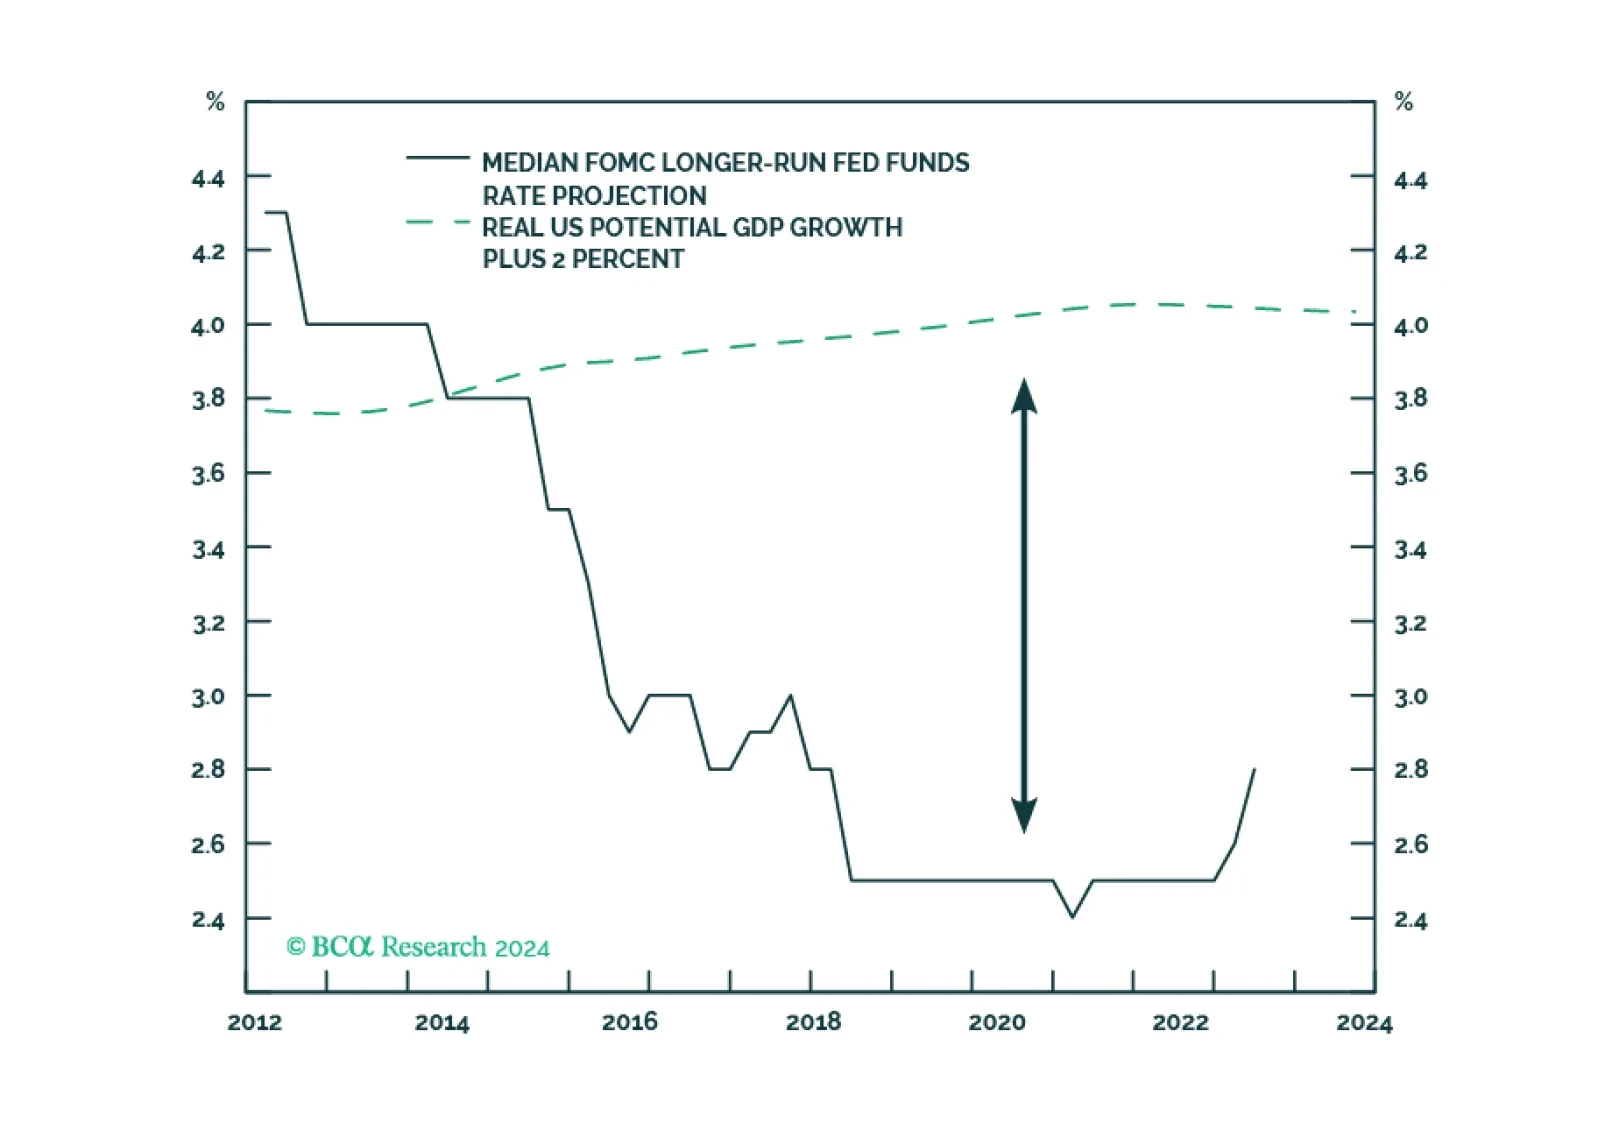

This report provides our framework for interpreting the messages from last week’s Third Plenum, and the potential implications for the economy and investors.
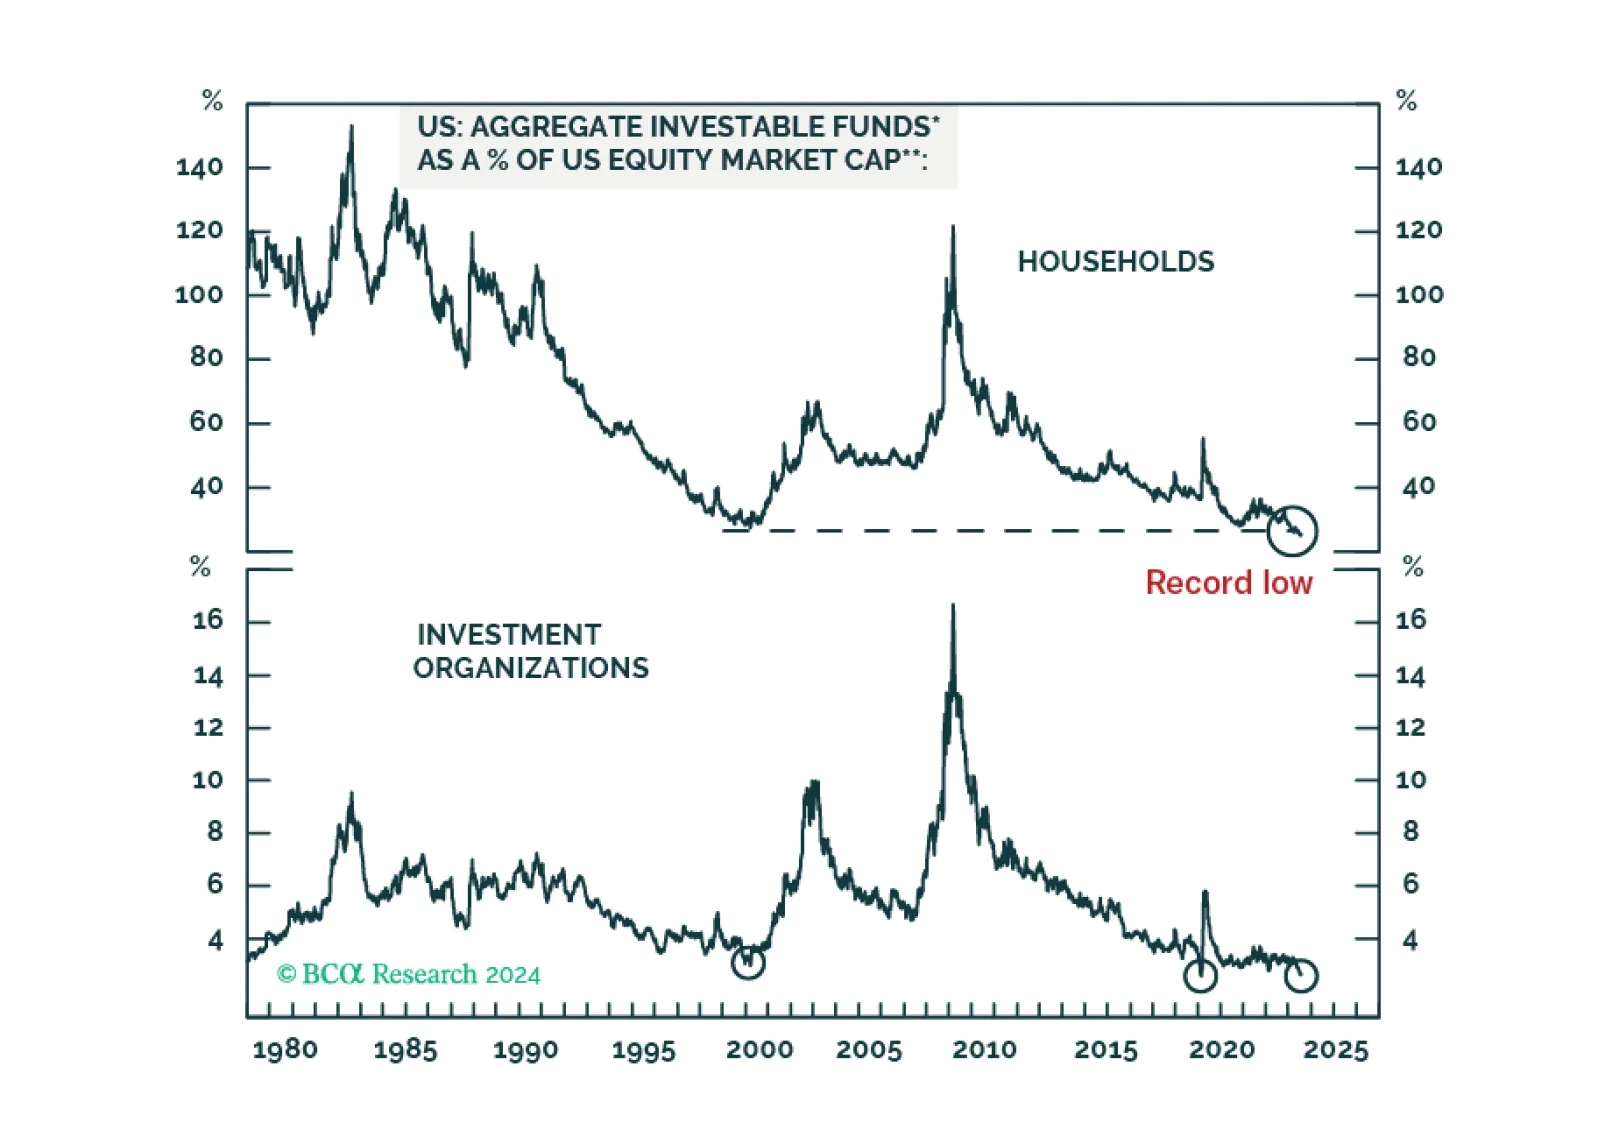
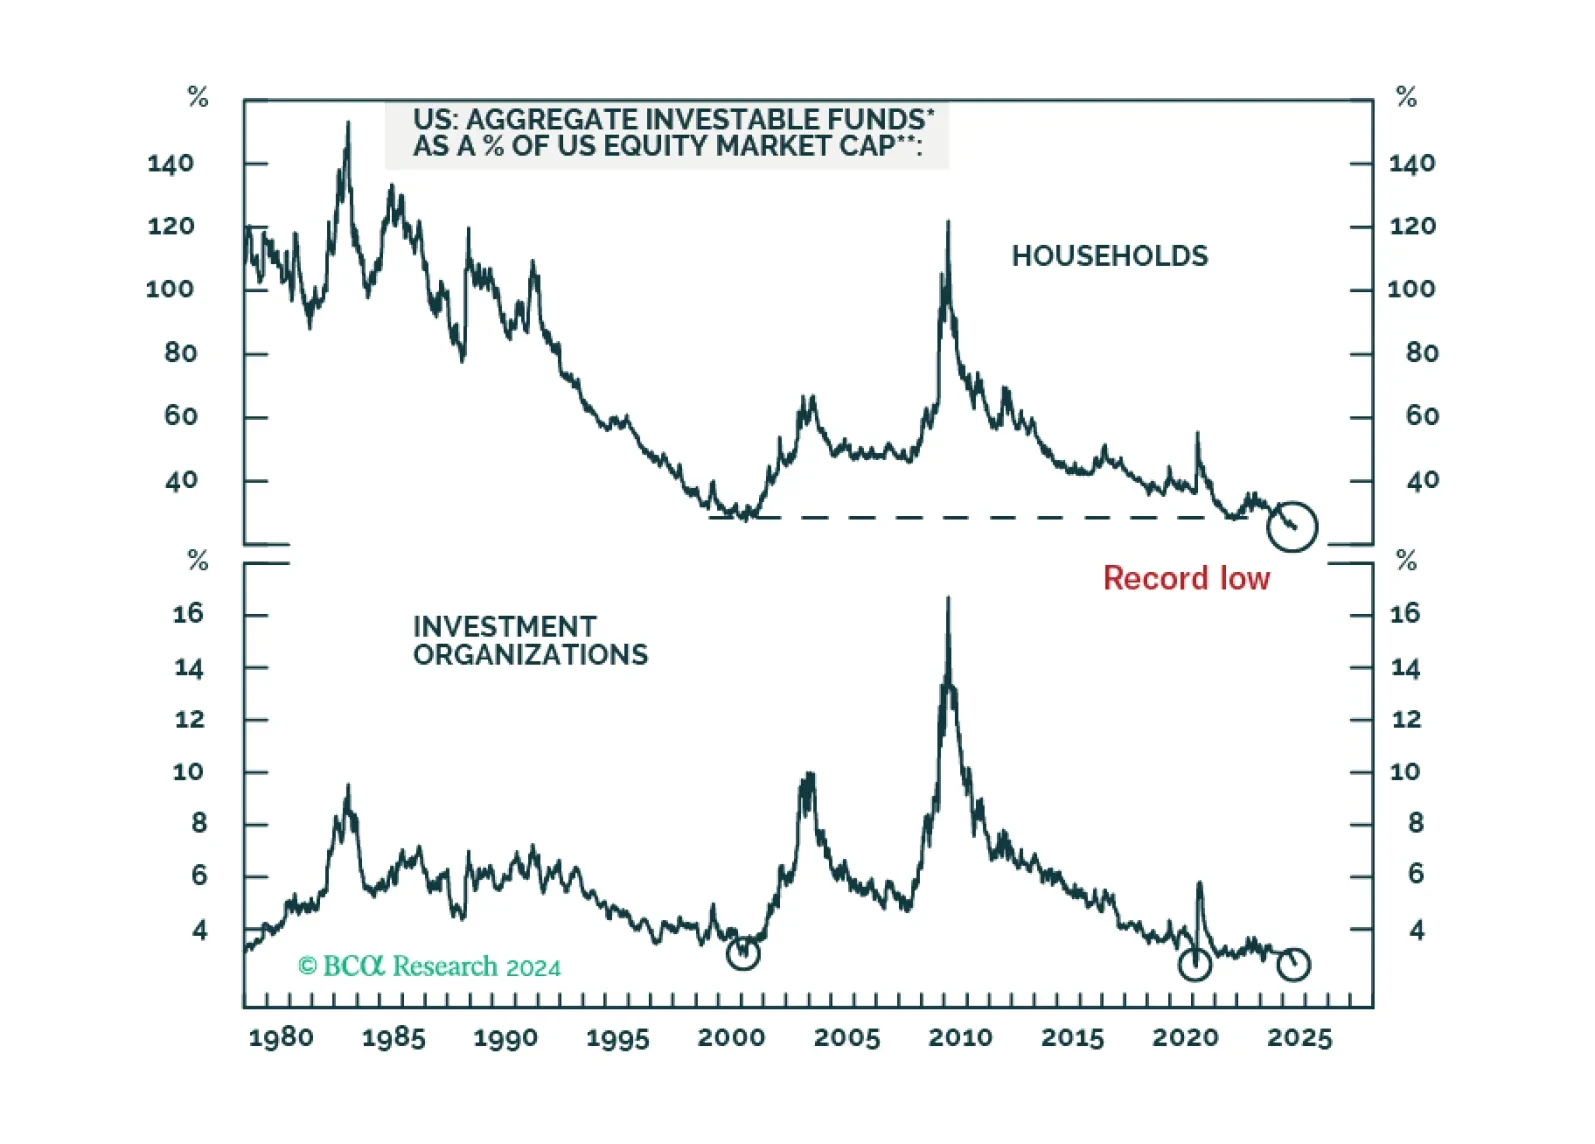
“Cash on the sidelines” as a share of the US equity market cap has declined to a record low. This is true for investable funds of both households and investment firms. Hence, there is little firepower left to sustain the equity rally.
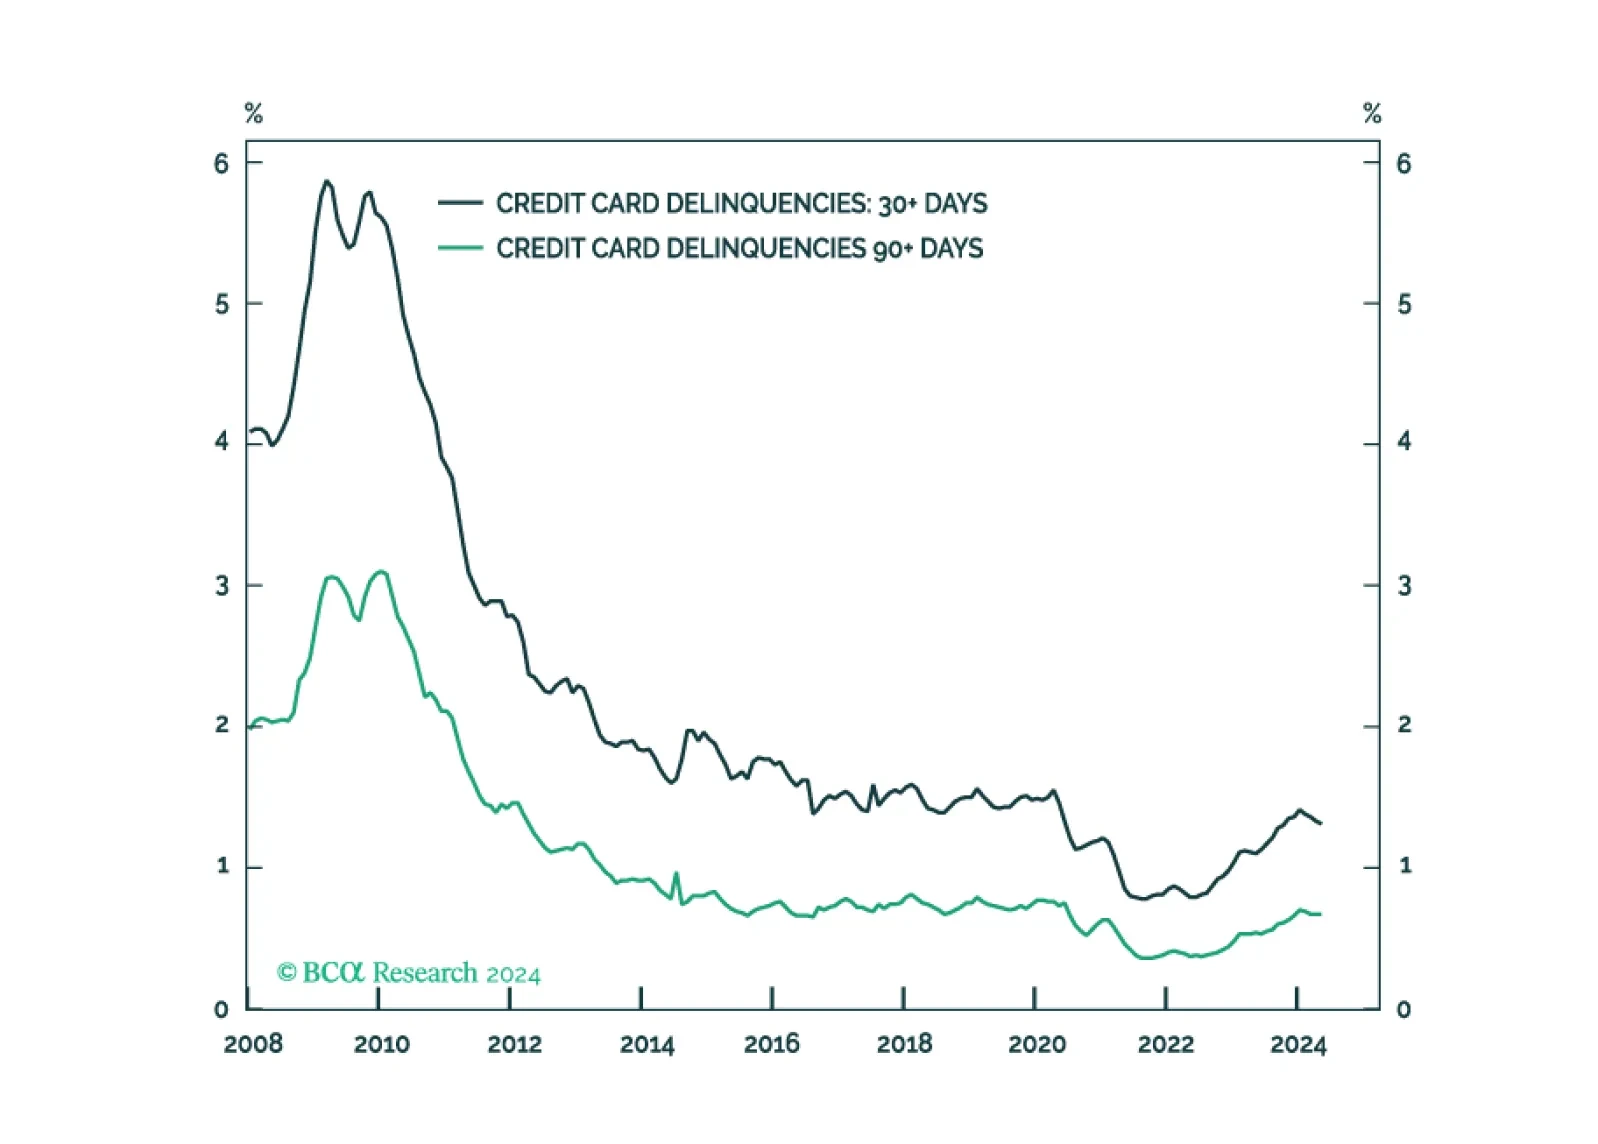
It’s status quo for the SIFI banks, as they don’t see consumer credit performance materially worsening from now-normalized levels and they are not meaningfully exposed to commercial real estate losses.