Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Insights

Access expert research, timely insights, and exclusive webcasts to help you make confident, data-driven decisions.
bca.ficc_si_2026_08_26_cms.png
Report
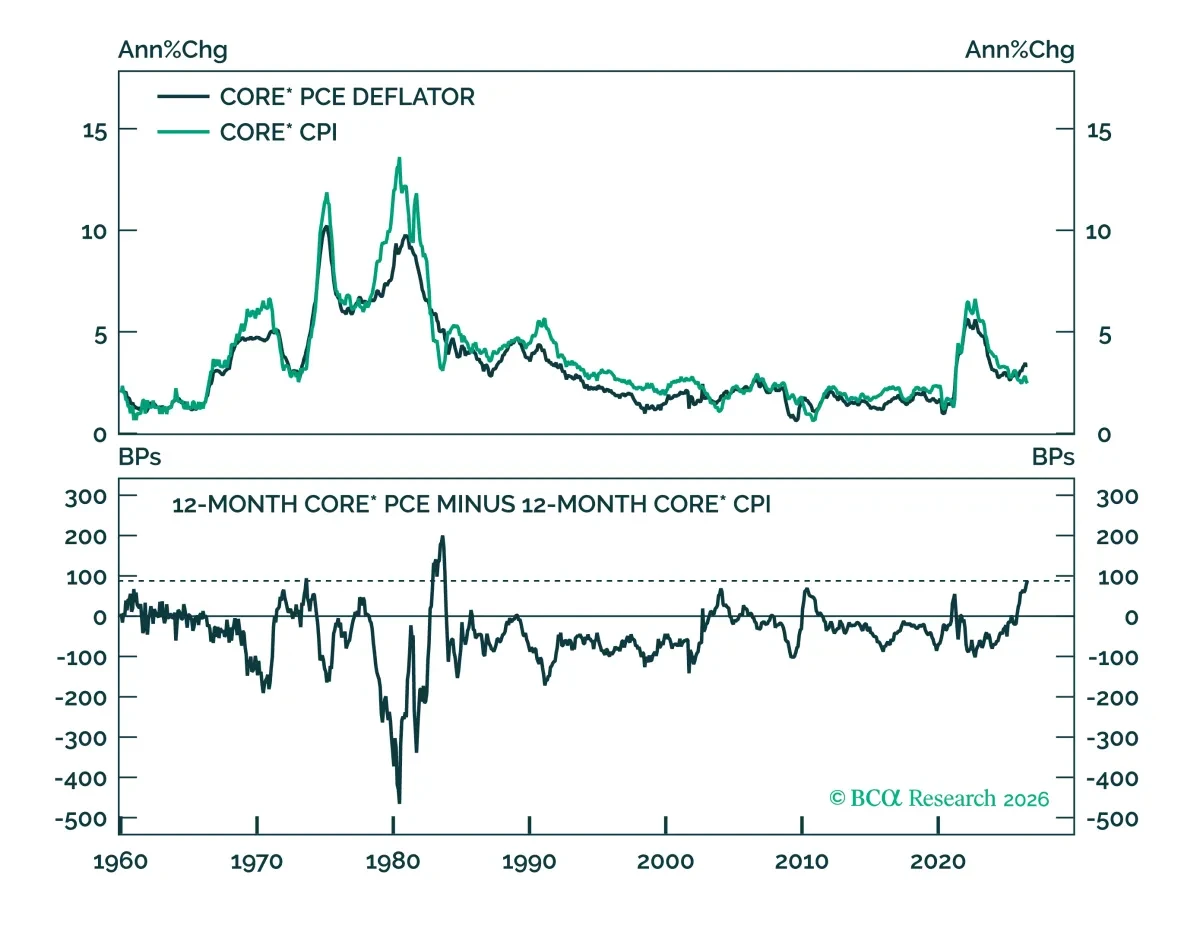
The PCE/CPI gap is an increasingly important factor driving the near-term outlook for Fed policy. We discuss the drivers of that gap and conclude that it’s likely to narrow in the coming months. ...
26 Aug 2026
gmac-crop-test.png
Report
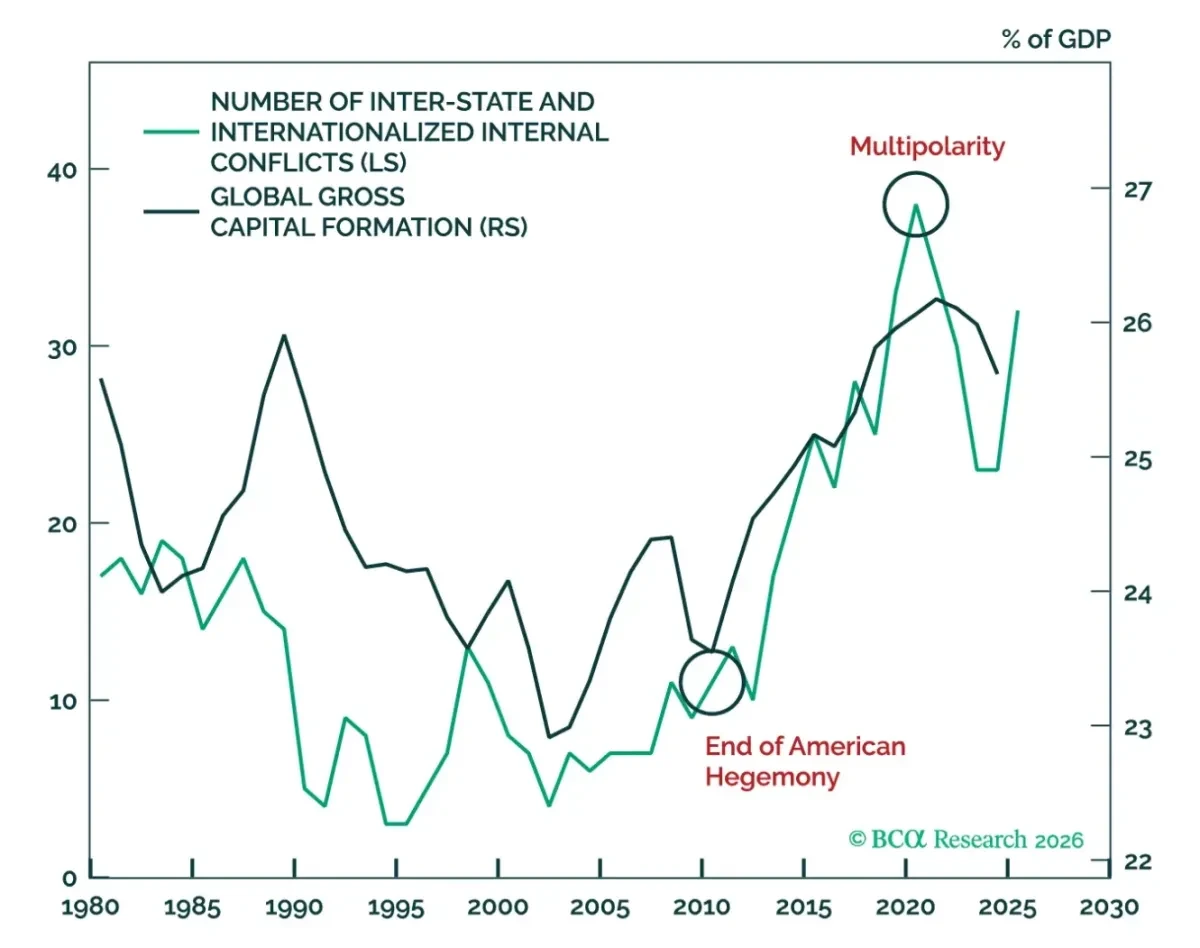
Many clients have asked us for an analysis of the long-term implications of the Hormuz Crisis. In this report, we posit that the conflict has been catalyzed by the multipolar context and that it will merely ossify the trends already afoot. Nothing offers incentives for more global capex like the thr...
25 Aug 2026
bca.core_cid_2026_08_25_cover.png
Report
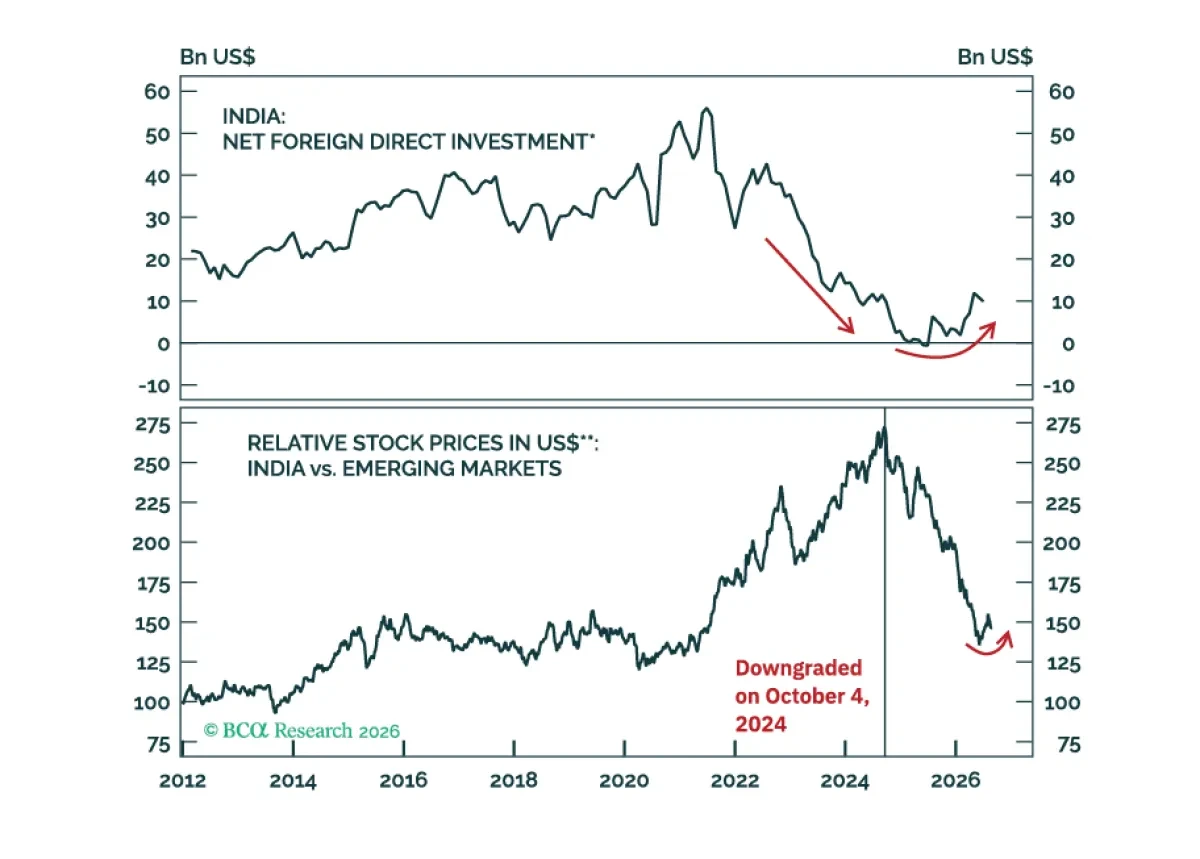
BCA's CoreMacro and Portfolio Construction teams combine two distinct but intersecting lenses to revisit a once heralded opportunity: India. We upgrade India across both public and private markets, but the conviction is not the same everywhere....
25 Aug 2026
bca.gmac_si_2026_08_24_cms.png
Report
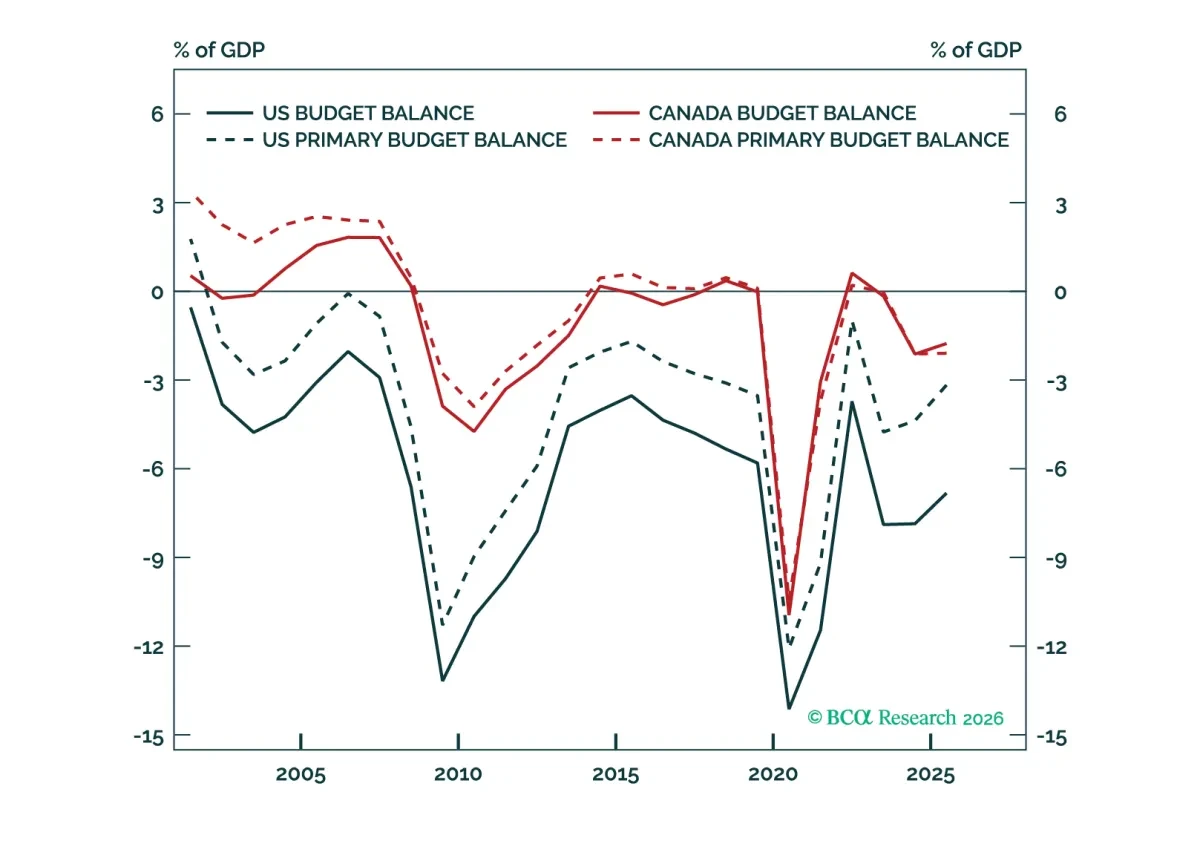
Canada may welcome a trade skirmish with the US. It has ample fiscal room with which to retaliate and its domestic political calculus – with bubbling risk of secession – means that fighting an external threat is a boon, not a bore....
24 Aug 2026
bca.ficc_si_2026_08_24_cms.png
Report
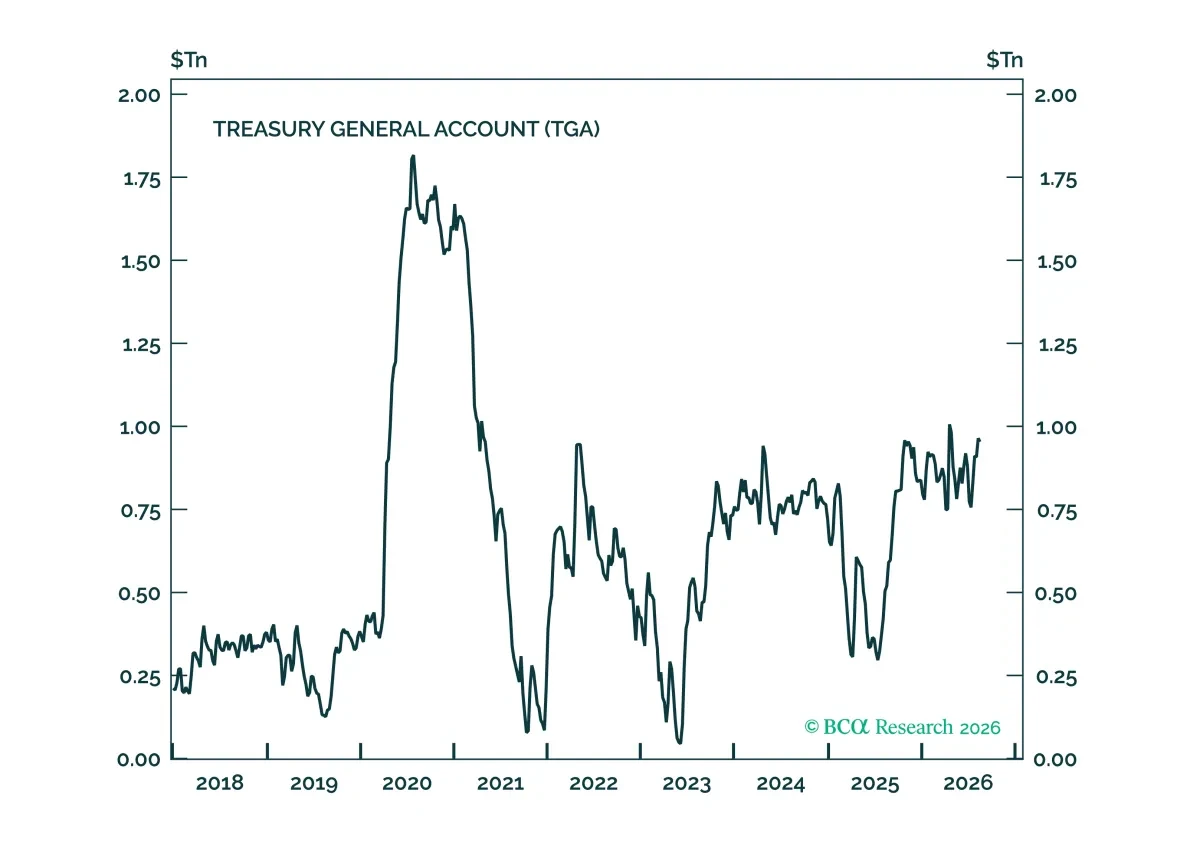
The US Treasury department’s attempts at yield suppression are doomed to fail unless the Federal Reserve gets involved....
bca.core_str_2026_08_21_cw.png
Report
If bond yields rise due to widening bond term premiums or escalating inflation expectations, Bessenomics is unlikely to avert a stock-bond collision. Buy back gold mining stocks....
bca.core_str_2026_08_20_cms.png
Report
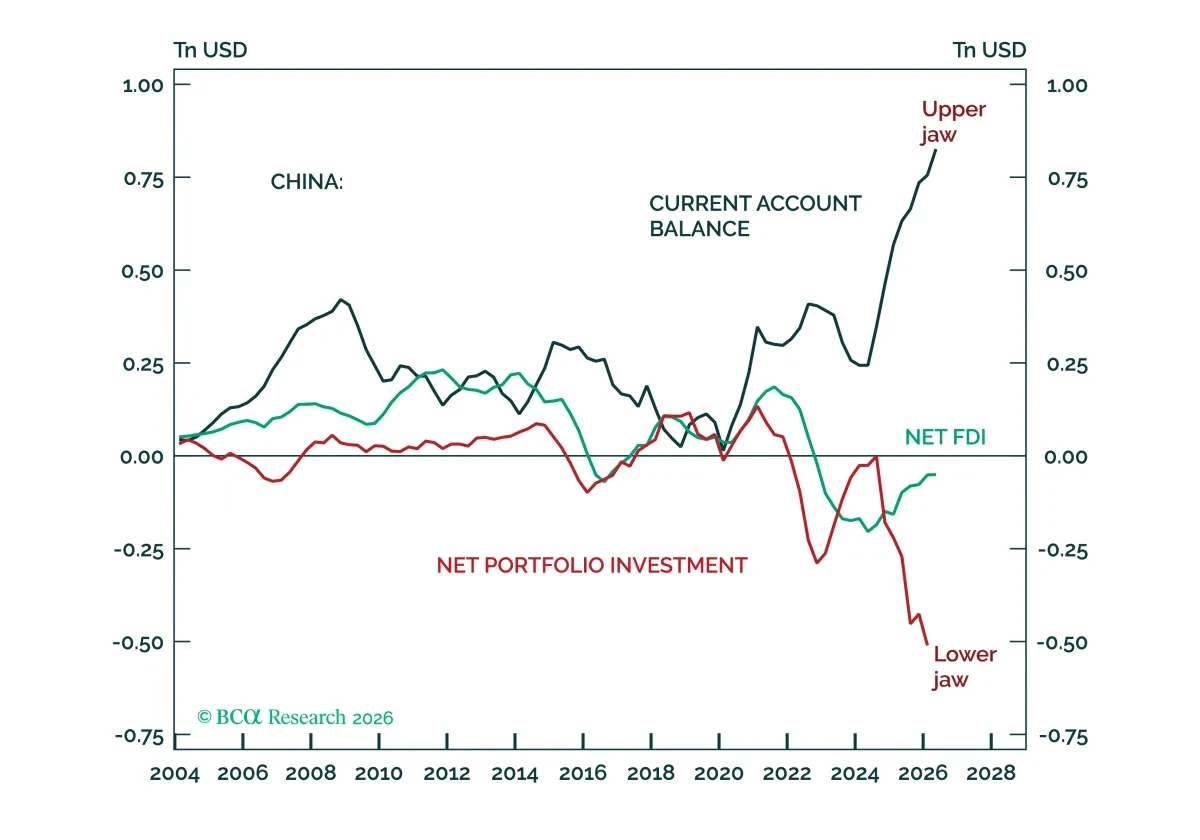
In this report, we highlight notable developments on both sides of China’s BoP: a widening external surplus on the current account side, and shifts in how that surplus is recycled abroad through BoP financial account....
20 Aug 2026
bca.ficc_si_2026_08_20_cms.png
Report
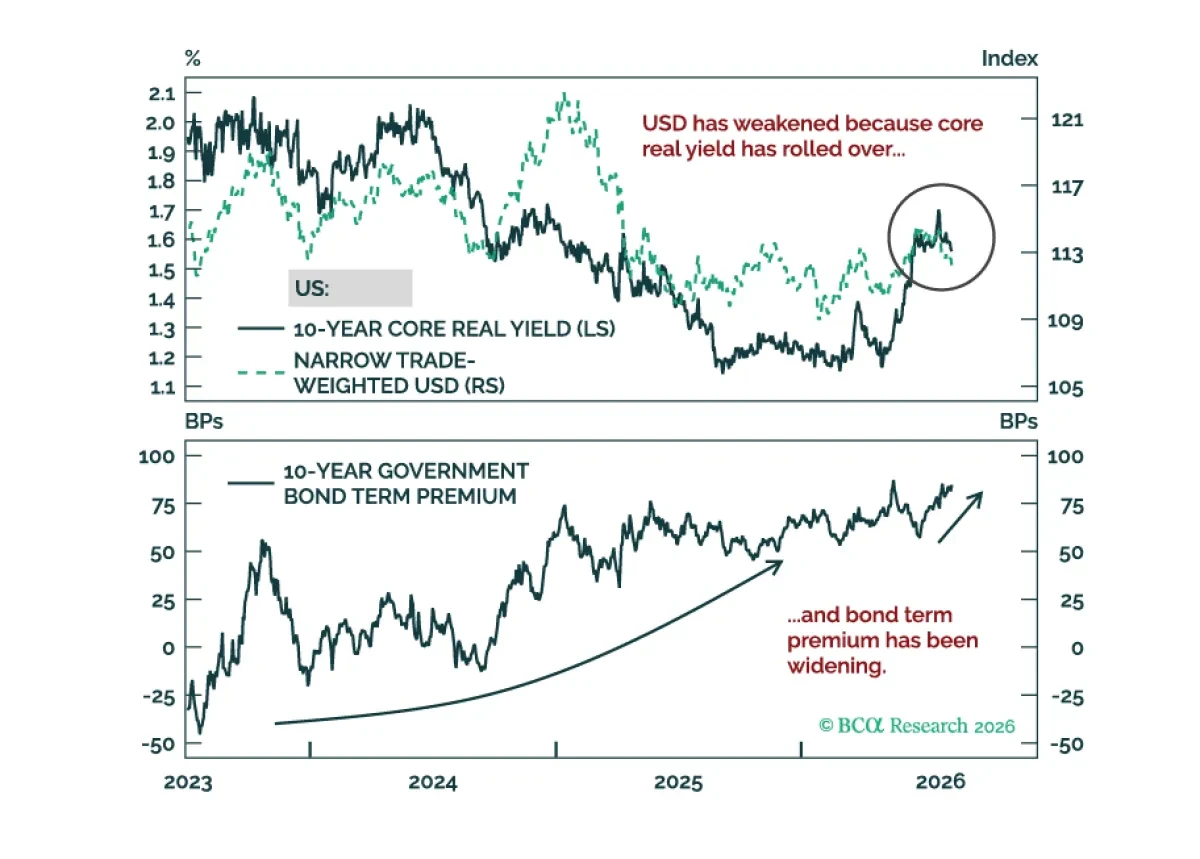
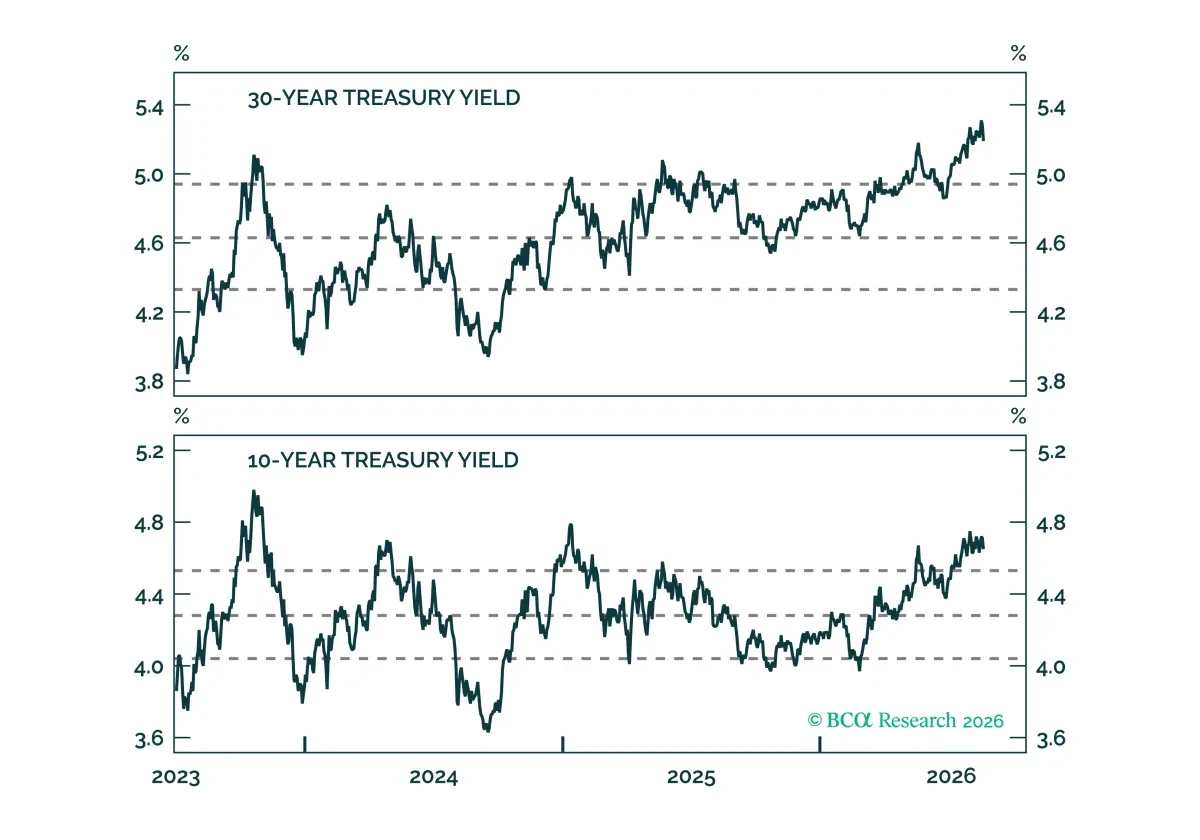
Despite recent increases, long-maturity Treasury yields are roughly consistent with fundamental fair value. We see limited value in long duration plays....
20 Aug 2026
bca.ficc_str_2026_08_20_cms.png
Report
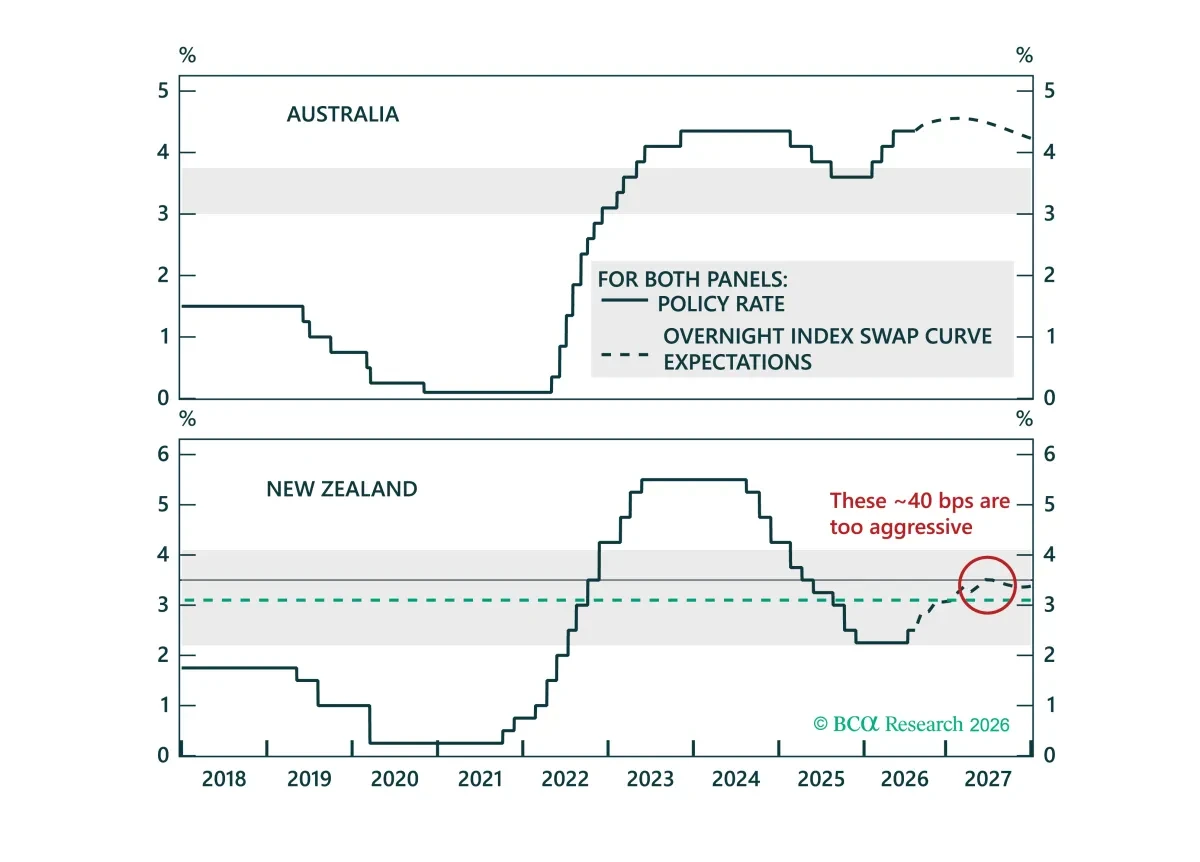
The RBA is likely done hiking, and the RBNZ overpriced for more hikes. We trace both conclusions back to housing, credit, and external dynamics, with implications for our country allocation in ANZ bonds and our long AUD/NZD view....
20 Aug 2026
Arthur-Budaghyan.png
Webcast Replay

Arthur discussed:

  • Global currency markets are on the edge: the US dollar will become pro-cyclical, and the euro will become counter-cyclical.
  • This regime shift would upend financial market correlations, and most investment portfolios are not positioned for it.
  • The main driver of currency markets will change from interest rates to the balance of payments.
  • The dollar’s dependence on net foreign flows into US equities is far greater today than ever.
  • A low bar for US dollar depreciation: No net capital outflows necessary — just smaller inflows.
  • A weaker US dollar will be deflationary, not reflationary, for the rest of the world.
  • EM stocks will not rally in absolute terms despite a weak US dollar.
  • Which asset classes and regions will perform the best during this US dollar devaluation?