Geopolitics
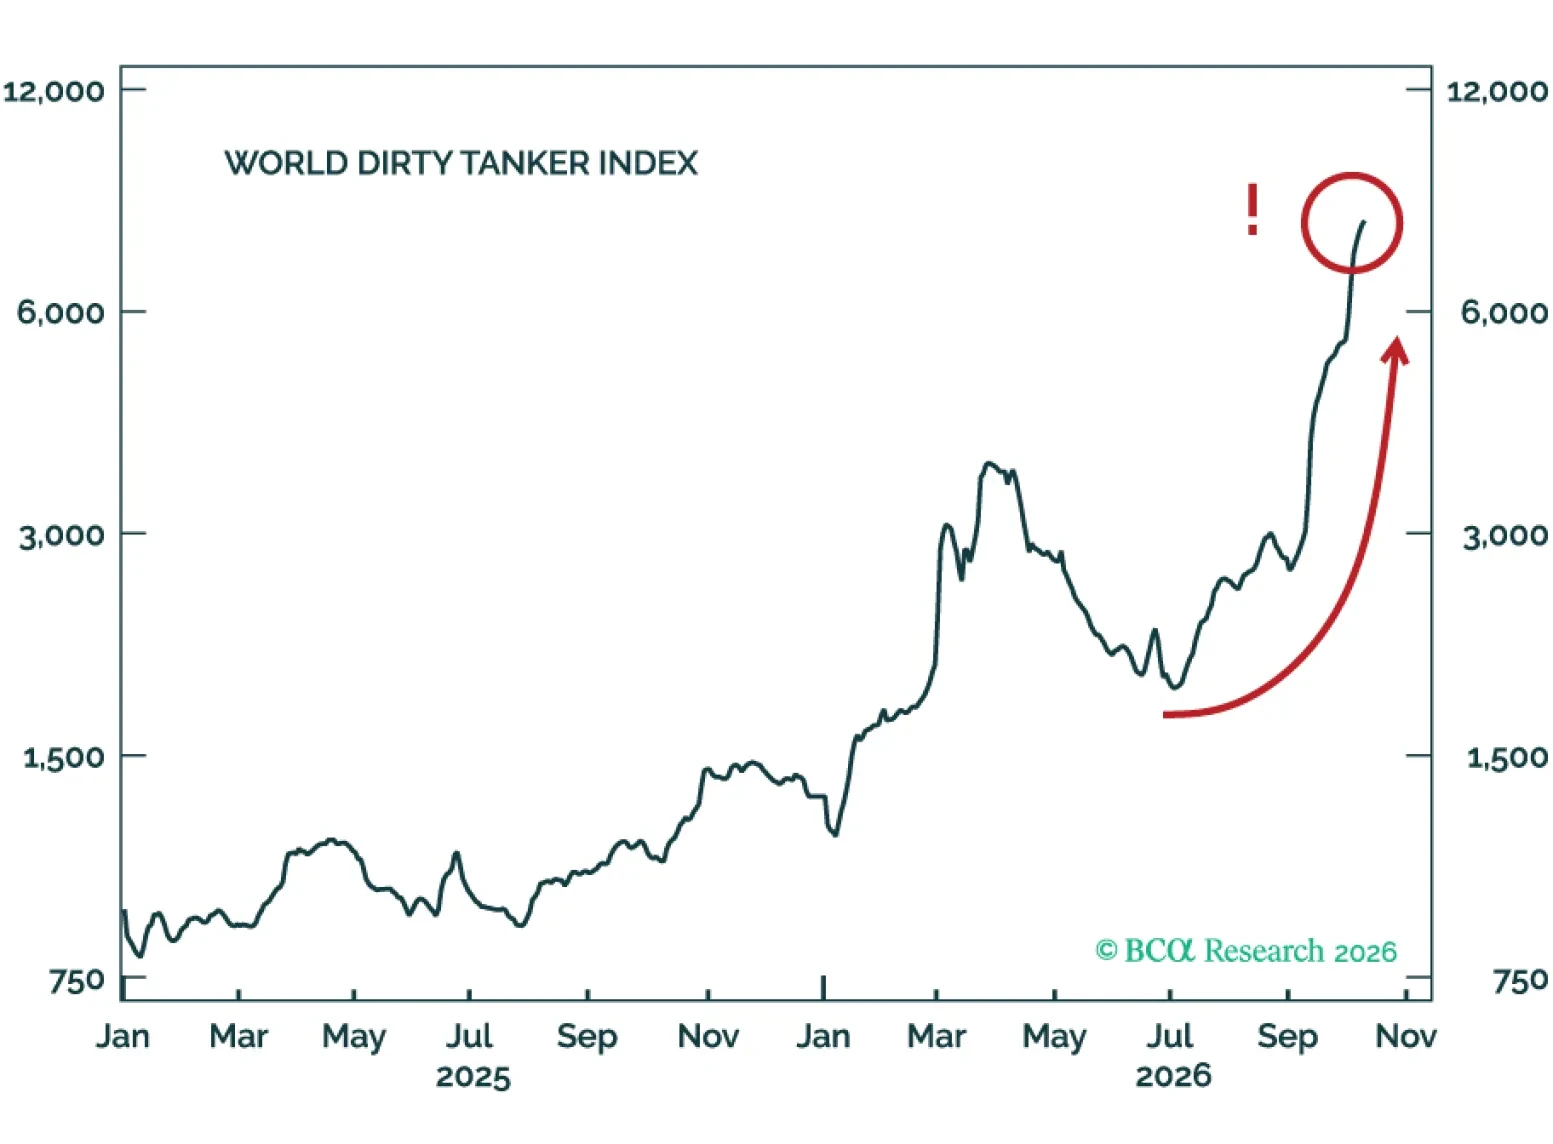
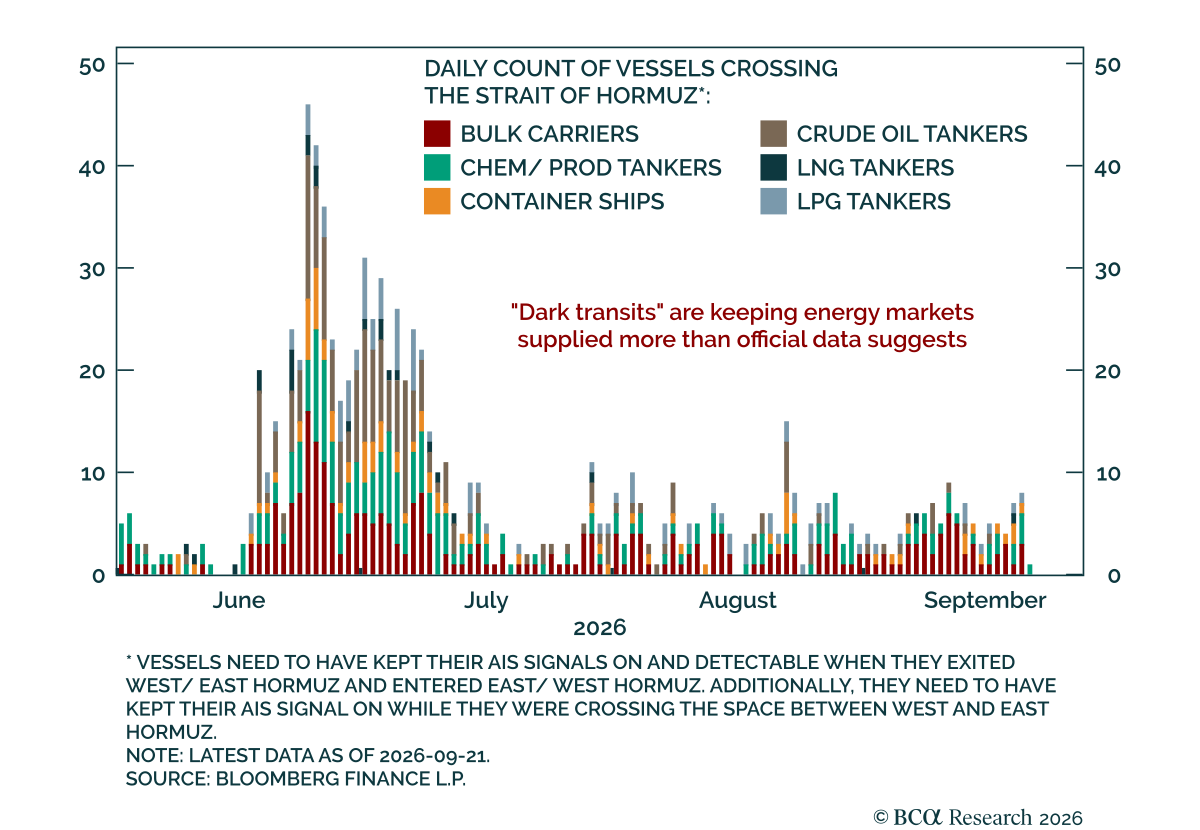
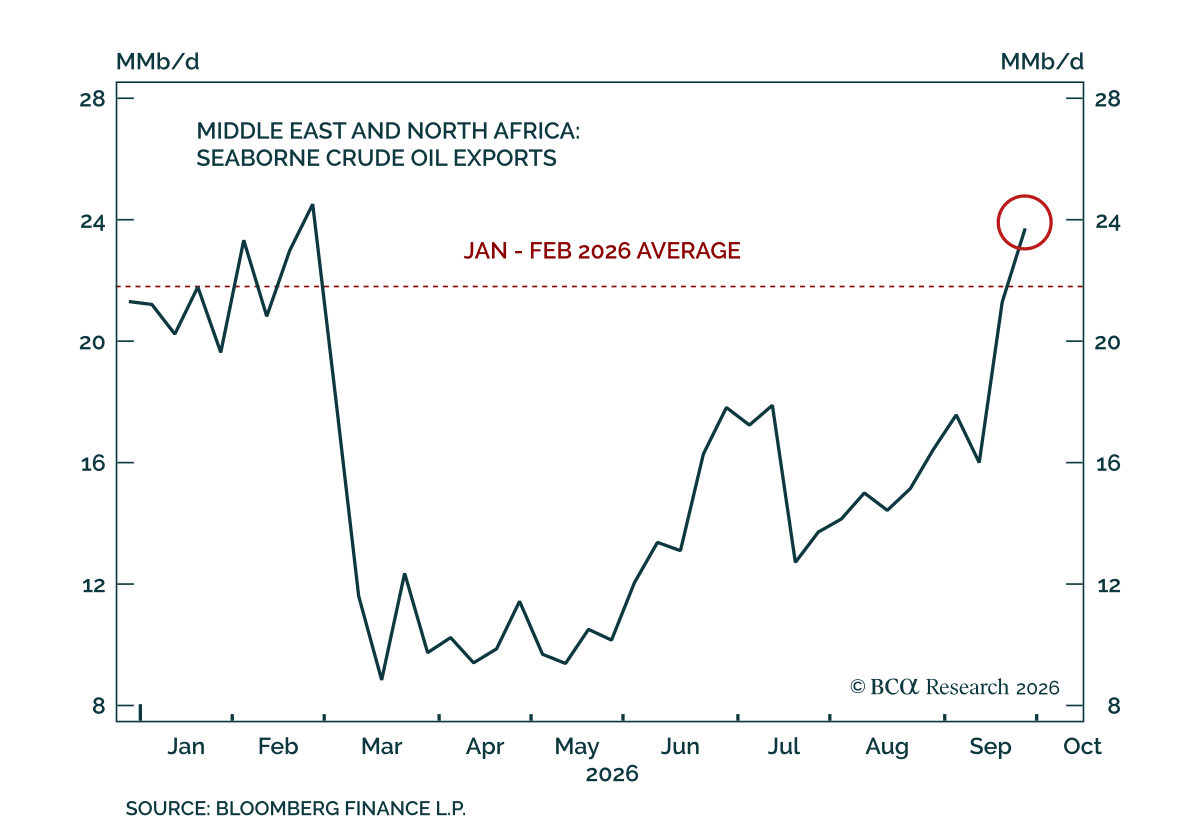
Middle Eastern crude exports are back at pre-war levels, yet Brent remains above $100/bbl. We explain why more barrels haven’t meant lower prices, and why policymakers have no clean fix. Even if Putin follows through on his reported agreement to release Russian diesel supplies into global markets, it is unlikely to meaningfully ease the fuel's supply disruption over the near term.
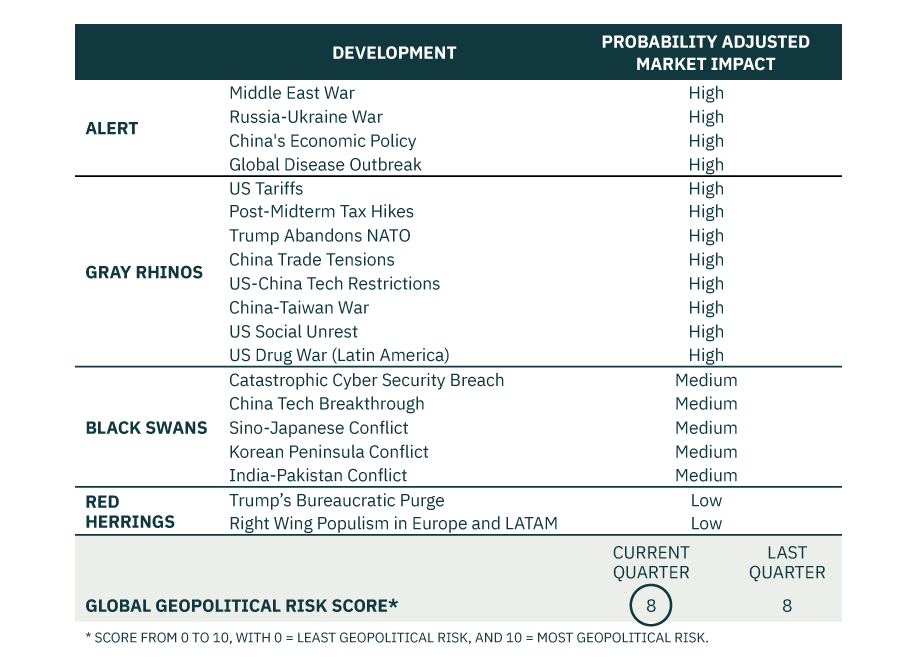
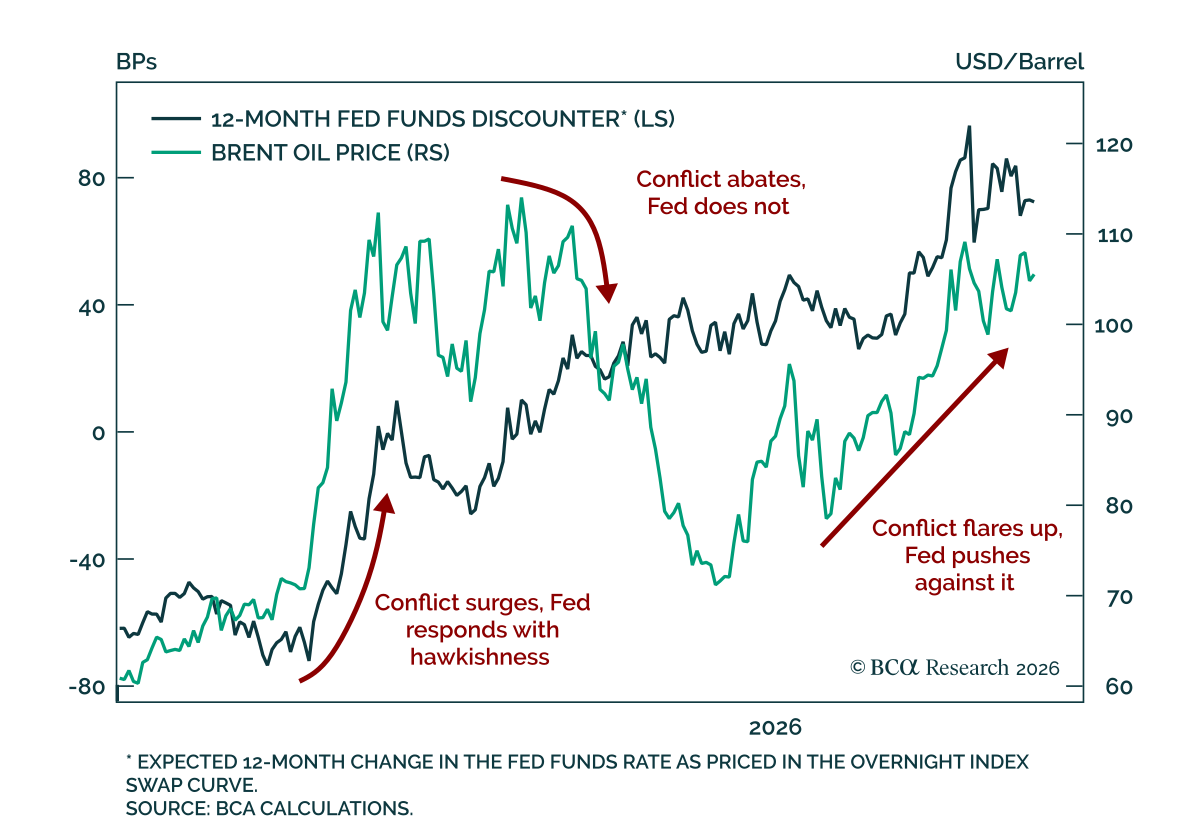
Long-dated bond yields rose another 48 bps since our last missive, quite a move in just a month. And yet, equities have remained resilient. This suggests that the move in bond yields is due to sanguine economic forces, not fiscal profligacy or inflation fears. In addition, the war in Iran is subsiding, partly because the Fed itself has conspired against it. Will President Trump restart the conflict regardless? Perhaps, however, the constraints are mounting against the White House foreign policy. We remain bullish on equities and reaffirm our view that investors with a long-term horizon should be nibbling at the current level of yields.
To make sure that our bearish clients are happy, we pivot to the risk of higher tax rates in the US. Specifically, we try to answer the question of when markets price higher tax rates.
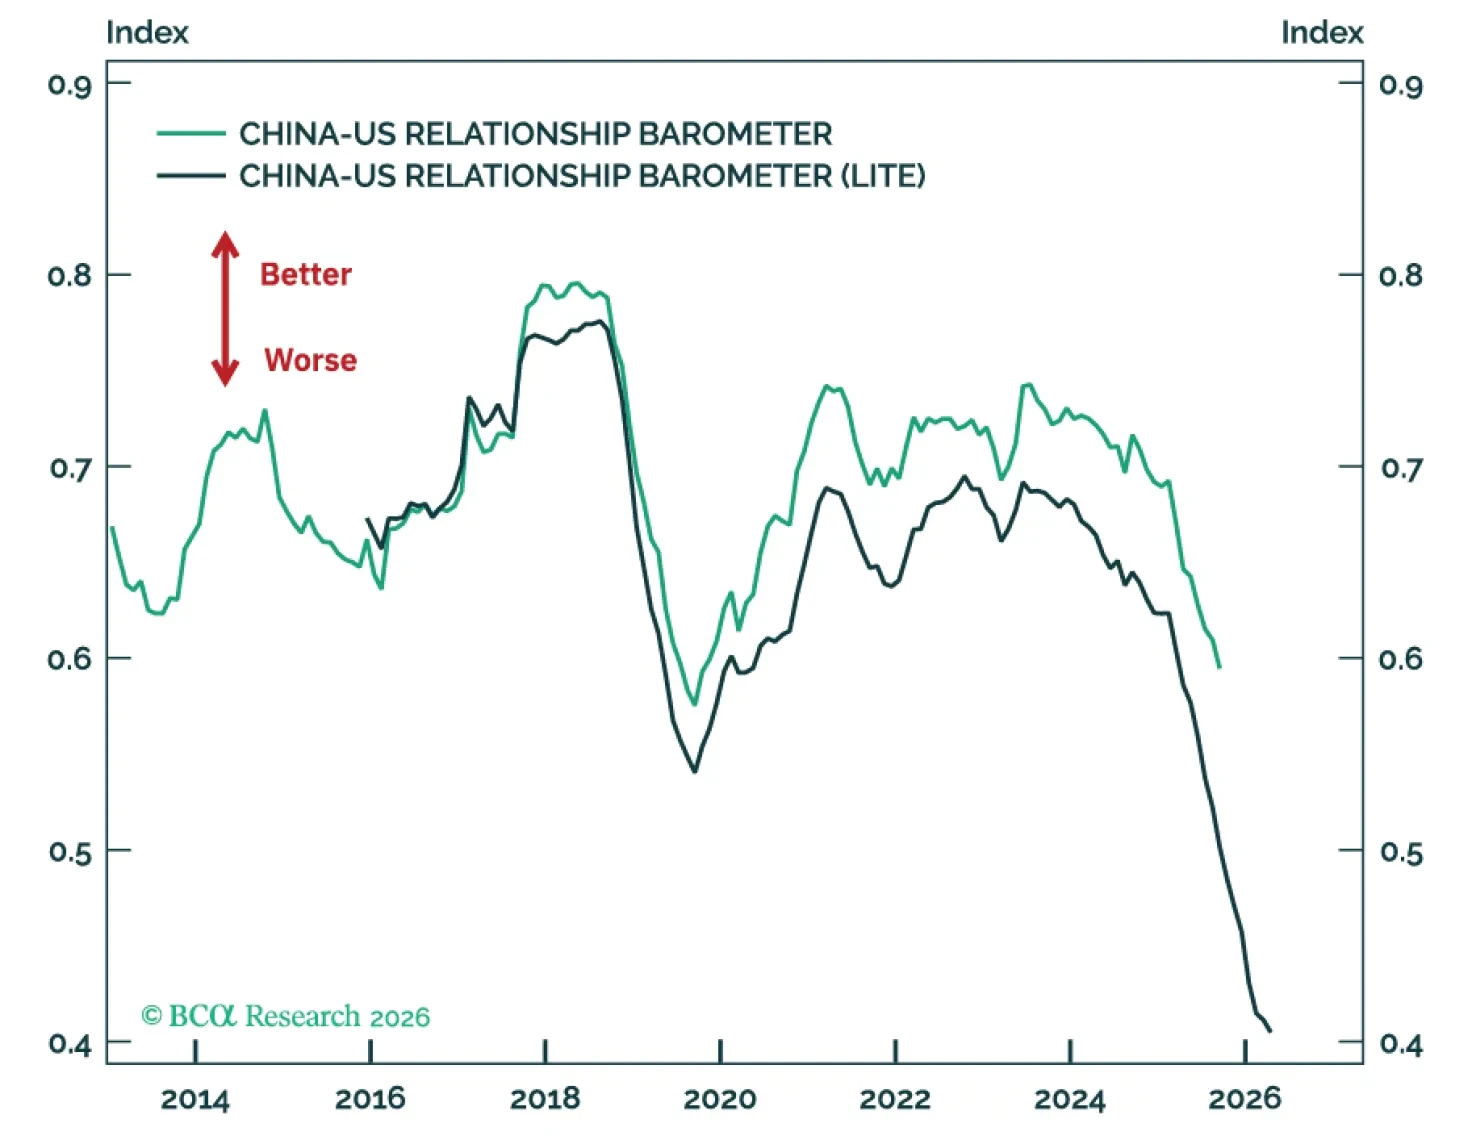
The Trump-Xi summit does not imply concrete benefits to US-China trade. Strategic tensions persist, forcing China to increase fiscal stimulus in 2027.