Sorry, you need to enable JavaScript to visit this website.
Skip to main content

Correlations

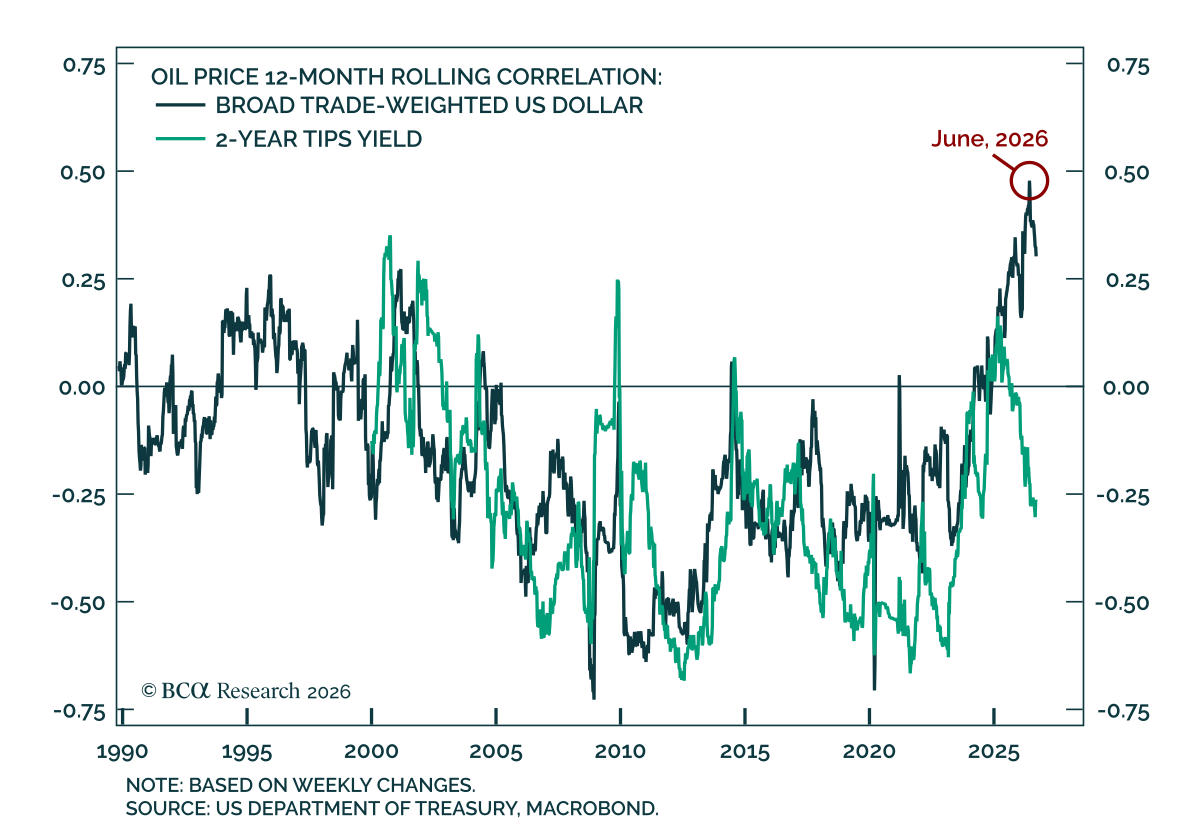
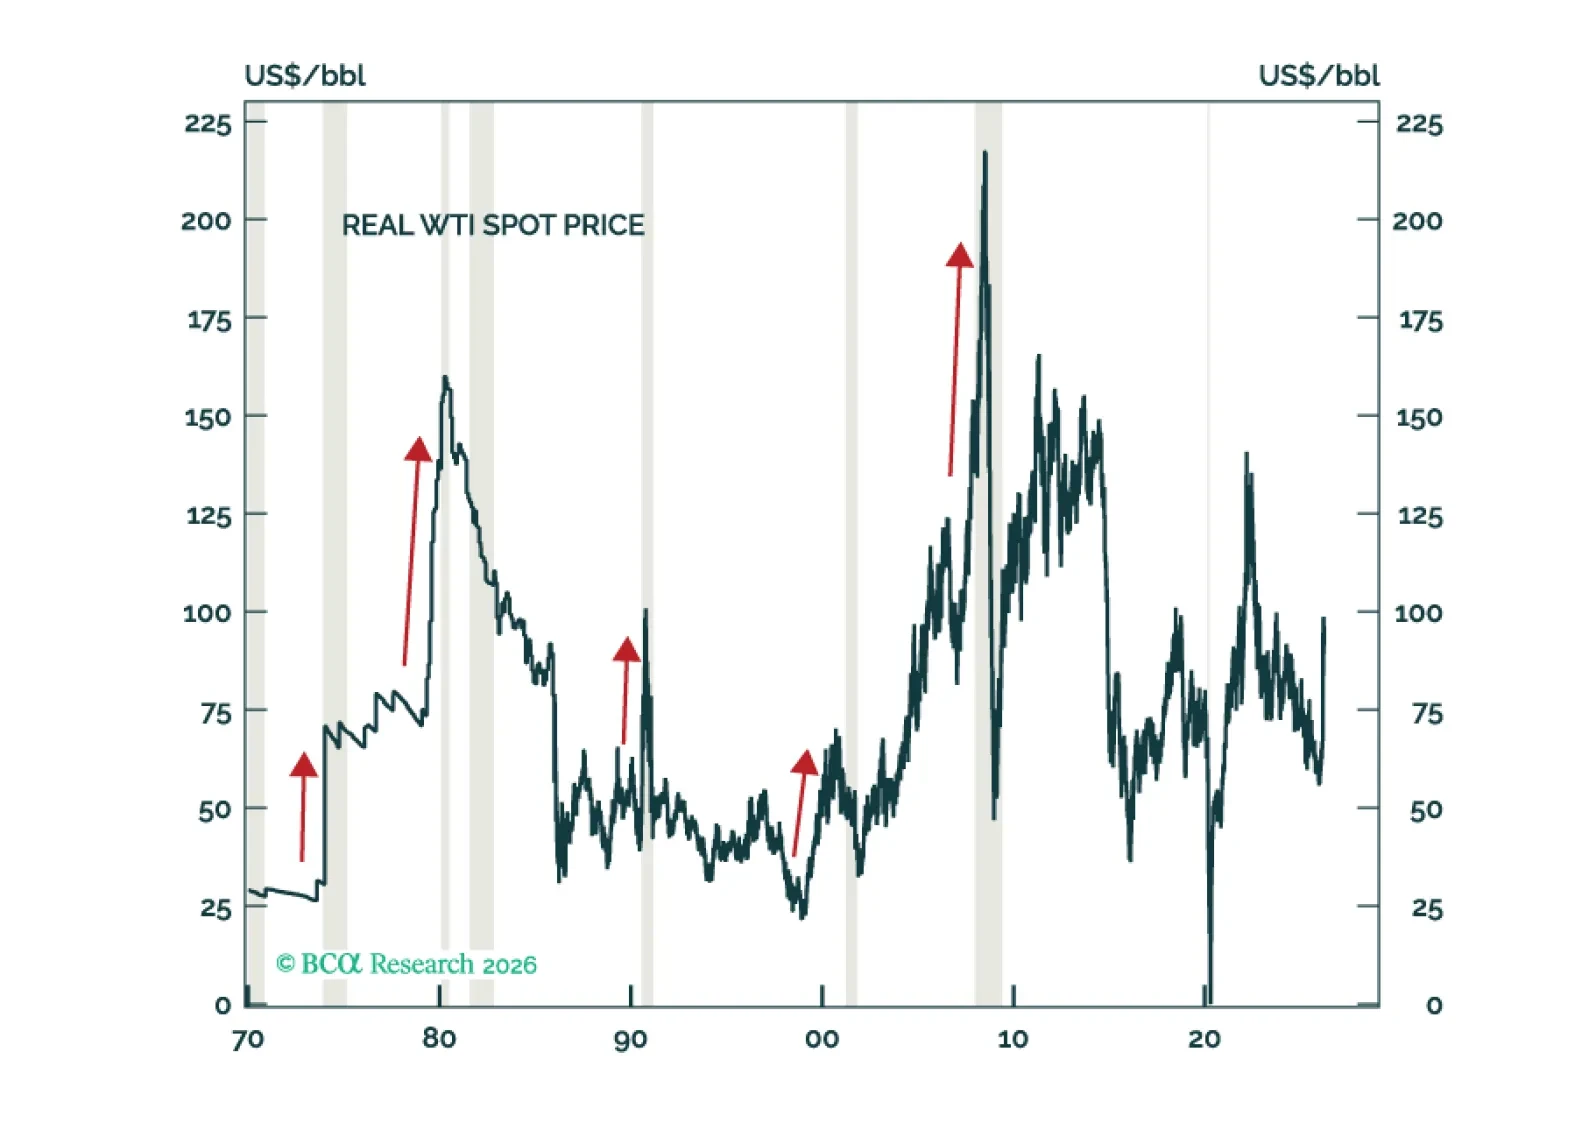
The USD-oil correlation reached a record high this year, confirming that energy shocks now reinforce dollar strength rather than weigh on it, arguing for overweighing USD against energy-importing currencies into further supply disruptions. This positive…
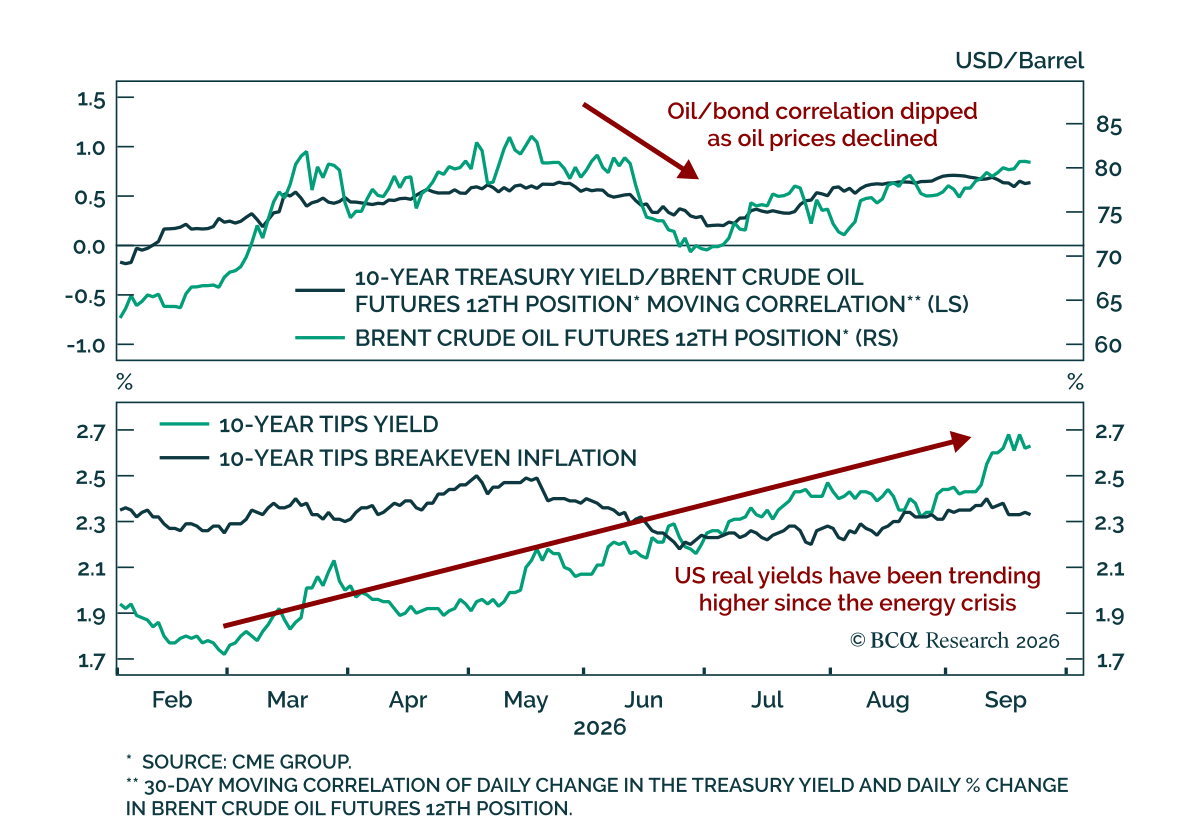
Oil prices and US Treasury yields have moved in lockstep this year, but oil matters less for US yields than the correlation suggests. The joint rise is not purely a coincidence. Higher oil prices play a role in the hawkish repricing of the Fed's policy path,…
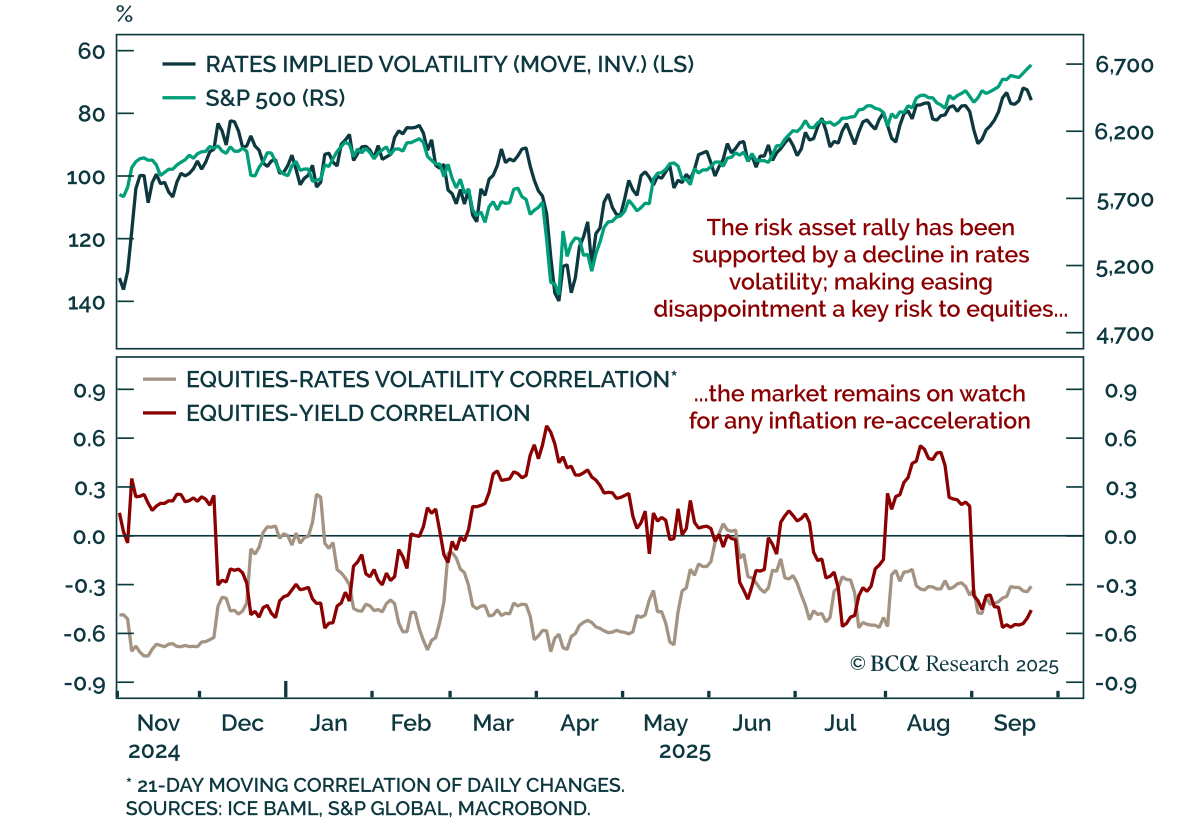
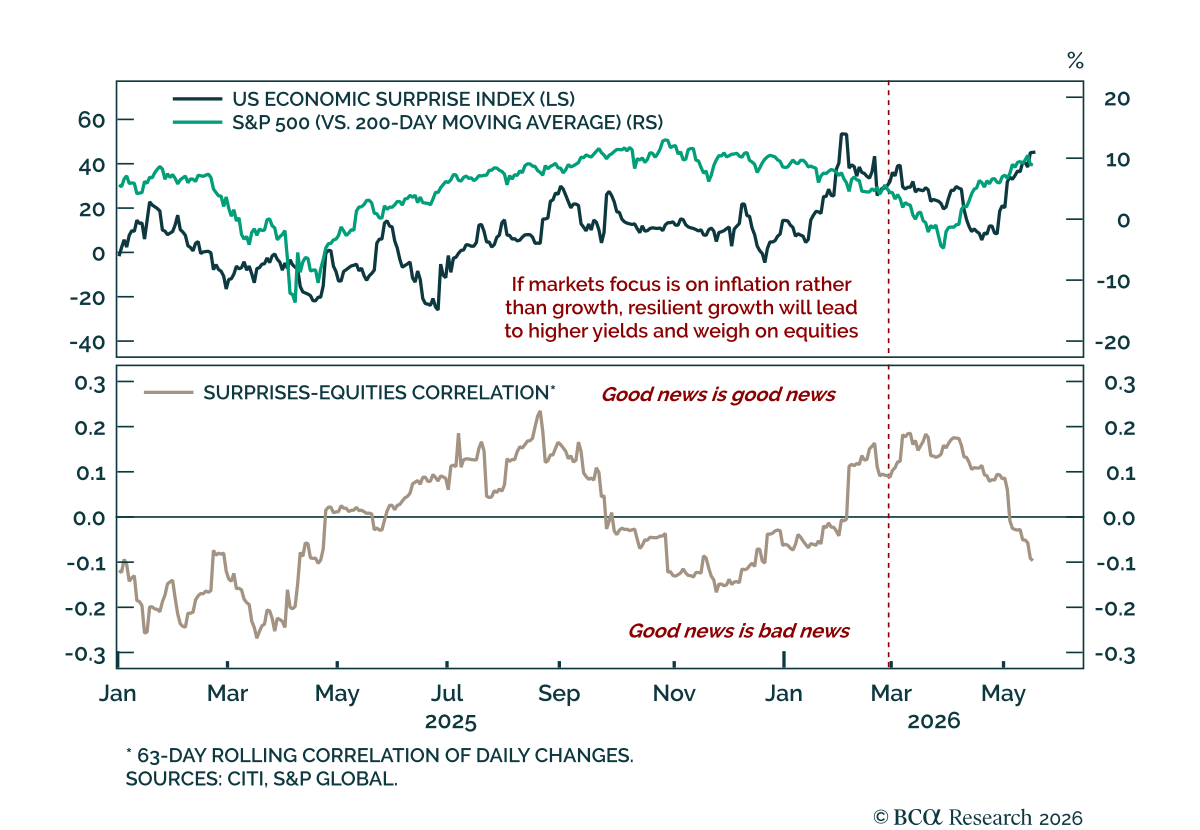
The Iran war has made inflation the market’s main focus again, creating a backdrop where resilient data could hurt equities. Long-term inflation expectations remain anchored, but the near-term inflation path is still uncertain. Markets are still trying to…

The current macro environment is a toxic brew of many of the same vulnerabilities that haunted the global economy in the lead-up to past recessions: Rising oil prices, an unsustainable tech capex boom, elevated equity valuations, excessively high homes prices, and brewing stresses in private credit and other parts of the financial system. While global equities look increasingly oversold in the very near term, they will still finish the year below current levels.
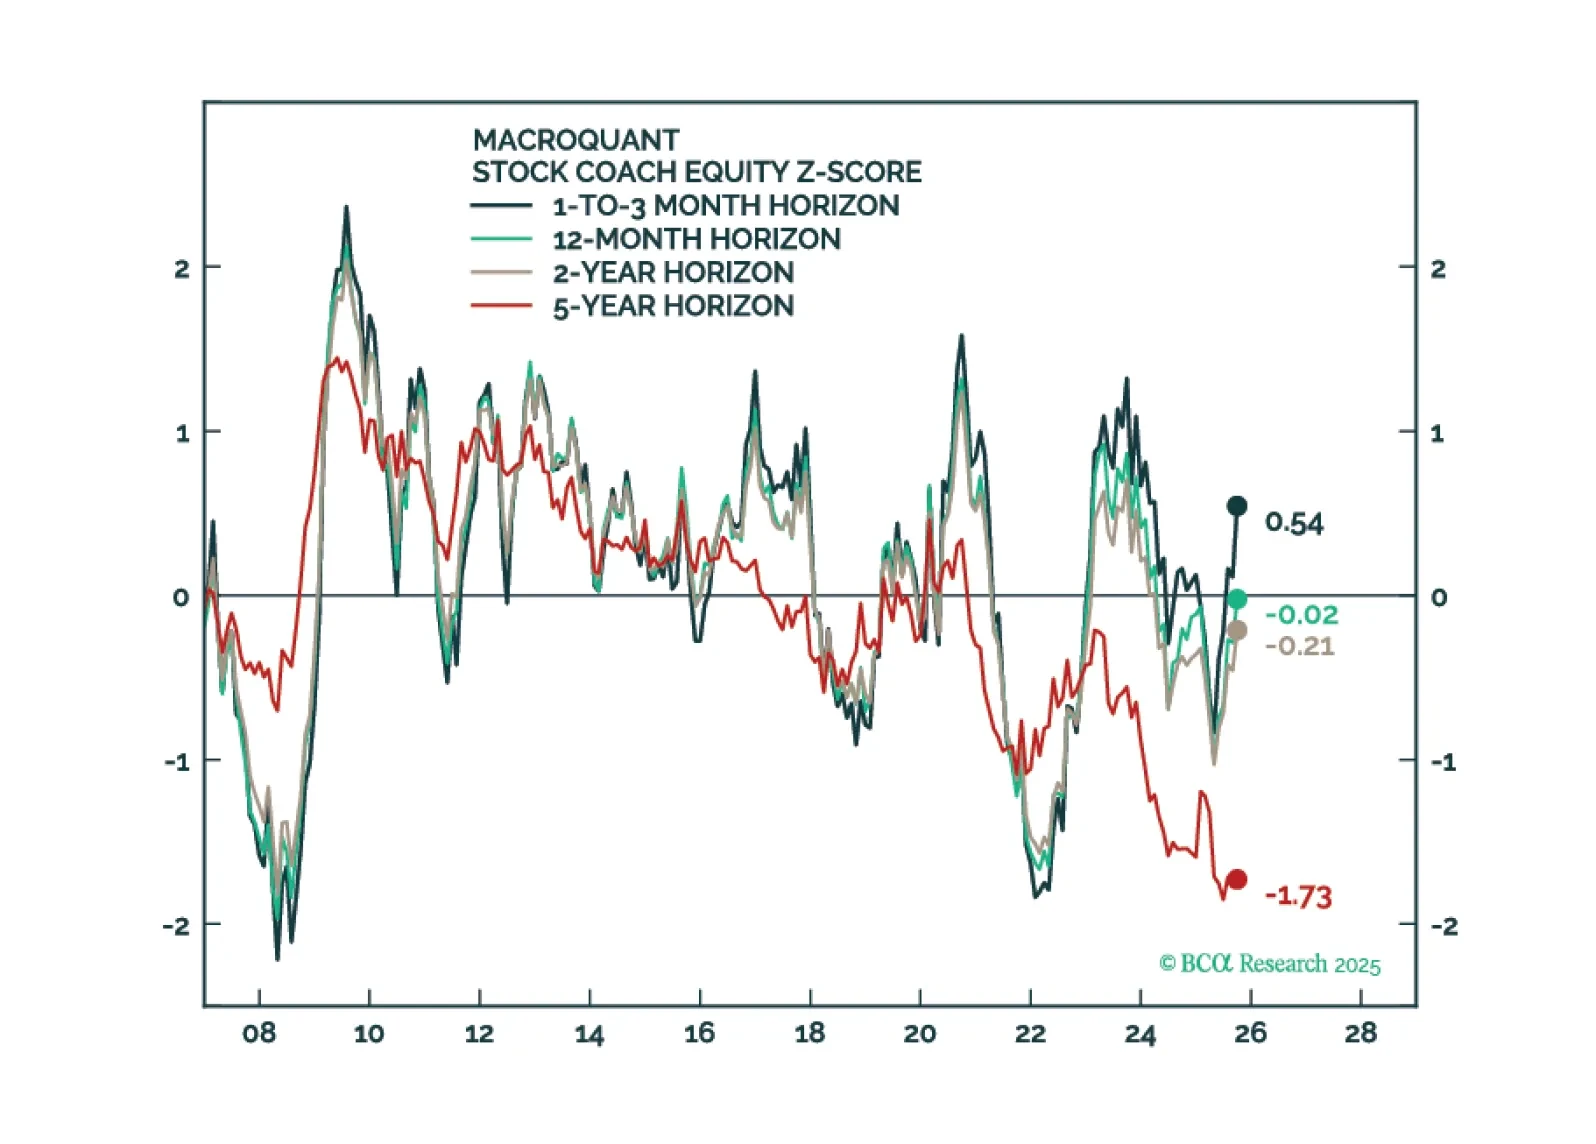
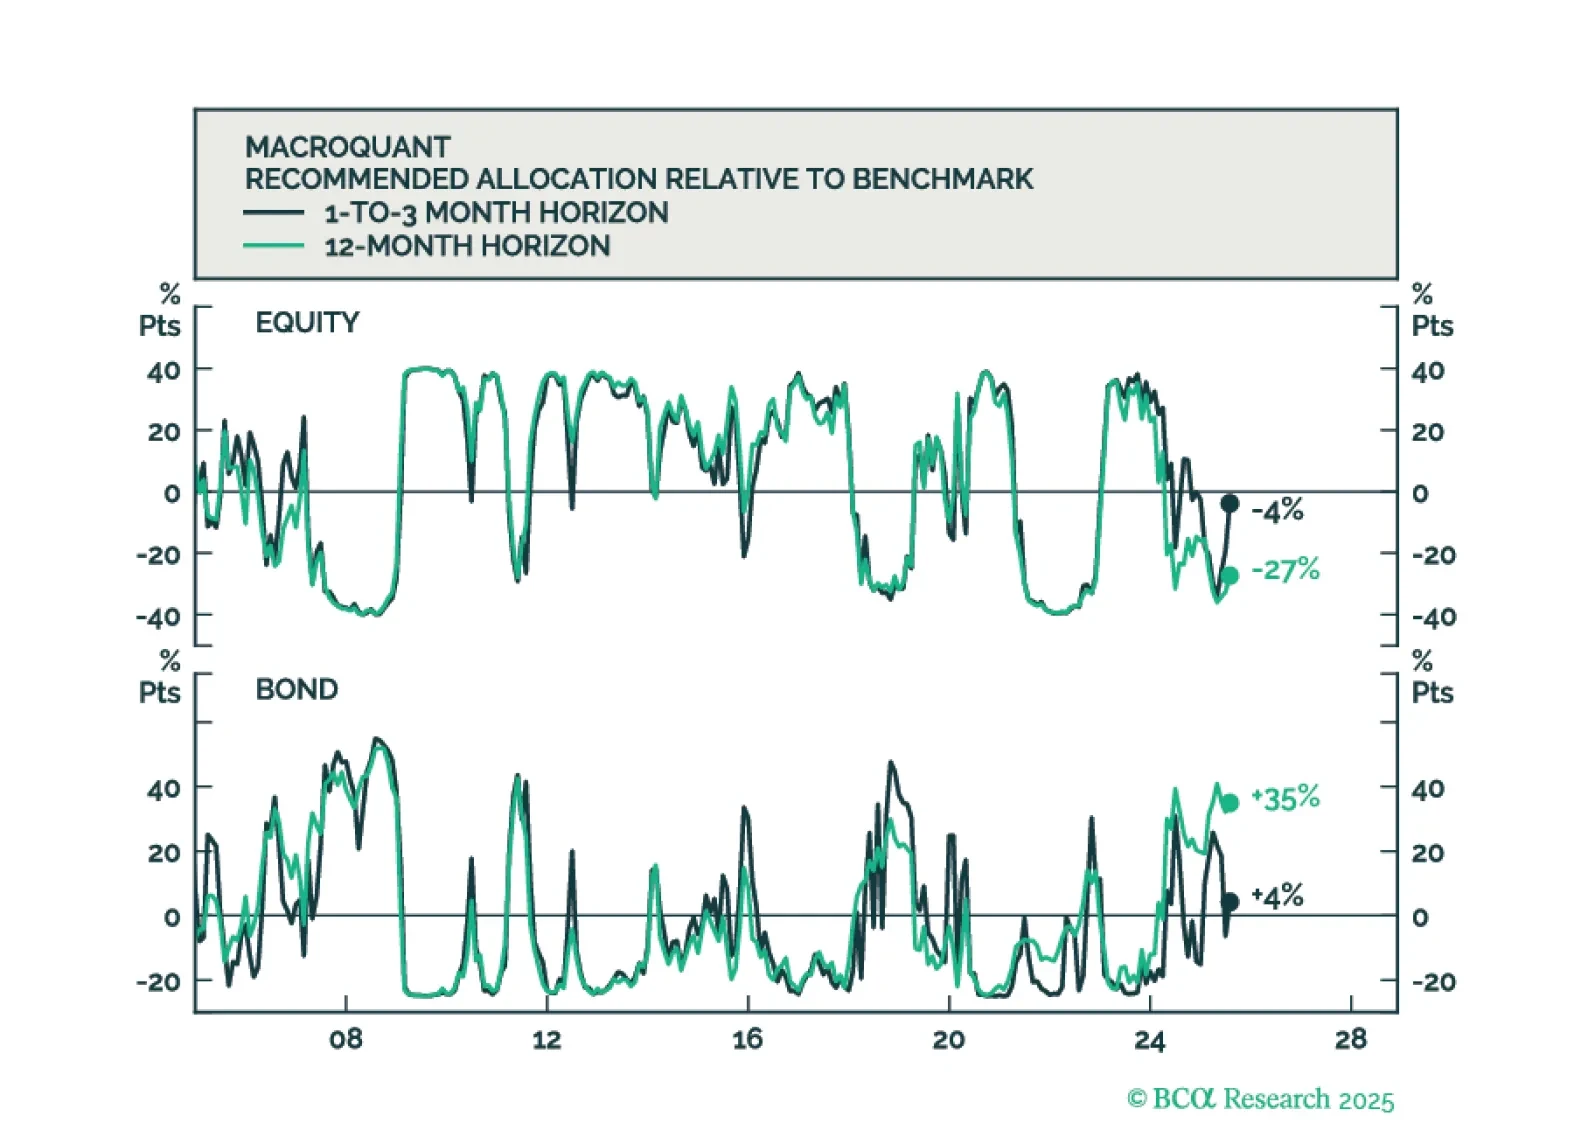
MacroQuant is tactically overweight equities, favors an above-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, and is bullish on gold and copper.
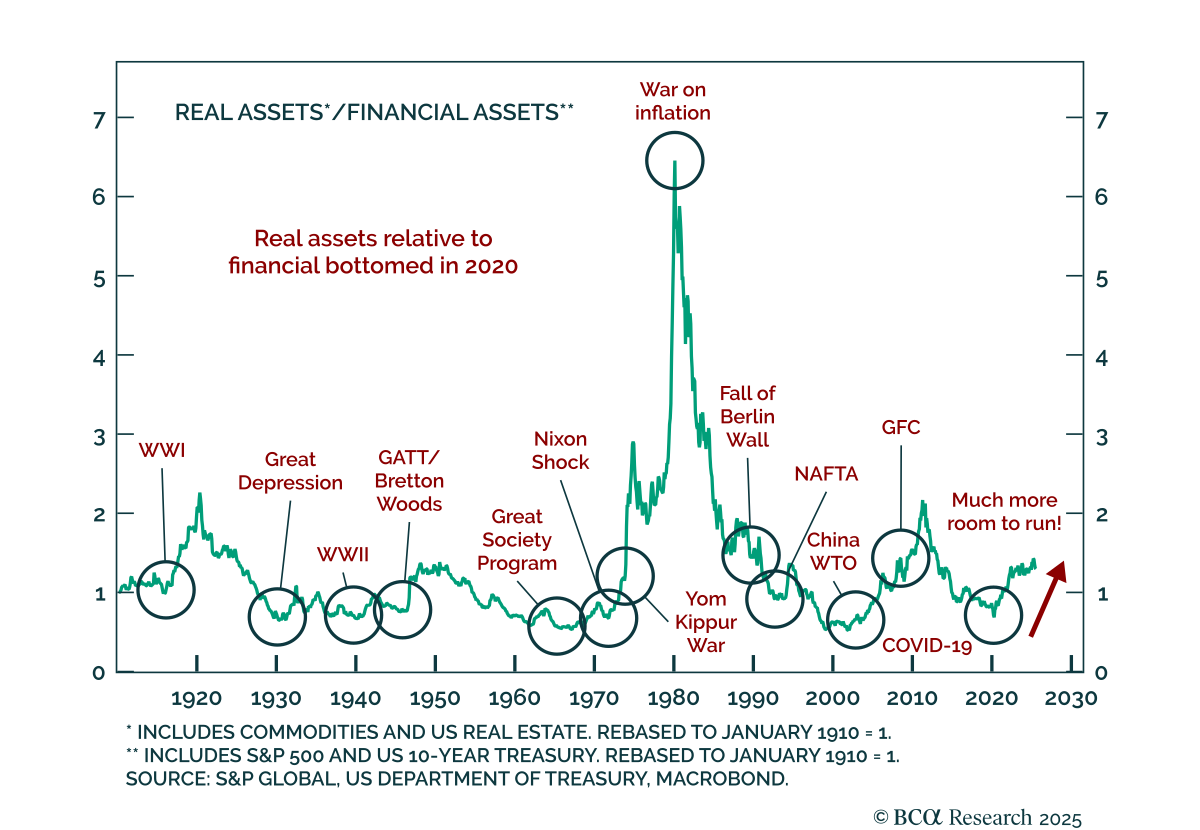
Our GeoMacro strategists remain overweight equities and bonds for now but warn that markets will soon test their “melt-up” thesis, as the cycle transitions from cash- to leverage-driven growth. The dominant theme of 2025 is not AI, but USD debasement. While a…
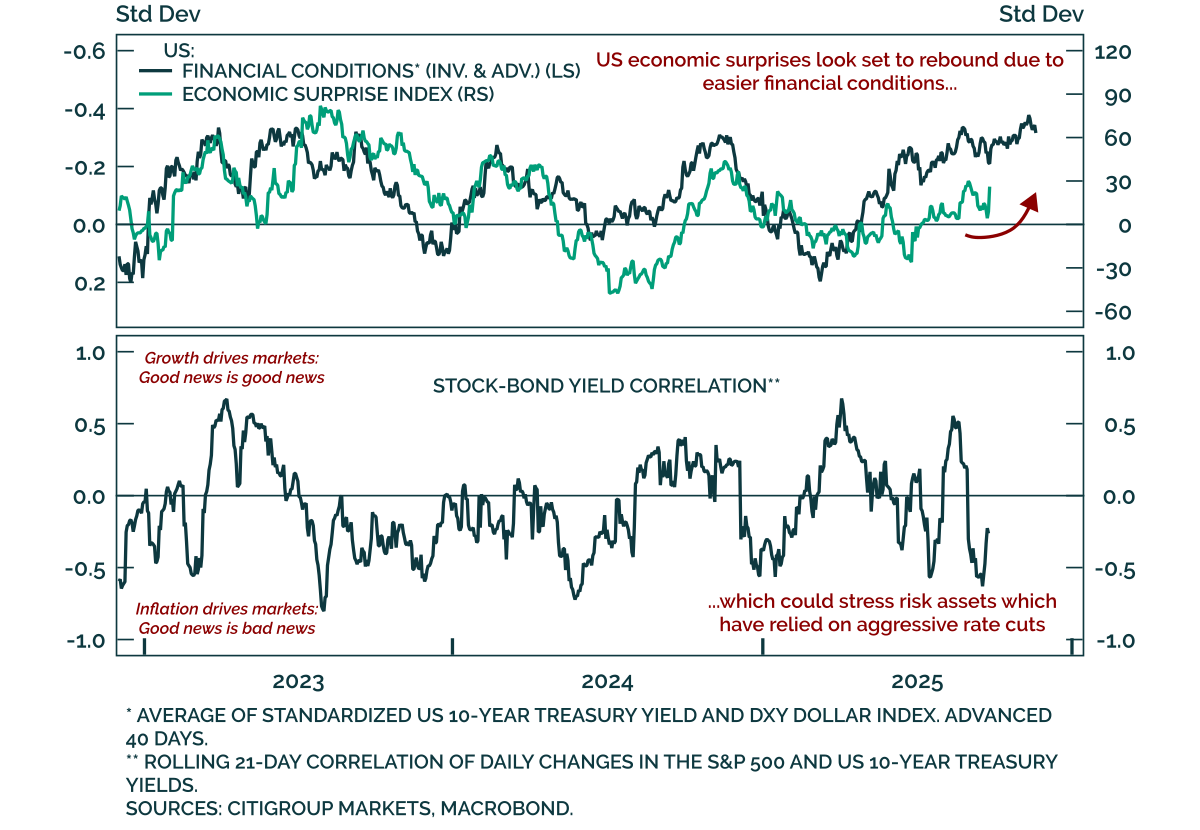
Our tactical framework, which tracks the reflexive loop between financial conditions and economic surprises, points to stronger near-term growth, leaving equities vulnerable if inflation re-accelerates. Data surprises move markets, while bond yields and the…
Low rates volatility has been a key tailwind for equities, but the fragile equilibrium leaves markets exposed to AI sentiment and inflation risks. Rates volatility, measured by the MOVE index, has drifted to multi-year lows and sits below its 20th percentile…

MacroQuant sees downside risks to stocks over a long-term horizon but is not yet saying that we are at imminent risk of an equity bear market.
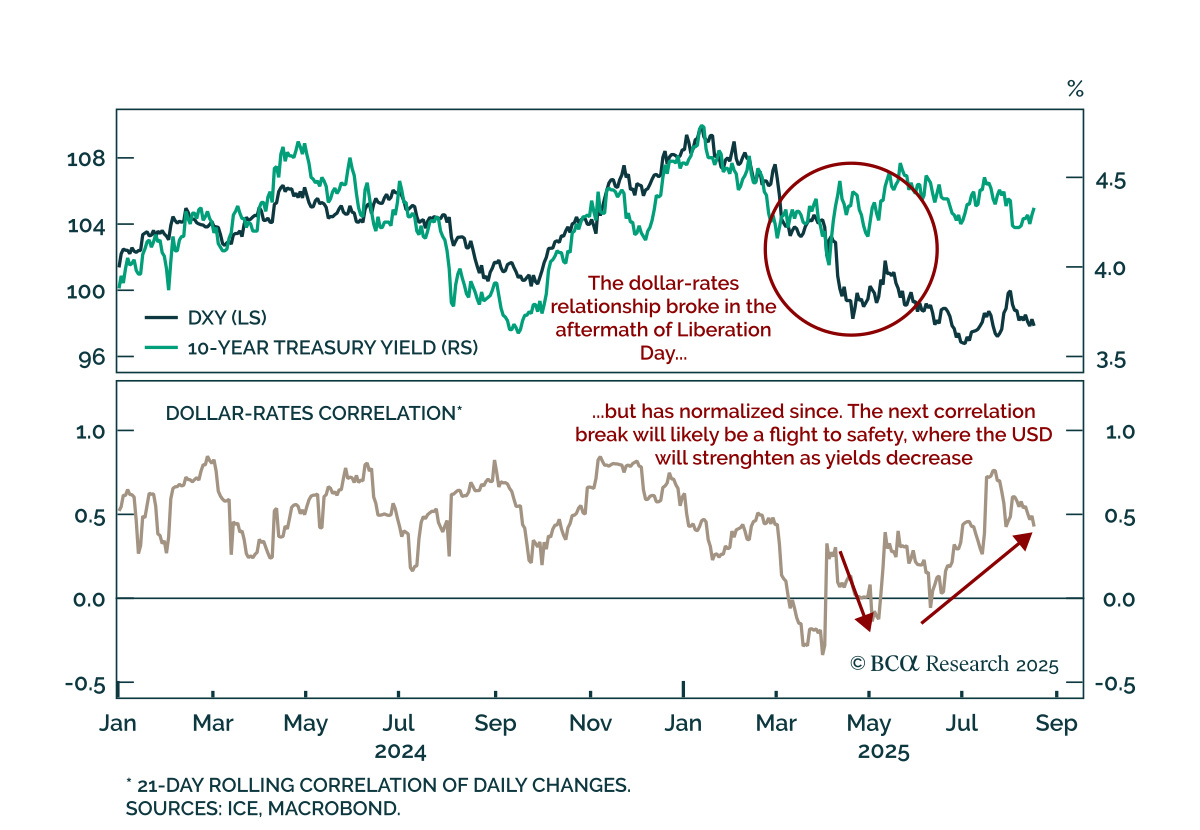
Trade tensions briefly broke the USD-rates link, but the dollar will remain a  countercyclical currency for the near future. A key 2025 trend has been USD depreciation, driven by foreign investors reducing exposure to US assets. At the peak of stress,…