 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
The window for "stealth" RMB depreciation is likely closed for now. The Chinese authorities are stepping up efforts to boost infrastructure construction with several major announcements last month. Capital spending on transportation infrastructure will likely accelerate at least through next year.
Both hawks and doves at the Federal Reserve, including Chair Yellen, have stepped up efforts to condition financial markets for a rate hike as early as June.
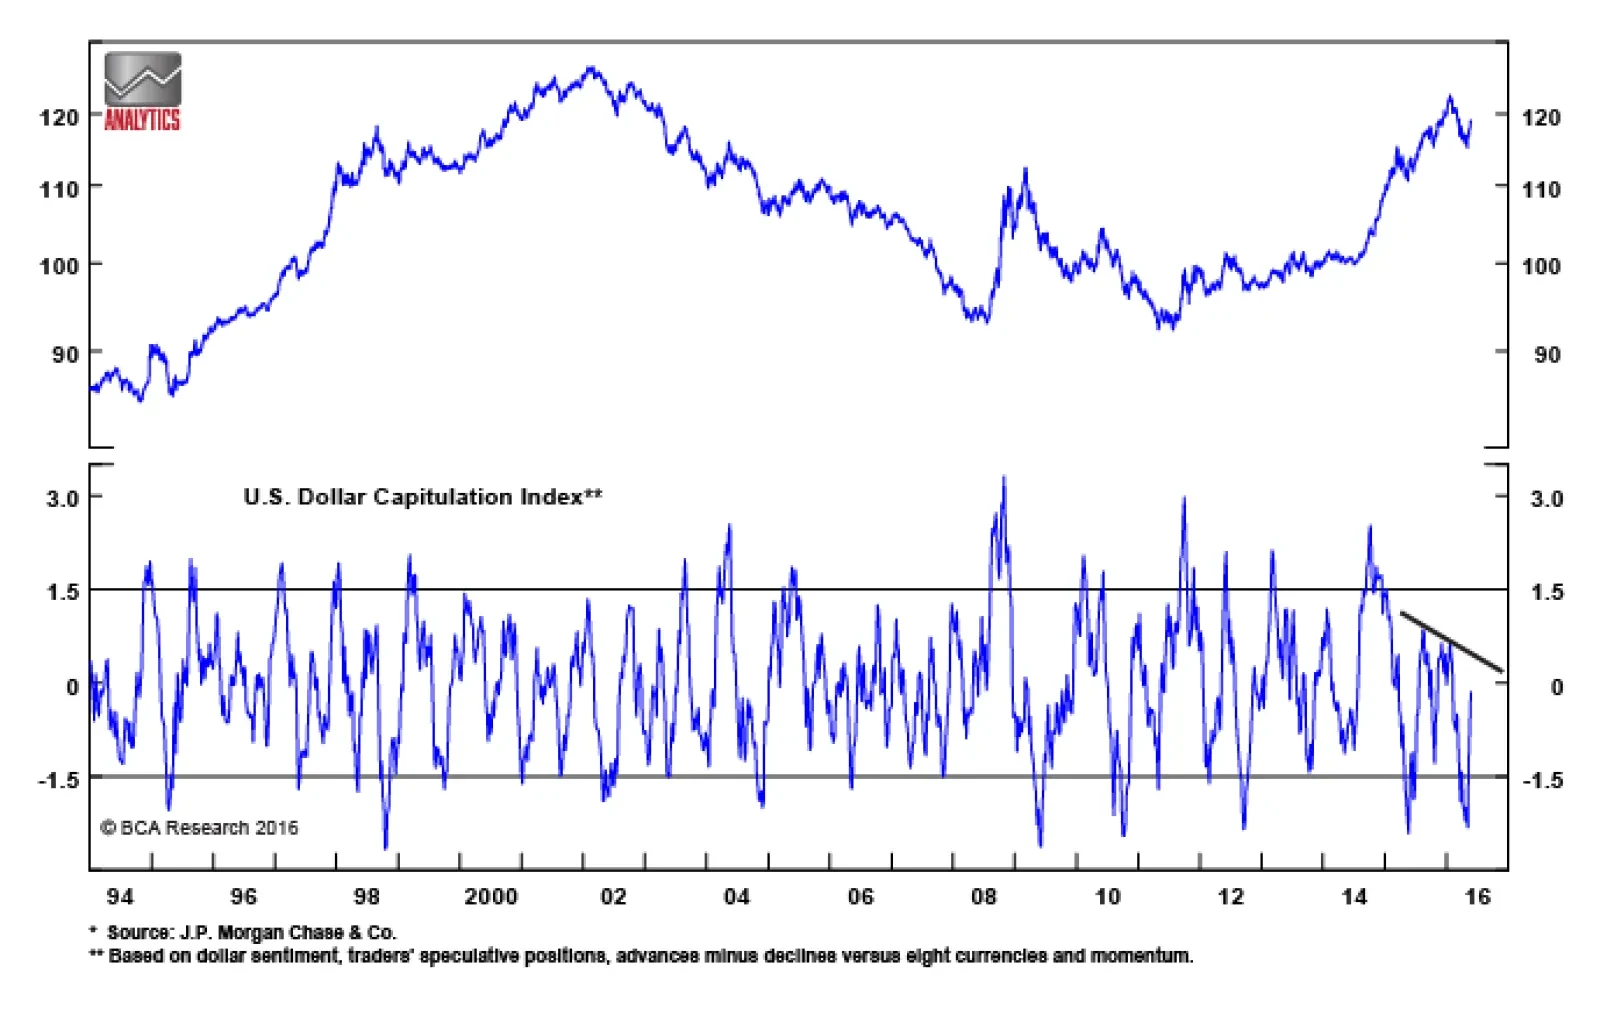
For the month of May, the model underperformed both global equities and the S&P 500. For the month of June, the model is further paring back its risk exposure.
The latest conclusions from the sector-based (right) way to pick stock markets. Plus some important conclusions for credit markets.
Risks to global growth remain to the downside. Selling pressure in cyclical markets and assets will escalate. EM currencies will make new lows versus the U.S. dollar, the euro and yen. Take profits on our long JPY/short KRW and long JPY/short SGD trades. Short KRW versus an equal-weighted basket of the U.S. dollar, yen and euro. Continue underweighting Peruvian equities.
Chinese housing construction does not look excessive relative to the size of its rapidly growing urban population. On average, China's new urban construction has been about 500 units per 1000 new urban citizens in the past 10 years, roughly comparable to other countries, and is much smaller than Korea and Japan during the prime stage of their urbanization process.
Tougher Fed talk warns that the Goldilocks combination of higher stock and bond prices in place since February is not sustainable.
China has fallen into the same "fiscal trap" that ensnarled Japan in the 1990s. Unprofitable investment projects undertaken by SOEs are a necessary evil. The underlying problem is not overinvestment, but an economy that is demand-deprived. Meanwhile, structural factors will ensure that savings remain high. Any efforts by the authorities to curb credit growth will result in a sharp economic downturn. China will continue to generate excess capacity and export deflation to the rest of the world, which is good for bonds. We recommend going long Chinese banks, the most hated equity sector.
We focus on 3 stress-points in the economy and markets which segue to several high conviction investment recommendations.