Latest from BCA Research
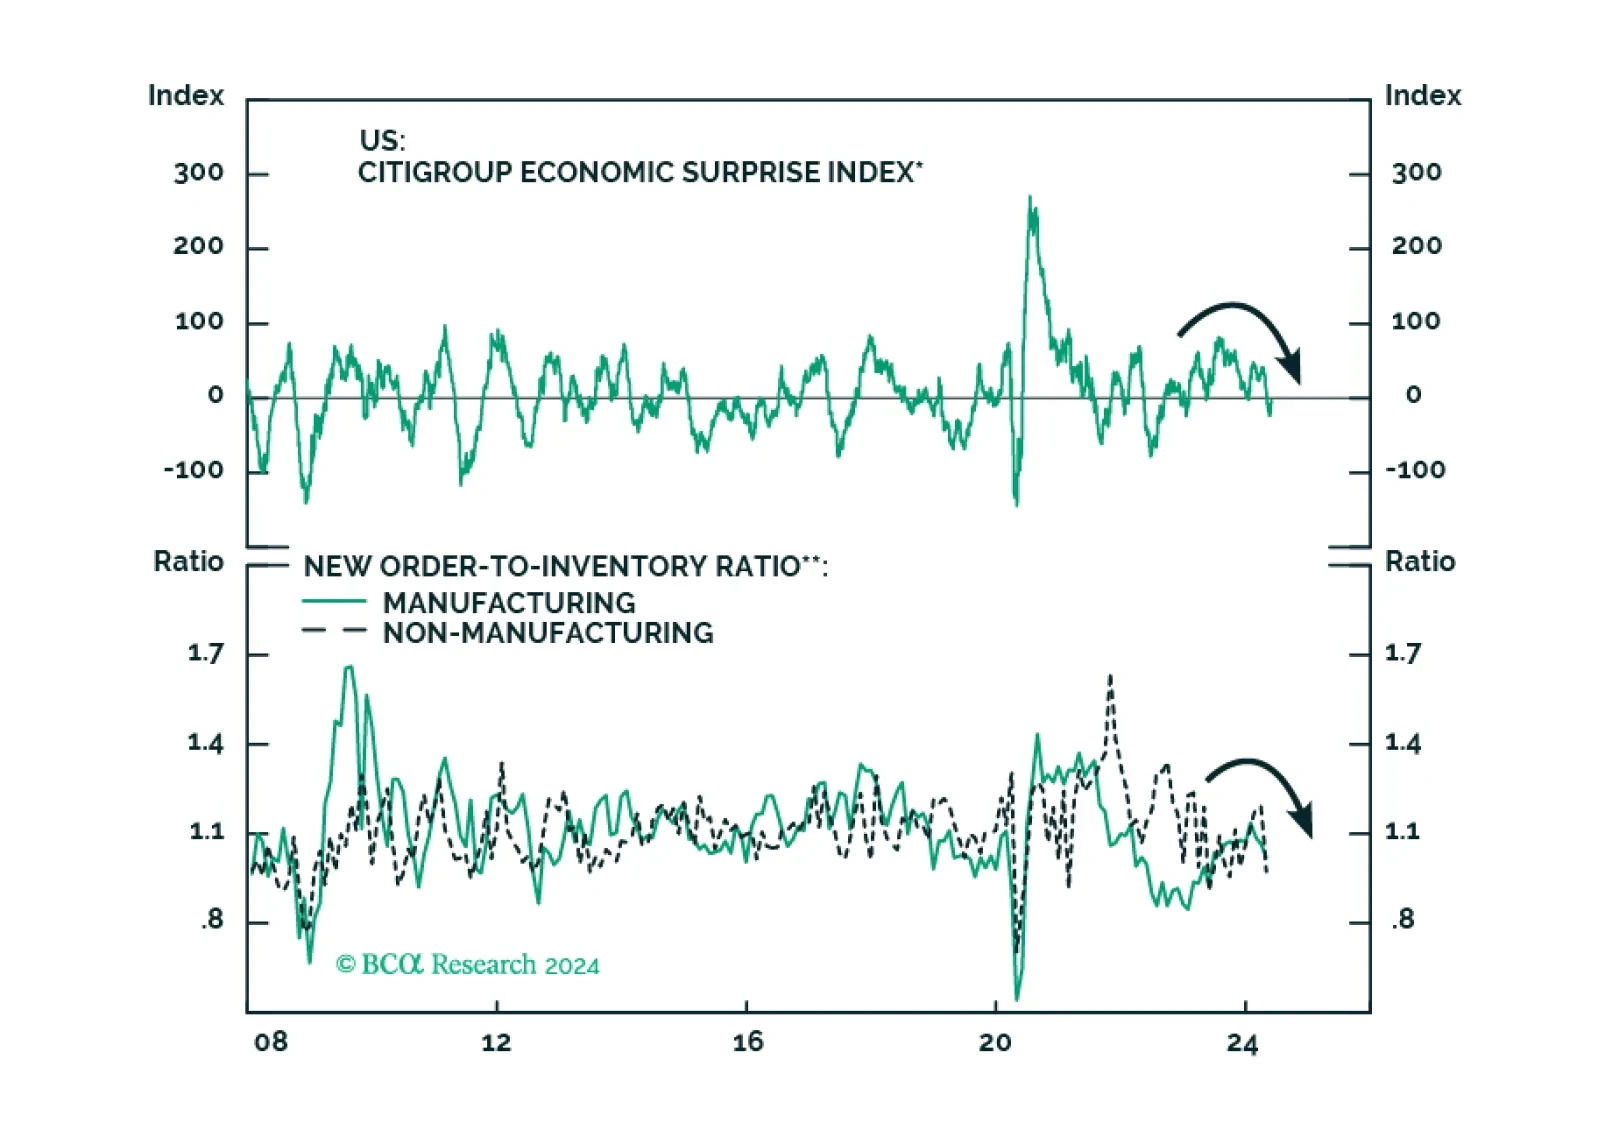
Democrats remain slightly favored for the White House because they are the four-year incumbent presidential party and the economy is not in recession. But if the unemployment rate rises in the lead up to November, then Biden and Democrats will become disfavored regardless of Trump’s convictions.
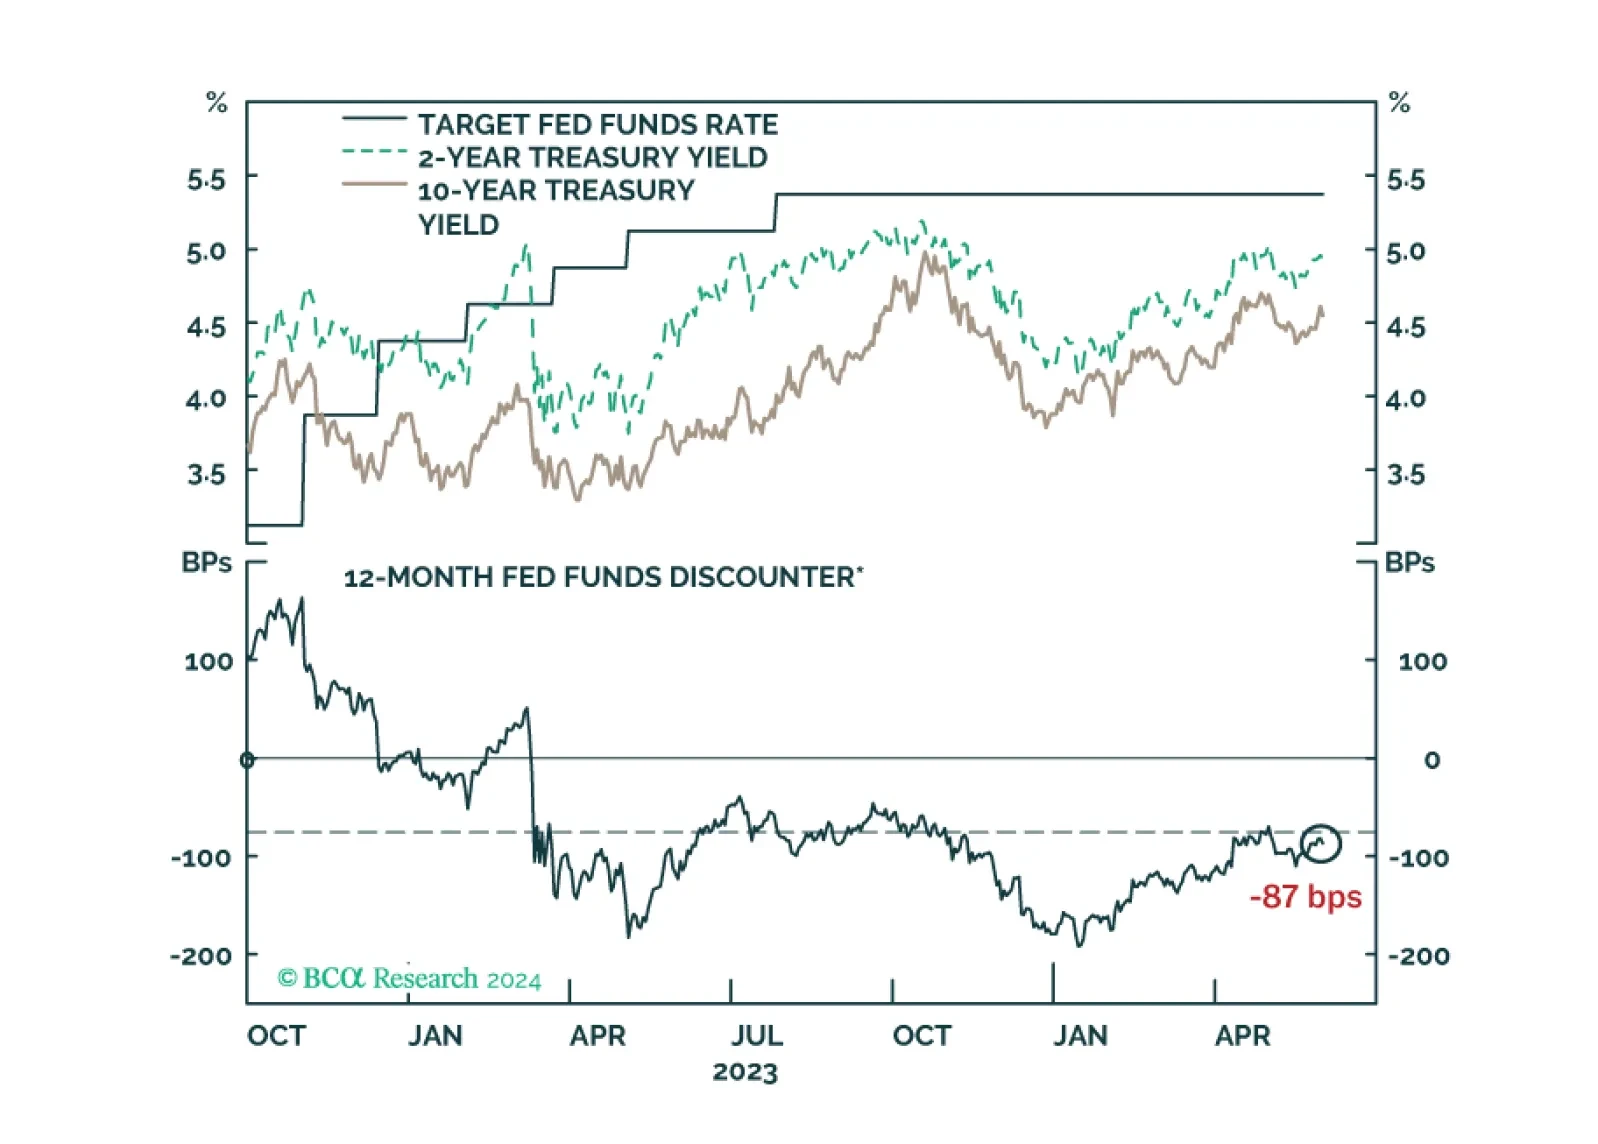
We comment on whether Treasury market valuation is sufficiently attractive to get long bonds and consider some of the common arguments for why yields may yet make new highs.
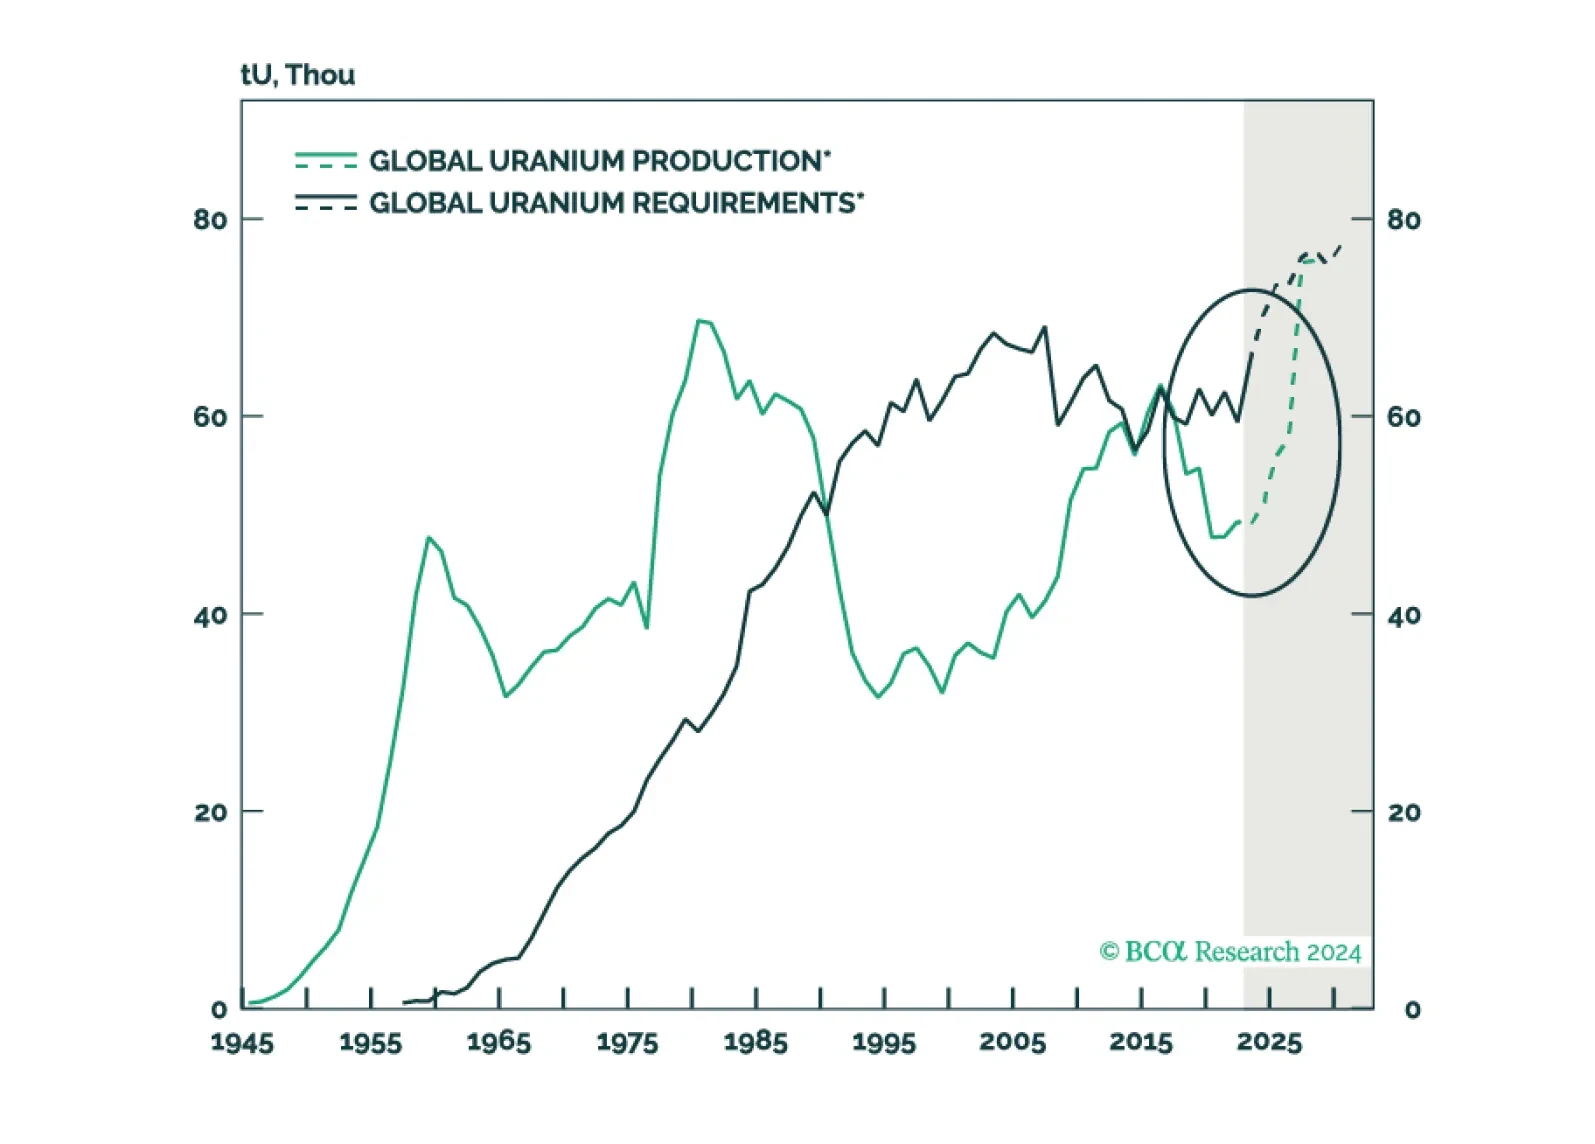
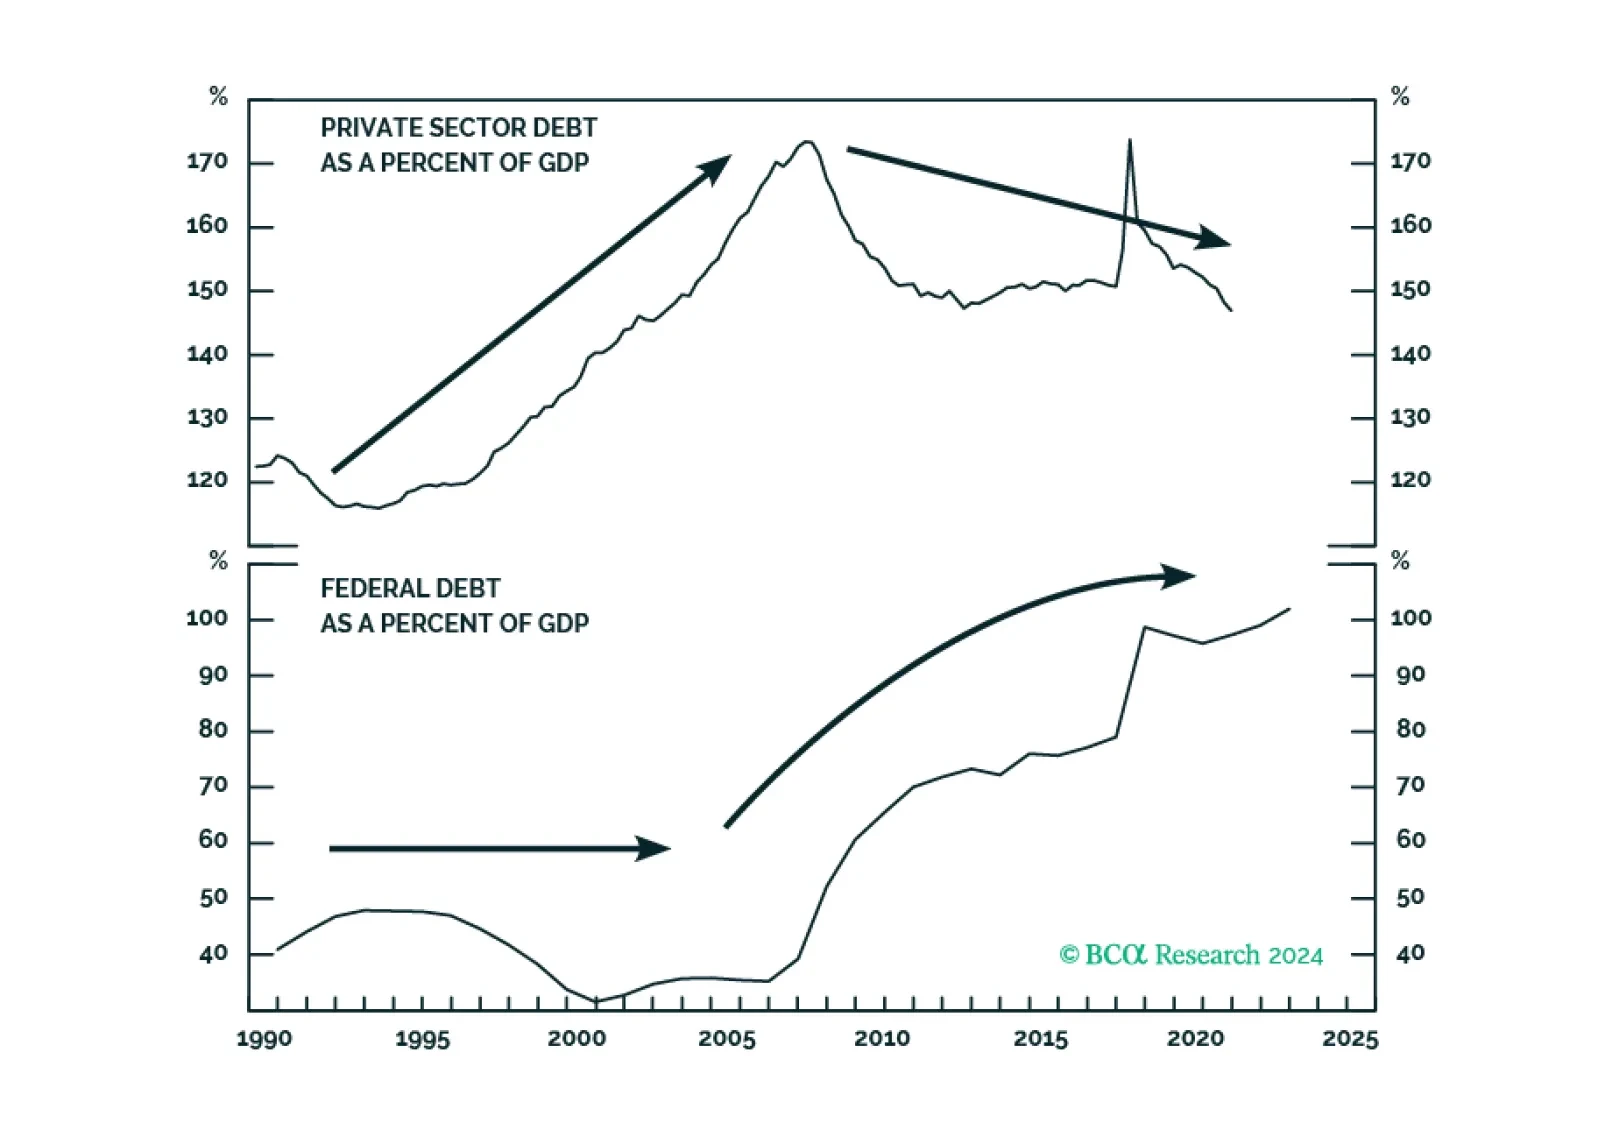
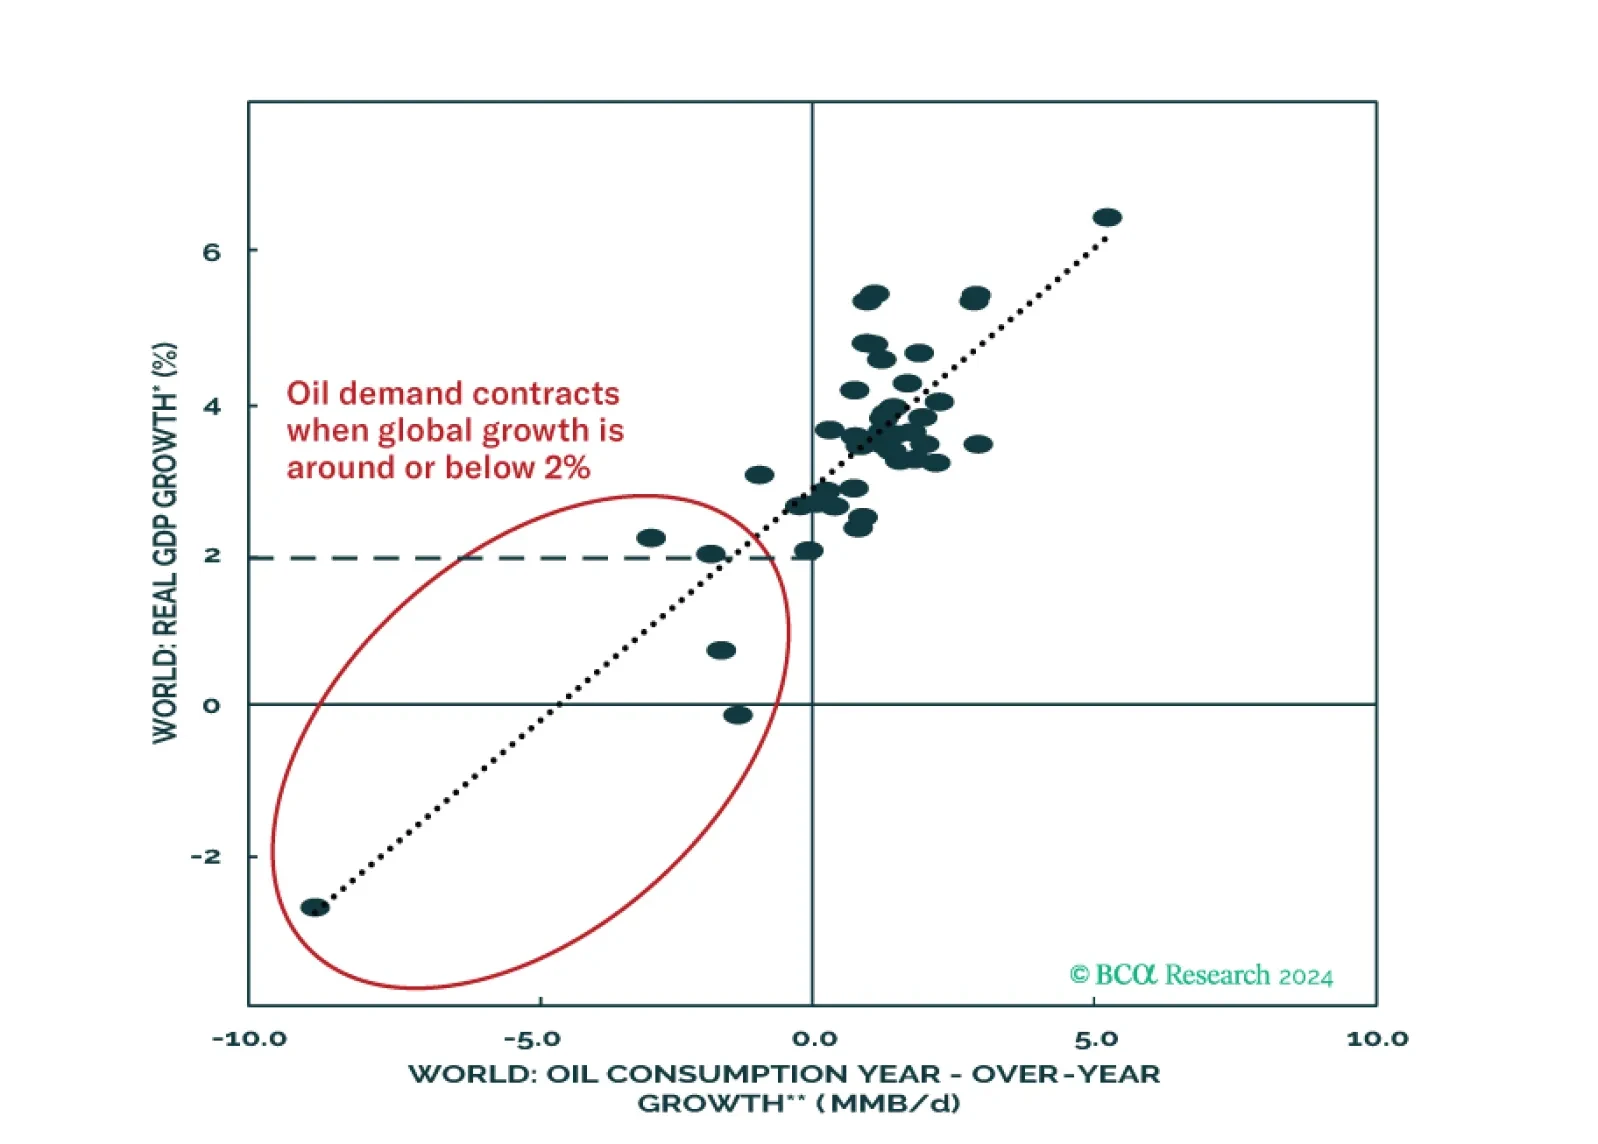
The three major oil forecasters – IEA, EIA, and OPEC – are forecasting oil demand growth until 2025 to be broadly in line with its range over the past four decades. On a cyclical horizon, we give high odds that a recession will begin within the coming 6-12 months, disappointing these oil demand forecasts. On a strategic horizon, the IEA projects EVs will displace 9% of global oil demand by 2035, serving as a long-term demand headwind.
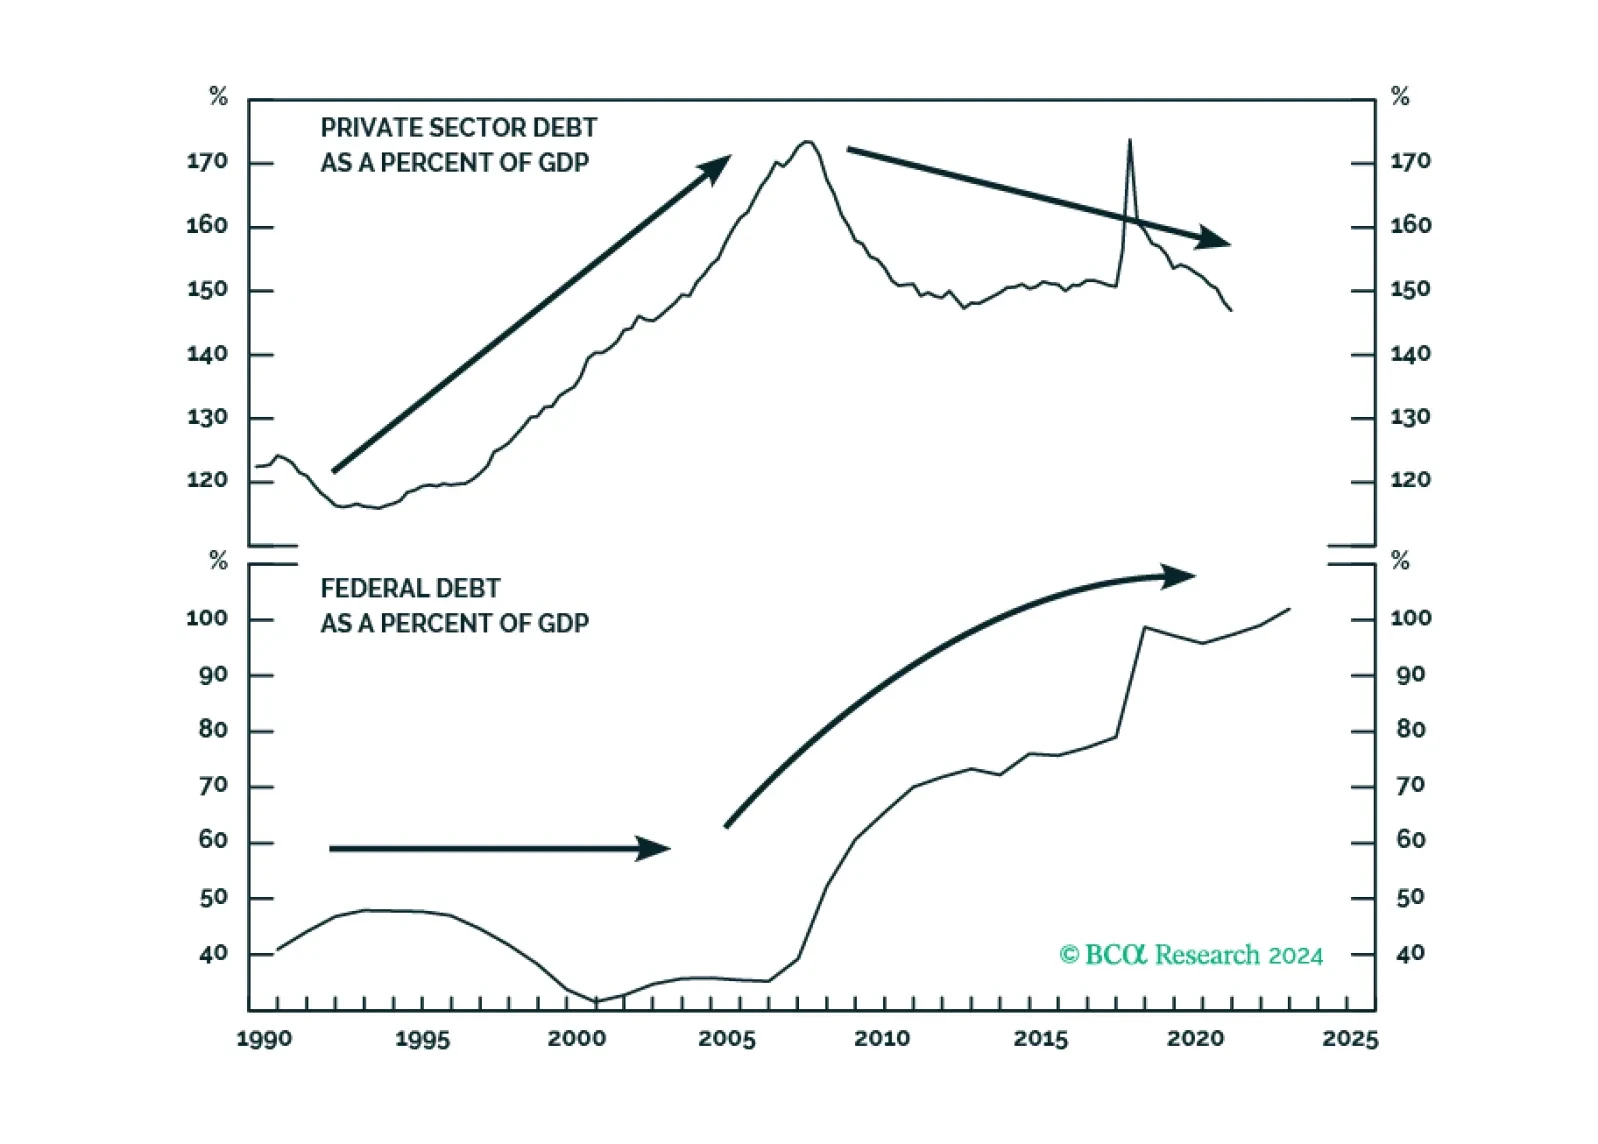
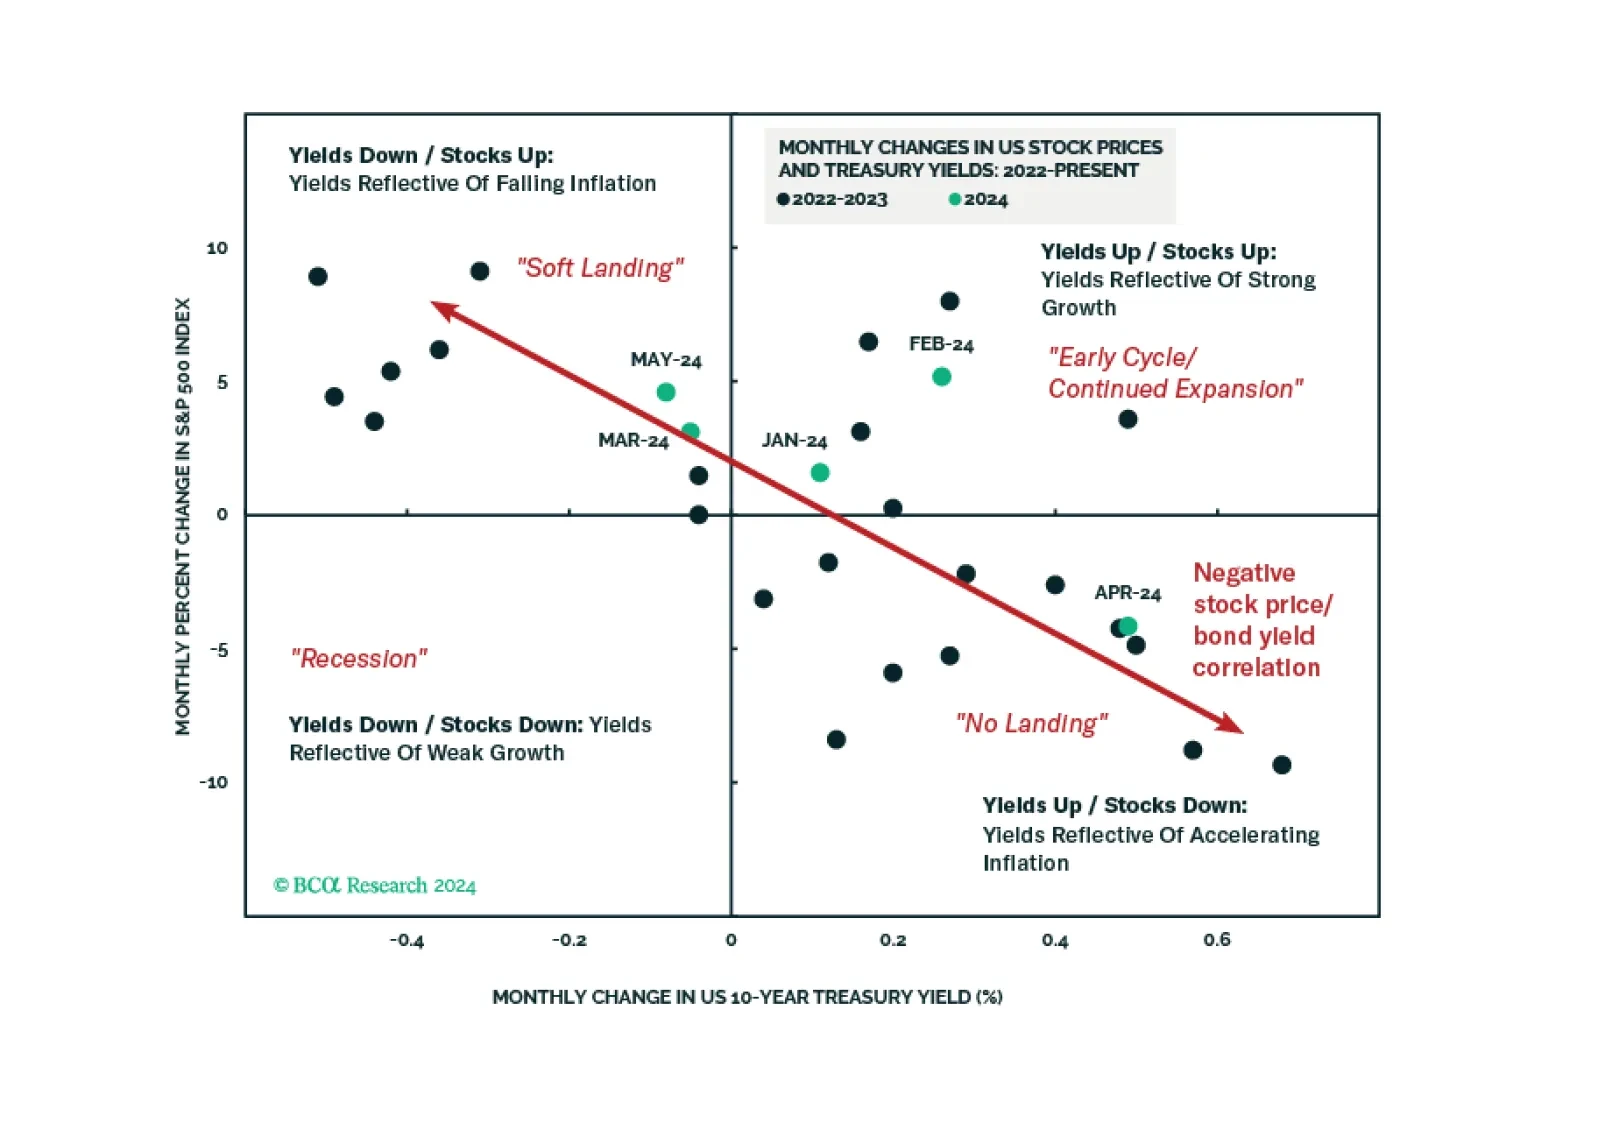
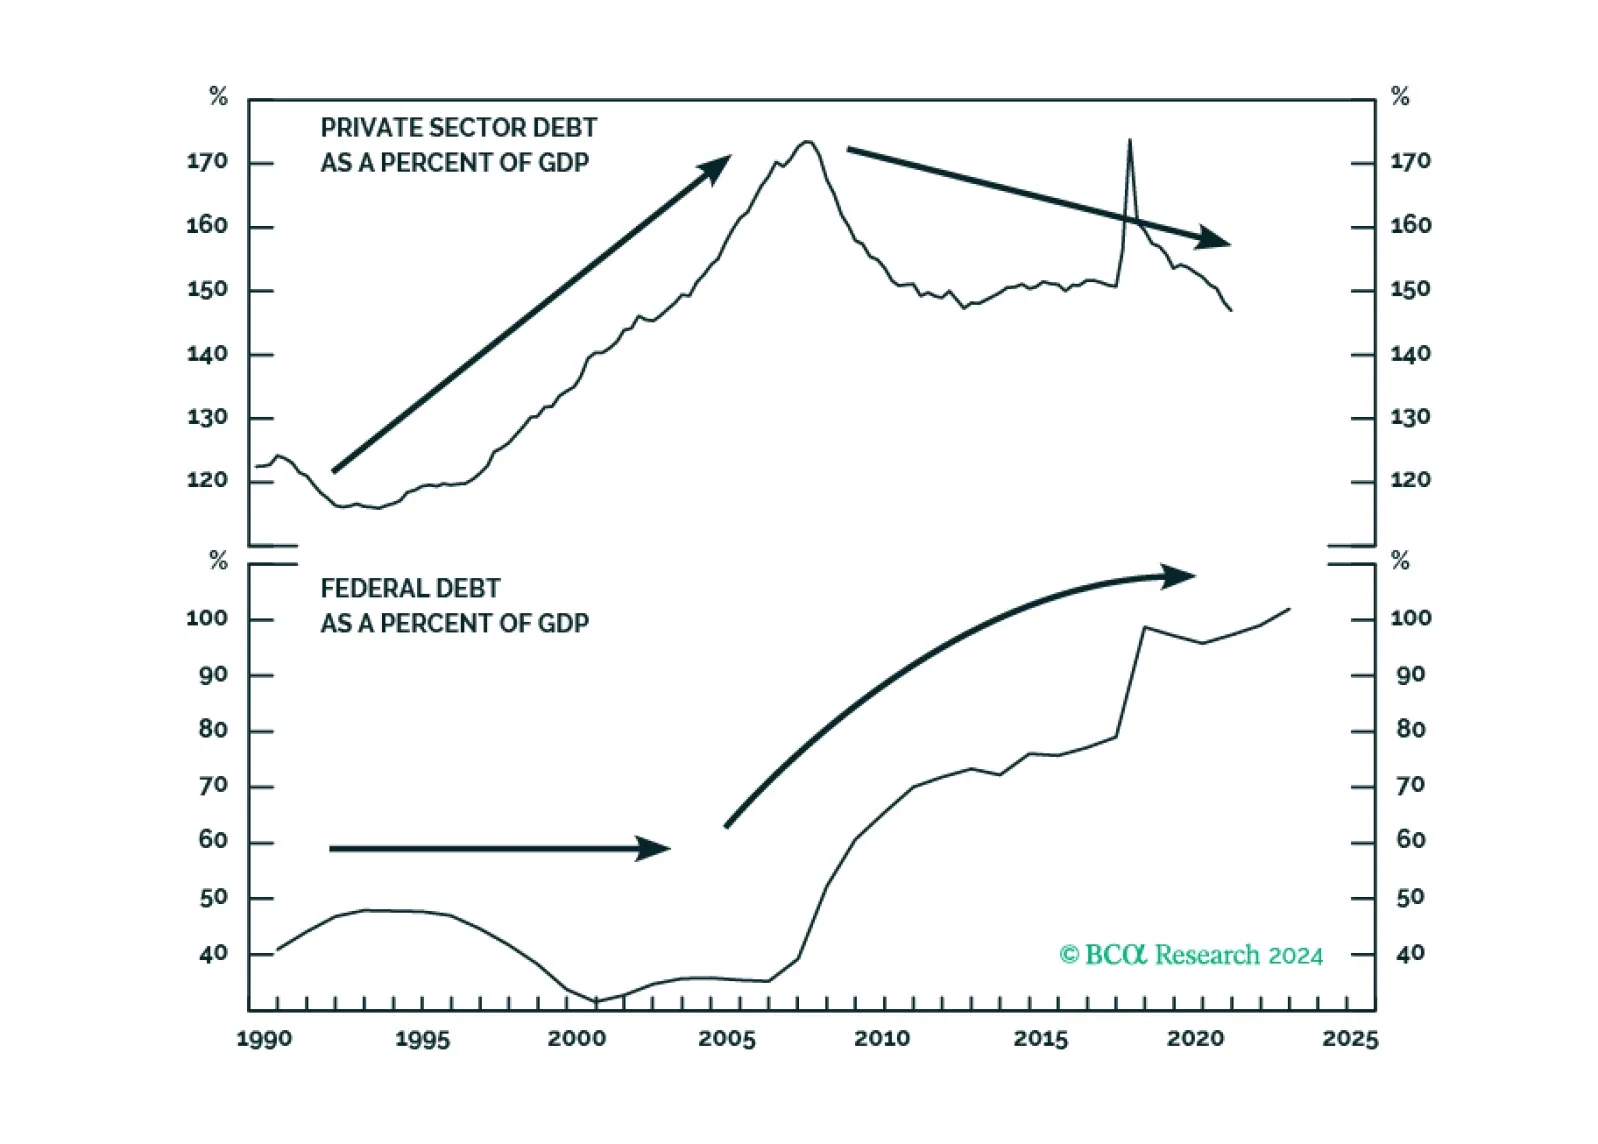

Favor defensive sectors, low-beta assets, and long-duration bonds until the election uncertainty is lifted one way or another over the next five months.
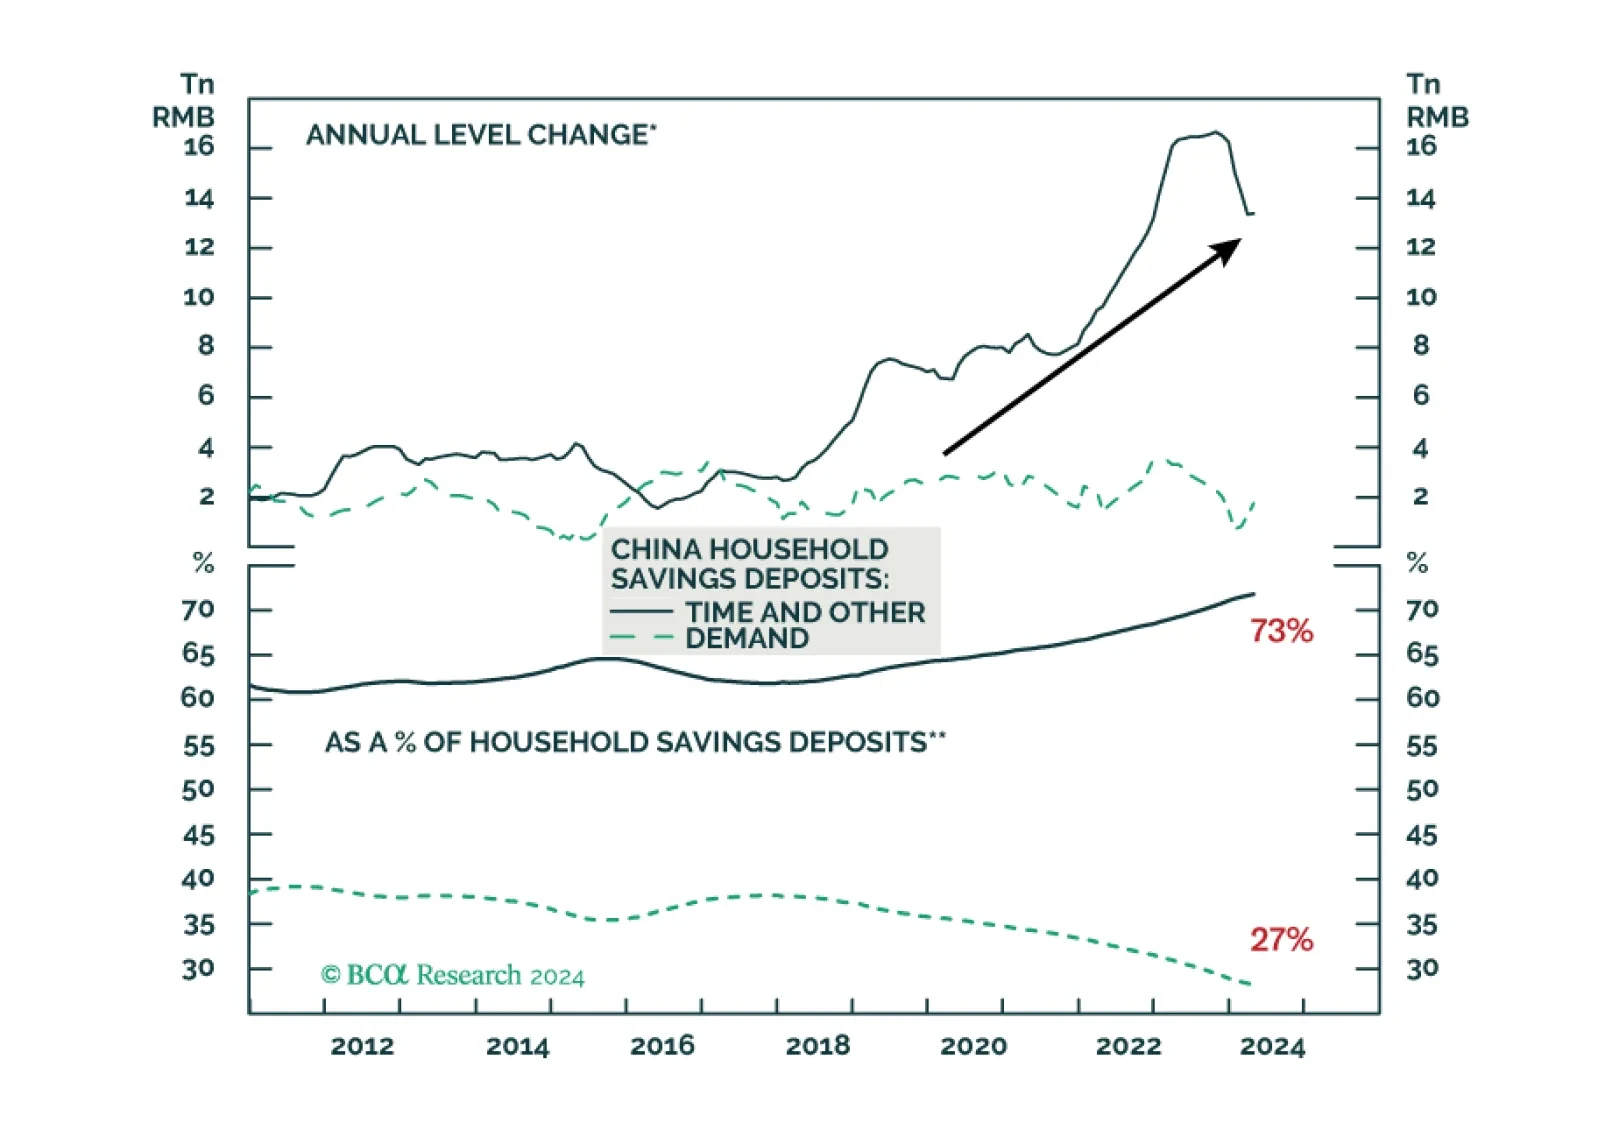
The large buildup in Chinese households’ savings deposits is unlikely to fuel consumption. Poor outlooks on labor market conditions, income, and households’ unwillingness to borrow will hinder consumption through the rest of 2024.