Latest from BCA Research

Our Portfolio Allocation Summary for October 2024.

The politically induced selloff in Mexican markets has gone too far. In our view, investor fears about the constitutional changes are largely unwarranted. These reforms will have little to no ramifications for the economy in the foreseeable future, and it is not clear to what extent they can undermine Mexican democracy. Moreover, the market riot is not justified by the country’s decent macro shape. All in all, Mexican markets will resume their outperformance versus their EM peers sooner rather than later.
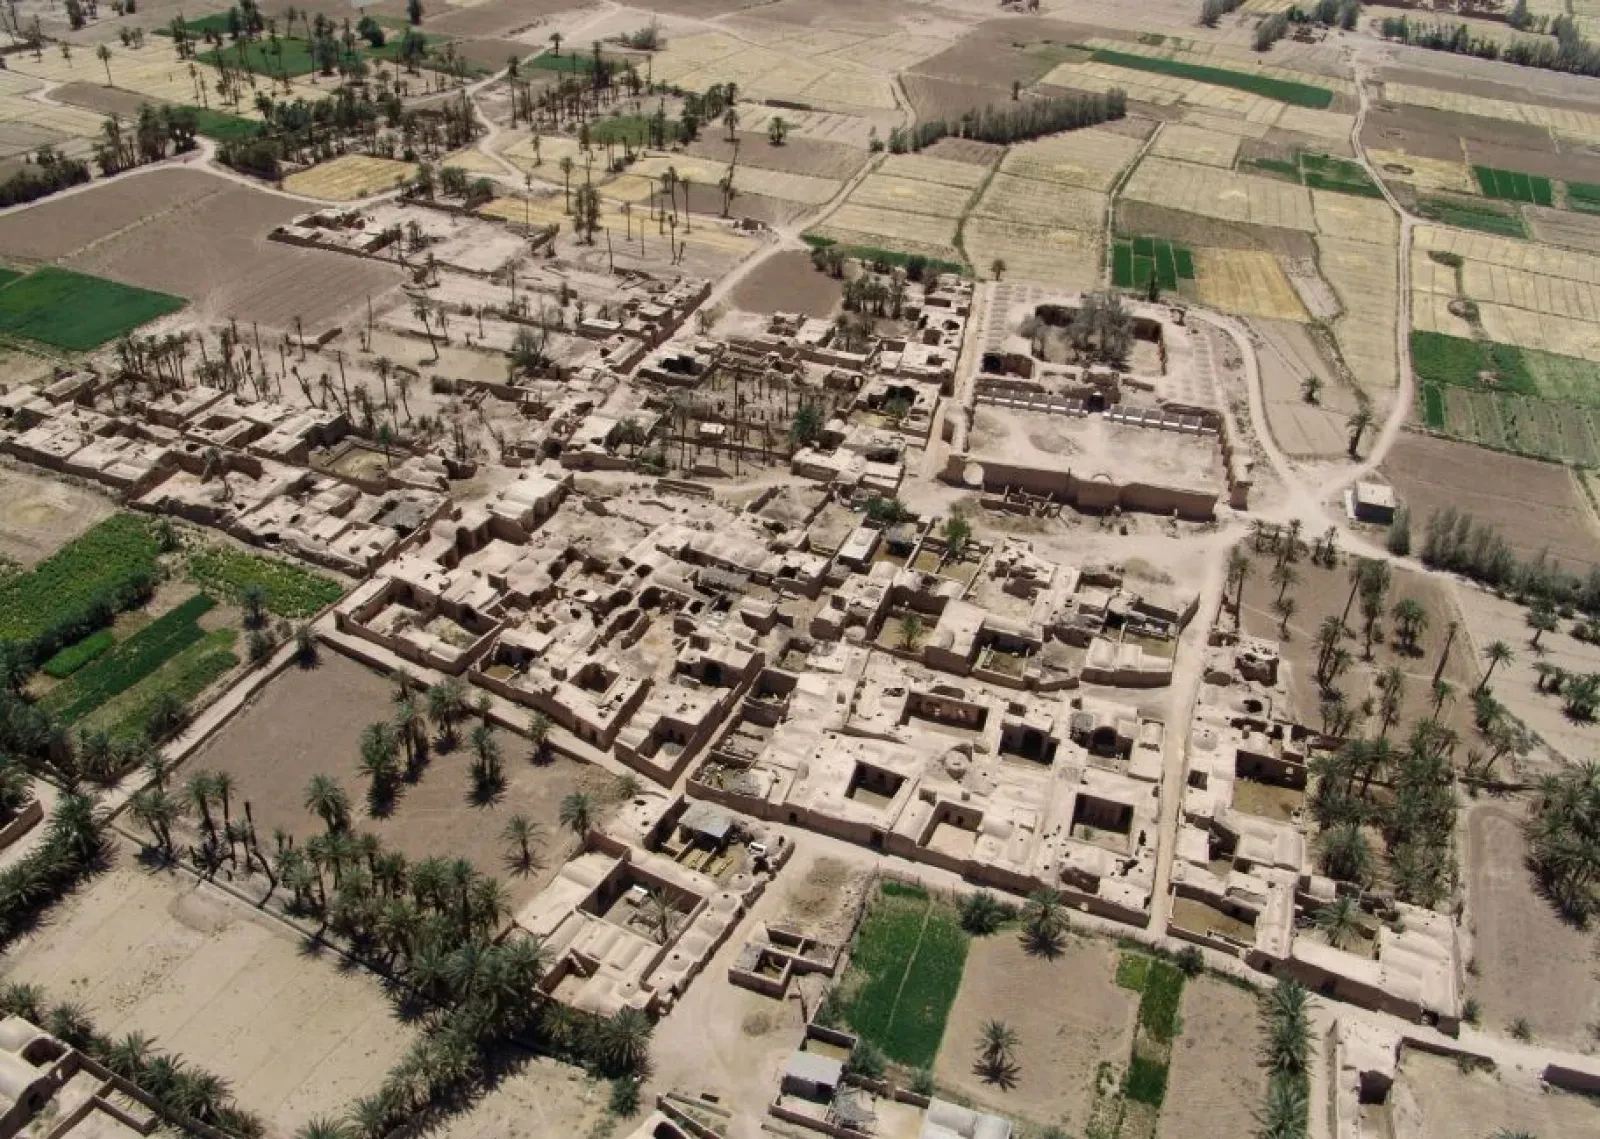
Iran has launched a salvo of ballistic missiles towards Israel on October 1 in retaliation for Israeli ground invasion against Lebanon. Thus far, the attack looks to be a bit different from the attack in April, with ballistic missiles making up the bulk of the reported projectiles. This means that the emphasis on drones, which were highly unsuccessful, has been replaced with an emphasis on missiles.
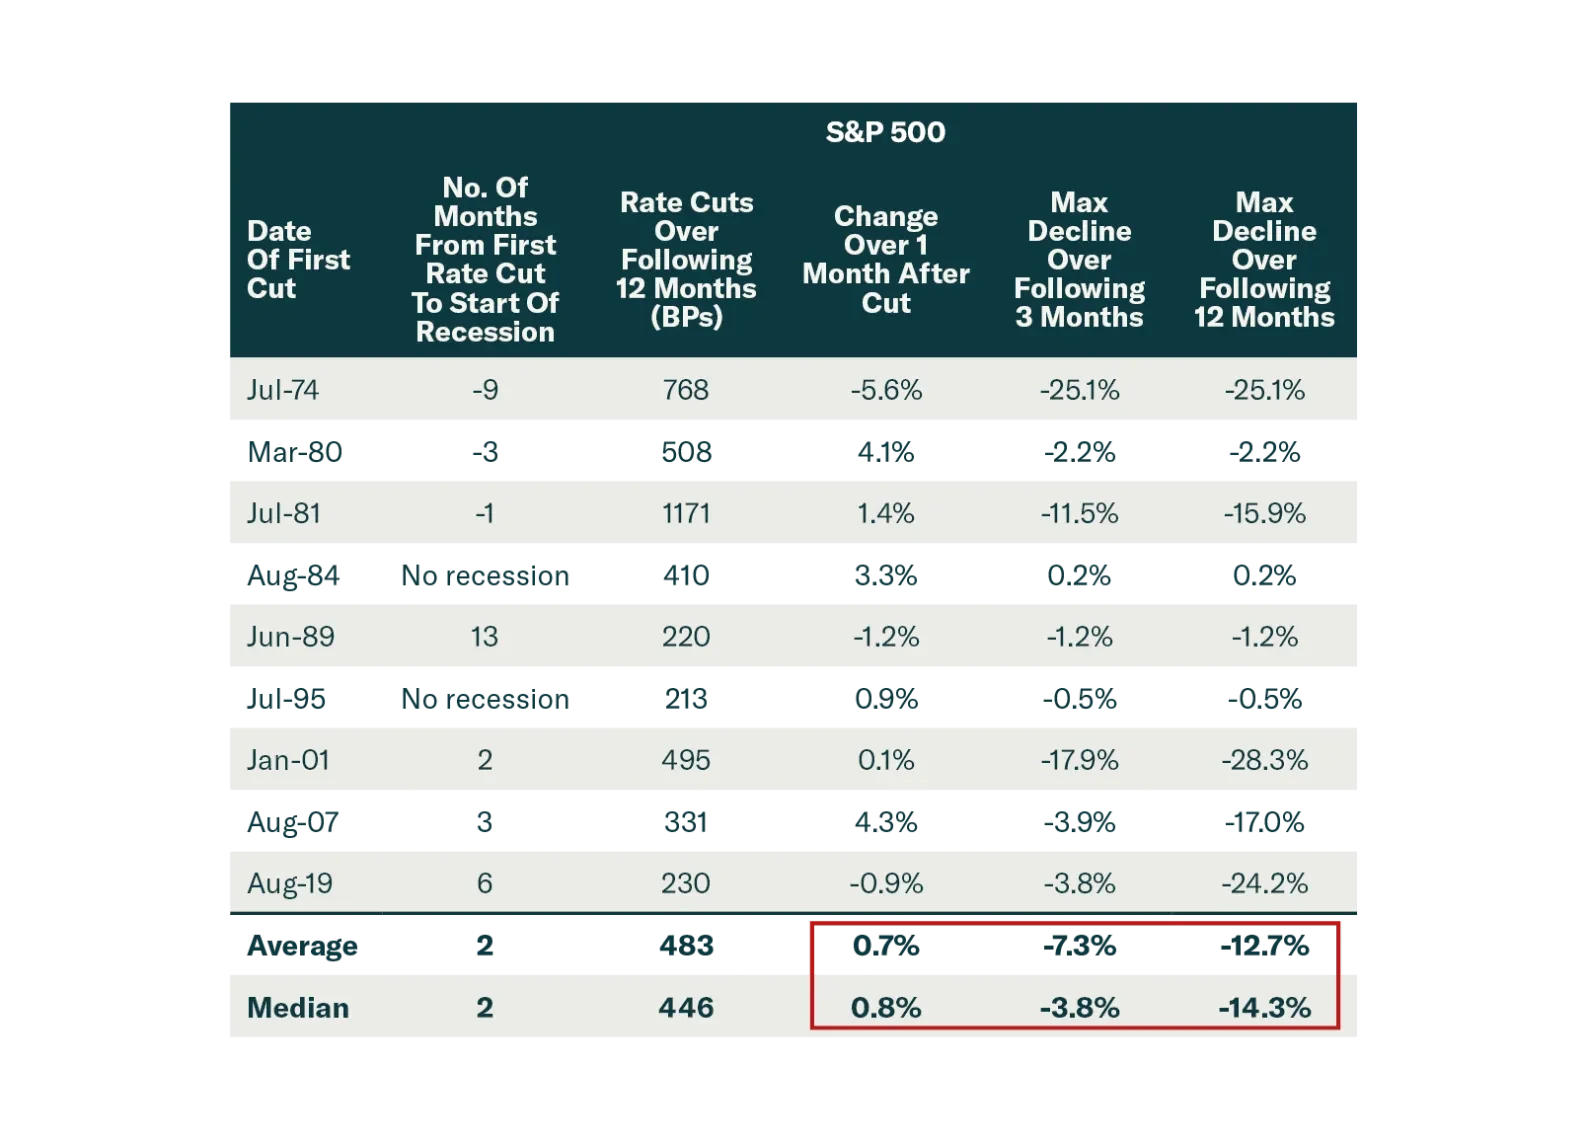
The market got excited by the 50 bps Fed cut and China stimulus. But these are a recognition that economies are slowing significantly. Stocks often rally after the first Fed cut, before falling sharply. Investors should stay defensive.
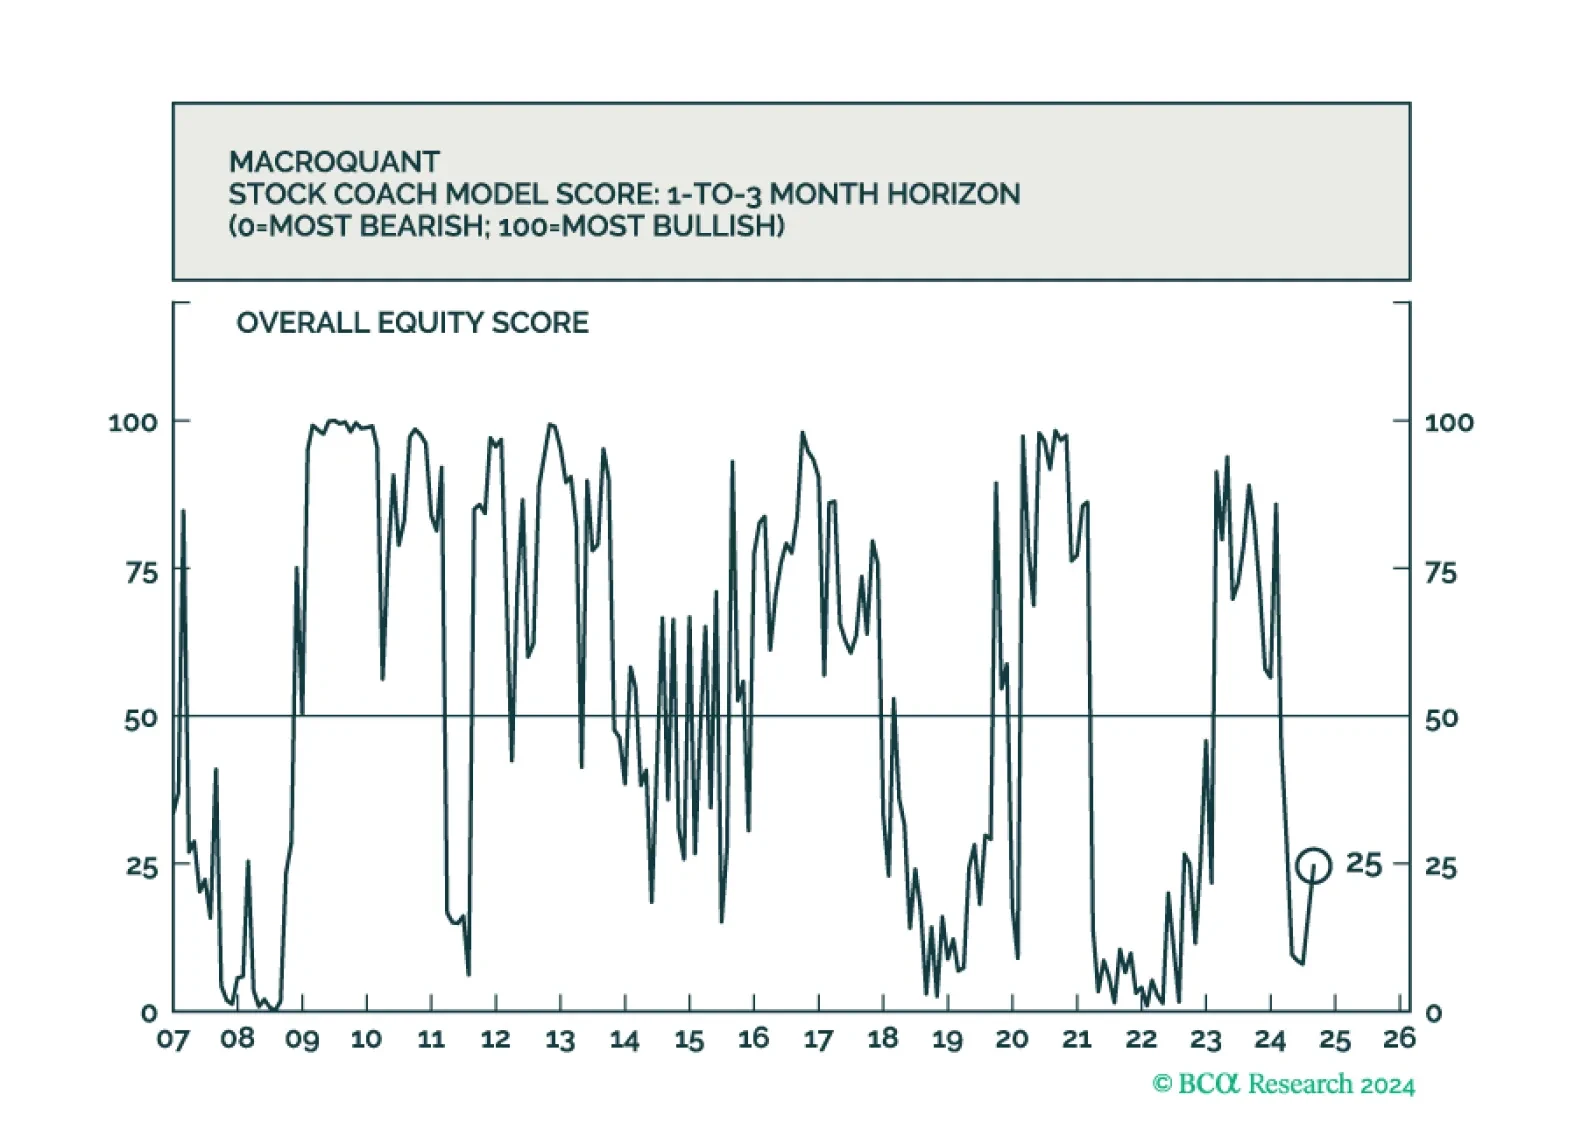
Despite the recent easing in financial conditions and hopes around Chinese stimulus, MacroQuant sees a heightened risk that the US will fall into a recession over the next 12 months. As such, it recommends an underweight to stocks, counterbalanced by an overweight to bonds.
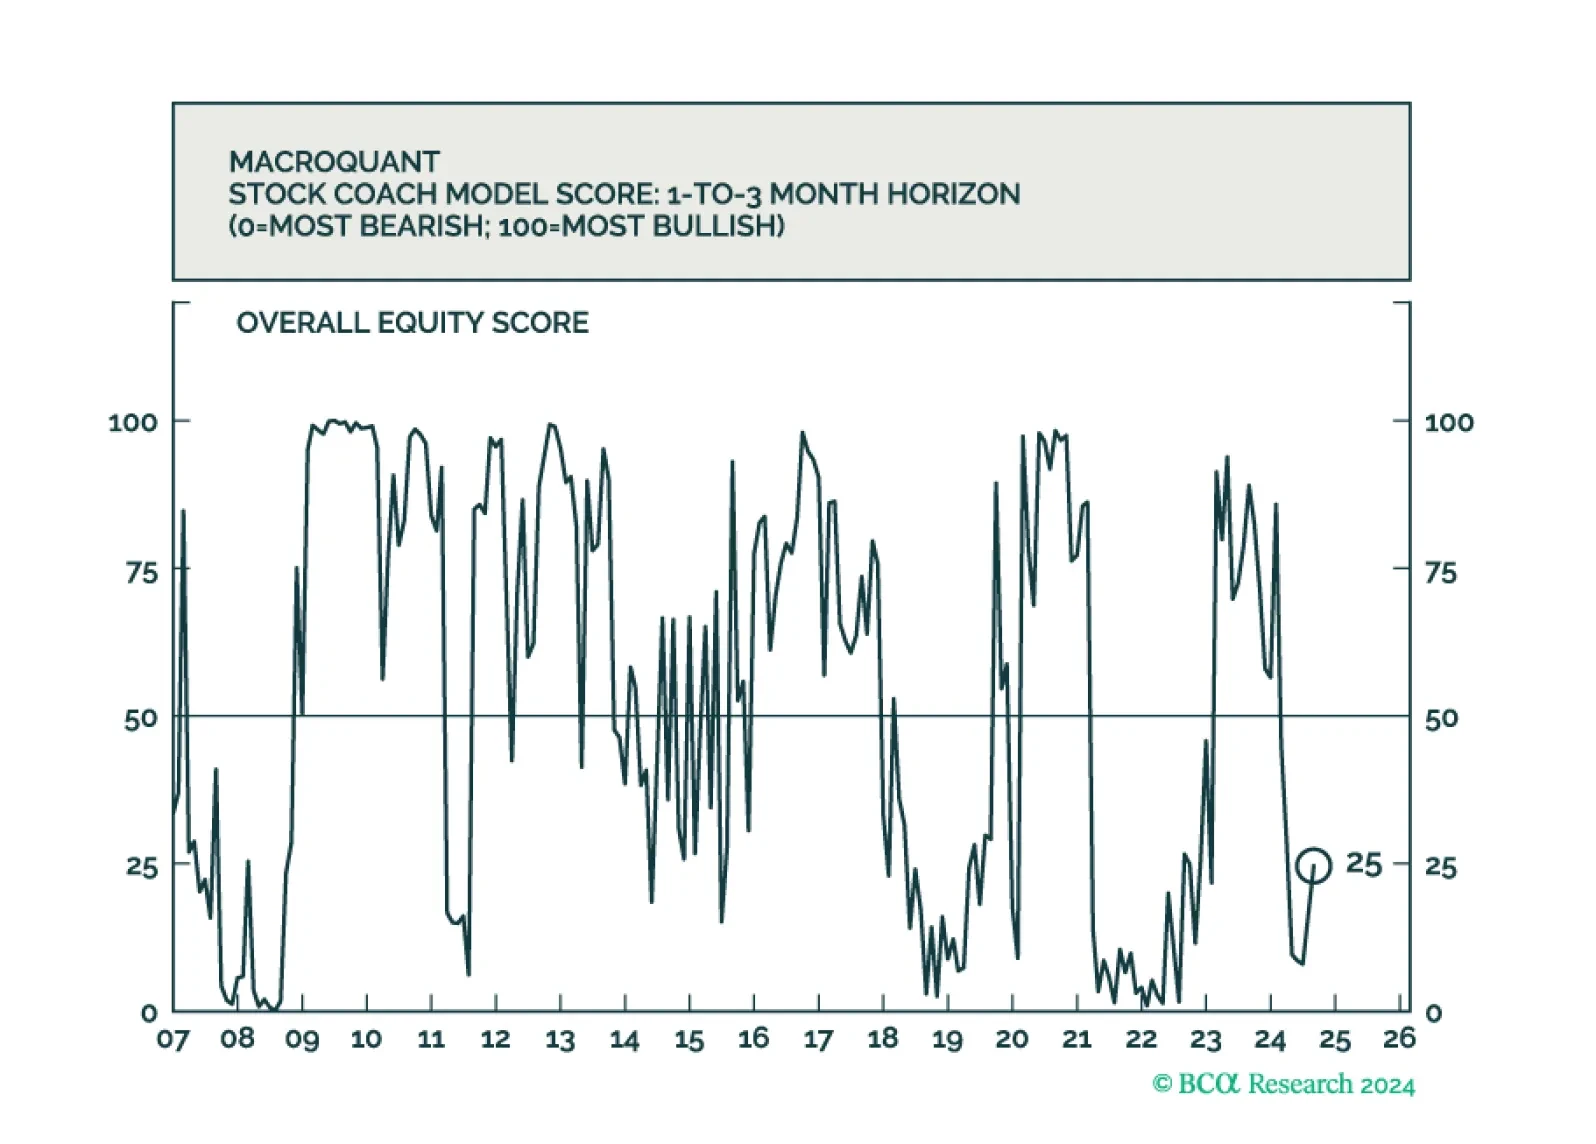
Despite the recent easing in financial conditions and hopes around Chinese stimulus, MacroQuant sees a heightened risk that the US will fall into a recession over the next 12 months. As such, it recommends an underweight to stocks, counterbalanced by an overweight to bonds.
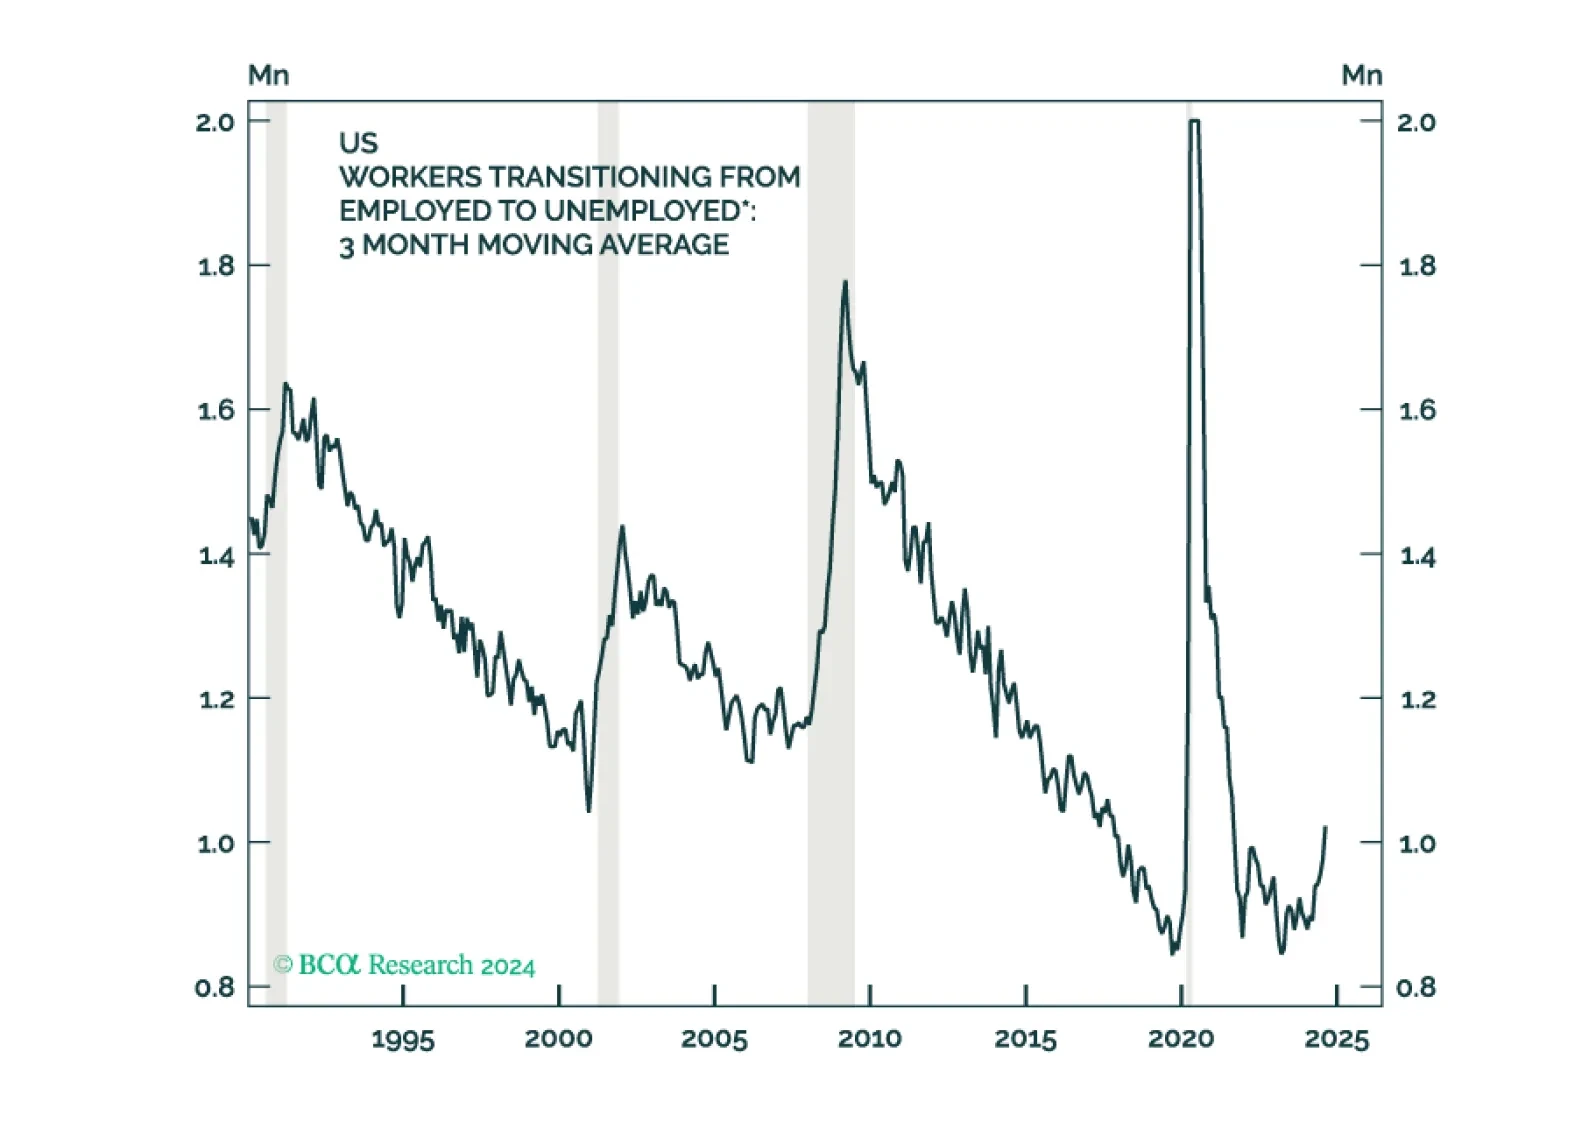
Back in 2022, when Jamie Dimon was predicting an economic hurricane, I was one of the few strategists reassuring clients that the US was not at imminent risk of a recession.