 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
Near-term, global yields will remain depressed, but the structural forces suppressing yields should abate and even reverse in the long-run. Slower potential GDP growth - and lower commodity prices - will eventually shift from tailwind to headwind for bonds. Stepped-up efforts to increase inflation will boost long-term nominal yields; populist politics and calls to curb income inequality will amplify this trend. Long-term investors should stay neutral global bonds for now, but prepare to shift to a structural underweight beyond this decade.
Are the arguments for overweighting European equities still valid? If so, overweighting relative to what?
Beyond the ongoing short-term rebound, EM currencies have more downside, and will depreciate by more than is implied by their forward rates on a 6-9 month horizon. This makes us reluctant to recommend buying local currency bonds to absolute-return investors. A new trade: Long Russian/short Malaysian equities. We also reiterate our short MYR/long RUB trade.
China will neither propose nor support any coordinated initiatives among central banks on the RMB issue in G20 meetings this year. RMB bonds will prove attractive to foreign investors, given their higher yields and lower exchange rate volatility.
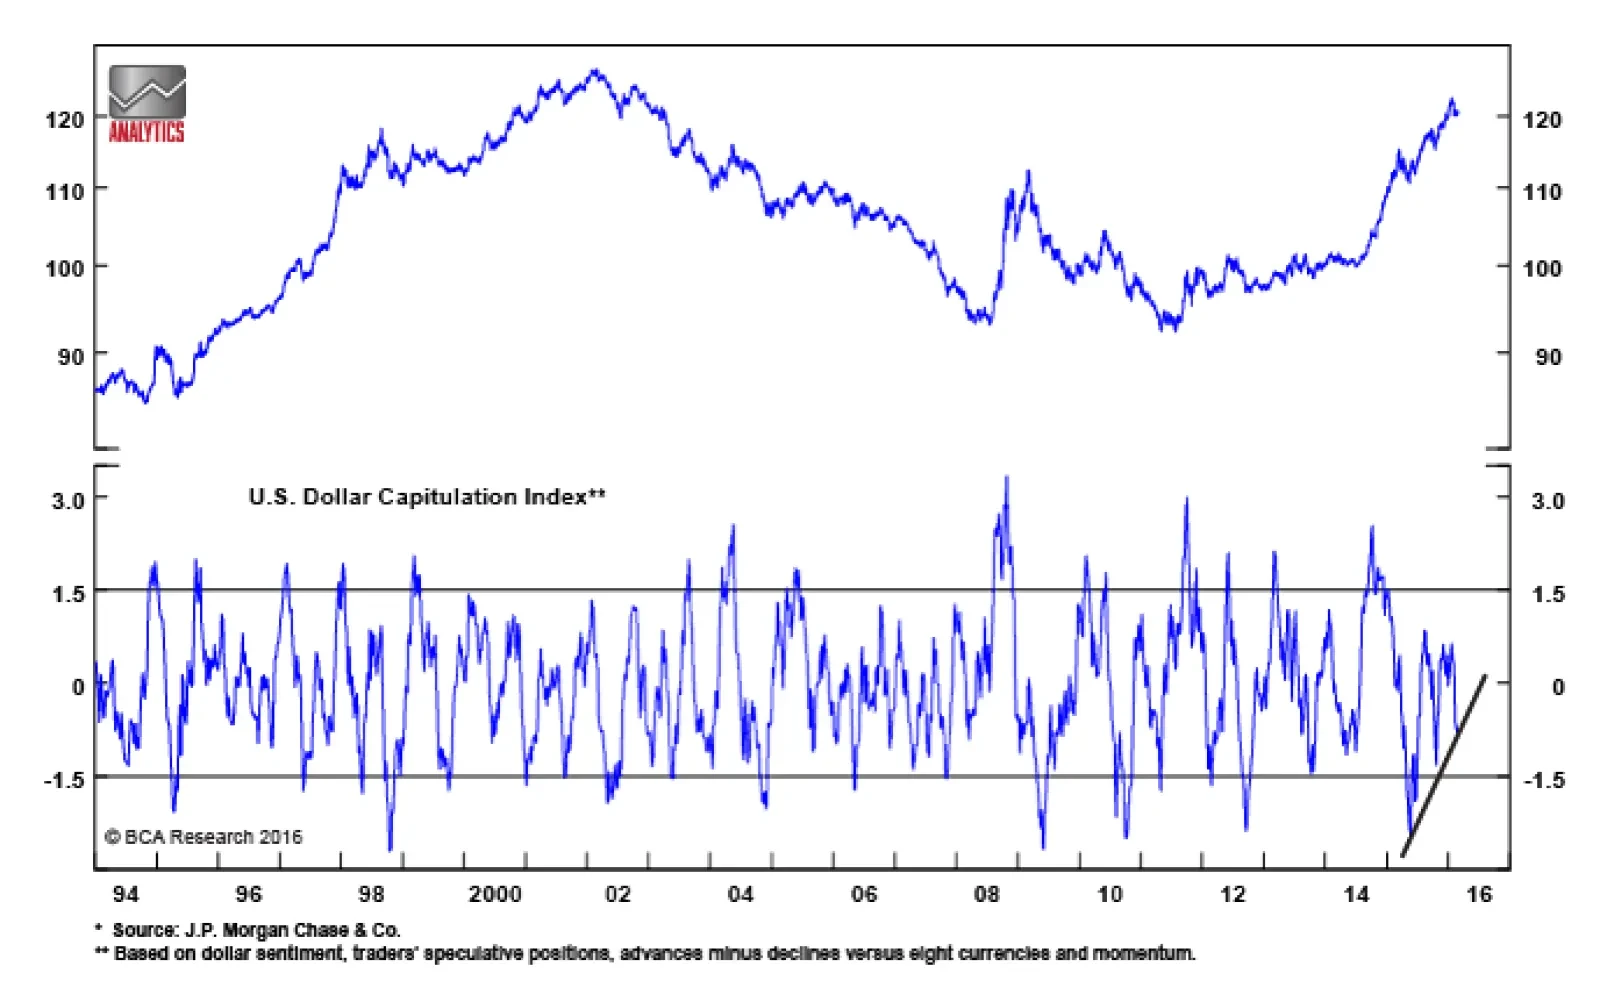
For the month of February, the model underperformed both global and U.S. equities. For March, the model has modestly pared back its equity risk exposure, shifting the allocation into bonds. While Europe remains the largest equity overweight, EM and Canada also received some allocation. The U.S. and New Zealand were slightly downgraded. In the fixed-income space, the model is sticking with Italy and Spain.
Where is the most likely mispricing of interest rates today? Plus our latest thoughts on the U.K.'s June 23 referendum on EU membership, and its market implications.
The Chinese authorities are stepping up coordinated efforts to boost the economy. There has been a clear shift of policy focus from the "supply side" reforms to "demand side" management. Quickening credit creation bodes well for industrial activity, the hardest hit sector in the ongoing growth slowdown.
Credit growth acceleration in China is a bearish development in the long run. Potential non-performing loans at Chinese banks could wipe out 40-55% of their equity capital. "Muddling through" for China, from its own internal standpoint, is possible. However, Chinese stocks and China-related equities worldwide will remain in a bear market. From the perspective of the rest of the world, China is now in recession.