 CoreMacro
BCA’s flagship global macro and investment strategy platform, helping investors anticipate regime shifts, connect signals across regions and asset classes, and navigate the world’s most difficult macro questions.
We discuss the technical and political problems with helicopter money, plus the near-term outlook for the euro area economy and markets.
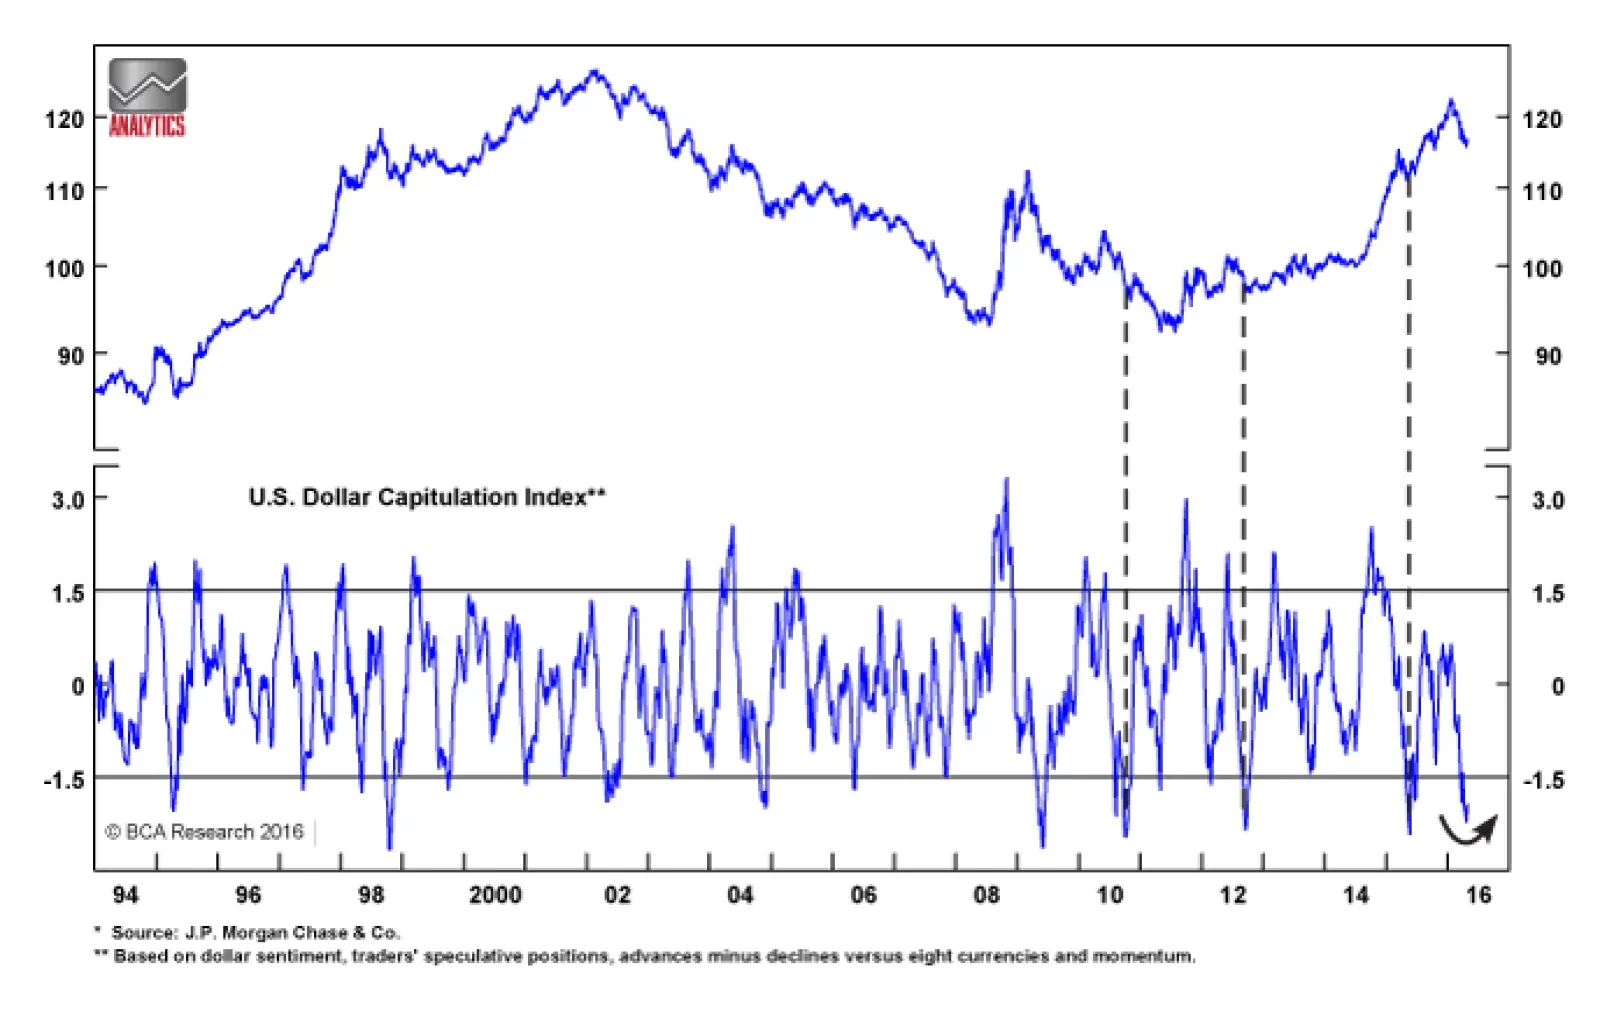
Profits are bottoming but the outlook is lackluster, even if further dollar weakness provides a temporary boost.
For the month of April, the model's performance was in line with the S&P 500, but lagged global equities. For May, the model is aggressively paring back its equity risk exposure. Both Europe and Emerging Markets were downgraded, but still possess the lion's share of the equity allocation, while defensive markets such as the U.S. and Switzerland received a boost. In the fixed-income space, U.S., Italian and Spanish paper were the model's favorites.
The Fed's statement underscored its 'go slow' approach, with a June hike increasingly unlikely, but September and December still in play. The BoJ stood pat, reluctant to admit that NIRP was a flop soon after it was launched. Nevertheless, we expect fresh easing this summer. Chinese stimulus should last a few more months, but commodities will resume their structural downtrend thereafter. Remain tactically bullish risk assets; be prepared to turn more cautious in Q2.
Policy easing works with a time lag, and the previous easing measures should continue to feed through to business activity. The recent decline in the trade-weighted RMB should lead to continued improvement in the industrial sector's performance for at least the next two quarters.
How big a problem are the non-performing loans in Italy and Greece? And what is the solution?
The near-term (next month or two) market dynamics in EM risk assets remain a coin toss. Beyond that the outlook for EM risk assets remains downbeat. EM financial markets are complacent and there are many potential negative EM/China developments that could derail the current EM rally. A new trade: go long the KOSPI / short EM overall equity index.