Tariffs
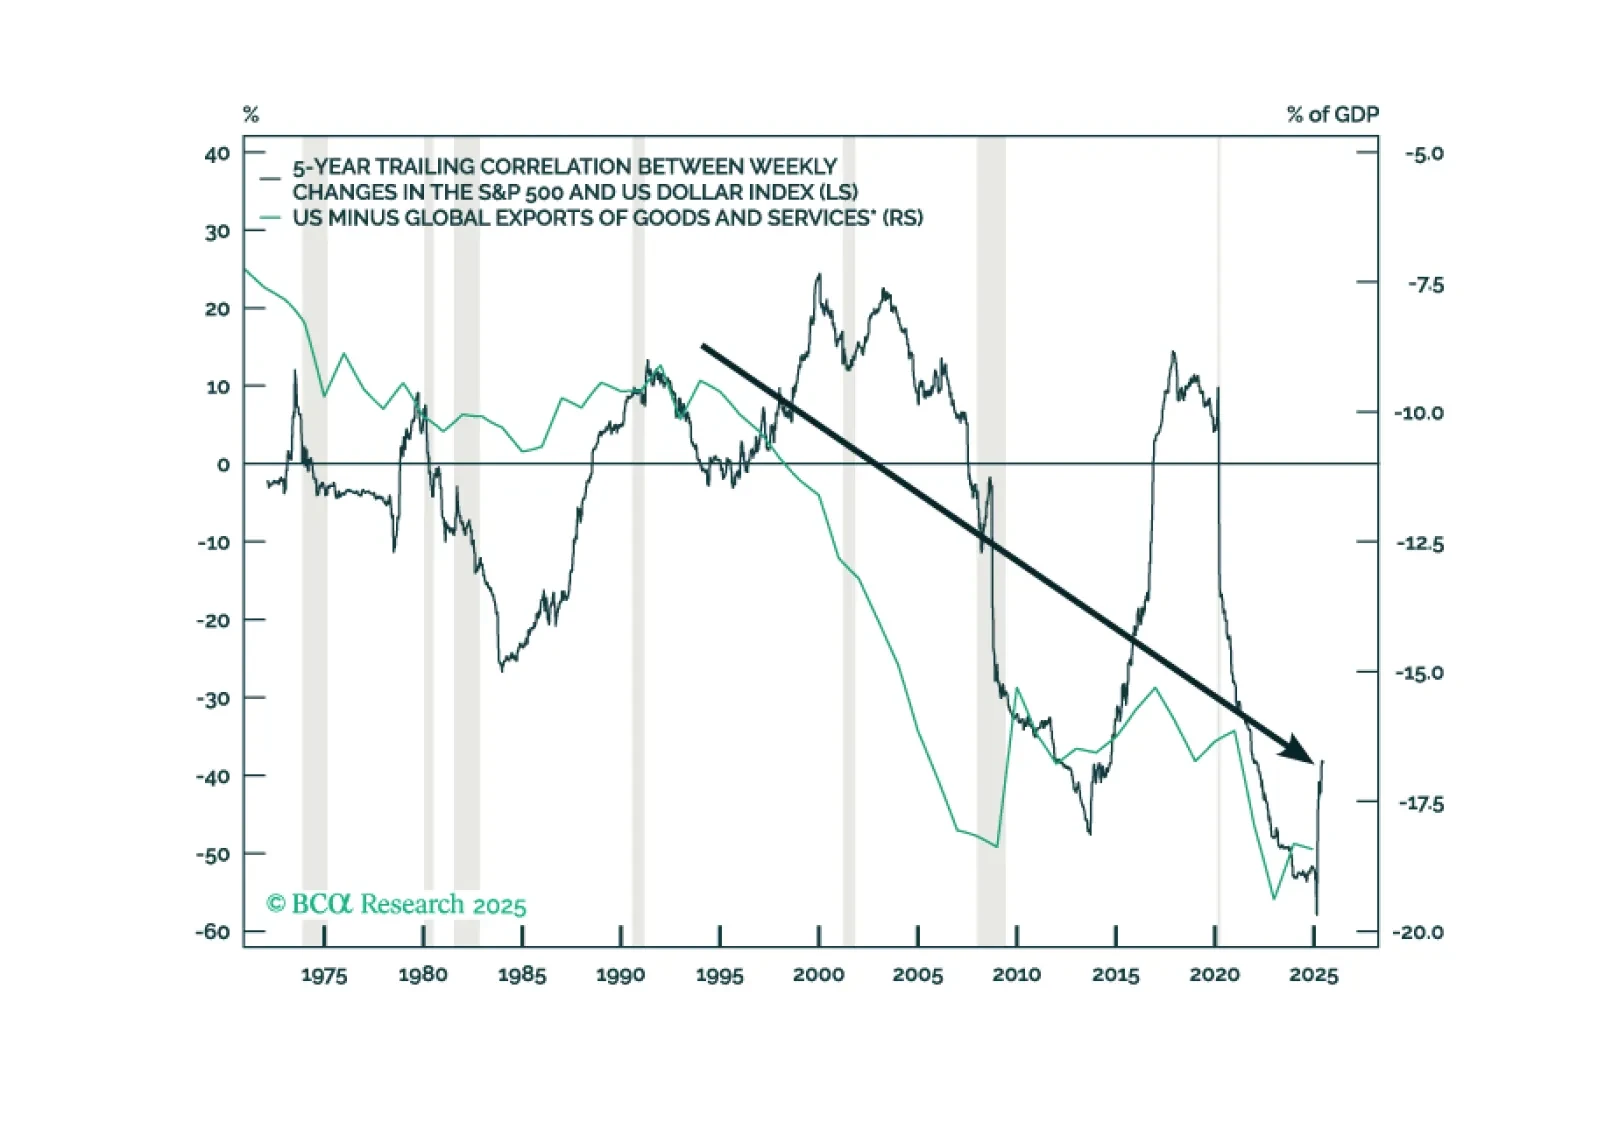
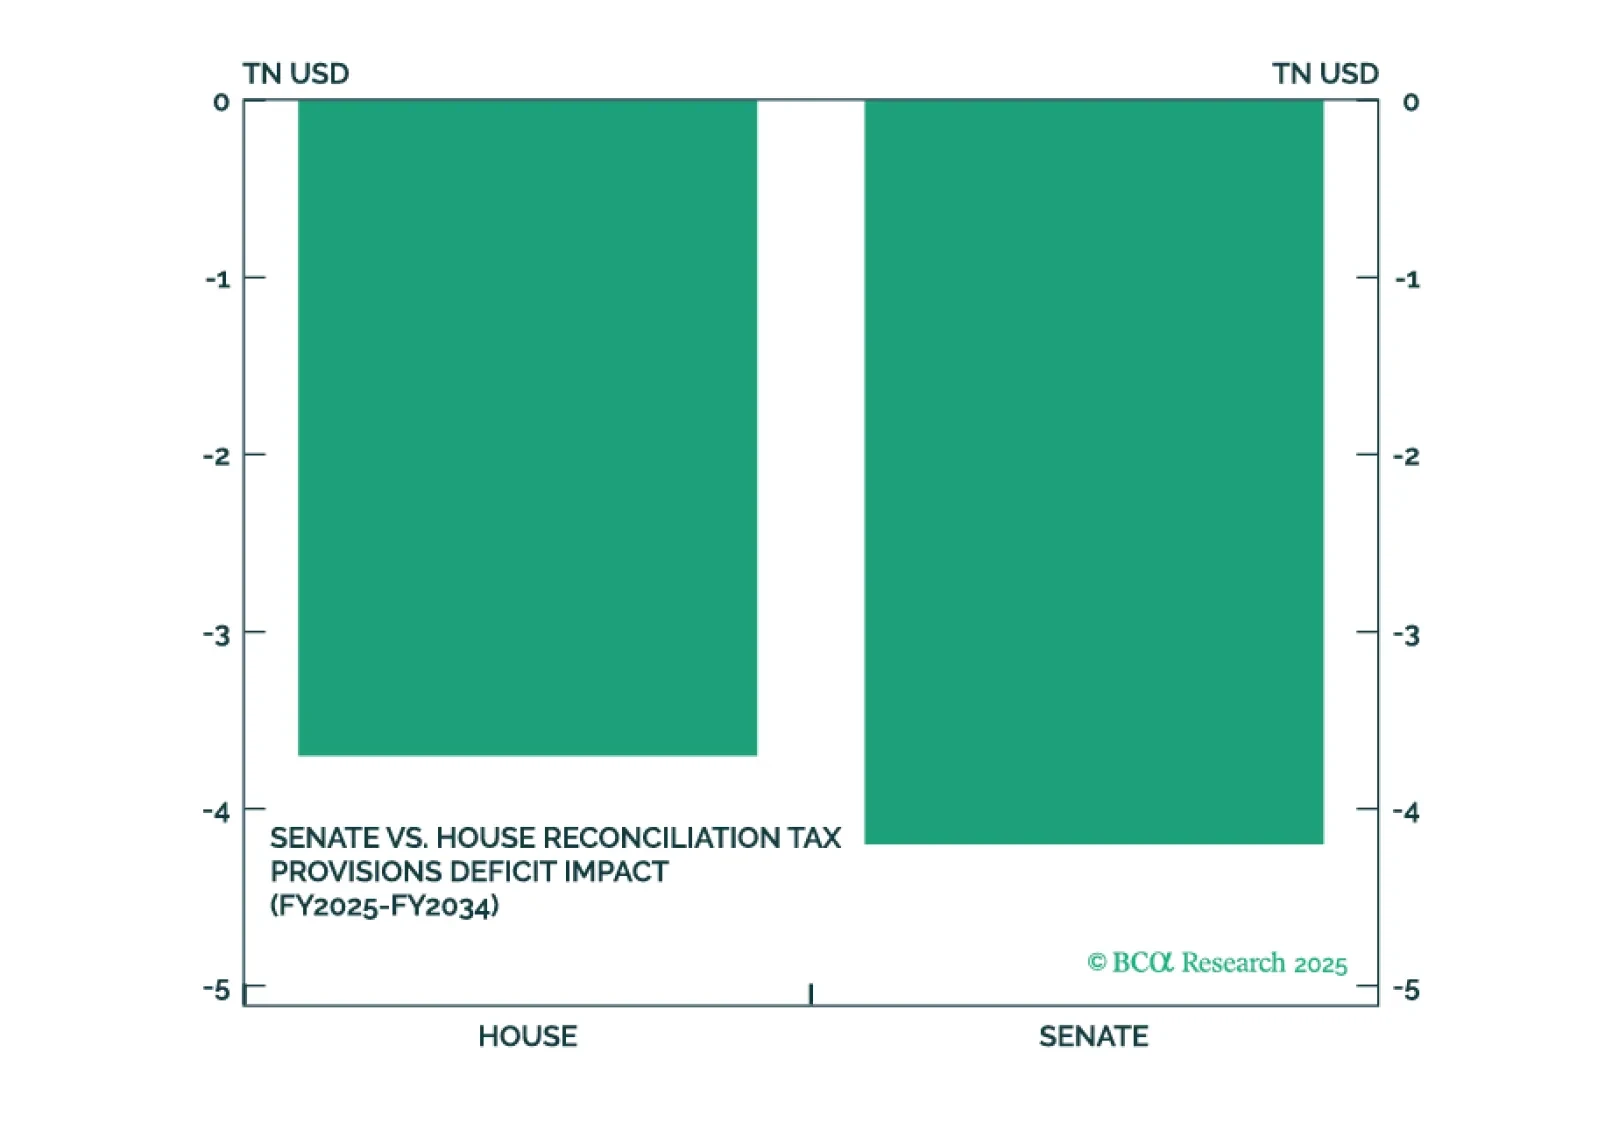
トランプ大統領の素晴らしい法案は可決されるものの、短期的なハードルがあり、政府の財政を緊縮することはありません。それは、新たな関税実施と相まって、債券市場と株式市場の両方に短期的なリスクをもたらします。イラン危機は収束し、トランプは彼の2期目を脱線させる可能性のあった大規模な石油ショックを回避しました。
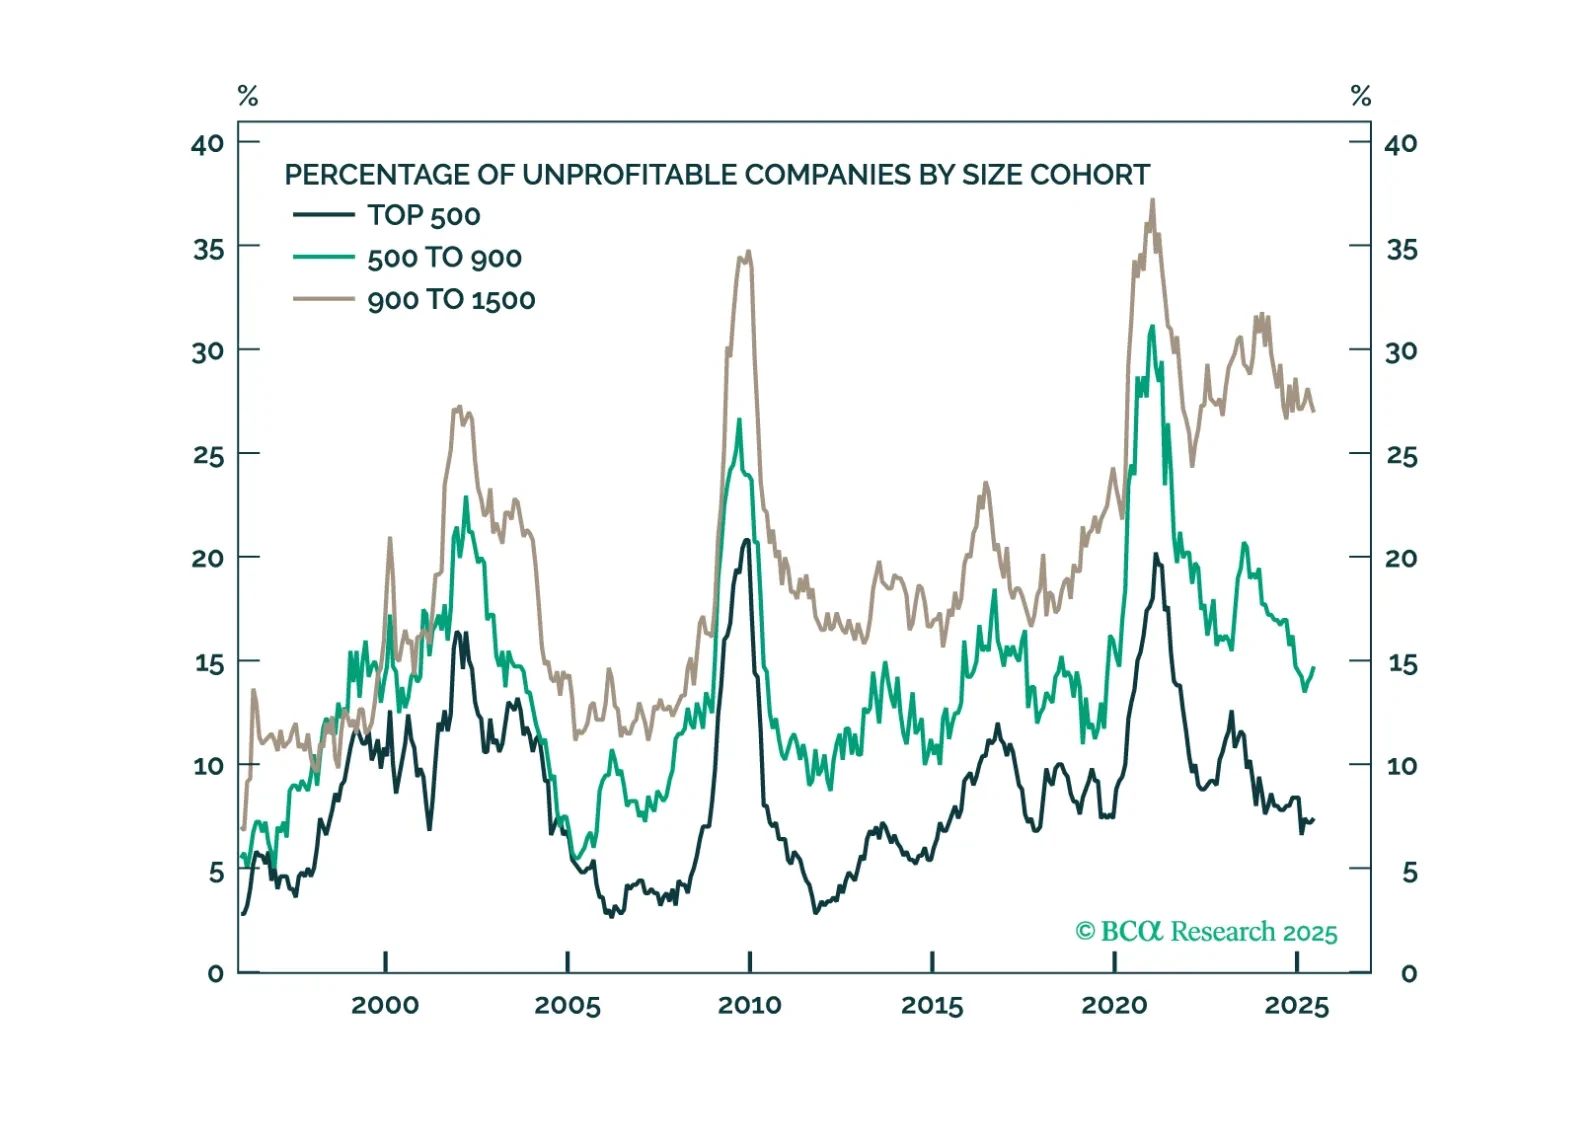
最近、小型株はアウトパフォームの兆しを見せています。本レポートでは、長期的な構造的トレンド、マクロ経済の背景、関税の影響、その他の重要な要因を分析し、この反発が持続可能かどうかを検証します。
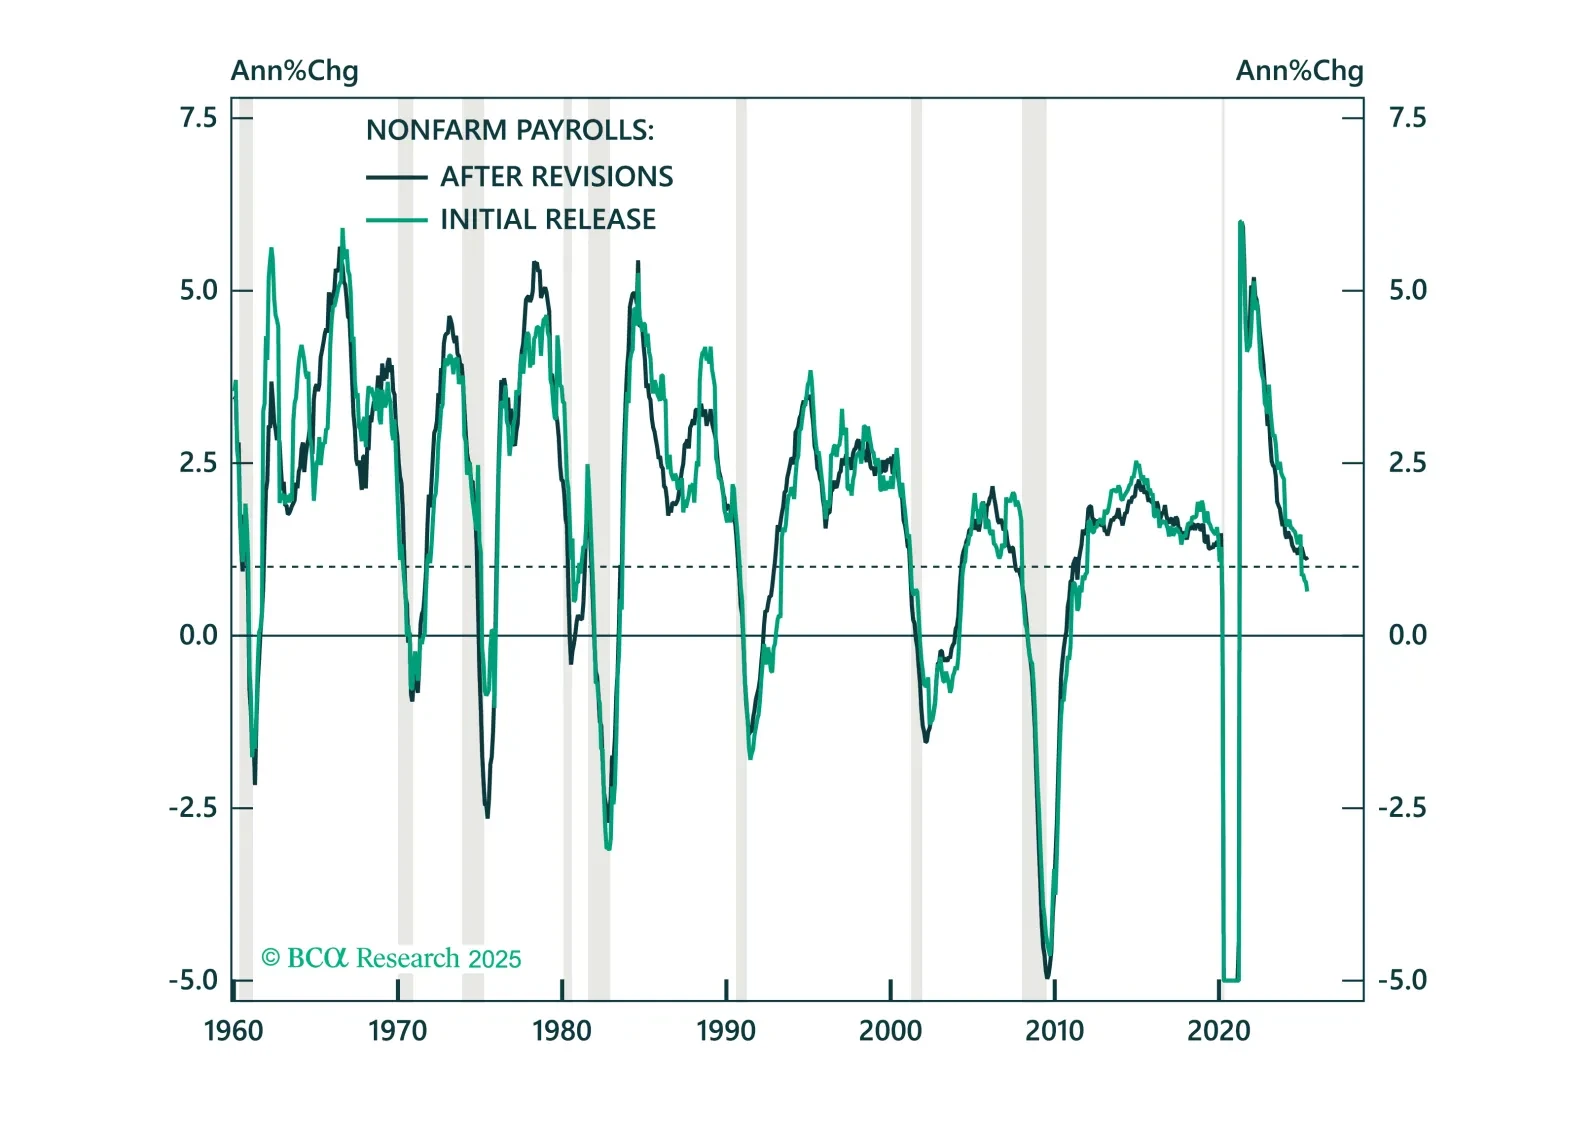
家庭のバランスシート、耐久財需要、関税の影響、DOGEが予算に与える影響、そして労働市場の冷却傾向に関する問題を迅速に見直した後、私たちは引き続き防御的な資産配分の推奨を強調します。
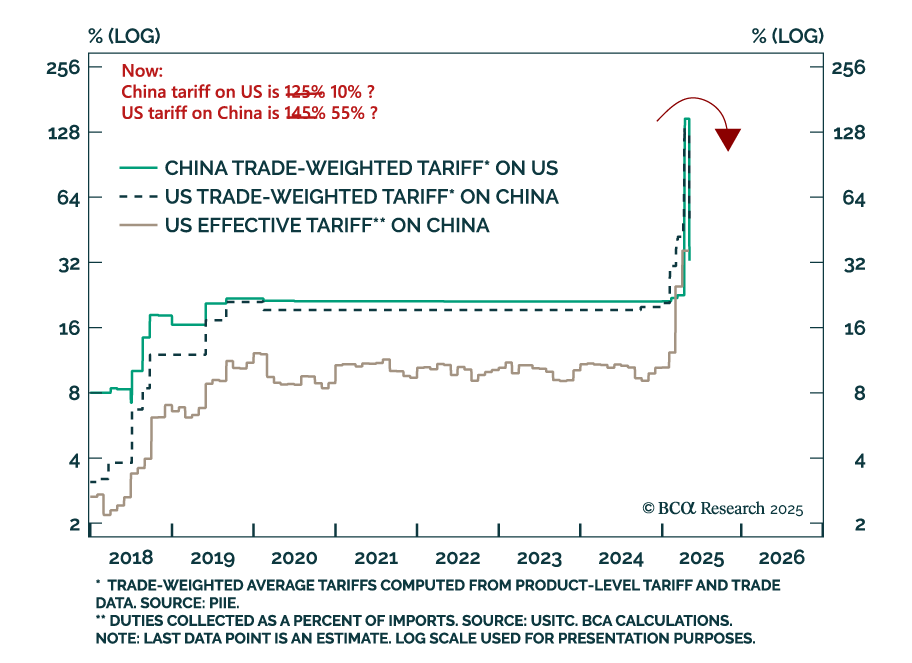
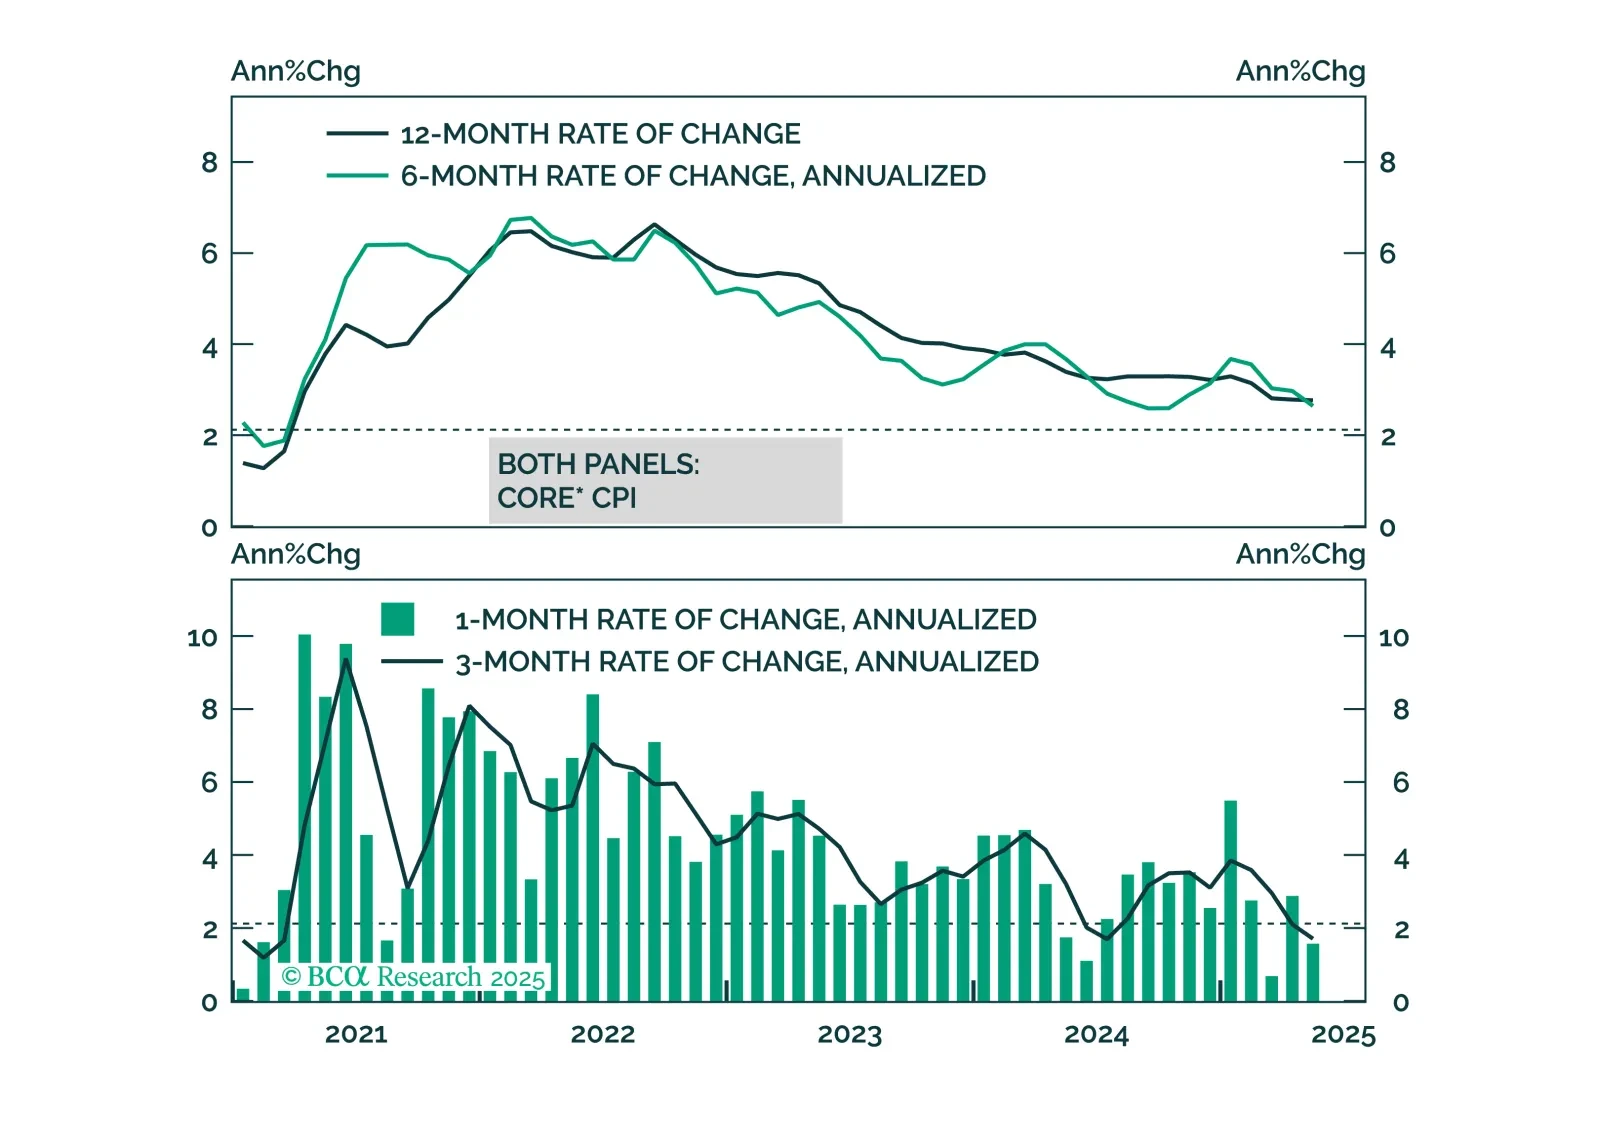
While we anticipate higher inflation in June, it looks increasingly likely that the price impact from tariffs will be less aggressive and long-lasting than many feared.
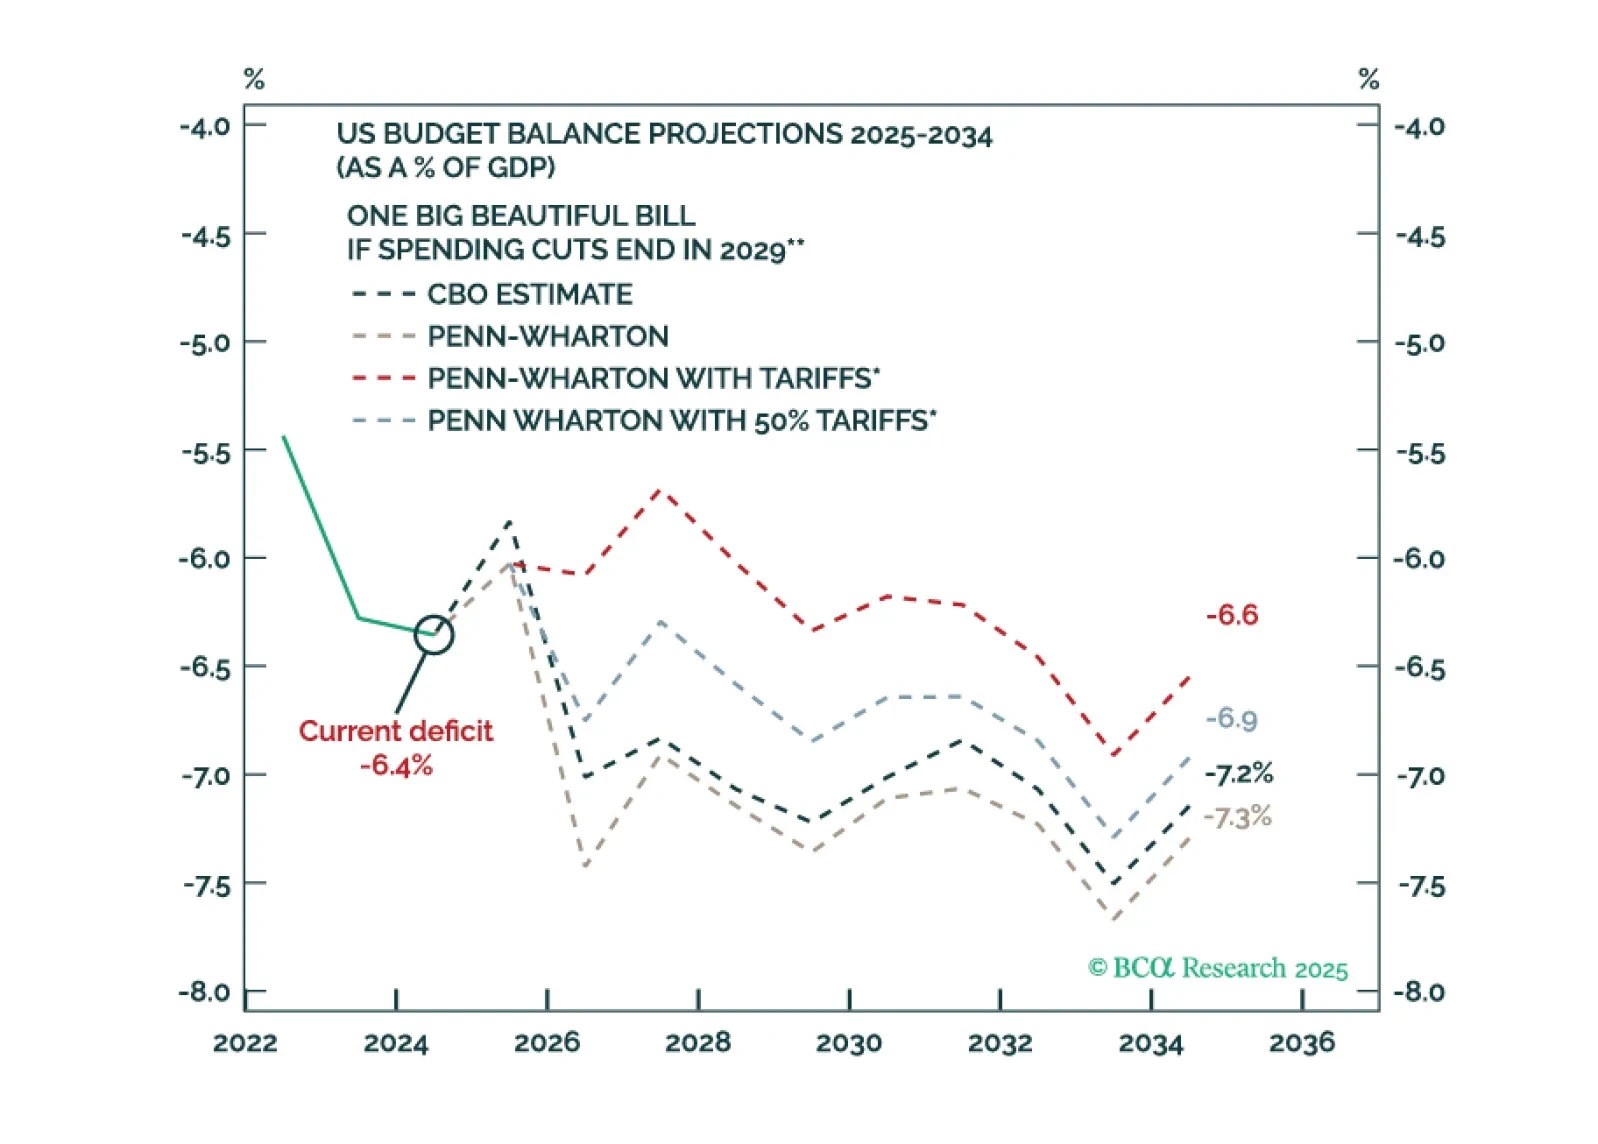
Bond market volatility will spike again in the near term. The Fed is committed to an easing cycle yet the Trump administration’s signature fiscal policy action will stimulate the economy. Tariffs are supposed to keep the budget deficit contained but they are inflationary.

The US economy has held up better so far this year than we had expected. For the time being, investors should remain modestly underweight equities. A more aggressive underweight would be justified only once the “whites of the recession’s eyes” are visible.
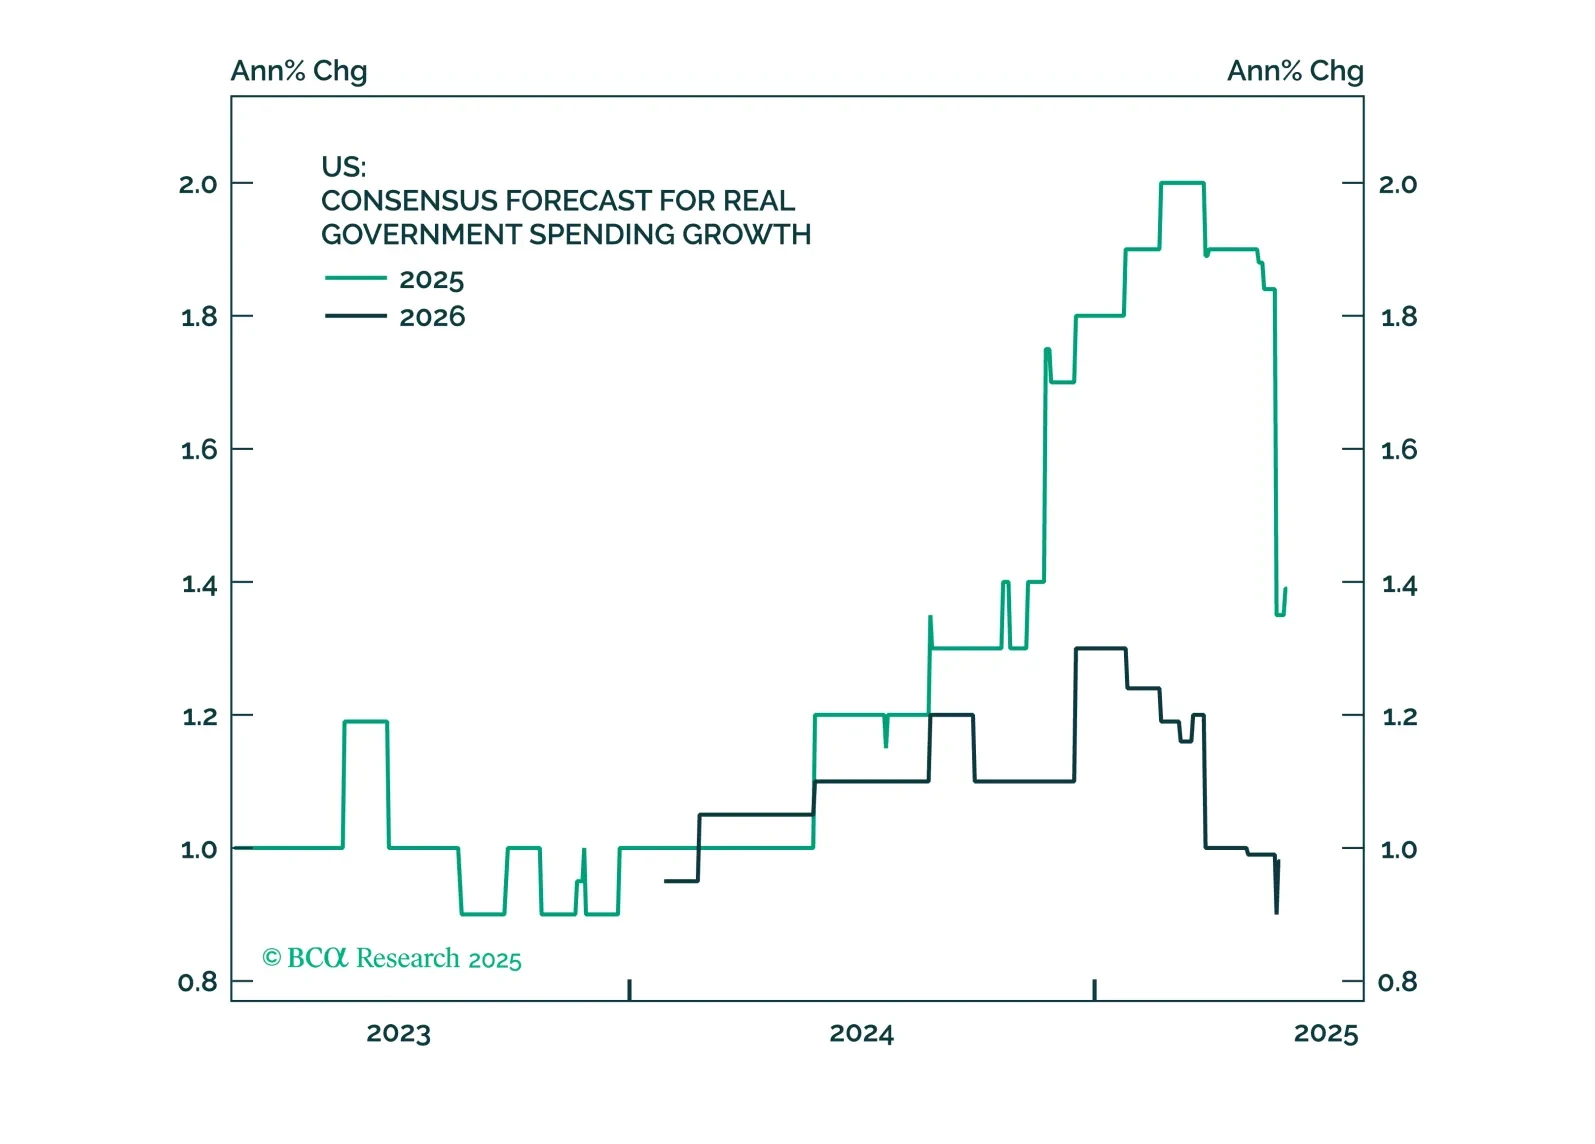
This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.