メインコンテンツにスキップ
メインコンテンツにスキップ

Latin America

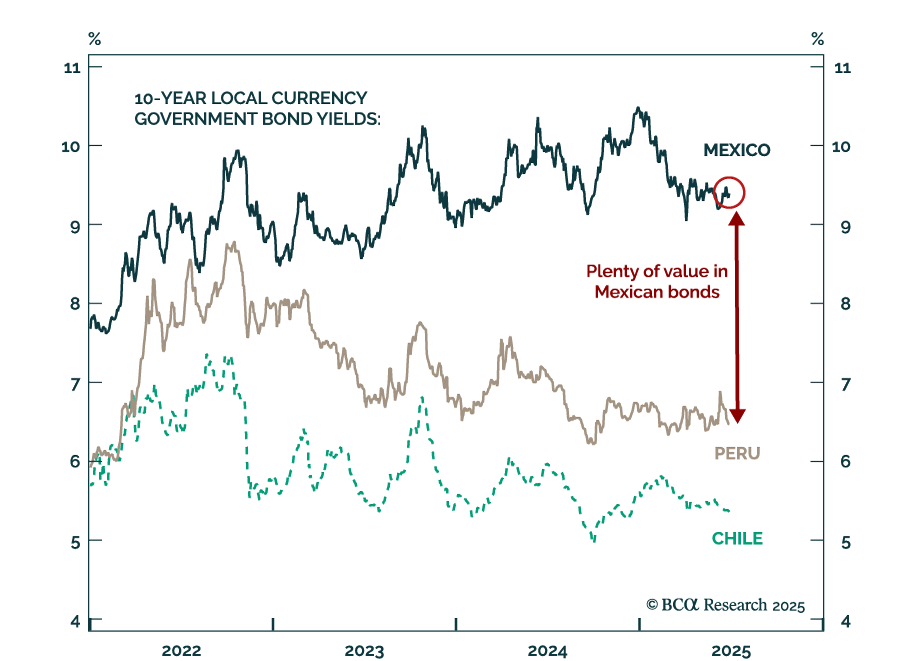
メキシコ国内債券を購入 メキシコ国内債券を購入 Banxicoのハト派的姿勢はメキシコ現地通貨債券に対する強気の見解を裏付けます。メキシコ中央銀行は金利をさらに50ベーシスポイント引き下げ、8%となりました。 中央銀行は来年まで金融緩和を継続する予定です。米国の需要の減速はメキシコの成長とインフレを押し下げ、今後数ヶ月で総合CPIとコアCPIが目標レンジに向かうでしょう。さらに、財政黒字と経常収支黒字の組み合わせにより米ドルに対するメキシコペソの通貨価値が上昇し、輸入インフレを抑えることができます。…
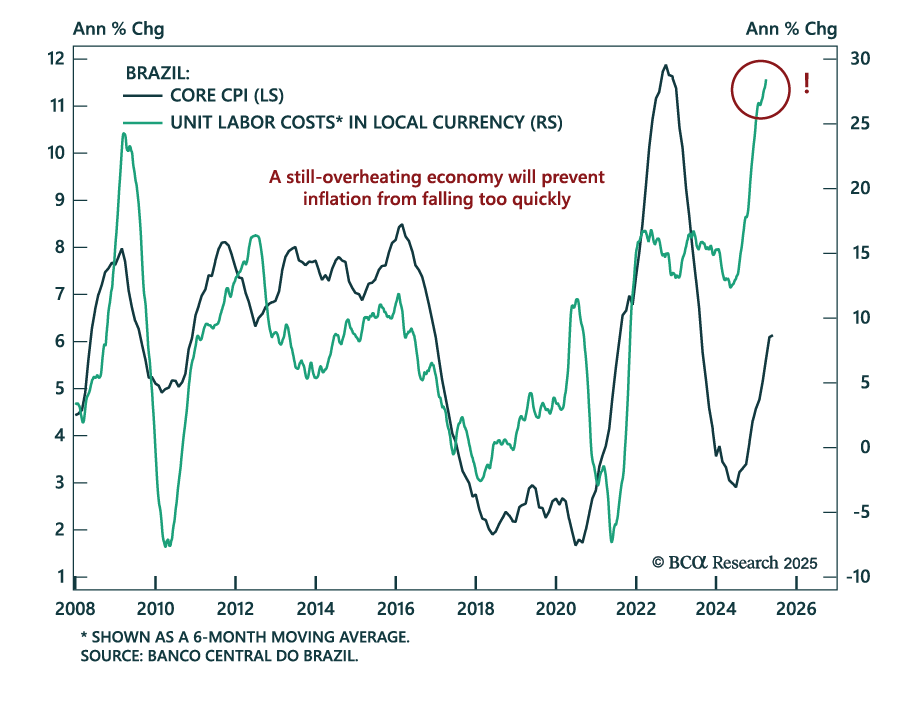
The May Brazilian CPI suggests that price pressures may have reached a peak, but do not expect immediate monetary easing to support fixed income markets. Headline CPI slowed to 5.3% y/y from 5.5% April, but core CPI remained flat at 6.1%. Despite peaking…
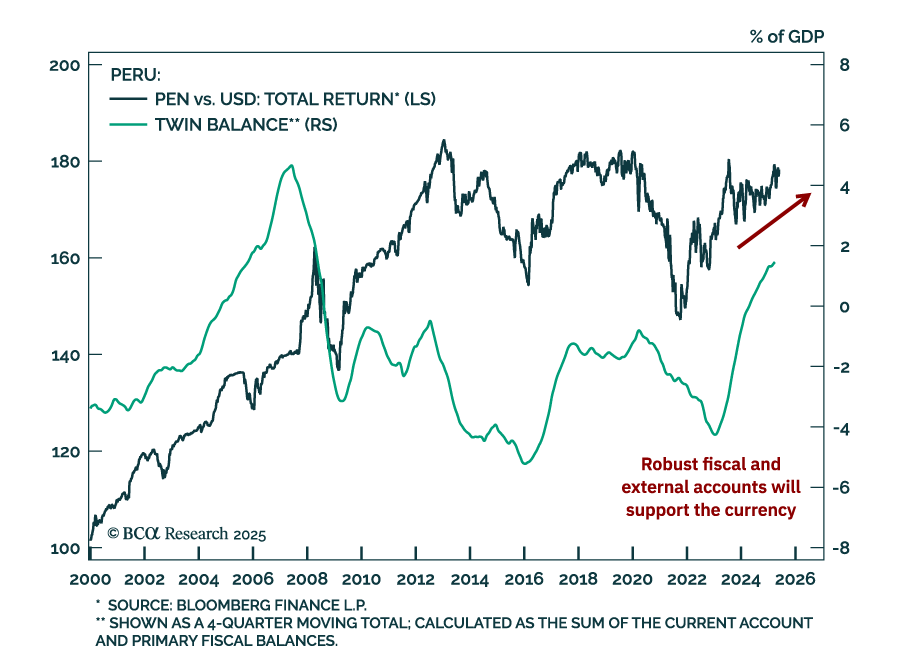
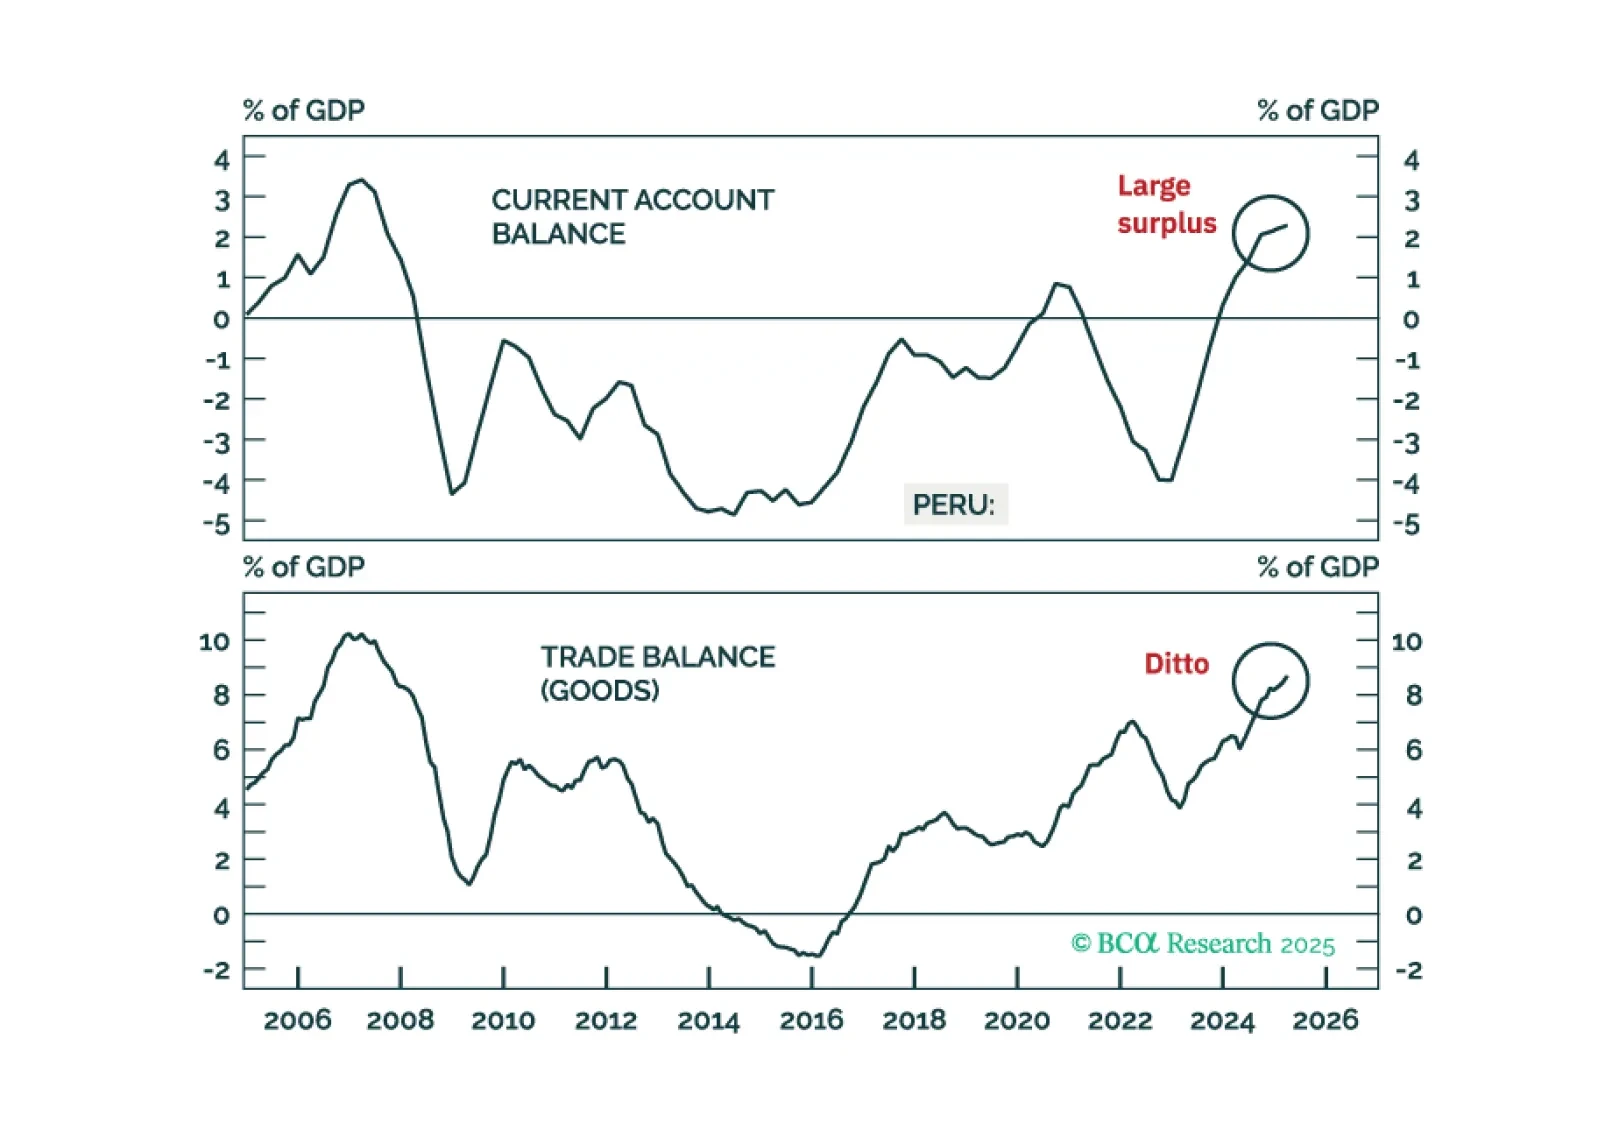
Peru’s economic resilience will help its markets outperform their EM peers. A global growth downturn will weigh on EM assets in absolute terms, but Peruvian markets offer attractive tradeable opportunities. The Andean nation has much better macro fundamentals…
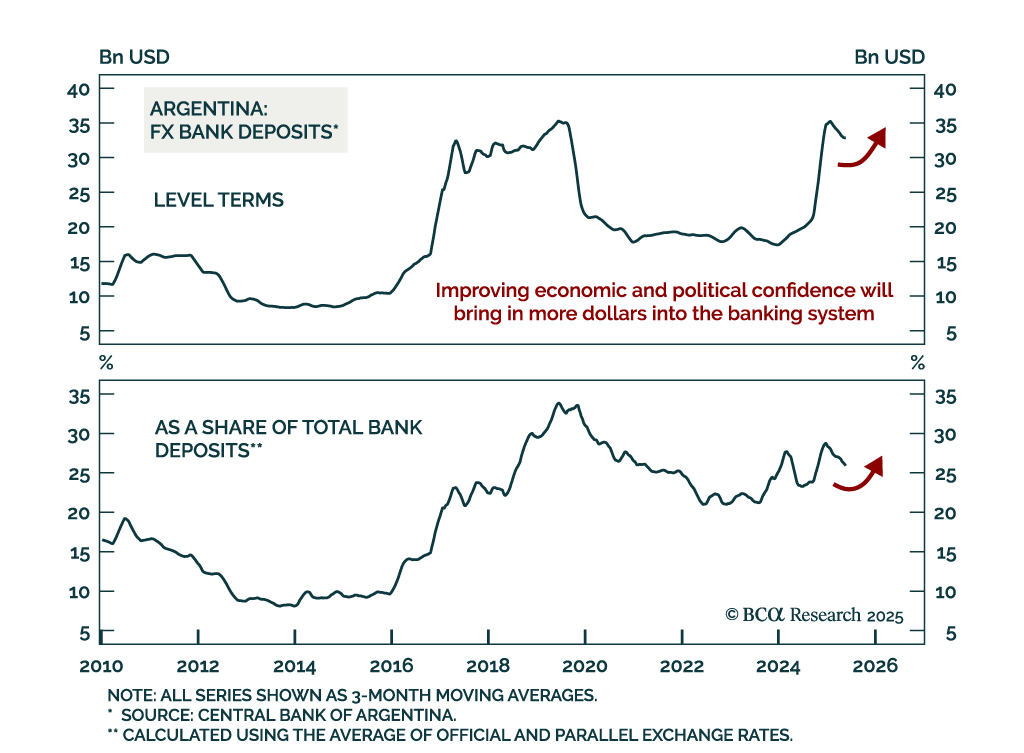
The latest political developments in Argentina increase the odds of further liberalizing reforms and solidify the economy’s structural upside. First, the libertarian governing party came out on top in Buenos Aires’ legislative elections. While municipal…

Peru’s economic resilience will help its markets outperform their EM peers. Domestic macro fundamentals are robust, and strong external accounts will lead to a stable-to-strengthening currency versus the US dollar. Overweight Peruvian equities, local bonds, and sovereign credit relative to their respective EM benchmarks, and go long 10-year domestic bonds (currency unhedged).
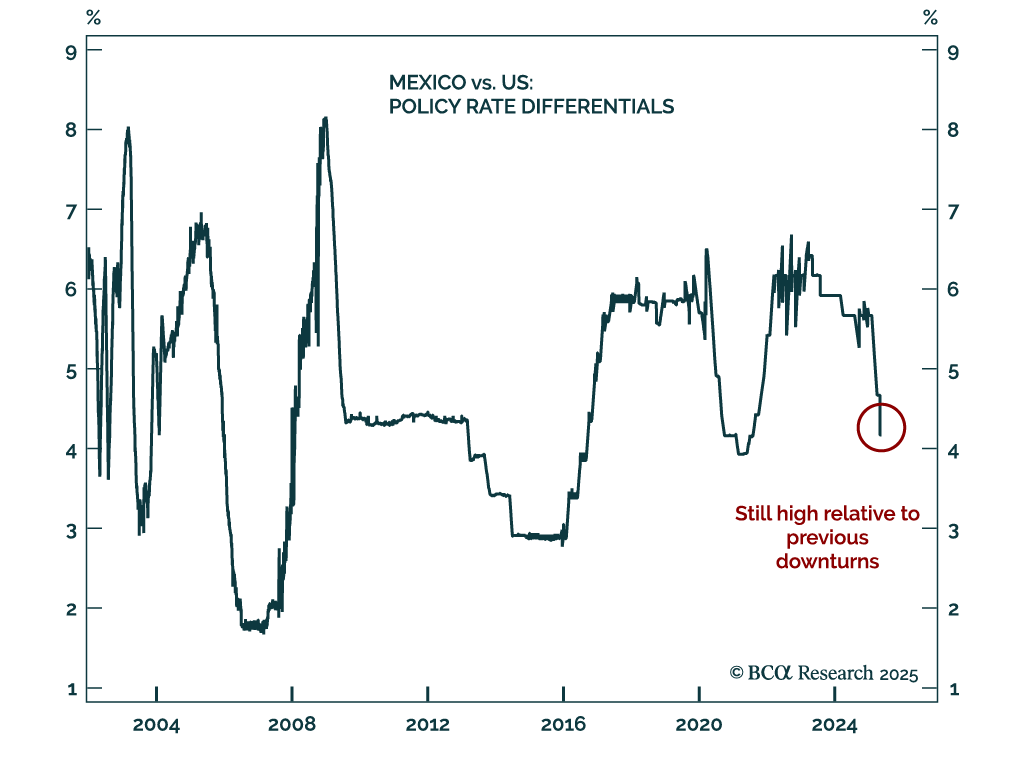
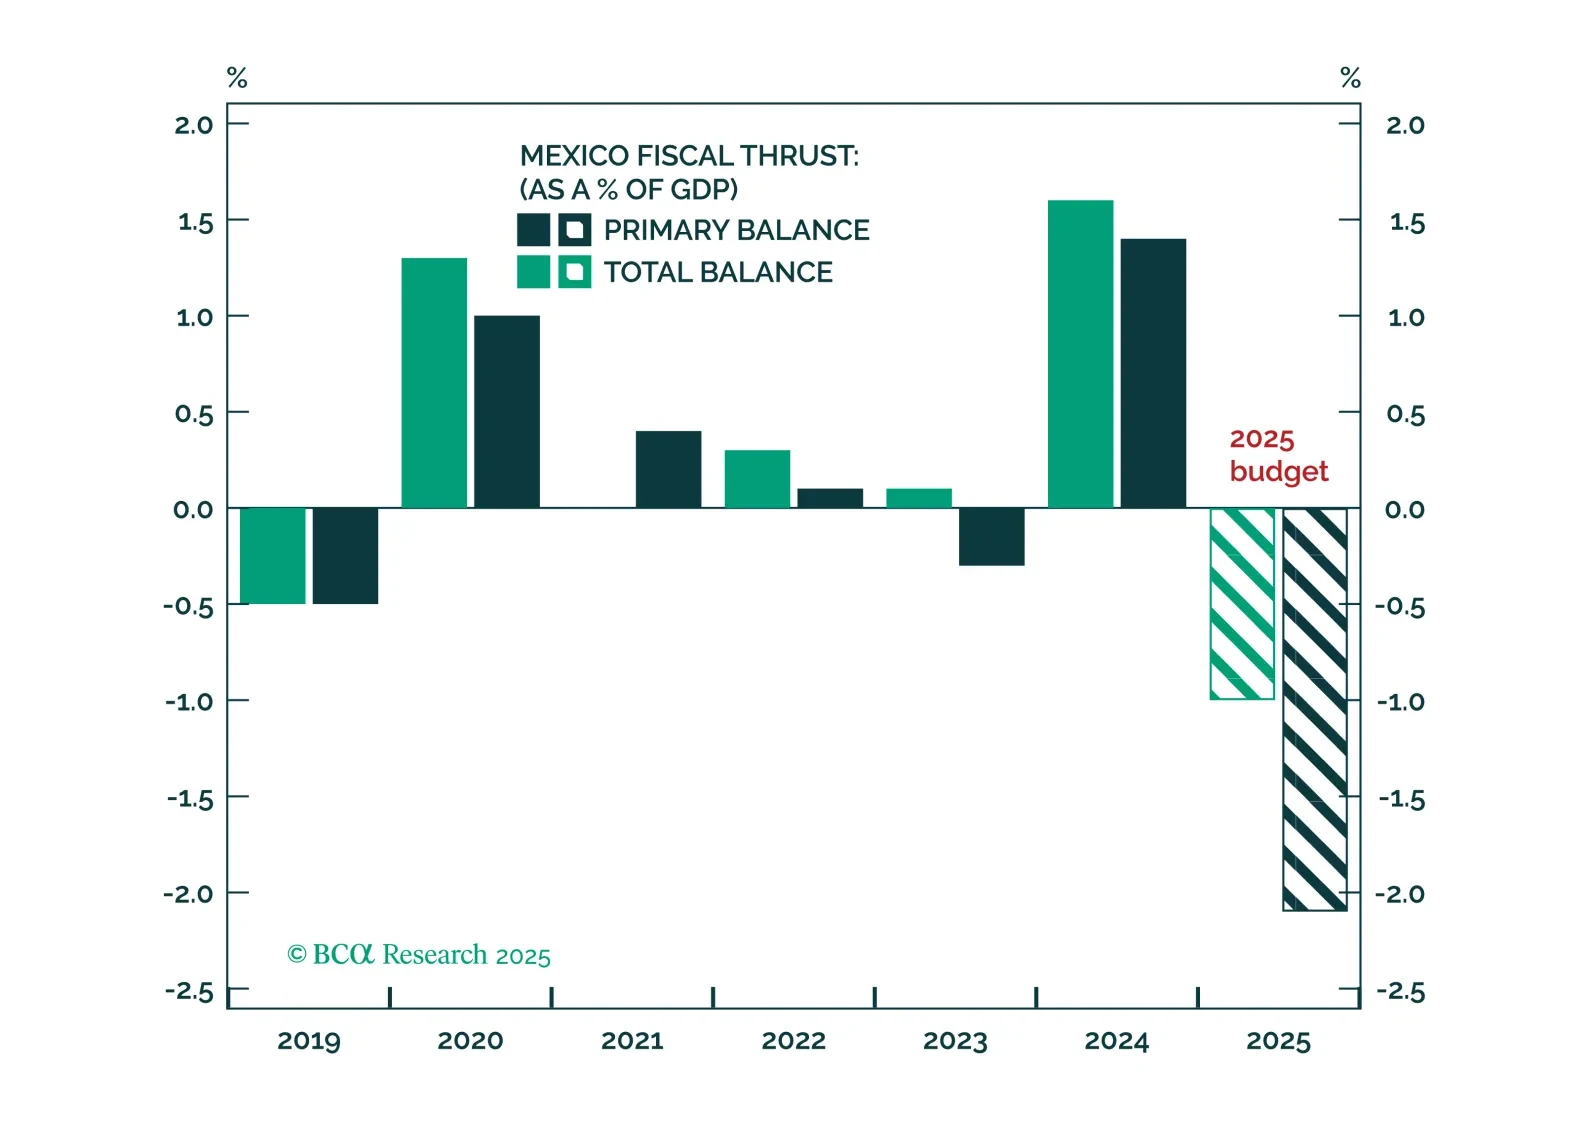
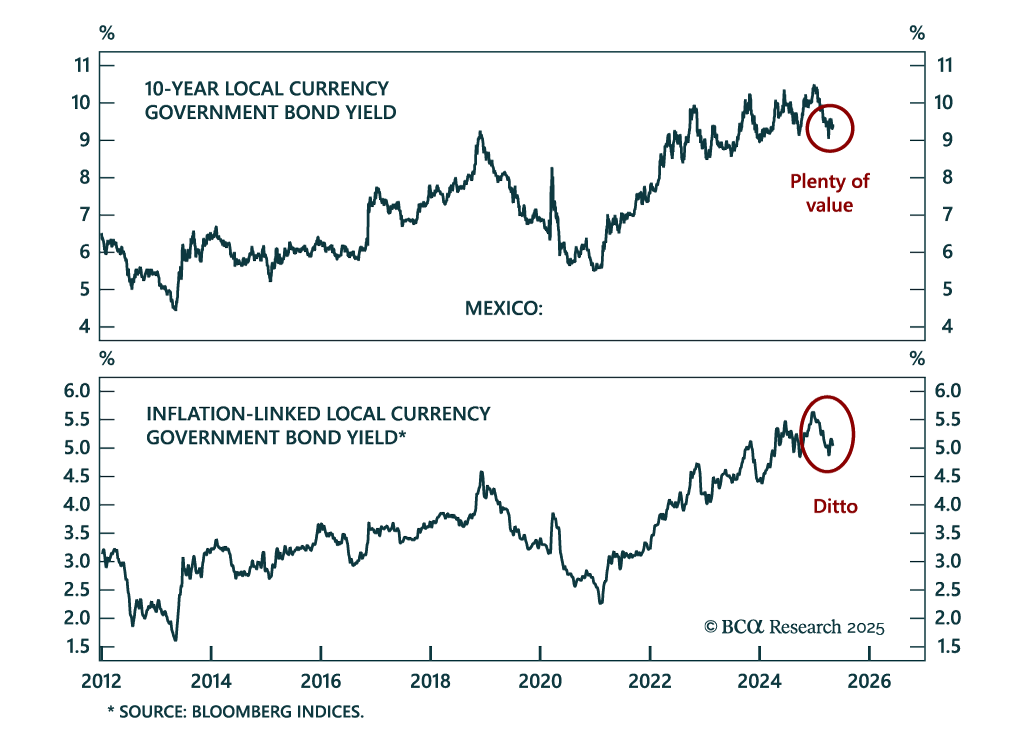
Banxico’s 50 bps rate cut reinforces our bullish view on Mexican bonds, with easing likely to continue as inflation falls and growth slows. The central bank unanimously lowered its policy rate to 8.5%, and we expect further cuts ahead as Mexico heads toward a…
特別レポート

Short-term pain from Trump-related concessions, fiscal tightening amid a US and Mexican slowdown, and rising labor slack will weigh further on Mexican assets. But long-run, policy direction will capitalize on the nearshoring trend and resume the trend of Mexican asset outperformance relative to other emerging markets.
Mexico will be one of the biggest winners of the global trade war, creating a structural tailwind for its assets. Mexican risk assets and the peso are uniquely positioned to outperform while EM assets suffer as global growth slumps. First, Mexico’s exports…

In the long run, Mexico will emerge as one of the biggest winners of US tariffs as the US diversifies supply chains away from China. In the medium term, however, a US growth slowdown and tariffs will push Mexico into recession. In EM portfolios, we remain overweight Mexican equities, domestic bonds, and sovereign credit. We are reiterating a buy on 10-year domestic bonds. Go long MXN versus CNH.

Amid the storm of global financial uncertainty, Argentina stands out as a free-market safe haven. The lifting of currency controls was the last step taken by this country to embrace market mechanisms. We recommend that investors buy Argentine equities, sovereign credit, and domestic bonds, and overweight Argentina within EM equity and fixed-income portfolios.