Inflation/Deflation
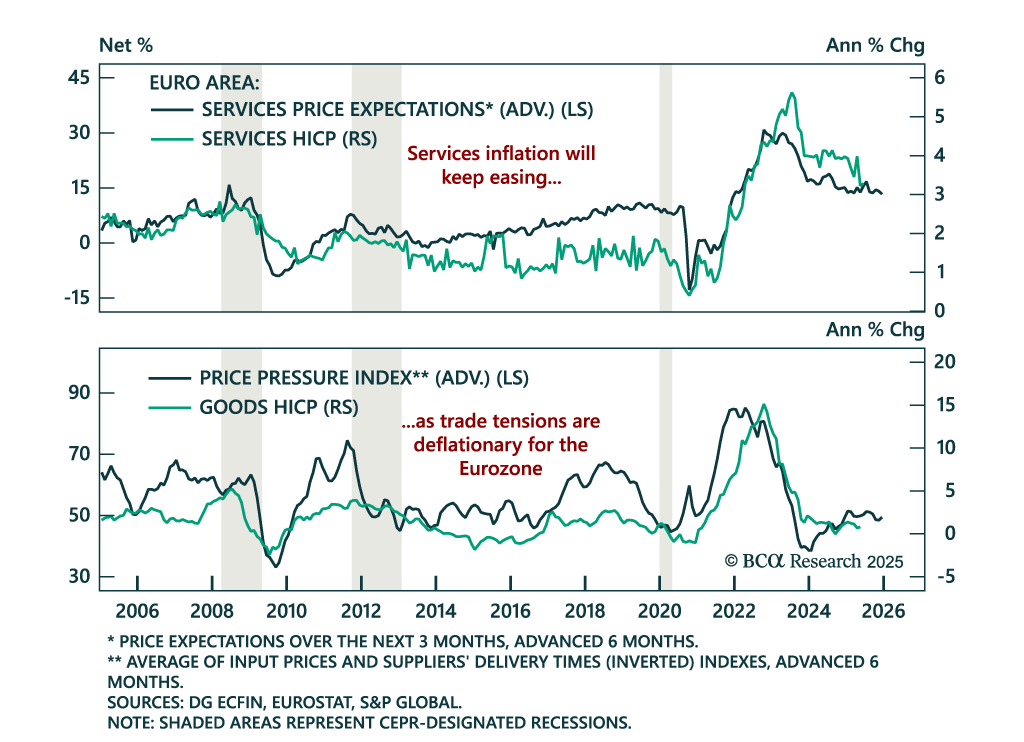
ユーロの強さと低調なインフレがさらなるECB利下げを正当化 ユーロの強さと低調なインフレがさらなるECB利下げを正当化 6月のユーロ圏インフレーションデータと弱い成長環境は、ECBのさらなる緩和を支持し、長期ヨーロッパ債券のエクスポージャーを強化する根拠となります。…
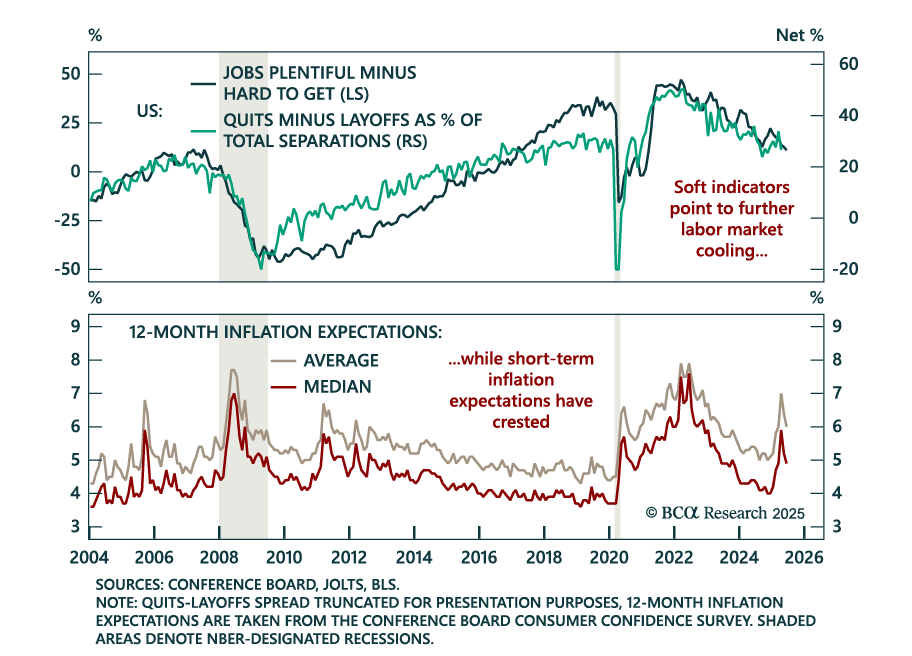
消費者信頼感の低下と労働市場の勢いの衰えは、インフレ懸念が後退する中で長期デュレーションのポジションを支援します。6月のコンファレンスボード消費者信頼感指数は93.0と、期待値を下回る5ポイントの減少を示しました。現状の見方と期待値の両方がこの低下に寄与しました。また、職が豊富か得るのが難しいかを追跡する「労働差異」も悪化しました。…
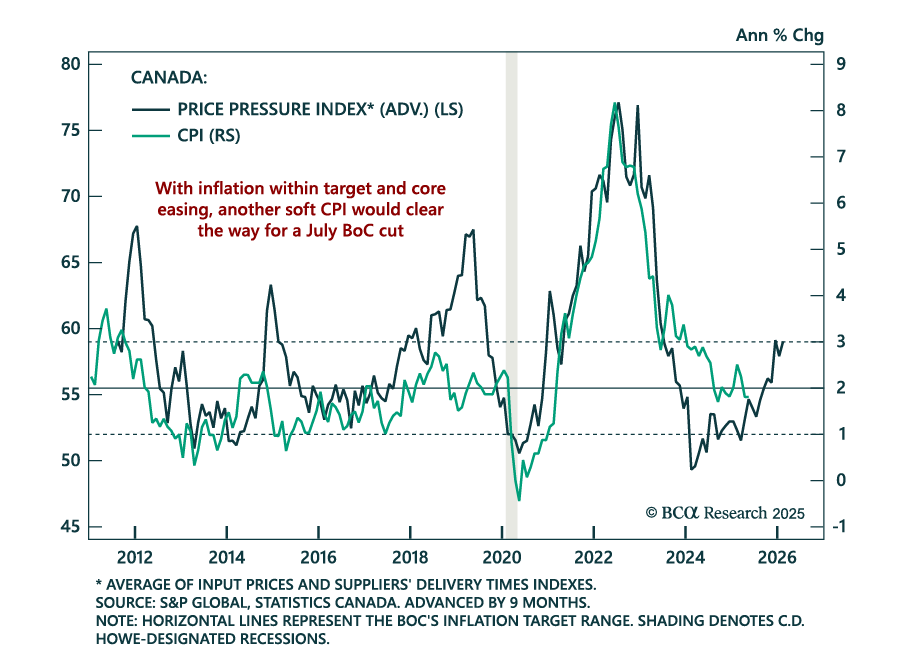
Contained Canadian inflation and soft macro conditions support our overweight on Canadian government bonds. May CPI was in line with expectations, with headline inflation holding at 1.7% y/y and core measures slowing to 3.0%, the upper bound of the BoC’s…
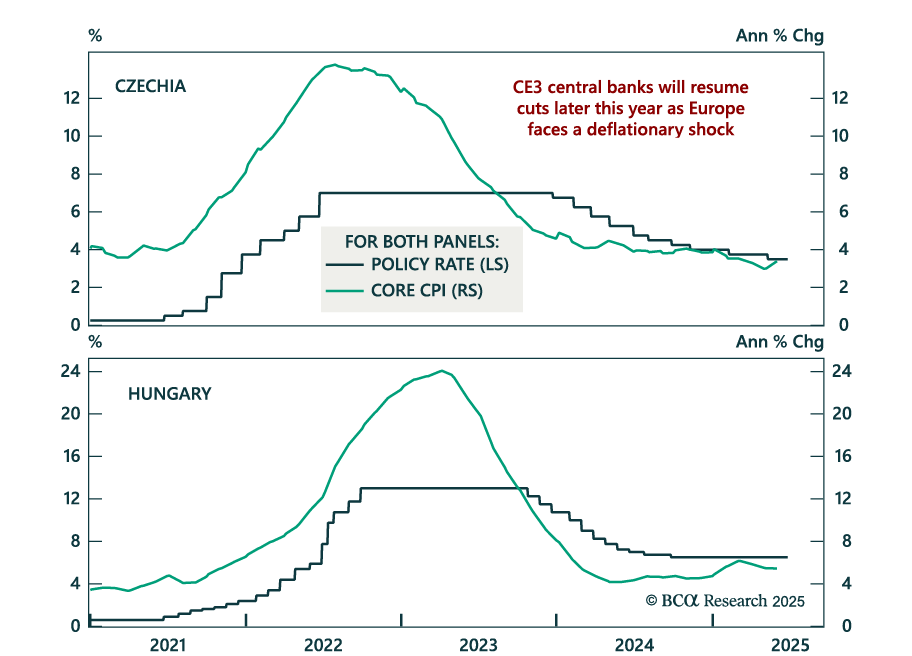
デフレ圧力と欧州コア経済の低成長は、利下げが近づく中でCE3国債のロングポジションを支援. チェコおよびハンガリー中央銀行は今週、それぞれ金利を3.5%と6.5%で据え置きました。これはポーランドが先週、金利を5.25%で据え置いた決定を追従する形です。インフレリスクを警告しながらも、欧州全体はデフレ圧力が拡大している状況に直面しています。…
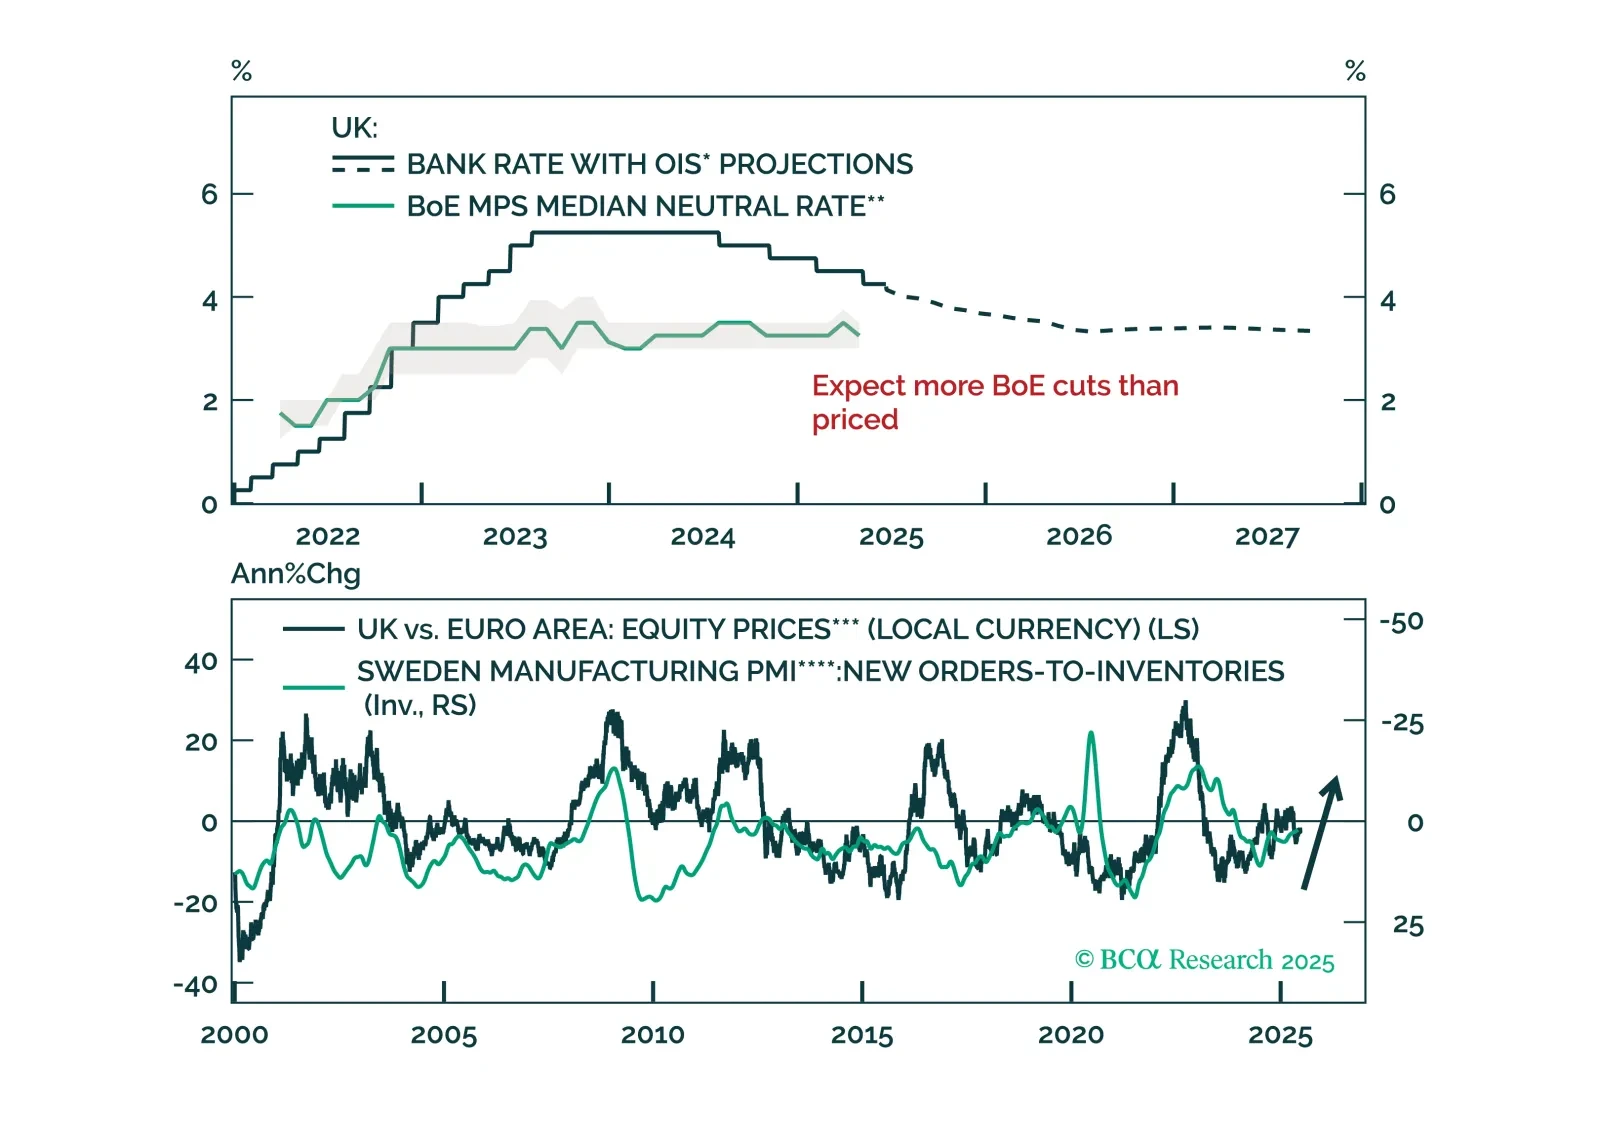
英国のインフレリスクは労働市場の弱体化を背景に低下しています。BoEの緩和が再開される中、ギルト債と英国株がなぜアウトパフォームする態勢にあるのかをお読みください。
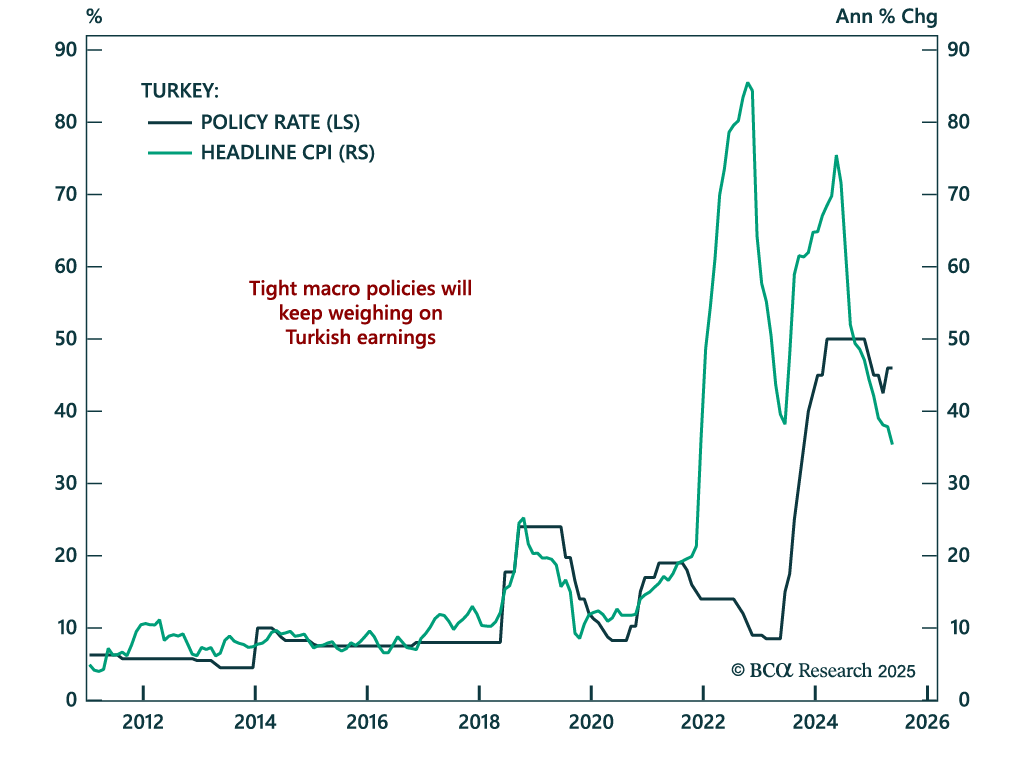
金融引き締め政策はトルコ株式市場に痛みを示唆 金融引き締め政策はトルコ株式市場に痛みを示唆 トルコの引き締めた政策スタンスが成長と収益に影響を与え、トルコ株式に対する弱気の見解を強化します。 中央銀行は金利を46%に据え置き、35%から1桁台までインフレを引き下げる努力と一致する形でタカ派的な姿勢を維持しました。財政政策も大幅に引き締められており、最近数ヶ月では支出が減速しています。…
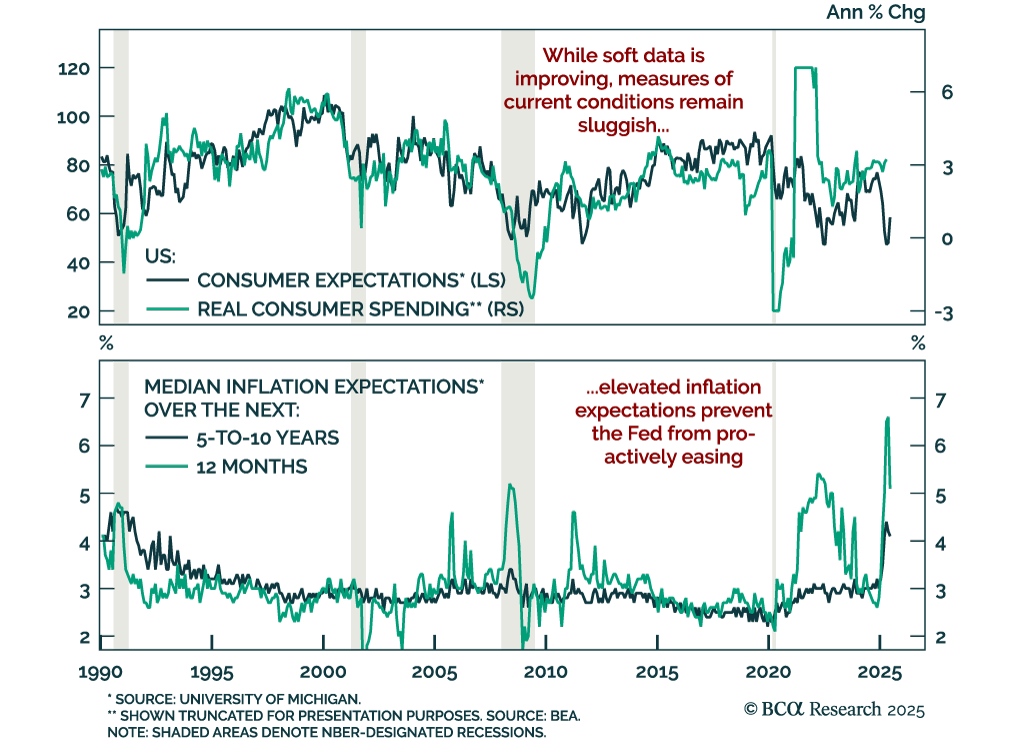
While consumer sentiment is rebounding, sticky inflation expectations and slowing growth warrant staying long duration and steepeners. The preliminary June University of Michigan Consumer Sentiment Index surprised to the upside, rising to 60.5 from 52.2.…
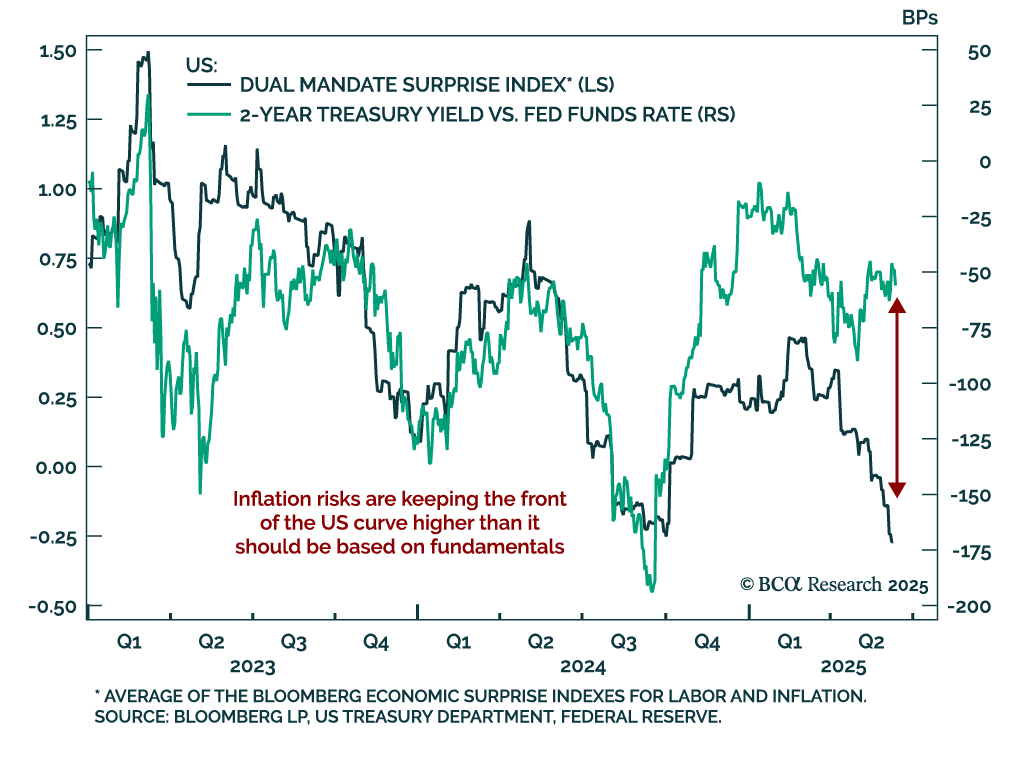
Elevated inflation expectations are keeping the Fed sidelined, reinforcing our long-duration and steepener bias in US rates. The US May CPI would have normally supported cuts, but the Fed cannot risk elevated short-term inflation expectations feeding into…
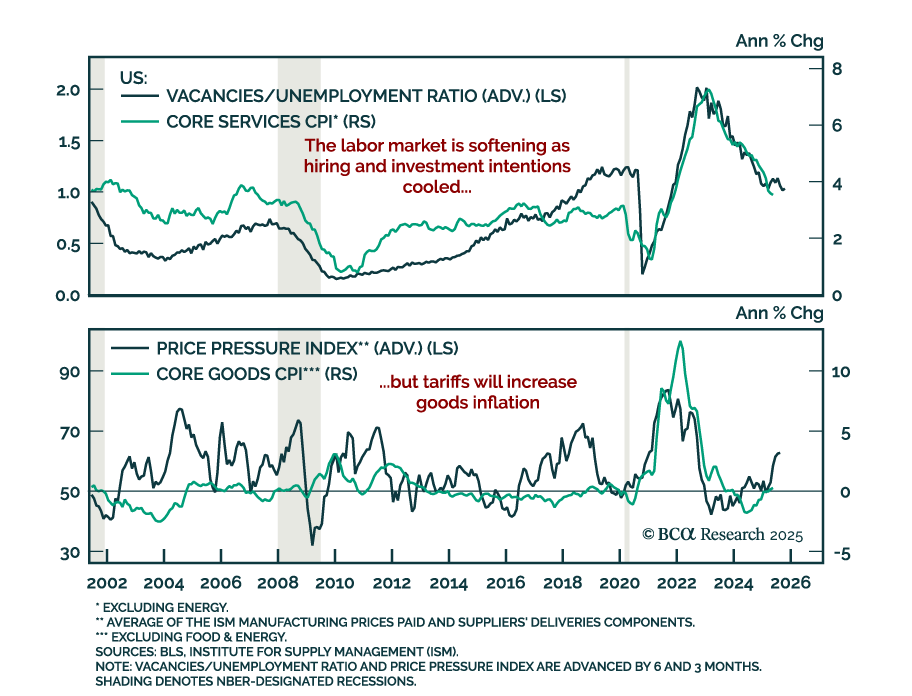
Colder May CPI reinforces our overweight in government bonds and tactical steepener trades as growth slows and the Fed stays cautious. Headline inflation rose 0.1% (2.4% y/y), below expectations, as did core CPI (2.8% y/y). Goods inflation was flat, and…
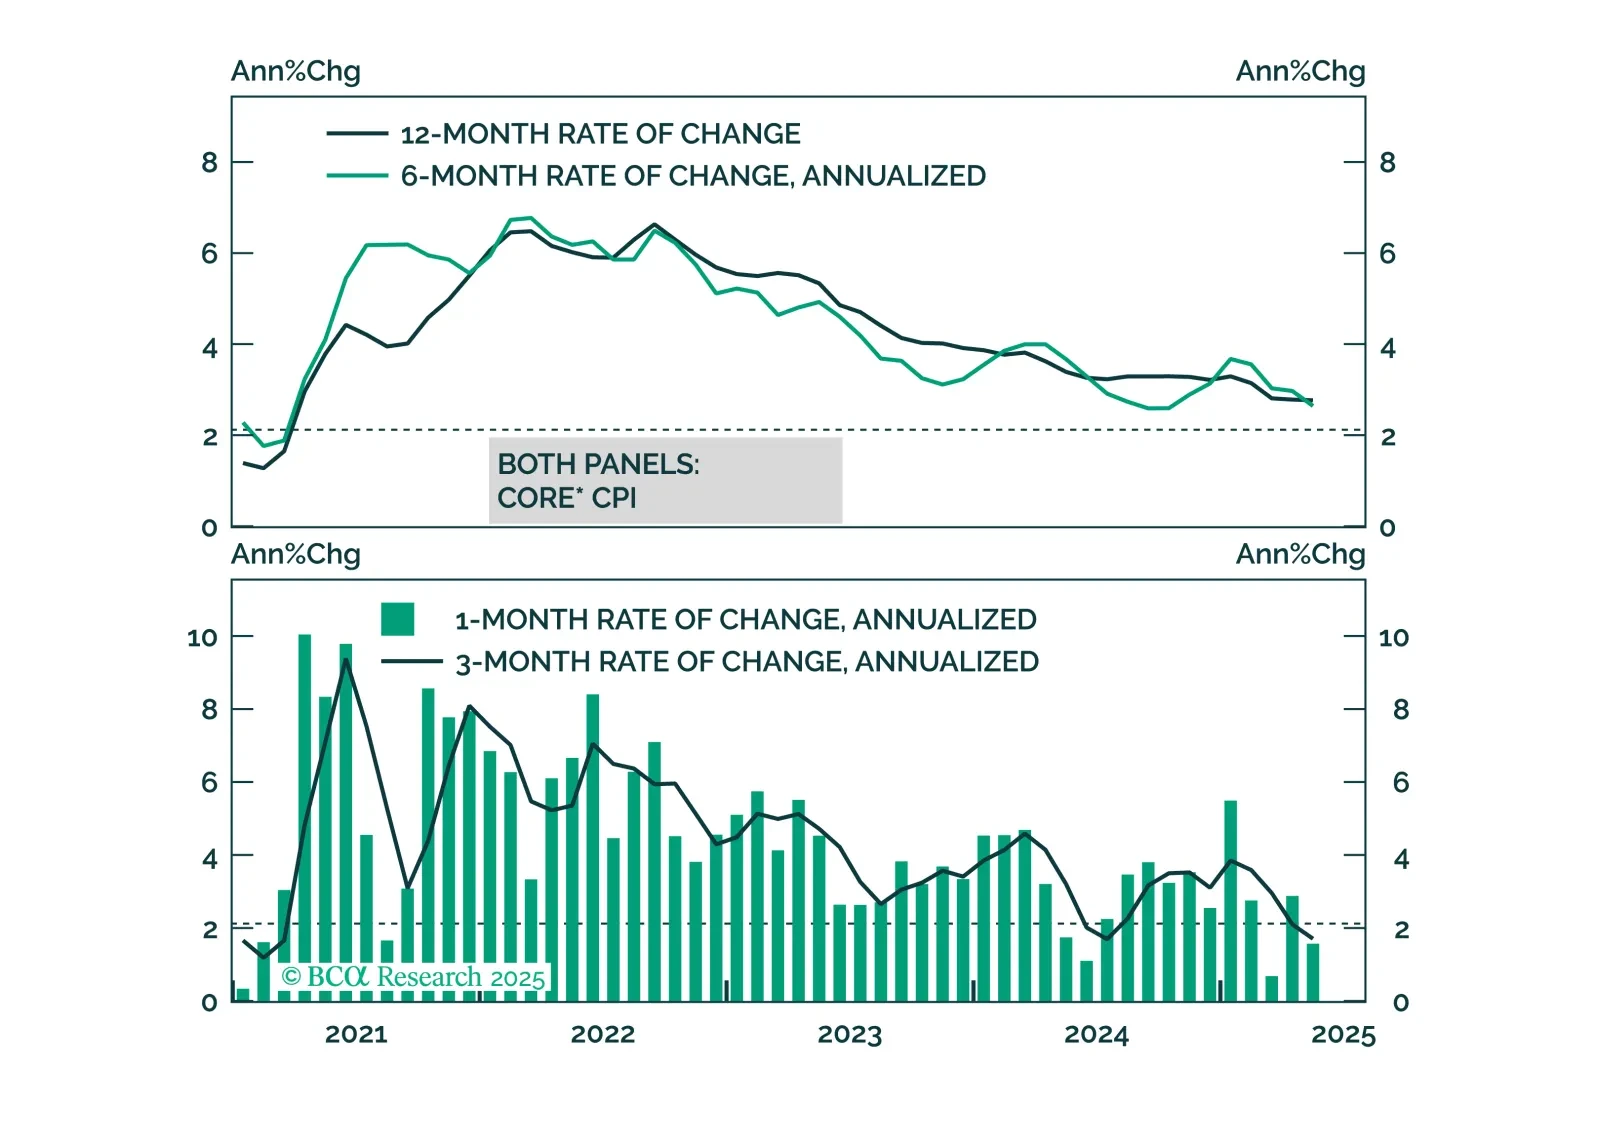
While we anticipate higher inflation in June, it looks increasingly likely that the price impact from tariffs will be less aggressive and long-lasting than many feared.